
 Business Travel Insurance Market | 2026-2036
Business Travel Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Business Travel Insurance Market Analysis
Buyer concentration among multinational corporations is restructuring distribution economics in business travel insurance. Fortune 500 procurement teams now negotiate master policies covering thousands of employees simultaneously, compressing broker margins. Allianz leverages its captive reinsurance capacity to undercut competitors on annual multi-trip corporate programs. AIG anchors its position through specialized war-risk and terrorism coverage for executives in unstable regions. Chubb differentiates via white-glass claims concierge services targeting C-suite travelers.
Business travel insurance is a short-term risk-transfer instrument underwritten to indemnify policyholders against financial losses arising from work-related travel disruptions, typically incorporating medical evacuation limits exceeding standard health policies and 24-hour assistance hotlines. Its primary commercial purpose is to shield employers from liability exposure and productivity losses when employees face emergencies abroad. Annual multi-trip policies now capture the dominant share of premium volume as corporations abandon single-trip ad hoc purchasing. Medical expenses coverage generates the thickest margin pool due to escalating healthcare costs in North America and Western Europe. Online platforms represent the fastest-growing distribution channel, displacing traditional broker relationships among SMEs and mid-market firms.
Regulatory oversight spans the EU's Insurance Distribution Directive mandating suitability assessments for commercial buyers, the UK's Financial Conduct Authority conduct standards for policy disclosures, and state-level insurance commissioners in the United States enforcing reserve adequacy for travel medical benefits. These frameworks elevate compliance costs for cross-border underwriters while creating barriers for unlicensed digital entrants. Stakeholders must monitor evolving biometric data privacy rules as wearable health monitoring integrates into dynamic premium pricing models.
Market Dynamics
Corporate procurement centralization is compressing distribution margins as Fortune 500 buyers negotiate master policies covering thousands of employees under single global contracts.
Growth Catalysts
- EU Digital Operational Resilience Act:Mandates upgraded cyber underwriting standards for business travelers, forcing insurers to enhance coverage scope and premium pricing power.
- Medical evacuation infrastructure:Specialized air ambulance networks in North America and Western Europe enable higher coverage limits that command thicker margins.
- Multinational employer mandates:US-based corporations now require comprehensive overseas assignment coverage as standard employment terms.
Market Restraints
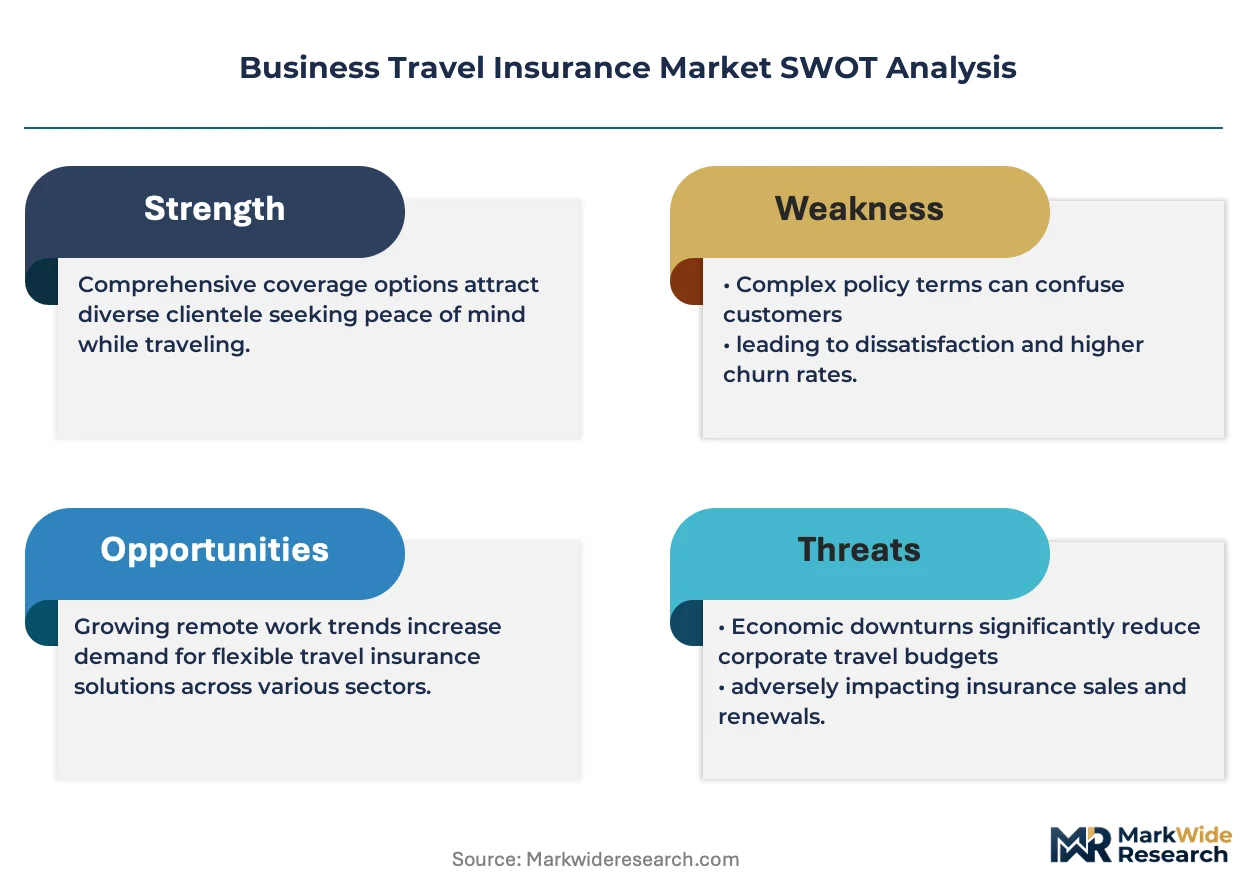
- Healthcare cost volatility:Escalating North American and Western European medical expenses compress loss ratios and reserve adequacy requirements.
- Broker margin compression:Centralized procurement eliminates ad hoc single-trip purchasing that historically generated higher commission rates.
- Regulatory fragmentation:Divergent state-level insurance commissioners in the United States create compliance complexity for cross-border underwriters.
Strategic Opportunities
- Wearable health monitoring convergence:Biometric data streams enable dynamic premium pricing models that align risk assessment with real-time traveler health status.
- SME digital channel penetration:Online platforms displace traditional broker relationships among mid-market firms underserved by corporate master policies.
- War-risk coverage specialization:Unstable region executive protection creates demand for terrorism and political violence endorsements.
Industry Challenges
- Biometric data privacy compliance:Evolving GDPR and state-level privacy rules create uncertainty around wearable-derived pricing algorithms.
- Legacy system integration:Dynamic pricing engines require costly API connectivity with established policy administration platforms.
- 24-hour assistance scaling:Multi-language hotline infrastructure demands specialized talent recruitment across time zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Business Travel Insurance Market |
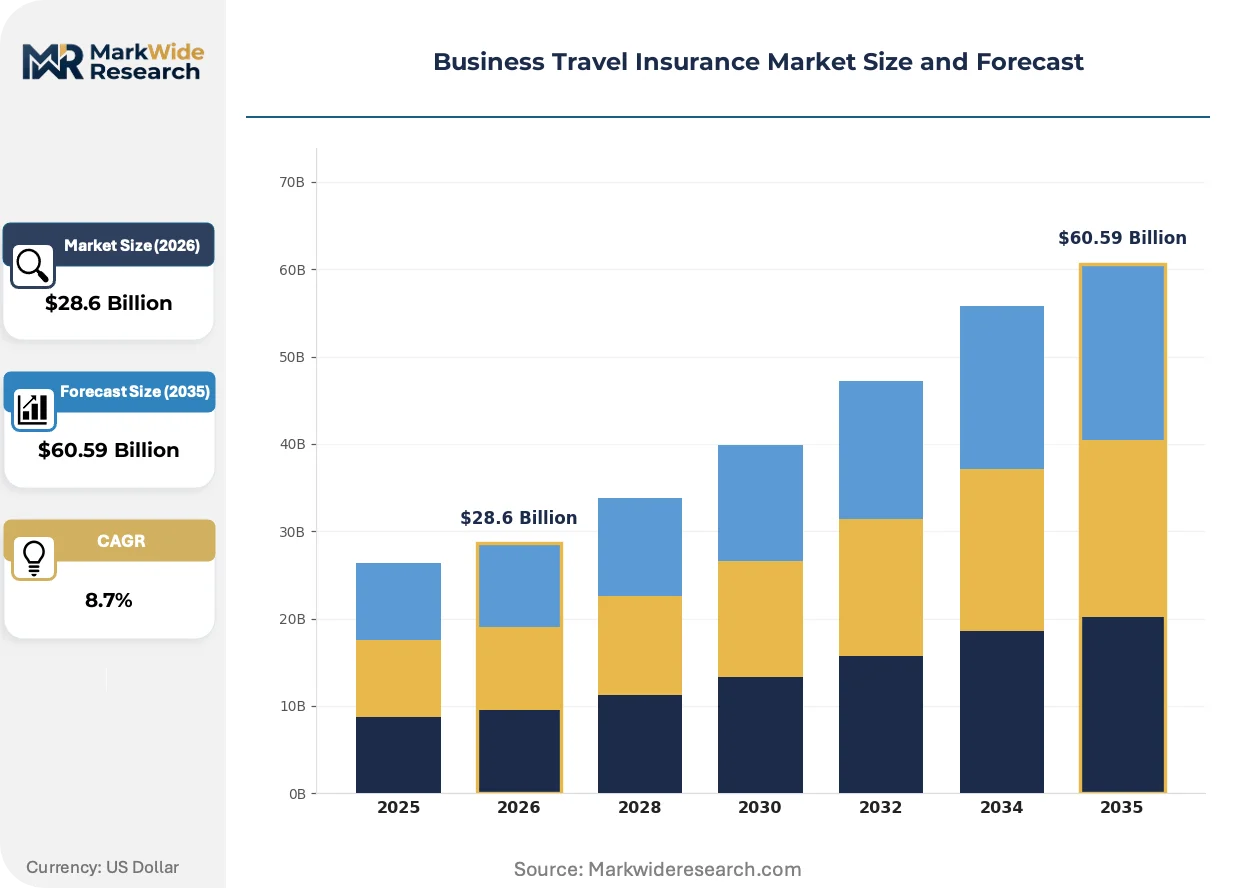
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Single Trip, Annual Multi-Trip, Group Policy, Long-Term Policy Coverage Options: Trip Cancellation, Medical Expenses, Personal Liability, Baggage Loss Target Customer: Frequent Travelers, Corporations, SMEs, Travel Agencies Distribution Channel: Online Platforms, Agents, Brokers, Direct Sales |
| Companies Covered | Allianz, AIG, Chubb, AXA, Berkshire Hathaway Specialty Insurance, Travel Guard, Cigna, Seven Corners Inc., Zurich Insurance Group Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Business Travel Insurance Market Emerging Trajectories
Technology convergence with health monitoring devices is enabling real-time risk assessment models that reshape underwriting economics and traveler safety protocols.
Telematics-enabled wearables is integrating continuous vital sign monitoring into policy pricing structures. Corporate risk managers at technology and financial services firms are piloting these programs for high-frequency travelers. The technology is integrating medical underwriting with trip-specific risk profiles, compressing traditional static rating models.
GDPR Article 9 restrictions on health data processing are tightening consent requirements for biometric-driven insurance products. Insurers must now demonstrate explicit traveler authorization for continuous monitoring during trips. European multinational employers are responding by segregating data processing across EU and non-EU policy blocks.
Annual multi-trip subscription models are displacing per-journey purchasing among mid-market professional services firms. Traditional brokers lose attachment as direct digital platforms capture renewal relationships. The shift is most visible in United Kingdom and German markets where SME density supports platform economics.
Business Travel Insurance Market Segmentation
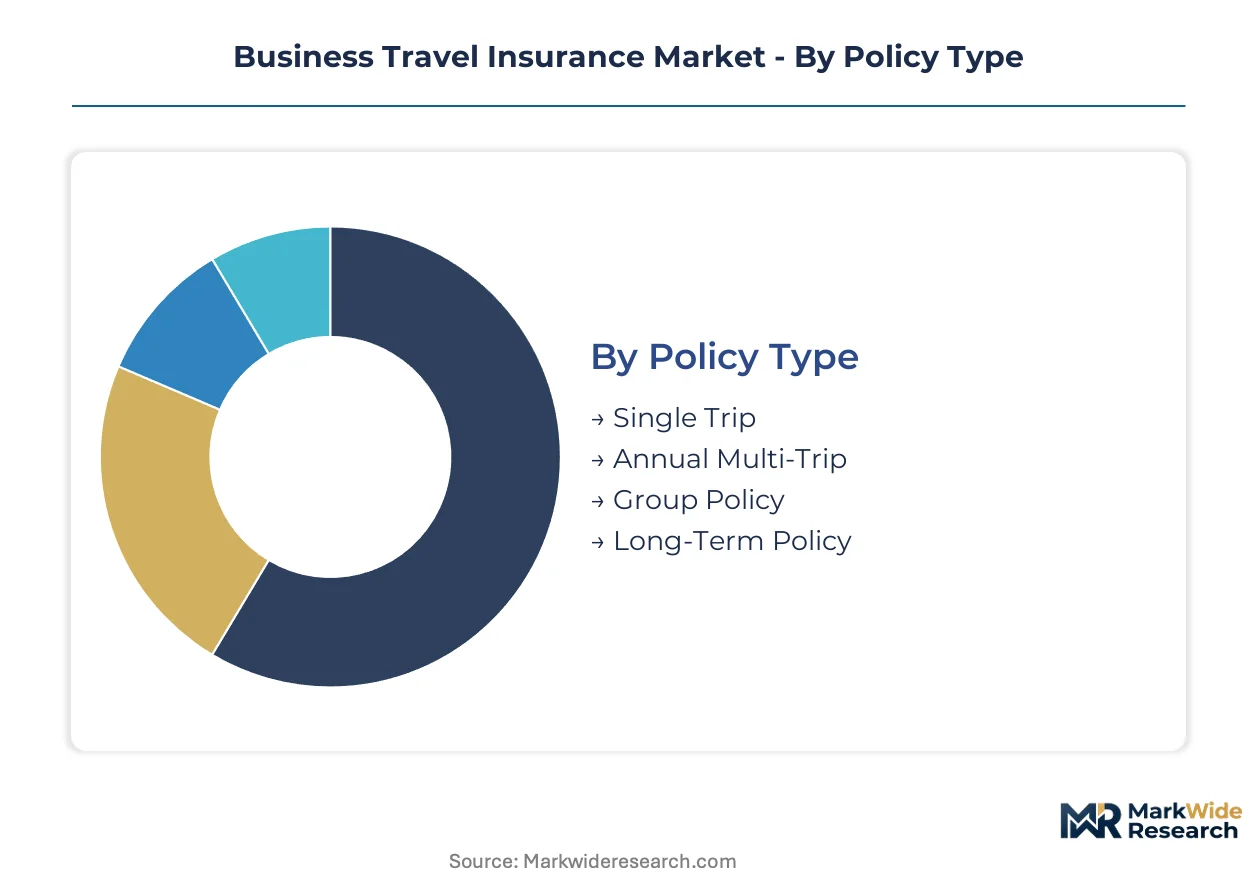
Segmentation in business travel insurance determines pricing architecture and distribution strategy. Policy structure, coverage depth, and buyer scale create distinct margin pools that reshape competitive positioning across underwriters.
Policy Type:
Corporate procurement cycles are driving replacement of single-trip ad hoc purchasing with annual master contracts that reduce administrative burden and negotiate volume discounts.
- Single Trip:Covers individual journeys with fixed departure and return dates. Demand concentrates among SMEs and occasional business travelers in Germany and France where procurement centralization lags.
- Annual Multi-Trip:Provides unlimited coverage within a 12-month window for frequent travelers. Fortune 500 procurement teams in the United States mandate these programs for cost predictability and streamlined claims processing.
- Group Policy:Insures employee cohorts under unified terms. Corporate HR departments in Japan leverage these for rotational assignment programs.
- Long-Term Policy:Extends coverage beyond standard annual windows for extended overseas postings. Expatriate management firms in the United Kingdom source these for 18-36 month executive relocations.
Annual Multi-Trip sits at the top of the volume ranking, with Group Policy climbing the fastest.
Coverage Options:
Cost tier differentiation separates premium-priced medical evacuation modules from commoditized baggage protection, creating margin stratification across coverage bundles.
- Trip Cancellation:Reimburses non-refundable deposits when business travel aborts. Conference-heavy sectors in Singapore and Hong Kong drive concentration as event cancellation risks escalate.
- Medical Expenses:Covers emergency treatment and hospitalization abroad. North American healthcare cost inflation pushes employers toward higher limit tiers, thickening underwriter margins.
- Personal Liability:Protects against third-party injury or property damage claims. Legal services firms in London and New York mandate this for partner-level travelers.
- Baggage Loss:Compensates for equipment and personal effects. Technology sector road warriors in South Korea prioritize this for high-value device transport.
Medical Expenses dominates premium volume, with Trip Cancellation expanding most quickly.
Target Customer:
Customer scale determines service intensity and pricing power, with multinational employers extracting steeper discounts than fragmented SME buyers.
- Frequent Travelers:Individual high-velocity road warriors purchasing personal annual policies. Management consultants based in Switzerland and the Netherlands self-procure these outside corporate programs.
- Corporations:Large employers with centralized travel risk management functions. US-based multinationals now mandate comprehensive overseas coverage as standard employment terms.
- SMEs:Mid-market firms with 50-500 employees and limited procurement specialization. German Mittelstand companies are migrating from broker relationships to direct digital platforms.
- Travel Agencies:Intermediaries bundling insurance with flight and hotel bookings. Corporate travel management companies in India embed coverage into managed travel programs.
Corporations command the largest premium pool, with SMEs gaining share fastest through digital channel migration.
Distribution Channel:
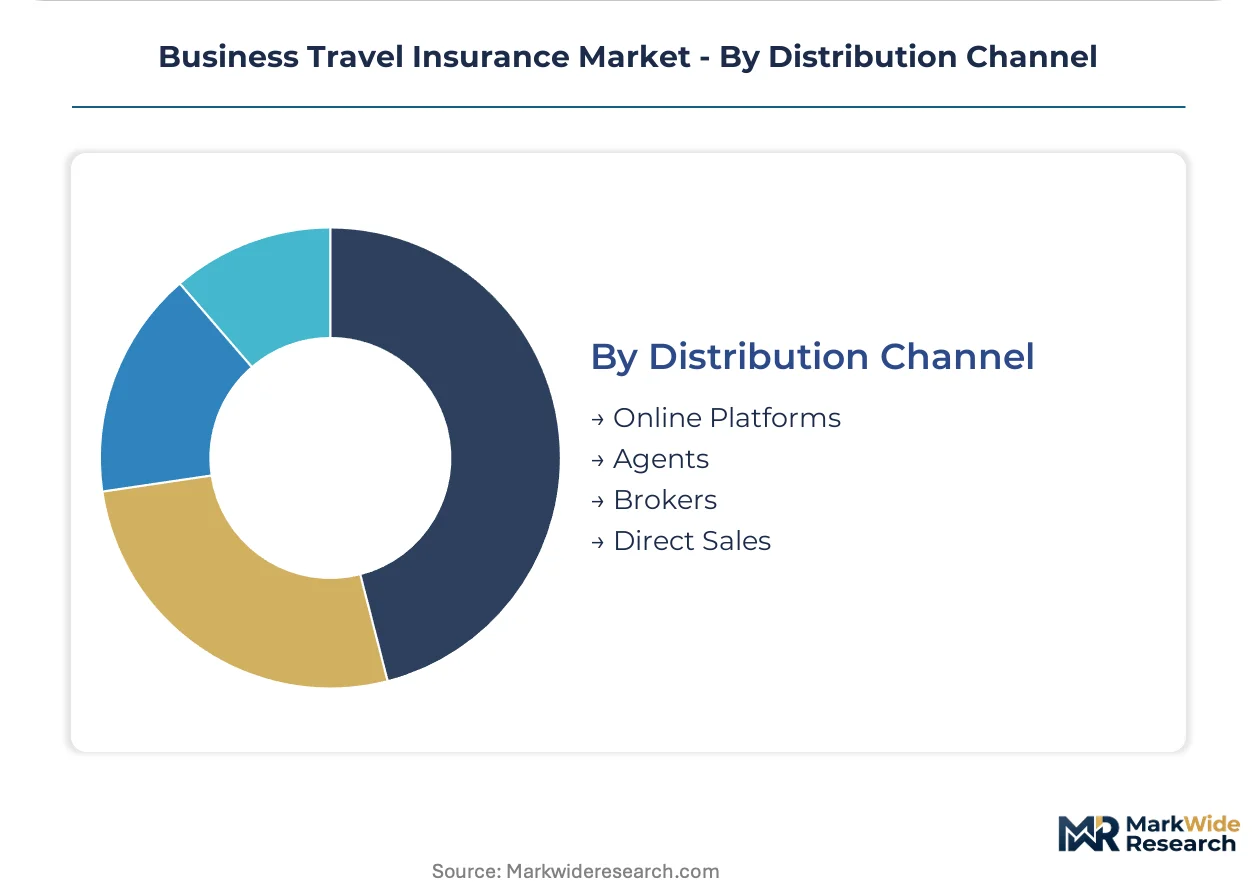
Channel economics are restructuring as online platforms displace traditional intermediaries, compressing commission structures and capturing renewal relationships.
- Online Platforms:Direct digital purchasing with instant quote-to-bind functionality. UK and German SME markets show the steepest platform adoption curves.
- Agents:Captive representatives of single underwriters with limited product range. Japanese corporate buyers still favor agent relationships for claims advocacy.
- Brokers:Independent intermediaries negotiating multi-carrier comparisons. Fortune 500 procurement teams compress broker margins through centralized RFP processes.
- Direct Sales:Underwriter-employed account executives targeting large corporate accounts. AIG and Chubb deploy dedicated teams for war-risk and executive coverage programs.
Online Platforms are expanding most quickly, while Direct Sales retains the highest value-per-policy ratio.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States extracts deeper volume discounts through centralized procurement than Germany, where Mittelstand fragmentation sustains broker relationships. Japan maintains agent-centric distribution despite digital pressure elsewhere. The United Kingdom and Singapore diverge in regulatory stringency around health data consent.
United States
Fortune 500 procurement teams mandate annual multi-trip master policies covering thousands of employees simultaneously. State-level insurance commissioners enforce reserve adequacy for travel medical benefits under divergent standards. New York and Chicago host the densest concentrations of corporate risk management functions negotiating these contracts.
Germany
Mittelstand companies with 50-500 employees sustain demand for single-trip policies where procurement centralization lags. The Insurance Distribution Directive mandates suitability assessments for commercial buyers across EU member states. Frankfurt and Munich clusters see accelerating migration from broker relationships to direct digital platforms.
United Kingdom
Professional services firms drive adoption of annual multi-trip subscription models displacing per-journey purchasing. The Financial Conduct Authority enforces conduct standards for policy disclosures affecting underwriter compliance costs. London's insurance hub concentrates claims concierge services targeting C-suite travelers.
Japan
Corporate HR departments leverage group policies for rotational assignment programs covering expatriate cohorts. METI oversight shapes product standardization for commercial insurance distribution. Tokyo and Osaka maintain agent-favored purchasing patterns resistant to platform displacement seen elsewhere.
Singapore
Conference-heavy sectors generate concentrated demand for trip cancellation coverage as event cancellation risks escalate. The country's national financial regulator monitors solvency standards for travel underwriters operating across ASEAN markets. The city-state's business district hosts regional headquarters of multinational insurers competing for corporate mandates.
Business Travel Insurance Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The structure consolidates around large multinational underwriters with captive reinsurance capacity and global assistance networks. Three archetypes dominate: integrated financial services groups with insurance divisions, specialty commercial underwriters with war-risk expertise, and digital-first platforms targeting SME displacement. Competitive moves concentrate on M&A for assistance infrastructure and geographic expansion into underserved Asian markets.
Within the integrated financial services tier, Allianz and AXA exemplify conglomerate diversification into business travel lines. AIG occupies a position representing specialty commercial underwriters with terrorism and political violence capabilities. Among digital-focused entrants, Seven Corners Inc. anchors the platform archetype competing for mid-market share.
| Leading Market Players |
|---|
| Allianz |
| AIG |
| Chubb |
| AXA |
| Berkshire Hathaway Specialty Insurance |
| Travel Guard |
| Cigna |
| Seven Corners Inc. |
| Zurich Insurance Group Ltd |
| Others |
Supply Flow & Price Mechanics
Medical inflation indices in North America and Western Europe cascade through reinsurance treaty renewals into premium rate floors across annual multi-trip corporate programs. This cost transmission mechanism compresses margins for underwriters lacking captive reinsurance capacity while amplifying pricing power for integrated carriers with vertical cost control.
Pricing Analysis
Capacity additions in Ireland and Bermuda are reshaping price floors for medical evacuation coverage as new air ambulance operators enter specialized networks. Three-tier pricing structure across premium concierge, standard assistance, and economy digital tiers segments buyer willingness-to-pay by service intensity. Pricing pressure stems from Fortune 500 procurement teams consolidating thousands of employees into single master contracts with volume discounts. SMEs exhibit highest price sensitivity, while C-suite executive programs demonstrate inelastic demand for white-glass claims services.
Supply Chain Analysis
Multilingual assistance coordinator availability in Philippines, India, and Portugal anchors 24-hour hotline infrastructure scaling across time zones. Underwriting capacity draws from London, Zurich, and Singapore as primary domiciles for travel insurance risk acceptance. Single-source vulnerability concentrates in specialized air ambulance networks serving remote extraction zones. Distribution runs through broker-mediated corporate RFP processes for large accounts, with direct digital platforms capturing SME renewal relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Digital Operational Resilience Act compounds demand for enhanced cyber coverage as mandatory procurement triggers across multinational employers. This regulatory milestone elevates baseline coverage requirements and premium pricing power simultaneously.
For Market Incumbents: Hedge against broker margin compression by deepening captive reinsurance capacity and acquiring assistance infrastructure in Southeast Asia. Allianz-style vertical integration into air ambulance networks defends pricing power as procurement centralization intensifies. Counter digital entrant threats through API-enabled dynamic pricing engines integrated with wearable health data streams. For New Entrants and Emerging Players: Launch via direct digital platforms targeting German Mittelstand companies migrating from traditional broker relationships. SME segment penetration offers lowest competitive density against established corporate master policy dominance. White-space opportunity concentrates in wearable-enabled dynamic pricing pilots for technology sector road warriors. For Investors and Strategic Acquirers: Asymmetric upside sits with specialty assistance infrastructure providers possessing multilingual coordinator networks and air ambulance dispatch capabilities. Five-to-ten year viability favors targets with established relationships in emerging market extraction zones. Monitor EU biometric data privacy enforcement actions as inflection indicator for wearable-driven pricing model regulatory risk.| Strategic Initiative | Industry Significance |
|---|---|
| Assistance Infrastructure Acquisition | Captive air ambulance networks in Southeast Asia reduce third-party dependency and thicken evacuation coverage margins. |
| Wearable Health Integration | API connectivity with biometric data streams enables real-time risk assessment and dynamic premium adjustment models. |
| Corporate Master Policy Expansion | Fortune 500 procurement consolidation demands scalable underwriting capacity and streamlined multi-country claims processing. |
| Cyber Coverage Enhancement | EU Digital Operational Resilience Act mandates upgraded business traveler protection, creating premium pricing power. |
| SME Digital Platform Buildout | Direct online distribution captures mid-market firms abandoning broker relationships in United Kingdom and German markets. |
Methodological Framework
Multiple input streams — corporate risk manager interviews, reinsurance broker consultations, assistance provider operational data, and regulatory filing analysis — were reconciled to construct market estimates. Primary fieldwork engaged underwriting executives at Lloyd's syndicates, procurement directors at multinational employers, and claims operations heads at major assistance companies. Secondary validation drew from EU Insurance Distribution Directive implementation reports, state insurance commissioner reserve adequacy filings, and air ambulance network capacity disclosures. Bottom-up premium volume estimates triangulated against top-down macroeconomic travel expenditure benchmarks.
Historical premium growth patterns cross-referenced against panel input from reinsurance pricing specialists and corporate buyer sentiment surveys shaped the projection framework. Segmentation modeling spanned policy type, coverage depth, buyer scale, and distribution channel across the analysis window. CAGRs derived from weighted average of scenario-based growth paths incorporating medical cost inflation assumptions and procurement centralization velocity. Industry-specific inputs included air ambulance network expansion timelines and wearable health device penetration curves in corporate wellness programs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt biometric data privacy regulatory shifts or sustained healthcare cost volatility. Material deviation in EU enforcement posture toward health data processing consent requirements warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Identity Theft Insurance Market
Insurance
Financial Protection Market
Insurance
Europe Bancassurance Market
Insurance
Agriculture Insurance Market
Insurance
Spain Group Health Insurance Market
Insurance
US Insurance Third-Party Administrator Market
Insurance
Singapore Business Income Insurance Market
Insurance
Netherlands Property and Casualty Insurance Market
Insurance
United Kingdom Car Insurance Market
Insurance
Title Insurance Market
Insurance
Green Insurance Market
Insurance
India Electronic Gadget Insurance Market
Insurance
UK Dental Insurance Market
Insurance
Usage-Based Insurance (UBI) Market
Insurance
Asia-Pacific AI in Insurance Market
Insurance
Global Fine Art Insurance Market