

Package Pumping Station Market Size, Share, and Industry Trends Forecast 2026-2036
Package Pumping Station Market Insights
Buyer concentration among municipal water utilities is restructuring procurement patterns across the package pumping station landscape. Grundfos leverages its vertical integration into pump manufacturing and controls to sustain pricing power in European infrastructure tenders. Xylem anchors its position through digital monitoring platforms that integrate with its package station hardware, while KSB competes on engineering depth in high-head wastewater applications.
A package pumping station is a prefabricated, factory-built system housing pumps, controls, valves, and piping within a single enclosed structure, typically designed for flow rates between 10 and 2,000 liters per second and discharge heads up to 100 meters. These systems serve as decentralized lifting and transfer points for wastewater, stormwater, and potable water in areas where gravity-fed infrastructure proves impractical or cost-prohibitive. Submersible pump configurations dominate municipal wastewater management due to their flood-resilience and reduced footprint, while compact modular installations represent the fastest-growing installation category as utilities prioritize rapid deployment and minimal civil works. Centrifugal pumps remain the mature, high-volume product segment, though positive displacement variants capture margin pools in sludge and high-solids applications where clogging resistance commands premium positioning.
The EU Urban Wastewater Treatment Directive and national implementations through regulators such as Germany's KBA-adjacent environmental enforcement and France's ANSM-linked water quality frameworks mandate nutrient removal and energy efficiency in new pumping infrastructure, directly shaping product specifications and market access conditions. EPA consent decrees in the United States accelerate replacement timelines for aging combined sewer overflow systems, creating compliance-driven demand for containerized and skid-mounted emergency bypass stations. Stakeholders must monitor how tightening energy efficiency standards and embodied carbon reporting requirements reshape supplier qualification criteria and lifecycle cost calculations in utility procurement frameworks.
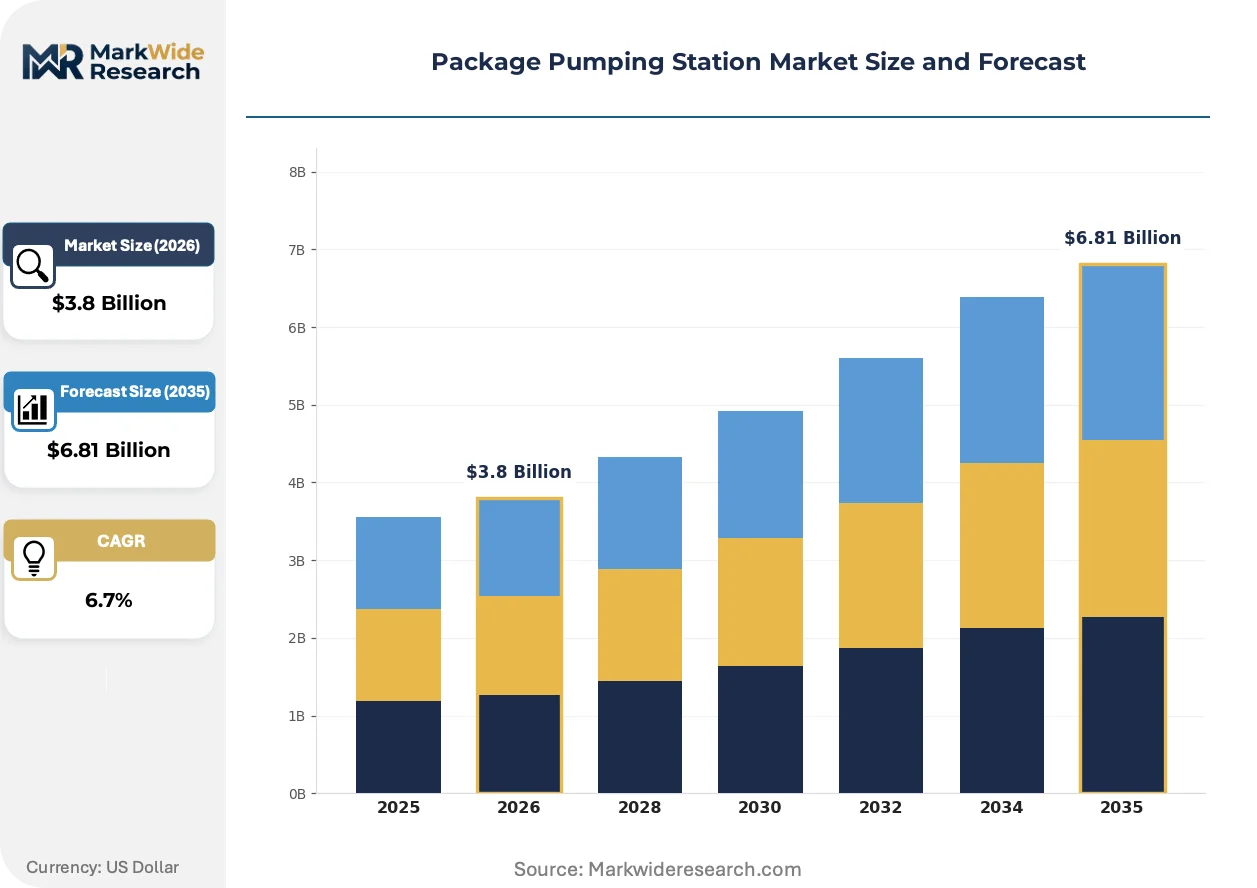
Market Dynamics
Modular factory-built systems are compressing project timelines for municipal utilities facing combined sewer overflow mandates and aging infrastructure replacement cycles across Germany, France, and the United Kingdom.
Growth Catalysts
- EU Urban Wastewater Treatment Directive revision:Tightened effluent standards for nitrogen and phosphorus removal are mandating pump station upgrades with integrated nutrient removal capabilities, forcing utilities toward prefabricated systems with factory-tested performance guarantees.
- Submersible pump configurations:Flood-resilient wet-well designs with submersible motor technology eliminate separate dry-well construction, cutting civil works costs by half for utilities in flood-prone catchments.
- Stormwater management intensity:Climate-driven rainfall pattern shifts across Northern European river basins are accelerating deployment of compact lift stations for urban retrofit projects where gravity drainage proves infeasible.
Market Restraints
- Specialized polymer supply concentration:High-density polyethylene and fiberglass-reinforced plastic resins for wet-well fabrication depend on petrochemical feedstock pricing tied to volatile natural gas markets, compressing margins for European fabricators.
- Electromechanical component lead times:Variable frequency drives and intelligent pump controllers face 16-24 week delivery schedules from concentrated Asian semiconductor foundries, delaying project commissioning.
- Site-specific hydraulic constraints:Each installation requires custom inlet invert elevations and discharge head calculations that resist full standardization, limiting economies of scale in design engineering.
Strategic Opportunities
- Digital twin integration:Real-time hydraulic modeling converging with IoT sensor networks enables predictive maintenance contracts that transform capital equipment sales into recurring revenue streams for system integrators.
- Containerized emergency bypass stations:EPA consent decree enforcement in the United States creates demand for rapid-deploy skid-mounted systems during main station rehabilitation, opening a specialized rental and lease market.
- Positive displacement pump variants:Progressive cavity and rotary lobe configurations for high-solids sludge transfer command premium positioning in industrial wastewater and biogas feedstock applications where clogging resistance justifies higher first cost.
Industry Challenges
- Controls integration complexity:Municipal SCADA protocols vary across water authority territories, requiring custom communication gateway programming that extends commissioning timelines and strains field service capacity.
- Skilled installation labor scarcity:Certified wet-well jointing and confined-space entry qualifications limit the contractor base capable of executing turnkey installations, creating bottlenecks during peak construction seasons.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Package Pumping Station Market Trends and Innovations
Intelligent automation and embedded carbon accounting are redefining how utilities evaluate pumping infrastructure, shifting procurement criteria from first cost to lifecycle performance and embodied emissions.
Dry-pit submersible pump arrangements are overtaking traditional dry-well designs in European municipal tenders. These systems combine flood-resilient motor cooling with above-grade maintenance access, eliminating separate dry-well excavation and ventilation requirements. German water utilities in the Ruhr industrial corridor are specifying this configuration for 80% of new lift station projects, compressing civil construction schedules from twelve weeks to four.
REACH chemical registration and the EU Green Deal's embodied carbon reporting mandates are reshaping material specifications for wet-well fabrication. Composite manufacturers must now disclose resin content and end-of-life recyclability, favoring suppliers with verified recycled glass fiber supply chains. French utilities under ANSM-linked water quality frameworks are prioritizing stations with Environmental Product Declarations, creating qualification barriers for uncertified fabricators.
Performance-based service contracting is displacing traditional equipment-only procurement in United Kingdom water company frameworks. Ofwat's price review mechanism incentivizes totex optimization, pushing Thames Water and United Utilities toward 15-year availability contracts where suppliers guarantee pump run-hours and energy consumption. This shifts capital risk to OEMs while locking in long-term spare parts and remote monitoring revenue streams.
Package Pumping Station Market Segmentation
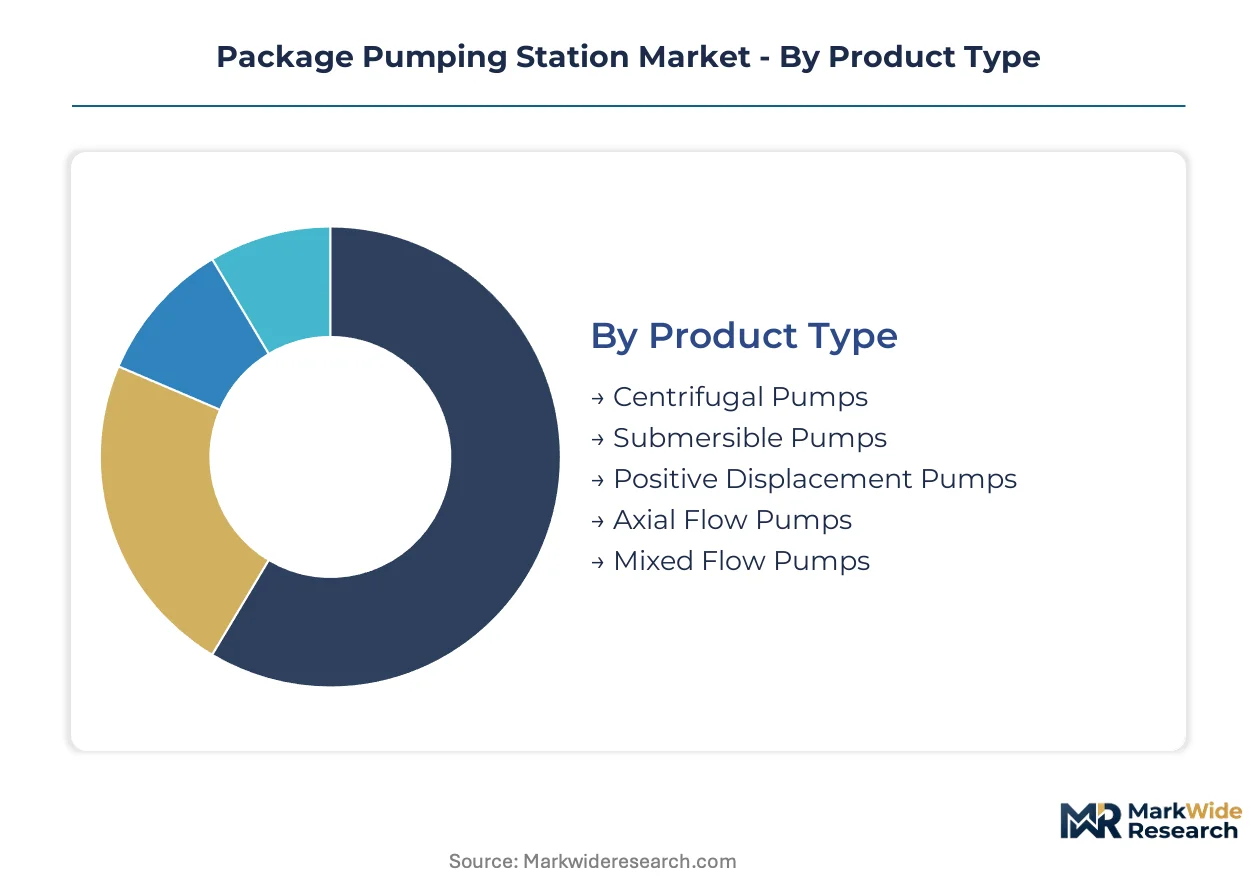
Package pumping stations serve heterogeneous demand profiles across municipal infrastructure, agricultural operations, and emergency services. Segmentation reveals where capital deployment concentrates and which configurations command premium positioning through technical differentiation.
Product Type:
Capital intensity varies sharply across pump technologies, with submersible configurations requiring integrated motor-sealing systems and positive displacement variants demanding precision-manufactured rotors and stators.
- Centrifugal Pumps:Radial-flow impeller designs dominate high-volume wastewater transfer with discharge heads up to 100 meters. German municipal utilities specify these for 60% of new lift station capacity, driven by EU energy efficiency mandates under the Ecodesign Directive.
- Submersible Pumps:Flood-resilient wet-well configurations eliminate separate dry-well construction, halving civil works costs. Demand concentrates in France's ANSM-linked water quality frameworks where combined sewer overflow compliance accelerates retrofit deployment.
- Positive Displacement Pumps:Progressive cavity and rotary lobe architectures command premium positioning in high-solids sludge applications.
- Axial Flow Pumps:Propeller-style designs serve low-head, high-capacity stormwater management in Dutch polder drainage systems.
- Mixed Flow Pumps:Hybrid impeller geometry bridges axial and centrifugal performance for variable head conditions.
Most installed capacity flows through centrifugal pumps. Expansion is steepest in submersible configurations.
Application:
Application segmentation tracks regulatory enforcement intensity, with wastewater management facing the most stringent effluent standards and fire protection governed by prescriptive safety codes.
- Wastewater Management:Municipal lift stations for sewage and stormwater transfer constitute the volume anchor. EPA consent decrees in the United States and EU Urban Wastewater Treatment Directive revisions force infrastructure replacement cycles.
- Municipal Water Supply:Potable water booster stations require NSF-certified materials and dual-redundant pump arrangements. German water utilities in the Ruhr corridor prioritize these for pressure zone management.
- Irrigation Systems:Agricultural deployment favors solar-powered submersible arrays in water-stressed Mediterranean regions.
- Construction Dewatering:Temporary bypass and groundwater control applications favor rental-oriented skid-mounted configurations.
- Fire Protection:NFPA-compliant jockey pump systems maintain static pressure in commercial and industrial sprinkler networks.
Wastewater management absorbs the largest share of annual investment. Steepest expansion trajectory belongs to municipal water supply as aging distribution networks require pressure augmentation.
Installation Type:
Installation economics divide between civil-works-heavy underground systems and factory-built alternatives that externalize construction risk to equipment suppliers.
- Compact Modular:Factory-integrated pump, control, and valve assemblies compress commissioning timelines to days rather than months. United Kingdom water companies under Ofwat's totex optimization framework specify these for 70% of urban retrofit projects.
- Underground:Traditional wet-well and dry-well configurations retain share in greenfield developments with available excavation budgets.
- Above Ground:Elevated installations serve temporary or flood-avoidance requirements in coastal zones.
- Skid-Mounted:Pre-piped base frames enable rapid relocation for construction dewatering and emergency bypass operations.
- Containerized:ISO-dimensioned enclosures support military, humanitarian, and rapid-deployment municipal applications.
Compact modular systems are gaining share fastest. Underground installations retain the largest installed base.
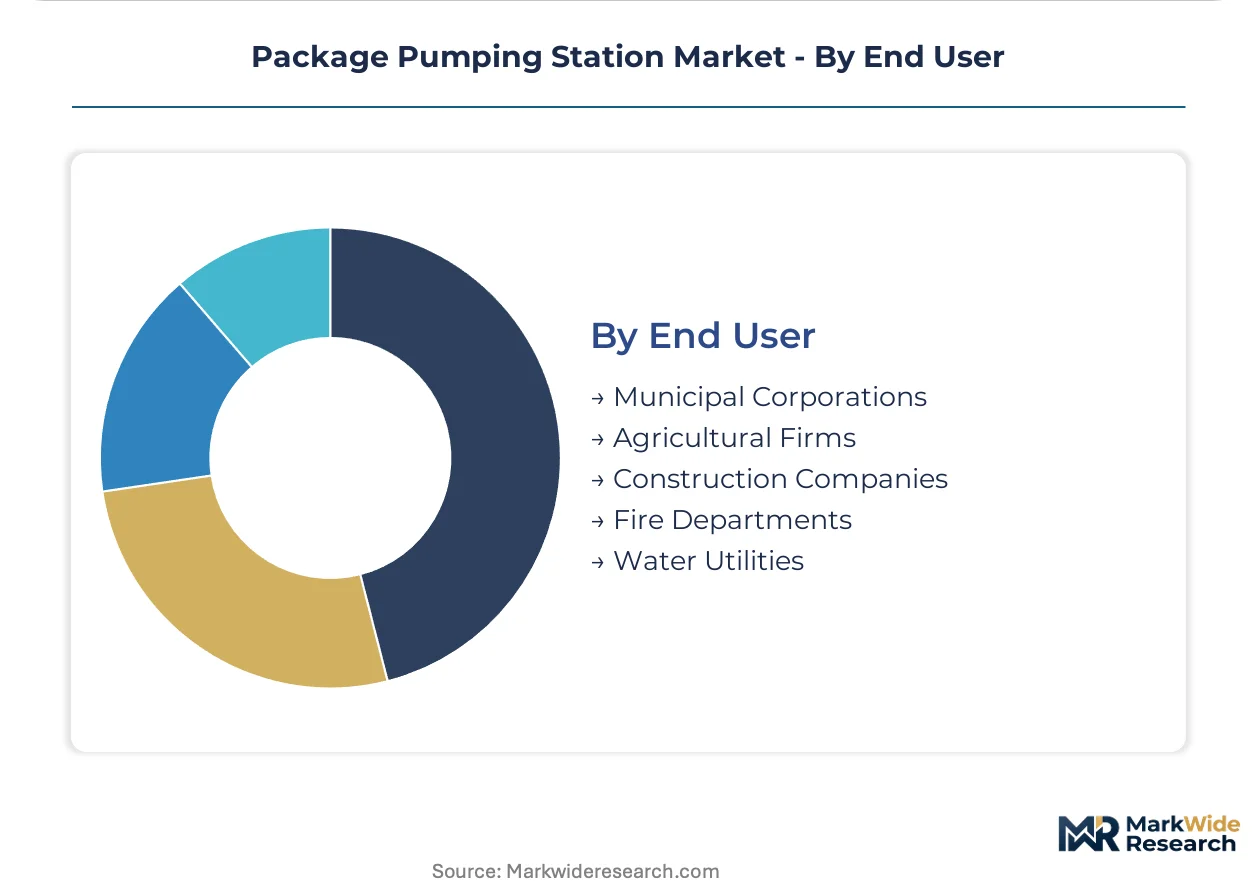
End User:
Buyer sophistication and procurement scale vary dramatically, from municipal water utilities negotiating 15-year availability contracts to agricultural firms purchasing on first-cost criteria.
- Municipal Corporations:City-level drainage authorities in Germany's combined sewer networks drive demand for integrated nutrient removal capabilities. REACH chemical registration and EU Green Deal carbon reporting reshape supplier qualification.
- Water Utilities:Regional water companies in England and Wales prioritize performance-based contracting with guaranteed energy consumption and pump availability metrics.
- Agricultural Firms:Irrigation cooperatives in Spain and Italy favor standardized submersible configurations with minimal automation.
- Construction Companies:Rental-oriented procurement dominates temporary dewatering applications.
- Fire Departments:Municipal safety authorities specify NFPA-compliant pressure maintenance systems for institutional buildings.
Municipal corporations command the largest procurement volumes. Water utilities are shifting fastest toward outcome-based contracting models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's combined sewer replacement cycles outpace France's retrofit intensity, though both markets operate under the same EU regulatory umbrella. Municipal procurement in the United Kingdom diverges toward performance contracting, while the United States responds to federal consent decree enforcement.
Germany
Ruhr industrial corridor utilities specify dry-pit submersible configurations for 80% of new lift station projects, compressing civil construction timelines. KBA-adjacent environmental enforcement tightens effluent standards for nitrogen and phosphorus removal. North Rhine-Westphalia's aging combined sewer networks drive replacement demand for integrated nutrient removal capabilities.
France
ANSM-linked water quality frameworks accelerate combined sewer overflow compliance through compact lift station deployment. EU Urban Wastewater Treatment Directive revisions mandate factory-tested performance guarantees for prefabricated systems. Paris metropolitan drainage authorities prioritize stations with Environmental Product Declarations in procurement frameworks.
United Kingdom
Ofwat's totex optimization mechanism pushes Thames Water and United Utilities toward 15-year availability contracts with guaranteed pump run-hours. Water companies specify compact modular installations for 70% of urban retrofit projects. England and Wales regional utilities lock in long-term spare parts and remote monitoring revenue streams through outcome-based contracting.
United States
EPA consent decrees accelerate replacement timelines for aging combined sewer overflow systems in legacy industrial cities. Federal enforcement creates compliance-driven demand for containerized and skid-mounted emergency bypass stations. Northeast and Midwest municipal utilities face compressed project timelines for infrastructure rehabilitation.
Netherlands
Polder drainage systems require low-head, high-capacity stormwater management solutions for climate-driven rainfall pattern shifts. National water management authorities specify axial flow pump configurations for variable head conditions. Dutch delta engineering clusters drive innovation in flood-resilient wet-well designs for below-sea-level catchments.
Package Pumping Station Market Competitive Landscape
European producers anchor the premium engineering tier; Asian fabricators hold cost-optimized positions for standardized configurations. Market structure consolidates around pump OEMs with captive controls capabilities and specialized wet-well fabricators with polymer processing expertise. Two strategic archetypes dominate: vertically integrated pump manufacturers with in-house production of motors and variable frequency drives, and modular system integrators outsourcing electromechanical components. Competitive moves concentrate on backward integration into semiconductor sourcing for intelligent controllers and geographic expansion through local assembly partnerships.
Within the integrated pump manufacturer tier, Grundfos and Xylem occupy positions defined by digital platform integration and factory-tested performance guarantees. KSB anchors the high-head wastewater application segment through engineering depth. These three companies exemplify how European pump OEMs leverage captive supply of critical components to sustain pricing power in municipal infrastructure tenders.
| Leading Market Players |
|---|
| Grundfos |
| Xylem |
| Siemens |
| ABB |
| Wilo |
| KSB |
| Sulzer |
| NOV |
| Excel Fluid Group |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap fabricators in Germany's Ruhr industrial corridor anchor wet-well polymer processing, translating captive resin compounding capabilities into pricing discipline that resists commoditization despite Asian cost pressure. Their ownership structure insulates margin targets from quarterly earnings pressure, enabling selective participation in performance-guarantee tenders where factory-tested systems command premium positioning.
Pricing Analysis
Capacity additions in China's standardized submersible pump segment are reshaping price floors for economy-tier municipal contracts, compressing margins for European producers lacking captive motor manufacturing. Three-tier pricing structure across premium, standard, and economy levels separates NSF-certified potable water systems from EU Ecodesign-compliant wastewater configurations and basic stormwater lift stations. Cost compression in the economy tier intensifies because Chinese producers now bundle variable frequency drives at landed costs below European component sourcing. Agricultural irrigation cooperatives in Spain and Italy exhibit highest price sensitivity, while English and Welsh water utilities under Ofwat's totex framework prioritize lifecycle cost over first cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan's semiconductor foundries supplying intelligent pump controllers and variable frequency drive chipsets, creating 16-24 week delivery bottlenecks that cascade through European system integrators. Manufacturing gravity centers on Germany for precision pump casting, China for motor laminations and electronics assembly, and Italy for specialized mechanical seals. Wet-well fabrication draws from high-density polyethylene resin supply anchored in Belgian and Dutch petrochemical complexes, with fiberglass-reinforced plastic dependent on German and French glass fiber production. Tariff exposure on Chinese electromechanical components threatens margin stability for modular system integrators outsourcing controller production. Distribution runs through authorized OEM service networks for municipal utilities, direct manufacturer relationships for agricultural buyers, and rental fleet operators for construction dewatering applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
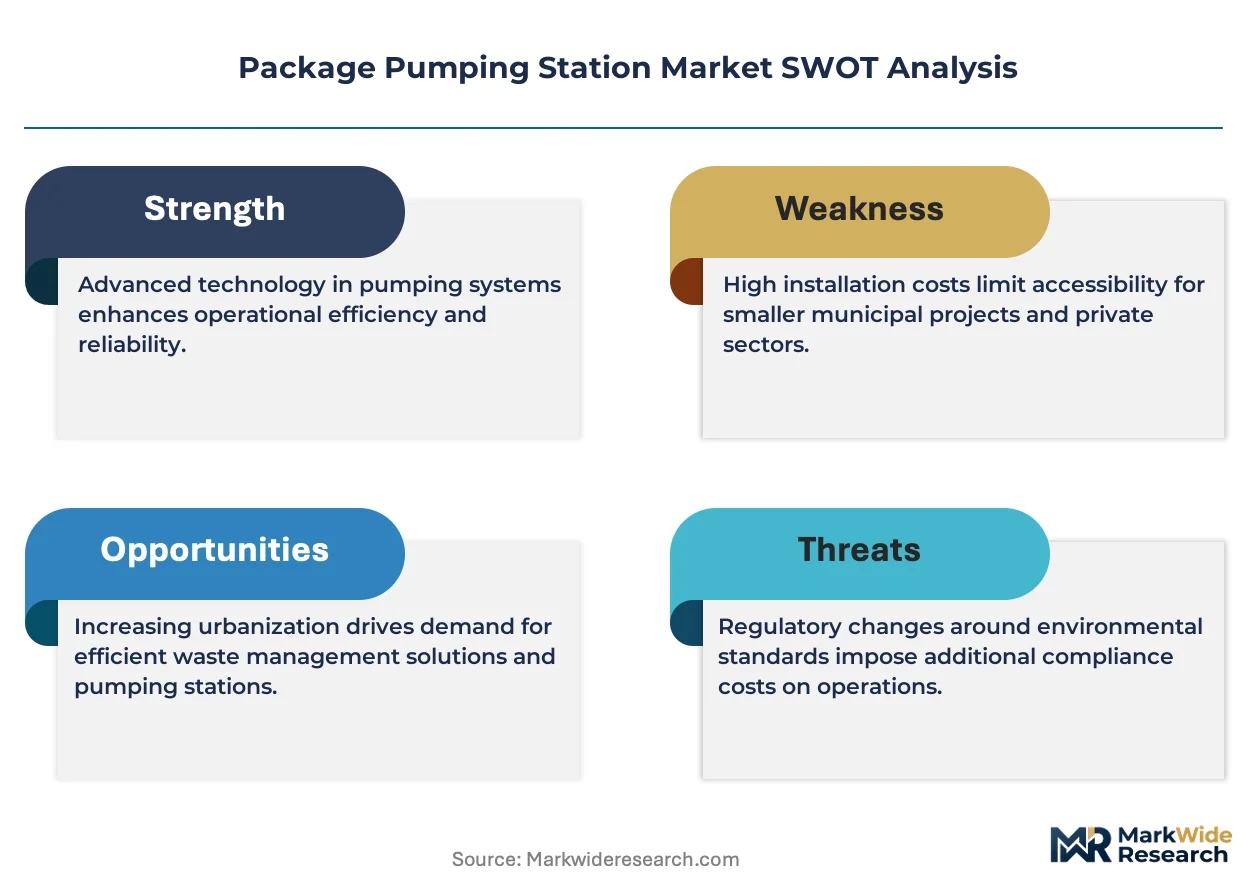
This market functions as a regulatory compounder where EU Urban Wastewater Treatment Directive revisions tighten effluent standards on predictable multi-year cycles, embedding replacement demand into municipal capital planning regardless of macroeconomic conditions.
For Market Incumbents: Deepen captive production of variable frequency drives and intelligent controllers to insulate margins from Asian semiconductor supply volatility. Secure long-term resin supply agreements with Belgian and Dutch petrochemical producers to hedge against natural gas price swings. The priority defensive move anchors factory-tested performance guarantees that lock out modular integrators lacking wet-well fabrication depth. For New Entrants and Emerging Players: EPA consent decrees in the United States open a window for containerized emergency bypass station specialization, a segment where rapid-deployment capabilities matter more than established brand recognition. Target skid-mounted rental configurations for construction dewatering and municipal rehabilitation projects. Pursue direct relationships with regional water authorities in England and Wales seeking totex-optimized availability contracts rather than equipment-only procurement. For Investors and Strategic Acquirers: Valuations sit cheapest among Italian and Spanish wet-well fabricators with polymer processing expertise but limited digital platform integration. Five-to-ten year viability hinges on EU Green Deal embodied carbon reporting mandates favoring suppliers with verified recycled glass fiber supply chains. Monitor Environmental Product Declaration adoption rates among French ANSM-linked procurement frameworks as the inflection signal for qualification barriers tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Sourcing | Intelligent controller production captive to Asian foundries exposes Grundfos and Xylem to margin compression. |
| Environmental Product Declaration Certification | French ANSM-linked frameworks now require verified recycled glass fiber content for wet-well procurement qualification. |
| Performance-Based Service Contracting | Thames Water and United Utilities lock 15-year availability guarantees that transform capital sales into recurring revenue. |
| Local Assembly Partnership Expansion | Modular integrators outsource electromechanical components to compress logistics costs in UK and German municipal tenders. |
| Digital Twin Platform Integration | Real-time hydraulic modeling with IoT sensor networks enables predictive maintenance contracts displacing break-fix service models. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with municipal water utility procurement directors, wet-well fabrication plant managers, pump OEM technical sales leads, and aftermarket service heads with secondary validation. Trade data from Eurostat and national customs authorities, EU Urban Wastewater Treatment Directive implementation reports, EPA consent decree filings, and Ofwat price review documentation anchored demand-side sizing. Bottom-up project pipeline analysis triangulated against top-down utility capital expenditure disclosures.
Segment-weighted modeling distributed value across centrifugal, submersible, positive displacement, axial flow, and mixed flow pump technologies, with cross-tabulation against wastewater management, municipal water supply, irrigation, construction dewatering, and fire protection applications. Installation type segmentation incorporated compact modular, underground, above ground, skid-mounted, and containerized configurations. CAGRs derived from regression analysis of historical procurement volumes against regulatory milestone timing, with sensitivity testing for polymer resin price volatility and semiconductor lead time fluctuations.
Revisions become necessary when EU Urban Wastewater Treatment Directive implementation timelines shift, EPA consent decree enforcement intensity changes, or petrochemical feedstock pricing experiences sustained dislocation. Forecasts embed assumptions about continued municipal preference for factory-tested performance guarantees and progressive adoption of embodied carbon reporting. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.