
 Jetting Pumps Market | 2026-2036
Jetting Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Jetting Pumps Market Outlook
The EU Green Deal is rebalancing procurement criteria across European water infrastructure, favoring energy-efficient jetting pump configurations in municipal tenders. Grundfos Holding A/S leverages its vertical integration in Denmark to sustain cost advantages in submersible electric systems. KSB SE & Co. KGaA anchors its position through specialized high-pressure product lines serving German industrial manufacturing. Wilo SE competes on compact hydraulic designs tailored to European wastewater retrofit projects.
Jetting pumps are fluid displacement devices that generate high-velocity discharge through converging nozzles, typically operating at pressure ratios exceeding 4:1 to entrain and transport secondary fluids or solids. These systems serve primary industrial functions in pipeline cleaning, reservoir aeration, and pressurized fluid injection where conventional centrifugal methods prove inadequate. Electric pumps dominate municipal water supply installations due to grid accessibility and operational precision, while hydraulic pumps retain structural importance in remote construction and fire fighting applications where power infrastructure remains unreliable. Submersible configurations represent the fastest-expanding product category as aquaculture operators in coastal zones seek corrosion-resistant immersion systems.
The US EPA enforces effluent limitations that compel wastewater facilities to upgrade jetting pump efficiency standards, while India's BIS mandates certification for high-pressure units deployed in industrial zones. REACH compliance in Europe restricts seal and gasket material composition, redirecting manufacturer sourcing toward fluoropolymer alternatives. Stakeholders must monitor evolving carbon-border adjustment mechanisms and their downstream impact on pump component supply chains.
Market Dynamics
Positive displacement technology is displacing legacy pneumatic systems across North American shale extraction, while EU Green Deal compliance timelines compress procurement cycles for municipal wastewater infrastructure in Germany and neighboring states.
Growth Catalysts
- EU Green Deal procurement mandates:German municipal wastewater plants face binding 2027 efficiency deadlines, accelerating tender volumes for energy-optimized jetting pump configurations.
- India's BIS certification expansion:Industrial corridors in Gujarat and Tamil Nadu require certified high-pressure units for textile processing clusters, creating standardized demand pools.
- Submersible corrosion-resistant designs:Coastal aquaculture operators in Vietnam and Indonesia specify immersion-grade stainless steel housings for continuous seawater exposure.
Market Restraints
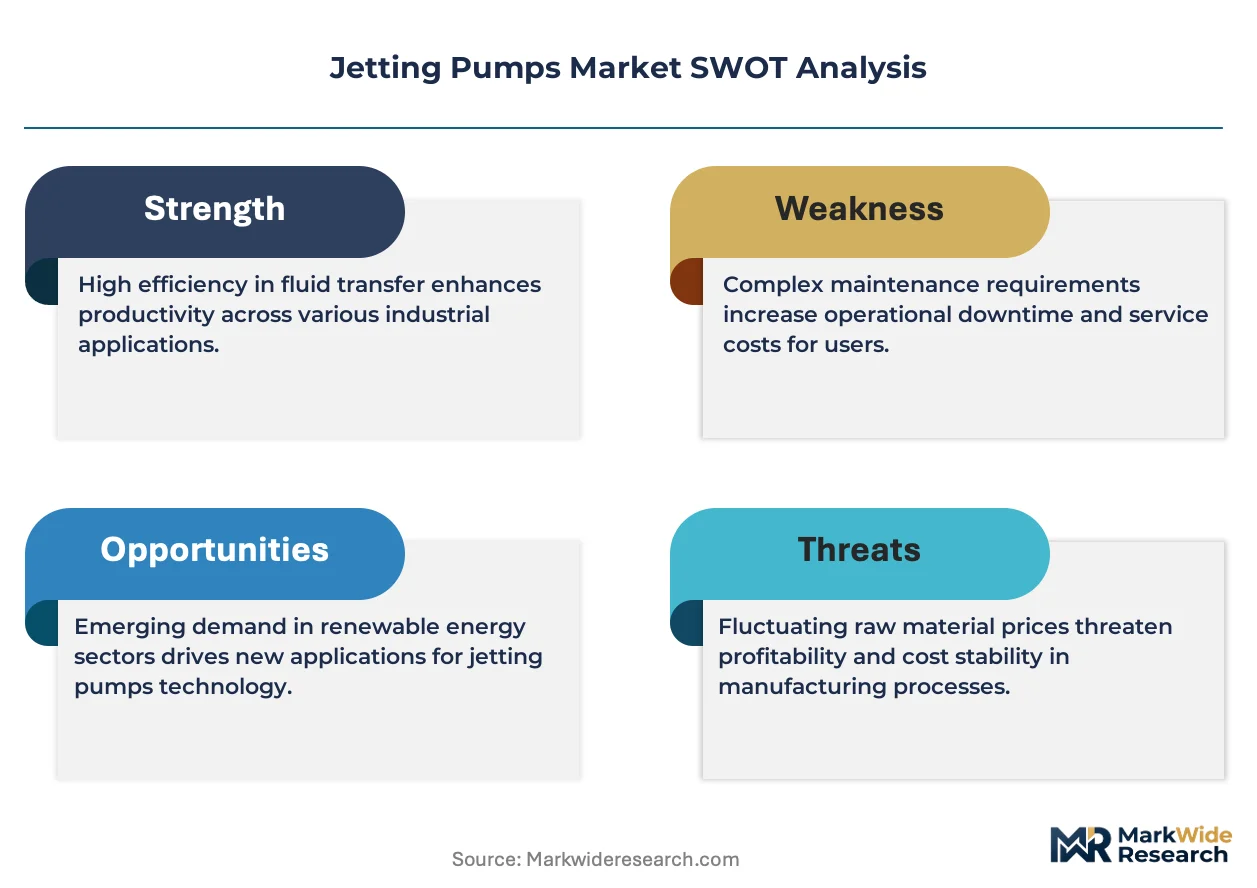
- Fluoropolymer seal material costs:REACH compliance redirects sourcing away from conventional elastomers toward perfluoroalkoxy resins, tightening input cost structures.
- Foundry capacity concentration:Precision casting for high-pressure pump housings clusters in select Chinese and Indian manufacturing zones, exposing supply chains to localized disruptions.
- Centrifugal pump substitution in low-pressure applications:Standard water transfer operations below 4:1 pressure ratios increasingly specify cheaper centrifugal alternatives.
Strategic Opportunities
- Carbon-border adjustment mechanism preparation:EU importers of pump components face embedded emissions reporting from 2026, rewarding early adopters of low-carbon steel sourcing.
- Remote hydraulic deployment:Fire suppression contractors in Australian mining camps and Indonesian plantation zones specify engine-driven units where grid access remains absent.
- Sensor-integrated predictive maintenance:Vibration and pressure telemetry modules converge with jetting pump architectures, enabling condition-based service intervals for municipal fleet operators.
Industry Challenges
- Multi-standard certification timelines:Manufacturers targeting simultaneous EU CE marking, US EPA efficiency verification, and India BIS approval face sequential testing bottlenecks extending product launch windows.
- Legacy pneumatic system integration:Shale operators in the Permian Basin require hybrid control interfaces bridging new positive displacement units with existing compressed air infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jetting Pumps Market |
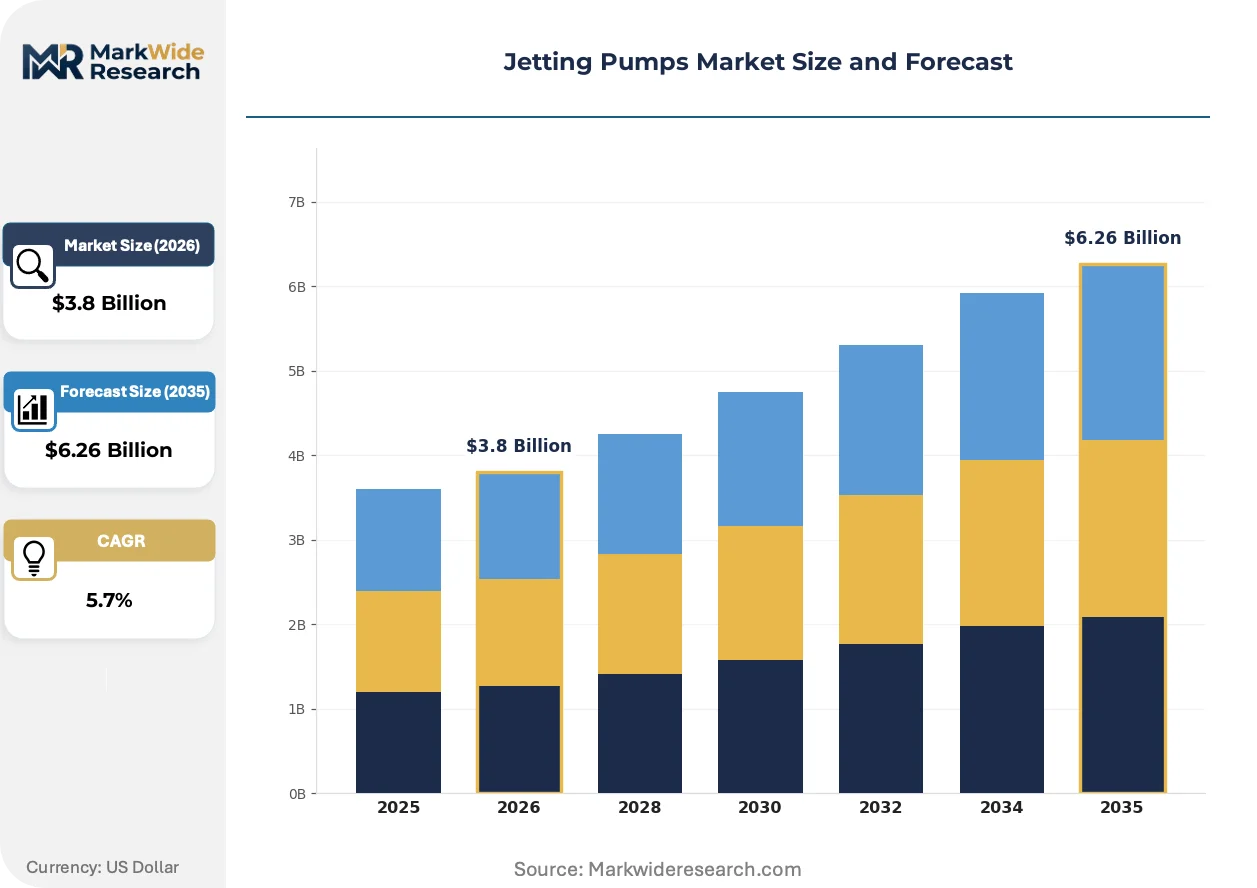
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Pressure Pumps, Electric Pumps, Hydraulic Pumps, Submersible Pumps Application: Water Supply, Wastewater Management, Fire Fighting, Irrigation End User: Aquaculture, Industrial Manufacturing, Agriculture, Construction Technology: Positive Displacement, Centrifugal, Pneumatic, Mechanical |
| Companies Covered | Grundfos Holding A/S, Xylem Inc., KSB SE & Co. KGaA, Franklin Electric, Goulds Water Technology, Dafu Intelligent Technology Co., Ltd., JEE Pumps, ITT Goulds Pumps, Wilo SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jetting Pumps Market Strategic Shifts
Digital telemetry and materials science are compressing maintenance intervals and expanding operational envelopes across municipal, industrial, and remote deployment scenarios.
Variable frequency drive controllers are converging with jetting pump motor assemblies to enable real-time pressure modulation. German wastewater utilities specify these configurations for diurnal flow matching. The technology is converging with legacy fixed-speed installations, enabling retrofit upgrades without full system replacement.
REACH Annex XVII restrictions on perfluorinated compounds are forcing seal compound reformulation across European supply chains. Manufacturers now qualify hydrogenated nitrile butadiene rubber alternatives for high-pressure rotary applications. German pump assemblers face the steepest compliance curve given their domestic chemical processing customer base.
Buyers in India's textile belt now unbundle aftermarket service contracts from initial equipment procurement. Surat and Tiruppur cluster operators negotiate separate spare parts and field service agreements, compressing upfront capital outlays. This pattern is concentrating margin pressure on OEMs while expanding independent service provider ecosystems.
Jetting Pumps Market Segmentation
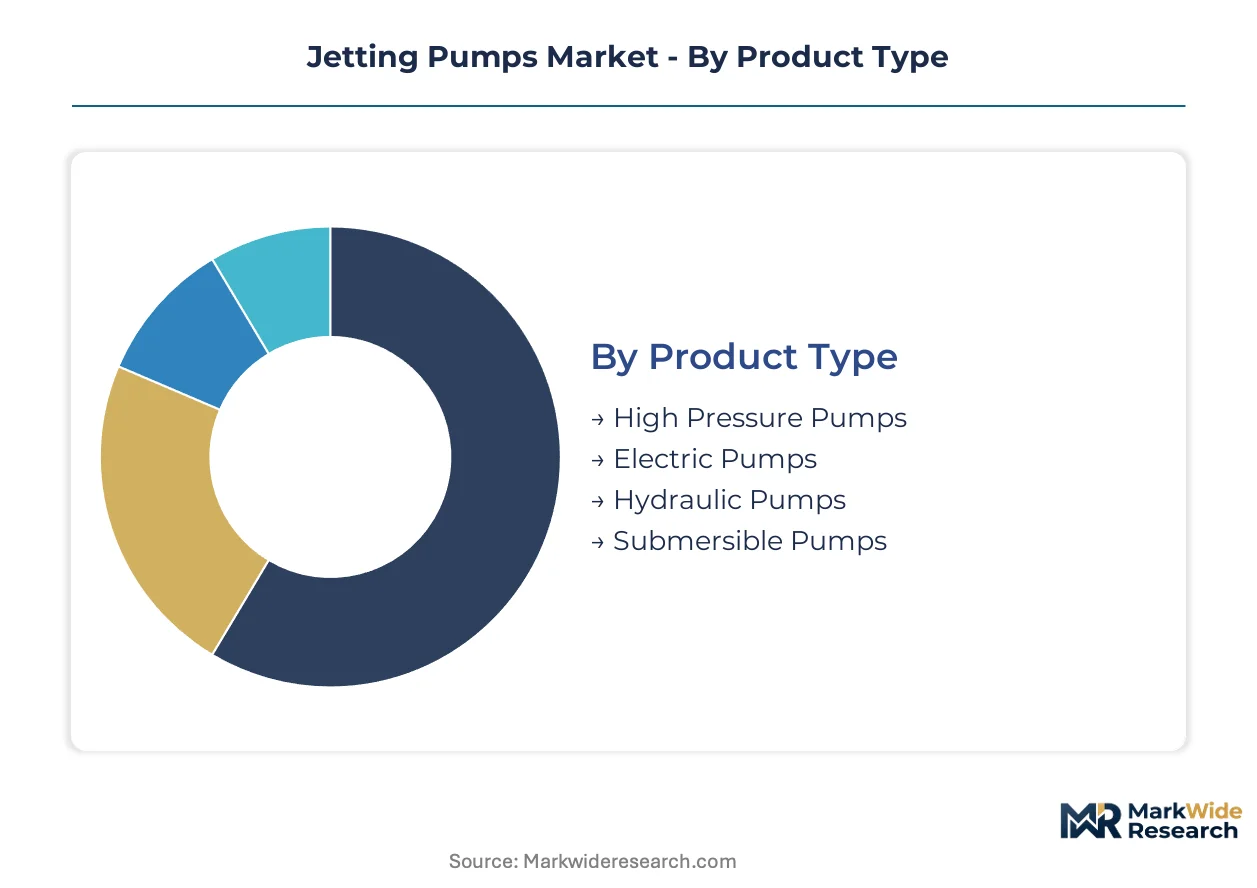
Jetting pump procurement patterns diverge sharply across pressure specifications, power sources, and deployment environments. Understanding these splits reveals where margin pools concentrate and which technology transitions are reshaping competitive positioning.
Product Type:
Volume deployment clusters in standardized electric configurations, while premium pricing attaches to specialized high-pressure and corrosion-resistant submersible systems.
- High Pressure Pumps:These units generate discharge pressure exceeding 4:1 ratios through precision-machined converging nozzles. German chemical processors and Indian textile clusters in Surat specify these for injection and cleaning operations where standard pumps fail. REACH-compliant seal materials are redirecting sourcing costs toward fluoropolymer alternatives.
- Submersible Pumps:Immersion-grade stainless steel housings protect motor assemblies from continuous seawater exposure. Vietnamese and Indonesian aquaculture operators are driving specification changes for corrosion-resistant architectures in coastal zones. This configuration is climbing the fastest among all product categories.
- Electric Pumps:Grid-tied municipal installations favor these for operational precision and remote monitoring compatibility.
- Hydraulic Pumps:Engine-driven units serve Australian mining camps and Indonesian plantation fire suppression where electrical infrastructure remains absent.
Mature deployment sits with electric pumps in established municipal grids. Newer deployment is concentrated in submersible configurations for coastal aquaculture expansion.
Application:
Revenue concentration follows regulatory enforcement intensity, with wastewater and water supply commanding premium pricing against price-sensitive irrigation segments.
- Wastewater Management:EU Green Deal compliance timelines are compressing procurement cycles across German municipal infrastructure. Variable frequency drive integration enables diurnal flow matching for energy-optimized operations.
- Water Supply:Grid-accessible urban distribution networks specify electric configurations with telemetry integration for pressure modulation.
- Fire Fighting:Remote deployment scenarios in mining and plantation zones specify hydraulic engine-driven units independent of electrical infrastructure.
- Irrigation:Large-scale agricultural operations in water-stressed regions prioritize capital efficiency over precision control.
Margin stability clusters in wastewater applications under regulatory pressure. Volume expansion is accelerating in irrigation as water scarcity intensifies agricultural mechanization.
End User:
Customer sophistication varies dramatically, with industrial manufacturing demanding predictive maintenance integration while agriculture prioritizes upfront cost minimization.
- Industrial Manufacturing:German automotive and chemical processors specify sensor-integrated pumps with vibration telemetry for condition-based service intervals. BIS certification mandates in Gujarat and Tamil Nadu textile corridors are standardizing procurement specifications.
- Aquaculture:Coastal operators in Vietnam and Indonesia require immersion-grade materials for continuous seawater exposure.
- Construction:Remote site deployment favors hydraulic portability over grid-dependent electric systems.
- Agriculture:Price-sensitive procurement patterns dominate, with unbundled aftermarket service contracts compressing OEM margin capture.
Technology leadership concentrates in industrial manufacturing. Steepest expansion trajectory is appearing in aquaculture as coastal protein production scales.
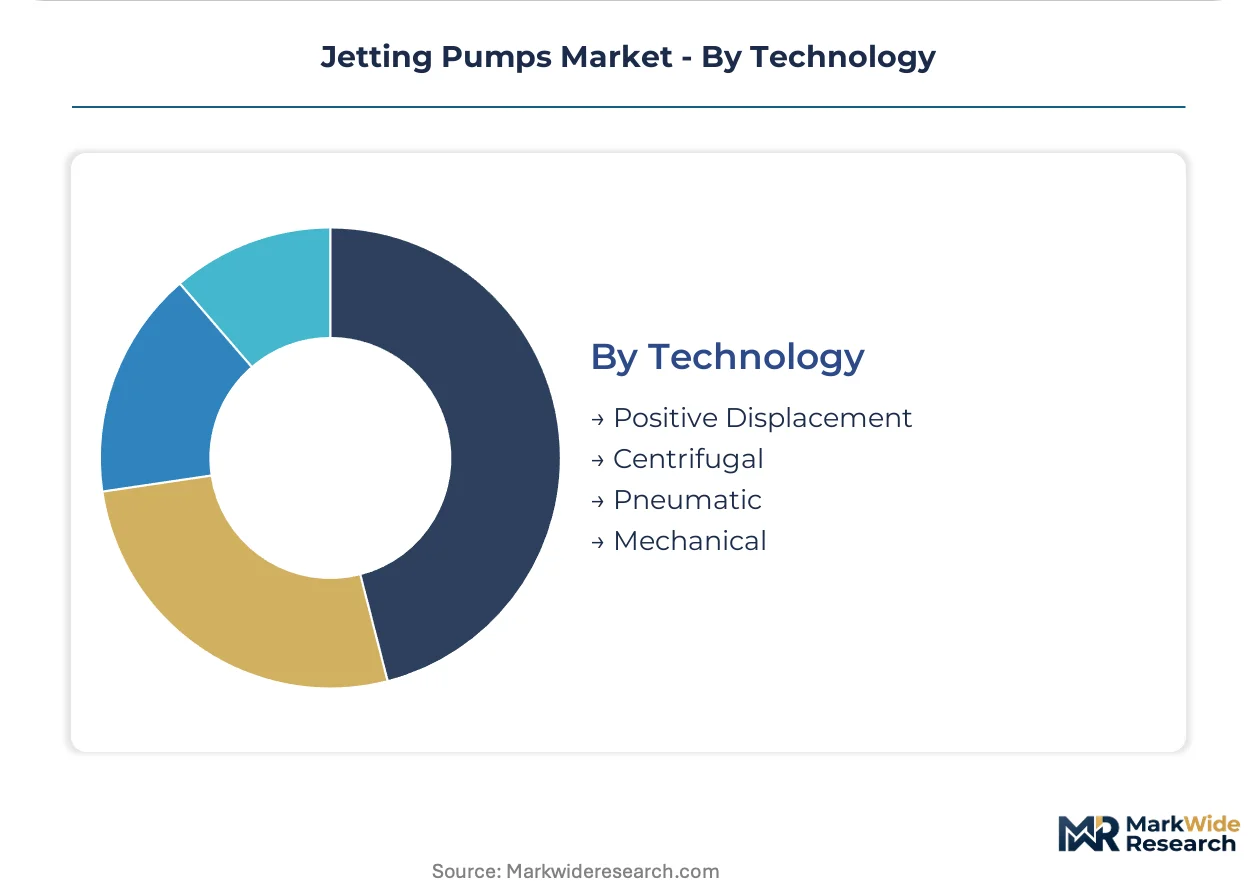
Technology:
Positive displacement architectures are displacing legacy pneumatic systems in high-pressure extraction applications, while centrifugal alternatives capture low-ratio water transfer.
- Positive Displacement:These systems generate precise volumetric output through mechanical compression, displacing pneumatic alternatives in North American shale extraction. Hybrid control interfaces are bridging new units with existing compressed air infrastructure in Permian Basin operations.
- Centrifugal:Lower capital cost and simpler maintenance dominate water transfer applications below 4:1 pressure ratios, constraining jetting pump addressable market.
- Pneumatic:Legacy installations persist where compressed air infrastructure is sunk cost, though new procurement is declining.
- Mechanical:Basic drive configurations serve cost-constrained applications with minimal automation requirements.
Installed base concentration remains with pneumatic systems in legacy extraction. Transition investment is concentrating in positive displacement for precision pressure control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Surat anchors procurement intensity for India's textile belt, where BIS-certified high-pressure units serve dyeing and finishing clusters under compressed compliance timelines.
United States
Shale operators in the Permian Basin deploy positive displacement systems to replace aging pneumatic infrastructure. EPA effluent limitations compel wastewater facilities across Texas and Pennsylvania to upgrade pump efficiency standards. Houston-area fabrication yards supply hybrid control interfaces bridging new units with legacy compressed air systems.
Germany
Municipal wastewater plants in the Ruhr region accelerate tender volumes ahead of binding EU Green Deal deadlines. REACH Annex XVII restrictions redirect seal compound sourcing toward hydrogenated nitrile butadiene rubber alternatives. KSB SE & Co. KGaA anchors specialized high-pressure product lines serving chemical processors in Ludwigshafen.
India
Textile manufacturing corridors in Gujarat and Tamil Nadu standardize procurement around BIS-certified configurations. DGFT import monitoring tightens component traceability for high-pressure assemblies. Tiruppur cluster operators unbundle aftermarket service contracts from initial equipment procurement, compressing upfront capital requirements.
Vietnam
Coastal aquaculture operators in the Mekong Delta specify immersion-grade stainless steel housings for continuous seawater exposure. Submersible configurations climb fastest among product categories as shrimp and catfish production scales. Can Tho and Ca Mau provinces concentrate specification changes for corrosion-resistant architectures.
Australia
Mining camps in Western Australia and Queensland specify engine-driven hydraulic units for fire suppression where grid infrastructure remains absent. Remote deployment scenarios favor portability over electric dependency. Kalgoorlie and Pilbara operations drive demand for independent power systems in arid extraction zones.
Jetting Pumps Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification intensity and material specification tiers. The vendor base stratifies between vertically integrated European specialists and Asia-Pacific fabricators serving price-sensitive agricultural procurement. Three archetypes dominate: integrated pump-system assemblers with captive component production, regional specialists targeting municipal retrofit specifications, and scale-driven manufacturers supplying standardized irrigation configurations. Consolidation pressure concentrates among mid-cap European players seeking geographic expansion, while Asian fabricators deepen backward integration into precision casting capacity.
Among Denmark-based integrated operators, Grundfos Holding A/S exemplifies the captive-supply archetype through in-house motor and control production. Wilo SE occupies a position within the compact-design tier serving European wastewater retrofit markets. Xylem Inc. represents the transnational scale-driven model with diversified application coverage across municipal and industrial segments.
| Leading Market Players |
|---|
| Grundfos Holding A/S |
| Xylem Inc. |
| KSB SE & Co. KGaA |
| Franklin Electric |
| Goulds Water Technology |
| Dafu Intelligent Technology Co., Ltd. |
| JEE Pumps |
| ITT Goulds Pumps |
| Wilo SE |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between REACH-compliant European assemblies and BIS-mandated Indian configurations shapes divergent margin structures and sourcing geographies. Premium-tier suppliers anchor pricing to fluoropolymer seal specifications and embedded emissions compliance, while commodity fabricators compete on foundry proximity to precision casting clusters.
Pricing Analysis
Outcome-based pricing tied to uptime guarantees and energy efficiency metrics anchors premium configurations serving German municipal wastewater utilities. Three-tier pricing structure across premium, standard, and economy levels separates sensor-integrated predictive maintenance systems from basic electric units and stripped agricultural configurations. Cost compression in economy tiers is intensifying because Indian textile clusters unbundle aftermarket service contracts from initial procurement. Agricultural buyers in water-stressed regions exhibit the steepest price sensitivity, while German chemical processors accept premium positioning for REACH-compliant seal materials.
Supply Chain Analysis
CE marking and BIS qualification gates concentrate component sourcing among pre-certified foundry networks in China, India, and Germany. Precision casting for high-pressure pump housings draws from specialty steel mills and fluoropolymer resin suppliers anchored in select Asian manufacturing zones. Single-source vulnerability runs through concentrated precision casting capacity in Zhejiang and Gujarat provinces. Distribution runs through OEM-direct municipal tender channels in Europe and unbundled aftermarket service ecosystems in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundry capacity concentration for precision high-pressure housings props pricing power among certified suppliers, constraining volume expansion for uncertified entrants.
For Market Incumbents: Deploy captive fluoropolymer seal compound qualification to lock in REACH-compliant supply ahead of carbon-border adjustment mechanism enforcement. Deepen backward integration into precision casting capacity in Gujarat and Zhejiang to buffer localized disruption risks. Defensive positioning against centrifugal pump substitution in sub-4:1 pressure applications requires variable frequency drive bundling to preserve municipal retrofit attach rates. For New Entrants and Emerging Players: Direct-to-utility digital tender platforms offer the lowest-friction route for submersible corrosion-resistant configurations targeting Vietnamese aquaculture expansion. White-space concentration appears in remote hydraulic fire suppression for Australian mining camps and Indonesian plantation zones where grid infrastructure remains absent. Sensor-integrated predictive maintenance modules present the most penetrable upsell angle for municipal fleet operators seeking condition-based service intervals. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap European specialists possessing captive CE marking and EU Green Deal compliance documentation given accelerating German municipal tender compression. Long-term viability over a multi-year horizon favors assemblers with demonstrated BIS certification pathways and established foundry relationships in India. Watch for carbon-border adjustment mechanism implementation timing as the critical inflection signal for low-carbon steel sourcing premiums.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Seal Compound Qualification | Secures European market access ahead of Annex XVII enforcement deadlines. |
| Precision Casting Capacity Expansion | Reduces single-source exposure in Zhejiang and Gujarat foundry clusters. |
| Variable Frequency Drive Integration | Enables diurnal flow matching for German wastewater utility retrofits. |
| Submersible Corrosion-Resistant Design Certification | Captures Vietnamese and Indonesian aquaculture specification changes. |
| Predictive Maintenance Telemetry Module Development | Creates condition-based service revenue streams for municipal fleet operators. |
Study Parameters
Multi-period observation of municipal tender volumes, BIS certification issuance rates, and foundry capacity utilization anchored the trend analysis, supplemented by interviews with plant engineers at German wastewater utilities, procurement leads at Indian textile clusters, aftermarket service heads at European OEMs, and aquaculture operators in Vietnam. Secondary validation drew from EPA effluent limitation filings, EU Green Deal procurement databases, DGFT import monitoring records, and REACH Annex XVII compliance disclosures. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Input-output matrices modeled demand drivers across product type, application, end user, technology, and regional regulatory cluster dimensions over the projection horizon. CAGRs were derived from segment-level growth rate synthesis. Industry-specific forecast inputs included EU Green Deal compliance timeline adherence rates and BIS certification pipeline velocity for high-pressure industrial units.
The model holds under stable regulatory enforcement schedules and intact foundry capacity; deviation in carbon-border adjustment mechanism implementation timing or precision casting supply disruption would shift volume and value trajectories. A model refresh is warranted upon material change in REACH seal compound substitution rates or Indian DGFT import monitoring intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Latin America Centrifugal Pumps Market
Pumps and Control Devices
Self-Priming Centrifugal Pump Market
Pumps and Control Devices
Commercial Booster Pumps Market
Pumps and Control Devices
India Solar Water Pump Systems Market
Pumps and Control Devices
Vacuum Pump Stations Market
Pumps and Control Devices
Radial Piston Pumps Market
Pumps and Control Devices
Vertical Immersion Pumps Market
Pumps and Control Devices
Melt & Gear Pump Market
Pumps and Control Devices
Vertical Turbine Pumps Market
Pumps and Control Devices
Latin America Hydraulic Filtration Market
Pumps and Control Devices
Global Submersible Pumps Market
Pumps and Control Devices
Spiral Classifier Market
Pumps and Control Devices
Automatic Tube Cleaning System Market
Pumps and Control Devices
Europe Centrifugal Pumps Market
Pumps and Control Devices
Sealless Magnetic Drive Pump Market
Pumps and Control Devices
Spin-On Hydraulic Filter Market