
 Asia-Pacific Additive Manufacturing Market | 2026-2036
Asia-Pacific Additive Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Additive Manufacturing Market Outlook
The gap between aerospace-grade metal additive systems and desktop polymer printers is broadening across the Asia-Pacific region. Stratasys anchors the professional polymer segment through established service bureau networks in Japan and Australia. Titomic Limited dominates cold-spray metal deposition for defense and space applications, leveraging proprietary high-deposition-rate technology developed in Melbourne.
Additive manufacturing constructs three-dimensional objects through sequential material deposition guided by digital design files, with layer thicknesses typically ranging from 20 to 100 micrometers depending on the process. Its primary industrial purpose centers on producing complex geometries, consolidated assemblies, and topology-optimized components that subtractive methods cannot machine economically. Selective Laser Sintering leads the technology segment for metal aerospace applications where powder bed fusion achieves full density in nickel superalloys. Metal materials command the highest margin pools, particularly titanium and aluminum powders qualified for aviation supply chains. Plastics sustain volume leadership through fused deposition modeling systems serving consumer products and prototyping workflows across Southeast Asian manufacturing hubs.
China's SAMR enforces GB standards for industrial additive equipment safety and emissions, while Japan's METI coordinates R&D consortia linking machine builders with end-users in automotive and medical device sectors. Australia's TGA regulates patient-specific implant manufacturing, creating compliance barriers for uncertified production workflows. Stakeholders must monitor divergence between national certification regimes as cross-border supply chain integration deepens.
Market Dynamics
China's GB standards for industrial 3D printing and Japan's METI innovation frameworks are compressing equipment certification timelines while aerospace manufacturers in Japan and South Korea accelerate metal powder bed fusion adoption for turbine blade production.
Growth Catalysts
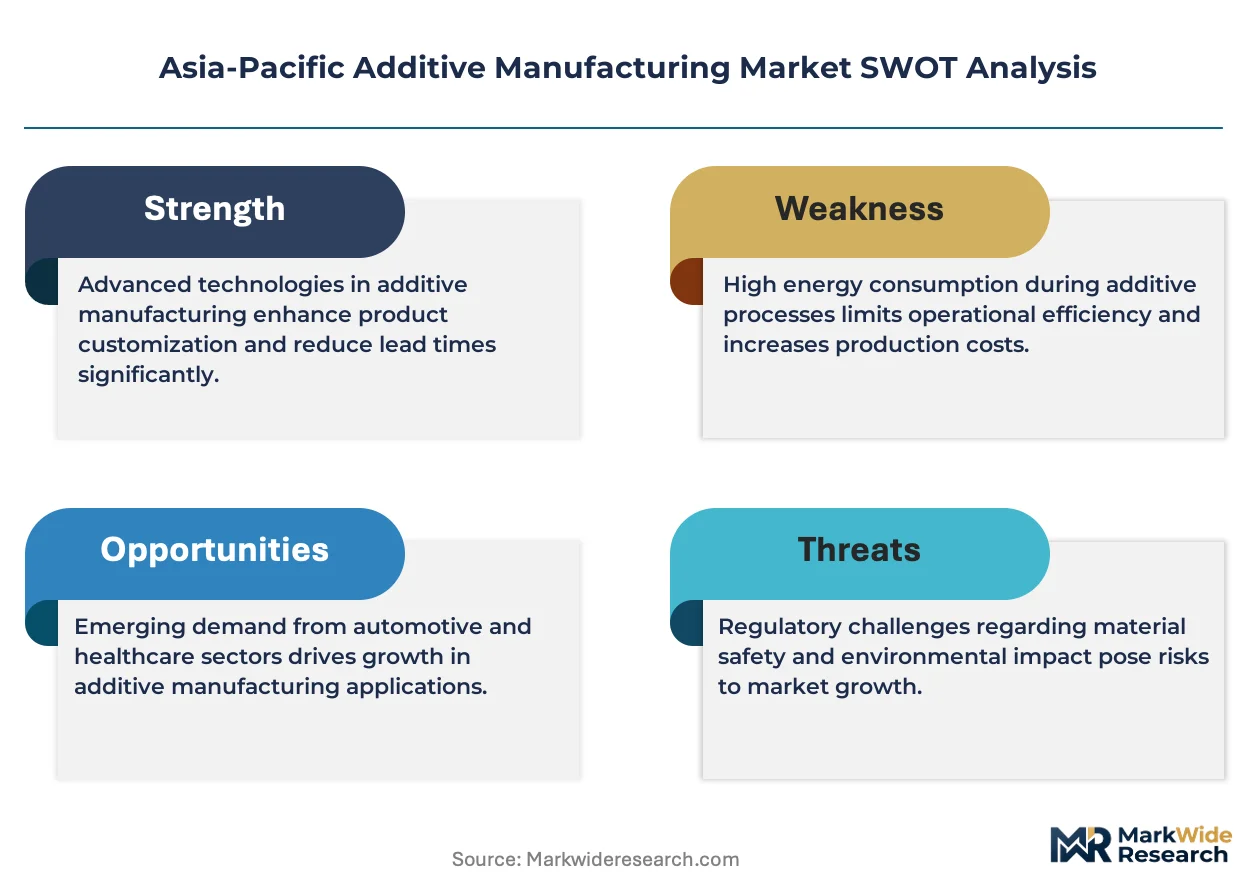
- GB Standards Acceleration:China's SAMR enforcement of industrial additive equipment safety and emissions standards is streamlining market entry for qualified machine builders.
- Aerospace Demand Concentration:Turbine blade production requirements from Japanese and South Korean aerospace manufacturers are pulling high-deposition-rate metal systems into serial manufacturing workflows.
- Yangtze River Delta Cluster:Demand concentrates across Shanghai, Jiangsu, and Zhejiang provinces where automotive and medical device end-users maintain dense supplier networks.
Market Restraints
- Titanium Powder Supply Concentration:Aviation-qualified titanium powder production concentrates among a limited set of plasma atomization suppliers, creating input cost volatility for metal additive operations.
- Cross-Border Certification Friction:Divergence between China's GB standards, Japan's JIS frameworks, and Australia's TGA requirements for patient-specific implants creates compliance barriers for integrated supply chains.
- Polymer Substitution Threat:High-performance thermoplastics in fused deposition modeling systems compete with metal solutions for non-structural aerospace brackets and ducting applications.
Strategic Opportunities
- Southeast Asian Manufacturing Hubs:Vietnam and Thailand prototyping workflows remain underpenetrated by industrial polymer systems relative to their electronics and consumer products output.
- Defense Cold-Spray Applications:Australia's defense and space sectors present emerging demand for high-deposition-rate metal deposition on existing substrate geometries without thermal distortion.
- Automotive-R&D Consortia:Japan's METI-coordinated programs linking machine builders with automotive end-users create regulatory tailwinds for production-scale metal additive qualification.
Industry Challenges
- Multi-Physics Simulation Talent Gap:Process-parameter optimization for nickel superalloy powder bed fusion requires scarce expertise in thermal-fluid-solid coupling analysis.
- Aviation Certification Timeline Compression:FAA and EASA equivalency recognition for Chinese and Japanese qualification test data remains inconsistent, extending airworthiness approval cycles.
- Legacy MES Integration Complexity:Shop-floor connectivity between additive work cells and existing enterprise resource planning systems demands custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Additive Manufacturing Market |
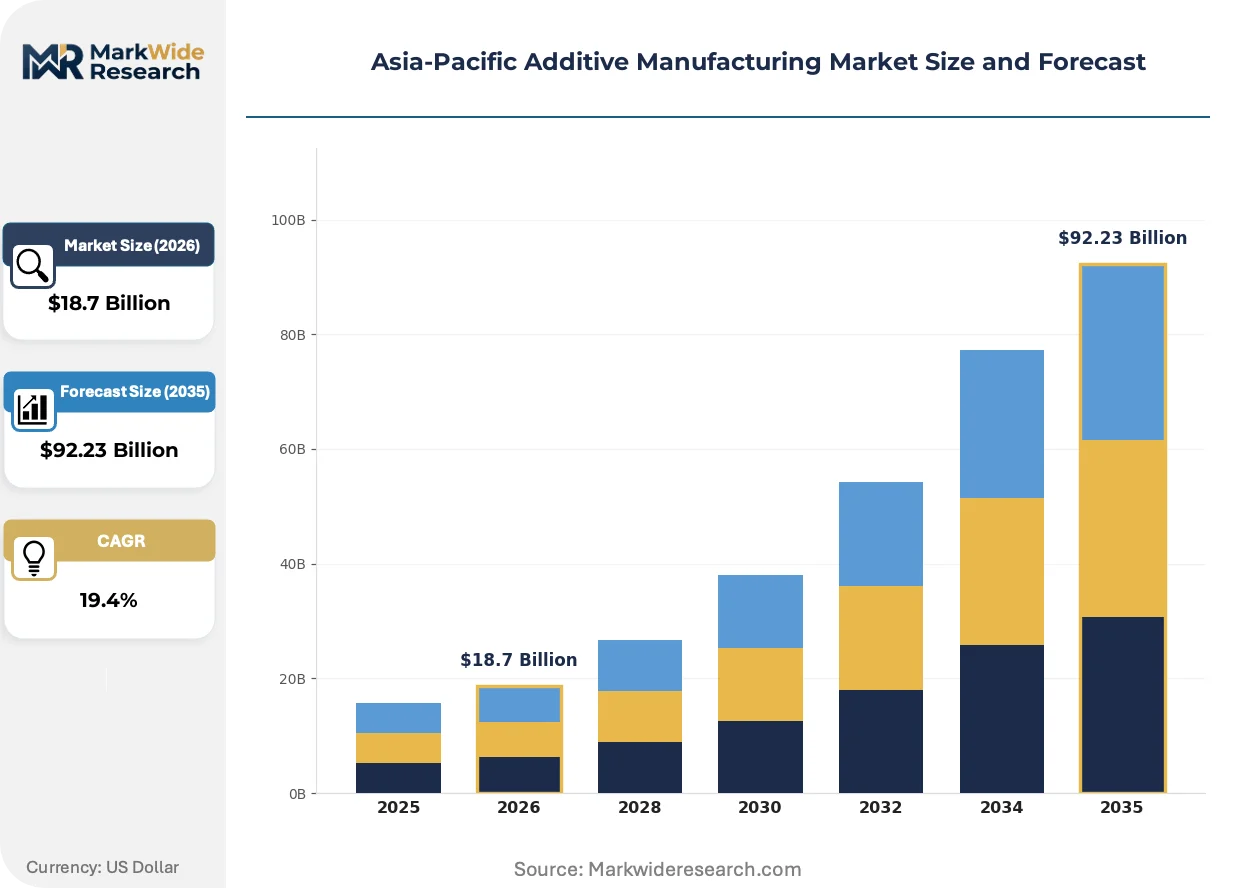
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $92.23 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fused Deposition Modeling, Stereolithography, Selective Laser Sintering, Digital Light Processing Material: Plastics, Metals, Ceramics, Composites Application: Aerospace, Healthcare, Automotive, Consumer Products End User: Manufacturers, Research Institutions, Startups, Hobbyists |
| Companies Covered | Renishaw plc., Markforged, Stratasys, Titomic Limited, Farsoon Technologies, 3D Systems, Materialise, Höganäs AB, EOS, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Additive Manufacturing Market Strategic Shifts
Multi-laser powder bed fusion architectures and in-process monitoring systems are redistributing production economics across the Asia-Pacific metal additive landscape. These developments compress the viable batch size for aerospace components while extending process control into previously unmonitored build phases.
Cold-spray metal deposition is decentralizing repair and feature-addition workflows for defense and space applications. Australian defense contractors are adopting the technology for field-deployable component restoration. This capability is compressing the traditional depot-repair supply chain for turbine casings and landing gear components.
Japan's METI innovation frameworks are mandating interoperability standards between machine builders and end-users in automotive and medical device sectors. The policy requires open process-parameter documentation for consortium participants. Medical implant manufacturers in Osaka and Nagoya clusters are responding by standardizing build-file exchange protocols.
Buyer concentration among tier-one aerospace contractors is compressing supplier qualification cycles and unbundling after-sales service contracts. Japanese and South Korean airframe integrators now require dedicated resident engineers from additive equipment vendors. This pattern is most visible in the Nagoya aerospace corridor where Mitsubishi Heavy Industries and Subaru coordinate supplier development programs.
Asia-Pacific Additive Manufacturing Market Segmentation
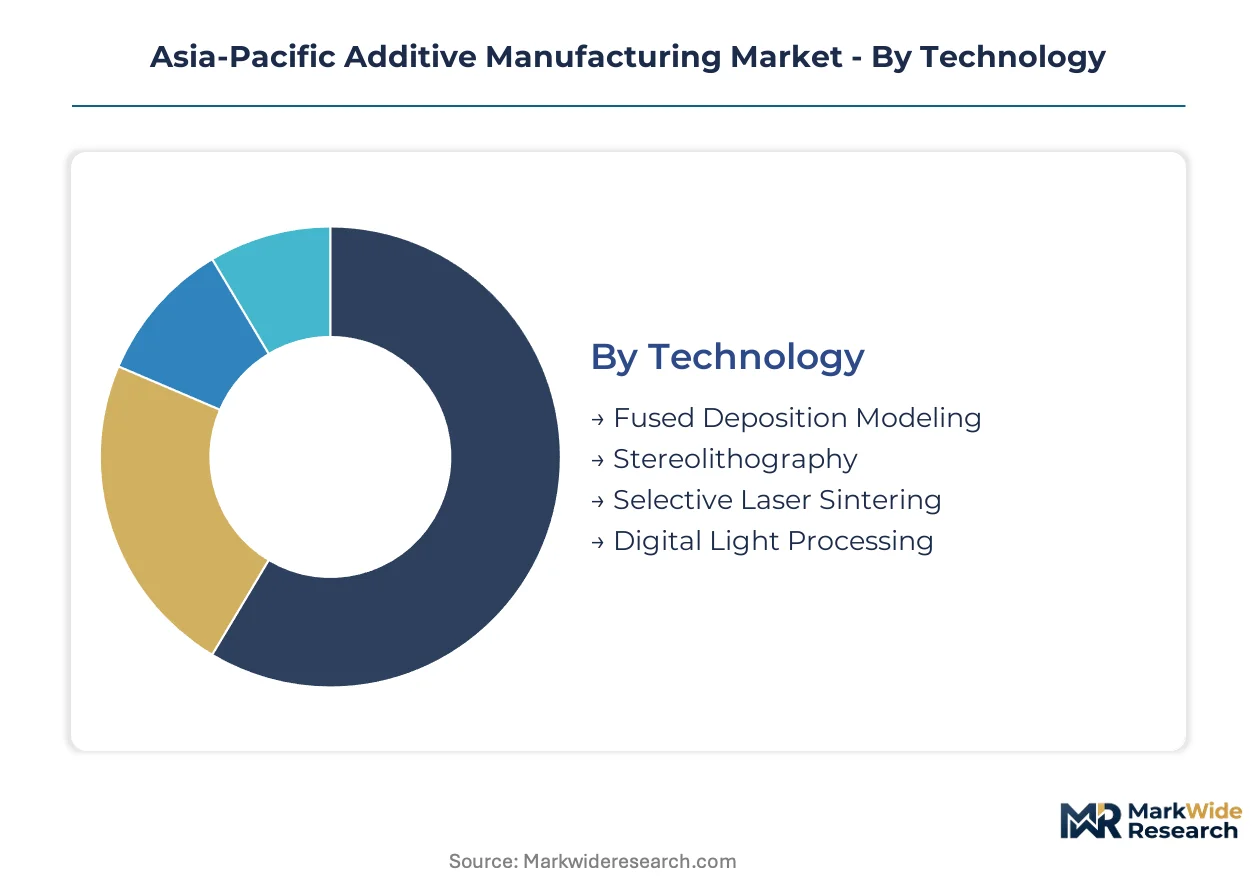
Technology choice dictates capital intensity and margin structure across Asia-Pacific additive manufacturing. Material qualification requirements and end-use certification timelines fragment addressable markets by production scale and regulatory burden.
Technology:
Volume leadership sits with polymer extrusion systems, while premium capture concentrates in powder bed fusion for aerospace-qualified metals.
- Selective Laser Sintering:Powder bed fusion achieves full density in nickel superalloys through precise laser energy input control. Japanese and South Korean aerospace manufacturers in the Nagoya corridor and Seoul satellite cities pull these systems into serial turbine blade production, constrained by multi-physics simulation talent scarcity.
- Fused Deposition Modeling:Polymer filament extrusion dominates unit volume through accessible hardware cost structures and minimal facility requirements. Vietnam and Thailand electronics manufacturing hubs deploy these systems for rapid prototyping workflows, though industrial-grade precision variants command pricing premiums over desktop alternatives.
- Stereolithography:Photopolymer vat polymerization delivers surface finish precision for dental and jewelry applications.
- Digital Light Processing:Projected light curing accelerates layer throughput for investment casting patterns and hearing aid shells.
Today's leader: Fused Deposition Modeling. Tomorrow's challenger: Selective Laser Sintering.
Material:
Margin pools concentrate in aviation-qualified powders, while plastics sustain revenue breadth through application diversity.
- Metals:Titanium and aluminum powders qualified for aviation supply chains command the highest margin pools, with plasma atomization supply concentrating among limited suppliers. China's Yangtze River Delta cluster and Japan's aerospace corridors drive qualification testing for nickel superalloy builds.
- Plastics:ABS, PLA, and high-performance thermoplastics like PEEK and ULTEM serve prototyping and end-use part production across Southeast Asian consumer electronics manufacturing. Substitution pressure from high-performance polymers competes with metal solutions for non-structural aerospace brackets.
- Ceramics:Oxide and non-oxide ceramic slurries enable biocompatible implants and high-temperature tooling.
- Composites:Continuous fiber reinforcement within thermoplastic matrices targets structural automotive and drone components.
Plastics generate the widest revenue base. Metals offer the steepest expansion trajectory as aerospace qualification deepens.
Application:
Certification maturity separates production-scale adoption from pilot-line experimentation.
- Aerospace:Turbine blade and structural bracket production demands full density metallurgy and traceable process parameters. Mitsubishi Heavy Industries and Subaru in Japan coordinate supplier development programs requiring resident engineers from equipment vendors.
- Healthcare:Patient-specific implants and surgical guides face Australia's TGA regulatory barriers for uncertified production workflows, while Japan's METI frameworks standardize build-file exchange protocols in Osaka and Nagoya medical device clusters.
- Automotive:Japan's METI-coordinated R&D consortia link machine builders with end-users for production-scale metal additive qualification.
- Consumer Products:Electronics housings and wearables prototyping concentrates in Shenzhen and Bangkok manufacturing ecosystems.
Aerospace commands the highest equipment specification. Healthcare is gaining share fastest through regulatory harmonization efforts.
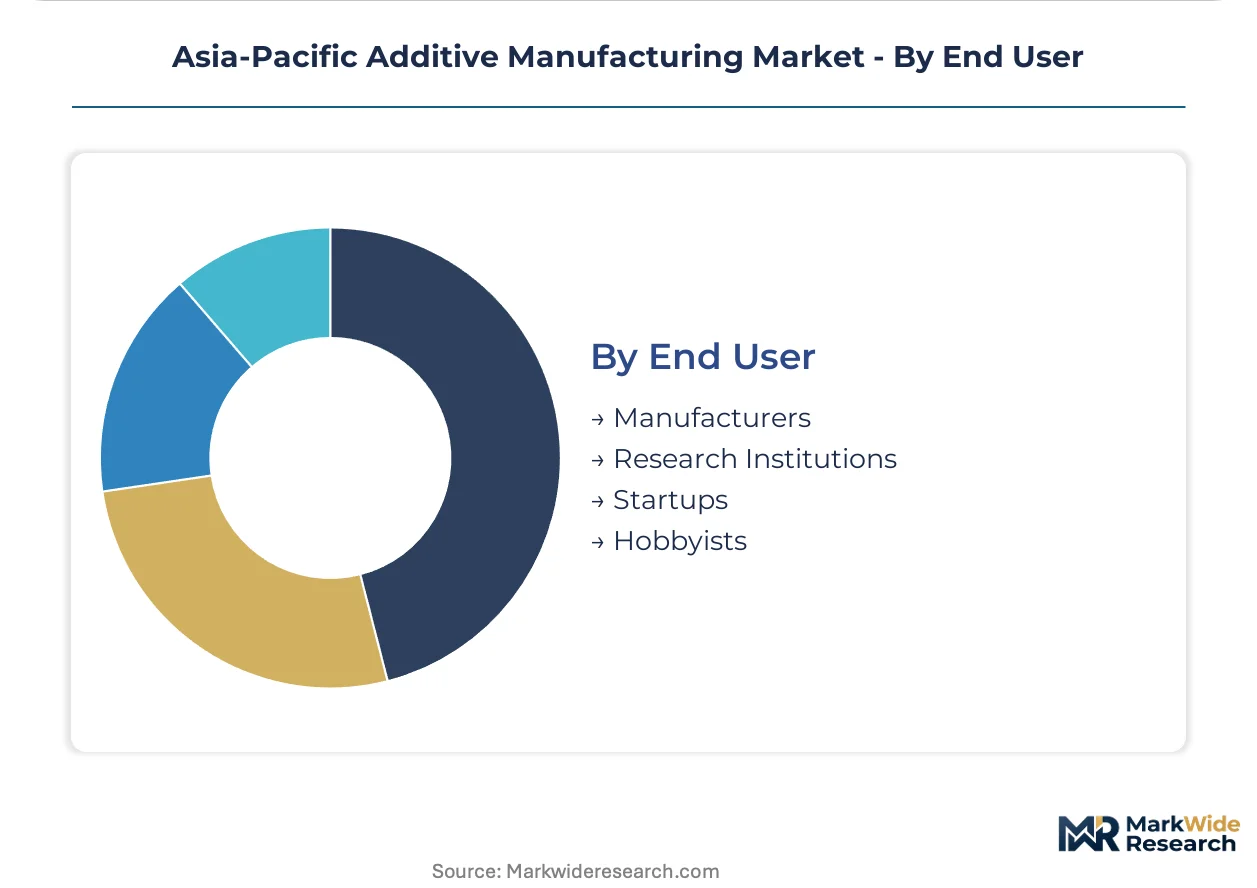
End User:
Capital access and technical capability stratify purchasing behavior across the technology maturity curve.
- Manufacturers:Tier-one aerospace contractors and automotive OEMs compress supplier qualification cycles and unbundle after-sales service contracts. Buyer concentration in Japanese and South Korean airframe integrators mandates dedicated technical support commitments.
- Research Institutions:Universities and national laboratories in Australia and Japan advance process-parameter optimization for novel alloy systems, feeding qualified datasets into industry consortia.
- Startups:Venture-backed service bureaus in Singapore and Bangalore target niche medical and dental applications with lower certification barriers.
- Hobbyists:Desktop polymer system owners represent minimal revenue per unit but drive brand awareness and filament aftermarket sales.
Manufacturers anchor equipment revenue. Research institutions are expanding most quickly as government R&D funding concentrates on sovereign manufacturing capability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Process-parameter optimization talent concentrates in Japanese national laboratories and Australian universities, feeding qualified datasets into industry consortia across the region.
China
Titanium powder demand from aviation supply chains and automotive prototyping workflows drive equipment procurement. SAMR enforces GB standards for industrial additive equipment safety and emissions. The Yangtze River Delta cluster spanning Shanghai, Jiangsu, and Zhejiang provinces hosts dense supplier networks for metal system qualification.
Japan
Turbine blade production requirements from Mitsubishi Heavy Industries and Subaru pull high-deposition-rate metal systems into serial manufacturing. METI coordinates R&D consortia mandating interoperability standards between machine builders and end-users. The Nagoya aerospace corridor demands dedicated resident engineers from equipment vendors under compressed supplier qualification cycles.
South Korea
Aerospace manufacturers accelerate metal powder bed fusion adoption for turbine components. National aerospace qualification frameworks align with FAA and EASA equivalency recognition efforts. Seoul satellite cities concentrate demand for nickel superalloy builds with traceable process parameters.
Australia
Defense contractors adopt cold-spray metal deposition for field-deployable component restoration. TGA regulations create compliance barriers for patient-specific implant manufacturing workflows. Melbourne anchors proprietary high-deposition-rate technology development for space applications.
Vietnam and Thailand
Electronics manufacturing hubs deploy fused deposition modeling systems for rapid prototyping workflows. Industrial-grade precision variants remain underpenetrated relative to consumer products output. Bangkok and Ho Chi Minh City manufacturing ecosystems sustain plastics volume leadership through accessible hardware cost structures.
Asia-Pacific Additive Manufacturing Market Competitive Environment
Top-tier vendors anchor equipment supply for aerospace-qualified metal systems, while mid-tier specialists concentrate on polymer service bureau networks and regional prototyping workflows. The vendor base stratifies across powder bed fusion architects, cold-spray deposition specialists, and filament extrusion platform providers. Strategic archetypes include integrated machine-and-materials suppliers, pure-play equipment manufacturers, and vertically integrated service bureaus. Competitive moves center on resident engineer deployment for tier-one aerospace contracts and unbundling of after-sales service agreements.
Among Asia-Pacific-based specialists, Titomic Limited exemplifies the cold-spray metal deposition archetype for defense applications. Stratasys anchors professional polymer segment supply through established service bureau networks. Farsoon Technologies occupies a position within the powder bed fusion tier serving industrial metal applications. These three entities represent distinct competitive vectors: proprietary deposition physics, regional service infrastructure, and integrated machine-platform scale.
| Leading Market Players |
|---|
| Renishaw plc. |
| Markforged |
| Stratasys |
| Titomic Limited |
| Farsoon Technologies |
| 3D Systems |
| Materialise |
| Höganäs AB |
| EOS |
| Others |
Value Chain & Pricing Dynamics
Multi-physics simulation talent scarcity in Japan's Nagoya aerospace corridor widens labor-cost differentials between premium metal powder bed fusion systems and standard polymer extrusion platforms, compressing mid-tier pricing spreads as buyers consolidate procurement around resident-engineer service bundles.
Pricing Analysis
Equipment vendors now unbundle resident-engineer service contracts from hardware sales, creating distinct pricing tiers based on after-sales support intensity. Price differentiation centers on aviation certification grade and geographic delivery cost, with Japanese airframe integrators commanding premium rates for dedicated technical support. Cost compression in standard polymer systems intensifies because Southeast Asian electronics manufacturers prioritize accessible hardware cost structures over precision variants. Tier-one aerospace contractors exhibit lowest price sensitivity due to qualification timeline pressures, while prototyping service bureaus in Vietnam and Thailand remain most cost-conscious.
Supply Chain Analysis
Regional distribution centers in Shanghai and Melbourne anchor hub-and-spoke patterns for titanium powder and cold-spray deposition equipment. Plasma atomization supply concentrates in Japan, China, and Australia, with aviation-qualified nickel superalloy powders drawing from limited qualified suppliers. Single-source vulnerability in titanium powder feedstock creates input cost volatility for metal additive operations. Distribution runs through tier-one aerospace contractor procurement channels and METI-coordinated R&D consortia, with aftermarket filament sales reaching desktop polymer system owners through electronics manufacturing hub retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific additive manufacturing offers margin expansion through titanium powder supply consolidation and premium-tier shift toward aviation-qualified metal systems with bundled resident-engineer support.
For Market Incumbents: Anticipate polymer substitution pressure from high-performance thermoplastics by deepening backward integration into plasma atomization capacity and securing exclusive resident-engineer contracts with Mitsubishi Heavy Industries and Subaru in the Nagoya corridor. Defend position by accelerating GB standards compliance certification ahead of SAMR enforcement timelines. For New Entrants and Emerging Players: Service bureau partnerships in Vietnam and Thailand offer the most penetrable entry path, with industrial-grade precision polymer systems remaining underdeployed relative to electronics manufacturing output. Target cold-spray metal deposition for Australian defense contractors seeking field-deployable component restoration capabilities without thermal distortion. For Investors and Strategic Acquirers: Tier-one aerospace contractors are the most active acquirer in this space, seeking captive additive manufacturing capability for turbine blade supply security. Long-term viability favors integrated machine-and-materials suppliers with proprietary high-deposition-rate technology and established aviation qualification datasets. Watch FAA-EASA equivalency recognition progress for Chinese and Japanese qualification test data as the inflection indicator for cross-border supply chain integration.| Strategic Initiative | Industry Significance |
|---|---|
| Resident Engineer Deployment | Mitsubishi Heavy Industries and Subaru now mandate dedicated vendor technical staff for supplier qualification. |
| Plasma Atomization Capacity Expansion | Captive titanium powder production reduces aviation supply chain exposure to limited qualified suppliers. |
| GB Standards Pre-Certification | SAMR compliance ahead of enforcement timelines accelerates market entry for industrial metal systems. |
| Cold-Spray Defense Contracting | Australian field-deployable restoration capability compresses traditional depot-repair supply chains. |
| Build-File Protocol Standardization | METI-mandated interoperability enables seamless machine builder and end-user collaboration in Osaka and Nagoya. |
Study Parameters
Direct dialogue with additive manufacturing equipment vendors, aerospace procurement directors, plasma atomization suppliers, and METI consortium coordinators grounded qualitative insights, validated against SAMR regulatory filings, Japanese patent databases, Australian TGA guidance documents, and customs trade data for titanium powder imports. Bottom-up and top-down triangulation reconciled equipment shipment volumes with end-user capacity expansion announcements.
Bottom-up modeling aggregated segment-level adoption curves across the projection horizon, with top-down cross-checks against regional industrial output and R&D expenditure patterns. Segmentation dimensions included technology type, material qualification tier, application certification maturity, and end-user capital access stratum. CAGRs derived from fitted adoption curves incorporating aviation qualification timeline compression and defense procurement acceleration.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FAA-EASA equivalency recognition divergence and titanium powder supply concentration. Forecasts reflect documented assumptions around SAMR enforcement timing and METI consortium participation rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
Additive Manufacturing Machines Market
3D Printing Technology
Rapid Prototyping Market
3D Printing Technology
3D Printing Enabled Augmented Manufacturing Market
3D Printing Technology
3D Printing in Aviation Market
3D Printing Technology
Europe Industrial 3D Printing Market
3D Printing Technology
Middle East and Africa Additive Manufacturing Market
3D Printing Technology
3D Printing in Automotive Additive Market
3D Printing Technology
Binder Jet Market
3D Printing Technology
Global Industrial 3D Printing Market
3D Printing Technology
Aluminum Alloy 3D Printing Service Market
3D Printing Technology
3D Printing Software Market
3D Printing Technology
Global 3D Metal Printing Machines Market
3D Printing Technology
Europe 3D Printing Market
3D Printing Technology
Automotive 3D Printing Consumables Market
3D Printing Technology
3D Printing Pellet Extruder Market
3D Printing Technology
Asia-Pacific Industrial 3D Printing Market