
 Additive Manufacturing Software Market | 2026-2036
Additive Manufacturing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Additive Manufacturing Software Market Insights
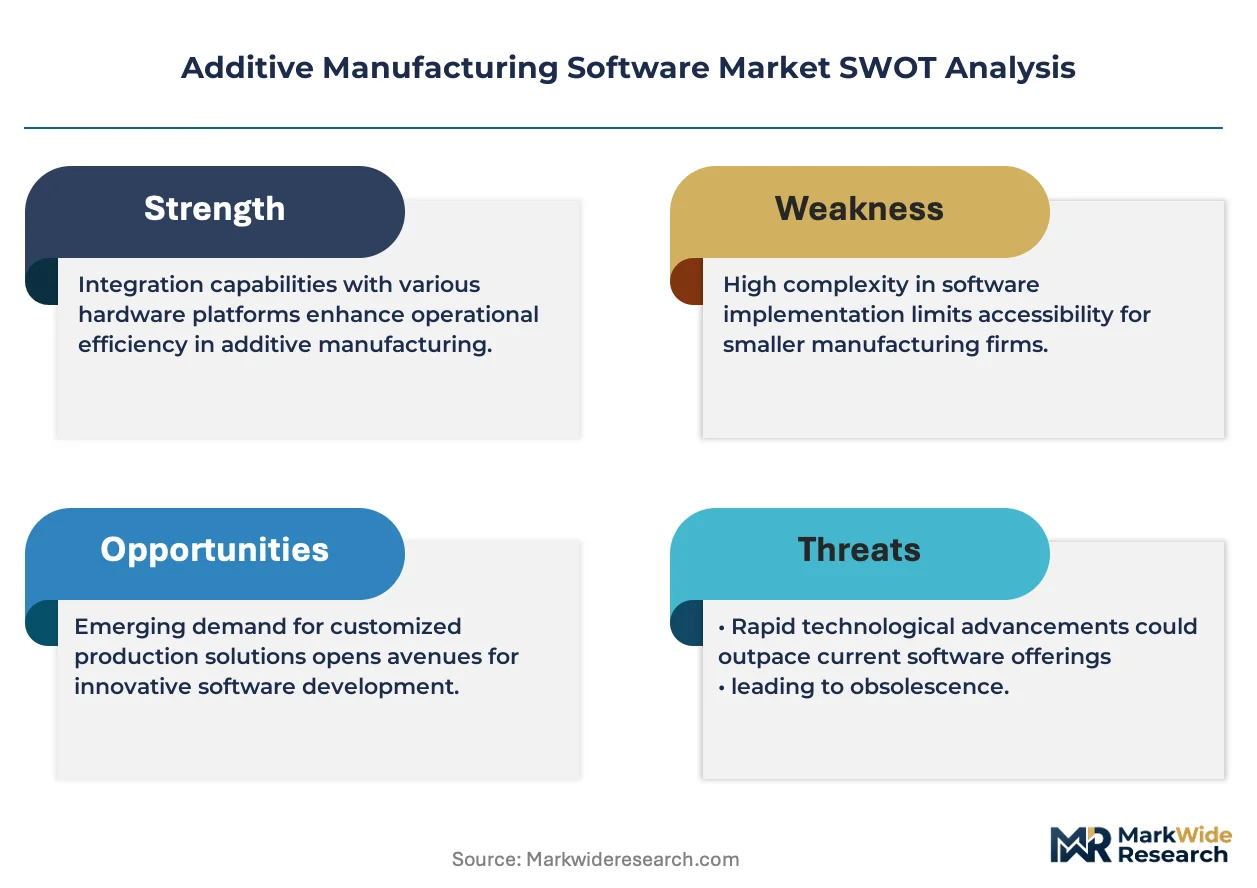
Aftermarket service revenue is narrowing as perpetual-license vendors shift toward subscription models. Autodesk leverages cloud-native architecture to capture recurring revenue from design-to-print workflows. Materialise sustains dominance in medical segmentation through FDA-cleared build-preparation tools. Stratasys anchors polymer-focused market share with printer-software bundling that locks in material consumption.
Additive manufacturing software encompasses the digital toolchain that translates 3D models into machine-readable instructions, typically handling tessellation, support generation, path planning, and thermal simulation for layer-by-layer fabrication. These platforms govern laser power modulation, scan-vector sequencing, and powder-bed recoater parameters to achieve specified density and surface finish in metal or polymer builds. Design software and simulation tools command the largest revenue pools today, while monitoring solutions represent the fastest-expanding segment as real-time melt-pool analytics become standard for aerospace qualification. Cloud-based deployment is displacing on-premises installations among mid-tier users seeking elastic compute for generative-design iterations.
FDA digital-health guidance and the EU Medical Device Regulation impose validation burdens on software used for patient-specific implant production, forcing vendors to maintain ISO 13485 quality systems and predicate-device documentation. The FAA's evolving airworthiness criteria for additively manufactured flight hardware require traceable process-parameter records that only integrated software platforms can generate. Stakeholders must weigh regulatory compliance costs against the margin expansion available from production-grade contracts in regulated industries.
Market Dynamics
Cloud-native architecture is compressing deployment cycles and forcing perpetual-license vendors toward recurring-revenue models, while regulatory validation burdens for patient-specific implants concentrate competitive advantage among ISO 13485-certified platform providers.
Growth Catalysts
- Aerospace qualification protocols:FAA airworthiness criteria for flight hardware mandate traceable process-parameter records that only integrated software platforms can generate, pulling demand from tier-one suppliers.
- EU Medical Device Regulation:MDR enforcement tightens software validation requirements for patient-specific implants, creating captive demand for FDA-cleared build-preparation tools in European orthopedic markets.
- Germany's Mittelstadt belt:Machine-tool OEMs bundle software with metal powder-bed systems, embedding digital toolchain adoption into industrial manufacturing workflows.
Market Restraints
- Specialized talent scarcity:Qualified computational geometry engineers and thermal simulation specialists command premium compensation, inflating R&D overhead for mid-tier vendors.
- Input cost volatility:Cloud compute pricing for generative-design iterations fluctuates with energy markets, compressing margins for subscription-model providers serving mid-market users.
- Regulatory fragmentation:Divergent FDA 510(k) digital-health pathways and EU MDR validation timelines force dual-track compliance investments that favor capital-rich incumbents.
Strategic Opportunities
- Real-time melt-pool analytics:In-situ monitoring convergence with machine learning creates white space for predictive quality-assurance platforms in aerospace production contracts.
- India's industrial corridor:PLI scheme incentives for advanced manufacturing equipment adoption open distribution channels for cloud-native design-to-print workflows among domestic automotive suppliers.
- Japan's METI roadmap:National additive manufacturing standardization initiatives create regulatory tailwinds for software vendors aligning with JIS certification frameworks.
Industry Challenges
- Cross-functional skill integration:Production engineers must simultaneously command materials science, thermal physics, and software parameter tuning, creating acute hiring bottlenecks.
- Legacy ERP integration:Shop-floor data exchange between additive platforms and incumbent manufacturing execution systems requires costly custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Additive Manufacturing Software Market |
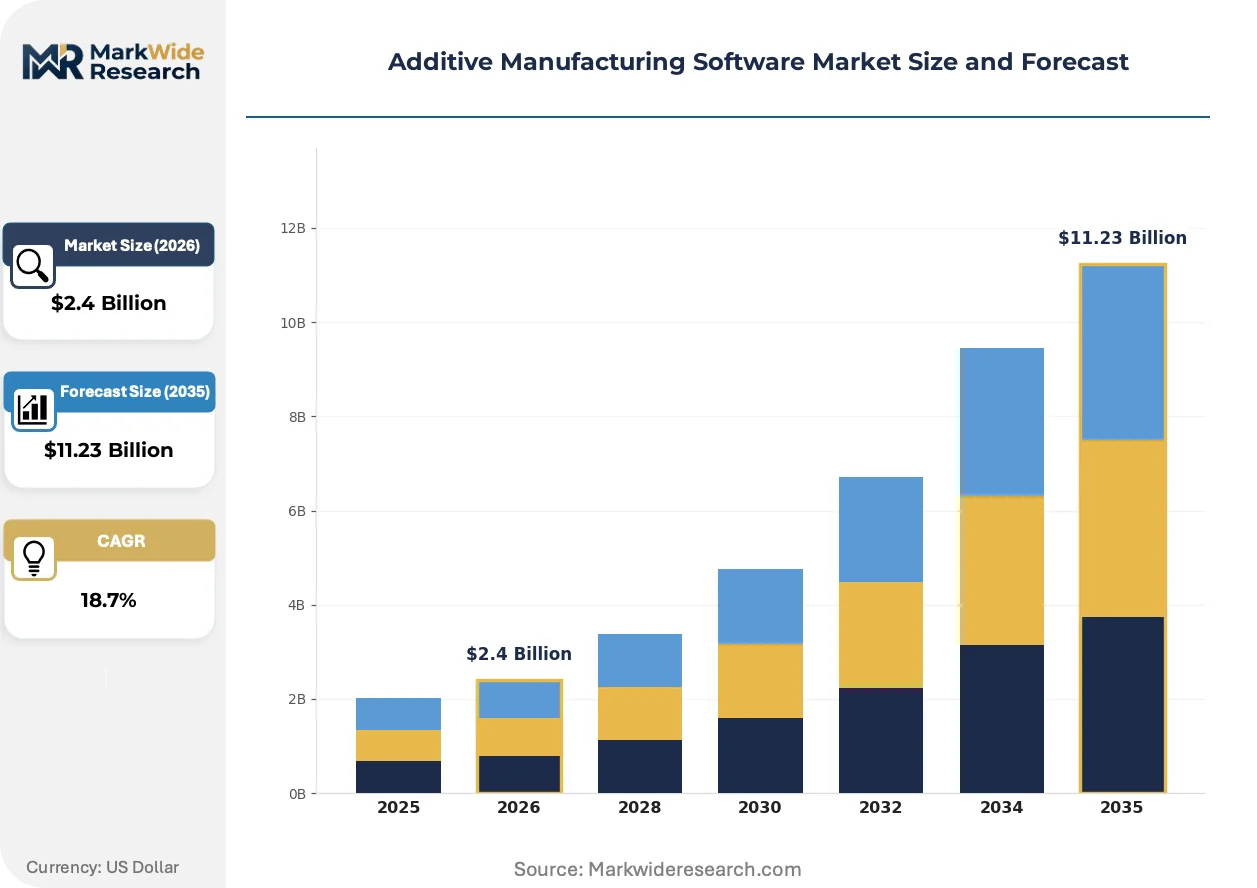
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $11.23 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Design Software, Simulation Tools, Slicing Software, Monitoring Solutions Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Aerospace, Automotive, Healthcare, Consumer Goods Application: Prototyping, Tooling, Production, Customization |
| Companies Covered | Stratasys, Velo3D, Materialise, EnvisionTEC, PTC, Autodesk, GE Additive, Proto Labs, 3D Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Additive Manufacturing Software Market Trends and Innovations
Generative-design algorithms and real-time process monitoring are collapsing the traditional separation between design optimization and production execution, compressing iteration cycles from weeks to hours.
Physics-informed neural networks for thermal distortion prediction are migrating from research environments into commercial build-preparation suites. Aerospace primes and medical device contract manufacturers deploy these tools for first-time-right qualification of complex geometries. The technology is migrating from academic licensing to embedded OEM partnerships, compressing the competitive window for standalone simulation vendors.
FDA's evolving digital-health guidance for software-as-medical-device creates compliance complexity for patient-specific implant workflows. The agency's predicate-device documentation requirements force vendors to maintain exhaustive design-control records. European orthopedic software providers face parallel EMA scrutiny, accelerating consolidation around ISO 13485-integrated quality systems.
Buyer concentration among tier-one aerospace and medical OEMs is compressing vendor negotiation leverage and extending payment terms. Procurement functions now demand outcome-based performance guarantees for software-enabled production contracts, displacing traditional per-seat licensing. This concentration is most visible in Germany's industrial belt, where machine-tool bundling agreements lock independent software vendors out of metal powder-bed installations.
Additive Manufacturing Software Market Segmentation
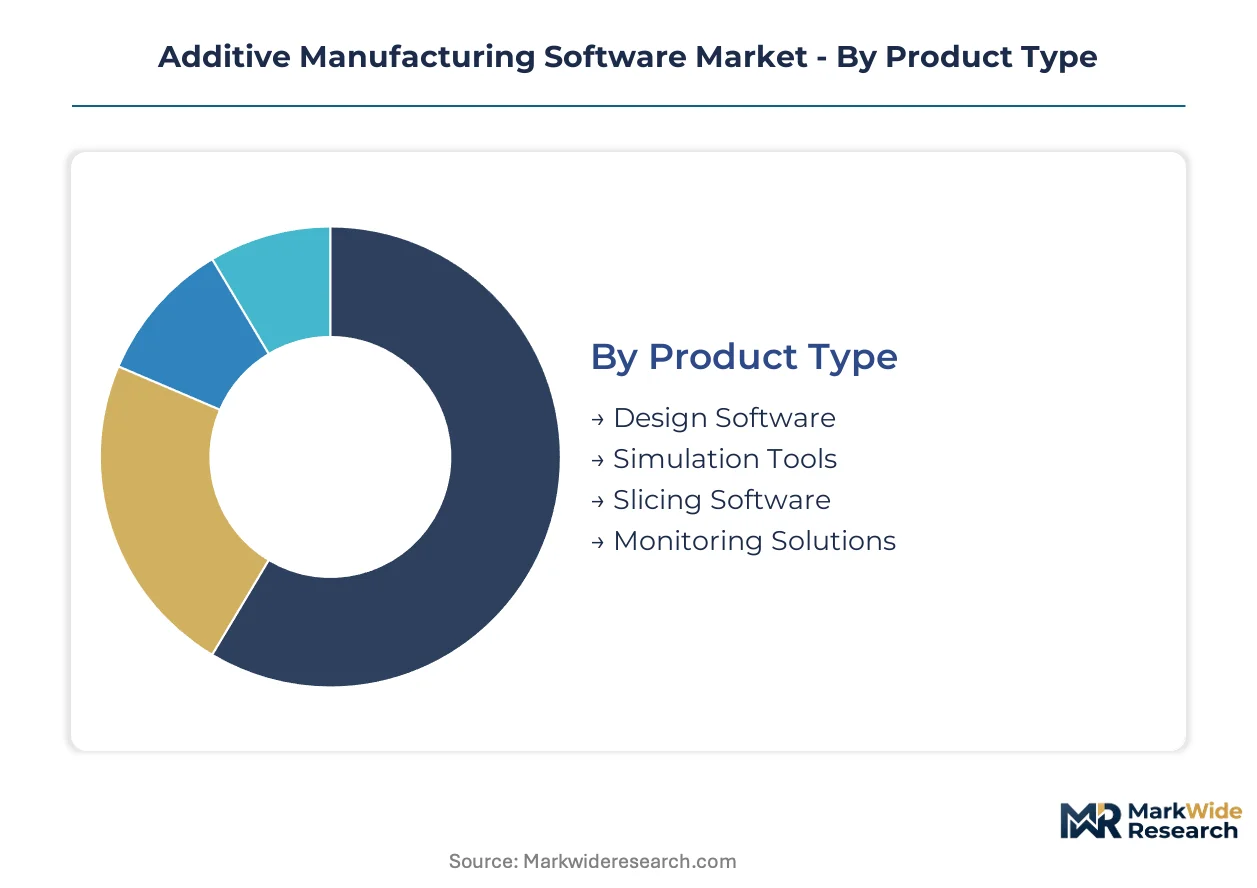
Segmentation in additive manufacturing software reveals divergent margin profiles and service intensity requirements across the digital toolchain. Vendors must calibrate pricing architecture and support infrastructure to match the computational demands and regulatory burdens inherent in each segment.
Product Type:
After-sales-service intensity varies sharply across the software stack, with simulation and monitoring solutions demanding continuous calibration support while design tools require less intervention post-deployment.
- Design Software:CAD-integrated platforms handle tessellation, lattice generation, and topology optimization for complex geometries. Demand clusters among Germany's Mittelstadt machine-tool OEMs bundling design-to-print workflows with metal powder-bed systems. Aerospace primes in Toulouse and Seattle drive premium module adoption for generative-design iterations.
- Simulation Tools:Physics-informed neural networks predict thermal distortion and residual stress in metal builds. FDA-cleared suites command validation premiums from orthopedic contract manufacturers in Warsaw and Minneapolis preparing patient-specific implant submissions. Cloud compute elasticity enables mid-tier users to access formerly enterprise-grade thermal modeling.
- Slicing Software:Converts optimized meshes into machine-readable G-code with laser power modulation and scan-vector sequencing.
- Monitoring Solutions:Real-time melt-pool analytics and pyrometry data streams for in-situ quality assurance.
By volume, design software leads. By growth pace, monitoring solutions are expanding most quickly.
Deployment:
Cost tier stratification separates capital-intensive on-premises installations from subscription-accessible cloud alternatives, with hybrid architectures capturing security-sensitive mid-market users.
- On-Premises:Perpetual-license installations on customer-managed servers satisfy ITAR-controlled aerospace facilities in California and Alabama. FAA airworthiness documentation requirements favor localized data retention for traceable process-parameter records.
- Cloud-Based:Elastic compute for generative-design iterations attracts automotive suppliers in Stuttgart and Pune seeking to avoid fixed infrastructure commitments. Autodesk's cloud-native architecture exemplifies recurring-revenue capture from this tier.
- Hybrid:Sensitive build data remains on-site while optimization workloads shift to cloud instances.
- SaaS:Browser-accessible build preparation with usage-based metering for prototype shops.
By installed base, on-premises retains dominance. By new contract velocity, cloud-based deployment is gaining share fastest.
End User:
Application maturity determines pricing power, with regulated medical and aerospace verticals accepting validation premiums while consumer goods buyers pressure per-seat costs.
- Aerospace:FAA airworthiness criteria mandate integrated software platforms generating traceable process-parameter records for flight hardware qualification. Tier-one suppliers in Toulouse, Hamburg, and Wichita embed build-preparation tools directly into production workflows.
- Healthcare:EU MDR and FDA 510(k) digital-health pathways impose ISO 13485 quality system requirements on patient-specific implant software. Materialise sustains European dominance through FDA-cleared build-preparation tools.
- Automotive:Tooling and production part qualification drives adoption among powertrain suppliers.
- Consumer Goods:Mass-customization workflows for eyewear and footwear accessories.
By contract value, aerospace leads. By regulatory-driven pricing expansion, healthcare shows the steepest trajectory.
Application:
Volume scale separates prototyping's high transaction frequency from production's concentrated revenue concentration, with tooling occupying an intermediate position on both dimensions.
- Production:Direct part manufacturing for aerospace brackets and orthopedic implants demands first-time-right qualification. Physics-informed neural networks for thermal distortion prediction migrate from research environments into commercial suites for this segment.
- Tooling:Conformal-cooled mold inserts and die components bridge prototype validation and production scale. Germany's automotive supply chain dominates regional demand for metal-printed injection molding tools.
- Prototyping:Design iteration acceleration for form-fit-function validation.
- Customization:Patient-specific implants and personalized consumer products.
By revenue concentration, production leads. By workflow integration depth, tooling demonstrates the fastest climb.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive suppliers in Stuttgart and Pune negotiate aggressively on per-seat licensing, while aerospace primes in Toulouse and Wichita absorb validation premiums without price elasticity. Medical device contract manufacturers in Warsaw and Minneapolis fall between these poles, accepting ISO 13485-driven cost premiums for FDA-cleared workflows.
United States
FAA airworthiness criteria for flight hardware pull demand from tier-one suppliers in Wichita and Seattle, mandating traceable process-parameter records. ITAR-controlled facilities in California and Alabama favor on-premises perpetual licenses for localized data retention. Cloud-native vendors capture recurring revenue from automotive suppliers in Detroit seeking elastic compute for generative-design iterations.
Germany
Machine-tool OEMs in the Mittelstadt belt bundle software with metal powder-bed systems, embedding digital toolchain adoption into industrial workflows. EU MDR enforcement tightens validation requirements for patient-specific implants, creating captive demand for ISO 13485-certified build-preparation tools. Automotive powertrain suppliers in Stuttgart drive conformal-cooled tooling adoption for injection molding applications.
China
Domestic machine-tool manufacturers in Yangtze River Delta clusters integrate build-preparation modules with metal powder-bed systems for aerospace subcontractors. MIIT standardization initiatives for additive manufacturing create regulatory tailwinds for software vendors aligning with GB certification frameworks. Automotive suppliers in Shenzhen and Chongqing pilot cloud-native design-to-print workflows for rapid prototyping.
India
PLI scheme incentives for advanced manufacturing equipment adoption open distribution channels for cloud-native workflows among automotive suppliers in Pune and Chennai. Domestic medical device manufacturers in Hyderabad and Ahmedabad face CDSCO scrutiny for patient-specific implant software, favoring vendors with predicate-device documentation. Tier-two machine shops in Gujarat and Tamil Nadu pressure vendors on subscription pricing.
Japan
METI national additive manufacturing standardization initiatives create regulatory tailwinds for software vendors aligning with JIS certification frameworks. Precision equipment manufacturers in Nagoya and Osaka integrate build-preparation tools with hybrid manufacturing systems. Aerospace subcontractors in Kobe and Fukuoka demand real-time melt-pool analytics for first-time-right qualification.
Additive Manufacturing Software Market Competitive Landscape
Cloud-native platform vendors and perpetual-license incumbents split the market along deployment-architecture lines, with regulatory certification acting as the decisive segmentation variable. The vendor base concentrates around three strategic archetypes: vertically integrated printer-software bundlers, independent build-preparation specialists, and CAD-integrated workflow providers. M&A activity targets ISO 13485-certified medical specialists, while strategic partnerships between machine-tool OEMs and software vendors lock out independent challengers from metal powder-bed installations.
Within the CAD-integrated tier, Autodesk exemplifies cloud-native recurring-revenue capture, while Materialise occupies a position anchoring medical segmentation through FDA-cleared build-preparation tools. Stratasys represents the printer-software bundling archetype, locking material consumption through integrated workflows. These three companies illustrate how regulatory certification, deployment architecture, and hardware bundling constitute the primary competitive dimensions.
| Leading Market Players |
|---|
| Stratasys |
| Velo3D |
| Materialise |
| EnvisionTEC |
| PTC |
| Autodesk |
| GE Additive |
| Proto Labs |
| 3D Systems |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in cloud compute infrastructure across Germany's Mittelstadt belt is compressing subscription pricing for design-to-print workflows while simultaneously pressuring machine-tool OEMs to absorb software bundling costs into hardware margins. This utilization dynamic forces perpetual-license vendors toward recurring-revenue models and concentrates pricing power among ISO 13485-certified platform providers serving regulated aerospace and medical verticals.
Pricing Analysis
After-sales service revenue from extended calibration contracts and validation support drives lifetime value for simulation and monitoring suite vendors. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and deployment architecture, with FDA-cleared medical modules commanding substantial premiums over uncertified alternatives. Pricing pressure stems from automotive suppliers in Stuttgart and Pune negotiating aggressively on per-seat licensing for generative-design iterations. Consumer goods prototyping shops exhibit highest price sensitivity, while aerospace primes in Toulouse and Wichita absorb validation premiums without elasticity.
Supply Chain Analysis
Extended payment terms demanded by tier-one aerospace and medical OEMs are straining working capital for independent software vendors competing against machine-tool bundlers. Supply concentration centers on Germany, the United States, and China, with cloud infrastructure providers in Frankfurt, Virginia, and Shanghai anchoring elastic compute delivery. The digital toolchain draws from specialized computational geometry engineering talent, GPU compute clusters, and regulatory consulting capacity. Single-source vulnerability around cloud hyperscaler concentration creates exposure for subscription-model providers. Distribution runs through direct enterprise sales teams, OEM bundling agreements, and channel partners serving mid-market prototype shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Additive manufacturing software represents a high-growth disruption as physics-informed neural networks collapse design-to-production iteration cycles from weeks to hours, while FAA and EU MDR regulatory frameworks simultaneously raise barriers to entry.
For Market Incumbents: Entrench regulatory certification moats by accelerating ISO 13485 quality system investments ahead of EU MDR enforcement expansion, while securing exclusive bundling agreements with metal powder-bed OEMs in Germany's industrial belt to lock out independent challengers. Cloud-native architecture migration remains essential as perpetual-license revenue pools narrow. Threat substitution from open-source build-preparation tools demands continuous R&D differentiation in thermal simulation accuracy. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized automotive supplier corridor, where cloud-native design-to-print workflows face lower incumbent saturation and price elasticity favors subscription penetration. White-space opportunities concentrate in real-time melt-pool analytics for aerospace subcontractors and FDA-cleared segmentation tools for domestic Indian orthopedic manufacturers. Go-to-market execution should leverage channel partnerships with advanced manufacturing equipment distributors rather than direct enterprise sales. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because certification burdens in medical and aerospace verticals create durable competitive moats that compound over extended procurement cycles. Acquisition targets should prioritize ISO 13485-certified build-preparation specialists with predicate-device documentation libraries and established FDA 510(k) pathways. Monitor FAA airworthiness criteria evolution as the decisive inflection signal for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Investment | ISO 13485 quality systems and FDA 510(k) pathways create captive demand in European orthopedic markets. |
| Cloud-Native Architecture Migration | Elastic compute for generative-design iterations captures recurring revenue from mid-tier automotive suppliers. |
| OEM Bundling Partnership | Machine-tool OEMs in Germany's Mittelstadt belt embed software adoption into metal powder-bed workflows. |
| Real-Time Monitoring Platform Launch | In-situ melt-pool analytics with machine learning addresses first-time-right qualification demands from aerospace primes. |
| Geographic Expansion | India's PLI scheme incentives open distribution channels for cloud-native workflows among domestic automotive suppliers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with additive manufacturing software executives, aerospace production engineers, orthopedic contract manufacturing managers, and cloud platform procurement officers. Secondary validation incorporated SEC filings from publicly traded vendors, FAA airworthiness directives, EU MDR guidance documents, and machine-tool OEM partnership announcements. Bottom-up segment sizing triangulated against top-down market envelope estimates derived from metal powder-bed system shipment data and software attach-rate assumptions.
Calibration against historical license conversion rates and cloud subscription renewal patterns anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, end-user vertical, application maturity, and regulatory certification tier. CAGRs were derived from elasticity-adjusted adoption curves and replacement-cycle analysis. Industry-specific forecast inputs encompassed FAA qualification timeline acceleration and EU MDR enforcement phase-in schedules.
Sensitivities concentrate around cloud compute pricing volatility, regulatory approval timeline slippage, and aerospace production contract award delays. Forecasts reflect documented assumptions regarding attach-rate evolution and vertical penetration ceilings. Macroeconomic contraction in capital equipment spending, regulatory harmonization failure between FDA and EMA pathways, or breakthrough open-source thermal simulation accuracy would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
United States 3D Printing Market
3D Printing Technology
North America Industrial 3D Printing Market
3D Printing Technology
PEEK Filament Market
3D Printing Technology
3D Concrete Printers Market
3D Printing Technology
3D Printing for Medical Market
3D Printing Technology
3D Printing Technology in Pharmaceutical Market
3D Printing Technology
Asia-Pacific Additive Manufacturing Market
3D Printing Technology
Conventional and Rapid Prototyping Market
3D Printing Technology
Global 3D Pens Market
3D Printing Technology
North America Additive Manufacturing Market
3D Printing Technology
North America Additive Manufacturing with Metal Powders Market
3D Printing Technology
3D Printing Robots Market
3D Printing Technology
3D Printer Market
3D Printing Technology
Military 3D Printing Market
3D Printing Technology
Aluminum Alloy 3D Printing Service Market
3D Printing Technology
Global Automated 3D Printing Market