
 Architectural Metal Coatings Market | 2026-2036
Architectural Metal Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Architectural Metal Coatings Market Insights
Performance-based coating maintenance contracts is restructuring how architectural metal finish suppliers monetize long-term building envelopes. PPG Industries, Inc. leverages its commercial coatings service network to embed multi-year substrate protection agreements into original specification packages. Akzo Nobel N.V. anchors its Interpon powder platform with digital color-matching subscriptions that lock fabricators into recurring specification cycles. The Sherwin-Williams Company dominates the North American coil coating channel through controlled distribution relationships with metal service centers.
Architectural metal coatings are resin-based protective films applied to aluminum, steel, and zinc substrates through spray, dip, or electrostatic processes, typically achieving dry film thicknesses of 25–100 microns to resist UV degradation, salt corrosion, and thermal cycling in exterior building applications. Fluoropolymer formulations command premium specification for high-rise facades and monumental roofing systems where color retention warranties extend beyond three decades. Powder coating technology leads volume throughput among fabrication workshops serving commercial construction, while liquid polyurethane systems retain share in field-applied renovation scenarios where on-site curing flexibility matters. Acrylic-alkyd hybrids occupy the economy tier for interior panel and balcony railing applications where aesthetic longevity requirements moderate.
EPA VOC regulations under the National Emission Standards for Hazardous Air Pollutants constrain solvent-borne liquid coating formulations across US fabrication facilities, pushing capital allocation toward powder coating conversion. REACH compliance and the EU Green Deal's embodied carbon reporting requirements through CSRD are elevating demand for water-reducible and high-solids alternatives in European specification channels. China's MEE enforcement of GB 30981 limits on architectural coating VOC content is compressing traditional alkyd production capacity in Shandong and Jiangsu provinces. Stakeholders must monitor how divergent regional chemical restriction timelines reshape formulation R&D prioritization and capital deployment across multi-continental manufacturing footprints.
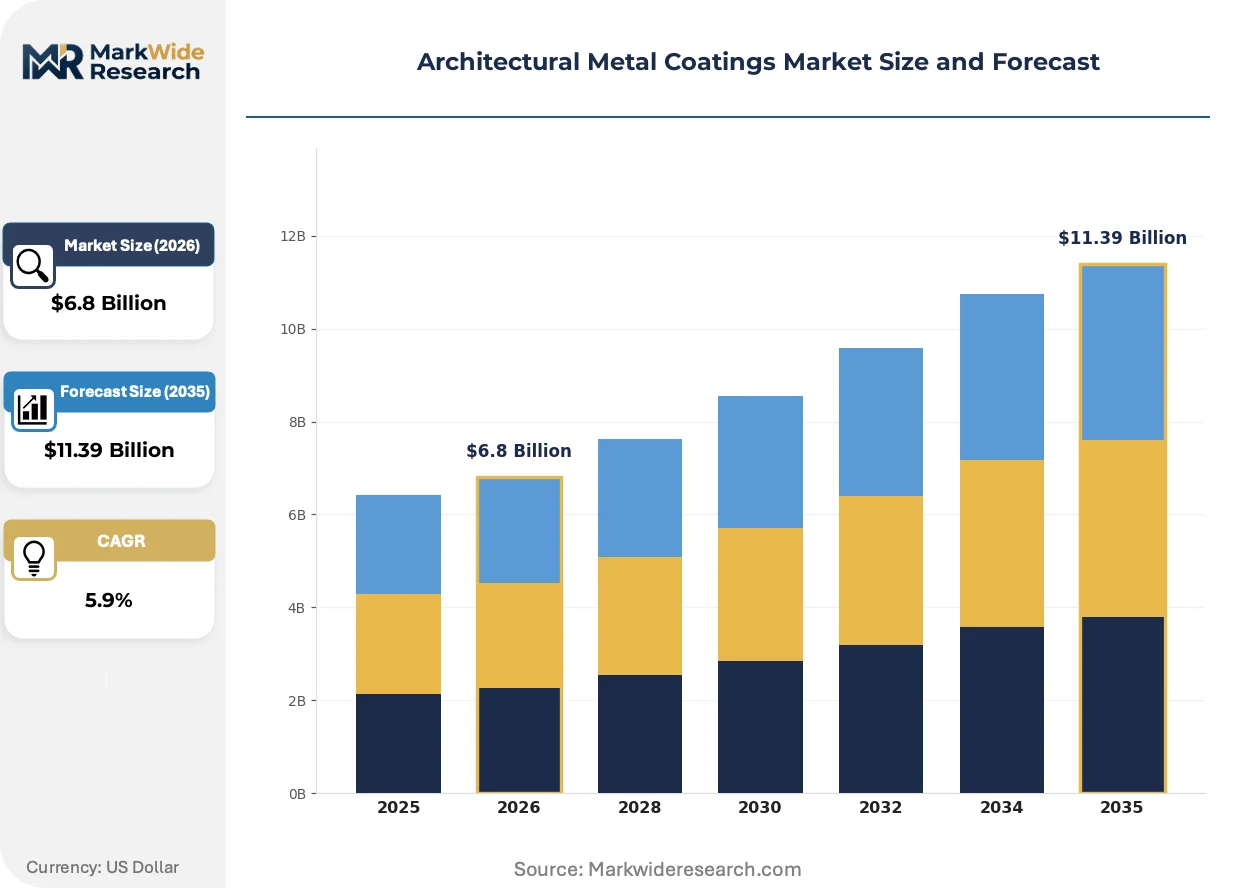
Market Dynamics
Performance-based maintenance contracts are restructuring monetization models across architectural metal finish supply chains, embedding long-term substrate protection into original specification packages and locking fabricators into recurring revenue cycles.
Growth Catalysts
- Fluoropolymer specification intensity:High-rise facade engineers specify extended-durability systems for curtain wall assemblies requiring multi-decade color retention warranties.
- India's western corridor infrastructure:New airport terminals and metro projects between Mumbai and Pune concentrate demand for premium metal finishes.
- EU F-Gas Regulation tightening:Permissible fluorinated compound limits in coating formulations accelerate reformulation toward lower-GWP alternatives.
Market Restraints
- Petrochemical feedstock volatility:Resin and solvent input costs fluctuate with crude oil derivatives, compressing formulation margins.
- MEE enforcement in Shandong:China's GB 30981 VOC limits are compressing traditional alkyd production capacity in coastal manufacturing provinces.
- Fluoropolymer technical ceiling:Premium systems require specialized application equipment and controlled-facility curing, limiting field deployment flexibility.
Strategic Opportunities
- Powder coating channel expansion:Fabrication workshops serving commercial construction represent underpenetrated conversion targets from liquid systems.
- Water-reducible formulation R&D:REACH compliance and CSRD embodied carbon reporting elevate specification pull for high-solids alternatives.
- Digital color-matching subscriptions:Recurring specification cycles lock metal service centers into platform-dependent procurement patterns.
Industry Challenges
- Applicator certification timelines:Fluoropolymer warranty programs require factory-trained technician credentials that constrain installation capacity scaling.
- Multi-continental formulation divergence:Divergent regional chemical restriction timelines force parallel R&D tracks and capital deployment fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Architectural Metal Coatings Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Epoxy, Acrylic, Alkyd, Silicone, Fluoropolymer Application: Building Facades, Roofing Systems, Window Frames, Doors, Interior Panels, Balconies Technology: Powder Coating, Liquid Coating, Anodizing, Electroplating, Thermal Spray, Galvanization End User: Construction Firms, Property Developers, Architectural Firms, Industrial Fabricators, Renovation Contractors, Fabrication Workshops |
| Companies Covered | The Sherwin-Williams Company, Akzo Nobel N.V., Axalta Coating Systems Ltd., PPG Industries, Inc., Beckers Group, Nippon Paint Holdings Co., Ltd., Kansai Paint Co., Ltd., Hempel A/S, Jotun A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Architectural Metal Coatings Market Trends and Innovations
Coating application technology and regulatory chemistry standards are actively reshaping competitive positioning, compressing traditional liquid system share while elevating digital-enabled service models.
Super-durable powder formulations is modularizing specification workflows for monumental roofing and high-rise envelope projects. Regional fabricators serving commercial construction are converting spray lines at accelerating pace. This technology is modularizing color-change logistics and reducing waste-stream disposal burdens.
REACH compliance and the EU Green Deal's embodied carbon reporting requirements are elevating demand for water-reducible and high-solids alternatives. European specification channels now prioritize products with verified lifecycle impact documentation. Coil coating operations in Germany and the Netherlands are retrofitting lines to handle reduced-solvent chemistries.
Specification authority is concentrating among architectural engineering firms managing envelope performance warranties. Metal service centers are losing direct influence as engineers embed coating selection into design-phase substrate protection agreements. This concentration is most visible in North American commercial construction where PPG Industries and Sherwin-Williams battle for controlled distribution relationships.
Architectural Metal Coatings Market Segmentation
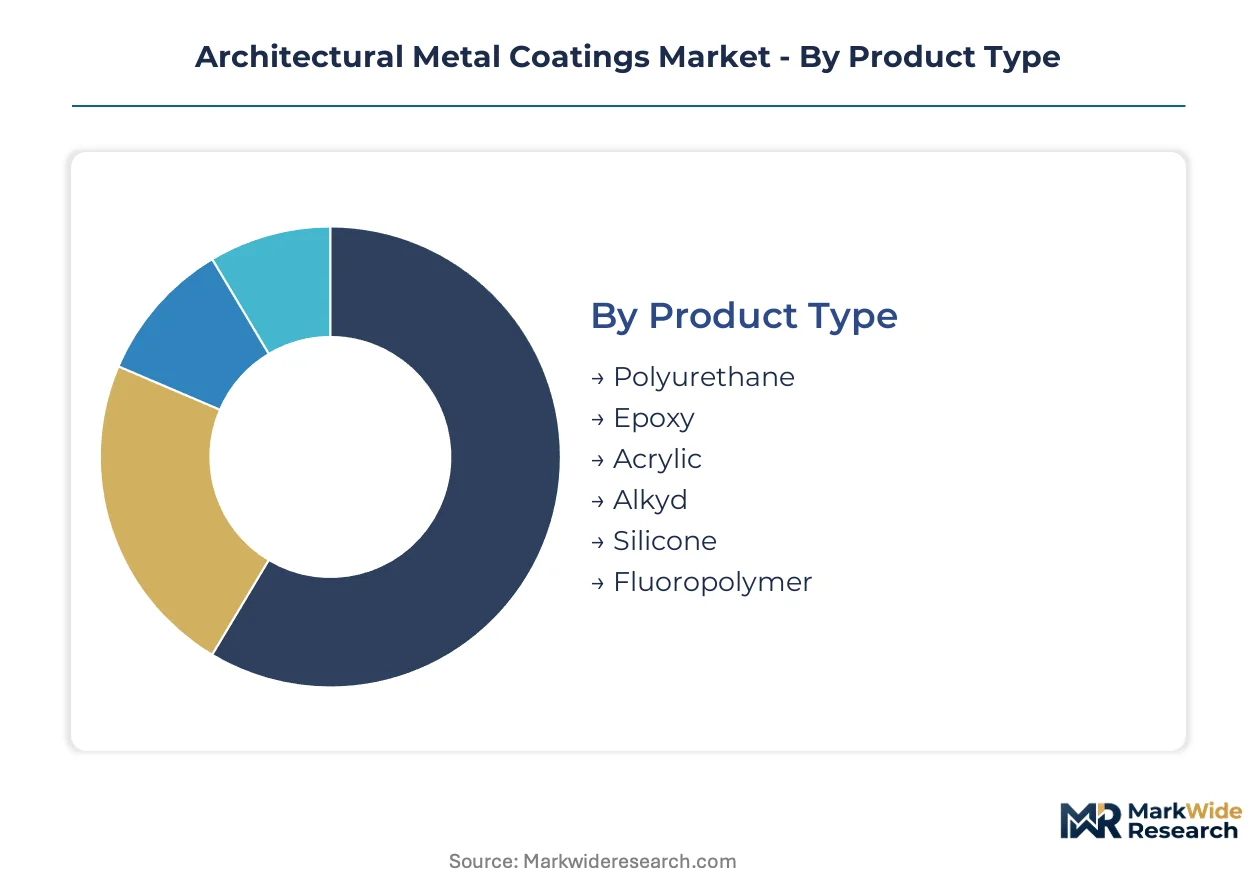
Architectural metal coatings segment across formulation chemistry, application method, and procurement channel, with each dimension carrying distinct margin profiles and specification authority. Understanding these splits reveals where technology leadership concentrates versus where volume throughput dominates.
Product Type:
Volume concentrates in economy-tier acrylic and alkyd formulations, while premium capture sits with fluoropolymer systems commanding extended-warranty specification.
- Fluoropolymer:PVDF and FEVE resin systems achieve 70% gloss retention after three decades of UV exposure. Demand concentrates on high-rise curtain walls in the UAE and Singapore where envelope performance warranties exceed 25 years. GB 30981 VOC limits and EU F-Gas Regulation are accelerating reformulation toward lower-GWP fluorinated alternatives.
- Polyurethane:Two-component aliphatic systems balance abrasion resistance with field-application flexibility. Specification clusters in North American renovation channels where on-site curing accommodates existing substrate conditions. Moisture-cure variants serve coastal industrial fabricators requiring salt-spray protection without bake ovens.
- Epoxy:Amine-cured systems dominate interior panel and structural steel priming applications where UV exposure remains minimal.
- Acrylic:Water-borne emulsions serve economy-tier balcony railing and decorative metalwork with moderate durability requirements.
- Alkyd:Traditional solvent-borne formulations face compression from China's MEE enforcement in Shandong and Jiangsu provinces.
- Silicone:High-temperature resistant coatings protect exhaust stacks and industrial ventilation hardware on commercial rooftops.
Today's leader: Fluoropolymer. Tomorrow's challenger: Polyurethane.
Application:
Facade and roofing specification drives premium formulation pull, while interior and secondary elements sustain volume throughput.
- Building Facades:Curtain wall assemblies require multi-layer coating systems achieving 25-100 micron dry film thickness. India's western corridor between Mumbai and Pune concentrates new terminal construction demanding 30-year color retention. Super-durable powder formulations are modularizing specification workflows for monumental envelope projects.
- Roofing Systems:Standing seam metal and composite panel roofing specify high-build fluoropolymer or silicone-modified polyester systems. Demand clusters in commercial construction across Germany and the Netherlands where CSRD embodied carbon reporting elevates lifecycle documentation requirements. Coil coating operations are retrofitting lines for reduced-solvent chemistries.
- Window Frames:Thermal break aluminum systems specify thin-film powder coatings for corner coverage and edge retention.
- Doors:High-traffic entry systems prioritize abrasion-resistant polyurethane or epoxy formulations.
- Interior Panels:Acrylic-alkyd hybrids occupy specification for aesthetic metalwork with minimal weathering exposure.
- Balconies:Coastal installations drive salt-spray resistant specification in Mediterranean and Southeast Asian markets.
Facade specification retains pricing power. Roofing volume expands fastest.
Technology:
Application method determines capital intensity, environmental compliance burden, and field versus factory deployment flexibility.
- Powder Coating:Electrostatic spray deposition achieves near-zero VOC emissions with overspray recovery rates exceeding 95%. Fabrication workshops serving commercial construction are converting liquid lines at accelerating pace. This technology is modularizing color-change logistics and reducing waste-stream disposal burdens.
- Liquid Coating:Solvent-borne and water-reducible systems retain specification in field-applied renovation scenarios. EPA NESHAP constraints across US fabrication facilities are pushing capital allocation toward powder conversion. High-solids polyurethane serves on-site touch-up and warranty repair work.
- Anodizing:Electrochemical oxide formation on aluminum substrates provides integral corrosion protection without organic films.
- Electroplating:Zinc and chrome deposition protects structural hardware and decorative metal components.
- Thermal Spray:Arc-sprayed aluminum and zinc coatings protect steel in aggressive marine environments.
- Galvanization:Hot-dip zinc coating dominates structural steel protection for infrastructure and industrial applications.
Powder coating leads factory throughput. Liquid systems defend renovation access.
End User:
Specification authority concentrates among engineering firms embedding substrate protection into design-phase agreements, compressing direct metal service center influence.
- Construction Firms:General contractors bundle coating specification into envelope performance warranties on commercial and institutional projects. PPG Industries and Sherwin-Williams battle for controlled distribution relationships through multi-year substrate protection agreements.
- Architectural Firms:Design-phase specification authority increasingly dictates coating selection before fabrication procurement. Akzo Nobel anchors fabricator relationships through Interpon powder platform digital color-matching subscriptions that lock recurring specification cycles.
- Property Developers:Asset-holding entities prioritize lifecycle cost over first-cost on premium commercial and residential portfolios.
- Industrial Fabricators:OEM metal component suppliers specify coatings compatible with automated production lines.
- Renovation Contractors:Field-applied liquid systems serve existing building envelope refresh and warranty repair channels.
- Fabrication Workshops:Regional metal service centers convert between liquid and powder systems based on customer mix and regulatory pressure.
Architectural firms capture specification authority. Fabrication workshops face margin compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting coating formulation capacity toward jurisdictions with slower chemical restriction timelines. Manufacturers face divergent compliance costs across North America, Europe, and Asia-Pacific, reshaping where capital deploys for new production lines.
United States
Commercial construction in Texas and Florida drives specification of high-performance fluoropolymer systems for hurricane-resistant building envelopes. EPA NESHAP enforcement constrains solvent-borne liquid coating formulations across fabrication facilities, accelerating powder coating conversion. Coil coating operations in the Midwest serve regional metal service centers with controlled distribution relationships.
Germany
CSRD embodied carbon reporting requirements elevate demand for water-reducible and high-solids alternatives in European specification channels. REACH compliance forces reformulation away from legacy chemistries. Coil coating lines in the Ruhr region and Bavaria retrofit for reduced-solvent handling capabilities.
China
MEE enforcement of GB 30981 limits compresses traditional alkyd production capacity in Shandong and Jiangsu provinces. Dual carbon goals accelerate low-VOC powder coating adoption across Yangtze River Delta fabrication workshops. Coastal manufacturers migrate capacity inland to escape tightening environmental inspections.
India
New airport terminals and metro infrastructure between Mumbai and Pune concentrate demand for extended-durability metal finishes. BIS standards on coating performance create specification barriers for imported formulations. Western corridor fabricators convert from liquid to powder systems to meet tightening state-level pollution control mandates.
UAE
High-rise facade projects in Dubai and Abu Dhabi specify PVDF systems achieving three-decade color retention warranties. MOHAP building material regulations align coating specification with Gulf Cooperation Council harmonization efforts. Local fabrication workshops serve Saudi Arabia and Qatar export markets from Jebel Ali industrial clusters.
Architectural Metal Coatings Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation technology holding pricing power in premium specification channels while volume throughput concentrates among regional fabricators. The vendor base organizes into three tiers: multinational coating houses controlling specification authority, mid-cap regional specialists serving fabrication workshops, and local contract manufacturers competing on conversion cost. Consolidation pressure runs highest where digital color-matching platforms lock recurring procurement cycles. Dominant competitive moves include strategic partnerships with architectural engineering firms and backward integration into resin production.
Within the multinational tier, PPG Industries, Inc., Akzo Nobel N.V., and The Sherwin-Williams Company occupy positions anchoring controlled distribution relationships with metal service centers. These entities exemplify the specification-driven archetype where multi-year substrate protection agreements embed long-term revenue into original project packages. Their geographic footprints span North American, European, and Asia-Pacific production bases, reflecting the capital intensity required to serve divergent regulatory environments simultaneously.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| Akzo Nobel N.V. |
| Axalta Coating Systems Ltd. |
| PPG Industries, Inc. |
| Beckers Group |
| Nippon Paint Holdings Co., Ltd. |
| Kansai Paint Co., Ltd. |
| Hempel A/S |
| Jotun A/S |
| Others |
Pricing and Supply Chain Analysis
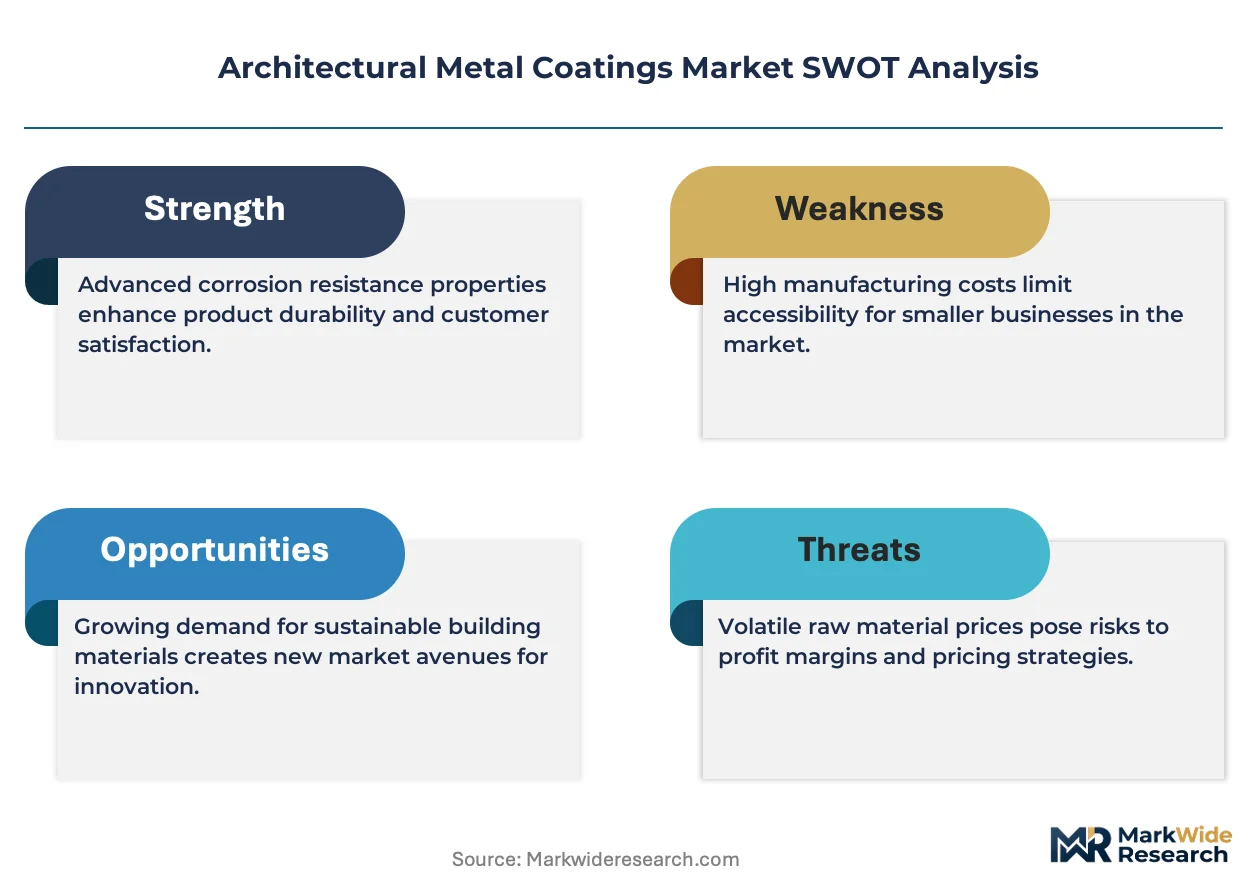
Backward integration into fluoropolymer resin production anchors pricing power for multinational coating houses serving specification-driven commercial construction channels. PPG Industries and Akzo Nobel leverage captive supply chains to defend premium-position margins against volatile petrochemical feedstock swings while regional fabricators absorb cost compression from China's MEE enforcement of GB 30981 VOC limits.
Pricing Analysis
Distributor margin stacking separates specification-grade fluoropolymer systems from economy-tier acrylic-alkyd hybrids through certification-grade differentiation. Three-tier pricing structure across premium, standard, and economy levels reflects warranty duration tiers and application complexity rather than raw material cost alone. Cost compression in solvent-borne liquid formulations is intensifying because EPA NESHAP compliance requires capital-intensive powder conversion. Property developers and architectural engineering firms demonstrate lowest price sensitivity due to lifecycle-cost framing, while renovation contractors and regional fabrication workshops face acute margin pressure from regulatory-driven equipment upgrades.
Supply Chain Analysis
India's BIS standards on coating performance and China's GB 30981 limits are reshaping sourcing patterns toward domestic formulation capacity. Resin production concentrates in Germany, China, and the United States, with fluoropolymer feedstocks drawing from specialty chemical operations in the Ruhr region and Yangtze River Delta. Pigment and solvent dependencies rest on titanium dioxide from Chinese sulfate-process plants and petrochemical derivatives from Gulf Coast crackers. Single-source vulnerability runs through concentrated PVDF resin supply for premium facade specification. Distribution runs through metal service centers and architectural engineering firms embedding substrate protection into design-phase agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where divergent regulatory timelines between China's accelerated VOC enforcement and India's emerging BIS standards create formulation capacity relocation incentives.
For Market Incumbents: Cement specification authority through multi-year substrate protection agreements that lock architectural engineering firms into recurring procurement cycles. Deepen backward integration into fluoropolymer resin production to offset petrochemical feedstock volatility threatening formulation margins. Defend against powder coating conversion pressure by controlling digital color-matching platforms that fabricators depend on for project workflow efficiency. For New Entrants and Emerging Players: EU F-Gas Regulation in Europe opens a window for lower-GWP fluorinated alternative formulations that incumbent coating houses must reformulate toward. Target India's western corridor fabrication workshops converting from liquid to powder systems under state-level pollution control mandates. Penetrate through water-reducible formulation partnerships with regional metal service centers seeking REACH compliance pathways without multinational coating house premiums. For Investors and Strategic Acquirers: Consolidation pressure builds where digital color-matching platforms lock recurring specification cycles and regional fabricators face margin compression from regulatory compliance costs. Acquisition targets include mid-cap powder coating specialists with captive application equipment fleets and established relationships with commercial construction general contractors. Monitor MEE enforcement intensity in Shandong and Jiangsu provinces as an inflection indicator for Chinese capacity migration patterns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive fluoropolymer supply insulates margin structure from petrochemical derivative volatility. |
| Powder Coating Line Conversion | Near-zero VOC emissions satisfy China's MEE enforcement while reducing waste-stream disposal burdens. |
| Digital Color-Matching Platform Deployment | Subscription models lock fabrication workshops into recurring specification cycles with platform-dependent procurement. |
| Water-Reducible Formulation R&D | High-solids alternatives capture specification pull from EU CSRD embodied carbon reporting requirements. |
| Multi-Year Substrate Protection Agreements | Performance-based contracts embed long-term revenue into original commercial construction project packages. |
Research Methodology
Multiple input streams — primary interviews with coating formulation chemists, architectural specification consultants, and metal service center procurement leads; secondary validation through customs trade data, SEC 10-K filings, and Cefic regional production reports; plus patent and regulatory filing analysis — were reconciled through bottom-up and top-down triangulation. Stakeholder conversations spanned plant managers at coil coating operations, technical R&D directors at multinational coating houses, and envelope performance warranty managers at commercial construction firms.
Data-stream reconciliation across the projection horizon applied segment-level modeling across formulation chemistry tiers, application method categories, end-use industry clusters, and regional regulatory frameworks. CAGRs were derived from installed base analysis and replacement cycle dynamics rather than simple trend extrapolation. Forecast inputs incorporated fluoropolymer specification intensity curves, powder coating conversion rates at fabrication workshops, and divergent VOC compliance timeline impacts on regional production capacity.
Revisions become necessary when MEE enforcement intensity shifts in China's coastal provinces, EU F-Gas Regulation implementation accelerates, or petrochemical feedstock volatility disrupts resin cost structures beyond historical bands. Forecasts reflect documented assumptions about specification authority concentration and technology substitution rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Europe Waterborne Polyurethane Coatings Market
Coatings
Thailand Architectural Coatings Market
Coatings
Ultraviolet (UV) Coatings Market
Coatings
South Africa Automotive OEM Coatings Market
Coatings
ASEAN Protective Coatings Market
Coatings
Shipping Container Coatings Market
Coatings
Middle East and Africa Super Hydrophobic Coatings Market
Coatings
Carbon Fiber Coatings Market
Coatings
Protective Coatings Market
Coatings
Asia-Pacific Superhydrophobic Coating Market
Coatings
Global Performance Coating Market
Coatings
Epoxy Powder Coatings Market
Coatings
Asia-Pacific Radiation Curable Coatings Market
Coatings
Packaging Coatings Market
Coatings
Sustained Release Coatings Market
Coatings
Waterborne Automobile Coating Market