
 North America Coil Coatings Market | 2026-2036
North America Coil Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
North America Coil Coatings Market Analytics
EPA VOC regulations for architectural coatings is recalibrating the cost-of-entry calculus for coil coating producers serving North American construction markets. AkzoNobel N.V. leverages its integrated resin and pigment supply chain to maintain formulation flexibility under shifting compliance thresholds. PPG Industries, Inc. anchors its position through deep relationships with regional steel mills across the United States and Mexico. BASF SE differentiates via specialty polyurethane intermediates that reduce cure energy while meeting performance specifications for exterior metal cladding.
Coil coatings are factory-applied liquid or powder finishes cured onto continuous metal strips, typically aluminum or galvanized steel, at line speeds exceeding 150 meters per minute to deliver uniform film thickness and corrosion resistance for downstream forming and fabrication. The primary commercial purpose centers on extending substrate lifespan in exterior building envelopes, automotive body panels, and appliance housings where field painting proves impractical. Polyester formulations dominate volume across roofing and wall panel applications due to their balance of cost and weatherability, while fluoropolymer coatings command premium positioning in high-performance exterior segments where chalk resistance and color retention define specification value. Roll coating technology leads production throughput for flat construction metal, though spray coating maintains share in custom architectural profiles requiring multi-color or textured finishes.
FERC efficiency standards for commercial building envelopes and OSHA workplace chemical exposure limits interact with EPA rules to shape formulation choices and capital allocation across the North American supply base. Health Canada and PMRA maintain parallel but distinct chemical substance review processes that affect cross-border product registration for coatings manufacturers operating in both markets. Stakeholders must monitor pending revisions to state-level VOC rules in California and northeastern jurisdictions, as these often prefigure broader North American compliance baselines that reshape competitive positioning for imported and domestic formulations alike.
Market Dynamics
The North American coil coatings sector is undergoing a fundamental recalibration as EPA VOC emission thresholds tighten and pre-coated metal displaces field-applied finishes across commercial construction. Formulation flexibility now determines competitive survival as waterborne systems capture specification share from solvent-borne alternatives.
Growth Catalysts
- EPA Architectural Coating Standards:Federal VOC limits are accelerating specification shifts toward waterborne polyester and polyurethane systems in roofing and wall panel applications across the United States.
- Pre-fabricated Metal Construction:Warehouse and distribution center developers in the southeastern United States are specifying factory-applied coil coatings to compress construction schedules and eliminate field painting.
- FERC Building Envelope Efficiency Mandates:Commercial envelope performance standards are driving thermal-reflective coating adoption on metal roofing systems to reduce HVAC loads.
Market Restraints
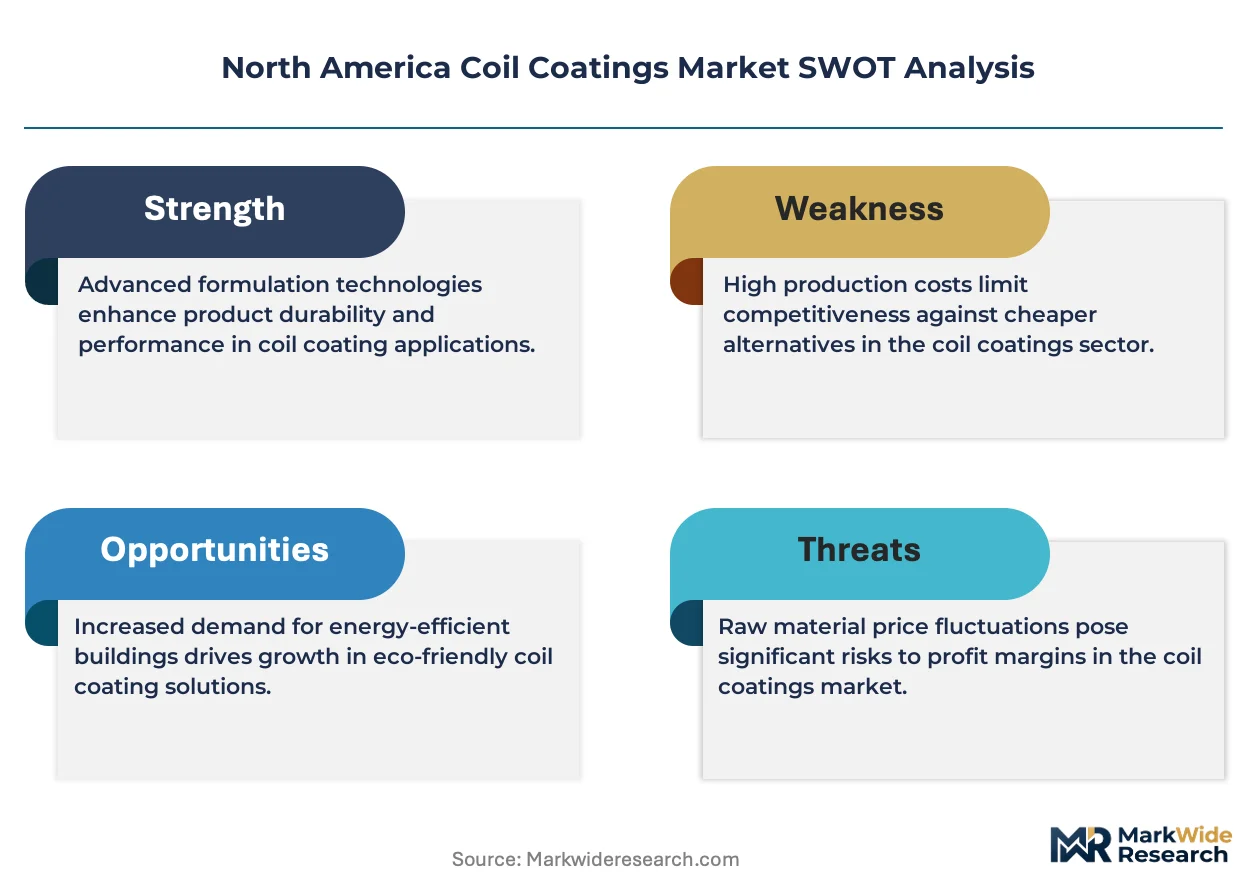
- Titanium Dioxide Supply Concentration:Pigment cost volatility and concentrated global production in China create margin pressure for North American formulators dependent on white-hiding performance.
- Fluoropolymer Raw Material Access:Limited domestic production of PVDF resin forces reliance on imported feedstocks subject to tariff and logistics disruption risk.
- Cure Energy Requirements:High-temperature baking processes for polyester and silicone-modified polyester systems limit line speed improvements and constrain throughput economics.
Strategic Opportunities
- Mexico Manufacturing Expansion:Nearshoring of appliance and automotive production is creating demand for coil-coated metal substrates at northern Mexico industrial parks.
- UV-Curable Formulation Development:Energy-cured coating technology convergence with LED curing systems offers pathway to ambient-temperature processing and line speed gains.
- Canadian Cross-Border Registration Efficiency:Streamlined PMRA-EPA data sharing protocols are reducing time-to-market for formulations registered in both jurisdictions.
Industry Challenges
- Formulation Chemist Talent Scarcity:Specialized expertise in waterborne resin design and low-VOC additive selection is concentrating at larger integrated suppliers.
- Coil Line Capital Intensity:Continuous coating line installation and environmental control upgrades require multi-million dollar commitments with extended payback periods.
- Multi-Jurisdictional Compliance Complexity:California Air Resources Board rules, northeastern state ozone requirements, and Health Canada substance evaluations create fragmented registration burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Coil Coatings Market |
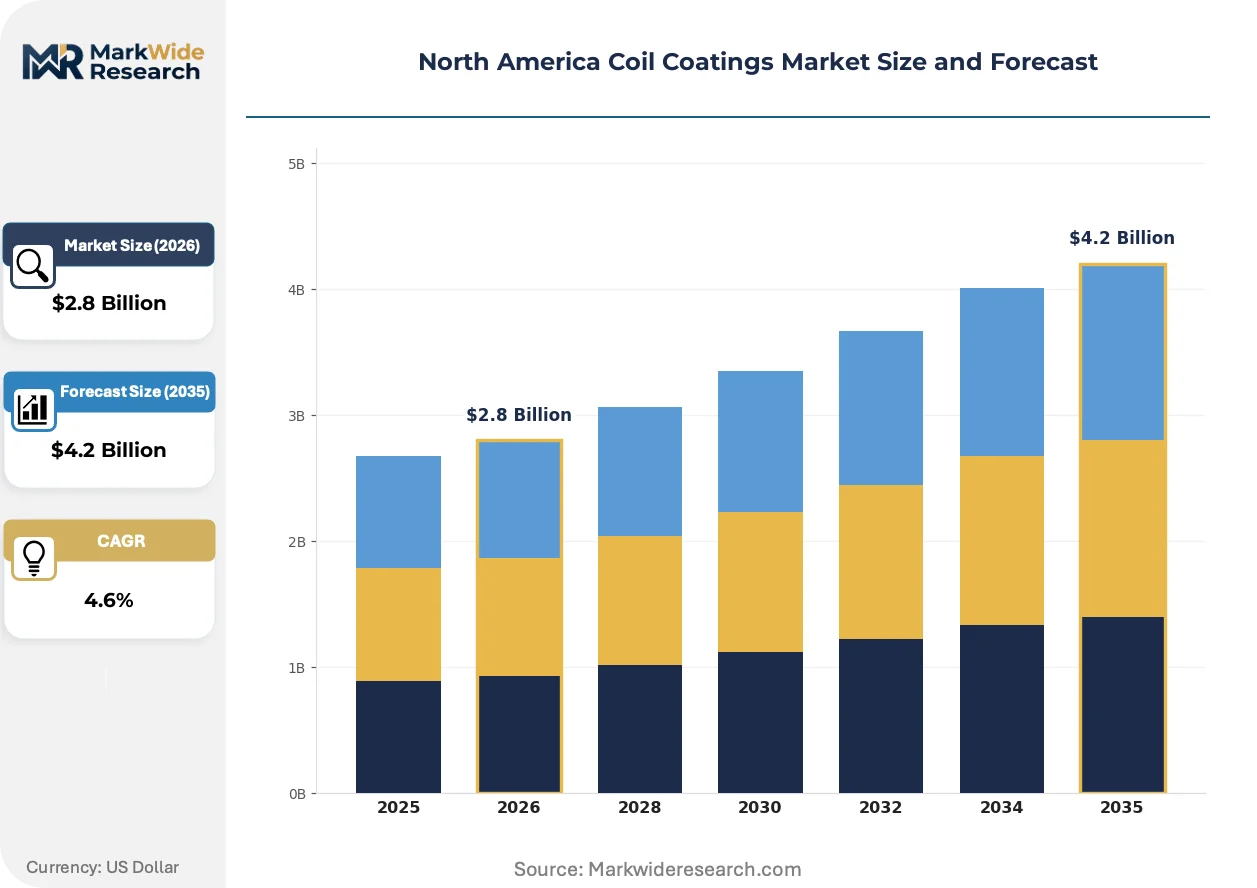
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Polyurethane, Fluoropolymer, Acrylic End User: Construction, Automotive, Appliances, HVAC Application: Interior, Exterior, Roofing, Wall Panels Technology: Roll Coating, Spray Coating, Electro Deposition, Liquid Coating |
| Companies Covered | AkzoNobel N.V., Beckers Group, The Sherwin-Williams Company, PPG Industries, Inc., Axalta Coating Systems Ltd., Valspar Corporation, BASF SE, Henkel AG & Co. KGaA, Wacker Chemie AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Coil Coatings Market Evolving Landscape
Digital color matching and rapid formulation platforms are compressing specification cycles while sustainability metrics reshape procurement criteria across construction and appliance end-uses. Three developments are restructuring competitive advantage.
Waterborne polyurethane dispersion technology is decentralizing coating production geography by enabling ambient-cure performance previously requiring high-temperature baking. Regional toll coaters in the United States and Mexico are adopting these systems to serve construction metal fabricators without capital-intensive oven infrastructure. The shift is fragmenting supply concentration away from integrated steel mill coating lines toward independent processors.
EPA's 2024 amendments to National Volatile Organic Compound Emission Standards for Architectural Coatings are mandating sub-100 g/L VOC limits across most metal coating categories. Formulators are accelerating silicone-polyester hybrid development to maintain exterior durability without fluoropolymer premium pricing. California and northeastern state regulators are signaling alignment with federal baselines, reducing multi-standard compliance burden.
General contractors and metal building distributors are consolidating specification authority through centralized coating selection for multi-site development programs. Large warehouse developers are bypassing regional fabricator preferences to mandate approved coating systems across their North American portfolios. The procurement pattern is most visible in southeastern United States industrial construction, where national logistics operators dominate ground-up development.
North America Coil Coatings Market Segmentation
Coil coating specifications diverge sharply across end-use durability requirements and regulatory exposure. Upgrade cycles in commercial construction and automotive refresh programs create tiered replacement demand that reshapes volume distribution across formulation types.
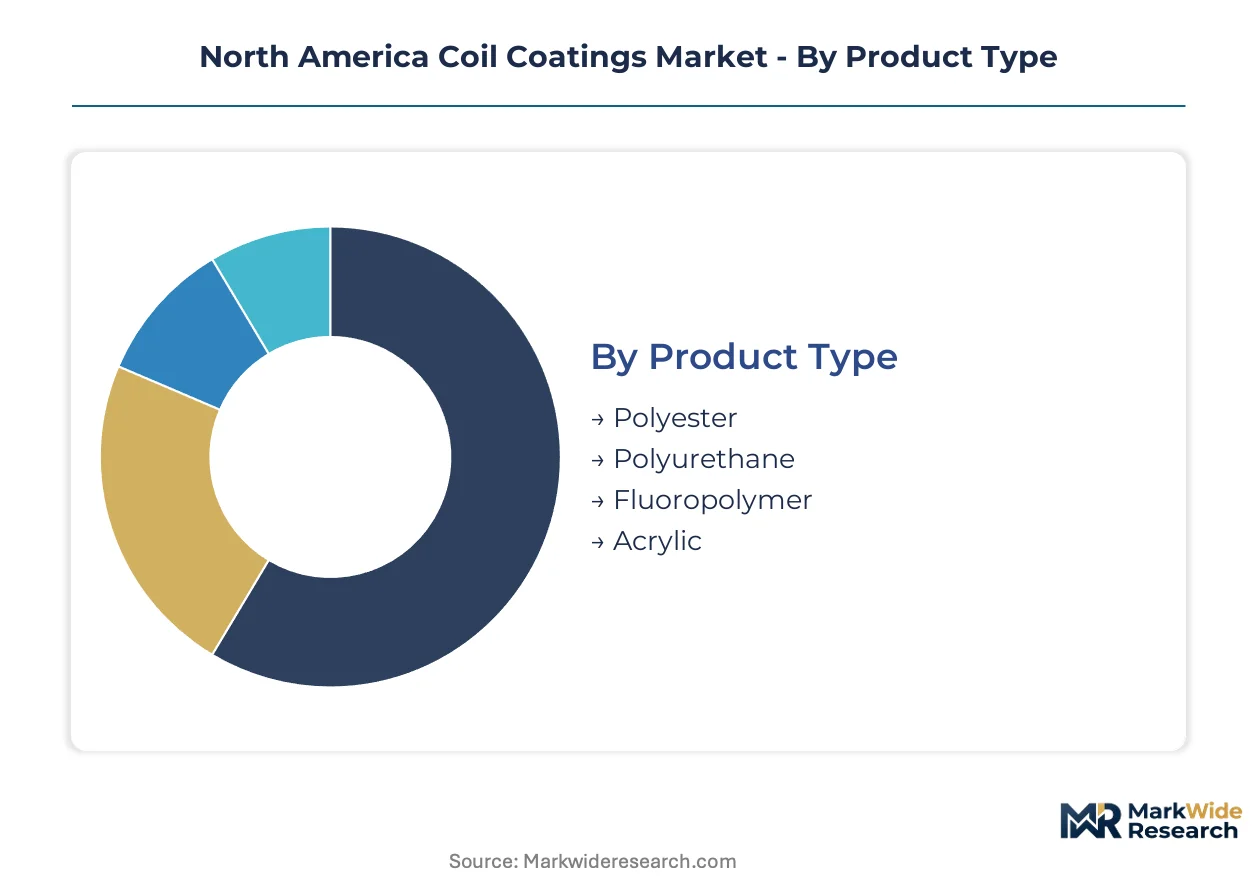
Product Type:
Replacement-cycle intensity varies by substrate protection lifespan, with shorter-duty coatings cycling faster in cost-sensitive construction segments.
- Polyester:Silicone-modified and standard polyester resins dominate metal roofing and wall panel specifications through balanced UV resistance and cost efficiency. Warehouse developers across the southeastern United States specify these systems for 15-20 year service life in low-slope commercial roofing.
- Polyurethane:Aliphatic polyurethane dispersions deliver superior scratch resistance and color retention for high-traffic architectural applications. Automotive trim and premium appliance segments specify these coatings where field performance must exceed substrate replacement cycles.
- Fluoropolymer:PVDF-based systems command specification in monumental architecture and coastal exposure zones where 30-year color retention is mandatory.
- Acrylic:Waterborne acrylics serve interior metal components and light-duty exterior applications with ambient-cure flexibility.
Polyester sits at the top of the volume ranking, with polyurethane climbing the fastest as durability specifications tighten across automotive and appliance refresh programs.
End User:
Customer concentration determines margin structure, with consolidated national accounts extracting volume discounts while fragmented regional fabricators accept premium pricing for technical service.
- Construction:Commercial envelope contractors specify pre-coated metal to compress project schedules and eliminate field painting liability. National logistics developers in Texas, Georgia, and the Carolinas mandate approved coating systems across multi-site warehouse portfolios.
- Automotive:Tier suppliers stamp coil-coated aluminum and steel for body panels, trim, and structural components where factory-applied consistency exceeds field repair quality. Nearshoring to northern Mexico industrial parks is expanding coated substrate demand for regional assembly plants.
- Appliances:Refrigerator, washer, and HVAC cabinet manufacturers specify coil coatings for corrosion resistance in high-humidity operating environments.
- HVAC:Heat exchanger and air handling unit fabricators require thermal-reflective coatings to meet FERC efficiency standards for commercial building envelopes.
Construction commands the volume base, though automotive is expanding most quickly as Mexico production capacity scales.
Application:
Exposure severity dictates formulation grade, with direct weathering applications requiring premium resin systems that interior specifications avoid.
- Exterior:Direct UV and moisture exposure mandates fluoropolymer or high-grade silicone-polyester systems for color retention and chalk resistance. Coastal commercial construction in Florida and California specifies these coatings for salt-air corrosion protection.
- Roofing:Metal roof panels absorb the highest thermal cycling stress, driving specification of reflective pigment packages and flexible resin backbones. Cool roof requirements in California and Arizona accelerate thermal-reflective coating adoption.
- Interior:Controlled environment exposure permits lower-cost acrylic and standard polyester formulations without weatherability additives.
- Wall Panels:Vertical exposure receives less direct UV than roofing, allowing mid-tier polyester specifications in most climate zones.
Exterior applications lead value concentration, with roofing gaining share fastest as energy code compliance tightens across southwestern states.
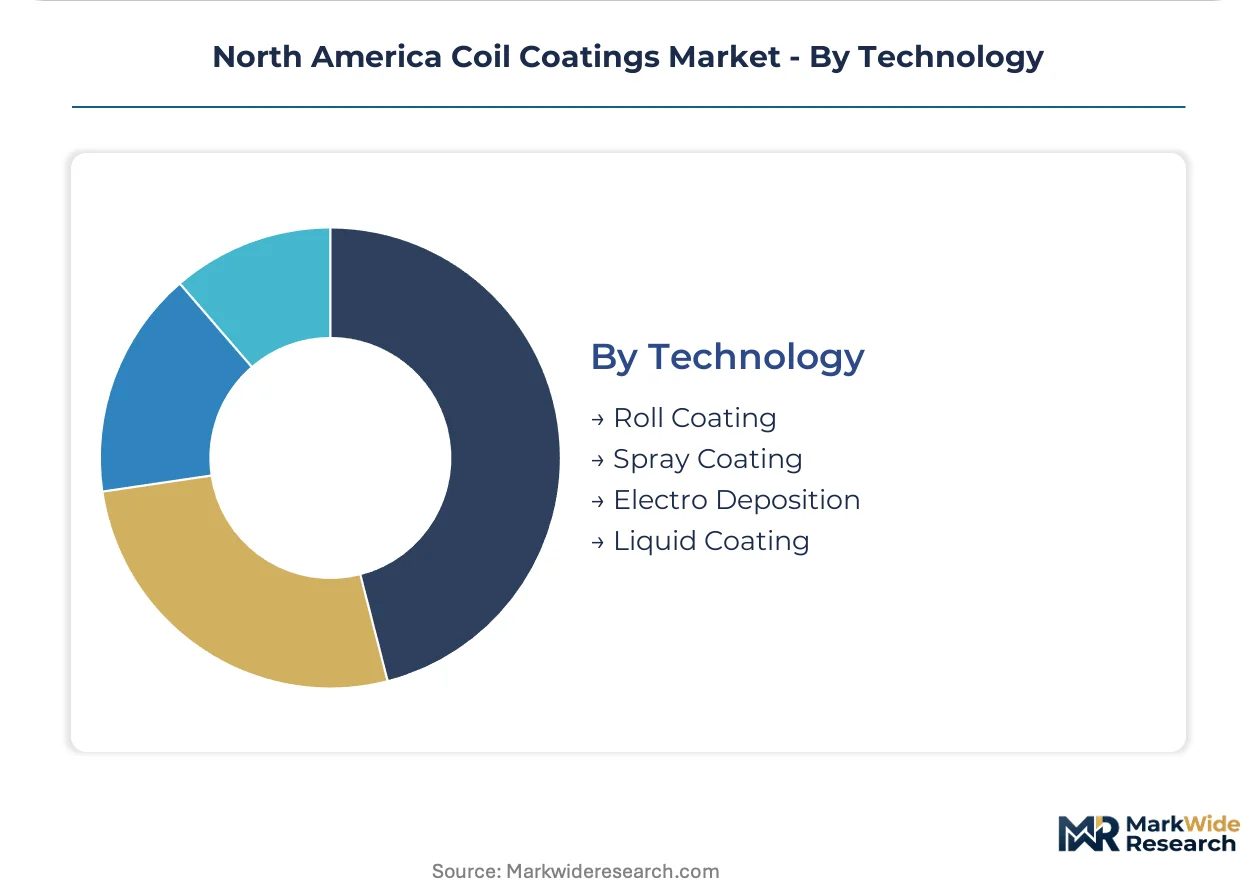
Technology:
Capital intensity and throughput economics separate high-volume continuous lines from flexible batch operations serving custom architectural demand.
- Roll Coating:Direct-roll and reverse-roll systems process flat construction metal at line speeds exceeding 150 meters per minute. Integrated steel mills across the United States and Mexico anchor capacity in this high-throughput segment.
- Liquid Coating:Solvent-borne and waterborne liquid systems maintain share in color-matched custom runs where rapid formulation changeover matters more than line speed.
- Spray Coating:Automated spray booths serve pre-formed architectural profiles and multi-color specifications that roll coating cannot achieve.
- Electro Deposition:E-coat primers provide uniform edge coverage and corrosion protection for automotive body panels prior to topcoat application.
Roll coating dominates volume throughput, while spray coating shows steepest expansion trajectory as architectural customization demand fragments production geography.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized formulation chemists concentrate in the United States industrial corridor, anchoring North American coil coating R&D capacity. Canadian technical service teams support cross-border specification alignment. Mexican process engineers scale coating line operations for nearshored manufacturing demand.
United States
Warehouse developers across Texas, Georgia, and the Carolinas specify pre-coated metal roofing to compress construction schedules. EPA's 2024 amendments to National Volatile Organic Compound Emission Standards for Architectural Coatings mandate sub-100 g/L VOC limits across metal coating categories. The southeastern industrial corridor from Atlanta to Charleston hosts the fastest-growing concentration of new coil coating specification authority as national logistics operators consolidate procurement.
Canada
Commercial building envelope contractors in Ontario and Quebec source coil-coated metal for institutional and retail construction. Health Canada and PMRA maintain parallel chemical substance review processes that affect cross-border product registration for coatings manufacturers. The Greater Toronto Area anchors Canadian demand for thermal-reflective roofing systems as provincial energy codes tighten.
Mexico
Appliance and automotive tier suppliers at northern Mexico industrial parks stamp coil-coated substrates for regional assembly plants. Mexican environmental regulators align with EPA frameworks while maintaining distinct permitting for coating line operations. Nuevo León and the Bajío Region concentrate new coated metal consumption as nearshoring accelerates manufacturing footprint expansion.
North America Coil Coatings Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation development and toll coating services. The North American coil coatings sector exhibits tiered concentration, with integrated resin suppliers commanding premium positioning and regional toll coaters fragmenting mid-market supply. Three archetypes define competitive structure: multinational chemical conglomerates with captive resin supply, independent coating formulators with specialized technical service capabilities, and steel mill-integrated coating operations with high-throughput roll coating infrastructure. Capacity expansion and strategic partnerships represent the dominant competitive moves as players position for waterborne formulation transitions and Mexico manufacturing growth.
Among European-headquartered chemical conglomerates, AkzoNobel N.V., BASF SE, and PPG Industries, Inc. occupy positions that exemplify integrated supply chain approaches to formulation flexibility. These Netherlands-based, Germany-based, and United States-based entities respectively represent archetypes of resin-backward integration, specialty intermediate differentiation, and regional steel mill relationship anchoring. Their positioning illustrates how scale and supply chain control shape competitive advantage under tightening EPA compliance thresholds.
| Leading Market Players |
|---|
| AkzoNobel N.V. |
| Beckers Group |
| The Sherwin-Williams Company |
| PPG Industries, Inc. |
| Axalta Coating Systems Ltd. |
| Valspar Corporation |
| BASF SE |
| Henkel AG & Co. KGaA |
| Wacker Chemie AG |
| Others |
Value Network & Pricing Analysis
Titanium dioxide benchmark pricing cascades through North American coil coating supply chains into three distinct formulation tiers, with pigment cost volatility compressing margins at the standard-grade end while fluoropolymer feedstock scarcity sustains premium pricing power for high-durability specifications.
Pricing Analysis
Bundled technical service and unbundled commodity supply splits the market into divergent pricing models. Three-tier pricing structure across premium fluoropolymer, standard silicone-polyester, and economy waterborne acrylic levels reflects certification grade and volume scale differentiation. Cost compression in economy tiers is intensifying because of concentrated Chinese TiO2 supply and resin import dependency, with regional toll coaters exhibiting highest price sensitivity while national logistics developers lock in long-term offtake contracts at fixed formulation specifications.
Supply Chain Analysis
Rail and trucking freight costs from Gulf Coast petrochemical corridors to southeastern construction markets add geographic pricing premiums that independent formulators absorb through compressed service margins. Resin production concentrates in the United States, Germany, and Japan, with coating formulation drawing from TiO2 pigment, PVDF resin, and aliphatic isocyanate feedstocks. Tariff exposure on Chinese pigment imports creates supply chain risk. Distribution runs through steel mill-integrated coating lines and regional toll coaters serving custom architectural demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America coil coatings market functions as a stable compounder, with EPA regulatory ratcheting providing predictable demand migration toward compliant waterborne systems that sustains replacement-cycle revenue visibility.
For Market Incumbents: Lock in resin-backward integration or captive supply agreements to defend margin position against TiO2 price volatility and emerging waterborne specialists. Prioritize certification investment for California Air Resources Board pre-approval to capture specification authority before federal alignment tightens compliance baselines nationwide. For New Entrants and Emerging Players: Begin with UV-curable formulation development targeting regional toll coaters lacking capital-intensive oven infrastructure, where ambient-cure technology creates service differentiation without competing against integrated steel mill throughput economics. Mexico northern industrial parks offer the most penetrable geography as nearshoring accelerates coated substrate demand for appliance and automotive assembly. For Investors and Strategic Acquirers: Consolidation pressure builds where formulation chemist talent scarcity concentrates at larger integrated suppliers, leaving mid-market independents exposed to talent flight and R&D obsolescence. Five-to-ten-year viability favors acquirers of regional toll coaters with established steel mill relationships and waterborne formulation libraries. Watch EPA enforcement intensity on architectural coating VOC limits as the signal for accelerated market share capture by compliant formulators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive polyurethane dispersion production insulates margin from imported feedstock tariff exposure. |
| Waterborne Formulation Scale-Up | EPA sub-100 g/L compliance mandates accelerate specification capture from solvent-borne incumbents. |
| Mexico Coating Line Expansion | Nearshored appliance and automotive assembly plants create regional substrate demand pull. |
| UV-Curable Technology Licensing | LED curing convergence enables toll coaters to bypass capital-intensive thermal oven infrastructure. |
| Cross-Border Registration Streamlining | PMRA-EPA data sharing protocols compress time-to-market for dual-jurisdiction formulations. |
Research Methodology
Multiple input streams — formulation chemist interviews, steel mill procurement lead discussions, and toll coater operational assessments — were reconciled against secondary validation from EPA regulatory filings, ACC industry statistics, and customs trade data. Bottom-up volume modeling across coating line throughput capacities was triangulated with top-down construction spending and automotive production forecasts. Primary fieldwork captured specification authority concentration among national logistics developers and regional fabricator procurement patterns.
Data-stream reconciliation anchored the analytical framework across the projection horizon, with segmentation modeling across resin chemistry tier, end-use industry exposure, application severity, and regional regulatory cluster. CAGRs were derived from replacement-cycle intensity differentials and compliance-driven specification shift velocities. Forecast inputs incorporated FERC building envelope efficiency mandate adoption curves and Mexico manufacturing capacity expansion timelines.
Caveats apply where EPA enforcement intensity, TiO2 supply disruption, or Mexico regulatory alignment shifts could materially shift the outlook. Forecasts reflect assumptions about waterborne formulation performance parity and cure energy cost trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Epoxy Surface Coatings Market
Coatings
Soft Touch Polyurethane Coatings Market
Coatings
Europe Anti-Friction Coatings Market
Coatings
Consumer Appliance Coatings Market
Coatings
Middle East and Africa Super Hydrophobic Coatings Market
Coatings
Flexible Waterproof Coating Market
Coatings
Technical Coil Coatings Market
Coatings
Acrylic Protective Coating Market
Coatings
Self-Healing Microcapsule Systems for Protective Coatings Market
Coatings
Fire Retardant Coatings Market
Coatings
Epoxy Powder Coatings Market
Coatings
Industrial Liquid Coating Market
Coatings
Waterborne Wood Coatings Market
Coatings
Epoxy Coating Market
Coatings
North America Powder Coatings Market
Coatings
Global Powder Coating Market