
 North America Powder Coatings Market | 2026-2036
North America Powder Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
North America Powder Coatings Market Insights
Epoxy-polyester hybrid chemistry is shifting the cost-performance frontier for appliance and furniture finishers across the region. PPG Industries sustains R&D intensity in low-temperature cure systems for heat-sensitive substrates. Sherwin-Williams controls distribution density through its dedicated powder coatings branch network. Axalta Coating Systems differentiates via color-matching technology leadership in automotive refinish and OEM segments.
Powder coatings are dry-finishing materials composed of thermoset or thermoplastic resins, pigments, flow agents, and curing additives that melt and crosslink when exposed to elevated temperatures, typically forming films 25-125 microns thick with zero volatile organic compound release. The formulation dimension splits between epoxy, polyester, and acrylic chemistries, with polyester dominating exterior architectural and automotive applications due to superior UV durability and gloss retention. Thermoset types anchor the volume base across industrial end users, while hybrid formulations capture margin pools in appliance and electronics segments requiring balanced chemical resistance and decorative performance.
EPA VOC emission standards under 40 CFR Part 60 and OSHA workplace exposure limits shape product formulation requirements and application equipment investments across US manufacturing facilities. State-level regulations in California through CARB and in Ontario through Environment and Climate Change Canada extend compliance obligations for coating operations. Stakeholders must monitor evolving low-cure technology readiness against existing oven infrastructure replacement cycles.
Market Dynamics
EPA VOC regulations under 40 CFR Part 60 are accelerating liquid-to-powder conversion across US manufacturing facilities, forcing capital reallocation toward compliant application systems and low-cure temperature technologies.
Growth Catalysts
- Automotive OEM Expansion:Michigan and Ohio chassis and wheel manufacturers are converting liquid coating lines to powder systems to meet EPA emission thresholds while reducing energy consumption.
- Low-Cure Technology Maturation:Heat-sensitive substrate compatibility is opening appliance and electronics segments previously blocked by thermal damage risks during curing cycles.
- Great Lakes Industrial Corridor Concentration:Dense clustering of agricultural equipment and appliance manufacturers in Illinois, Indiana, and Wisconsin generates localized demand pull for regional powder coating service providers.
Market Restraints
- Titanium Dioxide Feedstock Volatility:Pigment cost fluctuations compress formulation margins and complicate long-term contract pricing for coating suppliers serving price-sensitive industrial end users.
- Oven Infrastructure Replacement Cycles:Existing thermal curing equipment with 15-20 year depreciation schedules delays adoption of ultra-low temperature cure chemistries requiring capital-intensive retrofits.
- Liquid Coating Substitution Defense:High-performance liquid polyurethane and fluoropolymer systems retain defensive positions in extreme chemical exposure and thin-film architectural applications.
Strategic Opportunities
- Mexico Manufacturing Integration:Appliance and automotive component production expansion in Querétaro and Nuevo León creates demand for cross-border powder coating supply chains and technical service networks.
- UV-Curable Powder Convergence:Combination of photoinitiator chemistry with traditional thermoset powder bases enables heat-sensitive wood and plastic substrate penetration without thermal oven investment.
- California CARB Zero-VOC Mandates:Stricter state-level emission standards ahead of federal minimums position compliant powder systems for premium pricing in environmental performance markets.
Industry Challenges
- Application Technician Certification Bottlenecks:NACE and SSPC coating inspector credential scarcity constrains quality assurance scaling for job shop coating operations across the US Midwest.
- Color-Matching Algorithm Integration:Spectrophotometer-to-formulation software compatibility gaps between equipment vendors create workflow friction for custom color specification fulfillment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Powder Coatings Market |
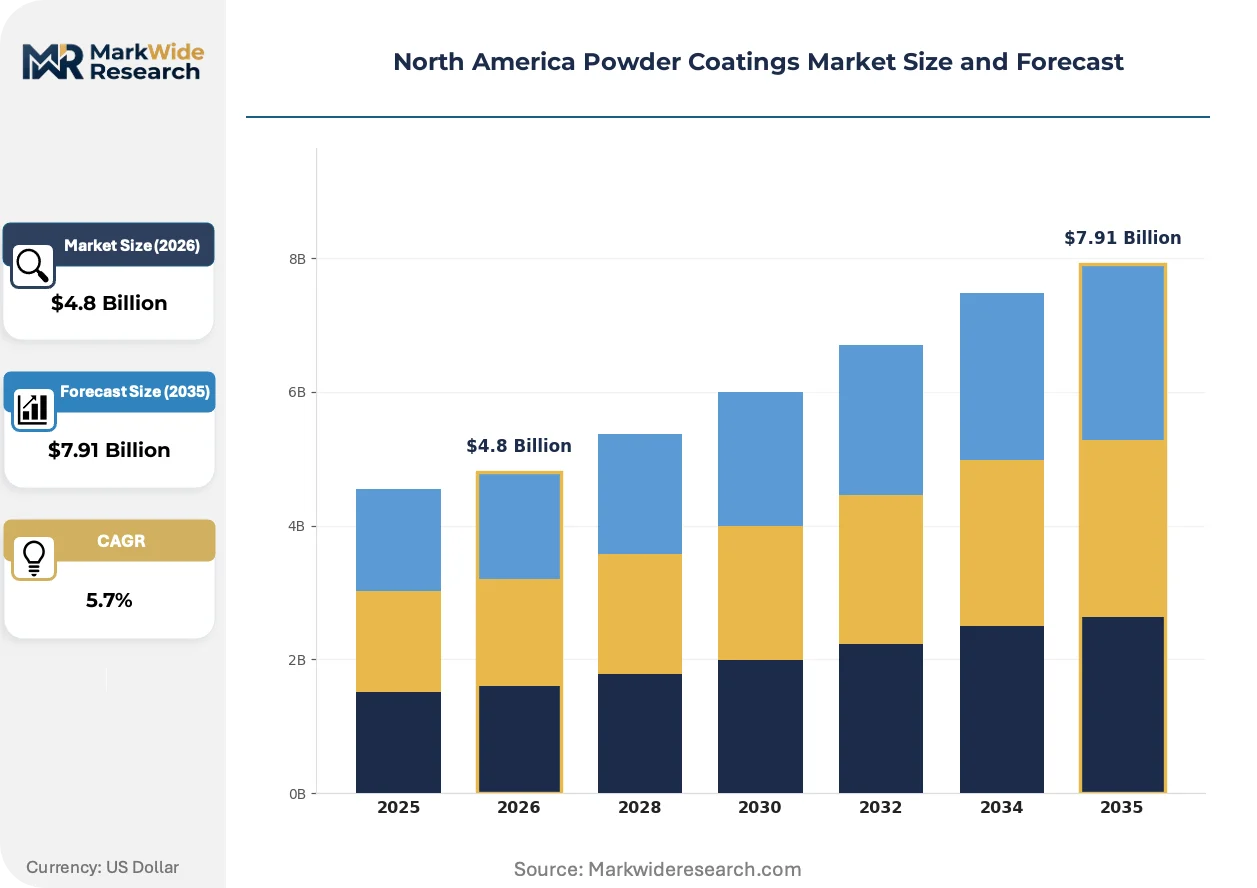
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Automotive, Furniture, Appliances, Electronics Type: Thermoset, Thermoplastic, Hybrid, Architectural End User: Industrial, Residential, Commercial, OEMs Formulation: Epoxy, Polyester, Acrylic, Others |
| Companies Covered | Akzo Nobel N.V., PPG Industries, Inc., The Sherwin-Williams Company, RPM International Inc., Axalta Coating Systems LLC, Jotun, BASF SE, Protech Group, Kansai Paint Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Powder Coatings Market Trends and Innovations
Active reformulation toward hybrid chemistries and digital color management is compressing specification cycles while expanding substrate compatibility across heat-sensitive manufacturing segments.
Low-temperature cure polyester technology is decentralizing production geography by eliminating the thermal bottleneck that previously concentrated powder coating operations near heavy industrial infrastructure. Furniture manufacturers and assembled wood product fabricators in non-traditional coating regions are adopting these systems without the gas-fired oven investments that historically required utility-scale energy access. Regional job shops in secondary markets are capturing finish work previously routed to centralized coating facilities.
EPA enforcement of 40 CFR Part 60 Subpart MMV for surface coating operations is tightening permissible organic HAP emission limits and triggering control technology upgrades across metal fabrication facilities. Compliance deadlines are compressing capital expenditure timelines for small and medium coating operations. Agricultural equipment manufacturers in Iowa and Nebraska are prioritizing powder conversion over add-on control devices to avoid continuous monitoring requirements.
Specification authority is migrating from general contractors to coating applicators as building product manufacturers seek single-source accountability for warranty performance. Architectural metal panel and window system suppliers are consolidating vendor lists to qualified powder coaters with in-house pretreatment and testing capabilities. This consolidation is most visible in commercial construction corridors across Texas and Florida where accelerated project schedules demand compressed sample approval cycles.
North America Powder Coatings Market Segmentation
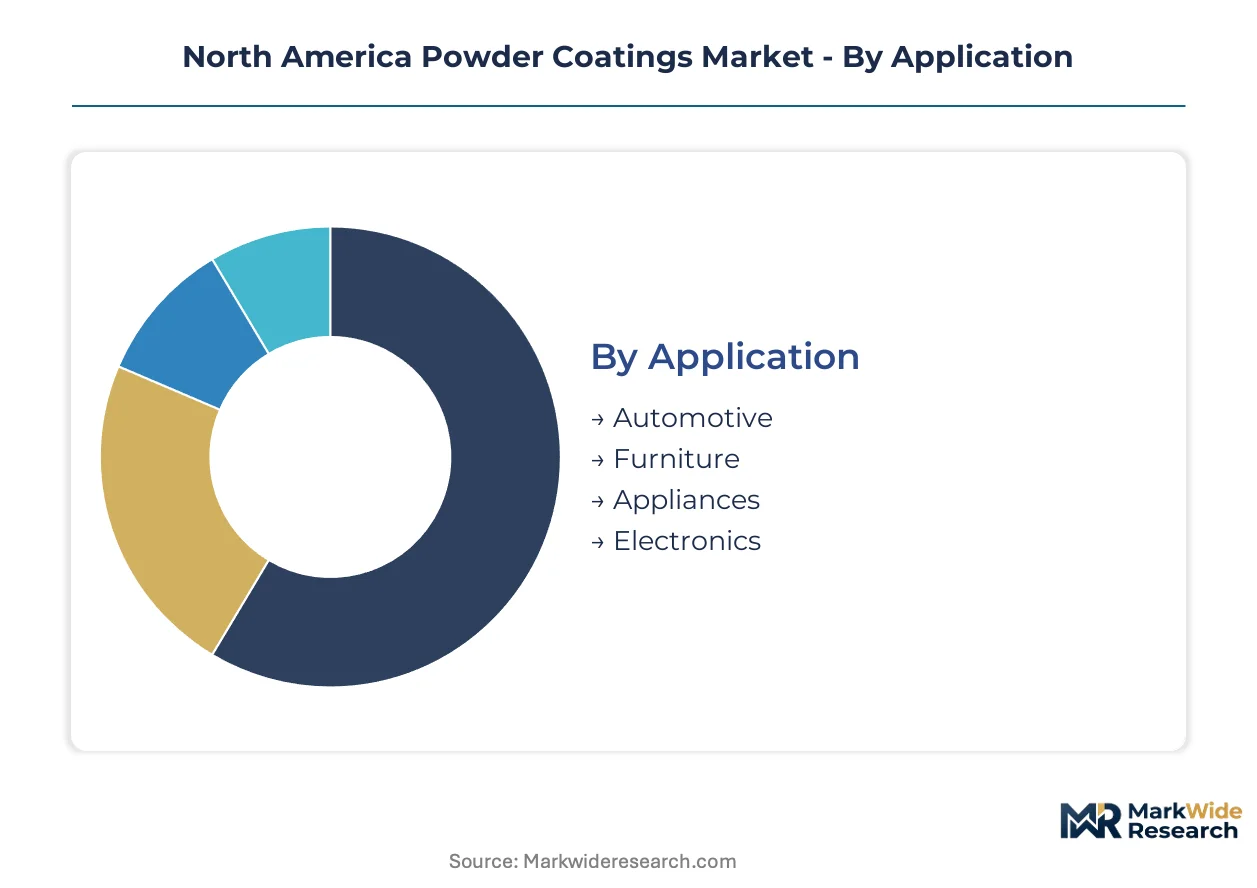
Powder coating specifications diverge sharply across end-use requirements, with thermal tolerance, chemical exposure, and aesthetic demands driving chemistry selection. Segmentation clarity enables suppliers to align formulation investments with replacement-cycle timing and regulatory compliance windows.
Application:
Equipment upgrade cycles and EPA compliance deadlines are redirecting specification authority toward applicators with integrated pretreatment capabilities.
- Automotive:Chassis, wheel, and underhood components specify polyester and hybrid chemistries for chip resistance and salt-spray durability. Michigan and Ohio OEMs are converting liquid lines to powder systems ahead of 40 CFR Part 60 enforcement, concentrating demand in the Great Lakes corridor.
- Appliances:Refrigerator racks, washer drums, and dryer cabinets require low-temperature cure hybrids to protect polymer gaskets and electronic controls during finishing. Heat-sensitive substrate compatibility is opening segments previously blocked by thermal damage risks.
- Furniture:Metal office and outdoor furniture segments favor polyester powders for UV stability and gloss retention in exterior exposures.
- Electronics:Server racks, enclosures, and heat sinks specify thin-film epoxy and acrylic formulations with electrostatic spray compatibility for complex geometries.
Volume placements concentrate in Automotive; the faster expansion belongs to Appliances.
Type:
Cost tier differentiation separates commodity thermoset volumes from premium hybrid and architectural grades commanding formulation premiums.
- Thermoset:Epoxy and polyester thermosets dominate industrial maintenance and general metal finishing with crosslinked films that resist solvents and mechanical abrasion. The US Great Lakes manufacturing corridor consumes bulk volumes for agricultural equipment and fabricated metal components.
- Hybrid:Epoxy-polyester hybrids balance chemical resistance with decorative performance for appliance interiors and furniture frames. Low-cure temperature variants are capturing margin pools in heat-sensitive manufacturing segments.
- Thermoplastic:PVC and nylon-based powders serve niche applications requiring remelt capability and impact resistance in fluid handling equipment.
- Architectural:Superdurable polyester and fluoropolymer-modified powders meet AAMA 2605 specifications for curtainwall and storefront systems in Texas and Florida commercial construction corridors.
Volume placements concentrate in Thermoset; the steepest expansion trajectory belongs to Hybrid.
End User:
Customer type determines specification complexity, with OEMs demanding lot-to-lot consistency and job shops prioritizing color-matching flexibility.
- Industrial:Metal fabricators, agricultural equipment manufacturers, and material handling producers specify standard polyester and epoxy powders in high-volume, long-run production. Iowa and Nebraska agricultural OEMs are prioritizing powder conversion over add-on control devices to avoid continuous monitoring requirements.
- OEMs:Automotive, appliance, and electronics original equipment manufacturers enforce stringent pretreatment and film thickness protocols with direct supplier quality agreements.
- Commercial:Architectural metal panel and window system suppliers consolidate vendor lists to qualified coaters with in-house testing capabilities.
- Residential:Custom metalwork, outdoor furniture, and home fixture segments drive specification diversity with shorter run lengths and broader color palettes.
Volume placements concentrate in Industrial; the fastest share gain belongs to OEMs.
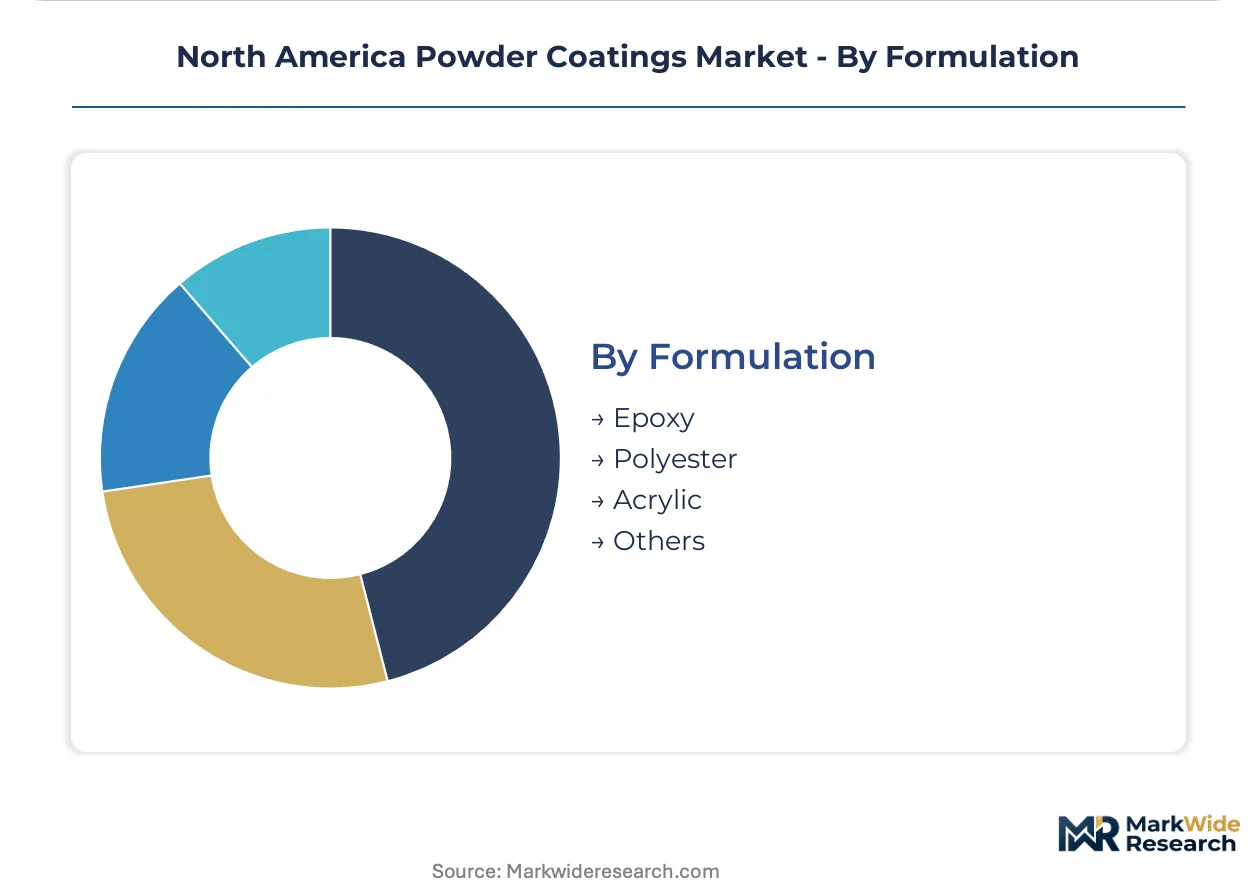
Formulation:
Supply concentration in titanium dioxide and resin feedstocks creates margin volatility that formulation strategists hedge through hybrid chemistry expansion.
- Polyester:Saturated and unsaturated polyester resins anchor exterior architectural and automotive applications with superior UV durability and gloss retention. Texas and Florida commercial construction demand pulls superdurable grades with 20-year color retention warranties.
- Epoxy:Bisphenol-A and novolac epoxy systems deliver chemical resistance for functional industrial applications including rebar, pipe, and tank linings.
- Acrylic:Thermoset acrylic powders provide exceptional clarity and exterior durability for automotive clearcoat and specialty decorative finishes.
- Others:Fluoropolymer, polyurethane, and silicone-modified powders serve extreme chemical exposure and high-temperature applications.
Volume placements concentrate in Polyester; the expansion climbing fastest belongs to Hybrid chemistries blending epoxy-polyester characteristics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foreign Trade Zones across the US-Mexico border and Great Lakes industrial corridor concentrate powder coating capacity through duty-deferral incentives and proximity to automotive assembly plants.
United States
EPA enforcement of 40 CFR Part 60 Subpart MMV tightens organic HAP limits for surface coating operations. Michigan and Ohio chassis manufacturers convert liquid lines to powder systems ahead of compliance deadlines. Iowa and Nebraska agricultural equipment OEMs prioritize powder conversion over add-on controls to bypass continuous monitoring mandates.
Canada
Environment and Climate Change Canada extends VOC compliance obligations for coating operations in Ontario and Quebec manufacturing zones. The Great Lakes industrial corridor generates localized demand from appliance and agricultural equipment clusters. Toronto-area job shops capture finish work from US cross-border supply chains.
Mexico
Appliance and automotive component expansion in Querétaro and Nuevo León creates demand for cross-border powder coating supply chains. Mexican environmental regulators align industrial emission standards with US EPA frameworks under USMCA technical cooperation protocols. Monterrey-based coating operations serve maquiladora assembly plants with just-in-time finishing services.
North America Powder Coatings Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation suppliers commanding premium positions in OEM direct agreements while regional job shops compete on color-matching flexibility and turnaround speed. The vendor base concentrates around three strategic archetypes: integrated resin-to-coating multinationals, dedicated powder specialists with distribution density advantages, and regional applicators with pretreatment-integrated service models. M&A activity targets niche formulation capabilities in low-temperature cure technologies, while capacity expansion concentrates near automotive assembly corridors in the US Midwest and Mexican industrial states.
Among Netherlands-based multinationals, Akzo Nobel N.V. exemplifies the integrated resin-to-coating archetype with global formulation reach. PPG Industries, Inc. and The Sherwin-Williams Company represent US-based specialists with distribution density and dedicated powder branch networks respectively. These three occupy positions across the premium formulation tier, with Axalta Coating Systems LLC anchoring the automotive refinish and OEM color-matching segment.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| PPG Industries, Inc. |
| The Sherwin-Williams Company |
| RPM International Inc. |
| Axalta Coating Systems LLC |
| Jotun |
| BASF SE |
| Protech Group |
| Kansai Paint Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
EPA 40 CFR Part 60 compliance deadlines are compressing procurement timelines for coating operations across Michigan and Ohio, forcing applicators to absorb premium formulation costs or risk losing automotive OEM contracts to qualified competitors with compliant systems already installed.
Pricing Analysis
Short lead time premiums dominate contract negotiations as automotive OEMs in the Great Lakes corridor penalize suppliers unable to meet compressed sample approval cycles. Three-tier pricing structure across superdurable architectural grades, standard industrial polyesters, and economy thermoset epoxies reflects certification tier and volume scale differentiation. Cost compression in economy thermoset grades is intensifying because titanium dioxide feedstock volatility squeezes formulation margins. Job shop coating operations exhibit highest price sensitivity due to thin working capital buffers, while OEM direct agreements show lowest sensitivity given warranty performance requirements.
Supply Chain Analysis
Dual-sourcing mandates from Tier 1 automotive suppliers are forcing powder coating formulators to qualify secondary resin suppliers in Germany and South Korea alongside domestic feedstock channels. Raw material dependencies center on epoxy and polyester resins from petrochemical complexes, titanium dioxide pigment from chloride-process plants, and curing agent additives. Single-source vulnerability concentrates in specialized low-temperature cure chemistries where patent-protected formulations limit supplier alternatives. Distribution runs through dedicated powder branch networks controlled by major suppliers, with regional job shops capturing spot demand in secondary markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from EPA enforcement timelines is eliminating sub-scale coating operations unable to fund compliant application system upgrades, creating acquisition opportunities for well-capitalized formulators with integrated pretreatment capabilities.
For Market Incumbents: Extend low-temperature cure technology leadership through captive R&D partnerships with oven equipment manufacturers, locking in specification authority as heat-sensitive substrate adoption accelerates. Backward integration into specialty resin production hedges against petrochemical feedstock volatility threatening margin stability in standard polyester grades.
For New Entrants and Emerging Players: Regional job shop networks represent the most penetrable channel archetype for UV-curable powder systems targeting furniture manufacturers in non-traditional coating geographies without gas-fired oven infrastructure. White-space capture should prioritize appliance component finishing in Querétaro and Nuevo León, leveraging cross-border technical service partnerships with established US formulators.
For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with proprietary low-cure formulations and in-house pretreatment capabilities, positioned for premium valuation as OEM vendor consolidation accelerates. Watch for inflection signals in California CARB rulemaking that would extend zero-VOC mandates ahead of federal minimums, reshaping competitive positioning for compliant powder systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Low-Temperature Cure Technology Licensing | PPG Industries' R&D partnerships with oven manufacturers accelerate heat-sensitive substrate penetration beyond traditional industrial corridors. |
| Cross-Border Supply Chain Integration | Sherwin-Williams' dedicated powder branch networks in Querétaro capture appliance and automotive component demand from maquiladora assembly plants. |
| Dual-Sourcing Resin Qualification | Akzo Nobel's secondary supplier validation in Germany and South Korea reduces single-source vulnerability in epoxy and polyester feedstocks. |
| UV-Curable Powder Platform Development | Axalta's photoinitiator chemistry convergence enables wood and plastic substrate penetration without thermal oven capital investment. |
| Pretreatment-Integrated Service Acquisition | Regional job shops with in-house testing capabilities command premium positioning as architectural metal panel suppliers consolidate vendor lists. |
Research Methodology
Document review covered EPA 40 CFR Part 60 enforcement guidance, ACC industry shipment reports, and SEC 10-K filings from coating suppliers, complemented by interviews with plant managers at automotive OEM coating operations, procurement leads at appliance manufacturers, distribution channel partners in the Great Lakes corridor, and technical R&D directors at formulation suppliers. Secondary validation drew from customs and trade data, Environment and Climate Change Canada regulatory filings, and USMCA technical cooperation protocols. Bottom-up demand modeling triangulated against top-down industry association aggregates.
Historical volume trajectories cross-referenced against expert panel input from coating applicators and OEM specification engineers shaped the analytical framework across the analysis window. Segmentation dimensions modeled include chemistry type, cure temperature tier, end-use industry, and regional production cluster proximity to automotive assembly corridors. CAGRs derived from replacement-cycle timing, regulatory compliance deadlines, and technology diffusion curves in low-temperature cure adoption.
Caveats apply where titanium dioxide feedstock volatility, EPA enforcement intensity variations, or oven infrastructure replacement cycle delays could materially shift the outlook. Deviation in California CARB rulemaking acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global UV-Cured Coatings Market
Coatings
Food Grade Ceramic Coatings Market
Coatings
Cool Roof Coatings Market
Coatings
Global Waterborne Coatings Market
Coatings
CVD Coating Technology Market
Coatings
Asia-Pacific Floor Coatings Market
Coatings
Corrosion Protective Coatings and Acid Proof Lining Market
Coatings
Consumer Appliance Coatings Market
Coatings
Polyester Coatings Market
Coatings
Global Sputter Coatings Market
Coatings
Corrosion Protection Coating Market
Coatings
Middle-East and Africa Thermal Spray Market
Coatings
Asia-Pacific Thermal Spray Market
Coatings
South Africa Automotive OEM Coatings Market
Coatings
Industrial Coatings Market
Coatings
Hull Coatings Market