
 Asia-Pacific Packaging Design Services Market | 2026-2036
Asia-Pacific Packaging Design Services Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Packaging Design Services Market Analytics
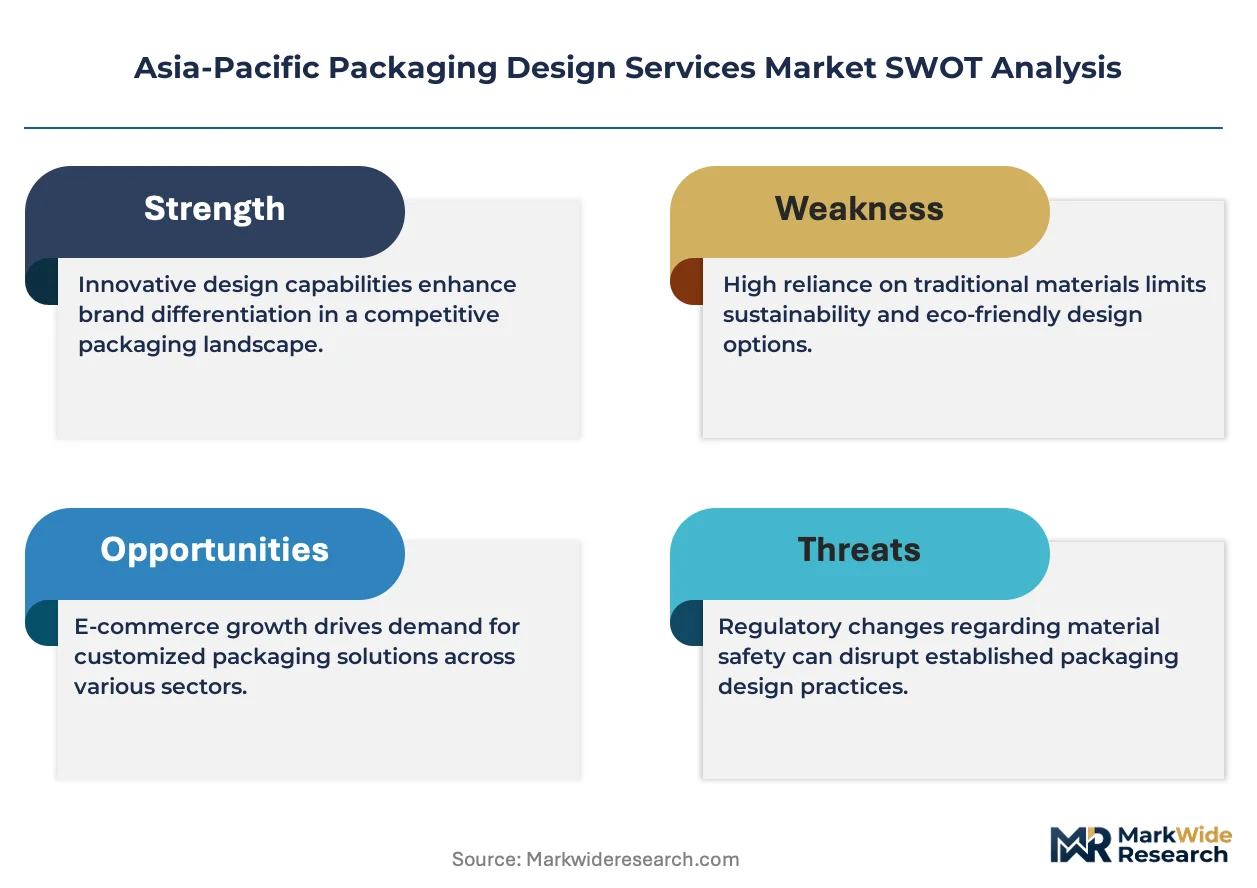
India's western manufacturing corridor is rewriting how packaging design services scale across the Asia-Pacific region. Arhue leverages deep prototyping capabilities to anchor premium beverage assignments for clients across Maharashtra and Gujarat. Pulp+Wire competes through material-specialized graphic design that dominates sustainable paper-based assignments in the Australian market.
Packaging design services encompass the creative and technical development of protective, communicative, and regulatory-compliant enclosures for consumer and industrial goods, spanning structural engineering, visual identity systems, and substrate selection for shelf impact and logistics durability. The service type dimension reveals consulting and prototyping as the margin-rich tiers where clients pay premiums for speed-to-market validation, while graphic design remains the volume layer commoditized by template-based tools. Material type segmentation shows paper commanding the fastest expansion as India's FSSAI labeling mandates and Australia's APCO sustainability targets push brands away from virgin plastic toward fiber-based alternatives.
India's BIS packaging standards, Australia's APCO 2025 targets, and China's GB/T national standards for food contact materials collectively raise compliance costs for design studios serving multinational clients across multiple jurisdictions. Japan's METI circular economy guidelines now require design-for-recyclability documentation before retail placement, forcing studios to embed lifecycle analysis into early creative phases. Stakeholders must monitor which regulatory frameworks their clients' export destinations activate, as divergence between Indian, Australian, and Chinese compliance paths threatens to fragment design retainer structures.
Market Dynamics
India's FSSAI labeling mandates and Australia's APCO 2025 targets are forcing design studios to restructure creative workflows around compliance-first documentation, compressing traditional concept-to-prototype cycles by embedding regulatory validation at ideation stages.
Growth Catalysts
- E-commerce fulfillment specialization:Southeast Asian online retailers commission protective structural designs to cut damage-related returns. Custom unboxing experiences now anchor brand loyalty programs for digital-native consumers.
- Japan's METI circular economy guidelines:Mandatory design-for-recyclability documentation before retail placement drives lifecycle analysis integration into early creative phases. Studios charge premiums for compliance-ready concept packages.
- Paper substrate acceleration:India's western manufacturing corridor concentrates FMCG headquarters demanding fiber-based alternatives to virgin plastic. Mumbai and Pune studios capture volume through rapid paper prototyping capabilities.
Market Restraints
- Recycled pulp input volatility:Australian and Indian recovered fiber prices fluctuate with import dependency on Southeast Asian collection networks. Design studios absorb margin compression when specifying post-consumer content.
- Specialized talent scarcity:Structural engineers with food-contact material expertise cluster in Tokyo and Sydney, leaving secondary cities dependent on remote collaboration with premium billing rates.
- Regulatory fragmentation:Divergent compliance paths between India's BIS standards, China's GB/T food contact rules, and Australia's APCO targets fragment retainer structures for multinational clients.
Strategic Opportunities
- Vietnamese manufacturing integration:Packaging design studios establishing satellite operations near Ho Chi Minh City electronics exporters capture just-in-time structural validation work previously routed through Chinese intermediaries.
- Pharmaceutical serialization convergence:Track-and-trace mandates across India, South Korea, and Japan create demand for design studios integrating authentication features at substrate selection stage.
- Digital twin adoption:Virtual prototyping platforms compress physical sampling cycles for Australian wine and Japanese cosmetics brands requiring rapid shelf-impact testing.
Industry Challenges
- Cross-jurisdictional certification timelines:Studios serving multinational FMCG clients face staggered approval windows across India's BIS, China's NMPA, and Australia's TGA packaging contact rules.
- Legacy CAD system integration:Mid-tier design houses in Thailand and Indonesia struggle to interface client ERP procurement platforms with proprietary structural engineering software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Packaging Design Services Market |
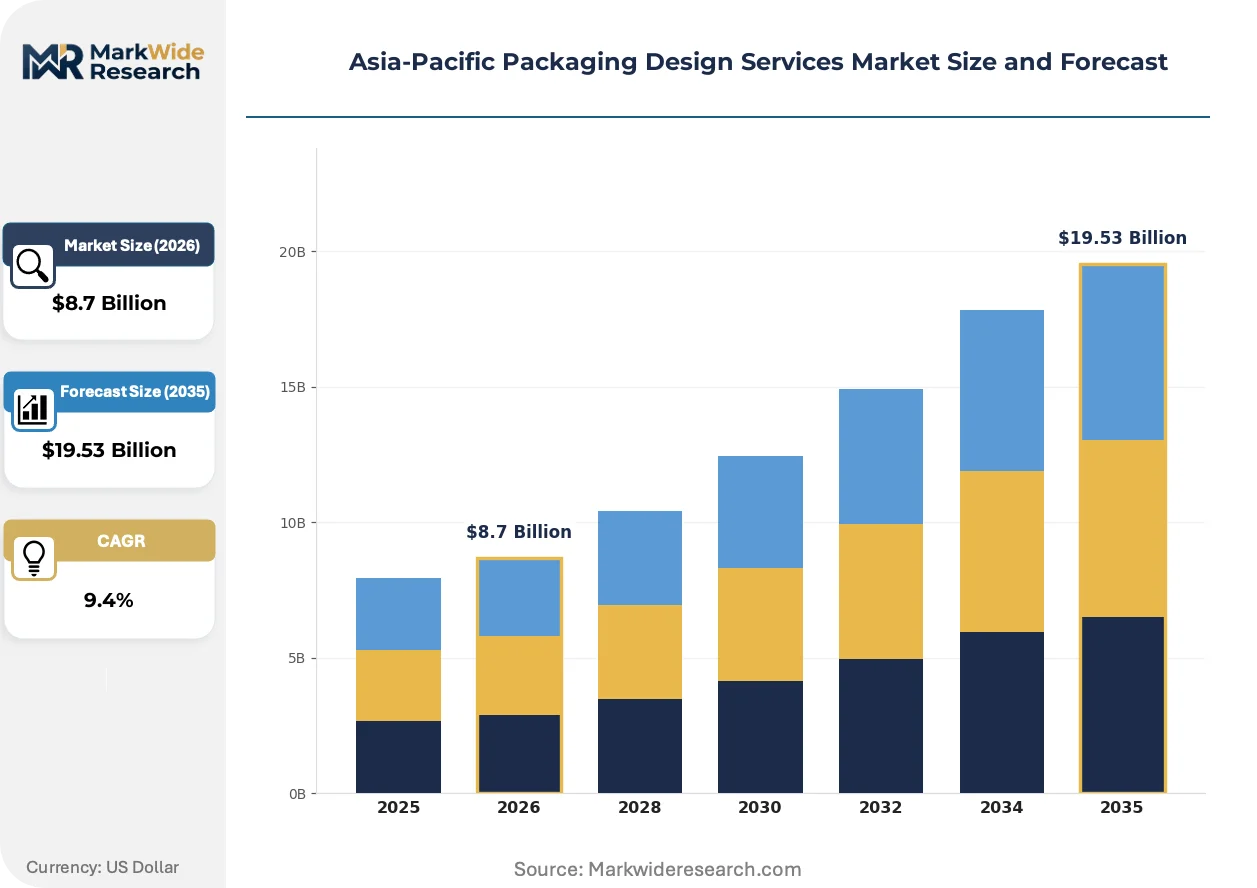
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
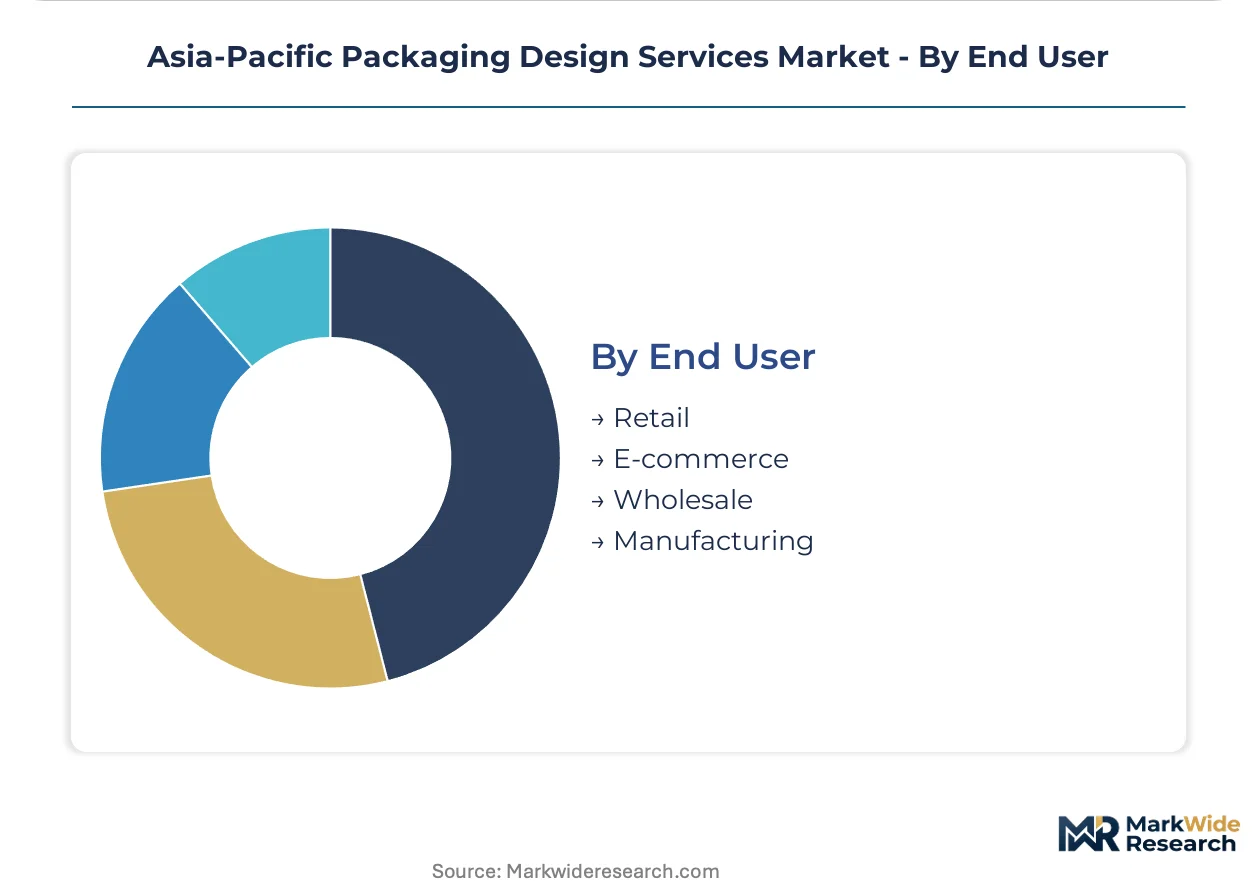
| Segmentation | Product Type: Food, Beverage, Personal Care, Pharmaceuticals Service Type: Consulting, Prototyping, Graphic Design, Market Research Material Type: Plastic, Glass, Paper, Metal End User: Retail, E-commerce, Wholesale, Manufacturing |
| Companies Covered | La Visual Inc., Murmur creative, Arhue, Ruckus Marketing, Pulp+Wire, DEI Creative, Legnd, Tank design, Forever Sincretix, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Packaging Design Services Market Evolving Landscape
Digital simulation tools and regulatory automation are compressing traditional design-service delivery models, while sustainability documentation requirements reshape how studios structure client retainers and talent deployment across the Asia-Pacific region.
Parametric structural modeling software is virtualizing the physical prototyping phase for beverage and personal care assignments. Japanese cosmetics brands and Australian premium food exporters now validate shelf presence through photorealistic renderings before committing to die production. This shift collapses concept-to-sample timelines from weeks to days, enabling studios to bid fixed-fee projects with compressed delivery schedules.
Japan's amended Packaging Recycling Act mandates higher recycled content thresholds for consumer goods entering domestic retail channels. The regulation forces design studios to document substrate provenance and end-of-life pathways at pitch stage, not post-award. Premium cosmetics and electronics brands face the steepest compliance ramps, with METI documentation requirements now filtering supplier shortlists before creative review begins.
Brand procurement teams in India and Southeast Asia are unbundling graphic design from structural engineering to optimize cost allocation. FMCG headquarters in Mumbai and Jakarta now retain separate specialists for visual identity systems versus protective enclosure development, fragmenting traditional full-service relationships. This bifurcation pressures studios to declare core competencies explicitly, with material-specialized boutiques capturing sustainable paper assignments and engineering-heavy firms anchoring complex logistics-durability work.
Asia-Pacific Packaging Design Services Market Segmentation
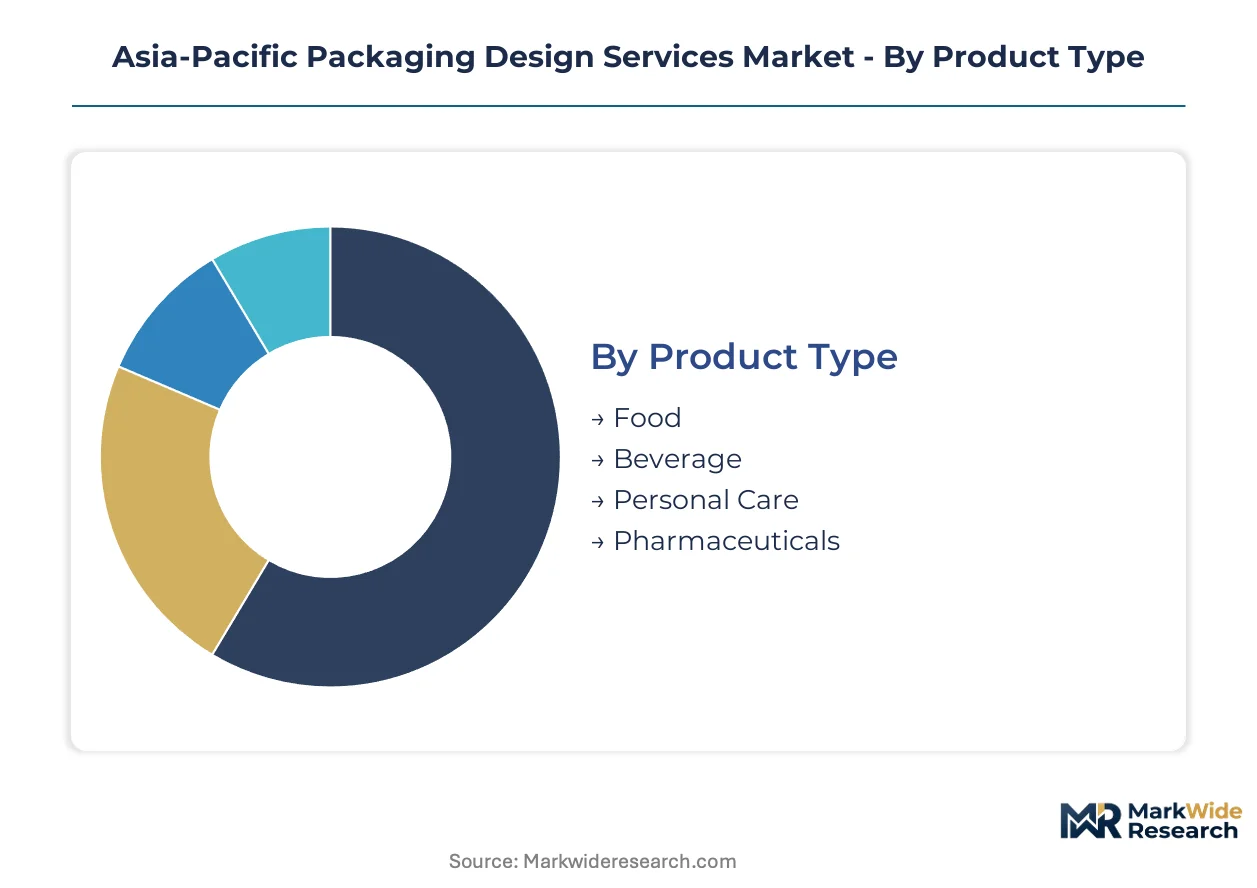
Packaging design services in Asia-Pacific fragment across four distinct dimensions, each commanding different margin profiles and compliance burdens. Studios structure retainers around whether assignments demand structural engineering depth, regulatory documentation intensity, or rapid graphic turnaround.
Product Type:
After-sales-service intensity varies sharply across product categories, with pharmaceutical and food assignments requiring ongoing regulatory amendment support while personal care work permits one-off delivery.
- Food:India's FSSAI labeling mandates force studios to embed compliance validation at concept stage, not post-award. Mumbai and Pune studios capture recurring amendment work as the regulator tightens nutritional disclosure rules.
- Pharmaceuticals:Track-and-trace serialization requirements across India, South Korea, and Japan demand design studios integrate authentication features during substrate selection. METI and CDSCO documentation cycles extend project timelines but lock in multi-year retainer relationships.
- Beverage:Premium spirits and functional drink brands in Australia and Japan commission structural designs balancing shelf impact with logistics durability.
- Personal Care:Cosmetics brands favor rapid graphic refresh cycles over structural innovation, compressing studio margins through template-based workflows.
By volume, Food leads. By growth pace, Pharmaceuticals is ahead.
Service Type:
Cost tier stratification separates premium consulting engagements from commoditized graphic production, with prototyping commanding intermediate pricing through speed-to-market validation.
- Consulting:Strategic advisory on regulatory pathway selection and material compliance documentation. Japanese electronics and Australian wine exporters pay premiums for METI and TGA pre-submission review.
- Prototyping:Physical and virtual sample development compressing concept-to-production timelines. Digital twin adoption among Japanese cosmetics brands collapses traditional weeks-long cycles to days.
- Graphic Design:Visual identity systems and label artwork, increasingly unbundled from structural engineering by cost-conscious FMCG procurement teams in Jakarta and Bangkok.
- Market Research:Shelf-impact testing and consumer preference studies, often outsourced to specialized agencies rather than integrated design studios.
Graphic Design handles the most assignments. Consulting delivers the steepest margin expansion.
Material Type:
Application requirements dictate material selection, with fiber-based substrates gaining share as India's western manufacturing corridor and Australia's APCO targets displace virgin plastic specifications.
- Paper:Fiber-based alternatives dominate sustainable assignments as FSSAI and APCO mandates accelerate brand migration from plastic. Mumbai studios capture volume through rapid paper prototyping capabilities.
- Plastic:Polymer substrates retain dominance in pharmaceutical blister packs and moisture-sensitive food applications where barrier properties remain non-negotiable.
- Glass:Premium beverage and cosmetics brands specify glass for perceived quality differentiation, though logistics durability concerns limit e-commerce adoption.
- Metal:Aerosol and canned food applications concentrated among legacy FMCG portfolios with established supply chain relationships.
Paper is expanding most quickly. Plastic retains the largest installed base.
End User:
Customer type determines service delivery models, with e-commerce platforms demanding protective structural specialization while retail channels prioritize shelf-impact optimization.
- E-commerce:Southeast Asian online retailers commission damage-reduction structural designs to cut return rates. Custom unboxing experiences anchor brand loyalty programs for digital-native consumers in Vietnam and Indonesia.
- Retail:Traditional brick-and-mortar channels in Japan and Australia emphasize point-of-sale visibility and regulatory compliance documentation for domestic placement.
- Wholesale:Bulk packaging optimization for logistics efficiency, with limited design innovation beyond standardization and palletization requirements.
- Manufacturing:Industrial goods packaging focused on protection during multi-modal transit, typically handled by in-house engineering teams rather than external studios.
E-commerce drives the steepest expansion trajectory. Retail maintains the deepest revenue base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Design studio capacity clusters along coastal manufacturing belts where FMCG headquarters, electronics exporters, and regulatory agencies concentrate compliance expertise. Japan's METI circular economy guidelines and India's FSSAI labeling mandates force studios to embed documentation into early creative phases, raising barriers for secondary-city operators.
India
Mumbai and Pune anchor the western manufacturing corridor where dense FMCG headquarters clusters commission rapid paper prototyping. FSSAI labeling mandates tighten nutritional disclosure rules, forcing studios to validate compliance at concept stage rather than post-award. Design boutiques in Maharashtra capture recurring amendment work as regulatory enforcement intensifies.
Japan
Tokyo and Osaka concentrate structural engineers with food-contact material expertise, creating talent scarcity premiums for secondary cities. METI's amended Packaging Recycling Act mandates higher recycled content thresholds and design-for-recyclability documentation before retail placement. Premium cosmetics and electronics brands filter supplier shortlists based on compliance readiness before creative review.
Australia
Sydney and Melbourne host studios serving wine exporters and premium food brands demanding rapid shelf-impact validation. APCO 2025 sustainability targets accelerate brand migration from virgin plastic toward fiber-based substrates. Digital twin adoption among cosmetics and beverage clients collapses traditional weeks-long prototyping cycles to days.
China
Yangtze River Delta electronics exporters drive demand for protective structural designs balancing logistics durability with unboxing experience. GB/T national standards for food contact materials raise compliance costs for studios serving multinational clients across multiple jurisdictions. Shanghai-based operators increasingly route just-in-time validation work previously handled through intermediaries.
Vietnam
Ho Chi Minh City electronics exporters commission damage-reduction packaging to cut return rates in Southeast Asian e-commerce channels. Studios establishing satellite operations near manufacturing zones capture structural validation work previously routed through Chinese intermediaries. Custom unboxing experiences anchor brand loyalty programs for digital-native consumers.
Asia-Pacific Packaging Design Services Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on material or regulatory documentation depth. The vendor base separates into three layers: full-service studios managing end-to-end creative-to-compliance workflows, material-specialized boutiques capturing sustainable substrate assignments, and rapid-prototyping houses serving speed-to-market validation. Consolidation pressures concentrate among mid-tier operators struggling to interface client ERP platforms with legacy CAD systems. Dominant competitive moves include geographic satellite expansion near manufacturing clusters and regulatory compliance bundling into retainer structures.
Within the material-specialized tier, Pulp+Wire and Arhue exemplify divergent positioning strategies. Pulp+Wire occupies a position anchored in fiber-based graphic design depth for sustainable paper assignments. Arhue represents the prototyping-heavy archetype serving premium beverage clients across India's western states. Murmur creative sits within the boutique segment emphasizing visual identity systems unbundled from structural engineering. These three players illustrate how studios declare core competencies explicitly as brand procurement teams fragment traditional full-service relationships.
| Leading Market Players |
|---|
| La Visual Inc. |
| Murmur creative |
| Arhue |
| Ruckus Marketing |
| Pulp+Wire |
| DEI Creative |
| Legnd |
| Tank design |
| Forever Sincretix |
| Others |
Value Network & Pricing Analysis
Mumbai and Pune design studio clusters concentrate rapid prototyping capacity for India's western FMCG corridor, translating geographic supply density into premium pricing power for compliance-ready concept packages. METI documentation requirements and FSSAI labeling mandates force buyers to absorb higher retainers for studios embedding regulatory validation at ideation stages.
Pricing Analysis
METI's amended Packaging Recycling Act dictates the pricing tier structure across Japanese assignments, separating compliance-ready studios from documentation-deficient competitors. Three-tier pricing structure across premium consulting, mid-market prototyping, and commoditized graphic design levels reflects certification depth and speed-to-market validation. Cost compression in graphic design tier is intensifying because template-based tools and unbundled procurement fragment traditional full-service relationships. FMCG procurement teams in Jakarta and Bangkok exhibit highest price sensitivity, while premium cosmetics and electronics brands in Tokyo and Osaka prioritize compliance readiness over cost minimization.
Supply Chain Analysis
Tariff exposure between Australia and Southeast Asian recovered fiber collection networks dominates supply chain risk calculus for paper-specialized studios. Raw material sourcing draws from Indonesian pulp plantations, Australian domestic recycling infrastructure, and Indian recovered fiber imports. Design studio operations rest on substrate provenance documentation, digital twin software licenses, and specialized structural engineering talent concentrated in Tokyo and Sydney. Single-source vulnerability characterizes the talent layer, where food-contact material expertise clusters in premium metropolitan markets. Distribution runs through direct retainer relationships with FMCG headquarters, bypassing traditional agency intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FMCG procurement consolidation across Mumbai and Jakarta fragments traditional full-service design relationships, concentrating buyer power with cost-optimization mandates. Brand headquarters now unbundle graphic design from structural engineering, forcing studios to declare explicit core competencies.
For Market Incumbents: Harden compliance bundling into multi-year retainer structures before METI and FSSAI enforcement intensifies. Anchor premium positioning through proprietary digital twin platforms that compress concept-to-sample timelines. Defensive capacity addition in Ho Chi Minh City satellite operations captures electronics exporter validation work migrating from Chinese intermediaries.
For New Entrants and Emerging Players: Pursue Vietnamese manufacturing integration as the most penetrable geography, where electronics exporters demand just-in-time structural validation previously routed through Shanghai-based operators. Target pharmaceutical serialization convergence across India, South Korea, and Japan as the white-space application. Go-to-market angle emphasizes authentication feature integration at substrate selection stage, locking in multi-year relationships through track-and-trace mandate compliance.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors material-specialized boutiques with fiber-based graphic design depth and regulatory documentation capabilities. Long-term viability rests on studios capturing sustainable paper assignments as APCO and FSSAI mandates accelerate brand migration from virgin plastic. Acquisition target archetype combines rapid prototyping infrastructure with embedded lifecycle analysis expertise. Signal to watch is divergence between Indian BIS, Chinese GB/T, and Australian APCO compliance paths fragmenting multinational retainer structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Compliance Bundling | METI documentation requirements filter supplier shortlists before creative review begins. |
| Digital Twin Platform Investment | Virtual prototyping collapses weeks-long cycles to days for Japanese cosmetics brands. |
| Vietnamese Satellite Expansion | Ho Chi Minh City proximity captures electronics exporter validation from Chinese intermediaries. |
| Material Specialization Pivot | Fiber-based graphic design depth captures APCO and FSSAI-driven paper acceleration. |
| Pharmaceutical Serialization Integration | Track-and-trace mandates across India, South Korea, and Japan lock in multi-year retainers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary research phases, combining structured interviews with design studio principals, FMCG brand managers, regulatory affairs specialists, and packaging procurement leads with secondary validation. Bottom-up triangulation drew from CDSCO filing databases, APCO sustainability reporting, METI circular economy guideline documentation, and customs records of recovered fiber trade flows. Top-down calibration referenced SEC disclosures from listed packaging converters and hyperscaler e-commerce fulfillment data.
Calibration against historical regulatory amendment cycles and technology adoption S-cures anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include service type tier, material substrate category, end-user channel, and product application vertical. CAGRs were derived through regression analysis of disclosed project volumes against regulatory enforcement intensity and e-commerce penetration indices. Forecast inputs incorporated digital twin adoption rates and pharmaceutical serialization mandate implementation timelines.
Sensitivities concentrate around recycled pulp input volatility, regulatory divergence between jurisdictions, and talent scarcity premiums in secondary cities. Forecasts reflect documented assumptions regarding enforcement intensity and technology diffusion rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging
PCR Bubble Films Market
Packaging
North America Aluminium Cans Market
Packaging
Coding Foils and Tapes Market
Packaging
USA and Canada Molded Fiber Pulp Packaging Market
Packaging
Thailand Rigid Plastic Packaging Market
Packaging
Asia-Pacific Retort Pouch Market
Packaging
Paper Tubes Market
Packaging
Automated Poly Bagging Machines Market
Packaging
Woven Sacks Market
Packaging
Malaysia Container Glass Market
Packaging
Paper Based Consumer Bags Market
Packaging
Spain Rigid Plastic Packaging Market
Packaging
Global Cosmetic Packaging Market
Packaging
Big Bag Discharge Station Market
Packaging
Europe Rigid Plastic Packaging Market
Packaging
Kraft Paper SOS Bag Market