
 Litho Laminated Packaging Market | 2026-2036
Litho Laminated Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Litho Laminated Packaging Market Foresight
Consumer electronics demand is decoupling from traditional corrugated plain boxes toward premium litho laminated formats. Smurfit Kappa Group leverages its European recycled fiber network to anchor supply for high-graphic retail-ready packaging. Graphic Packaging International, LLC differentiates through beverage multi-pack litho laminated carriers with integrated handles. Amcor plc extends its flexible packaging expertise into hybrid paper-polypropylene laminated structures for moisture-sensitive goods.
Litho laminated packaging combines offset-printed paper sheets adhesively bonded to corrugated or solid fiberboard substrates, typically achieving print resolutions of 175-200 line screen for photographic-quality graphics. The primary purpose is to merge protective shipping performance with shelf-ready brand communication, eliminating the need for separate outer sleeves or labels. Boxes dominate volume across food and beverage end users where retail visibility directly influences purchase decisions, while pouches represent the fastest-growing product type as snack brands convert from rigid to flexible laminated formats. Kraft material grades command premium positioning in organic and sustainable product lines, whereas BOPP film laminations serve electronics and cosmetics applications requiring grease and moisture barriers.
FDA food contact substance regulations govern adhesive and ink migration limits for U.S. litho laminated food packaging, while REACH compliance in Europe restricts certain phthalate-based plasticizers in laminated films. The EU Green Deal's packaging waste reduction targets are forcing converters to validate recyclability claims through certified testing protocols. Stakeholders must monitor how extended producer responsibility schemes reshape cost allocation between brands, converters, and retailers across major demand centers.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing converter timelines for recyclability validation while simultaneously pulling brand investment toward mono-material laminated structures over multi-layer alternatives.
Growth Catalysts
- E-commerce unboxing premiumization:Consumer electronics brands now specify litho laminated rigid boxes with soft-touch coatings and magnetic closures to drive social media shareability.
- REACH compliance migration:European food brands are converting from plastic trays to paper-based litho laminated carriers to preempt ECHA restrictions on single-use plastics.
- Water-based adhesive advances:New starch-polymer hybrid formulations eliminate solvent-based lamination, opening FDA food-contact applications previously blocked by migration limits.
Market Restraints
- Recycled pulp cost volatility:OCC (old corrugated containers) price swings in Germany's Ruhr industrial corridor directly compress converter margins on kraft-grade litho laminated orders.
- Platemaking bottleneck concentration:High-resolution 200-line screen photopolymer plate production concentrates among three European suppliers, creating 6-8 week lead time exposure for North American converters.
- Flexible pouch substitution:Stand-up pouches with rotogravure printing are capturing snack volume from rigid litho laminated boxes due to freight cube efficiency and shelf-ready hanging display compatibility.
Strategic Opportunities
- India PLI scheme alignment:Electronics manufacturing incentive clusters in Tamil Nadu and Karnataka are attracting litho laminated packaging investment for smartphone export boxes.
- Pharmaceutical serialization integration:EU Falsified Medicines Directive compliance requirements are creating demand for litho laminated cartons with embedded RFID and tamper-evident tear strips.
- Direct-to-retail channel expansion:Club store private-label beverage brands are bypassing traditional distributor networks, specifying pallet-ready litho laminated display trays with integrated handles.
Industry Challenges
- Color management specialist scarcity:Litho-to-corrugated registration tolerance of ±0.3mm demands press operators trained in both offset and flexographic disciplines, a combination rare outside Düsseldorf and Chicago training centers.
- Recyclability certification lag:PPWR-compliant testing through accredited European laboratories currently requires 14-18 weeks, delaying new product launches for seasonal food promotions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Litho Laminated Packaging Market |
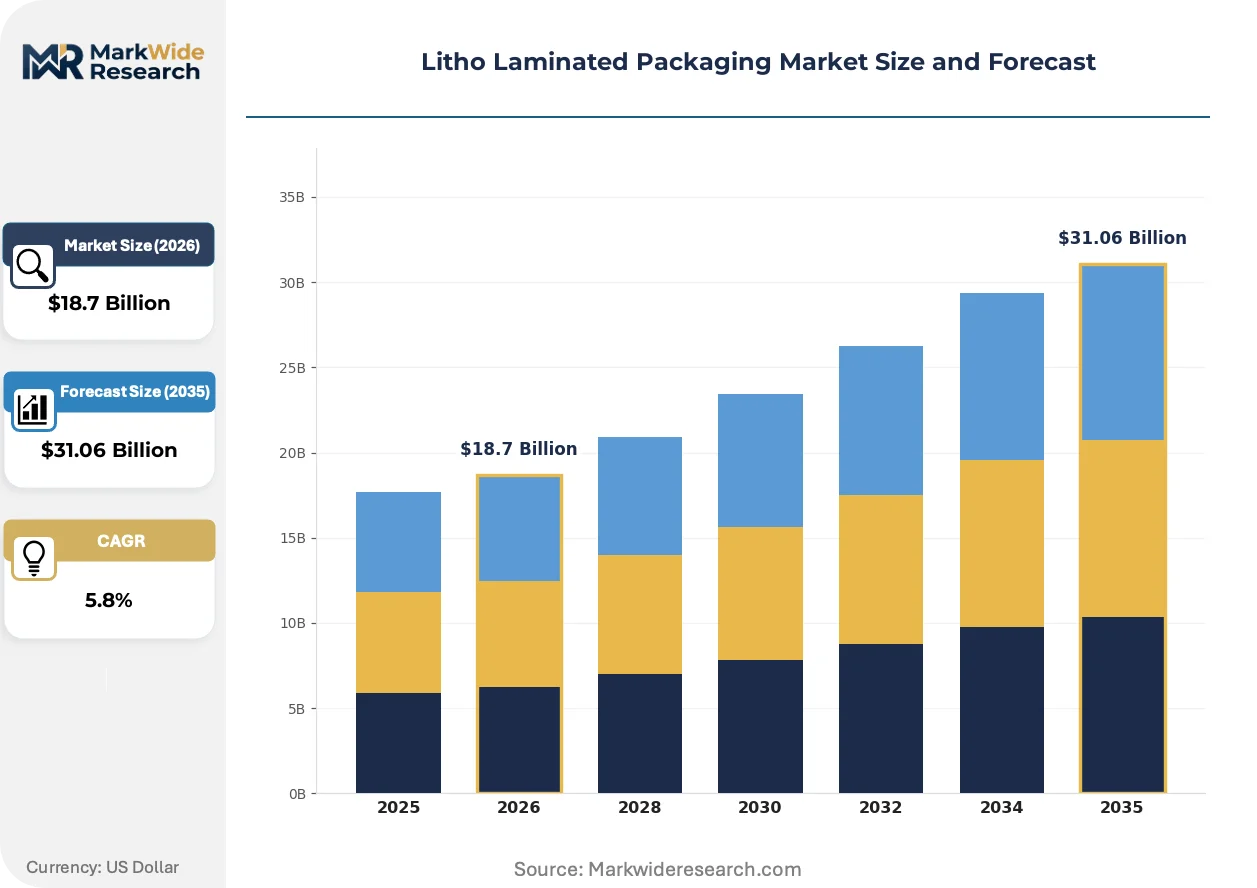
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Trays, Labels, Pouches End User: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Material: Paperboard, Polypropylene, BOPP, Kraft Design Type: Graphics, Textured, Custom Shapes, Functional |
| Companies Covered | International Paper Company, Smurfit Kappa Group, Graphic Packaging International, LLC, Mayr-Melnhof Karton AG, Parksons Packaging Ltd., Greif, Inc., Amcor plc, Sonoco Products Company, Huhtamaki, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Litho Laminated Packaging Market Shifts & Advancements
Digital print hybridization and mono-material structural redesign are converging to collapse the traditional trade-off between graphic fidelity and circularity performance.
Water-based barrier coatings are expanding into high-moisture food applications previously reserved for plastic laminations. Snack brands in the Netherlands and California are piloting these coatings on litho laminated boxes for frozen appetizers. This expansion is compressing the addressable market for conventional PE extrusion lamination while validating new ASTM recyclability protocols.
EU Green Deal packaging waste reduction targets are forcing converters to eliminate non-fiber components from laminated structures. Germany's VerpackG extended producer responsibility scheme now assigns higher fees to non-recyclable multi-material packaging, redirecting R&D investment toward fiber-only alternatives with heat-sealable aqueous coatings.
Brand procurement teams are consolidating supplier panels to capture volume leverage on sustainability-certified substrates. Food and beverage multinationals in France and the United Kingdom are reducing qualified litho laminated converters from twelve to four per region, replacing fragmented spot-buying with multi-year framework agreements tied to verified recycled content thresholds.
Litho Laminated Packaging Market Segmentation
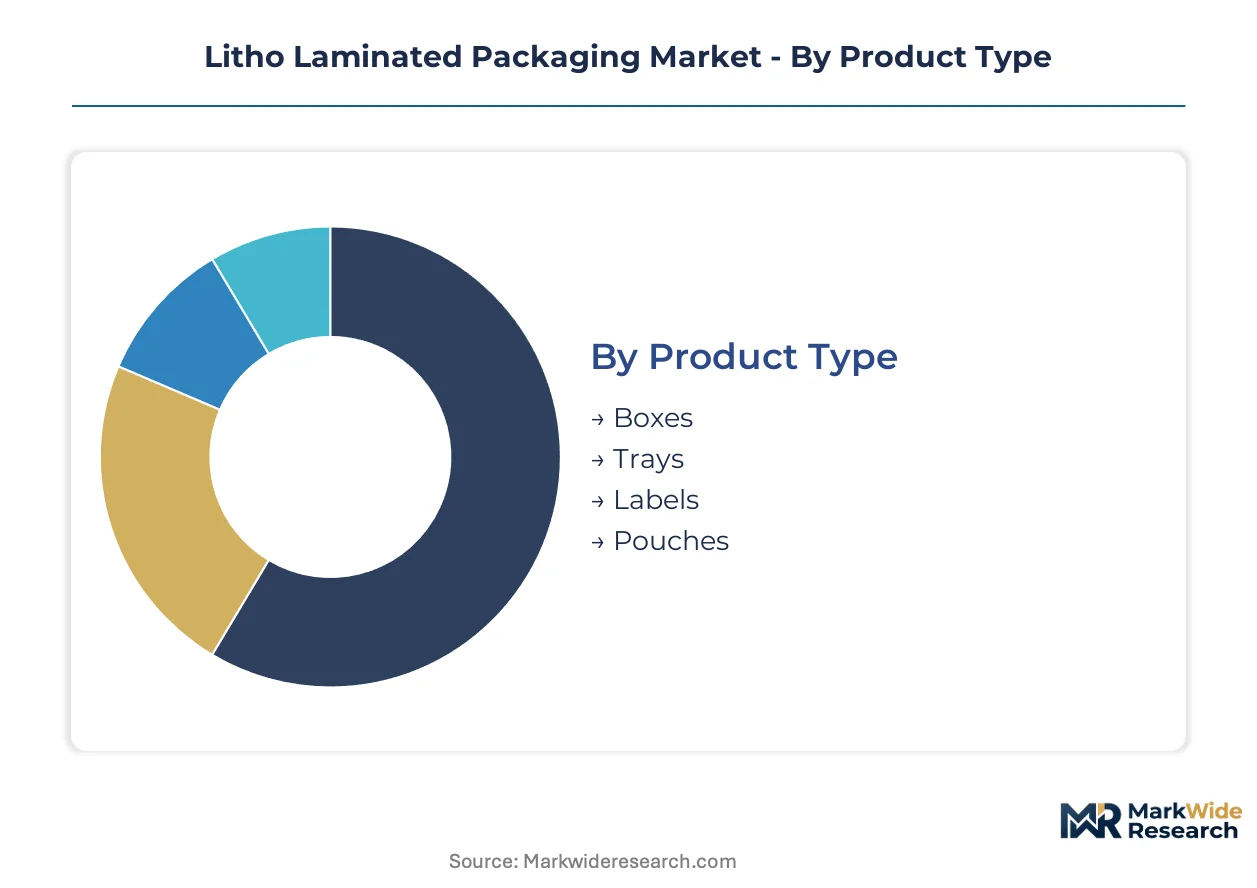
Litho laminated packaging serves divergent performance requirements across rigid shipping protection, retail shelf impact, and flexible convenience formats. Material selection and structural design directly determine recyclability compliance costs and brand procurement decisions.
Product Type:
End-use durability requirements and freight cube economics drive format selection across consumer goods supply chains.
- Boxes:Rigid corrugated substrates bonded with offset-printed litho sheets achieve 175-200 line screen resolution for photographic shelf presence. Food and beverage brands in Germany's industrial corridor specify these for retail-ready case packs where graphic quality influences purchase decisions at point-of-sale.
- Pouches:Flexible laminated structures with rotogravure or hybrid digital printing displace rigid formats in snack applications. Stand-up pouch configurations with resealable zippers are expanding most quickly in California and Netherlands frozen appetizer trials using water-based barrier coatings.
- Trays:Shallow-depth corrugated carriers with integrated handles serve club store beverage multi-packs. These structures reduce material versus full boxes while maintaining pallet stability.
- Labels:Pressure-sensitive litho laminated facestocks adhere to primary containers for premium cosmetics and electronics unboxing experiences.
Boxes lead on scale; pouches lead on momentum.
End User:
Regulatory exposure and margin structure vary sharply across customer verticals.
- Food & Beverage:FDA food contact substance regulations and EU REACH compliance govern adhesive and ink migration limits. Brands converting from plastic trays to paper-based carriers face compressed timelines for PPWR recyclability validation through accredited European laboratories.
- Electronics:Unboxing experience specifications now mandate soft-touch coatings and magnetic closures for social media shareability. Smartphone export manufacturing in Tamil Nadu and Karnataka under India's PLI scheme is pulling dedicated packaging investment.
- Pharmaceuticals:EU Falsified Medicines Directive serialization requirements drive demand for cartons with embedded RFID and tamper-evident tear strips.
- Cosmetics:Premium positioning relies on textured substrates and custom structural finishes for gift set presentations.
Food & Beverage dominates procurement volume; Electronics commands the steepest expansion trajectory.
Material:
Recycled content thresholds and barrier performance requirements determine substrate economics.
- Kraft:Unbleached recycled fiber grades command premium positioning in organic and sustainable product lines. Germany's VerpackG extended producer responsibility scheme assigns preferential fee structures to fiber-only structures.
- BOPP:Biaxially oriented polypropylene film laminations provide grease and moisture barriers for electronics and cosmetics applications. Multi-material constructions face escalating compliance costs under EU Green Deal waste reduction targets.
- Paperboard:Solid bleached sulfate and coated unbleached kraft substrates balance printability with structural rigidity for high-graphic retail applications.
- Polypropylene:Extruded and cast film layers enable heat-sealable flexible formats, though mono-material redesign pressures are forcing substitution with aqueous-coated fiber alternatives.
Kraft anchors sustainable positioning; BOPP retains barrier-critical applications despite circularity headwinds.
Design Type:
Brand procurement consolidation toward multi-year framework agreements ties design specifications to verified sustainability credentials.
- Graphics:High-resolution photographic imagery with spot gloss and matte varnishes dominates mass-market food and beverage shelf competition. Registration tolerances of ±0.3mm demand press operators cross-trained in offset and flexographic disciplines.
- Functional:Integrated handles, tear strips, and resealable closures merge structural utility with brand communication. Club store private-label beverage brands specify pallet-ready display trays bypassing traditional distributor networks.
- Textured:Soft-touch aqueous coatings and embossed patterns differentiate premium cosmetics and electronics unboxing experiences.
- Custom Shapes:Die-cut windowing and irregular perimeters create distinctive silhouettes for limited-edition promotional campaigns.
Graphics commands the largest qualified supplier base; Functional design captures the fastest-growing specification category.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting litho laminated packaging investment toward jurisdictions with lower compliance costs and stronger manufacturing incentive frameworks. Production capacity is migrating from high-fee regulatory environments to zones offering extended producer responsibility relief and export-oriented industrial policy support.
Germany
Food and beverage brands in the Ruhr industrial corridor are converting plastic tray formats to paper-based litho laminated carriers under VerpackG extended producer responsibility fee pressure. REACH compliance migration is accelerating as ECHA restrictions on single-use plastics tighten. Düsseldorf anchors the continent's highest concentration of cross-trained press operators capable of maintaining ±0.3mm litho-to-corrugated registration tolerances.
China
Coastal manufacturing zones in Guangdong and Zhejiang provinces are absorbing smartphone export packaging demand from Tamil Nadu and Karnataka production clusters. SAMR packaging waste regulations are tightening recyclability validation requirements for domestic consumer goods. Shenzhen's electronics assembly ecosystem is pulling dedicated litho laminated box capacity for premium unboxing specifications with soft-touch coatings.
United States
FDA food contact substance regulations govern adhesive and ink migration limits for litho laminated food packaging across the Midwest and Southeast converting corridors. Water-based adhesive advances are opening applications previously blocked by solvent-based lamination restrictions. Chicago's graphic arts training infrastructure supplies press operators cross-trained in offset and flexographic disciplines.
India
Electronics manufacturing incentive clusters in Tamil Nadu and Karnataka under the PLI scheme are attracting litho laminated packaging investment for smartphone export boxes. DGFT export promotion frameworks support packaging material localization requirements. Bengaluru's industrial suburbs are emerging as dedicated capacity zones for high-graphic retail-ready formats.
Netherlands
Snack brands in Randstad logistics hubs are piloting water-based barrier coatings on litho laminated boxes for frozen appetizers, compressing PE extrusion lamination demand. EU Green Deal packaging waste reduction targets are forcing elimination of non-fiber components from laminated structures. Eindhoven's materials science ecosystem supports aqueous coating R&D for heat-sealable fiber-only alternatives.
Litho Laminated Packaging Market Competitive Landscape
Capacity expansion dominates the current landscape as converters race to capture e-commerce unboxing premiumization demand and pharmaceutical serialization integration opportunities. The vendor base stratifies across three tiers: integrated fiber-to-box conglomerates with captive pulp supply, mid-scale regional specialists focused on seasonal food promotions, and technology-forward players investing in digital print hybridization. Strategic archetypes include sustainability-certified substrate consolidators and mono-material structural redesign specialists. M&A activity and geographic expansion into India's PLI corridors represent the dominant competitive vectors.
Among integrated fiber-to-box conglomerates, Smurfit Kappa Group and International Paper Company occupy positions anchored by European and North American recycled fiber networks respectively. Graphic Packaging International, LLC exemplifies the beverage multi-pack specialization archetype. These three entities represent distinct strategic postures: fiber network control, retail-ready graphic integration, and format-specific carrier design.
| Leading Market Players |
|---|
| International Paper Company |
| Smurfit Kappa Group |
| Graphic Packaging International, LLC |
| Mayr-Melnhof Karton AG |
| Parksons Packaging Ltd. |
| Greif, Inc. |
| Amcor plc |
| Sonoco Products Company |
| Huhtamaki |
| Others |
Supply & Pricing Matrix
Cross-trained press operators in Düsseldorf and Chicago command wage premiums that propagate through litho laminated packaging pricing tiers, widening spreads between premium high-resolution formats and standard-grade alternatives as brands absorb skilled-labor scarcity into procurement decisions.
Pricing Analysis
Distributor margin compression in European electronics channels is intensifying as direct-to-OEM contracts for smartphone export boxes bypass traditional intermediaries. Three-tier pricing structure across premium, standard, and economy levels separates soft-touch coated unboxing formats from kraft-grade sustainable carriers and basic corrugated alternatives. Price differentiation hinges on certification grade — PPWR-compliant recyclability validation carries premium positioning — and volume scale, with club store beverage multi-packs extracting freight-cube discounts. Food and beverage brands show highest price sensitivity due to OCC pulp cost volatility, while cosmetics and electronics buyers prioritize graphic fidelity over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with European photopolymer plate suppliers for 200-line screen production, concentrating high-resolution tooling capacity among three specialized converters. Geographic supply concentration centers on Germany's Ruhr industrial corridor for kraft-grade fiber, China's Guangdong province for electronics assembly-integrated packaging, and India's Tamil Nadu for PLI-scheme export manufacturing. Raw material dependencies draw from recycled OCC pulp, BOPP film laminations, and starch-polymer hybrid adhesives. Tariff exposure on Chinese coated paperboard imports threatens margin stability for North American converters. Distribution runs through pallet-ready direct-to-retail channels for club store beverage brands and traditional distributor networks for seasonal food promotions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Litho laminated packaging represents a late-cycle quality story as consumer electronics procurement shifts decisively toward premium unboxing specifications with soft-touch coatings and magnetic closures.
For Market Incumbents: Deploy backward integration into captive recycled fiber networks to anchor kraft-grade supply against OCC price volatility. Consolidate platemaking partnerships across Düsseldorf and Chicago training centers to secure ±0.3mm registration tolerance capacity. Mono-material structural redesign investment preempts ECHA single-use plastic restrictions threatening multi-material BOPP laminations. For New Entrants and Emerging Players: Digital print hybridization technology offers entry into seasonal food promotion segments where 14-18 week PPWR certification timelines exclude established players. Target pharmaceutical serialization integration in EU Falsified Medicines Directive compliance markets, where embedded RFID and tamper-evident tear strips command specialist premiums. Partner with Eindhoven materials science clusters for aqueous coating R&D to bypass PE extrusion lamination incumbency. For Investors and Strategic Acquirers: Integrated fiber-to-box conglomerates are the most active acquirer in this space, seeking geographic expansion into India's PLI corridors and sustainability-certified substrate consolidation. Long-term viability rests on circularity-performance convergence — fiber-only alternatives with heat-sealable aqueous coatings displacing plastic laminations. Watch for water-based barrier coating validation in frozen appetizer applications as inflection indicator for PE extrusion substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-material Structural Redesign | Eliminates non-fiber components to satisfy EU Green Deal waste reduction targets and VerpackG fee structures. |
| Digital Print Hybridization | Collapses graphic fidelity-circularity trade-off for seasonal food promotions with compressed certification timelines. |
| Backward Integration into Recycled Fiber | Captive OCC pulp supply insulates converter margins from Ruhr industrial corridor price volatility. |
| Pharmaceutical Serialization Integration | EU Falsified Medicines Directive compliance creates demand for RFID-embedded cartons with tamper-evident features. |
| Geographic Expansion into PLI Corridors | Tamil Nadu and Karnataka electronics manufacturing incentives pull dedicated packaging capacity for smartphone exports. |
Research Methodology
Multiple input streams — primary interviews with packaging procurement directors, converter operations managers, and brand sustainability officers; secondary validation through customs trade records, SEC converter filings, and EU PPWR regulatory databases; plus technical R&D documentation from aqueous coating pilots — were reconciled through bottom-up and top-down triangulation to establish market sizing and growth trajectory parameters.
Historical volume trajectories were cross-referenced against panel input from industry stakeholders to anchor projection assumptions across the analysis window. Segmentation modeling incorporated product type, end-use vertical, material grade, and regional regulatory cluster dimensions. CAGRs were derived from fitted growth curves calibrated to e-commerce unboxing premiumization rates and pharmaceutical serialization mandate compliance timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA plastic restriction enforcement velocity and India PLI scheme extension decisions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Metalized Flexible Packaging Market
Flexible Packaging
Flexible Packaging Paper Market
Flexible Packaging
Mexico Flexible Plastic Packaging Market
Flexible Packaging
GCC Shrink Sleeves Market
Flexible Packaging
Germany Flexible Plastic Packaging Market
Flexible Packaging
Saudi Arabia Flexible Plastic Packaging Market
Flexible Packaging
Industrial Flexible Packaging Market
Flexible Packaging
Canada Flexible Packaging Market
Flexible Packaging
Canada Multilayer Flexible Packaging Market
Flexible Packaging
Europe, Middle East and Africa (EMEA) Flexible Packaging Market
Flexible Packaging
Multilayer Flexible Packaging Market
Flexible Packaging
ASEAN Flexible Packaging Market
Flexible Packaging
Latin America Flexible Plastic Packaging Market
Flexible Packaging
Stretch Packaging Market
Flexible Packaging
Canada Flexible Plastic Packaging Market
Flexible Packaging
Benelux Flexible Plastic Packaging Market