
 Multilayer Flexible Packaging Market | 2026-2036
Multilayer Flexible Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Multilayer Flexible Packaging Market Outlook
Food & Beverage end users is consolidating procurement around extended-shelf-life pouch formats for ready-to-eat meals and retorted proteins. Amcor plc leverages its global extrusion footprint to supply coextruded barrier films at scale across multiple continents. Mondi Group anchors Central European demand through integrated kraft paper and plastic film operations that serve fresh produce chains. Sealed Air Corporation differentiates via automated packaging systems bundled with multilayer film supply, tightening customer lock-in.
Multilayer flexible packaging consists of laminated or coextruded films combining three or more polymer layers, typically incorporating ethylene vinyl alcohol or polyamide barrier cores with sealant-grade polyethylene skins, engineered to control oxygen transmission below 1 cc per square meter per day for sensitive contents. Its primary purpose centers on preserving food safety, extending shelf stability, and reducing material mass versus rigid alternatives in supply chain distribution. Pouches and stand-up pouches capture expanding margin pools as brand owners shift from glass and metal formats in premium sauces, baby food, and pet nutrition. Polyethylene and polypropylene substrates dominate volume throughput, though nylon and BOPP films gain share in puncture-resistant medical device overwrap and high-speed form-fill-seal pharmaceutical operations.
FDA food contact substance notifications govern barrier adhesive chemistry approvals in the United States, while ECHA REACH restrictions on perfluorinated compounds and EU Green Deal circularity targets are forcing material redesign across European supply chains. India's BIS standards for plastic food packaging and the CDSCO's evolving pharmaceutical packaging guidelines create dual compliance burdens for converters serving both sectors. Stakeholders must monitor regulatory divergence between jurisdictions and decide whether to standardize formulations globally or maintain region-specific product lines.
Market Dynamics
Food & Beverage manufacturers are consolidating procurement around high-barrier pouch formats, forcing converters to retool extrusion lines and adhesive chemistries simultaneously. This demand compression is reshaping supplier relationships and capacity allocation across polymer supply chains.
Growth Catalysts
- ECHA REACH compliance deadlines:European converters are accelerating solvent-free adhesive adoption ahead of perfluorinated compound restrictions, creating pull-through demand for compliant lamination equipment.
- India PLI scheme for food processing:Domestic packaging conversion is accelerating as subsidy-backed cold chain infrastructure expands, drawing multilayer film investment toward Maharashtra and Gujarat clusters.
- Retorted protein formats:Ready-to-eat meal brands are specifying oxygen transmission rates below 0.5 cc per square meter per day, tightening technical specifications across barrier layer engineering.
Market Restraints
- Ethylene vinyl alcohol supply concentration:Three Asian petrochemical groups control over 70 percent of global EVOH resin capacity, exposing converters to force majeure risk and quarterly price volatility.
- Multi-layer recycling incompatibility:Current mechanical separation technologies cannot economically delaminate polyethylene-polyamide bonds, blocking circular economy claims and landfill diversion targets.
- FDA notification timelines:Food contact substance approvals for novel barrier adhesives stretch 18-24 months, freezing formulation innovation cycles for US-bound exports.
Strategic Opportunities
- Pharmaceutical cold chain expansion:Temperature-sensitive biologics distribution is creating demand for insulated multilayer pouches with phase-change material integration, a category with minimal incumbent supply.
- Digital printing convergence:HP Indigo and EFI systems are enabling run-length flexibility down to 5,000 units, allowing regional brands to trial SKU proliferation without plate costs.
- BIS certification acceleration:India's mandatory plastic food packaging standards are disqualifying unorganized converters, creating acquisition targets for compliant mid-cap players.
Industry Challenges
- Adhesive chemist scarcity:Formulation expertise combining polymer science with regulatory compliance is concentrated among retiring specialists, constraining R&D throughput at Tier-2 converters.
- Legacy solvent-based line stranding:Capital-intensive lamination equipment with 15-year depreciation schedules cannot be economically retrofitted for water-based or solventless chemistry, freezing asset turnover.
- Multi-jurisdiction certification stacking:Simultaneous FDA, EFSA, and FSSAI approvals for global food brands extend product launch timelines by 8-14 months versus single-market equivalents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multilayer Flexible Packaging Market |
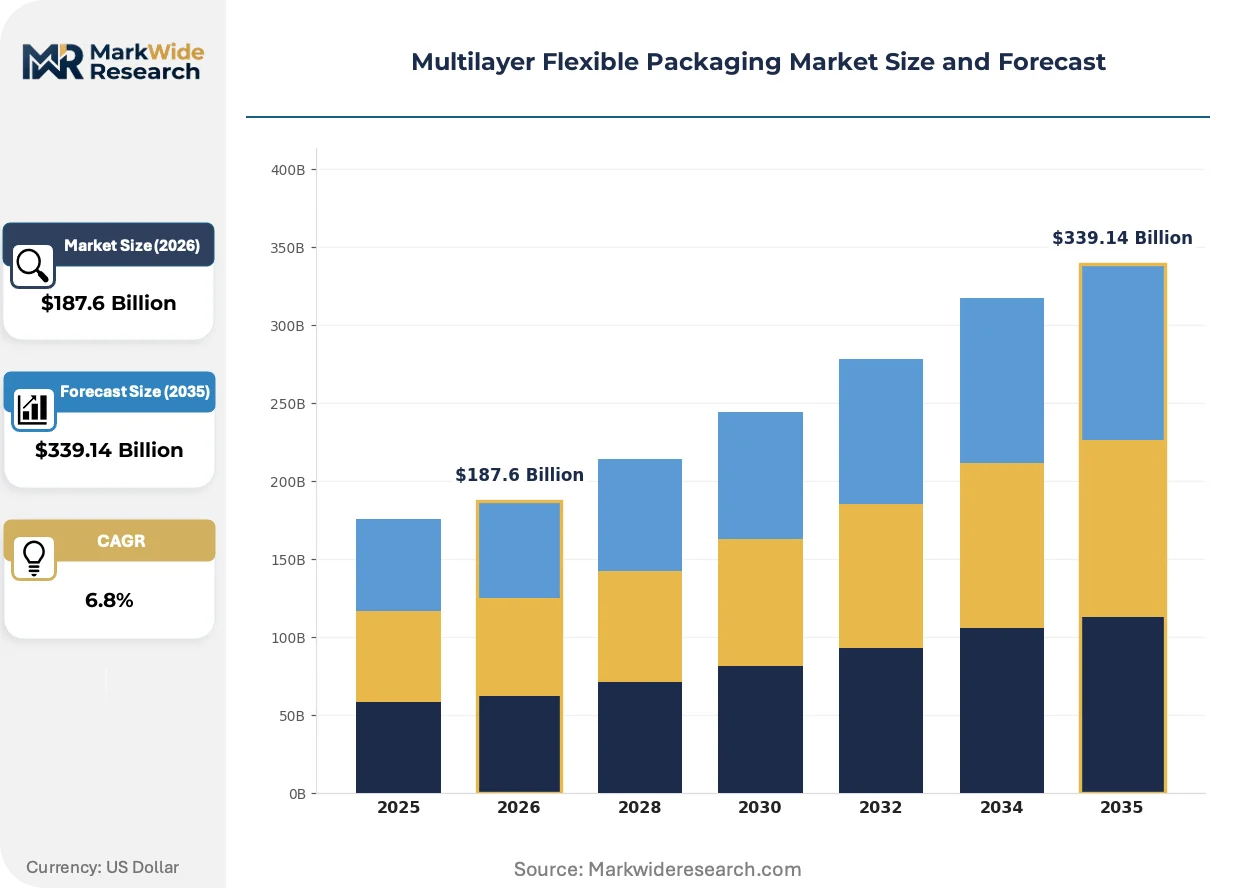
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $339.14 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Pouches, Films, Rollstock Material: Polyethylene, Polypropylene, Nylon, BOPP End User: Food & Beverage, Pharmaceuticals, Cosmetics, Personal Care Packaging Type: Rigid, Semi-Rigid, Flexible, Stand-Up Pouches |
| Companies Covered | Sealed Air Corporation, Winpak Ltd., Amcor plc, Coveris Holdings S.A., Schur Flexibles Holding GmbH, Mondi Group, Constantia Flexibles, Clondalkin Flexible Packaging, Berry Global Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multilayer Flexible Packaging Market Strategic Shifts
Barrier technology and regulatory chemistry are converging to redefine competitive positioning in multilayer packaging. Three distinct vectors are compressing legacy approaches and opening white space for compliant, high-performance formats.
Mono-material polyethylene barrier films are unifying sealant and barrier functions within single-polymer structures. Retail grocery private labels are specifying these formats for store-brand snacks and frozen vegetables to preempt extended producer responsibility fees. This unification is collapsing the traditional laminate supply chain into streamlined coextrusion operations, displacing multi-step adhesive lamination for mid-barrier applications.
EU Green Deal circularity targets are mandating recyclable-by-design packaging across member states by 2030. The industrial consequence is forced elimination of polyamide and EVOH barrier layers in favor of compatible polyethylene or polypropylene alternatives. Fresh produce chains in Germany and the Netherlands are already rejecting non-recyclable formats, compressing the transition window for converters serving pan-European accounts.
Brand-owner technical audits are replacing certificate-based supplier qualification. Major food manufacturers are deploying on-site extrusion line inspections and barrier testing protocols before contract award, bypassing traditional distributor relationships. This behavioral shift is most visible in North American protein packaging, where Tyson and JBS subsidiaries are consolidating approved vendor lists to under twenty qualified converters.
Multilayer Flexible Packaging Market Segmentation
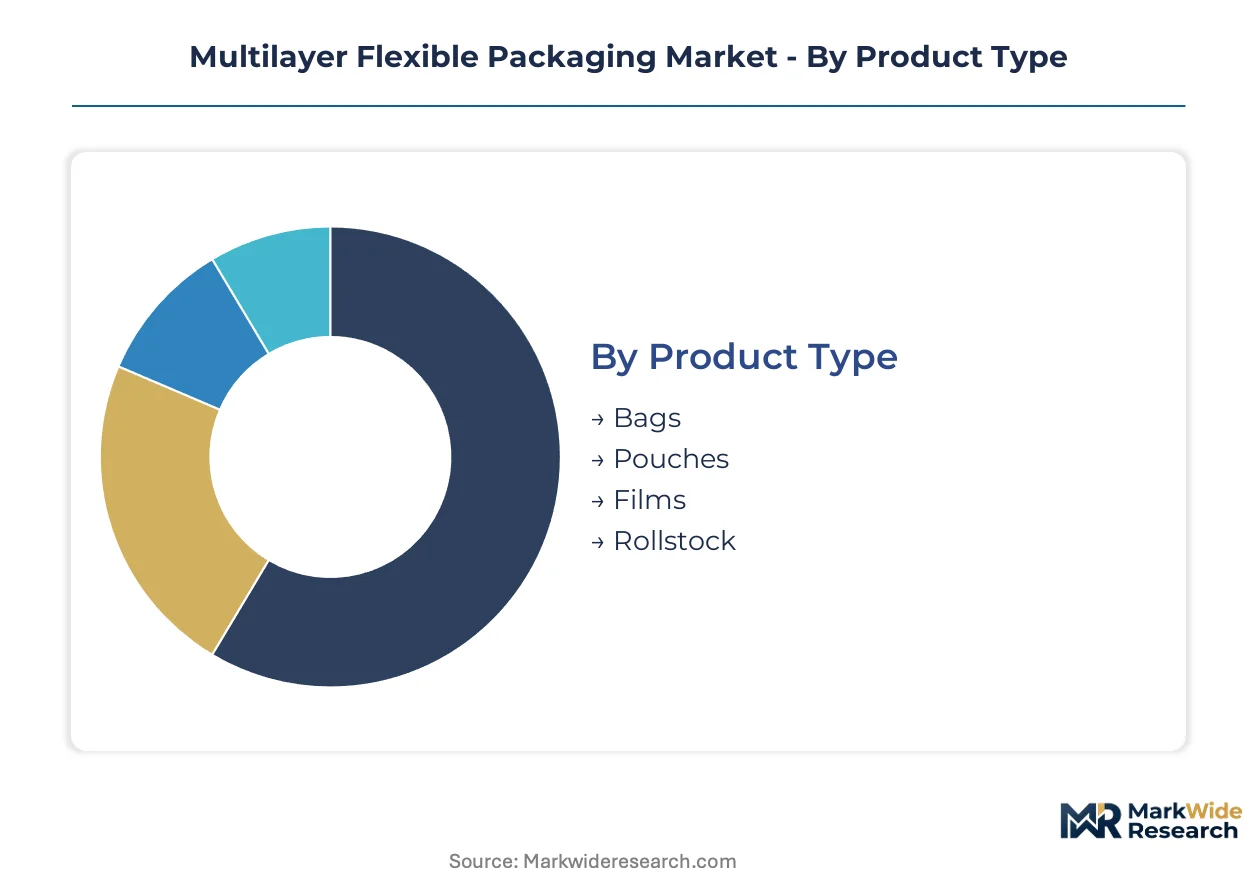
Multilayer flexible packaging segmentation reveals divergent margin structures across material grades and end-use specifications. Product type and material selections determine barrier performance thresholds, while end-user consolidation is compressing supplier diversity in high-volume categories.
Product Type:
Pouches command premium positioning against commodity bags, with volume concentration shifting toward formats that displace rigid alternatives.
- Bags:Three-side-seal and gusseted configurations dominate dry goods and frozen vegetable applications. Demand concentrates in North American retail private labels where cost-per-unit sensitivity overrides barrier sophistication.
- Pouches:Spouted and fitment-equipped formats incorporate EVOH or polyamide cores with polyethylene sealant skins for retorted proteins and premium sauces. European ready-to-eat meal brands are specifying oxygen transmission below 0.5 cc per square meter per day, tightening converter qualification protocols.
- Films:Coextruded barrier webs serve medical device overwrap and pharmaceutical blister lidding with puncture-resistant nylon or BOPP surface layers.
- Rollstock:Form-fill-seal compatible webs enable high-speed automated packaging lines for snack foods and confectionery, with throughput economics favoring integrated converter operations.
Mature deployment sits with Bags. Newer deployment is concentrated in Pouches.
Material:
Substrate selection traces directly to barrier requirements and recycling compatibility pressures across jurisdictions.
- Polyethylene:Linear low-density and metallocene grades function as sealant layers and, in mono-material constructions, unified barrier-sealant structures. Retail grocery chains in Germany and the Netherlands are mandating recyclable-by-design specifications that eliminate incompatible polymer combinations.
- Polypropylene:Cast and oriented films provide clarity and moisture barrier for snack and confectionery applications. India's BIS certification requirements for plastic food packaging are accelerating domestic polypropylene film capacity expansion in Maharashtra and Gujarat clusters.
- Nylon:Polyamide 6 and 6/6 copolymers deliver puncture resistance and thermoformability for medical device packaging and vacuum-sealed meat products.
- BOPP:Biaxially oriented polypropylene offers high gloss and printability for premium label and overwrap applications with moderate barrier demands.
Polyethylene and polypropylene together constitute volume leadership. Nylon maintains premium positioning in technical medical and protein packaging segments.
End User:
Procurement consolidation patterns diverge sharply between shelf-stable food systems and regulated healthcare packaging.
- Food & Beverage:Manufacturers are compressing approved vendor lists to under twenty qualified converters per category, deploying on-site extrusion line audits and barrier testing protocols before contract award. Retorted protein and ready-to-eat meal specifications are driving oxygen transmission rate tightening across supply chains.
- Pharmaceuticals:Temperature-sensitive biologics distribution is creating demand for insulated multilayer pouches with phase-change material integration. CDSCO evolving guidelines and FDA food contact substance notification timelines create dual compliance burdens for converters serving both Indian and US markets.
- Cosmetics:Premium skincare and fragrance brands specify high-clarity films with metallized or oxide-coated barrier layers for aesthetic and shelf-life requirements.
- Personal Care:Wipes and hygiene product packaging prioritizes moisture barrier and reseal functionality over oxygen exclusion, permitting simpler coextruded structures.
Food & Beverage anchors volume throughput. Pharmaceuticals represents the steepest expansion trajectory as cold chain infrastructure proliferates.
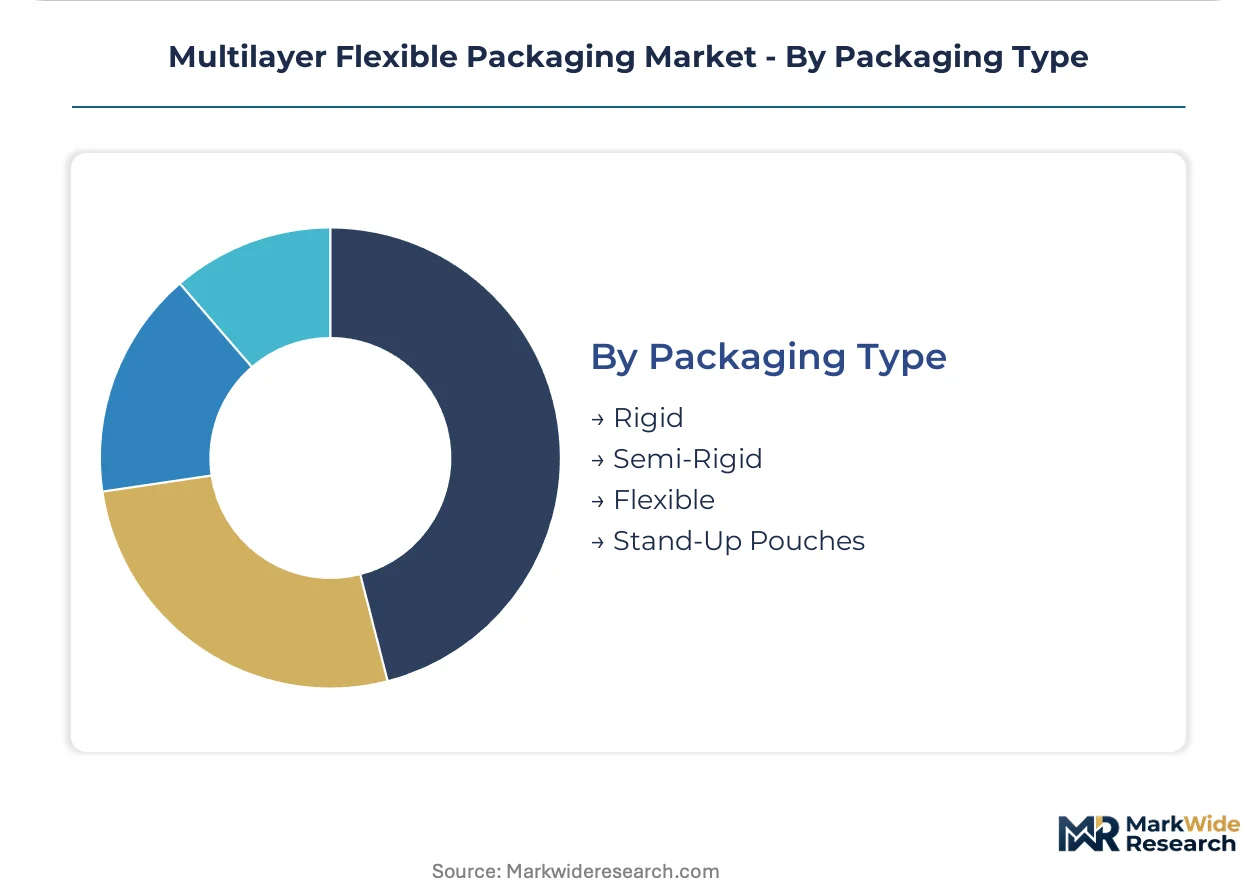
Packaging Type:
Flexibility gradation determines equipment compatibility and logistics density in distribution networks.
- Rigid:Thermoformed multilayer trays and cups retain shape for automated handling in protein and prepared meal applications.
- Semi-Rigid:Modified atmosphere packaging formats balance stackability with material reduction versus fully rigid alternatives.
- Flexible:Pillow packs and flow-wrapped formats maximize cube utilization in transportation and retail shelf density.
- Stand-Up Pouches:Doyen and K-seal configurations with bottom gussets provide shelf presence and dispensing convenience for premium sauces, baby food, and pet nutrition, displacing glass and metal formats.
Flexible formats dominate commodity throughput. Stand-Up Pouches are gaining share fastest in brand-owner premiumization strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Production Linked Incentive scheme for food processing infrastructure is concentrating multilayer film investment in Maharashtra and Gujarat industrial corridors. Germany's EU Green Deal compliance deadlines are forcing material redesign across converter operations. The United States maintains stringent FDA food contact substance notification requirements that govern barrier adhesive approvals.
United States
Retorted protein and ready-to-eat meal brands are consolidating procurement around oxygen transmission specifications below 0.5 cc per square meter per day. FDA notification timelines for novel barrier adhesives stretch 18-24 months, freezing formulation innovation cycles for domestic converters. Tyson and JBS subsidiaries in the Midwest and Southeast are compressing approved vendor lists to under twenty qualified converters per category.
Germany
Fresh produce chains in Germany and the Netherlands are rejecting non-recyclable multilayer formats ahead of 2030 circularity mandates. ECHA REACH restrictions on perfluorinated compounds are accelerating solvent-free adhesive adoption across lamination operations. The Ruhr industrial cluster hosts integrated kraft paper and plastic film operations serving pan-European distribution networks.
India
BIS certification standards for plastic food packaging are disqualifying unorganized converters and creating acquisition targets for compliant mid-cap players. The PLI scheme subsidy-backed cold chain infrastructure is expanding across Maharashtra and Gujarat clusters. Domestic packaging conversion is accelerating as food processing investment concentrates in western industrial corridors.
China
Three Asian petrochemical groups control over 70 percent of global EVOH resin capacity, exposing converters to force majeure risk and quarterly price volatility. National standards for food contact materials govern barrier layer approvals in the domestic market. Yangtze River Delta manufacturing zones concentrate coextrusion equipment and adhesive formulation capabilities for export-oriented production.
Multilayer Flexible Packaging Market Competitive Environment
Top-tier vendors anchor global extrusion and lamination capacity, while mid-cap specialists occupy regional niches with certified formulations for specific end-use segments. The vendor base stratifies across integrated multinational operations, regional converter networks, and equipment-bundled solution providers. Strategic archetypes include scale-driven barrier film suppliers, compliance-focused regional converters, and automated packaging system integrators. Dominant competitive moves center on adhesive chemistry retrofitting for regulatory compliance and extrusion line consolidation to serve consolidating food brand procurement.
Among integrated multinational operators, Amcor plc and Mondi Group occupy positions exemplifying global extrusion footprint leverage and integrated kraft-plastic operations respectively. Sealed Air Corporation represents the equipment-bundled archetype, tightening customer relationships through automated packaging system integration with film supply. These three entities anchor distinct competitive vectors within a market where procurement consolidation and regulatory chemistry redesign are compressing legacy positioning.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Winpak Ltd. |
| Amcor plc |
| Coveris Holdings S.A. |
| Schur Flexibles Holding GmbH |
| Mondi Group |
| Constantia Flexibles |
| Clondalkin Flexible Packaging |
| Berry Global Group |
| Others |
Value Chain & Pricing Dynamics
Solvent-free adhesive retrofitting across European lamination operations simultaneously compresses production economics and concentrates supplier relationships around compliant equipment vendors. This technology transition forces converters to absorb capital costs while EVOH resin supply concentration in Asian petrochemical corridors limits their ability to pass through price adjustments to consolidated food brand buyers.
Pricing Analysis
Short lead-time premiums dominate converter pricing structures, with spot inventory availability commanding substantial markups over contract-scheduled deliveries. Three-tier pricing structure across premium, standard, and economy levels separates certified pharmaceutical-grade barrier films from commodity snack packaging and unbranded agricultural formats. Pricing pressure stems from food brand procurement consolidation, which squeezes mid-tier converters between specification tightening and volume concentration demands. Private label retail chains exhibit highest price sensitivity, while pharmaceutical cold chain operators prioritize barrier performance over unit cost.
Supply Chain Analysis
Freight cost volatility from Asian EVOH resin corridors to European and North American converter operations has amplified working capital requirements across the value chain. Supply concentrates in China, South Korea, and Japan for barrier resin production, while film extrusion and lamination capacity clusters in Germany, the United States, and India. Raw material dependencies center on ethylene vinyl alcohol copolymers, polyamide resins, and solvent-free adhesive formulations. Single-source vulnerability from three Asian petrochemical groups controlling over 70 percent of global EVOH capacity exposes converters to force majeure disruption. Distribution runs through integrated converter-direct relationships with consolidating food and pharmaceutical brand owners, displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multilayer flexible packaging is consolidating around regulatory-compliant scale players as ECHA REACH deadlines and FDA notification timelines disqualify formulation-limited competitors. Procurement compression from Tyson, JBS, and European ready-to-eat meal brands is accelerating this shakeout.
For Market Incumbents: Deploy solvent-free adhesive retrofitting as the priority lever to defend European contract positions ahead of perfluorinated compound restrictions. Incumbents should simultaneously consolidate extrusion capacity in Maharashtra and Gujarat clusters to capture PLI-subsidized Indian food processing demand. This dual-track approach counters emerging mono-material polyethylene specialists while locking in high-barrier pouch specifications with consolidating protein brands. For New Entrants and Emerging Players: Launch via pharmaceutical cold chain specialization targeting temperature-sensitive biologics distribution with phase-change material integration. New entrants should prioritize India's BIS certification acceleration window, where mandatory plastic food packaging standards are disqualifying unorganized converters and creating acquisition-ready mid-cap targets. This regulatory-driven entry path bypasses entrenched food brand supplier relationships while capturing the steepest expansion trajectory in end-use demand. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated multinational operators seeking compliant regional capacity. Long-term viability favors converters with backward integration into adhesive formulation and demonstrated multi-jurisdiction certification stacking capabilities across FDA, EFSA, and FSSAI frameworks. Investors should monitor EVOH resin price volatility spikes as the inflection signal for distressed asset availability among working-capital-constrained Tier-2 players.| Strategic Initiative | Industry Significance |
|---|---|
| Solvent-Free Adhesive Retrofitting | ECHA REACH compliance deadlines force capital deployment ahead of perfluorinated compound restrictions. |
| Integrated Kraft-Plastic Operations | Mondi Group's Ruhr cluster model serves pan-European fresh produce chains with unified paper-film supply. |
| Automated Packaging System Bundling | Sealed Air Corporation tightens customer lock-in through equipment-film integration contracts. |
| Mono-Material Polyethylene Transition | EU Green Deal circularity mandates eliminate polyamide barrier layers by 2030 compliance deadlines. |
| Pharmaceutical Cold Chain Expansion | Biologics distribution creates white space for insulated multilayer pouches with minimal incumbent supply. |
Study Parameters
Independent corroboration across converter operations managers, food brand procurement directors, adhesive formulation chemists, and pharmaceutical packaging engineers underwrites the qualitative findings in this study. Primary fieldwork combined structured interviews with secondary validation through ECHA REACH regulatory filings, FDA food contact substance notifications, BIS certification databases, and customs trade data for EVOH resin imports. Bottom-up capacity assessments at Maharashtra and Gujarat industrial clusters were triangulated against top-down demand modeling from PLI scheme disbursement trajectories.
Rate-of-change decomposition across the analysis window separates volume growth from value expansion and margin compression dynamics. Segmentation dimensions modeled include product type, material substrate, end-user industry, and packaging flexibility grade, with additional granularity on barrier performance tier and regulatory certification status. CAGRs were derived from polynomial trend fitting of historical capacity utilization and forward projection of procurement consolidation patterns. Industry-specific forecast inputs incorporate EVOH resin supply concentration risk and solvent-free lamination equipment deployment rates.
EVOH supply disruption, regulatory timeline acceleration, and mechanical recycling technology breakthrough are the dominant revision risks that could materially alter trajectory assumptions across the projection horizon. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Global Flexible Plastic Packaging Market
Flexible Packaging
Asia Pacific Single-Use Packaging Market
Flexible Packaging
Japan Flexible Plastic Packaging Market
Flexible Packaging
GCC Shrink Sleeves Market
Flexible Packaging
Mexico Flexible Plastic Packaging Market
Flexible Packaging
Metalized Flexible Packaging Market
Flexible Packaging
Indonesia Flexible Packaging Market
Flexible Packaging
Morocco Flexible Packaging Market
Flexible Packaging
Latin America Flexible Plastic Packaging Market
Flexible Packaging
Latin America Flexible Packaging Market
Flexible Packaging
Asia-Pacific Flexible Plastic Packaging Market
Flexible Packaging
Brazil Flexible Plastic Packaging Market
Flexible Packaging
Egypt Flexible Packaging Market
Flexible Packaging
Converted Flexible Packaging Market
Flexible Packaging
France Flexible Plastic Packaging Market
Flexible Packaging
United Arab Emirates Flexible Plastic Packaging Market