
 Africa Flexible Packaging Market | 2026-2036
Africa Flexible Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Flexible Packaging Market Outlook
Food and beverage processing is consolidating as the dominant demand vertical across the continent. Huhtamaki Group leverages its regional manufacturing footprint to supply laminated pouches to pan-African dairy and snack brands. Constantia Afripack Flexibles anchors its position through backward integration into film extrusion, while Amcor Group competes on high-barrier pharmaceutical sachet specifications. PrimePak Industries Nigeria Ltd dominates the Lagos market through channel control of local distribution networks.
Flexible packaging comprises pliable substrates—polypropylene, polyethylene, BOPP, and paper—formed into bags, pouches, wraps, and labels through extrusion, lamination, or printing processes, designed to protect contents from moisture, oxygen, and mechanical damage during distribution and shelf life. Polyethylene leads material demand due to its cost position and heat-seal reliability across ambient and chilled supply chains. Pouches represent the fastest-growing product configuration, driven by portion-control trends in personal care and single-serve food formats in urban retail.
South Africa's Department of Forestry, Fisheries and Environment enforces extended producer responsibility frameworks that mandate post-consumer collection targets for plastic packaging. Kenya's National Environment Management Authority prohibits specific single-use plastic categories, redirecting converter investment toward paper-based and recyclable mono-material structures. Nigeria's Standards Organisation develops material migration limits for food-contact films. Stakeholders must monitor regulatory divergence between East and West African economic communities when configuring regional product portfolios.
Market Dynamics
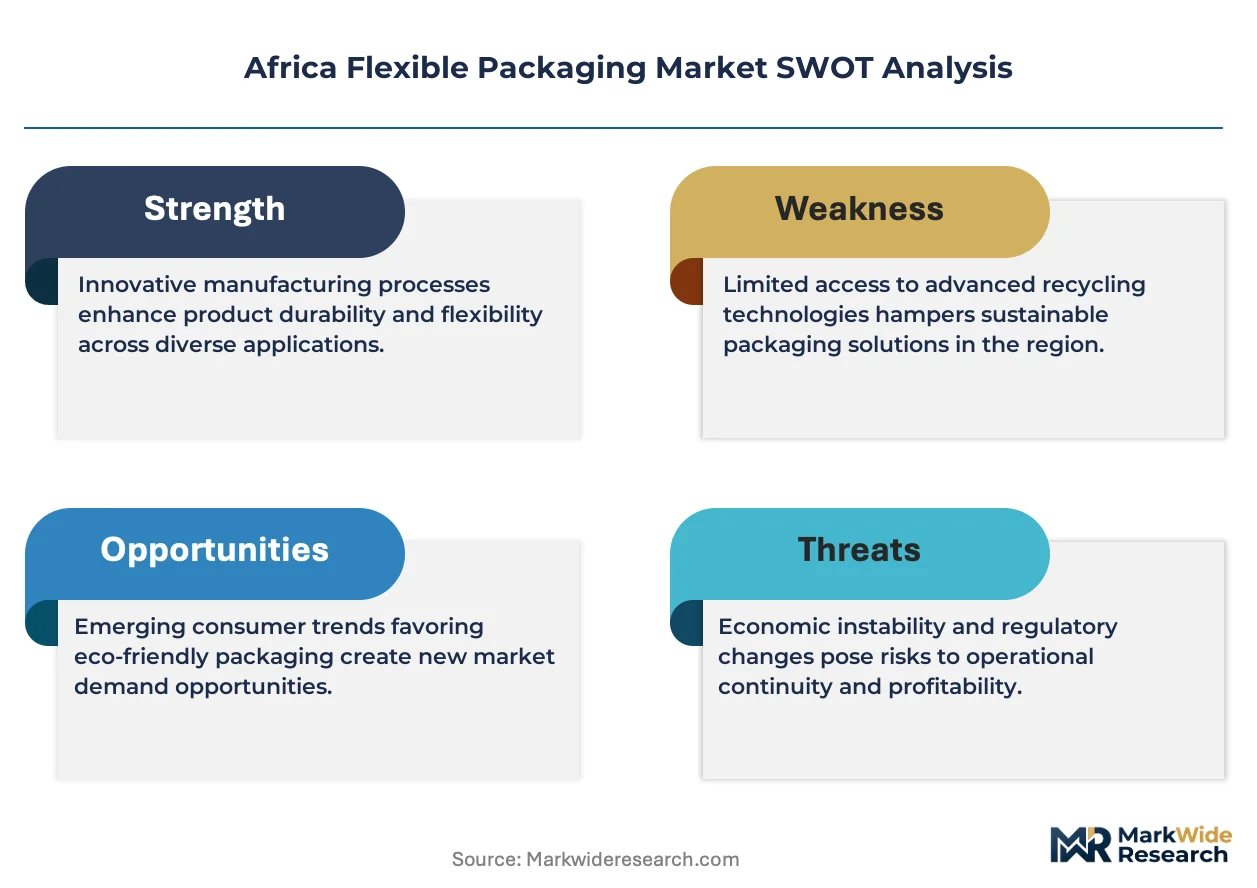
Extended producer responsibility frameworks across South Africa and Kenya are redirecting converter capital toward recyclable mono-material structures, compressing legacy multi-layer film specifications while opening substitution pathways for paper-based barriers.
Growth Catalysts
- Kenya's plastic waste management policies:Prohibitions on specific single-use plastic categories redirect investment toward paper-based and recyclable mono-material structures, creating demand for compliant barrier solutions.
- Food and beverage processing consolidation:Pan-African dairy and snack brands are standardizing packaging specifications around multi-layer barrier films to reduce spoilage rates across extended distribution networks.
- Lagos-Ibadan industrial corridor concentration:Fast-moving consumer goods manufacturers in this Nigerian cluster are upgrading packaging specifications, driving regional demand for high-performance flexible formats.
Market Restraints
- Polyethylene price volatility:Feedstock cost fluctuations for polyethylene resin compress converter margins and destabilize contract pricing across ambient and chilled supply chains.
- Film extrusion supply concentration:Backward-integrated regional players control captive resin supply, limiting independent converters' access to cost-competitive substrate sources.
- Multi-layer recycling technical limitation:Incompatibility of laminated pouch structures with existing mechanical recycling infrastructure blocks circular economy compliance pathways.
Strategic Opportunities
- Underpenetrated East African Community markets:Tanzania and Ethiopia present white space for mono-material pouch adoption as retail formalization accelerates in urban centers.
- Pharmaceutical sachet specifications:High-barrier requirements for unit-dose drug packaging create premium positioning opportunities distinct from commodity food applications.
- South Africa's EPR collection targets:Mandated post-consumer collection thresholds incentivize investment in closed-loop recycling infrastructure and design-for-recyclability services.
Industry Challenges
- Migration testing capability gaps:Nigeria's Standards Organisation food-contact compliance requirements exceed local analytical laboratory capacity, extending certification timelines.
- Legacy equipment retrofit costs:Converters face capital intensity in reconfiguring extrusion and lamination lines for mono-material production without co-extrusion capability loss.
- Regulatory divergence complexity:Divergent material migration limits between East and West African economic communities fragment regional product portfolio configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Flexible Packaging Market |
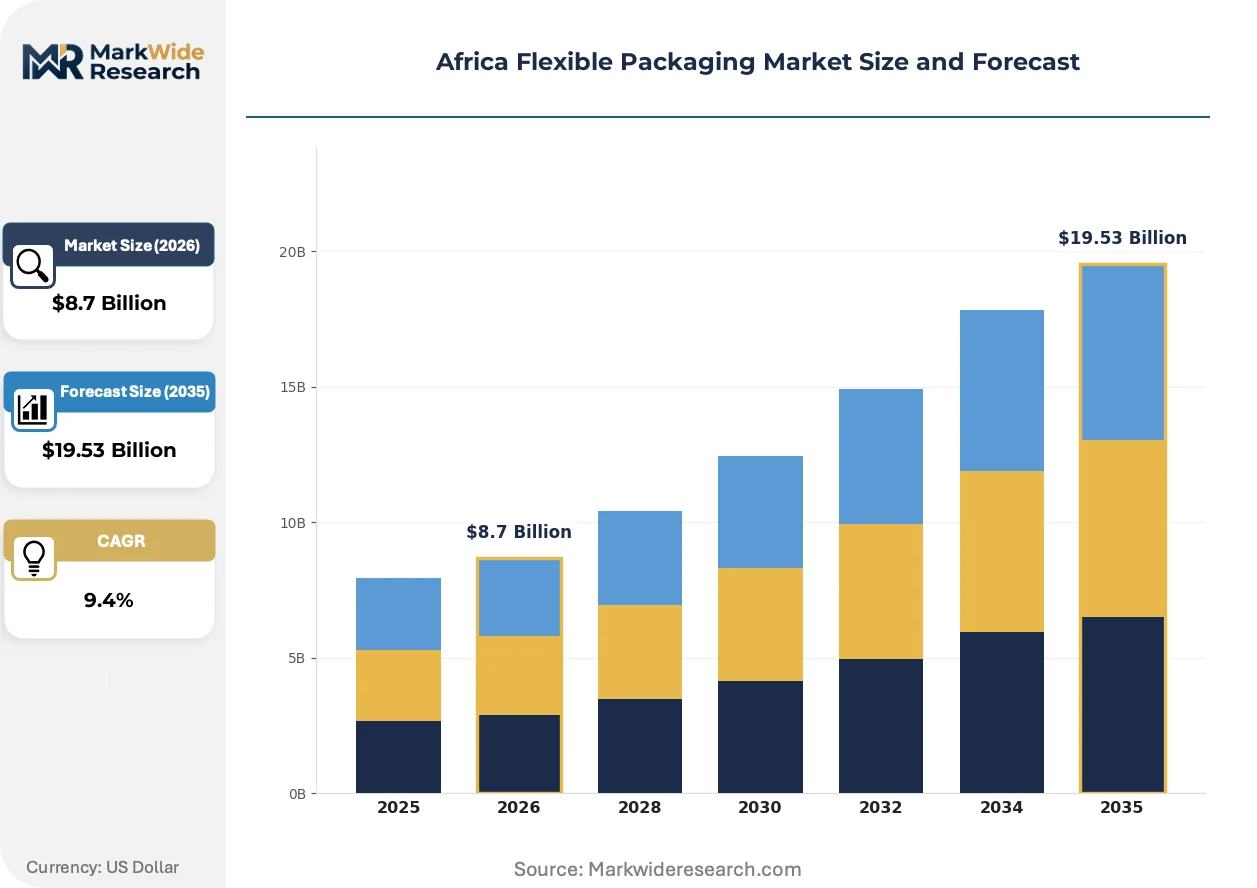
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Pouches, Wraps, Labels Material: Polypropylene, Polyethylene, BOPP, Paper End User: Food & Beverages, Personal Care, Pharmaceuticals, Chemicals Application: Retail, Industrial, Medical, Agriculture |
| Companies Covered | Hana Packaging Limited, PrimePak Industries Nigeria Ltd, Aristocrat Industries Ltd, Huhtamaki Group, CTP Flexibles Ltd, Sonnex Packaging Nigeria Ltd, Colpak Pty Ltd, Constantia Afripack Flexibles Ltd, Amcor Group, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Flexible Packaging Market Strategic Shifts
Digital printing and mono-material barrier development are compressing traditional converter value chains while enabling shorter-run customization for brand owners across fragmented African retail markets.
Water-based barrier coatings are decentralizing the flexible packaging value chain by eliminating solvent-based lamination steps and enabling regional toll-coating operations. Mid-size converters in Kenya and Nigeria are adopting these coatings to serve local snack brands with customized oxygen barrier specifications. This technology is decentralizing production geography away from South African film extrusion centers toward distributed coating and converting nodes.
South Africa's Department of Forestry, Fisheries and Environment enforces extended producer responsibility frameworks with escalating post-consumer collection targets for plastic packaging. Converters must now integrate collection infrastructure costs into product pricing or partner with waste management cooperatives. Food-contact film specifications face the tightest compliance scrutiny as brand owners demand documentation for EPR audit trails.
Urban retail formalization is compressing traditional open-market packaging procurement toward specification-driven tender processes. Pan-African fast-moving consumer goods manufacturers are consolidating supplier panels and demanding migration test documentation, technical service support, and inventory financing. Nigeria's Lagos-Ibadan corridor exhibits the most visible procurement transformation as modern trade penetration restructures distributor relationships.
Africa Flexible Packaging Market Segmentation
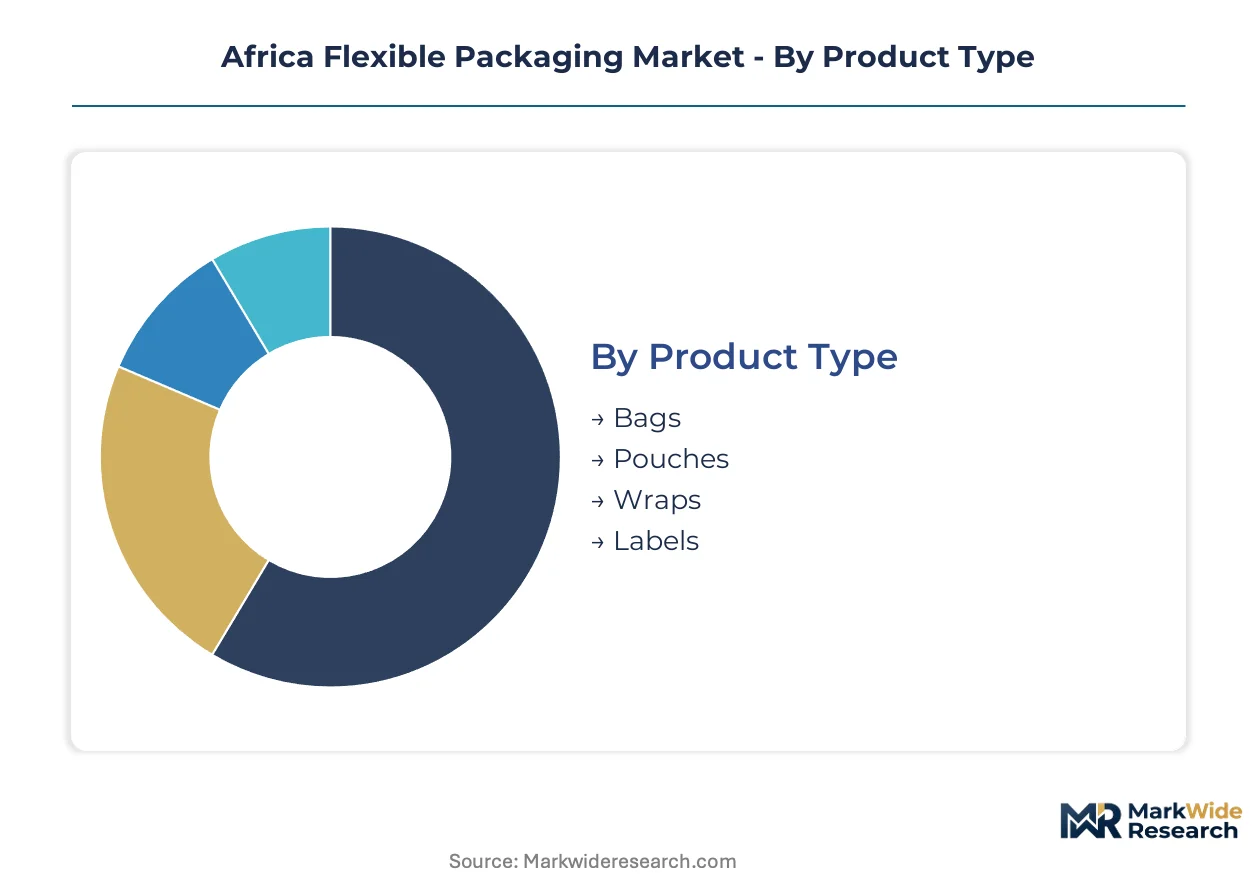
Flexible packaging configurations in Africa span commodity formats and specification-driven barrier systems. Converter investment priorities diverge sharply between high-volume food applications and compliance-intensive pharmaceutical segments. Procurement consolidation by pan-African brand owners is compressing supplier diversity within each segment cluster.
Product Type:
Customization intensity varies from standardized commodity bags to engineered multi-layer pouches with active barrier properties.
- Pouches:Multi-layer laminates with oxygen and moisture barriers dominate premium food and pharmaceutical applications. Lagos-Ibadan corridor fast-moving consumer goods manufacturers are standardizing pouch specifications to cut spoilage rates across extended distribution networks.
- Bags:Single-ply polyethylene and polypropylene formats serve bulk agricultural and industrial chemical containment. South African extended producer responsibility frameworks are redirecting bag production toward recyclable mono-material structures with post-consumer collection documentation.
- Wraps:Stretch and shrink films protect palletized goods through ambient supply chains. Kenyan plastic waste management prohibitions are accelerating paper-based wrap substitution in fresh produce export packaging.
- Labels:Pressure-sensitive and in-mold formats carry branding and regulatory information. Nigerian Standards Organisation migration testing requirements are extending certification timelines for food-contact label adhesives.
Most installed capacity flows through Bags. Expansion is steepest in Pouches.
Material:
Cost positioning separates commodity thermoplastics from specialty substrates with regulatory compliance premiums.
- Polyethylene:Linear low-density and high-density grades provide heat-seal reliability across ambient and chilled supply chains. Nigeria's Lagos-Ibadan industrial corridor concentrates polyethylene pouch demand as dairy processors upgrade packaging specifications.
- Polypropylene:Cast and oriented films deliver clarity and stiffness for snack and confectionery visibility packaging. Kenya's National Environment Management Authority prohibitions on specific single-use plastics are redirecting converter investment toward recyclable polypropylene mono-materials.
- BOPP:Biaxially oriented polypropylene offers moisture barrier and print surface for high-graphic labels and overwraps. South African film extrusion centers control captive BOPP supply, limiting independent converter access.
- Paper:Kraft and glassine substrates with water-based barrier coatings substitute for plastic in fresh produce and dry food segments. Kenyan and Nigerian mid-size converters are adopting decentralized toll-coating operations to serve local snack brands.
Polyethylene commands the largest installed extrusion base. Paper is climbing the fastest as EPR frameworks tighten.
End User:
Application maturity spans from fragmented agricultural supply chains to consolidated pharmaceutical procurement with audit documentation requirements.
- Food & Beverages:Dairy, snack, and beverage processors drive multi-layer barrier film consolidation across pan-African manufacturing footprints. Extended distribution networks in Nigeria and Kenya demand upgraded oxygen barrier specifications to reduce spoilage.
- Pharmaceuticals:Unit-dose sachets and strip packs require high-barrier specifications with migration test documentation. South Africa's Department of Forestry, Fisheries and Environment enforces tightest compliance scrutiny for food-contact film audit trails.
- Personal Care:Single-serve pouches for shampoo and lotion samples target urban retail formalization. Portion-control trends in Kenya's urban centers drive mono-material pouch adoption.
- Chemicals:Industrial bags and liners contain fertilizers, pesticides, and construction materials. Specifications prioritize mechanical strength over barrier performance in Nigeria's agricultural input distribution.
Food & Beverages absorbs the majority of converter output. Pharmaceuticals shows the steepest specification escalation.
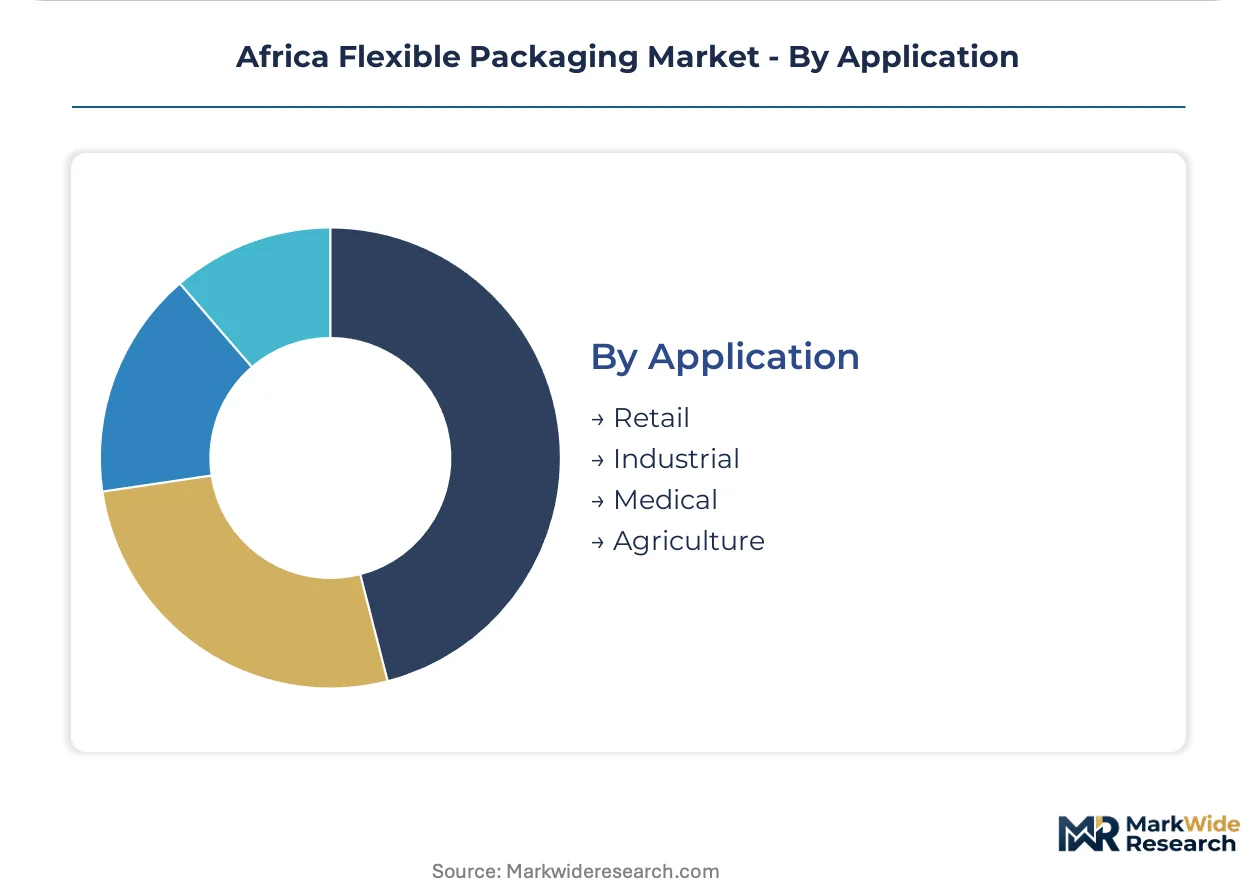
Application:
Channel structure ranges from informal open-market procurement to tender-driven modern trade with technical service requirements.
- Retail:Branded pouches and labels serve supermarkets and convenience stores in South Africa and Nigeria's formalizing urban trade. Pan-African fast-moving consumer goods manufacturers are consolidating supplier panels and demanding inventory financing.
- Industrial:Bulk bags and wraps protect intermediate goods through manufacturing and logistics chains. Kenya's plastic waste policies are accelerating paper-based substitution in agricultural export packaging.
- Medical:Sterile barrier systems and unit-dose pharmaceutical packaging require ISO-compliant manufacturing environments. South Africa's EPR collection targets incentivize closed-loop recycling infrastructure investment.
- Agriculture:Seed, fertilizer, and produce bags serve fragmented smallholder supply chains. Nigerian Standards Organisation material migration limits are beginning to structure previously informal procurement.
Retail channels command the deepest converter relationships. Medical applications are gaining share fastest on compliance premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lagos-Ibadan industrial corridor anchors continental flexible packaging demand as Nigerian fast-moving consumer goods manufacturers upgrade specifications to cut spoilage across extended distribution networks.
South Africa
Food-contact film specifications concentrate converter compliance investment as the Department of Forestry, Fisheries and Environment enforces escalating post-consumer collection targets. Johannesburg-Pretoria manufacturing belt houses backward-integrated extrusion capacity serving pan-African dairy brands.
Kenya
Urban retail formalization accelerates mono-material pouch adoption for portion-control personal care formats. National Environment Management Authority prohibitions on specific single-use plastic categories redirect capital toward paper-based barrier structures. Nairobi-Thika industrial zone hosts mid-size converters adopting water-based coating toll operations.
Nigeria
Dairy processors in the Lagos-Ibadan corridor drive polyethylene pouch specification upgrades to reduce ambient supply chain losses. Standards Organisation migration testing requirements for food-contact films exceed local laboratory capacity, extending certification timelines. Kano's agricultural input distribution maintains demand for mechanical-strength-focused industrial bags.
Egypt
Pharmaceutical unit-dose packaging specifications create premium positioning opportunities distinct from commodity food applications. The country's national pharmaceutical regulator tightens barrier documentation requirements for imported drug packaging materials. Cairo-Alexandria industrial corridor concentrates high-barrier laminate converting for regional pharmaceutical exporters.
Ethiopia
Retail formalization in Addis Ababa opens white space for mono-material pouch adoption as modern trade penetration restructures procurement. The country's standards authority develops draft food-contact compliance frameworks modeled on East African Community protocols. Eastern industrial zone clusters attract toll-coating investment serving emerging snack brand demand.
Africa Flexible Packaging Market Competitive Environment
Backward integration into film extrusion dominates the current landscape as regional players secure captive resin supply and compress independent converter margins. Market structure consolidates around three tiers: multinational groups with pan-African manufacturing footprints, mid-size national converters with channel control in specific industrial corridors, and distributed toll-coating specialists serving local snack brands. Two strategic archetypes define positioning: specification-driven barrier film suppliers competing on pharmaceutical and dairy compliance documentation, and cost-optimized commodity bag producers serving agricultural and industrial chemical containment. Capacity expansion and portfolio diversification toward recyclable mono-materials represent the dominant competitive moves as extended producer responsibility frameworks tighten across South Africa and Kenya.
Among Nigeria-based converters, PrimePak Industries Nigeria Ltd and Sonnex Packaging Nigeria Ltd occupy positions anchored in Lagos-Ibadan corridor distribution control, while South Africa's Constantia Afripack Flexibles Ltd exemplifies the backward-integrated archetype with captive film extrusion capacity serving pan-African brand procurement panels.
| Leading Market Players |
|---|
| Hana Packaging Limited |
| PrimePak Industries Nigeria Ltd |
| Aristocrat Industries Ltd |
| Huhtamaki Group |
| CTP Flexibles Ltd |
| Sonnex Packaging Nigeria Ltd |
| Colpak Pty Ltd |
| Constantia Afripack Flexibles Ltd |
| Amcor Group |
| Others |
Value Chain & Pricing Dynamics
Polyethylene resin spot indices in Rotterdam and Singapore anchor converter input cost structures across the Africa Flexible Packaging Market, cascading through three distinct pricing tiers that separate backward-integrated multinational supply from toll-dependent national converters and informal bag producers serving agricultural channels. South Africa's Department of Forestry, Fisheries and Environment collection mandates and Kenya's National Environment Management Authority prohibitions add compliance premiums that widen spreads between specification-grade and commodity-grade film procurement.
Pricing Analysis
Input-cost pass-through from resin indices operates through contract-based long-term offtake agreements for multinational converters, while independent operators face spot market volatility. Price differentiation rests on certification grade—ISO-compliant pharmaceutical barrier films command substantial premiums over standard food-contact specifications—and volume scale, with pan-African dairy brands leveraging procurement consolidation for preferential terms. Pricing pressure stems from polyethylene price volatility compressing margins at toll-coating specialists in Kenya and Nigeria. Agricultural bag buyers in Nigeria's Kano corridor exhibit highest price sensitivity; pharmaceutical exporters in Egypt's Cairo-Alexandria zone show least sensitivity due to barrier documentation requirements.
Supply Chain Analysis
Freight costs from South African film extrusion centers to Lagos-Ibadan and Nairobi-Thika corridors dictate regional converter competitiveness, with inland logistics consuming disproportionate share of delivered film costs. Geographic supply concentrates in South Africa, Kenya, and Nigeria, with Johannesburg-Pretoria housing captive BOPP and polyethylene extrusion, Nairobi-Thika hosting mid-size toll-coating operations, and Lagos-Ibadan anchoring pouch converting for dairy and snack brands. Raw material dependencies draw from Saudi and Qatari polyethylene resin, Malaysian BOPP film, and European specialty barrier coatings. Single-source vulnerability runs through South African backward-integrated players controlling resin supply to independent converters. Distribution runs through pan-African fast-moving consumer goods manufacturer supplier panels, modern trade procurement tenders, and fragmented agricultural input dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Africa Flexible Packaging Market represents a late-cycle quality story as extended producer responsibility frameworks and migration testing requirements redirect procurement toward specification-compliant suppliers capable of audit documentation. Pan-African dairy and pharmaceutical brands are consolidating supplier panels around barrier film specialists with certified manufacturing environments and technical service capabilities.
For Market Incumbents: Lock in backward integration advantages by expanding captive film extrusion capacity in South Africa's Johannesburg-Pretoria belt to serve pan-African pharmaceutical sachet demand. Deepen channel control through inventory financing partnerships with Lagos-Ibadan fast-moving consumer goods manufacturers facing spoilage pressure across extended distribution networks. The threat of water-based barrier coating decentralization from Kenyan and Nigerian toll-coating specialists demands preemptive certification investment in design-for-recyclability services. For New Entrants and Emerging Players: Distributor relationships with informal agricultural input networks in Nigeria's Kano corridor offer lowest barrier entry points for mechanical-strength-focused industrial bag production. Ethiopia's Addis Ababa retail formalization presents white space for mono-material pouch adoption serving emerging snack brands with customized oxygen barrier specifications. A toll-coating partnership model with Nairobi-Thika mid-size converters enables asset-light barrier film production without extrusion capital intensity. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-size national converters possessing channel control in underpenetrated East African Community markets and technical capability to pivot toward pharmaceutical barrier specifications. Long-term viability over the next decade hinges on regulatory compliance infrastructure and closed-loop recycling partnerships rather than commodity volume scale. The signal to watch is Kenya's National Environment Management Authority enforcement intensity against single-use plastic prohibitions, which would accelerate capital flight from multi-layer laminate producers toward mono-material specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | South Africa's EPR collection targets reward converters with captive resin supply and closed-loop recycling infrastructure. |
| Design-for-Recyclability Services | Kenya's plastic waste prohibitions create premium positioning for converters offering mono-material barrier documentation. |
| Pharmaceutical Barrier Certification | Egypt's national pharmaceutical regulator tightens documentation requirements for unit-dose sachet exporters. |
| Toll-Coating Partnership Expansion | Water-based barrier coatings enable decentralized production serving Nigerian and Kenyan snack brands without extrusion assets. |
| Channel Control in Lagos-Ibadan Corridor | Fast-moving consumer goods manufacturers demand inventory financing and technical service support beyond commodity supply. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with converter operations managers, procurement leads at pan-African dairy and snack brands, regulatory affairs officers at South Africa's Department of Forestry, Fisheries and Environment, and distribution channel partners in Nigeria's Lagos-Ibadan corridor with secondary validation. Secondary sources included customs and trade data on polyethylene and BOPP film imports, SEC filings from multinational packaging groups, East African Community and ECOWAS regulatory gazettes, and industry association reports from Flexible Packaging Europe and Packaging SA. Bottom-up capacity estimates from identified converter facilities were triangulated against top-down demand calculations from end-use consumption patterns.
Segment-weighting across product type, material, end user, and application dimensions shaped the analytical framework, with pouch, bag, wrap, and label configurations each assigned demand coefficients derived from procurement panel consolidation trends. Geographic clustering captured South Africa, Kenya, Nigeria, Egypt, and Ethiopia as distinct regulatory and demand environments. CAGRs were derived from installed capacity expansion announcements, EPR implementation timelines, and retail formalization indices. Industry-specific forecast inputs included polyethylene resin price trajectory assumptions and pharmaceutical barrier specification escalation rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Kenya's National Environment Management Authority enforcement intensity, Nigeria's Standards Organisation laboratory capacity expansion, and South Africa's EPR collection target revisions. Forecasts reflect documented assumptions on resin cost pass-through elasticity and regulatory compliance timeline adherence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Indonesia Flexible Packaging Market
Flexible Packaging
ASEAN Flexible Packaging Market
Flexible Packaging
Vietnam Flexible Plastic Packaging Market
Flexible Packaging
Metalized Flexible Packaging Market
Flexible Packaging
Indonesia Flexible Plastic Packaging Market
Flexible Packaging
Flexible Food Packaging Market
Flexible Packaging
Asia-Pacific Flexible Plastic Packaging Market
Flexible Packaging
Canada Multilayer Flexible Packaging Market
Flexible Packaging
Flexible Packaging Paper Market
Flexible Packaging
India Flexible Plastic Packaging Market
Flexible Packaging
Latin America Flexible Packaging Market
Flexible Packaging
Europe Flexible Packaging Market
Flexible Packaging
Industrial Flexible Packaging Market
Flexible Packaging
Global Breathable Films Market
Flexible Packaging
Middle East and Africa Flexible Plastic Packaging Market
Flexible Packaging
Flexible Intermediate Bulk Container Market