
 Global Flexible Plastic Packaging Market | 2026-2036
Global Flexible Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flexible Plastic Packaging Market Analysis
Polymer engineering talent is rotating toward barrier coating and sealant chemistry specializations, tightening recruitment pipelines for conventional extrusion operators. Amcor leverages its global film manufacturing footprint to sustain supply agreements with multinational food brands. Mondi competes through integrated kraft paper and plastic hybrid solutions that reduce overall material weight.
Flexible plastic packaging denotes pliable polymer-based enclosures manufactured through blown film extrusion, cast film processes, or lamination, typically achieving thicknesses below 250 micrometers to provide moisture, oxygen, and light barrier protection for consumable and industrial goods. The primary purpose centers on extending product shelf life while minimizing material usage and transportation cost relative to rigid alternatives. Pouches and stand-up formats are capturing margin pools in premium food and personal care segments where consumer convenience commands price premiums. PE and PP material grades dominate volume production due to cost efficiency and established recycling infrastructure, though mono-material films are displacing multi-layer laminates in sustainability-sensitive applications.
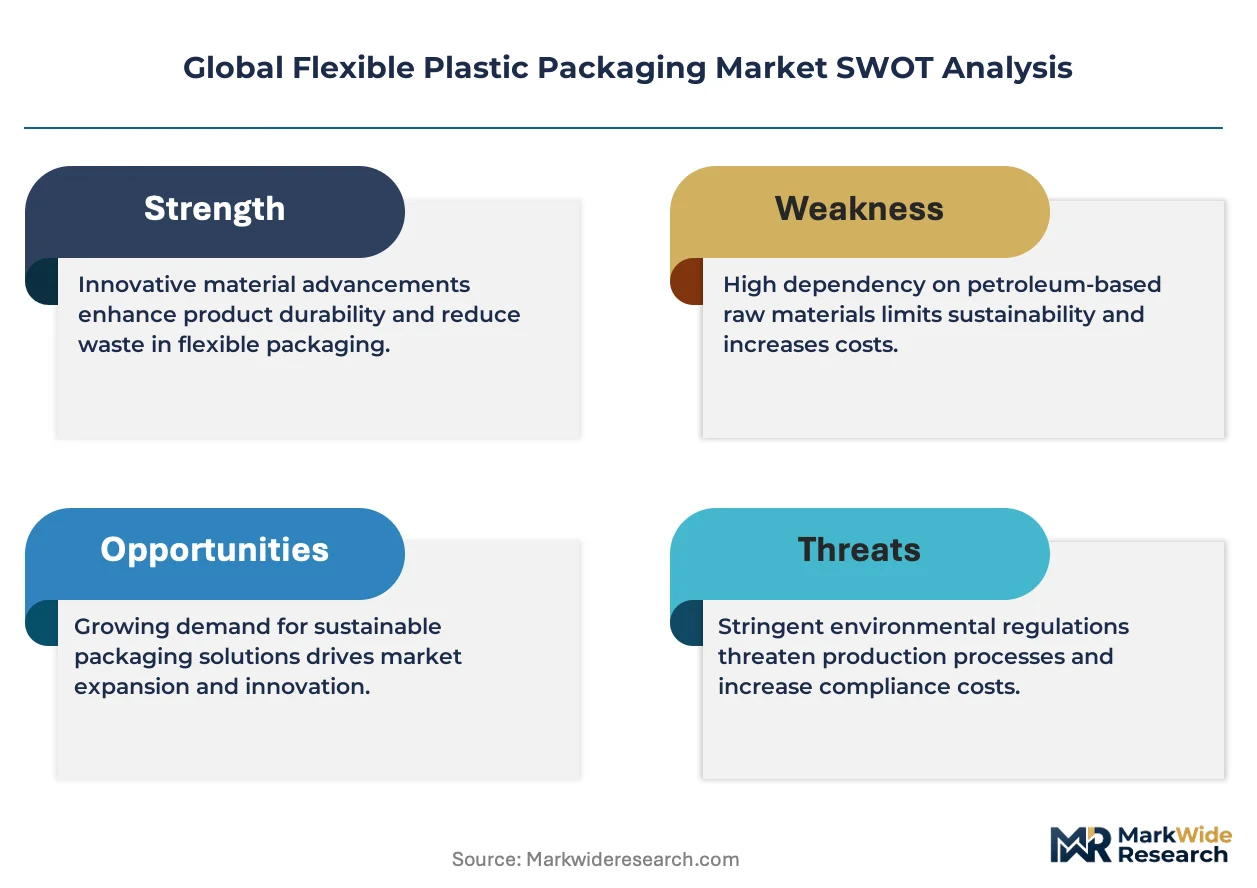
FDA food contact regulations in the United States, EU REACH and F-Gas frameworks in Europe, and India's BIS packaging standards collectively govern migration limits, chemical composition, and recyclability claims that determine market access and product liability exposure. ECHA substance restrictions are forcing reformulation of certain adhesive and ink chemistries used in laminated structures. Stakeholders must monitor evolving extended producer responsibility schemes and chemical inventory updates that will determine which material platforms qualify for circular economy labeling.
Market Dynamics
EU REACH substance restrictions and ECHA chemical inventory updates are forcing rapid reformulation of adhesive and sealant chemistries, compressing product development cycles for laminated film structures across all major supply bases.
Growth Catalysts
- EU Green Deal packaging mandates:Extended producer responsibility schemes in France and Germany accelerate mono-polymer film adoption for circular economy labeling eligibility.
- Barrier coating chemistry advances:Solvent-free and water-based coating technologies enable thinner film gauges while maintaining oxygen and moisture protection for shelf-stable foods.
- India organized retail expansion:FMCG brands scaling packaged food penetration in tier-2 and tier-3 cities drive pouch and stand-up bag volume requirements.
Market Restraints
- Ethylene and propylene feedstock volatility:Crude oil price swings transmit directly to PE and PP resin costs, compressing converter margins and destabilizing annual contract negotiations.
- Multi-layer laminate technical lock-in:Existing high-speed filling lines calibrated for specific film structures create switching costs that slow mono-material transitions.
- Mechanical recycling infrastructure gaps:Collection and sorting systems in the United States and India lack capacity to process flexible film at scale, limiting closed-loop claims.
Strategic Opportunities
- India BIS standards compliance:Early alignment with evolving national packaging standards creates first-mover positioning for export-ready converters serving multinational food brands.
- Paper-plastic hybrid formats:Integration of kraft paper layers with polymer barriers captures sustainability-sensitive premium segments in personal care and specialty foods.
- Chemical recycling partnerships:Pyrolysis and depolymerization of contaminated flexible films opens feedstock pathways currently excluded from mechanical streams.
Industry Challenges
- Barrier coating talent scarcity:Polymer engineering expertise is rotating toward sealant and coating specializations, creating recruitment bottlenecks for conventional blown film extrusion operations.
- FDA food contact notification timelines:New substance approvals for adhesive and ink chemistries extend 18-24 months, delaying product launches for reformulated structures.
- Legacy lamination asset utilization:Capital-intensive solvent-based laminators face stranded cost risk as brand owners specify aqueous and solvent-free alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flexible Plastic Packaging Market |
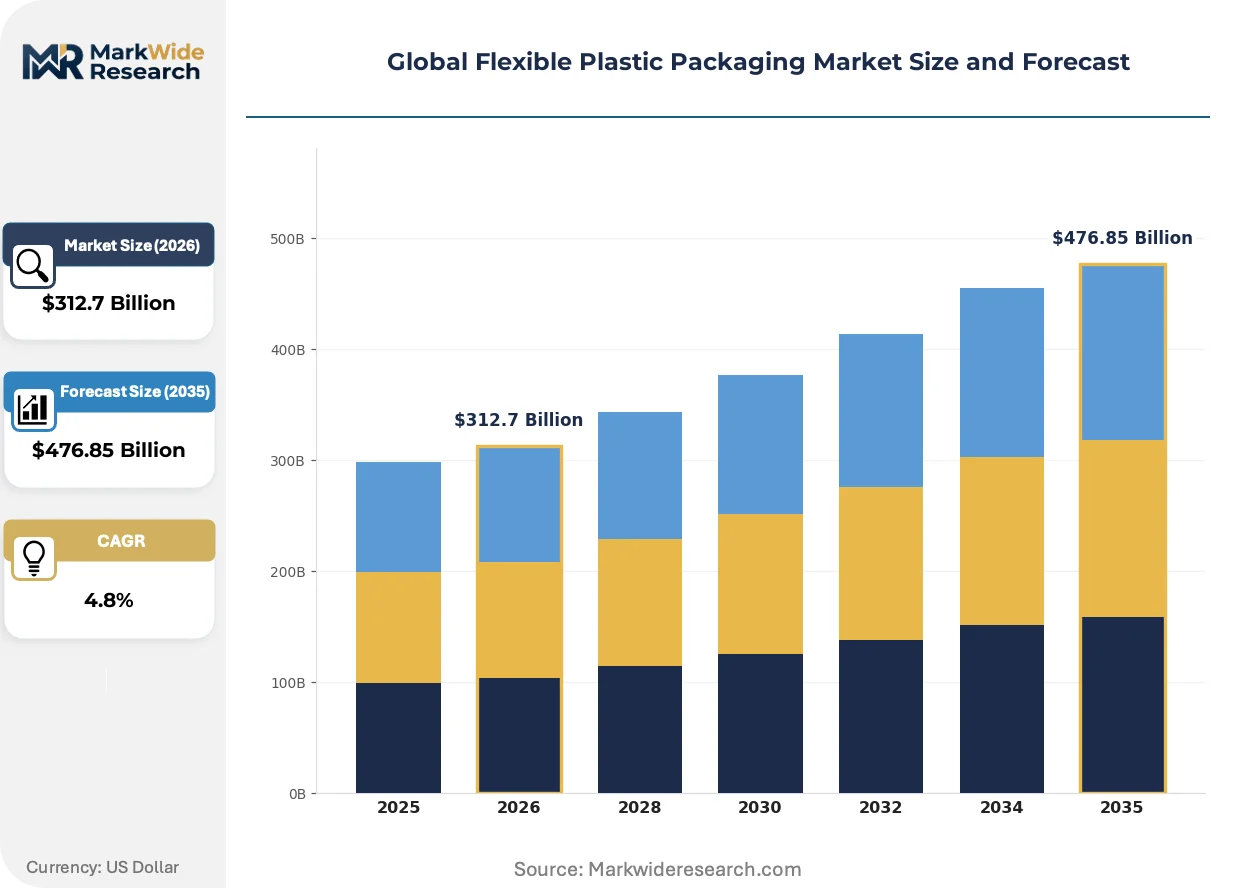
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $476.85 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Pouches, Films, Wraps End Use Industry: Food & Beverage, Healthcare, Personal Care, Household Material: PE, PET, PVC, PP Packaging Type: Stand-Up Pouches, Roll Stock, Sachets, Gusseted Bags |
| Companies Covered | Berry Global, Amcor, Mondi, Sealed Air, Constantia Flexibles, Huhtamaki, Sonoco Products Company, ProAmpac, DS Smith, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flexible Plastic Packaging Market Emerging Trajectories
Material science breakthroughs and regulatory chemistry restrictions are converging to restructure flexible packaging from multi-layer laminates toward recyclable mono-polymer and fiber-based alternatives.
Mono-material polyethylene films with enhanced ethylene vinyl alcohol coextrusion layers are decomposing the technical barrier performance of conventional PET/PE/foil laminates. Snack food and frozen vegetable processors in Germany and the Netherlands are qualifying these structures for 12-18 month shelf life requirements. The shift is compressing demand for aluminum foil interlayers and specialized adhesive systems while expanding investment in EVOH resin capacity and compatible sealant formulations.
ECHA restrictions on per- and polyfluoroalkyl substances are eliminating fluorinated barrier coatings from food contact applications in the European Union. Converters must reformulate grease-resistant papers and high-barrier films using silicon dioxide or clay-based alternatives before 2025 enforcement deadlines. Premium chocolate and confectionery brands with pan-European distribution face the most acute reformulation pressure, with several accelerating supplier qualification programs for PFAS-free structures.
Brand owner sustainability scorecards are consolidating supplier relationships around converters with verified recycling pathway documentation. Multinational food and personal care companies in the United States and United Kingdom are reducing approved vendor lists from 15-20 film suppliers to 3-5 strategic partners with integrated resin-to-recycling traceability. This concentration rewards scale players with in-house recycling partnerships and penalizes regional converters lacking verified end-of-life solutions.
Global Flexible Plastic Packaging Market Segmentation
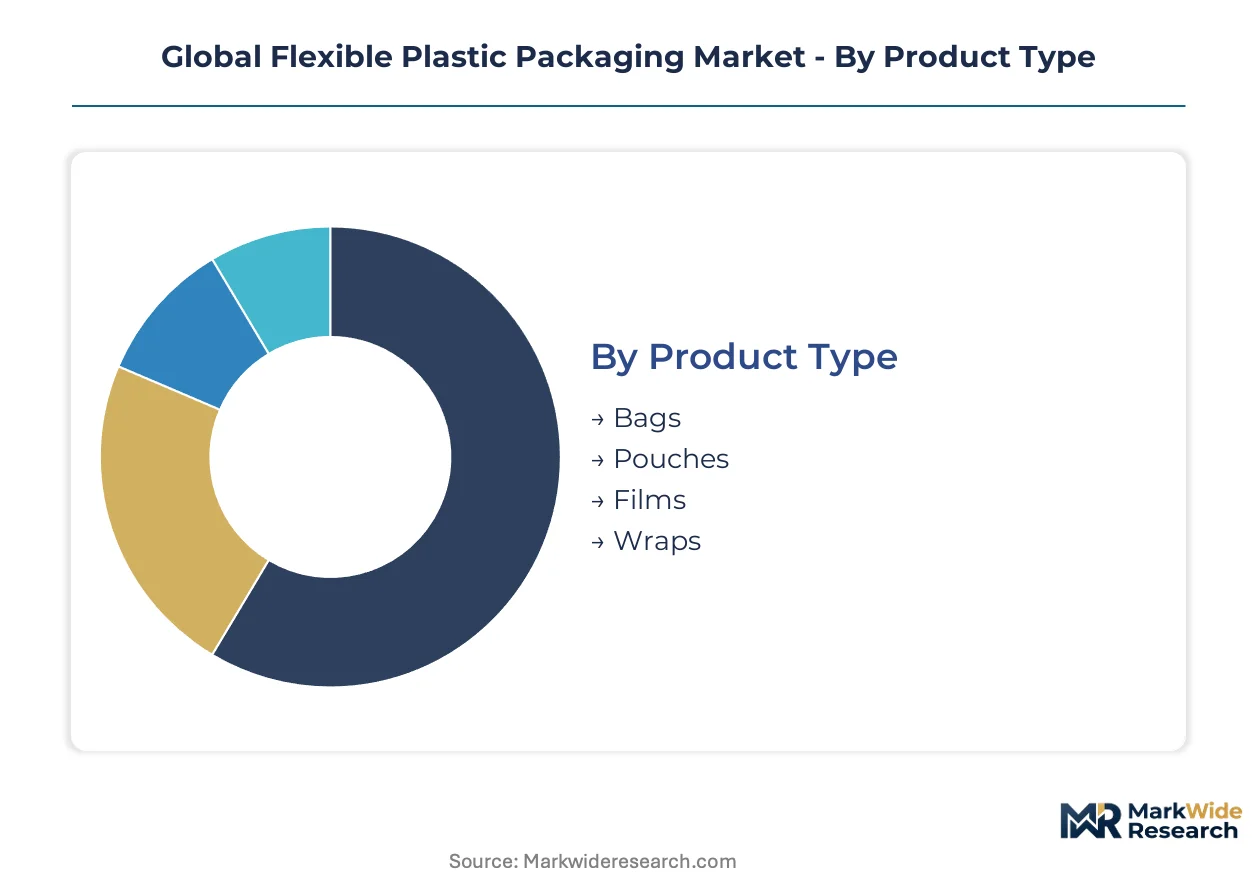
Segmentation in flexible plastic packaging reveals distinct margin architectures across product formats and material platforms. Converter profitability varies sharply by barrier complexity and end-use certification requirements.
Product Type:
Pouches command premium pricing in convenience-driven food applications while films dominate volume throughput in commodity segments.
- Pouches:Stand-up and flat formats incorporate zipper closures and spout fitments for ready-to-eat meals and beverages. German snack brands and Dutch frozen vegetable processors are qualifying mono-material polyethylene pouches for extended shelf life requirements.
- Films:Cast and blown extrusions serve as primary substrates for lamination, achieving gauges below 250 micrometers for barrier performance. Indian FMCG expansion into tier-2 and tier-3 cities is driving roll stock volume for form-fill-seal operations.
- Bags:Wicketed and wicketless configurations target high-speed bakery and produce packing lines with cost-optimized polyethylene structures.
- Wraps:Stretch and shrink formats secure palletized loads and unitize multi-pack consumer goods with linear low-density polyethylene formulations.
Films hold installed capacity. Pouches are rotating up the share rankings.
End Use Industry:
Application-specific barrier requirements create tiered margin pools with food contact compliance commanding the steepest certification premiums.
- Food & Beverage:Oxygen and moisture barriers extend shelf life for shelf-stable goods, snack foods, and frozen vegetables. EU Green Deal mandates are accelerating mono-polymer transitions in French and German retail channels.
- Healthcare:Sterile barrier systems for medical devices and pharmaceutical products require validated seal integrity and migration-tested chemistries. FDA food contact notification timelines extend development cycles for adhesive formulations.
- Personal Care:Premium positioning in cosmetics and toiletries drives stand-up pouch adoption with high-definition printing and tactile finishes.
- Household:Detergent and cleaning product formats emphasize chemical resistance and child-resistant closures in concentrated formula packaging.
Food & Beverage captures volume concentration. Healthcare is climbing the fastest on compliance-driven pricing.
Material:
Resin selection determines recycling pathway eligibility and feedstock cost exposure across converter operations.
- PE:Linear low-density and high-density grades dominate flexible film production with established mechanical recycling infrastructure. EVOH coextrusion layers are decomposing technical barriers previously requiring aluminum foil laminates.
- PP:Cast and oriented polypropylene films deliver clarity and stiffness for snack food and confectionery applications. Biaxial orientation lines in India are scaling capacity for export-ready converters.
- PET:Metallized and clear polyester films provide oxygen barriers and print surface quality in laminated structures.
- PVC:Shrink sleeve and blister applications persist in specific pharmaceutical and household segments despite regulatory pressure on plasticizer chemistries.
PE holds installed capacity. PP is rotating up the share rankings.
Packaging Type:
Format innovation concentrates in convenience-driven configurations that reduce material weight while preserving shelf presence.
- Stand-Up Pouches:Gusseted bottom structures with resealable fitments capture premium positioning in pet food, baby nutrition, and adult beverages. Brand owner sustainability scorecards are consolidating supplier relationships around converters with verified recycling documentation.
- Roll Stock:Unformed film supplied to form-fill-seal operations minimizes transport cube and inventory carrying costs for high-volume food manufacturers.
- Sachets:Single-serve portions for condiments, cosmetics, and pharmaceuticals optimize sample distribution and unit economics in emerging markets.
- Gusseted Bags:Side and bottom gusset configurations expand volumetric capacity for coffee, dried goods, and industrial components.
Roll Stock holds installed capacity. Stand-Up Pouches are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major economies, with European buyers prioritizing circular-economy-compliant mono-materials while Indian and Chinese markets emphasize cost-efficient volume throughput for rapidly modernizing retail sectors.
United States
Snack food processors and pet food brands drive pouch format demand, with California and Illinois hosting dense converter clusters. FDA food contact notification requirements extend 18-24 months for new adhesive chemistries, compressing product launch timelines. The Midwest manufacturing belt around Chicago anchors blown film capacity serving national CPG distribution networks.
Germany
Retail chains and frozen vegetable processors qualify mono-polyethylene structures for extended shelf life applications. EU REACH substance restrictions and ECHA chemical inventory updates force rapid reformulation of laminated film adhesives. The Rhine-Ruhr industrial corridor concentrates extrusion and lamination capacity serving pan-European brand owners.
India
FMCG expansion into tier-2 and tier-3 cities escalates roll stock demand for form-fill-seal operations. BIS packaging standards compliance creates qualification barriers for export-ready converters. Gujarat and Maharashtra host integrated film manufacturing clusters supplying domestic and Southeast Asian markets.
China
E-commerce fulfillment and fresh food delivery platforms absorb high volumes of lightweight barrier pouches. GB standards and MIIT circular economy directives accelerate mono-material transitions in coastal provinces. The Yangtze River Delta around Shanghai anchors the world's largest flexible film production base.
Netherlands
Pan-European distribution hubs and sustainable packaging innovation centers concentrate demand for recyclable structures. EU Green Deal extended producer responsibility schemes in neighboring France and Germany create cross-border compliance spillover. The Rotterdam-Antwerp corridor hosts specialized barrier coating operations serving premium food exporters.
Global Flexible Plastic Packaging Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale advantages concentrated in resin backward integration and global film manufacturing footprints. The competitive terrain separates into three archetypes: multinational converters with captive recycling partnerships, regional specialists with hybrid paper-plastic capabilities, and commodity film suppliers competing on throughput. Dominant competitive moves include strategic consolidation to secure EVOH resin supply and partnerships with pyrolysis operators to establish chemical recycling pathways.
Within the integrated multinational tier, Amcor and Mondi exemplify divergent strategic positions—Amcor leveraging global extrusion capacity for multinational brand supply agreements, while Mondi anchors paper-plastic hybrid solutions that reduce material weight for sustainability-sensitive segments. Berry Global occupies a position among North American scale players with diversified resin processing capabilities across PE, PP, and specialty barrier grades. These three represent the competitive spectrum from pure-play polymer integration to fiber-based material science.
| Leading Market Players |
|---|
| Berry Global |
| Amcor |
| Mondi |
| Sealed Air |
| Constantia Flexibles |
| Huhtamaki |
| Sonoco Products Company |
| ProAmpac |
| DS Smith |
| Others |
Supply Flow & Price Mechanics
Mono-material polyethylene films displacing multi-layer aluminum foil laminates are redrawing supply geography toward EVOH resin producers in Germany and the United States while collapsing premium pricing tiers previously sustained by specialized adhesive systems and metallized barrier layers. This substitution dynamic concentrates procurement power among converters with backward integration into sealant chemistry, forcing commodity film suppliers into volume-based contract structures with compressed margin pools.
Pricing Analysis
Long-term offtake agreements dominate converter-brand owner relationships, with annual volume commitments locking in resin costs against ethylene and propylene feedstock volatility. Price differentiation rests on barrier certification tier and geographic delivery cost, with FDA food contact notification tiers commanding premiums over standard industrial grades. Cost compression in commodity roll stock intensifies because Indian FMCG expansion absorbs capacity at thin margins. Small regional converters exhibit highest price sensitivity, while multinational food brands with sustainability scorecards prioritize verified recycling documentation over unit cost.
Supply Chain Analysis
Strategic stockpile preferences vary by converter scale, with integrated multinationals maintaining EVOH resin safety stocks against supply interruption while regional specialists run lean just-in-time polyethylene inventories. Supply concentrates in China, Germany, and India, with blown film extrusion capacity anchored in the Yangtze River Delta and the Rhine-Ruhr corridor. The chain draws from ethylene feedstock, EVOH barrier resins, and solvent-free adhesive systems. Single-source vulnerability sits with specialized sealant chemistry suppliers qualified under EU REACH frameworks. Distribution runs through converter-direct relationships with multinational CPG brand owners, bypassing traditional distributor networks for high-volume pouch and roll stock contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as EU Green Deal mandates and India's organized retail penetration create dual tailwinds for mono-material and convenience-format adoption. The convergence of regulatory chemistry restrictions and brand owner sustainability scorecards is accelerating supplier consolidation around scale players with verified circular economy pathways.
For Market Incumbents: Consolidate barrier coating chemistry capabilities through captive R&D investment or targeted acquisition of sealant formulation specialists, as polymer engineering talent scarcity threatens conventional extrusion operations. Deepen backward integration into EVOH resin supply to defend margin position against feedstock volatility and secure qualification pipelines for multinational food brand contracts. Prioritize certification investment for FDA food contact notification tiers to sustain premium pricing power in healthcare and shelf-stable food segments.
For New Entrants and Emerging Players: Differentiate on paper-plastic hybrid formats targeting sustainability-sensitive premium segments in personal care and specialty foods, where kraft paper integration commands price premiums unavailable in commodity polyethylene films. Target India's tier-2 and tier-3 cities for form-fill-seal roll stock supply, as BIS standards compliance creates qualification barriers that favor early-mover positioning. Pursue chemical recycling partnerships as the primary go-to-market angle, offering converters closed-loop documentation unavailable from mechanical recycling infrastructure.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated converters with captive recycling partnerships and global film manufacturing footprints. Long-term viability over the next decade rests on securing EVOH resin supply and pyrolysis feedstock agreements as mechanical recycling infrastructure gaps persist. Acquisition target archetype: regional specialists with hybrid paper-plastic capabilities and established multinational brand relationships. The signal to watch is ECHA chemical inventory updates forcing adhesive reformulation, which will accelerate stranded cost risk for solvent-based laminators and create distressed asset opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EVOH Resin | Secures barrier chemistry supply against ECHA restriction-driven reformulation cycles. |
| Pyrolysis Partnership Formation | Opens chemical recycling pathways for contaminated films excluded from mechanical streams. |
| FDA Food Contact Notification Investment | Accelerates adhesive chemistry approval timelines for healthcare and shelf-stable applications. |
| India BIS Standards Early Alignment | Captures first-mover positioning for export-ready converters serving multinational FMCG brands. |
| Paper-Plastic Hybrid Format Development | Reduces material weight for EU Green Deal compliance while preserving premium shelf presence. |
Methodological Framework
Initial hypotheses were tested against primary input from blown film extrusion plant managers, procurement leads at multinational food brands, barrier coating R&D directors, and sustainability officers at personal care companies, and refined through secondary validation against customs and trade data, SEC filings from integrated packaging converters, ECHA substance restriction updates, and BIS packaging standard drafts. Bottom-up capacity and demand modeling triangulated with top-down macroeconomic drivers across the analysis window.
Variance decomposition across product format, material platform, end-use industry, and regional regulatory cluster shaped the analytical framework, with CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs included ethylene and propylene feedstock price trajectories, EU extended producer responsibility scheme adoption timelines, and Indian organized retail penetration rates by city tier.
The analysis sits within stated boundaries; outcomes outside sustained crude oil price stability, ECHA enforcement consistency, or India BIS implementation pace would require recalibration. Forecasts reflect assumptions on resin cost transmission, regulatory chemistry restriction timelines, and mechanical recycling infrastructure development. Revision becomes warranted when mono-material qualification timelines at multinational brand owners cross acceleration thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Mexico Flexible Packaging Market
Flexible Packaging
Nigeria Flexible Packaging Market
Flexible Packaging
Nigeria Flexible Plastic Packaging Market
Flexible Packaging
Flexible Bottle Market
Flexible Packaging
Thailand Flexible Packaging Market
Flexible Packaging
Spain Flexible Plastic Packaging Market
Flexible Packaging
Egypt Flexible Packaging Market
Flexible Packaging
Litho Laminated Packaging Market
Flexible Packaging
United States Flexible Plastic Packaging Market
Flexible Packaging
Confectionery Flexible Packaging Market
Flexible Packaging
Flexible Lid Stock Packaging Market
Flexible Packaging
Converted Flexible Packaging Market
Flexible Packaging
Latin America Flexible Plastic Packaging Market
Flexible Packaging
China Flexible Plastic Packaging Market
Flexible Packaging
Saudi Arabia Flexible Packaging Market
Flexible Packaging
Africa Flexible Packaging Market