
 Thermoforming Packaging Market | 2026-2036
Thermoforming Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoforming Packaging Market Outlook
REACH compliance is consolidating the cost-of-entry calculus for European thermoforming suppliers, forcing reformulation investments that favor scaled producers. Amcor Plc leverages its global resin sourcing network to sustain margin stability across regulatory jurisdictions. Berry Global Inc. anchors its position through captive PET recycling capacity that reduces virgin material exposure. Sealed Air Corporation differentiates via barrier technology leadership in modified-atmosphere food trays.
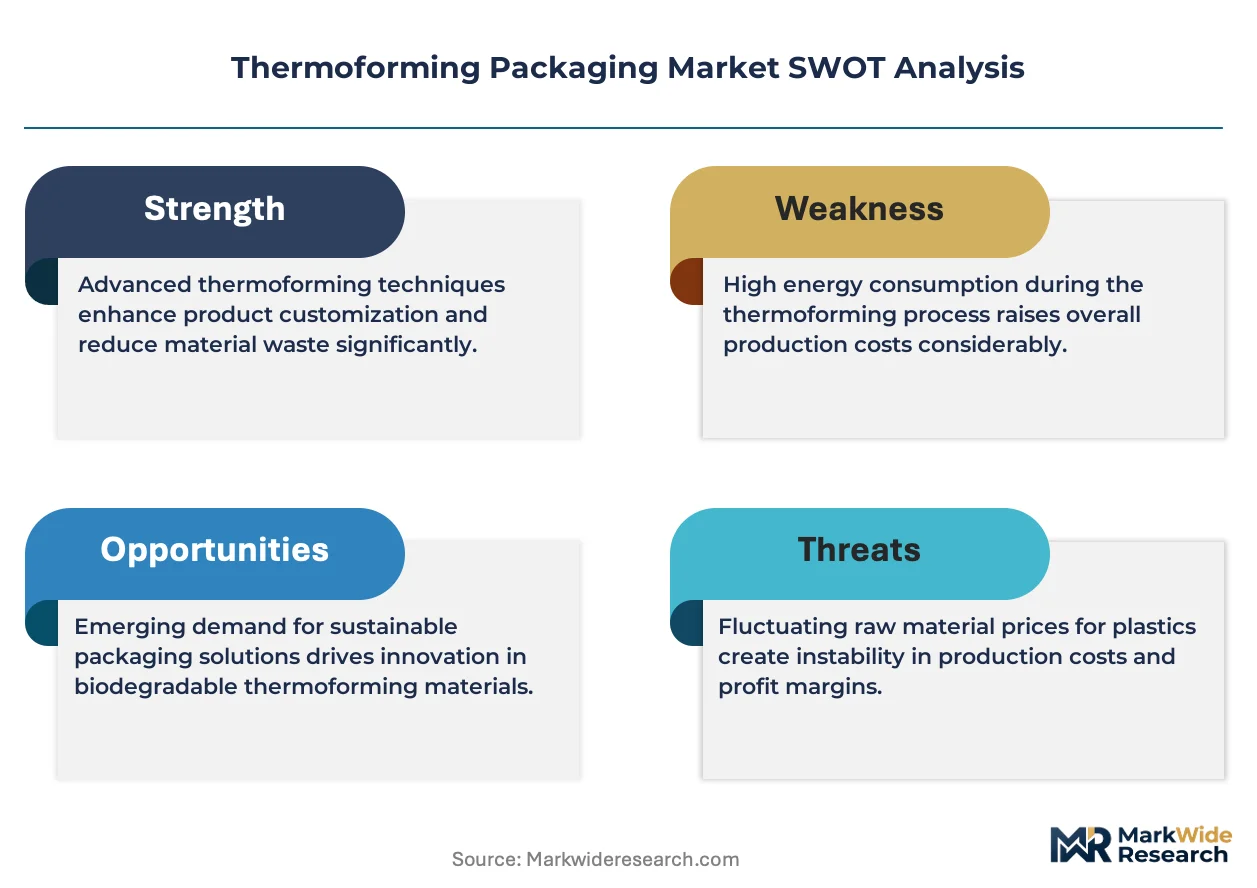
Thermoforming packaging refers to rigid or semi-rigid containers produced by heating thermoplastic sheets until pliable, then vacuum-forming or pressure-forming them over molds with typical gauge ranges from 0.005 to 0.060 inches for thin-gauge disposables and up to 0.500 inches for heavy-gauge industrial dunnage. The process yields hermetic seals, custom cavity geometries, and optical clarity suited to retail display, medical sterilization, and automated filling lines. Blister packs dominate pharmaceutical compliance packaging where unit-dose accountability and child-resistance standards command premium pricing. PET material grades are displacing PVC in food trays as brand owners respond to retailer sustainability scorecards and recycling stream compatibility requirements. Healthcare packaging applications sustain above-average margins due to FDA validation protocols and ISO 11607 sterilization barrier testing that limit supplier switching.
The FDA enforces 21 CFR Part 177 indirect food additive regulations that govern monomer migration limits in thermoformed food contact articles, while the EPA tracks fluorinated grease-resistant chemistries under emerging PFAS restrictions. EFSA maintains parallel migration thresholds that constrain multi-layer coextrusion designs for EU-exported dairy and meat trays. Stakeholders must monitor evolving state-level extended producer responsibility laws in California and Washington that will reshape post-consumer collection economics and resin credit valuations.
Market Dynamics
EU Green Deal packaging waste directives are forcing substrate transitions across the thermoforming value chain, compelling processors to abandon multi-material laminates in favor of mono-polymer designs compatible with existing recycling infrastructure.
Growth Catalysts
- Extended Producer Responsibility mandates:Germany's Verpackungsgesetz amendments tighten recycled content quotas for food-contact thermoforms, creating pull-through demand for rPET sheet.
- Modified-atmosphere food retail:European supermarket chains specify high-barrier thermoformed trays for protein categories, replacing expanded polystyrene with vacuum-formed PET/EVOH structures.
- Pharmaceutical serialization:EU Falsified Medicines Directive enforcement drives unit-dose blister adoption, with thermoformed PVC/PVDC formats dominating compliance packaging for oral solids.
Market Restraints
- rPET flake supply concentration:European bottle-to-sheet recycling capacity clusters in Germany and France, creating feedstock bottlenecks for southern European thermoformers.
- PFAS grease-resistant chemistry phase-out:EPA scrutiny under TSCA Section 6 eliminates fluorinated additives for microwaveable trays, forcing reformulation toward mineral-filled PP alternatives with inferior barrier performance.
- Aluminum substitution in premium segments:Retortable aluminum trays retain share in ready-meal categories where thermoformed PP/EVOH structures fail 121°C sterilization cycles.
Strategic Opportunities
- Healthcare sterilization barriers:ISO 11607-compliant thermoformed Tyvek-lidded trays for Class II medical devices remain underpenetrated in Eastern European contract manufacturing.
- Chemical recycling feedstock partnerships:Pyrolysis-based monomer regeneration enables food-grade rPET from mixed-color flake, bypassing mechanical recycling limitations for thermoform-specific sheet grades.
- Direct-to-film digital printing:UV-inkjet decoration of thermoformed containers eliminates pressure-sensitive label substrates, aligning with EU single-use plastics directive reduction targets.
Industry Challenges
- Multi-layer coextrusion technician scarcity:EVOH tie-layer optimization and gauge control require specialized extrusion expertise concentrated among aging workforces in northern Italy and southern Germany.
- FDA migration study timelines:21 CFR Part 177 food additive notifications for novel bio-based polyesters extend validation cycles to 24-36 months, delaying commercial launches for sustainable substrate innovators.
- Legacy form-tool retrofit costs:Aluminum mold sets for PVC thermoforming require complete replacement to process heat-stabilized PET at elevated forming temperatures, stranding capital for mid-tier converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermoforming Packaging Market |
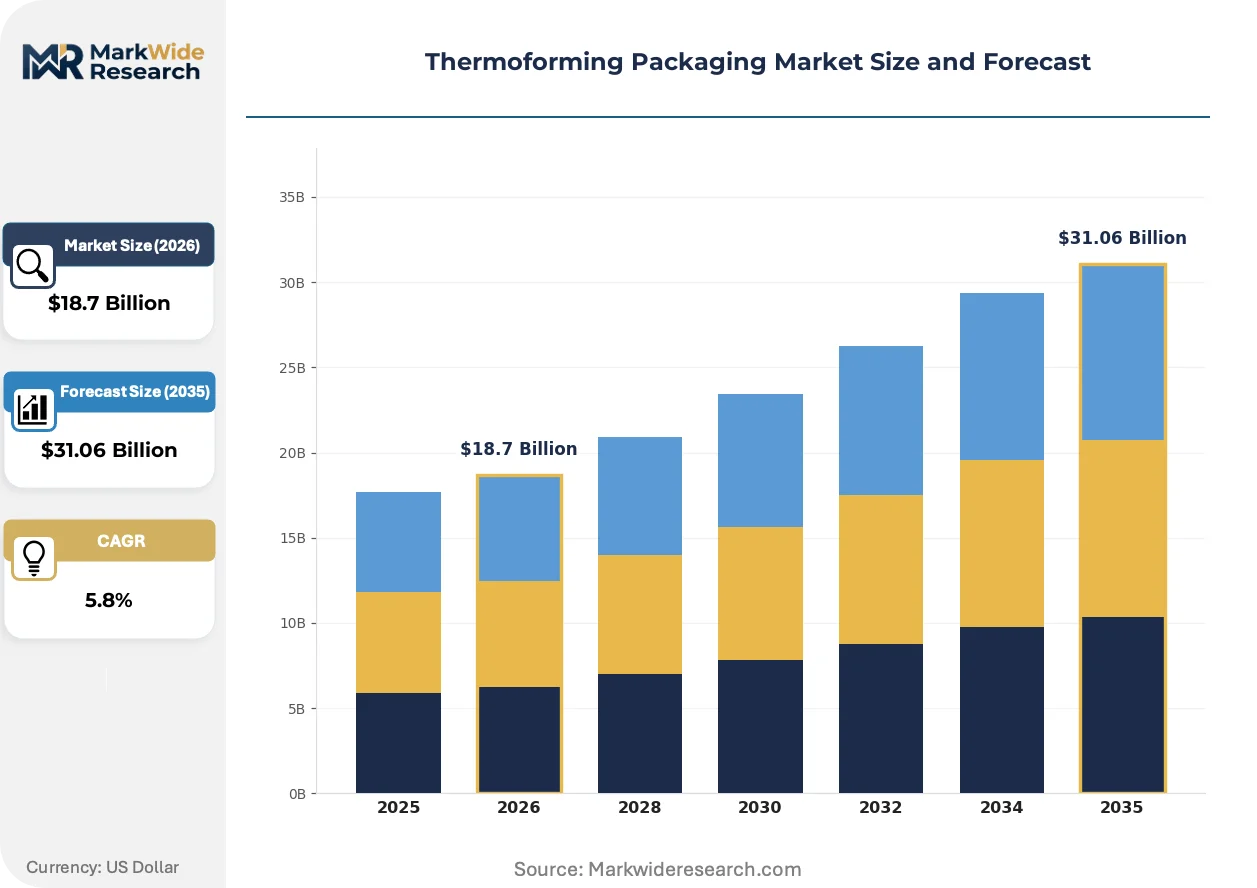
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Packs, Clamshells, Trays, Cups Material: Polyethylene, Polypropylene, PVC, PET Application: Food Packaging, Healthcare Packaging, Consumer Goods, Electronics End User: Food Industry, Pharmaceutical Industry, Cosmetics, Electronics Manufacturers |
| Companies Covered | Amcor Plc, Sonoco Products Company, Berry Global Inc., Sealed Air Corporation, Huhtamaki Oyj, Anchor Packaging, Sabert Corporation, Pactiv Evergreen, DS Smith, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoforming Packaging Market Strategic Shifts
Digital manufacturing integration and material science advances are compressing development cycles for thermoformed packaging, with sustainability metrics now embedded as design constraints rather than after-the-fact optimizations.
Mono-material PET tray structures with integrated functional barriers are consolidating technical specifications across European retail private label programs. Major food processors specify these formats for meat and dairy applications to satisfy retailer sustainability scorecards. The technology is consolidating supplier bases by disqualifying converters lacking coextrusion capability or rPET sourcing relationships.
REACH Article 33 substance-of-very-high-concern disclosure requirements now extend to full supply chain transparency for packaging articles. Thermoformers must document plasticizer and stabilizer chemistries through tier-three suppliers to maintain EU market access. Medical device packaging segments face the steepest compliance burden due to multi-layer film constructions incorporating phthalate-based adhesives.
Centralized procurement of thermoformed packaging by pan-European retail alliances is compressing supplier qualification timelines. Buying consortiums in the Netherlands and Scandinavia now mandate recycled content certifications and carbon footprint disclosures as gate criteria for tender participation. This behavioral shift is most visible in fresh protein categories where private label concentration exceeds sixty percent of shelf space.
Thermoforming Packaging Market Segmentation
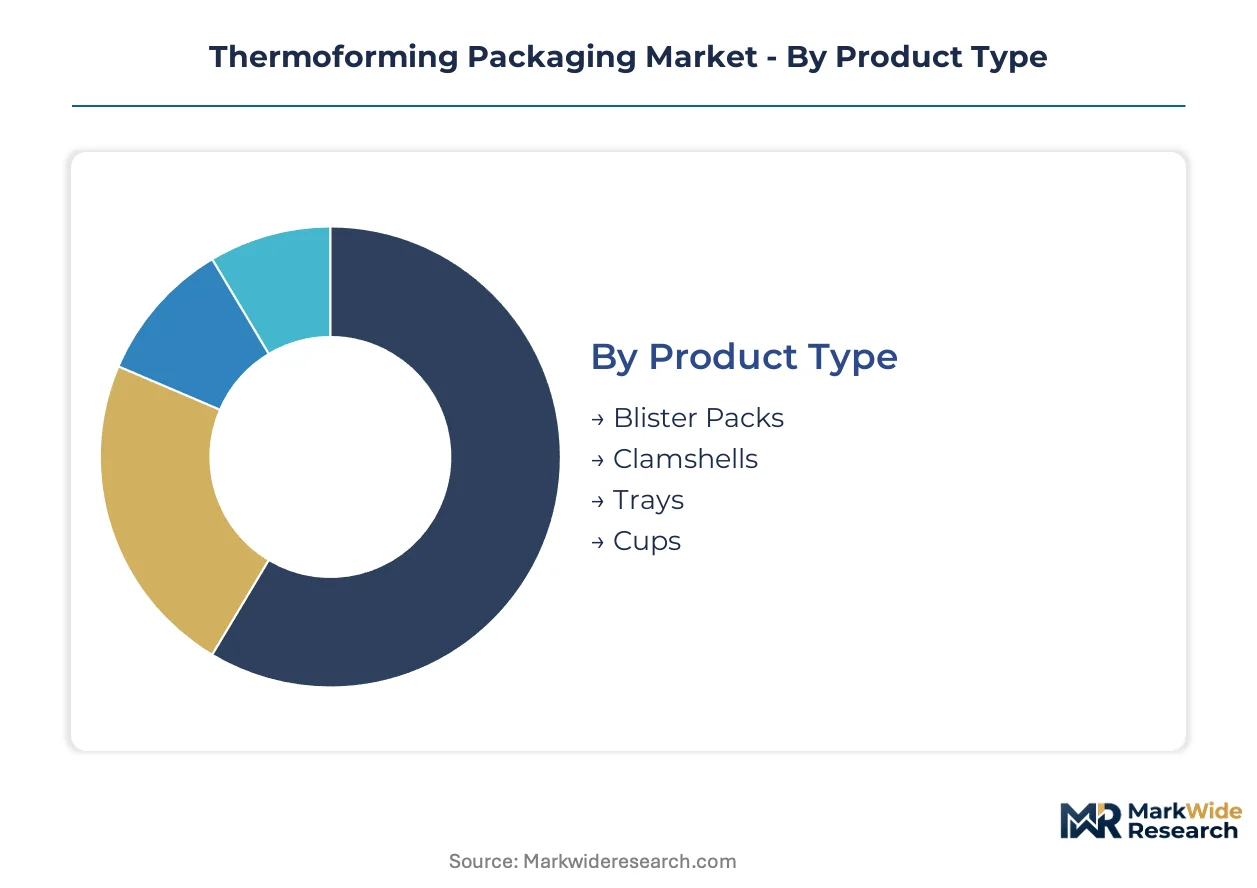
Thermoforming packaging serves distinct functional requirements across product protection, shelf presence, and automated handling. Segmentation reveals how material choices and forming geometries align with regulatory constraints and end-use performance thresholds. Each category carries implications for tooling investment, cycle economics, and recycling pathway design.
Product Type:
Standalone thermoformed containers dominate high-volume disposables, while embedded formats integrate with secondary packaging systems for controlled distribution.
- Blister Packs:Unit-dose cavities sealed to lidding foil or film, engineered for pharmaceutical compliance with child-resistance and senior-friendly access standards. Demand concentrates in oral solid dosage packaging for EU Falsified Medicines Directive compliance, where PVC/PVDC and cold-form aluminum alternatives compete on barrier performance and line speed.
- Clamshells:Hinged two-piece containers with integral locking features, thermoformed from clear PET or RPET for retail theft deterrence and product visibility. Electronics and consumer goods manufacturers in Germany specify these for point-of-sale display, driven by retailer sustainability scorecards favoring mono-material recyclability over multi-component alternatives.
- Trays:Single-cavity or multi-cavity platforms for protein, produce, and ready-meal containment, often paired with modified-atmosphere lidding.
- Cups:Tapered cylindrical containers for dairy, beverages, and portion-controlled foods, formed through plug-assisted pressure forming for uniform wall distribution.
Volume placements concentrate in Trays; the faster expansion belongs to Clamshells.
Material:
Substrate selection balances forming temperature windows, barrier requirements, and post-consumer collection economics across European recycling infrastructure.
- PET:Amorphous and crystallizable grades dominate food-contact applications, offering optical clarity, EVOH compatibility in coextruded structures, and established bottle-to-sheet recycling streams. German food processors specify rPET sheet grades to satisfy Verpackungsgesetz recycled content mandates, creating pull-through demand that outstrips southern European flake supply.
- Polypropylene:Homopolymer and random copolymer formulations serve microwaveable and retortable applications where thermal resistance exceeds PET limits. Mineral-filled PP grades are displacing PFAS-treated alternatives under EPA TSCA Section 6 restrictions, though barrier performance trade-offs constrain adoption in high-fat food categories.
- Polyethylene:LDPE and HDPE sheet grades for flexible-temper containers and industrial dunnage with lower clarity requirements.
- PVC:Rigid formulations persist in pharmaceutical blister packs for moisture barrier and thermoforming precision, though food-contact applications face retailer phase-out pressures.
Procurement volumes favor PET; polypropylene gains share fastest in heat-resistant formats.
Application:
Application segmentation tracks how forming precision, barrier specifications, and sterilization compatibility diverge across end-use environments.
- Food Packaging:Modified-atmosphere trays and lidded containers for fresh protein, dairy, and prepared meals, specifying EVOH oxygen barriers and anti-fog surfaces. European supermarket private label concentration above sixty percent drives standardization toward mono-PET structures with integrated functional layers.
- Healthcare Packaging:Sterilization barriers for medical devices and pharmaceutical compliance formats, requiring ISO 11607 validation and FDA 21 CFR Part 177 food additive compliance. Eastern European contract manufacturing growth sustains above-average margins for Tyvek-lidded tray suppliers with established validation protocols.
- Consumer Goods:Cosmetic and personal care inserts, formed trays for premium positioning and retail theft protection.
- Electronics:Anti-static and conductive formulations for component shipping and retail display, with ESD protection specifications.
Food Packaging commands the largest placement volumes; Healthcare Packaging delivers the steepest expansion trajectory.
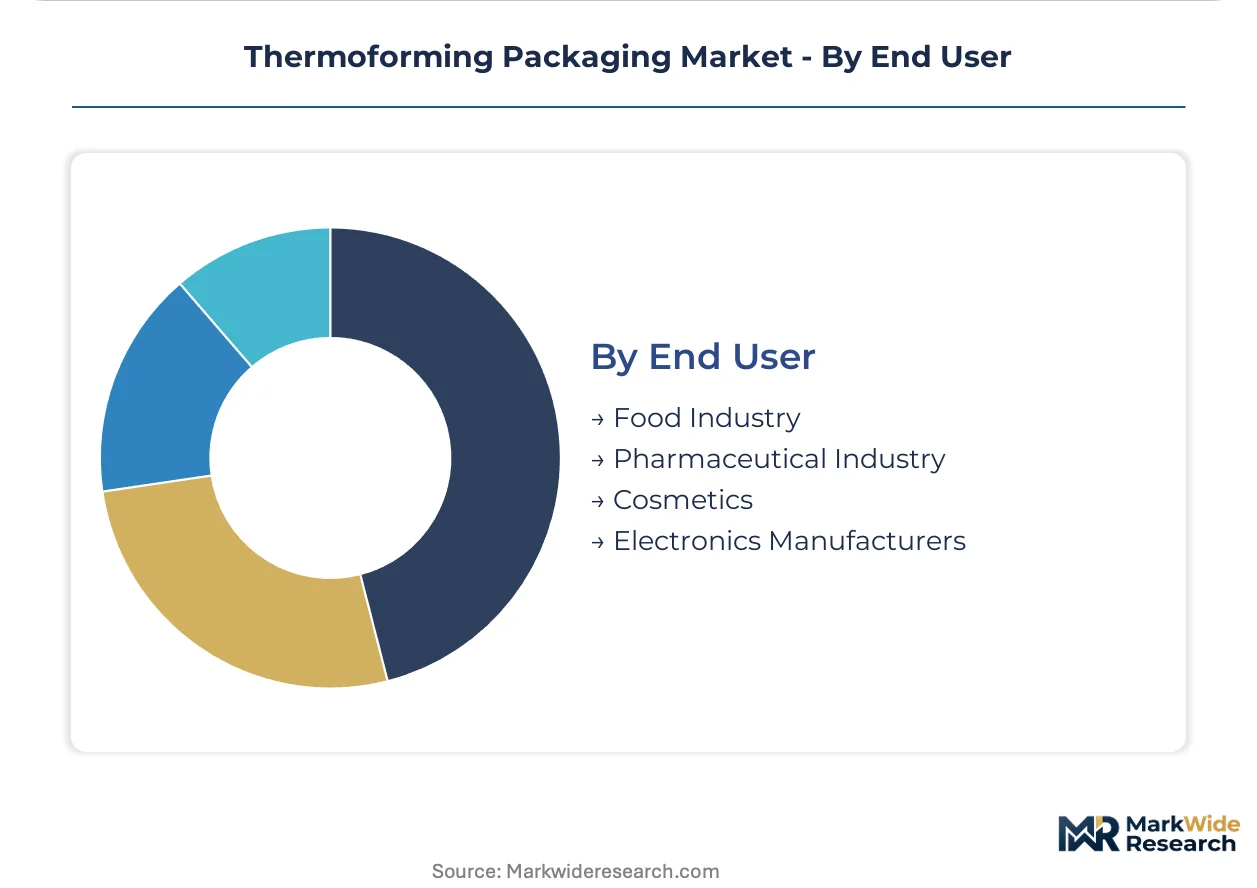
End User:
End user categories reflect procurement scale, specification authority, and sustainability mandate intensity across the value chain.
- Food Industry:Meat, dairy, and ready-meal processors with centralized packaging specification authority, increasingly consolidated under pan-European retail alliance procurement. Netherlands and Scandinavian buying consortiums now mandate recycled content certifications and carbon footprint disclosures as tender gate criteria.
- Pharmaceutical Industry:Dosage form manufacturers and contract packaging organizations governed by EU Falsified Medicines Directive serialization requirements and FDA validation protocols. Unit-dose blister adoption climbs with serialization mandates, though thermoformed formats face competition from stick packs and bottle alternatives.
- Cosmetics:Brand owners specifying formed inserts and secondary packaging for premium positioning and unboxing experience.
- Electronics Manufacturers:OEMs and contract manufacturers requiring ESD protection, retail display compatibility, and logistics durability.
Food Industry placements dominate current volumes; Pharmaceutical Industry procurement expands most quickly under compliance-driven format conversions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food processing clusters in Germany concentrate thermoforming demand through Verpackungsgesetz compliance requirements, while regulatory divergence across major economies fragments supply chain configuration.
Germany
Meat and dairy processors in Lower Saxony and Bavaria specify rPET sheet grades for modified-atmosphere trays. ECHA REACH Article 33 disclosure mandates force documentation of plasticizer chemistries through tier-three suppliers. The Frankfurt-Rhine-Main corridor hosts technical extrusion expertise for EVOH tie-layer optimization.
United States
Pharmaceutical serialization under FDA 21 CFR Part 11 drives unit-dose blister adoption in New Jersey and Pennsylvania manufacturing belts. EPA TSCA Section 6 restrictions on PFAS grease-resistant additives compel reformulation toward mineral-filled PP for microwaveable trays. Chicago-area converters serve protein processors with high-barrier PET structures.
France
ANSM pharmaceutical packaging standards sustain demand for PVC/PVDC blister formats in the Île-de-France region. EU Green Deal packaging waste directives accelerate transitions from multi-material laminates toward mono-PET designs. Lyon-based dairy processors specify thermoformed cups with integrated functional barriers for retailer sustainability scorecards.
China
SAMR food contact material regulations govern monomer migration limits for thermoformed dairy and beverage containers. Yangtze River Delta electronics manufacturers specify anti-static clamshells for component shipping and retail display. Shanghai-area converters expand coextrusion capacity to serve pan-Asian supply chains.
India
FSSAI packaging safety standards constrain multi-layer constructions for dairy and ready-meal applications. Maharashtra and Gujarat food processors adopt thermoformed trays for organized retail penetration. Mumbai-Pune industrial corridor converters develop rPET sheet capability to meet emerging recycled content mandates.
Thermoforming Packaging Market Competitive Environment
North American producers anchor one tier; European specialists hold differentiated positions through regulatory compliance depth. The vendor base structures across three tiers: integrated resin-to-package conglomerates, regional extrusion converters with captive recycling, and niche healthcare sterilization barrier suppliers. Strategic moves concentrate on backward integration into rPET flake sourcing and chemical recycling feedstock partnerships.
Among diversified packaging conglomerates, Amcor Plc and Berry Global Inc. exemplify scale-driven archetypes with global resin sourcing networks. Sealed Air Corporation occupies a position within the barrier technology specialist tier. These three entities represent contrasting strategic postures: resin network leverage, captive recycling integration, and functional layer differentiation respectively.
| Leading Market Players |
|---|
| Amcor Plc |
| Sonoco Products Company |
| Berry Global Inc. |
| Sealed Air Corporation |
| Huhtamaki Oyj |
| Anchor Packaging |
| Sabert Corporation |
| Pactiv Evergreen |
| DS Smith |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up converters in Germany and France anchor pricing discipline through captive rPET flake sourcing, while family-owned Italian extrusion specialists defend margin stability via EVOH tie-layer expertise that commands premium sheet grades from pan-European retail consortiums.
Pricing Analysis
Short lead-time premiums apply to rush orders for modified-atmosphere tray specifications, while spot inventory of standard PET sheet trades at discounts. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Pricing pressure stems from rPET flake supply bottlenecks in southern Europe as German Verpackungsgesetz mandates outstrip mechanical recycling capacity. Food processors in Netherlands buying consortiums exhibit highest price sensitivity due to standardized tender formats, while pharmaceutical contract packers show lowest sensitivity given FDA validation switching costs.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from German meat processors in Lower Saxony and Bavaria, while distributor networks serve mid-tier converters across southern Europe. Raw material dependencies center on PET resin from Belgium and the Netherlands, EVOH barrier resins from Japan and USA, and rPET flake concentrated in German and French bottle-to-sheet recycling clusters. Single-source vulnerability in EVOH tie-layer resin exposes converters to supply disruption from Asian petrochemical complexes. Distribution runs through regional extrusion hubs in northern Italy and southern Germany with technical workforce concentration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The thermoforming packaging sector sits in a substrate-transition phase as mono-material PET structures displace multi-layer PVC laminates under EU Green Deal compliance deadlines.
For Market Incumbents: Acquire captive rPET flake recycling assets in Germany or France to secure feedstock against Verpackungsgesetz recycled content mandates. Build ISO 11607 sterilization barrier validation capability for Eastern European medical device contract manufacturing growth. Defensive moves must counter chemical recycling entrants bypassing mechanical flake limitations. For New Entrants and Emerging Players: Eastern European healthcare sterilization barrier suppliers represent the most penetrable buyer archetype given ISO 11607 validation scarcity and pan-European OEM relocation trends. Target Indian organized retail penetration with rPET sheet capability ahead of FSSAI recycled content mandates. Go-to-market leverage rests on direct extrusion-to-thermoformer partnerships bypassing distributor markups. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier Italian converters with EVOH coextrusion capability but stranded without rPET sourcing relationships. Long-term viability favors assets with backward integration into chemical recycling feedstock partnerships. Watch pyrolysis-based monomer regeneration cost curves as inflection signal for mechanical recycling displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Flake Sourcing | Verpackungsgesetz compliance in Germany requires secure recycled content supply chains. |
| Chemical Recycling Feedstock Partnership | Pyrolysis-based monomer regeneration bypasses mechanical recycling color-sorting limitations. |
| ISO 11607 Sterilization Barrier Certification | Eastern European medical device manufacturing growth demands validated tray suppliers. |
| Direct-to-Film Digital Printing Capability | UV-inkjet decoration aligns with EU single-use plastics directive label reduction targets. |
| Multi-Layer Coextrusion Technician Training Programs | EVOH tie-layer expertise scarcity in aging northern Italian workforces constrains capacity expansion. |
Study Parameters
Trade association filings, ECHA REACH registration databases, and EU packaging waste directive implementation reports formed the secondary backbone for substrate transition trend analysis. Primary interviews with thermoforming plant managers, retail procurement leads at Netherlands buying consortiums, EVOH resin technical directors, and pharmaceutical packaging regulatory affairs specialists validated secondary findings. Bottom-up capacity modeling across German and French rPET sheet extruders triangulated against top-down demand estimates from meat and dairy processor packaging specifications.
Historical trendline analysis of PET resin pricing volatility, rPET flake supply-demand balances, and thermoformed tray specification shifts informed projection frameworks. Segmentation dimensions modeled include product type, material substrate, application end-use, and regional regulatory cluster. CAGRs derived from elasticity-adjusted volume projections incorporating Verpackungsgesetz mandate compliance timelines and FDA 21 CFR Part 177 notification cycle impacts. Industry-specific forecast inputs encompass EVOH barrier resin capacity expansion announcements and chemical recycling commercialization milestones.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to pyrolysis technology cost curves and PFAS regulatory phase-out acceleration. Forecasts reflect assumptions regarding mechanical recycling infrastructure deployment and EVOH resin supply continuity. Periodic stress-testing of base assumptions is recommended against ECHA substance-of-very-high-concern list expansions and state-level extended producer responsibility law adoptions in California and Washington.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Mexico Flexible Packaging Market
Flexible Packaging
Litho Laminated Packaging Market
Flexible Packaging
China Flexible Plastic Packaging Market
Flexible Packaging
ASEAN Flexible Packaging Market
Flexible Packaging
Kenya Flexible Packaging Market
Flexible Packaging
Flexible Food Packaging Market
Flexible Packaging
Saudi Arabia Flexible Plastic Packaging Market
Flexible Packaging
Global Breathable Films Market
Flexible Packaging
Africa Flexible Packaging Market
Flexible Packaging
Metalized Flexible Packaging Market
Flexible Packaging
North America Flexible Plastic Packaging Market
Flexible Packaging
Asia Pacific Single-Use Packaging Market
Flexible Packaging
Indonesia Flexible Plastic Packaging Market
Flexible Packaging
China Flexible Packaging Market
Flexible Packaging
Europe Flexible Packaging Market
Flexible Packaging
Thailand Flexible Plastic Packaging Market