
 Canada Flexible Packaging Market | 2026-2036
Canada Flexible Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Flexible Packaging Market Analysis
Canada's Single-Use Plastics Prohibition Regulations is repositioning capital allocation across the domestic supply base. Transcontinental Inc. leverages its integrated printing and converting footprint to serve private-label food brands with shorter run lengths. Winpak Ltd anchors its competitive stance through advanced barrier film coextrusion capabilities at its Winnipeg operations. Cascades Flexible Packaging differentiates via recycled-content paper structures that align with extended producer responsibility frameworks in Ontario and Quebec.
Flexible packaging comprises pliable substrates—polymer films, paper laminates, metallized foils, and compostable resins—engineered into pouches, bags, wraps, and sachets through extrusion, lamination, printing, and coating processes, with oxygen transmission rates and seal integrity as critical performance parameters for shelf-life extension. Stand-up pouches command premium positioning in the food and beverage channel due to their retail shelf presence and material efficiency versus rigid alternatives. Compostable materials represent the fastest-expanding material category as provincial organic waste diversion mandates tighten disposal requirements for conventional multilayer plastics.
Health Canada regulates food-contact materials under the Food and Drugs Act, while the Canadian Food Inspection Agency enforces label integrity and safety standards that dictate barrier specifications and migration limits for packaging substrates. Provincial extended producer responsibility programs in British Columbia, Ontario, and Quebec are forcing brand owners to redesign packaging for recyclability or compostability, directly shaping converter R&D priorities. Stakeholders must monitor regulatory divergence between federal plastics bans and provincial recycling infrastructure readiness to anticipate which material platforms will achieve scale.
Market Dynamics
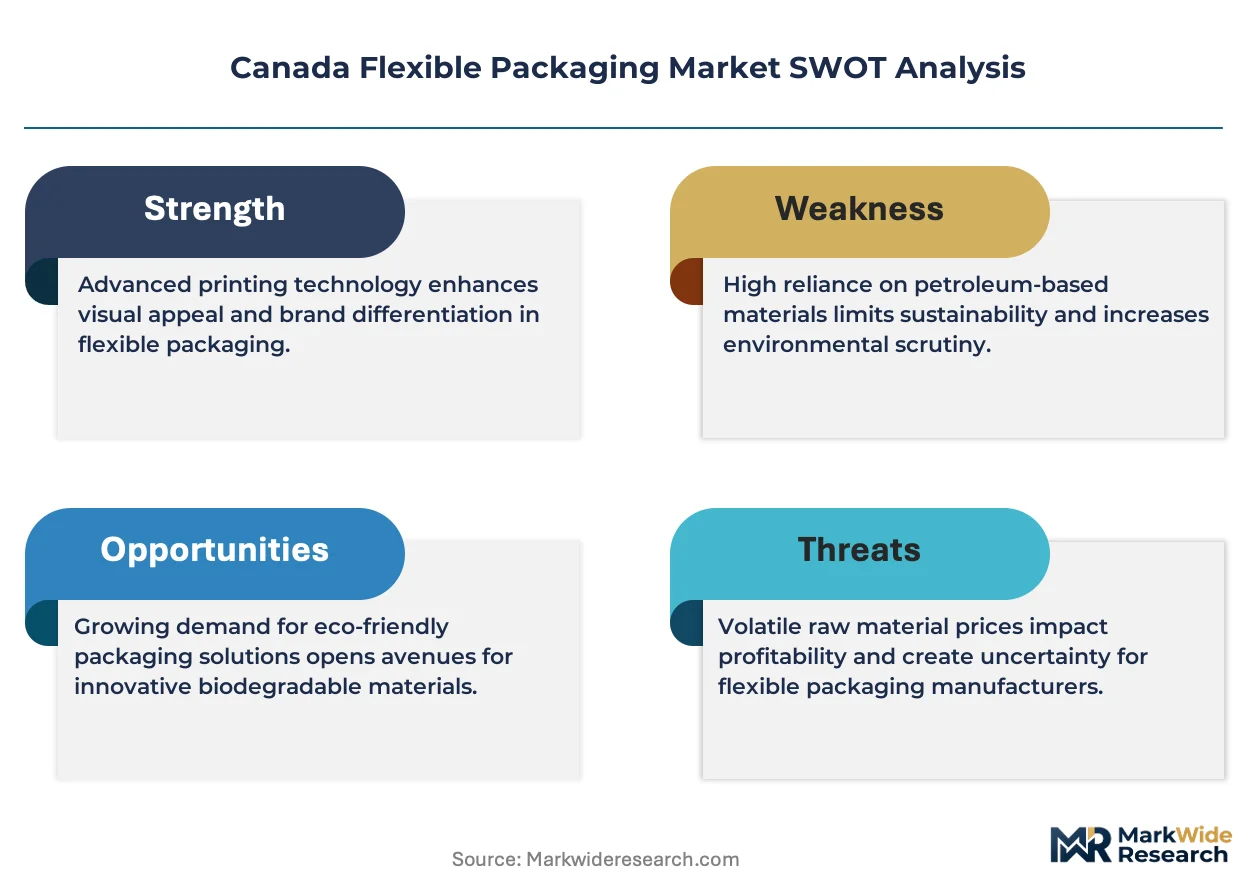
Health Canada's Single-Use Plastics Prohibition Regulations is forcing converters to redesign multilayer structures around compostable substrates and paper-barrier laminates, compressing development cycles and reallocating capital from conventional extrusion lines toward pilot-scale compostable resin processing.
Growth Catalysts
- Provincial organic waste mandates:British Columbia, Ontario, and Quebec have enacted extended producer responsibility frameworks that penalize non-recyclable packaging. Brand owners are accelerating pouch-format adoption to meet diversion targets.
- Pouch-based ready-to-eat meal expansion:Food processors in Ontario's Golden Horseshoe are migrating shelf-stable proteins and prepared meals from rigid trays to retortable stand-up pouches. This format shift reduces material weight and extends shelf life.
- Barrier film coextrusion advances:Winnipeg-based converters have deployed nine-layer extrusion lines that replace metallized foils with high-barrier polymer nanolaminates. The technology enables thinner gauges without oxygen transmission rate degradation.
Market Restraints
- Compostable resin supply concentration:Polylactic acid and polyhydroxyalkanoate feedstock relies on US Midwest corn processing and limited European fermentation capacity. Price volatility in agricultural inputs transmits directly to substrate costs.
- Multilayer recycling infrastructure gap:Mechanical separation of polyethylene-nylon-ethylene vinyl alcohol laminates remains uneconomical at municipal scale. The technical limitation forces brand owners toward costlier monomaterial redesigns.
- Extended producer responsibility fee structures:Ontario's Blue Box transition shifts full cost recovery to producers in 2026. Small and mid-size converters face disproportionate compliance burden versus integrated competitors with in-house sustainability teams.
Strategic Opportunities
- Atlantic Canada food processing expansion:Nova Scotia and New Brunswick seafood exporters lack local high-barrier flexible packaging capacity. Converters with retort pouch expertise can capture margin currently lost to US and Quebec suppliers.
- Pharmaceutical sachet and strip pack growth:Health Canada's serialization requirements for unit-dose compliance packaging are accelerating demand for aluminum-paper laminates with integrated track-and-trace features.
- Digital printing-converting integration:Hybrid inkjet-flexo systems enable run-length compression from 50,000 to 5,000 units. Private-label brands in Quebec's specialty food sector are adopting this for seasonal and regional SKU proliferation.
Industry Challenges
- Compostable certification timeline compression:ASTM D6400 and BPI certification for new resin formulations requires 180-day industrial composting trials. Product launch schedules compress against regulatory deadlines with limited testing lab capacity.
- Legacy solvent-based lamination asset stranding:Converters with substantial toluene-based adhesive coating lines face accelerated depreciation as brand owners mandate water-based or solventless alternatives for volatile organic compound reduction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Flexible Packaging Market |
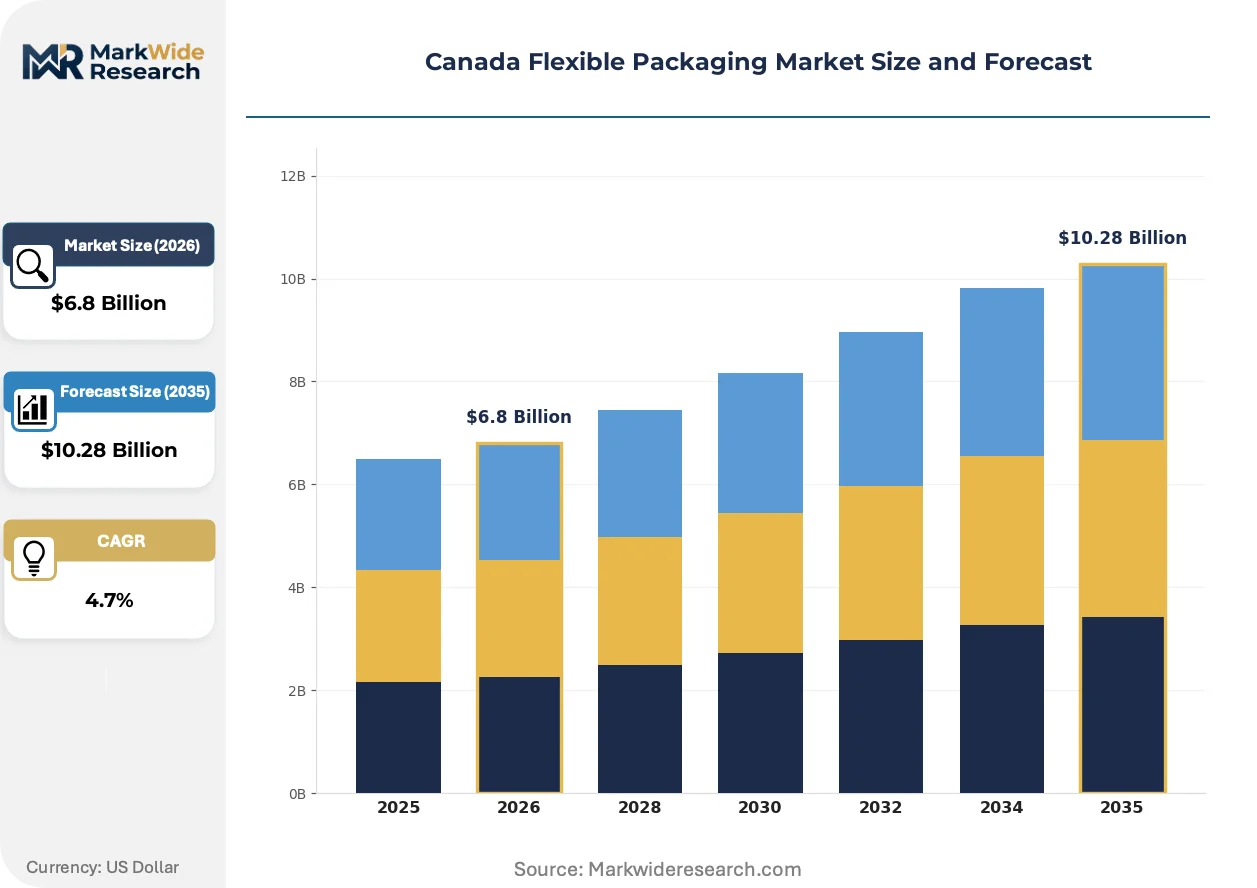
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Bags, Wraps Material: Plastic, Paper, Aluminum Foil, Compostable End User: Food & Beverage, Personal Care, Pharmaceuticals, Household Technology: Printing, Coating, Laminating, Extrusion |
| Companies Covered | Transcontinental Inc., Winpak Ltd, Cascades Flexible Packaging, Amcor PLC, Sonoco Products Company, ProAmpac LLC, Sealed Air Corporation, Mondi PLC, St. Johns Packaging, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Flexible Packaging Market Emerging Trajectories
Digital printing, compostable barrier chemistry, and provincial extended producer responsibility frameworks are converging to restructure how converters design, produce, and take financial responsibility for packaging formats across Canada's food and pharmaceutical supply chains.
Paper-barrier laminate technology is unifying fiber-based substrates with ultra-thin ethylene vinyl alcohol and bio-derived coatings to replace conventional plastic pouches. Major retail banners in Ontario and Quebec are piloting these structures for dry pasta, nuts, and coffee. The technology is unifying shelf appeal with circularity claims, though oxygen transmission rates remain 15-20% higher than metallized alternatives.
Health Canada's Single-Use Plastics Prohibition Regulations and accompanying guidance documents are mandating compostability or recyclability for checkout bags, cutlery, and foodservice ware by 2025. The industrial consequence is a forced pivot in converter R&D spending from barrier performance optimization toward disintegration testing and organic waste facility compatibility verification. Stand-up pouches for single-serve snacks face the steepest redesign imperative.
Consolidated procurement by Loblaw, Sobeys, and Metro is compressing supplier panels and extending payment terms from 45 to 75 days. Tier-two converters without captive resin supply or integrated printing are accepting margin compression to maintain volume, while vertically integrated competitors capture category management contracts. The behavioral shift is most visible in Ontario's Golden Horseshoe, where three retail banners control 85% of grocery flexible packaging specifications.
Canada Flexible Packaging Market Segmentation
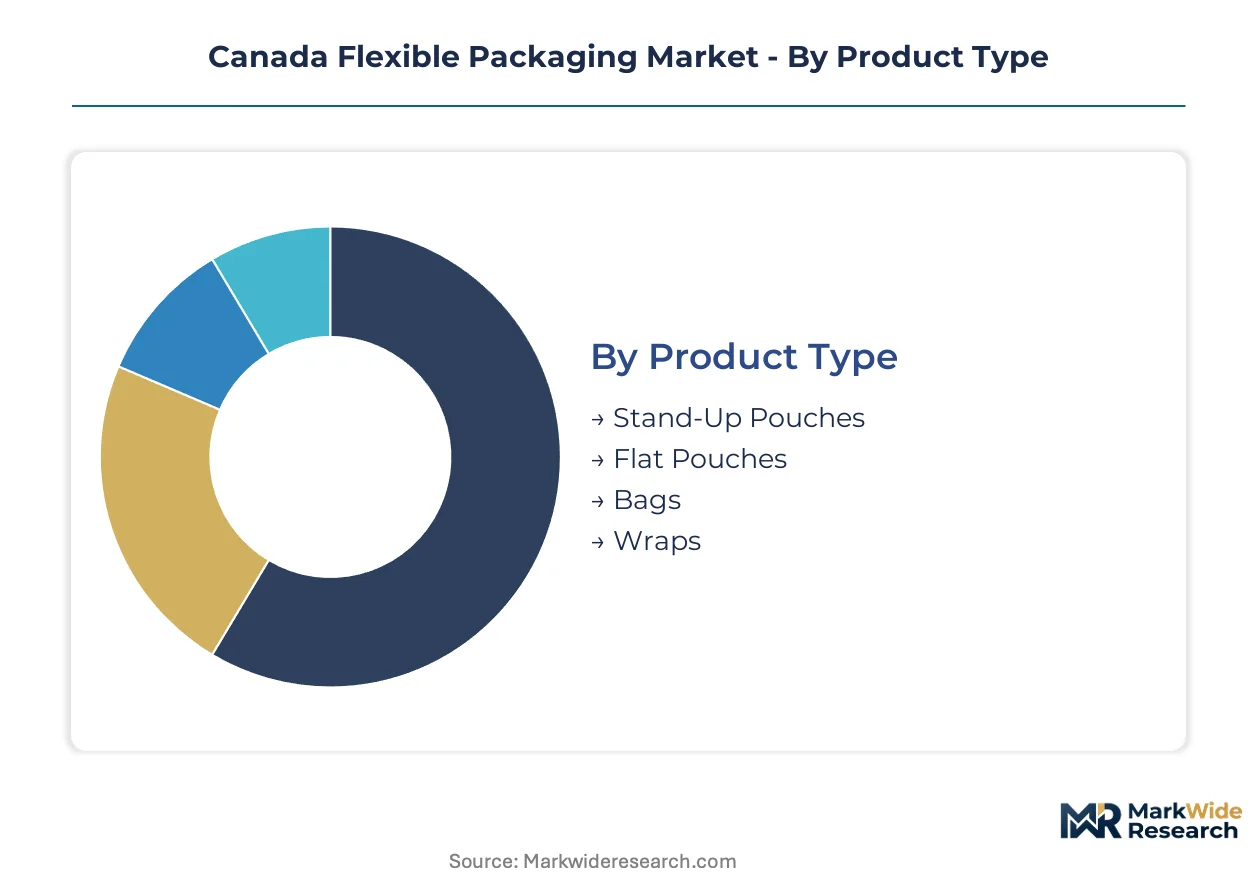
Canada's flexible packaging market segments along four critical dimensions that determine converter capital allocation and brand owner procurement strategy. Each category reflects distinct technical requirements, regulatory pressures, and geographic demand patterns across Ontario's Golden Horseshoe and Quebec's food processing belt.
Product Type:
Format selection determines barrier performance, retail shelf presence, and compliance with provincial extended producer responsibility frameworks.
- Stand-Up Pouches:Retortable multilayer structures with gusseted bases dominate shelf-stable proteins and ready-to-eat meals. Ontario food processors in the Golden Horseshoe corridor are migrating rigid tray formats to these pouches to reduce material weight and meet organic waste diversion targets.
- Flat Pouches:Three-side-seal and four-side-seal configurations serve portion-controlled snacks and pharmaceutical unit-dose packaging. Quebec's specialty food sector deploys shorter-run digital-printed flat pouches for seasonal SKU proliferation.
- Bags:Side-gusseted and pillow formats handle bulk dry goods with lower barrier requirements.
- Wraps:Flow-wrap and overwrap structures protect fresh produce and bakery items with breathable film specifications.
Stand-Up Pouches lead volumes today; Flat Pouches are gaining share fastest in pharmaceutical and specialty food channels.
Material:
Substrate selection has become the primary lever for compliance with Health Canada's Single-Use Plastics Prohibition Regulations and provincial organic waste mandates.
- Plastic:Polyethylene, polypropylene, and polyester films remain the workhorse substrate, though converters are thinning gauges and shifting toward monomaterial structures to improve recyclability. Winnipeg-based extrusion lines now deploy nine-layer coextrusion to replace metallized foils with polymer nanolaminates.
- Compostable:Polylactic acid and polyhydroxyalkanoate resins are climbing the fastest as British Columbia, Ontario, and Quebec tighten disposal requirements for conventional multilayer plastics. Certification bottlenecks at ASTM D6400 testing labs constrain supply expansion.
- Paper:Fiber-based substrates with ultra-thin ethylene vinyl alcohol and bio-derived coatings are piloting for dry pasta, nuts, and coffee in Ontario and Quebec retail banners.
- Aluminum Foil:High-barrier metallized layers face displacement in snack applications but retain critical roles in pharmaceutical blister and strip packs requiring near-zero oxygen transmission.
Plastic maintains dominant share; Compostable materials are expanding most quickly under regulatory pressure.
End User:
Demand concentration varies sharply across customer verticals, with food and beverage procurement patterns setting the pace for converter equipment investment.
- Food & Beverage:Shelf-stable proteins, ready-to-eat meals, and specialty coffee drive the majority of flexible packaging volume. Loblaw, Sobeys, and Metro consolidated procurement is compressing supplier panels and extending payment terms.
- Pharmaceuticals:Unit-dose sachets and strip packs with integrated track-and-trace features are accelerating under Health Canada serialization requirements. Aluminum-paper laminates dominate this specification-intensive segment.
- Personal Care:Stand-up pouches for liquid soaps and single-use samples face redesign pressure toward recyclable or compostable substrates.
- Household:Refill pouches for cleaning products are gaining traction as brand owners test concentrated formulations to reduce shipping weight.
Food & Beverage commands the largest volume position; Pharmaceuticals is climbing fastest on compliance-driven unit-dose growth.
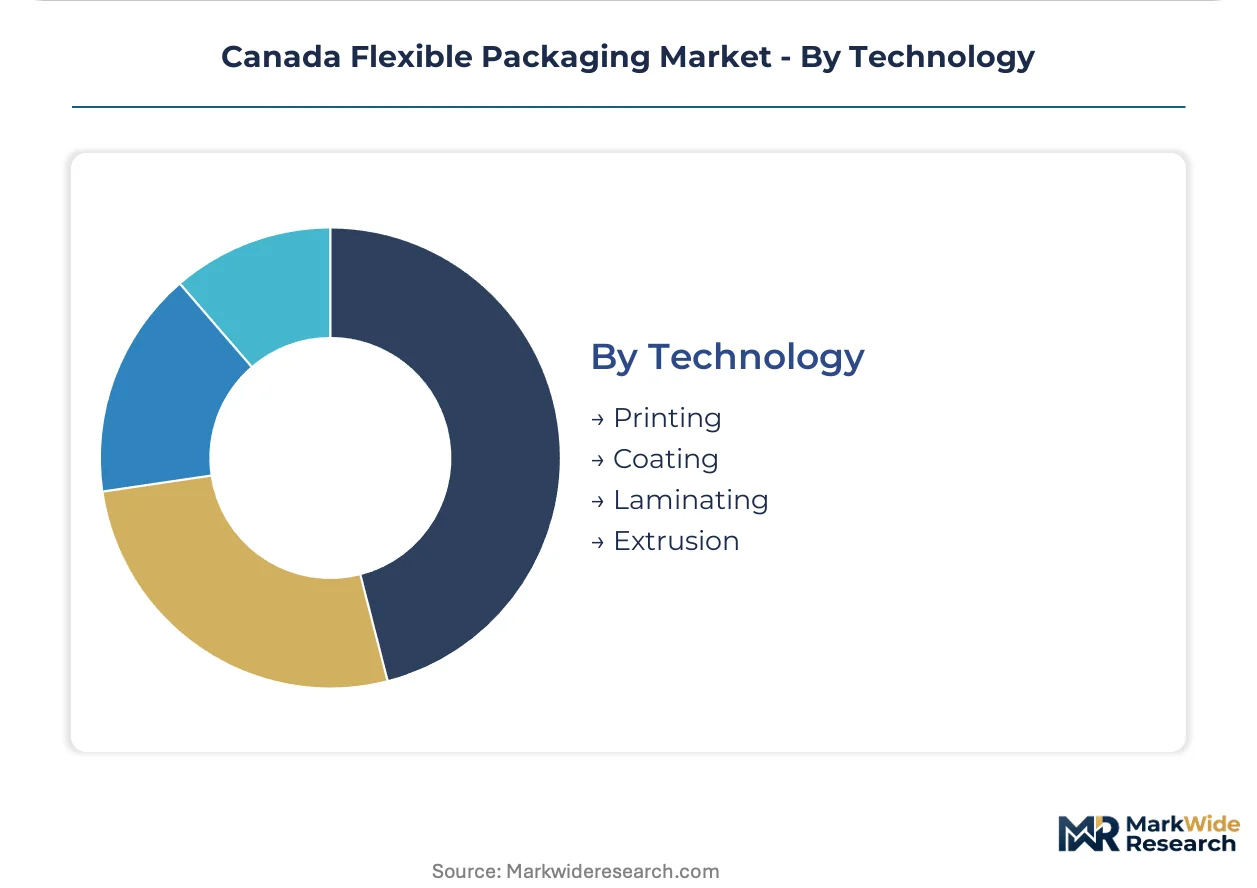
Technology:
Process capability determines which converters can execute the format and material transitions demanded by brand owners and regulators.
- Extrusion:Blown and cast film lines with barrier layer coextrusion anchor converter competitiveness. Nine-layer systems at Winnipeg operations enable thinner gauges without oxygen transmission degradation.
- Laminating:Solventless and water-based adhesive systems are displacing legacy toluene-based coating lines as volatile organic compound regulations tighten.
- Printing:Hybrid inkjet-flexo systems enable run-length compression from 50,000 to 5,000 units for private-label seasonal programs.
- Coating:Ultra-thin barrier coatings applied to paper and compostable substrates are critical for replacing conventional plastic pouches.
Extrusion holds the largest installed base; Laminating is retooling fastest to meet solvent reduction mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converting talent clusters in Ontario and Quebec anchor Canadian flexible packaging capacity, with Winnipeg extrusion specialists and Vancouver sustainability labs rounding out the national footprint.
Ontario
The Golden Horseshoe manufacturing corridor concentrates food and beverage processors migrating rigid tray formats to retortable stand-up pouches. Ontario's Blue Box transition shifts full cost recovery to producers in 2026, forcing packaging redesigns for recyclability. Toronto-area converters deploy hybrid inkjet-flexo systems to serve private-label brands with compressed run lengths.
Quebec
Montreal's food processing belt drives specialty coffee and prepared meal packaging demand with shorter-run seasonal SKU proliferation. The province's extended producer responsibility framework penalizes non-recyclable packaging, accelerating compostable substrate adoption. Quebec-based converters differentiate through recycled-content paper structures aligned with provincial circularity mandates.
Manitoba
Winnipeg operations anchor advanced barrier film coextrusion capabilities serving Prairie agricultural processors. Health Canada's Single-Use Plastics Prohibition Regulations pressure local converters to pilot compostable resin processing. The city's nine-layer extrusion lines enable thinner polymer nanolaminates that replace metallized foils without oxygen transmission degradation.
British Columbia
Vancouver and Lower Mainland facilities focus on compostable certification and organic waste diversion compliance for West Coast brand owners. The province's extended producer responsibility program mandates packaging recyclability, driving R&D spending toward disintegration testing. Local testing labs face capacity constraints as certification timelines compress against regulatory deadlines.
Atlantic Canada
Nova Scotia and New Brunswick seafood exporters lack local high-barrier flexible packaging capacity, ceding margin to Quebec and US suppliers. Provincial organic waste mandates are tightening disposal requirements for conventional multilayer plastics. Halifax-area converters with retort pouch expertise can capture share currently lost to distant competitors.
Canada Flexible Packaging Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across Canada's flexible packaging supply base. The market structure tilts toward consolidated procurement power at the customer end, with Loblaw, Sobeys, and Metro compressing supplier panels and extending payment terms from 45 to 75 days. Three strategic archetypes dominate: integrated printing-converting conglomerates with captive resin supply, barrier film coextrusion specialists with advanced multilayer capabilities, and sustainability-focused converters with compostable and recycled-content platforms. Competitive moves center on M&A-driven geographic expansion and portfolio diversification into pharmaceutical and personal care verticals.
Within the integrated conglomerate tier, Transcontinental Inc. and Amcor PLC occupy positions shaped by their printing and converting footprints across North American food and beverage supply chains. Winpak Ltd exemplifies the barrier film specialist archetype through its Winnipeg-based coextrusion operations. Cascades Flexible Packaging anchors the sustainability-focused segment with recycled-content paper structures. These three names illustrate how Canadian converter strategy diverges across integration depth, technical specialization, and circularity positioning.
| Leading Market Players |
|---|
| Transcontinental Inc. |
| Winpak Ltd |
| Cascades Flexible Packaging |
| Amcor PLC |
| Sonoco Products Company |
| ProAmpac LLC |
| Sealed Air Corporation |
| Mondi PLC |
| St. Johns Packaging |
| Others |
Supply Flow & Price Mechanics
Consolidated procurement by Loblaw, Sobeys, and Metro anchors contract-based long-term offtake as the dominant pricing model, with payment term extension from 45 to 75 days compressing converter margins across Ontario's Golden Horseshoe.
Pricing Analysis
Converters bundle extrusion, printing, and laminating services into integrated supply agreements for private-label food brands, while unbundled component sales serve smaller Quebec specialty food processors. Price differentiation hinges on volume scale and certification grade—ASTM D6400 compostable certification commands premium positioning. Cost compression in standard plastic laminates is intensifying because thin-gauge nine-layer coextrusion displaces metallized foils. Small and mid-size converters exhibit highest price sensitivity due to Ontario's Blue Box full cost recovery transition.
Supply Chain Analysis
Single-source vulnerability sits with US Midwest corn processing for polylactic acid feedstock and limited European fermentation capacity for polyhydroxyalkanoate resins. Raw material dependencies center on polyethylene, polypropylene, and bio-derived barrier coatings. Tariff exposure on imported compostable resins transmits agricultural commodity volatility directly to substrate costs. Distribution runs through converter-direct relationships with brand owners, bypassing traditional distribution intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's flexible packaging market functions as a stable compounder, with regulatory-driven material transitions providing steady replacement demand across food and pharmaceutical end uses.
For Market Incumbents: Deepen backward integration into compostable resin supply to offset PLA and PHA price volatility from US Midwest corn markets. Expand retort pouch capacity in Atlantic Canada to capture seafood export margin currently lost to distant competitors. Health Canada's Single-Use Plastics Prohibition Regulations timeline compression is the critical threat requiring accelerated certification investment. For New Entrants and Emerging Players: Atlantic Canada seafood processors represent the most penetrable buyer archetype, lacking local high-barrier flexible packaging capacity. Nova Scotia and New Brunswick exporters currently source from Quebec and US suppliers, creating geographic arbitrage opportunity. Pharmaceutical unit-dose sachets with integrated track-and-trace features offer second white-space target, with compliance-driven demand accelerating under Health Canada serialization requirements. Lead with retort pouch technical expertise and compostable certification capability as the go-to-market angle. For Investors and Strategic Acquirers: Integrated printing-converting conglomerates with captive resin supply are the most active acquirer in this space, consolidating tier-two converters facing Ontario Blue Box compliance burden. Five-to-ten-year viability rests on material platform diversification across plastic, compostable, and paper-barrier laminates. Watch compostable certification lab capacity expansion as the signal indicating which substrate platforms achieve regulatory-scale deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Compostable Resin Processing Scale-Up | ASTM D6400 certification bottlenecks constrain supply expansion against Health Canada regulatory deadlines. |
| Nine-Layer Coextrusion Deployment | Winnipeg-based lines replace metallized foils with polymer nanolaminates, reducing oxygen transmission without gauge penalty. |
| Atlantic Canada Capacity Addition | Halifax-area retort pouch expertise captures seafood export margin currently lost to Quebec and US suppliers. |
| Hybrid Inkjet-Flexo Integration | Toronto-area systems enable run-length compression from 50,000 to 5,000 units for private-label seasonal proliferation. |
| Recycled-Content Paper Structure Development | Quebec-based converters align with provincial extended producer responsibility circularity mandates. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with extrusion plant managers, brand owner procurement leads at Loblaw and Sobeys, compostable certification lab directors, and Health Canada regulatory affairs specialists with secondary validation. Secondary sources included Canadian Food Inspection Agency enforcement data, provincial extended producer responsibility program filings, customs and trade statistics on resin imports, and SEC disclosures from listed packaging conglomerates. Bottom-up capacity and demand modeling triangulated against top-down market sizing.
Comparable historical periods anchored the projection horizon to observed regulatory transition phases and material substitution cycles. The analytical framework segmented by product type, material substrate, end-use vertical, and regional production cluster across the modeling period. CAGRs derived from segment-level volume trajectories calibrated to extrusion line deployment schedules and brand owner format migration timelines. Key forecast inputs included provincial organic waste mandate implementation schedules and compostable resin fermentation capacity expansion announcements.
Underlying measurement precision varies by segment; stand-up pouch and food and beverage verticals carry tighter precision than emerging pharmaceutical and personal care applications. Forecasts reflect documented assumptions on regulatory enforcement intensity and resin supply elasticity. Compostable certification timeline compression and multilayer recycling infrastructure gaps constitute primary revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Nigeria Flexible Plastic Packaging Market
Flexible Packaging
Saudi Arabia Flexible Plastic Packaging Market
Flexible Packaging
Benelux Flexible Plastic Packaging Market
Flexible Packaging
Asia-Pacific Flexible Plastic Packaging Market
Flexible Packaging
Middle East and Africa Flexible Plastic Packaging Market
Flexible Packaging
Thermoform Packaging Market
Flexible Packaging
APAC Flexible Packaging Market
Flexible Packaging
Japan Flexible Plastic Packaging Market
Flexible Packaging
Flex Pack Coatings Market
Flexible Packaging
Metalized Flexible Packaging Market
Flexible Packaging
Italy Flexible Plastic Packaging Market
Flexible Packaging
Global Flexible Packaging Market
Flexible Packaging
Europe Flexible Packaging Market
Flexible Packaging
Thermoforming Packaging Market
Flexible Packaging
Flexible Containers Market
Flexible Packaging
Stretch Packaging Market