
 Screen-Printing Glass Market | 2026-2036
Screen-Printing Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Screen-Printing Glass Market Outlook
A shift from outsourced ceramic-ink formulation to in-house pigment synthesis is hardening among large-format glass processors. Saint-Gobain leverages captive ink laboratories in France to protect recipe intellectual property. Guardian Glass anchors North American supply through integrated float-to-print lines at its Carleton, Michigan facility. PPG Industries competes on automotive windshield contracts where OEMs require batch-to-batch color consistency.
Screen-printing glass applies ceramic frit or organic ink through a mesh stencil onto annealed or tempered substrates, then fires the coating at 600–720°C to fuse durable, UV-stable imagery or functional patterns onto the surface; this process yields spandrel panels, busbar patterns for photovoltaic modules, and anti-glare textures for displays. Flat glass occupies the dominant volume position because architectural project specifications standardize on large rectangular lites that accommodate automated rotary printing. Electronics displays represents the fastest-growing application segment as touch-panel manufacturers adopt fine-line silver-paste screen printing for capacitive sensor grids.
The US EPA oversees volatile organic compound emissions from glass-printing facilities under National Emission Standards for Hazardous Air Pollutants, while the EU REACH regulation restricts cadmium and lead content in ceramic frit pigments. China's GB standards mandate energy-efficiency labeling for building-integrated glazing, directing procurement toward low-emissivity coated glass with printed functional layers. Stakeholders must monitor evolving chemical-substance restrictions and regional building codes to align product portfolios with compliance-driven specification trends.
Market Dynamics
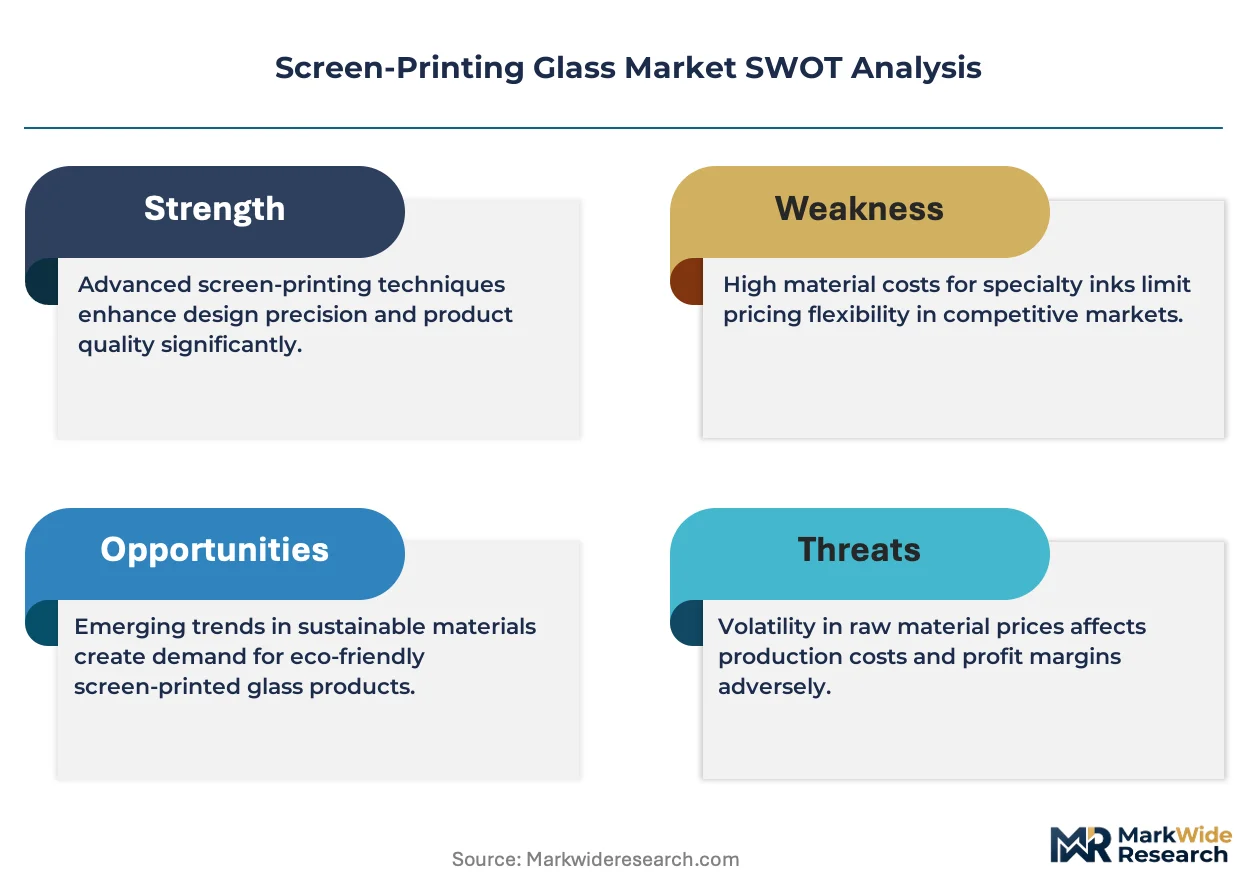
The screen-printing glass market pivots on ceramic-ink formulation secrecy as large processors retreat from external suppliers to captive pigment laboratories, hardening intellectual property moats while compressing third-party ink vendor margins.
Growth Catalysts
- EU Green Deal building renovation targets:The regulation tightens energy-performance standards for glazing assemblies across commercial retrofits, forcing specification upgrades toward solar-control printed glass in Germany and France.
- Touch-panel silver-paste printing:Electronics manufacturers accelerate fine-line screen printing for capacitive sensor grids in smartphones and automotive displays, pulling volume from architectural into electronics applications.
- Passivhaus-certified construction clusters:German builders anchor regional offtake through mandatory high-performance glazing in certified projects, creating concentrated demand pull for low-emissivity printed substrates.
Market Restraints
- Raw material concentration in ceramic frit:Specialty oxide supply chains cluster in Chinese smelting regions, exposing processors to export quota volatility and freight cost spikes.
- REACH cadmium and lead restrictions:ECHA pigment bans force reformulation of red and yellow ceramic frits, extending R&D timelines and qualifying costs for EU-bound production.
- Digital inkjet substitution threat:Drop-on-demand glass printers achieve sub-millimeter resolution without mesh degradation, capturing premium decorative work from rotary screen lines.
Strategic Opportunities
- Building-integrated photovoltaics:Printed busbar patterns for solar glass modules open utility-scale and residential rooftop segments as GB standards mandate energy-efficiency labeling in China.
- Automotive OEM windshield contracts:Batch-to-batch color consistency requirements create specification lock-in for processors with captive ink laboratories serving tier-one glass suppliers.
- Anti-glare texture demand from display manufacturers:Fine-mesh screen printing for matte surface finishes penetrates monitor and television panel production in South Korea and Japan.
Industry Challenges
- Specialized firing technician scarcity:600–720°C kiln operation and thermal profile optimization require skills concentrated in European and Japanese glass processing clusters, limiting greenfield facility staffing.
- Float-to-print line integration complexity:Automated rotary printing on large rectangular lites demands precise substrate handling synchronization, extending commissioning timelines for new capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Screen-Printing Glass Market |
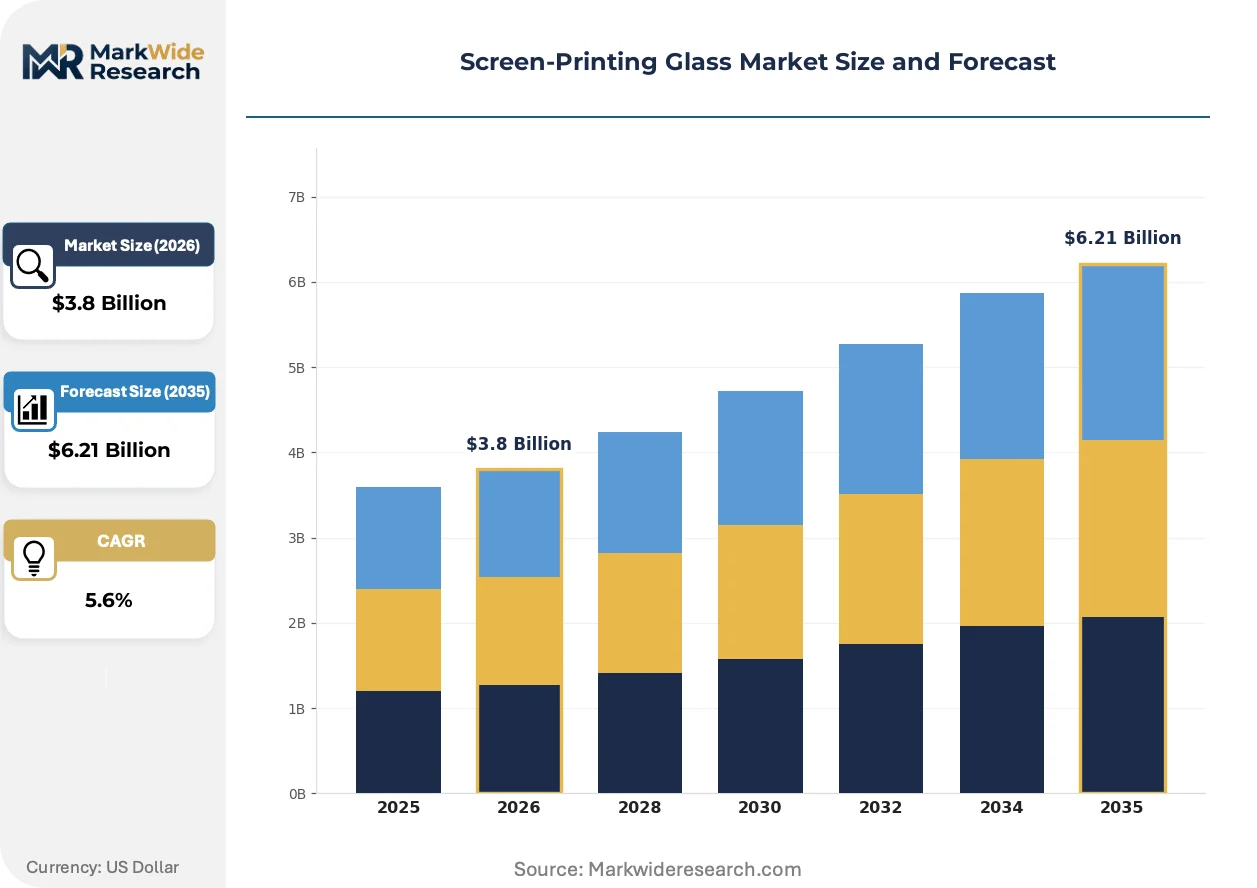
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Glass, Textured Glass, Coated Glass, Laminated Glass End User: Automotive, Packaging, Electronics, Architecture Application: Labels, Signage, Decoratives, Electronics Displays Technology: Digital Printing, Rotary Printing, Manual Printing, Inkjet Printing |
| Companies Covered | Corning Inc., Guardian Glass, Saint-Gobain, Beijing Glass Group, Pilkington NSG Group, PPG Industries, Nippon Sheet Glass Co., Cardinal Glass Industries, AGC Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Screen-Printing Glass Market Strategic Shifts
Ceramic-ink synthesis, regulatory chemical restrictions, and procurement model evolution are restructuring competitive advantage around captive technical capabilities rather than equipment scale alone.
Digital pre-press workflows are decentralizing color separation and stencil preparation from centralized service bureaus to plant-floor inkjet proofing systems. Mid-size architectural glass processors in Italy and Spain adopt on-demand mesh coating to compress job-changeover times from days to hours. This capability diffusion erodes the historical advantage of large-format printers with dedicated pre-press departments.
REACH substance restrictions are forcing pigment substitution roadmaps across European ceramic frit suppliers. Cadmium-based reds and lead-bearing yellows face phase-out deadlines, compelling reformulation toward rare-earth and bismuth vanadate alternatives. German ink laboratories front-load qualification testing to protect automotive windshield color-matching contracts from supply interruption.
Buyer concentration among national construction groups is compressing specification influence toward procurement departments and away from architect-led selection. French and Dutch commercial developers now bundle printed glass into facade system tenders, forcing processors to integrate with curtain-wall contractors rather than sell commodity lites. This channel consolidation rewards processors with project management capabilities and certified installation partnerships.
Screen-Printing Glass Market Segmentation
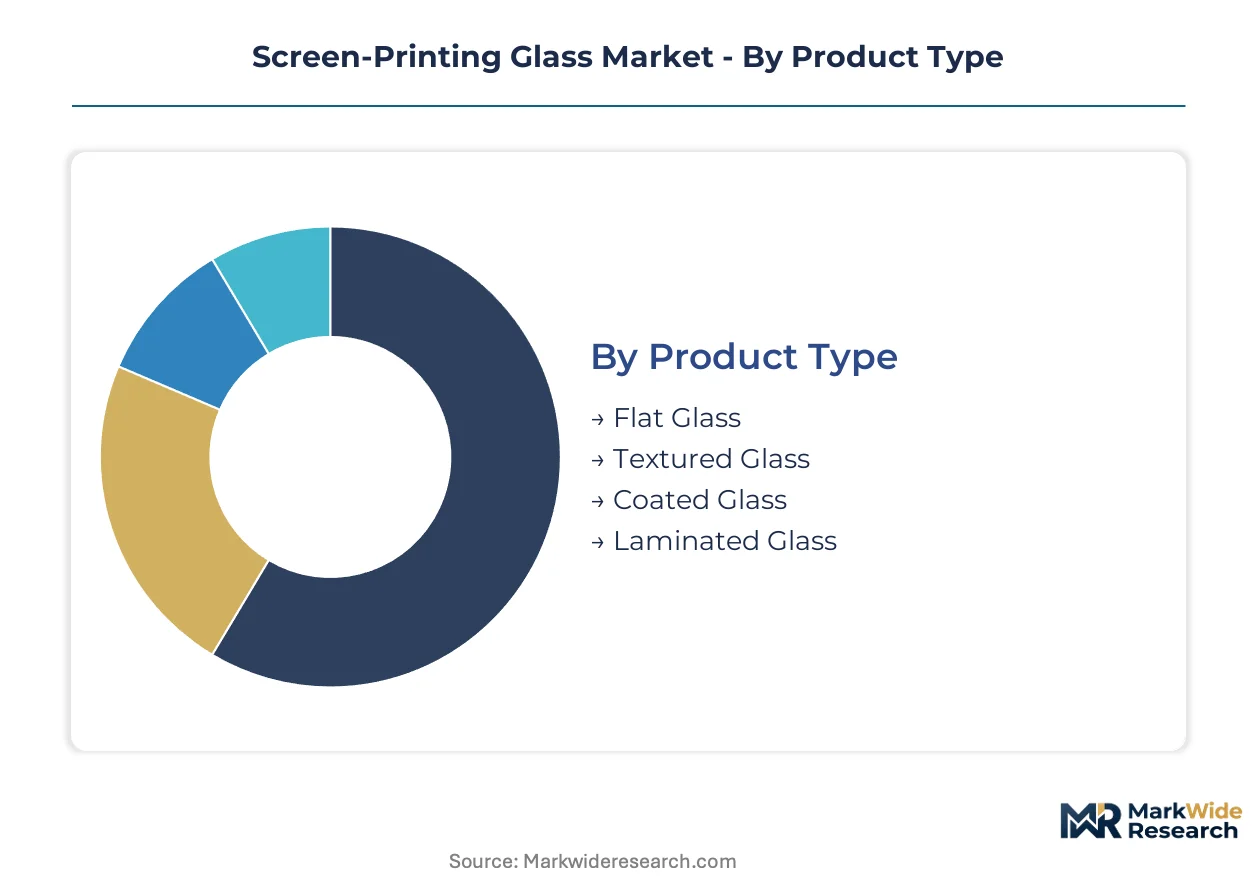
Screen-printing glass markets fragment across substrate geometry, end-use performance requirements, and firing compatibility. Specification-grade segments demand kiln infrastructure investments that commodity categories avoid entirely.
Product Type:
Capital intensity separates segments by firing infrastructure requirements and substrate handling automation.
- Flat Glass:Large rectangular lites dominate architectural specifications for facades and interior glazing. Automated rotary printing lines at integrated float-to-print facilities in Germany and Michigan concentrate volume for Passivhaus-certified commercial projects.
- Coated Glass:Low-emissivity substrates require precise thermal profile control to preserve metallic oxide layers during ceramic frit firing. China's GB standards mandate energy-efficiency labeling for building-integrated glazing, directing procurement toward functional printed layers on coated stock.
- Textured Glass:Patterned substrates serve decorative interior applications with lower firing precision requirements.
- Laminated Glass:Interlayer compatibility constrains ink formulation and firing temperature windows for safety glazing segments.
Flat glass absorbs the bulk of installed capacity; coated glass is expanding most quickly.
End User:
Customer concentration and contract duration determine margin stability across demand sources.
- Automotive:OEM windshield contracts enforce batch-to-batch color consistency through captive ink laboratory relationships. Tier-one glass suppliers in Germany and Japan lock in multi-year specifications that exclude commodity processors.
- Electronics:Touch-panel manufacturers drive fine-line silver-paste printing for capacitive sensor grids in smartphones and automotive displays. South Korean and Japanese display fabs pull volume from architectural applications.
- Architecture:National construction groups in France and the Netherlands bundle printed glass into facade system tenders, compressing specification influence toward procurement departments.
- Packaging:Premium cosmetic and spirits bottles utilize ceramic frit durability for brand differentiation in European markets.
Automotive commands the longest contract durations; electronics is gaining share fastest.
Application:
Resolution requirements and job-changeover frequency separate segments by pre-press workflow investment.
- Electronics Displays:Fine-mesh screen printing achieves sub-millimeter silver-paste lines for capacitive sensor grids. Anti-glare texture demand from South Korean and Japanese monitor manufacturers penetrates television panel production.
- Decoratives:Architectural branding and interior glazing systems require UV-stable imagery with solar-control functional patterns. EU Green Deal renovation targets tighten energy-performance standards across German and French commercial retrofits.
- Signage:Exterior durability specifications favor ceramic frit over organic inks for transit and retail applications.
- Labels:Short-run customization favors digital pre-press workflows and on-demand mesh coating capabilities.
Decoratives holds the largest installed base; electronics displays follows the steepest expansion trajectory.
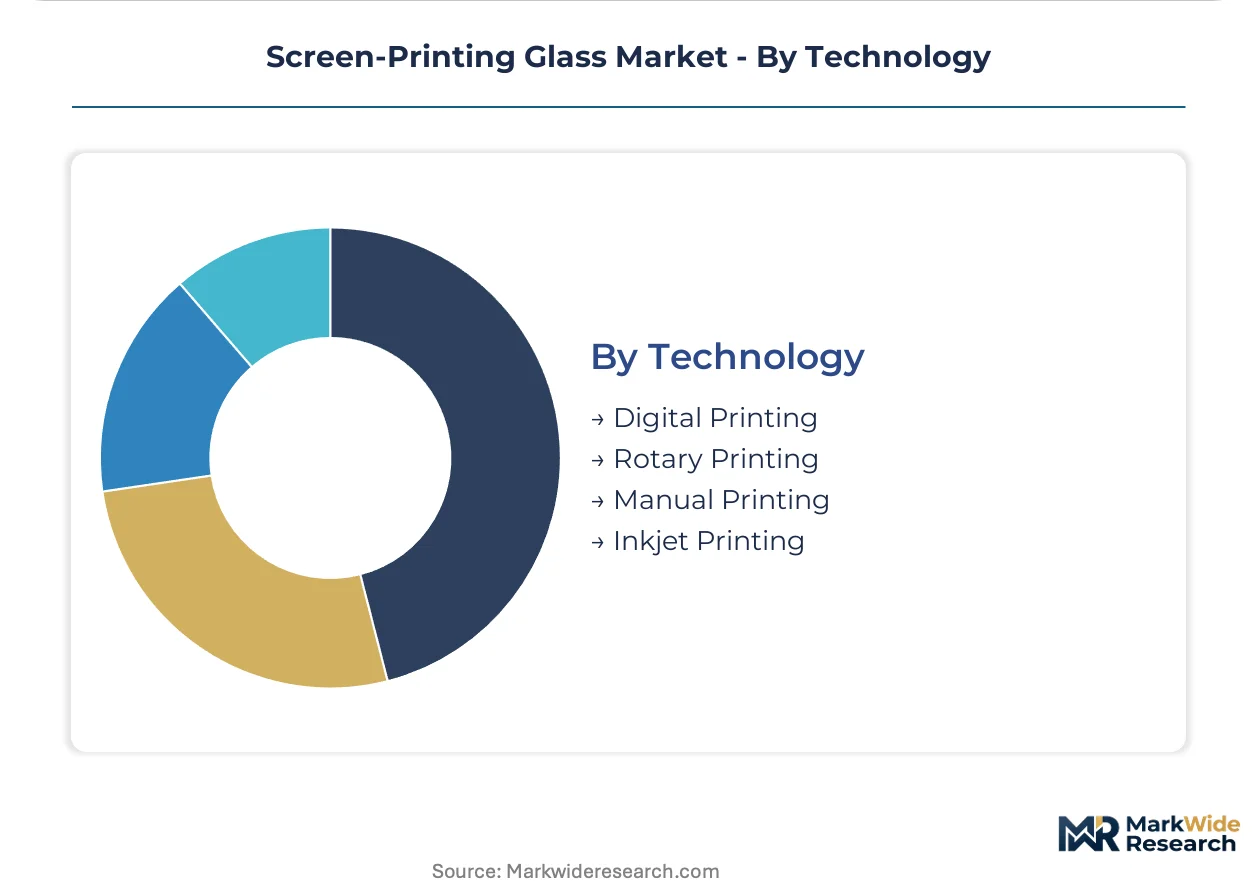
Technology:
Equipment depreciation schedules and technician scarcity constrain technology selection for new capacity.
- Rotary Printing:Automated systems on large rectangular lites synchronize substrate handling with firing kiln throughput. Float-to-print line integration complexity extends commissioning timelines for greenfield facilities.
- Digital Printing:Drop-on-demand glass printers achieve sub-millimeter resolution without mesh degradation, capturing premium decorative work from rotary lines. Mid-size Italian and Spanish processors adopt on-demand mesh coating to compress job-changeover times.
- Inkjet Printing:Organic ink formulations face US EPA volatile organic compound emissions oversight under National Emission Standards for Hazardous Air Pollutants.
- Manual Printing:Artisan and prototype work persists in custom architectural and artistic applications with limited scale.
Rotary printing retains the dominant equipment base; digital printing climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for screen-printing glass clusters in Germany, where Passivhaus-certified construction and automotive OEM contracts concentrate regional offtake. Commercial builders across France, the United States, China, and Japan specify decorative and functional printed glass for branding and solar control applications.
Germany
Passivhaus-certified projects and automotive windshield contracts anchor European demand. The EU Green Deal's building renovation targets tighten energy-performance standards for glazing assemblies across commercial retrofits. Carleton, Michigan-based Guardian Glass maintains integrated float-to-print lines serving German tier-one suppliers.
France
Commercial developers bundle printed glass into facade system tenders, compressing specification influence toward procurement departments. REACH cadmium and lead restrictions force reformulation of red and yellow ceramic frits. Saint-Gobain leverages captive ink laboratories to protect recipe intellectual property for architectural projects.
United States
Automotive OEMs require batch-to-batch color consistency for windshield contracts. The EPA oversees volatile organic compound emissions from glass-printing facilities under National Emission Standards for Hazardous Air Pollutants. PPG Industries competes on specification-grade automotive contracts through captive technical capabilities.
China
GB standards mandate energy-efficiency labeling for building-integrated glazing, directing procurement toward low-emissivity coated glass with printed functional layers. Specialty oxide supply chains cluster in Chinese smelting regions. Beijing Glass Group occupies a position serving domestic construction and electronics display manufacturers.
Japan
Display manufacturers drive fine-line silver-paste screen printing for capacitive sensor grids in smartphones and automotive panels. METI standards influence precision requirements for electronics applications. AGC Inc. and Nippon Sheet Glass Co. exemplify the integrated glass processor archetype serving South Korean and Japanese monitor production clusters.
Screen-Printing Glass Market Competitive Environment
Captive ink laboratory investment dominates the current landscape as large processors retreat from external suppliers to protect formulation intellectual property. The vendor base stratifies across integrated float-to-print operators, specialty ceramic frit synthesizers, and regional job-shop decorators. Three archetypes define positioning: multinational glass manufacturers with captive pigment capabilities, mid-size architectural processors with on-demand mesh coating, and electronics-focused specialists in fine-line silver-paste printing. Competitive moves concentrate on backward integration into ceramic-ink synthesis and strategic partnerships with curtain-wall contractors.
Among multinational integrated manufacturers, Saint-Gobain, Guardian Glass, and PPG Industries exemplify the captive laboratory archetype. Saint-Gobain represents European formulation secrecy through in-house pigment synthesis. Guardian Glass anchors North American supply chain configuration through integrated production assets. PPG Industries occupies a position on automotive specification contracts requiring color consistency protocols. These three entities sit within the premium tier where intellectual property protection and kiln infrastructure create specification lock-in with tier-one customers.
| Leading Market Players |
|---|
| Corning Inc. |
| Guardian Glass |
| Saint-Gobain |
| Beijing Glass Group |
| Pilkington NSG Group |
| PPG Industries |
| Nippon Sheet Glass Co. |
| Cardinal Glass Industries |
| AGC Inc. |
| Others |
Value Chain & Pricing Dynamics
Specialty oxide price indices for cadmium sulfide and lead-bearing pigments cascade through ceramic frit supply chains into three-tier pricing structures across premium, standard, and economy levels. German automotive OEMs absorb premium tier costs for batch-to-batch color consistency, while Chinese building-integrated glazing procurement compresses mid-tier margins under GB standards compliance.
Pricing Analysis
Volume concentrates in flat glass architectural contracts with compressed margins, while margin accretes to electronics display silver-paste printing for capacitive sensor grids. Price differentiation hinges on certification grade—Passivhaus compliance commands premium positioning—and captive ink laboratory ownership. Cost compression in standard architectural tiers intensifies because digital inkjet substitution threatens rotary screen lines. National construction groups in France and the Netherlands exhibit highest price sensitivity through bundled facade system tenders; automotive OEMs in Germany and Japan show lowest sensitivity due to specification lock-in.
Supply Chain Analysis
Dual-sourcing requirements from tier-one automotive glass suppliers mandate multi-supplier qualification for ceramic frit pigments across German, Chinese, and Japanese smelting regions. Raw material dependencies center on rare-earth oxides, bismuth vanadate alternatives, and silver-paste formulations for electronics. Single-source vulnerability concentrates in Chinese specialty oxide clusters exposed to export quota volatility. Distribution runs through integrated float-to-print facilities for architectural volume, while electronics applications feed directly from processor laboratories to South Korean and Japanese display fabs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized firing technician scarcity constrains kiln capacity expansion, propping pricing power for processors with qualified European and Japanese labor pools. This bottleneck sustains margin premiums across specification-grade segments.
For Market Incumbents: Anticipate digital inkjet displacement in decorative architectural applications by accelerating backward integration into rare-earth pigment synthesis before REACH phase-out deadlines. Secure captive ink laboratory capacity in France and Germany to defend automotive color-matching contracts. Channel control through curtain-wall contractor partnerships protects specification influence against procurement department consolidation.
For New Entrants and Emerging Players: The mid-tier price-point gap between Saint-Gobain's premium architectural positioning and Chinese commodity processors creates entry space for Italian and Spanish mid-size operators with on-demand mesh coating capabilities. Target electronics display anti-glare texture production in South Korea and Japan where fine-line silver-paste skills concentrate. Go-to-market through direct relationships with monitor manufacturers bypasses entrenched float-to-print architectural channels.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-size European architectural processors with certified installation partnerships in France and the Netherlands. Long-term viability over the projection horizon rests on regulatory compliance infrastructure—REACH-qualified laboratories and EPA-permitted firing capacity. Watch cadmium and lead pigment substitution timelines as inflection indicators for reformulation cost spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic-Ink Synthesis | Protects recipe intellectual property from REACH-mandated reformulation disruptions. |
| Float-to-Print Line Integration | Automated rotary printing at Guardian Glass's Carleton facility anchors North American supply. |
| Curtain-Wall Contractor Partnerships | French and Dutch developers bundle printed glass into facade tenders, requiring certified installation alliances. |
| Fine-Line Silver-Paste Capability Expansion | South Korean and Japanese display fabs pull volume from architectural into electronics applications. |
| Dual-Chemistry Pigment Laboratory Investment | German ink laboratories front-load rare-earth and bismuth vanadate qualification testing. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with kiln operations managers, automotive glass procurement leads, ceramic frit R&D directors, and curtain-wall contractor project managers combined with secondary validation from EPA National Emission Standards documentation, ECHA REACH substance restriction updates, and Chinese GB standards bulletins. Bottom-up capacity modeling and top-down demand triangulation cross-checked volume estimates.
Granularity-level modeling deployed separate frameworks for substrate geometry, firing compatibility, and end-use performance requirements across the projection horizon. Segmentation dimensions included product type, application resolution requirements, and regional regulatory clusters. CAGRs derived from fitted growth curves applied to base-year market sizing. Industry-specific forecast inputs incorporated Passivhaus certification penetration rates and touch-panel silver-paste consumption trends.
Underlying measurement precision varies by segment; electronics display applications carry tighter precision than commodity architectural lites. Forecasts reflect assumptions around REACH cadmium phase-out timelines and EU Green Deal renovation target achievement. Deviation in Chinese specialty oxide export quotas or firing technician training pipeline expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Recycled Glass Market
Glass
Antibacterial Glass Market
Glass
Glass Tableware Market
Glass
Glazing Gel Market
Glass
Low-E Glass Market
Glass
Europe Silica Sand for Glass Making Market
Glass
Coated Glass Market
Glass
Patterned Glass Market
Glass
Global Anti-Reflective Glass Market
Glass
Glass Lined Equipment Market
Glass
Glass Like Carbon Market
Glass
Middle East and Africa Glassware Market
Glass
Shatterproof Glass Market
Glass
Global Glass Flake Coatings Market
Glass
Latin America Flat Glass Market
Glass
Fiberglass Window Market