
 Solvent Borne Coatings Market | 2026-2036
Solvent Borne Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Solvent Borne Coatings Market Analysis
Automotive OEM refinishing is redrawing demand patterns for solvent borne coatings as commercial construction maintenance budgets tighten. PPG Industries Inc. leverages its captive refinish distribution network across North American collision centers. Akzo Nobel NV anchors European marine protective demand through specialized epoxy formulations for North Sea offshore platforms.
Solvent borne coatings are liquid film-forming systems that use organic solvents as the primary viscosity-reducing carrier, typically containing 30-60% volatile organic compounds by volume, designed to deposit durable protective or decorative layers on metal, wood, and concrete substrates. The alkyd segment occupies mature architectural maintenance channels where cost sensitivity dominates specification decisions. Polyurethane coatings lead automotive clearcoat applications due to superior gloss retention and chemical resistance under hood temperatures. High solids technology is displacing conventional formulations as EPA VOC limits tighten in US industrial finishing operations.
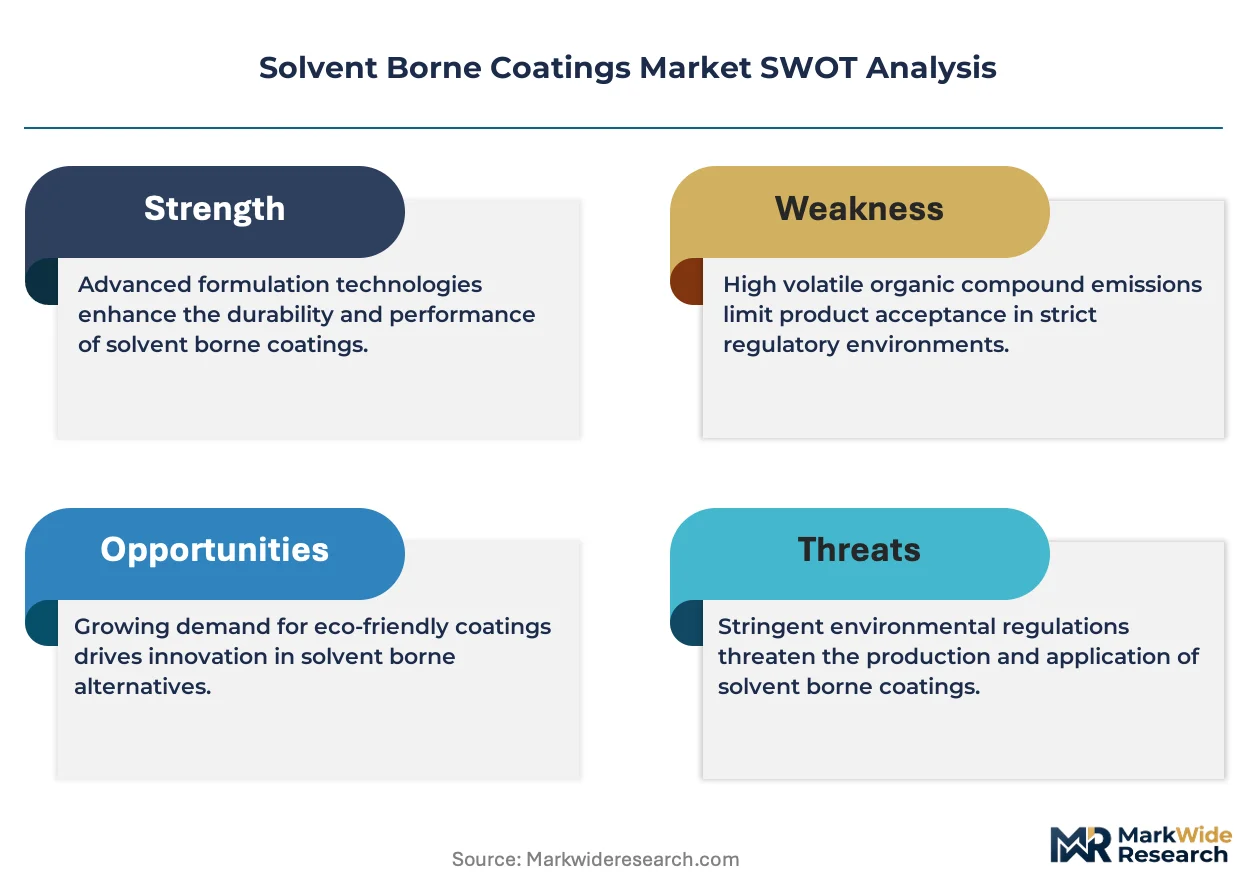
EPA NESHAP standards and EU REACH Annex XVII restrictions on aromatic solvent content are forcing reformulation investments across European and North American manufacturing bases. China's MEE enforces GB standards on industrial coating VOC emissions that determine facility operating permits in Jiangsu and Zhejiang provinces. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded formulation assets and misaligned capacity investments.
Market Dynamics
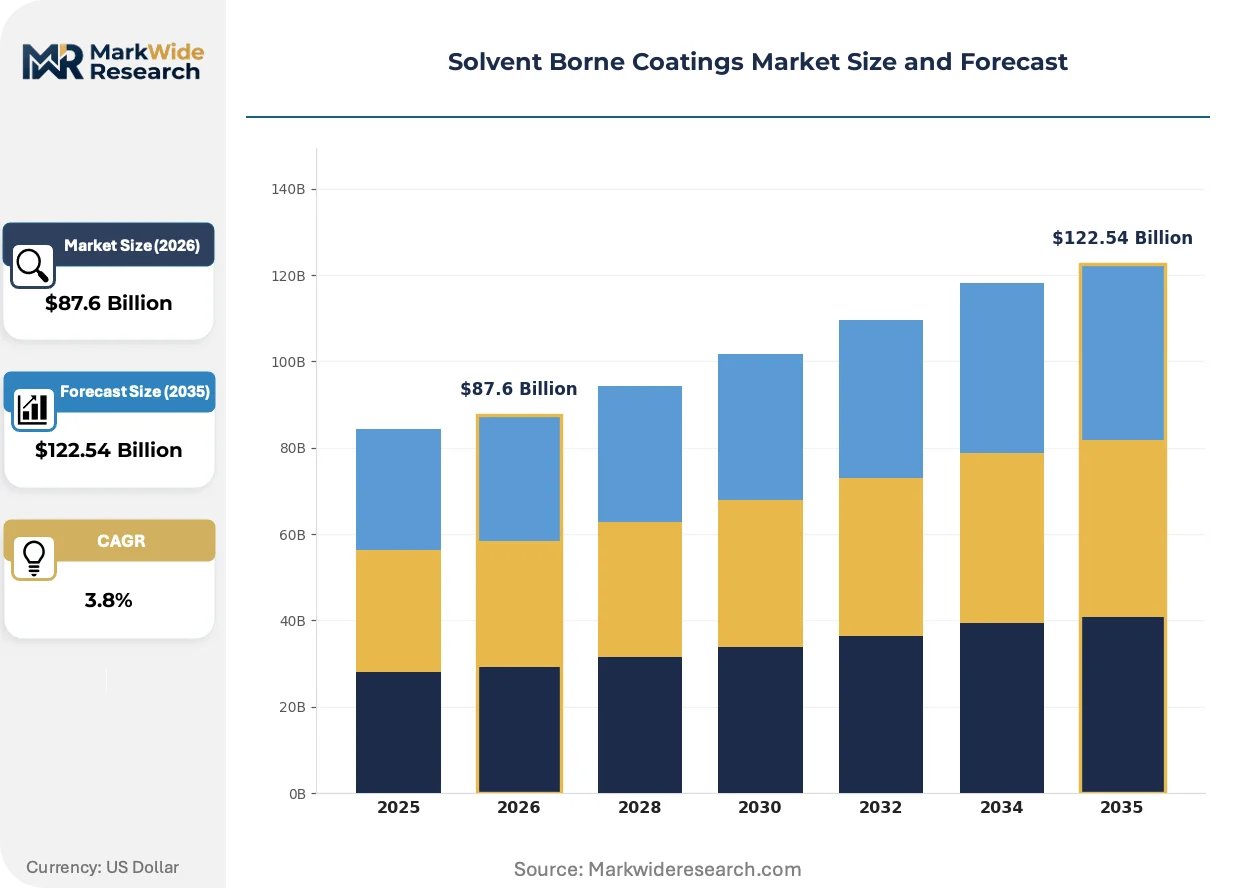
High-solids and water-borne substitution technologies are compressing conventional solvent borne coating volumes as EPA VOC thresholds and EU REACH aromatic restrictions tighten formulation flexibility across industrial finishing operations.
Growth Catalysts
- Automotive OEM refinishing:Collision center networks in the United States and Germany are standardizing polyurethane clearcoat specifications for superior gloss retention under thermal stress.
- REACH Annex XVII:European aromatic solvent restrictions are accelerating compliant epoxy formulation investments for North Sea offshore platform maintenance.
- China's Yangtze River Delta:Industrial corridor concentration in Jiangsu and Zhejiang provinces is driving consolidated procurement for alkyd architectural maintenance channels.
Market Restraints
- Crude oil derivative volatility:Petrochemical feedstock cost swings compress margin predictability for alkyd resin producers serving cost-sensitive maintenance segments.
- Titanium dioxide supply concentration:Pigment sourcing dependence on Chinese sulfate-process capacity creates formulation cost vulnerability for North American industrial coaters.
- Water-borne substitution:Low-VOC acrylic emulsion technology is capturing interior architectural share from conventional solvent borne decorative coatings.
Strategic Opportunities
- India's industrial corridor expansion:Maharashtra and Gujarat manufacturing zones present underpenetrated demand for polyurethane protective systems in metal fabrication.
- GB standards compliance services:China's MEE VOC enforcement creates advisory revenue streams for formulation houses navigating Jiangsu facility permitting.
- UV-curable convergence:Hybrid solvent-UV systems are opening electronics conformal coating applications with instant cure and solvent-based adhesion properties.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in high-solids rheology control and exempt solvent selection is concentrating among aging technical workforces in European coating centers.
- Legacy equipment retrofit costs:Conventional spray booth ventilation and solvent recovery infrastructure requires capital replacement to meet EPA NESHAP capture efficiency mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solvent Borne Coatings Market |
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $122.54 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Alkyd, Epoxy, Polyurethane End User: Automotive, Furniture, Construction, Marine Application: Protective Coatings, Decorative Coatings, Industrial Coatings, Specialty Coatings Technology: Conventional, High Solids, Water-Reduced, UV-Curable |
| Companies Covered | Sherwin-Williams Company, RPM International Inc., BASF SE, Jotun Group, Valspar Corporation, Akzo Nobel NV, Axalta Coating Systems Ltd., Nippon Paint Holding Co. Ltd., PPG Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solvent Borne Coatings Market Emerging Trajectories
Reformulation chemistry and application equipment are converging to preserve solvent borne performance advantages while compressing VOC emissions profiles across regulated industrial finishing environments.
High-solids alkyd technology is miniaturizing the solvent fraction in decorative maintenance coatings while preserving brushability and open time. North American architectural contractors are adopting these systems for metal door and trim applications where water-borne alternatives fail on adhesion. The technology is miniaturizing conventional low-solids volume demand in US residential repainting channels.
EPA NESHAP standards for hazardous air pollutants are mandating capture and control equipment upgrades across US automotive and industrial finishing operations. These rules are accelerating booth replacement cycles and favoring coating houses with integrated application engineering capabilities. The collision repair segment is responding with consolidated purchasing agreements that bundle compliant coatings with ventilation system packages.
Specification authority is migrating from general contractors to facility maintenance managers with direct accountability for coating lifecycle costs. Industrial asset owners in Germany's chemical processing belt are unbundling coating procurement from construction contracts to secure technical service continuity. This pattern is most visible in Bavaria and North Rhine-Westphalia where plant engineering departments retain dedicated coating specification engineers.
Solvent Borne Coatings Market Segmentation
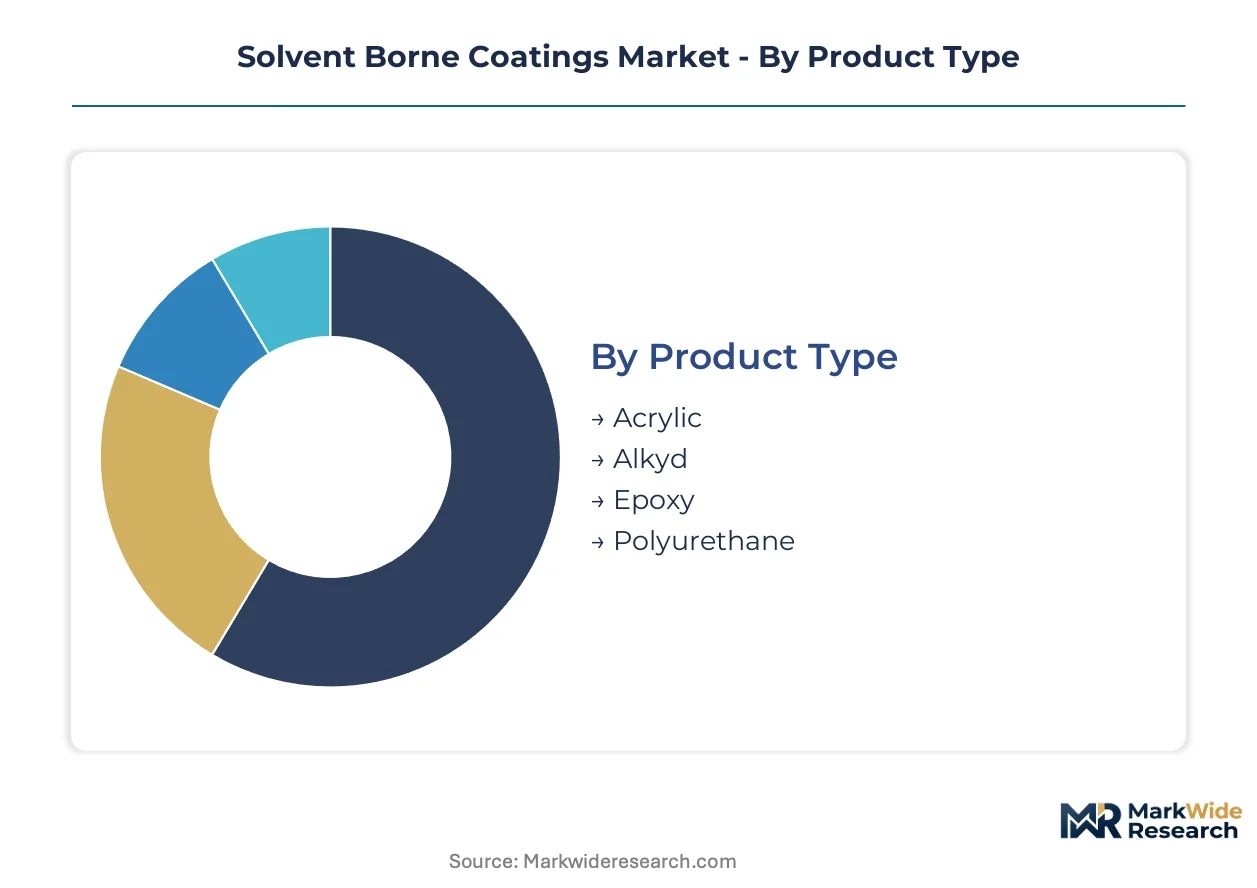
Solvent borne coatings segmentation reveals how formulation chemistry, end-use durability requirements, and regulatory compliance layers interact to determine profitability. Margin pools concentrate where VOC thresholds force premium high-solids conversions and where automotive clearcoat specifications demand polyurethane performance.
Product Type:
Margin concentration follows resin chemistry sophistication, with polyurethane and epoxy commanding premium positions over commodity alkyds.
- Polyurethane:Two-component isocyanate-cured systems deliver superior gloss retention and chemical resistance for automotive clearcoats. Collision centers in Germany and the United States are standardizing these specifications under thermal stress from under-hood temperatures, compressing alkyd alternatives in refinishing channels.
- Epoxy:Amine-cured bisphenol-A formulations provide exceptional adhesion and corrosion resistance for marine and industrial protective applications. North Sea offshore platform maintenance drives concentrated demand in Norway and the United Kingdom as REACH aromatic restrictions force compliant formulation investments.
- Acrylic:Thermoplastic and thermosetting acrylic resins serve decorative and automotive basecoat applications where UV stability matters.
- Alkyd:Oil-modified polyester resins dominate cost-sensitive architectural maintenance channels with mature, price-competitive supply.
The dominant share belongs to alkyd systems, while polyurethane is closing the gap fastest through automotive specification upgrades.
End User:
Application durability requirements and regulatory exposure separate high-value protective segments from commoditized decorative demand.
- Automotive:OEM and refinish operations require coatings surviving thermal cycling, stone chip impact, and fuel exposure. China's Yangtze River Delta manufacturing clusters are consolidating procurement for foreign-brand joint venture plants, while EPA NESHAP capture mandates reshape US collision center supplier relationships.
- Marine:Immersion service and atmospheric zone protection for hulls, decks, and offshore structures demand specialized epoxy and polyurethane systems. North Sea platform operators in Norway and the United Kingdom unbundle coating procurement from construction contracts to secure technical service continuity.
- Construction:Architectural maintenance and industrial building applications span metal, concrete, and wood substrates with varying VOC compliance timelines.
- Furniture:Decorative wood finishing for residential and commercial interiors faces water-borne substitution pressure from low-VOC acrylic emulsions.
Automotive applications retain the largest revenue pool, with marine protective systems gaining share fastest through offshore infrastructure aging.
Application:
Functional performance specifications determine pricing power, with protective and specialty layers commanding premiums over decorative alternatives.
- Protective Coatings:Heavy-duty systems preventing corrosion and chemical attack on industrial assets. Germany's chemical processing belt in Bavaria and North Rhine-Westphalia drives specification authority migration to facility maintenance managers with lifecycle cost accountability.
- Industrial Coatings:OEM finishing for machinery, appliances, and transportation equipment requiring consistent film build and cure schedules.
- Decorative Coatings:Aesthetic film-forming for architectural surfaces where cost sensitivity dominates and water-borne alternatives erode solvent share.
- Specialty Coatings:Electronics conformal coatings, high-temperature systems, and other niche applications where hybrid solvent-UV technology opens instant-cure opportunities.
Protective coatings hold the dominant position, while specialty applications are expanding most quickly through electronics miniaturization demands.
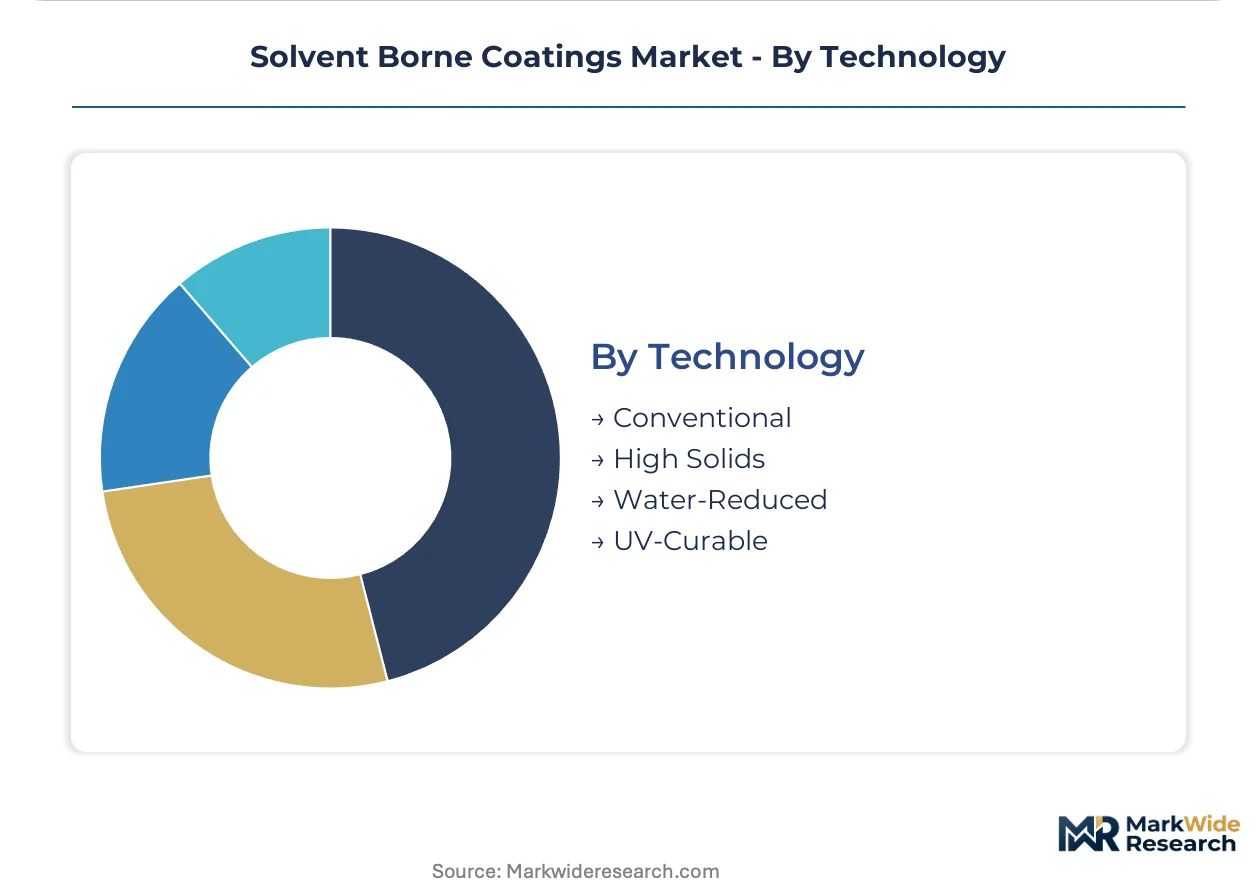
Technology:
Regulatory pressure intensity and capital equipment requirements stratify technology tiers, with high-solids and UV-curable systems capturing investment focus.
- High Solids:Formulations with solvent content reduced to 20-30% by volume while maintaining application properties through oligomeric resin design. US industrial finishing operations are adopting these systems to meet EPA VOC limits without full water-borne conversion costs.
- UV-Curable:Hybrid solvent-UV systems combining solvent-based adhesion with instant photoinitiated cure for electronics conformal coating and wood finishing. Japan's electronics manufacturing clusters are piloting these systems for throughput advantages.
- Conventional:Traditional low-solids formulations facing volume compression from regulatory thresholds across all major jurisdictions.
- Water-Reduced:Intermediate technology using co-solvent and water blends, serving as a transition pathway for some industrial applications.
Conventional technology retains installed-base volume leadership, though high-solids systems are gaining share fastest through EPA and REACH compliance deadlines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEM refinishing demand concentrates procurement authority among collision center networks and industrial facility managers across four major manufacturing jurisdictions. REACH and EPA thresholds compress formulation flexibility differently in each market, reshaping supplier relationships.
United States
Collision center consolidation drives polyurethane clearcoat standardization through multi-shop purchasing agreements. EPA NESHAP mandates accelerate booth replacement cycles favoring bundled coating-ventilation packages. The Great Lakes automotive belt concentrates refinish demand around Detroit and Chicago manufacturing corridors.
Germany
Bavaria and North Rhine-Westphalia chemical processing plants unbundle coating procurement from construction contracts to secure technical service continuity. REACH Annex XVII aromatic restrictions force compliant epoxy formulation investments for North Sea offshore platform maintenance. Hamburg anchors marine protective specification authority.
China
GB standards enforcement by MEE determines facility operating permits in Jiangsu and Zhejiang provinces. The Yangtze River Delta industrial corridor consolidates procurement for foreign-brand automotive joint ventures. Shanghai and Suzhou manufacturing clusters drive alkyd architectural maintenance volume.
Japan
Electronics conformal coating demand pilots hybrid solvent-UV systems in Kanto manufacturing clusters. METI industrial standards shape high-solids adoption timelines for machinery OEM finishing. Nagoya automotive suppliers standardize polyurethane specifications for thermal stress resistance.
India
Maharashtra and Gujarat manufacturing zones present underpenetrated demand for polyurethane protective systems in metal fabrication. BIS certification requirements create formulation advisory opportunities for multinational coating houses. Mumbai-Pune industrial corridor concentrates automotive supplier coating procurement.
Solvent Borne Coatings Market Vendor Landscape
Player mix skews toward integrated multinational chemical conglomerates with captive resin production and specialized regional formulators serving protective coating niches. Tiered structure separates premium polyurethane clearcoat suppliers from commodity alkyd producers. Strategic archetypes include automotive refinish specialists, marine protective formulators, and architectural maintenance suppliers. Competitive moves concentrate on high-solids technology licensing and regional compliance service expansion.
Among North American integrated suppliers, PPG Industries Inc. and Sherwin-Williams Company represent the collision center distribution archetype, while Akzo Nobel NV exemplifies European marine protective specialization. BASF SE anchors the chemical conglomerate tier with captive resin integration. These three occupy positions spanning automotive OEM, industrial protective, and architectural maintenance specification channels.
| Leading Market Players |
|---|
| Sherwin-Williams Company |
| RPM International Inc. |
| BASF SE |
| Jotun Group |
| Valspar Corporation |
| Akzo Nobel NV |
| Axalta Coating Systems Ltd. |
| Nippon Paint Holding Co. Ltd. |
| PPG Industries Inc. |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Chinese titanium dioxide sulfate-process plants shapes both pigment cost floors and formulation pricing power across North American industrial coaters. Scale concentration in Jiangsu and Zhejiang resin manufacturing clusters compresses margin recovery for smaller alkyd producers serving cost-sensitive architectural maintenance channels.
Pricing Analysis
Cost-plus contracts with crude oil derivative indexation dominate alkyd resin procurement between European formulators and petrochemical suppliers. Price differentiation rests on VOC compliance tier and high-solids conversion certification, with EPA NESHAP-compliant systems commanding premiums over conventional formulations. Pricing pressure stems from water-borne acrylic emulsion substitution in interior architectural segments. Cost-sensitive maintenance contractors exhibit highest price sensitivity, while automotive collision centers prioritize performance over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies prevail among German automotive OEMs, whereas North Sea offshore platform operators maintain strategic stockpiles of REACH-compliant epoxy systems. Supply concentrates in China, Germany, and the United States for resin manufacturing and formulation. Raw material dependencies include crude oil derivatives, titanium dioxide pigment, and isocyanate curing agents. Tariff exposure on Chinese sulfate-process TiO2 creates formulation cost vulnerability. Distribution runs through captive refinish networks and specialized industrial distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solvent borne coatings market functions as a defensive-moat industry where regulatory entrenchment around EPA NESHAP and REACH compliance creates durable switching costs for approved suppliers.
For Market Incumbents: Consolidate collision center distribution relationships through bundled coating-ventilation packages that lock in EPA NESHAP compliance workflows. Acquire high-solids formulation expertise in European technical centers where chemist scarcity concentrates. Water-borne substitution technology poses the primary threat to conventional volume. Vertical integration into captive resin production secures margin control against petrochemical feedstock volatility. For New Entrants and Emerging Players: Differentiate on GB standards advisory services for Jiangsu and Zhejiang facility permitting under MEE enforcement. Target India's Maharashtra and Gujarat manufacturing zones for polyurethane protective systems penetration. White-space opportunities concentrate in electronics conformal coating hybrid solvent-UV applications. Go-to-market positioning should emphasize compliance navigation over commodity formulation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors high-solids specialists with integrated application engineering capabilities over conventional formulation houses. Long-term viability hinges on regulatory compliance service revenue streams and automotive refinish network control. Acquisition targets should demonstrate EPA or REACH certification entrenchment with collision center or industrial facility relationships. The signal to watch is MEE enforcement intensity accelerating Chinese domestic consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| High-Solids Capacity Expansion | EPA NESHAP compliance deadlines force conversion investments across US industrial finishing operations. |
| Backward Integration into Resin Manufacturing | Captive alkyd and polyurethane resin production insulates margin from crude oil derivative volatility. |
| GB Standards Compliance Services | MEE VOC enforcement in Jiangsu creates recurring advisory revenue from facility permitting navigation. |
| Collision Center Network Acquisition | Consolidated refinish distribution locks in polyurethane clearcoat specification authority. |
| Hybrid Solvent-UV Technology Licensing | Electronics conformal coating applications in Japan's Kanto clusters reward instant-cure throughput advantages. |
Methodological Framework
Cross-validation between primary field interviews and secondary trade data anchors the qualitative findings in this analysis. Conversations with plant managers at coating manufacturing facilities, procurement leads at automotive OEMs, technical R&D directors at resin suppliers, and distribution channel partners informed demand-side and supply-side dynamics. Secondary validation drew from EPA NESHAP regulatory filings, ECHA REACH registration databases, ACC and Cefic industry reports, and customs trade data on titanium dioxide and petrochemical feedstock flows. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Sensitivity analysis around VOC regulatory enforcement timelines and crude oil price scenarios tested forecast robustness. The analytical framework modeled volume and value across resin chemistry tier, end-use industry, application durability requirement, and regional regulatory cluster. CAGRs derived from segment-level growth rate reconciliation with macroeconomic drivers. Industry-specific forecast inputs included collision center network expansion rates and offshore platform maintenance cycle intensity.
Decision-makers should treat outputs as directional under sustained EPA and REACH enforcement assumptions; material deviation in regulatory stringency would warrant model refresh. Forecasts reflect bottom-up demand aggregation and supply-side capacity assessments. Specific revision triggers include MEE enforcement intensity exceeding baseline scenarios or water-borne technology performance breakthroughs in automotive clearcoat applications. Revision becomes warranted when water-borne substitution rates in architectural segments cross thresholds that compress solvent borne volume assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Marine Deck Coatings Market
Coatings
Functional Coil Coating Market
Coatings
Noise and Vibration Coatings Market
Coatings
Plastic-Coated Wires Market
Coatings
Mold Release Coatings Market
Coatings
Stain Resistance Coatings Market
Coatings
Superhydrophobic Coatings Market
Coatings
Soft Touch Polyurethane Coatings Market
Coatings
Clear Coatings Market
Coatings
Vacuum Coating Machine Market
Coatings
Plasma Impulse Chemical Vapor Deposition (PICVD) Coating Market
Coatings
Protective and Marine Coatings Market
Coatings
Technical Coil Coatings Market
Coatings
Self-Healing Microcapsule Systems for Protective Coatings Market
Coatings
Dispersion Coating Market
Coatings
Global Anti-Smudge Coatings Market