
 Anti-Microbial Powder Coatings Market | 2026-2036
Anti-Microbial Powder Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Microbial Powder Coatings Market Outlook
Multi-source procurement of active biocide additives is shifting toward vertically integrated resin-compounding operations. AkzoNobel NV leverages captive silver-ion supply chains to secure formulation consistency across European healthcare projects. PPG Industries Inc. anchors its position through North American distribution networks serving medical device OEMs. Nippon Paint Holdings Co., Ltd. specializes in hybrid epoxy-polyester systems tailored to Japanese hospital hygiene standards.
Anti-microbial powder coatings are thermoset finishes incorporating inorganic biocides such as silver ions, copper compounds, or zinc pyrithione into a resin matrix, then applied electrostatically and cured at 160-200°C to form a durable, sanitizable surface barrier. The primary commercial purpose is to suppress microbial colonization on high-touch substrates in environments requiring continuous hygienic performance without repeated chemical disinfection. Epoxy formulations dominate medical device and food processing equipment applications due to superior chemical resistance and adhesion to metal substrates. Polyester and hybrid systems lead furniture and HVAC specifications where UV stability and cost efficiency outweigh maximum biocidal potency. Acrylic variants occupy emerging niches requiring optical clarity or low-temperature cure compatibility.
The EPA regulates biocide claims under FIFRA, requiring substantiated efficacy data before manufacturers market anti-microbial performance, while FDA device coatings face additional biocompatibility scrutiny through ISO 10933 testing protocols. REACH restrictions on certain organic biocides in Europe are accelerating silver-ion and copper-based formulation migration, with ECHA evaluations determining acceptable migration thresholds for food-contact applications. Stakeholders must monitor evolving registration requirements across multiple jurisdictions while validating long-term biocidal durability against emerging resistant strains.
Market Dynamics
EPA registration requirements under FIFRA are compressing formulation windows for organic biocides while silver-ion and copper-additive chemistries capture specification share in healthcare and food-contact applications.
Growth Catalysts
- Joint Commission sanitation protocols:US healthcare facility managers are expanding procurement of antimicrobial-protected surfaces to meet accreditation standards for high-touch environments.
- German hospital renovation programs:Industrial kitchen upgrades and certified antimicrobial finish specifications are concentrating demand in Western European healthcare infrastructure.
- Hybrid epoxy-polyester systems:Japanese hospital hygiene standards are driving formulation innovation for environments requiring both chemical resistance and UV stability.
Market Restraints
- Silver-ion raw material concentration:Supply chain vulnerability exists where captive mining and refining operations cluster in limited geographic corridors.
- REACH migration threshold compliance:ECHA evaluations for food-contact applications impose testing burdens that extend commercialization timelines for new formulations.
- High-temperature cure infrastructure:Capital requirements for 160-200°C curing ovens exclude smaller metal fabrication shops from specification pools.
Strategic Opportunities
- HVAC specification expansion:Antimicrobial powder coatings are penetrating ventilation system components where continuous sanitizable surfaces reduce maintenance cycles.
- ISO 10993 biocompatibility pathways:FDA device coating approvals create regulated entry points for medical device OEM supply chains.
- Low-temperature acrylic variants:Optical clarity requirements in electronics and display manufacturing are opening formulation niches incompatible with standard thermoset systems.
Industry Challenges
- Biocide efficacy validation against resistant strains:Long-term durability testing protocols must demonstrate sustained antimicrobial performance under real-world wear conditions.
- Multi-jurisdiction registration synchronization:Formulators face divergent EPA, ECHA, and PMDA data requirements that fragment product development roadmaps.
- Electrostatic application technician certification:Skilled labor gaps in powder coating booth operations constrain capacity expansion for specialized antimicrobial formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Microbial Powder Coatings Market |
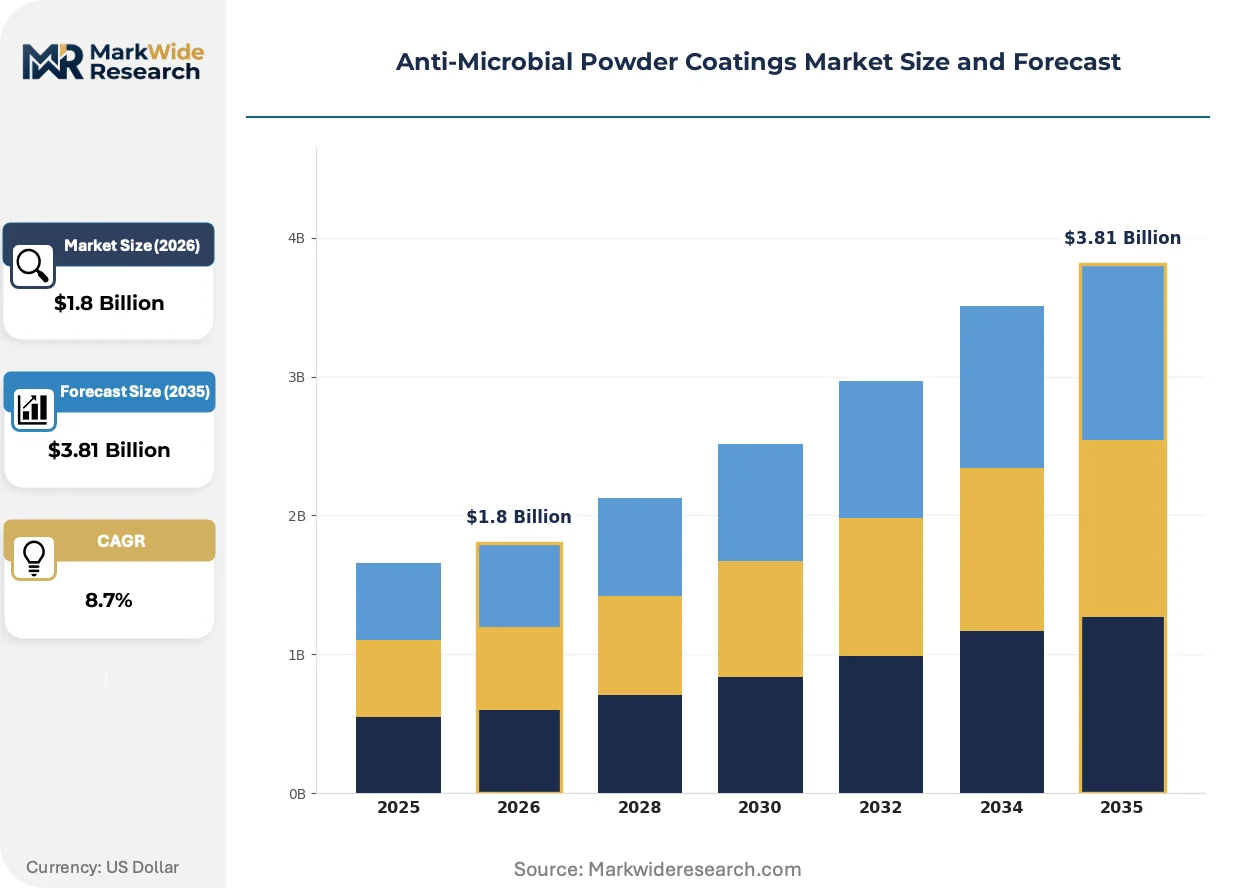
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyester, Hybrid, Acrylic Application: Medical Devices, Food Processing Equipment, HVAC Systems, Furniture Formulation: Water-Based, Solvent-Based, UV-Cured, Powder Coated End User: Healthcare, Food Industry, Construction, Automotive |
| Companies Covered | AkzoNobel NV, The Sherwin-Williams Company, PPG Industries Inc., Axalta Coating Systems, Diamond Vogel, Berger Paints India Limited, RPM International Inc., Nippon Paint Holdings Co., Ltd., Jotun Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Microbial Powder Coatings Market Strategic Shifts
Formulation chemistry and application infrastructure are undergoing parallel transformation as regulatory pressure and end-use specification complexity reshape competitive requirements.
Silver-ion dispersion technology is converging with nanostructured carrier systems to achieve controlled release rates in medical device coatings. Orthopedic implant manufacturers are specifying these hybrid formulations for instruments requiring both biocompatibility and sustained antimicrobial protection. The structural consequence is compression of organic biocide market share as inorganic alternatives demonstrate superior durability under sterilization cycles.
REACH restrictions on certain organic biocides are accelerating migration toward copper-based and silver-ion alternatives across European food-contact applications. ECHA evaluations determining acceptable migration thresholds are forcing reformulation investments before legacy chemistries lose authorization. Medical device and industrial kitchen equipment segments are responding with preemptive specification changes to avoid supply discontinuity.
Specification-driven procurement is consolidating around certified antimicrobial finishes with documented efficacy data rather than commodity powder coatings with unverified claims. Healthcare facility managers and food processing equipment buyers are demanding third-party validation as a gatekeeper criterion. This pattern is most visible in German hospital renovation programs and US Joint Commission-accredited facilities where surface hygiene protocols carry liability implications.
Anti-Microbial Powder Coatings Market Segmentation
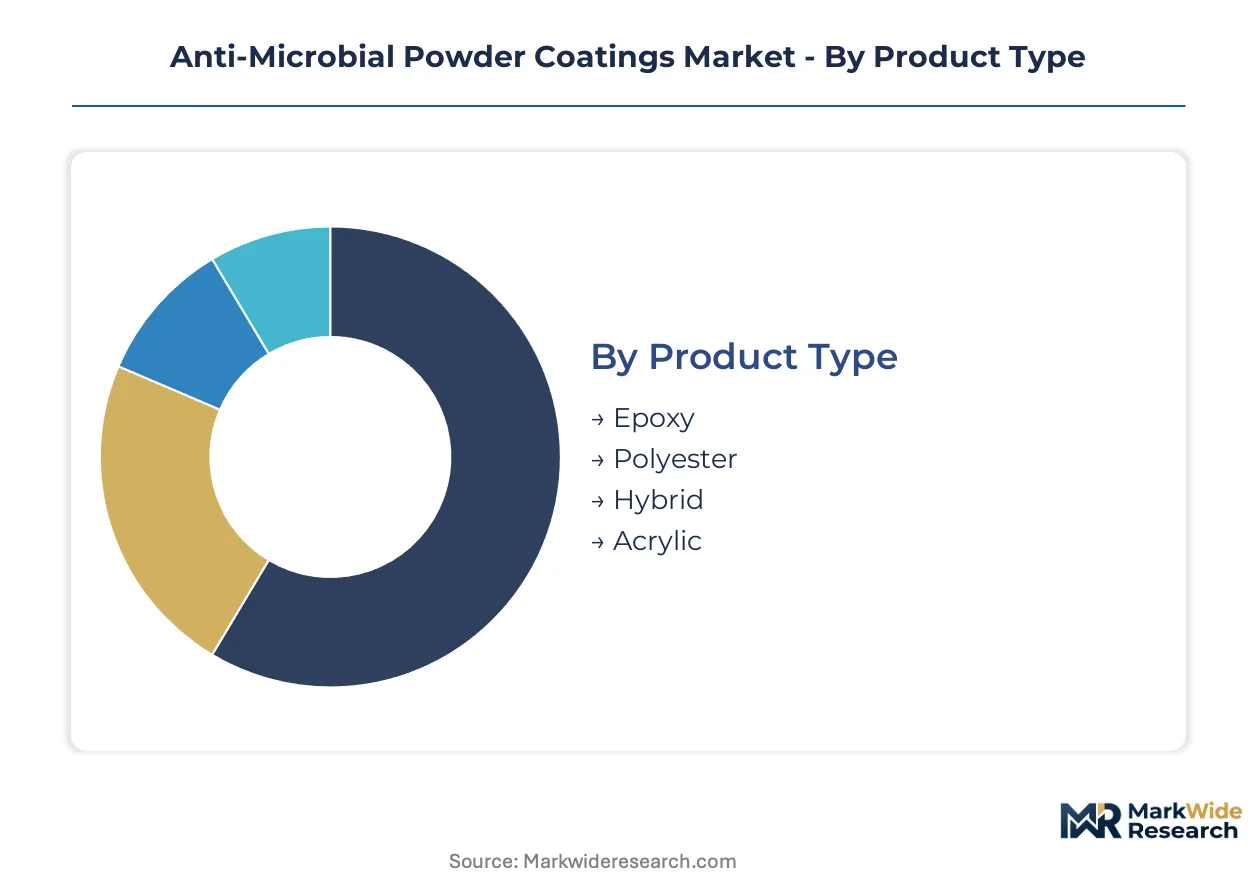
Anti-microbial powder coatings fragment across multiple technical and commercial dimensions that determine specification pathways and margin structures. Each segmentation axis carries distinct regulatory burdens, application requirements, and supply chain configurations that shape competitive positioning.
Product Type:
Epoxy formulations function as standalone protective systems requiring no substrate pretreatment beyond standard cleaning, while hybrid and acrylic variants embed within multi-layer coating architectures demanding precise intercoat compatibility.
- Epoxy:Thermoset systems built from bisphenol-A and bisphenol-F resins deliver maximum chemical resistance and substrate adhesion for medical device sterilization environments. German hospital renovation programs specify epoxy finishes for surgical instrument cabinets and patient room fixtures where repeated disinfection cycles degrade lesser formulations.
- Polyester:TGIC-free and HAA-cured variants dominate outdoor furniture and architectural metalwork where UV stability determines service life. US healthcare facility managers specify polyester systems for exterior handrails and emergency department entrance hardware exposed to weathering and high-touch traffic.
- Hybrid:Epoxy-polyester combinations balance chemical resistance with gloss retention for food processing equipment requiring both sanitation durability and aesthetic maintenance.
- Acrylic:Low-temperature cure compatibility and optical clarity serve electronics enclosures and display manufacturing where standard thermoset systems damage heat-sensitive substrates.
Volume placements concentrate in epoxy; the faster expansion belongs to acrylic.
Application:
Medical device coatings carry ISO 10993 biocompatibility certification costs that exclude commodity suppliers, while HVAC and furniture applications compete on throughput and color-matching speed.
- Medical Devices:Implantable instrument coatings demand silver-ion dispersion in nanostructured carrier systems achieving controlled release rates under sterilization. FDA device coating approvals through ISO 10993 pathways create regulated entry barriers that compress organic biocide market share.
- Food Processing Equipment:Industrial kitchen upgrades across Western Europe specify REACH-compliant copper-additive formulations with documented migration thresholds. ECHA evaluations for food-contact applications extend commercialization timelines but secure long-term authorization security.
- HVAC Systems:Ventilation component coatings reduce maintenance cycles through continuous sanitizable surfaces in high-occupancy buildings.
- Furniture:Healthcare seating and workstation frames prioritize scratch resistance and color stability over maximum biocidal potency.
Medical device coatings command premium pricing; HVAC systems are climbing the fastest as building ventilation hygiene gains regulatory attention.
Formulation:
Water-based systems compete on VOC compliance in regulated environments, while powder coated architectures dominate where durability and edge coverage outweigh application speed.
- Water-Based:Liquid dispersions of silver-ion additives serve applications where substrate size or geometry prevents electrostatic powder application. EPA FIFRA registration requirements apply equally to liquid and powder biocide claims, creating parallel compliance burdens.
- Solvent-Based:Declining specification share reflects tightening VOC regulations across US states and European member countries.
- UV-Cured:Rapid cure chemistry enables heat-sensitive substrate protection where thermal exposure risks component damage.
- Powder Coated:Electrostatic application and 160-200°C thermal cure form the dominant architecture for metal substrates in healthcare and food processing infrastructure.
Powder coated placements dominate current volumes; water-based alternatives are expanding most quickly in retrofit and field-application scenarios.
End User:
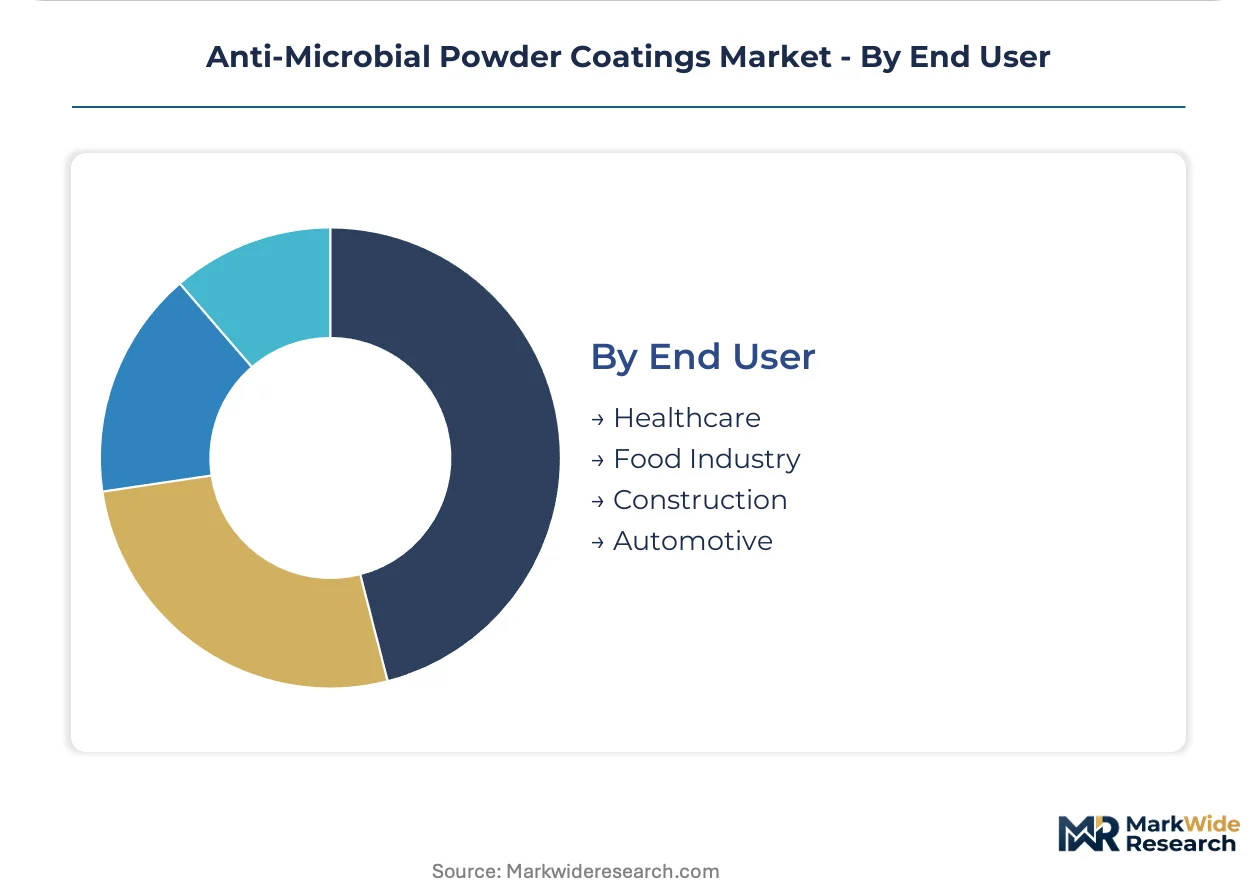
Healthcare procurement operates through group purchasing organizations demanding documented efficacy data, while food industry buyers prioritize migration compliance and construction specifications emphasize weathering performance.
- Healthcare:Joint Commission sanitation protocols drive specification of certified antimicrobial finishes with third-party validation. US hospital facility managers require substantiated efficacy data as gatekeeper criteria for high-touch surface procurement.
- Food Industry:Industrial kitchen equipment manufacturers preemptively reformulate toward copper-based and silver-ion alternatives to avoid REACH authorization discontinuity for legacy organic biocides.
- Construction:Architectural metalwork and infrastructure components specify UV-stable polyester systems for exterior durability.
- Automotive:Interior trim and HVAC ducting applications represent emerging specification territory where antimicrobial claims differentiate supplier offerings.
Healthcare captures the largest revenue concentration; automotive represents the steepest expansion trajectory as cabin hygiene becomes a competitive feature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in healthcare infrastructure hubs where regulatory pressure on surface hygiene intersects with capital renovation cycles. Hospital procurement managers in high-income markets specify certified antimicrobial finishes with documented efficacy data. Industrial kitchen equipment manufacturers preemptively reformulate toward compliant chemistries ahead of authorization deadlines.
United States
Joint Commission sanitation protocols drive specification of antimicrobial-protected surfaces in high-touch healthcare environments. EPA registration requirements under FIFRA compress formulation windows for organic biocides while validating silver-ion alternatives. Medical device OEMs in the Minneapolis-St. Paul corridor and Boston metro anchor North American demand for biocompatible coating systems.
Germany
Hospital renovation programs and industrial kitchen upgrades concentrate demand for REACH-compliant antimicrobial finishes. ECHA evaluations on migration thresholds for food-contact applications force reformulation investments before legacy chemistries lose authorization. The Rhine-Ruhr industrial cluster hosts specification activity for certified finishes in healthcare infrastructure and food processing equipment.
Japan
Hospital hygiene standards drive formulation innovation for hybrid epoxy-polyester systems balancing chemical resistance and UV stability. PMDA oversight of medical device coatings creates regulated entry barriers that favor established suppliers with biocompatibility validation. The Kanto region around Tokyo anchors demand for orthopedic implant instrument coatings requiring sustained antimicrobial protection.
China
Healthcare infrastructure expansion and food safety enforcement accelerate procurement of antimicrobial surface treatments. GB standards and SAMR oversight of coating imports shape specification criteria for domestic and foreign suppliers. The Yangtze River Delta manufacturing corridor concentrates production capacity for powder coating resins and electrostatic application equipment.
India
Hospital accreditation expansion and industrial food processing growth create specification opportunities for antimicrobial finishes. CDSCO oversight of medical device coatings and FSSAI food-contact requirements impose parallel compliance burdens on suppliers. The Maharashtra-Gujarat industrial belt hosts metal fabrication clusters adopting powder coating infrastructure for healthcare and food equipment.
Anti-Microbial Powder Coatings Market Competitive Environment
Backward integration into captive biocide supply chains dominates the current landscape as formulators secure formulation consistency against raw material volatility. The vendor base organizes around three strategic tiers: multinational coating conglomerates with healthcare certification portfolios, regional specialists in food-contact compliant systems, and commodity powder suppliers pivoting toward validated antimicrobial claims. Scale-driven capacity expansion and geographic licensing partnerships represent the primary competitive vectors as players defend specification position in regulated end-use segments.
Among European-headquartered coating conglomerates, AkzoNobel NV and Axalta Coating Systems exemplify the integrated model combining resin compounding with captive silver-ion supply chains. PPG Industries Inc. anchors the North American tier through distribution networks calibrated to medical device OEM procurement cycles. These three occupy positions where regulatory validation investments create defendable specification corridors in healthcare and food processing infrastructure.
| Leading Market Players |
|---|
| AkzoNobel NV |
| The Sherwin-Williams Company |
| PPG Industries Inc. |
| Axalta Coating Systems |
| Diamond Vogel |
| Berger Paints India Limited |
| RPM International Inc. |
| Nippon Paint Holdings Co., Ltd. |
| Jotun Group |
| Others |
Value Chain & Pricing Dynamics
Silver spot price volatility cascades through antimicrobial powder coating supply chains into three distinct pricing tiers: premium biocompatible formulations for medical devices, mid-tier REACH-compliant systems for food processing, and economy-grade architectural finishes where specification pressure remains weakest.
Pricing Analysis
High-volume epoxy formulations for healthcare infrastructure operate on thin margins, while specialized acrylic variants for electronics command substantial premiums due to low-temperature cure compatibility and optical clarity requirements. Price differentiation hinges on ISO 10993 certification tier and captive silver-ion supply chain ownership. Cost compression in economy-grade polyester systems is intensifying as commodity powder suppliers enter antimicrobial segments with unverified claims. Hospital procurement managers through group purchasing organizations exhibit lowest price sensitivity; small metal fabrication shops excluded from high-temperature cure infrastructure face highest cost barriers.
Supply Chain Analysis
Dual-sourcing requirements from German hospital renovation programs and US Joint Commission-accredited facilities mandate qualified backup suppliers for silver-ion and copper-additive biocides. Raw material concentration centers on Mexico for captive mining operations, Germany for resin compounding infrastructure, and Japan for nanostructured carrier systems. Formulation dependencies include bisphenol-A resins, HAA-cured polyester powders, and electrostatic application equipment. Single-source vulnerability persists where ECHA migration threshold evaluations delay authorization for new biocide chemistries. Distribution runs through regional coating distributors serving medical device OEM corridors in Minneapolis-St. Paul and Boston metro areas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EPA FIFRA registration requirements and REACH authorization timelines erect barrier-to-entry moats favoring incumbents with validated biocide portfolios and existing regulatory dossiers.
For Market Incumbents: Acquire captive silver-ion refining capacity to secure formulation consistency against raw material volatility and preempt supply discontinuity risks from REACH authorization lapses. Deepen hospital system partnerships through group purchasing organization contracts that embed long-term specification lock-in. Prioritize ISO 10993 biocompatibility pathway investments to defend medical device coating margins against emerging hybrid epoxy-polyester specialists. For New Entrants and Emerging Players: Regional distributors serving HVAC retrofit markets represent the most accessible channel partner type for bypassing incumbent-dominated healthcare procurement. White-space concentration exists in low-temperature acrylic variants for electronics manufacturing where standard thermoset systems damage heat-sensitive substrates. Target automotive interior trim applications where antimicrobial claims differentiate supplier offerings but regulatory validation burdens remain lighter than medical device tiers. For Investors and Strategic Acquirers: The window for entry favors coating specialists with existing EPA FIFRA registrations and demonstrated ECHA compliance track records over pure-play biocide suppliers lacking formulation integration. Long-term viability hinges on backward integration into resin compounding and captive biocide supply chains rather than additive-only business models. Monitor ECHA evaluation timelines for legacy organic biocides as the critical inflection signal determining reformulation investment cycles and acquisition premium justification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silver-Ion Supply | Captive refining secures formulation consistency against Mexico mining corridor volatility. |
| ISO 10993 Biocompatibility Certification | FDA device coating approvals create regulated entry barriers for medical device OEM supply chains. |
| REACH-Compliant Formulation Migration | Preemptive copper-additive and silver-ion investments avoid authorization discontinuity for legacy organic biocides. |
| HVAC Specification Expansion | Ventilation component coatings reduce maintenance cycles in high-occupancy buildings requiring continuous sanitizable surfaces. |
| Low-Temperature Acrylic Development | Optical clarity requirements in electronics manufacturing open formulation niches incompatible with standard thermoset cure profiles. |
Study Parameters
Independent corroboration across EPA registration databases, ECHA authorization filings, and hospital procurement contract records underwrites the qualitative findings in this study. Primary interviews with coating formulators, medical device OEM procurement leads, hospital facility managers, and industrial kitchen equipment manufacturers combined with secondary validation from SEC 10-K filings, customs trade data, and Joint Commission sanitation protocol documentation. Bottom-up volume estimates from electrostatic application equipment installations and top-down cross-checks against resin compounding capacity data establish analytical triangulation.
Comparable-period anchoring to historical biocide registration cycles and hospital renovation program timelines structured the forecast window across the projection horizon. Segmentation modeling incorporated product type, application, formulation chemistry, and end-use industry dimensions alongside regional regulatory cluster differentiation. CAGRs derived from weighted average growth assumptions across healthcare infrastructure expansion, food safety enforcement intensity, and HVAC specification penetration rates. Silver-ion raw material cost trajectories and REACH authorization timeline probabilities served as industry-specific forecast inputs.
Caveats apply where ECHA migration threshold evaluation delays, EPA FIFRA registration backlog expansions, or emergence of biocide-resistant microbial strains could materially shift the outlook. Forecasts reflect assumptions regarding sustained regulatory pressure on surface hygiene protocols and continued capital availability for high-temperature cure infrastructure investments. Deviation in silver supply concentration or REACH authorization discontinuity timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
US Antifouling Yacht Coatings Market
Coatings
Global Flat Glass Coatings Market
Coatings
Marine Coatings Market
Coatings
Anti-Microbial Nano Coatings Market
Coatings
Acrylic Protective Coating Market
Coatings
Paper Coating Binders Market
Coatings
Global Powder Coating Market
Coatings
Radiation Curable Coatings Market
Coatings
Coatings Raw Materials Market
Coatings
Corrosion Protection Coating Market
Coatings
United States Automotive OEM Coatings Market
Coatings
Global Floor Coatings Market
Coatings
ASEAN Protective Coatings Market
Coatings
Asia-Pacific Automotive Refinish Coatings Market
Coatings
North America Superhydrophobic Coating Market
Coatings
France Protective Coatings Market