
 Asia-Pacific Electronic Gadgets Insurance Market | 2026-2036
Asia-Pacific Electronic Gadgets Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Electronic Gadgets Insurance Market Outlook
Premium-tier coverage is bifurcating the Asia-Pacific electronic gadgets insurance landscape. Samsung Premium Care leverages its manufacturing scale to bundle protection at point of sale across Southeast Asian markets. Allianz Insurance competes through standalone commercial policies that anchor corporate fleet deployments in Australia and Japan. Syska Gadget Secure specializes in retail-affinity models that dominate Indian metro electronics chains.
Asia-Pacific electronic gadgets insurance constitutes risk-transfer instruments covering repair, replacement, or financial indemnity for portable consumer electronics, typically triggered by accidental damage, theft, liquid ingress, or component failure beyond standard manufacturer warranty periods. These products incorporate deductible tiers, depreciation schedules, and claims-fulfillment SLAs measured in hours or days. Smartphone coverage leads premium volume given replacement costs and breakage frequency, while wearables represent the fastest-growing product segment as fitness-tracker and smartwatch penetration deepens. Extended warranty coverage commands the most stable margin pool due to predictable actuarial profiles, whereas accidental damage policies absorb higher claims volatility.
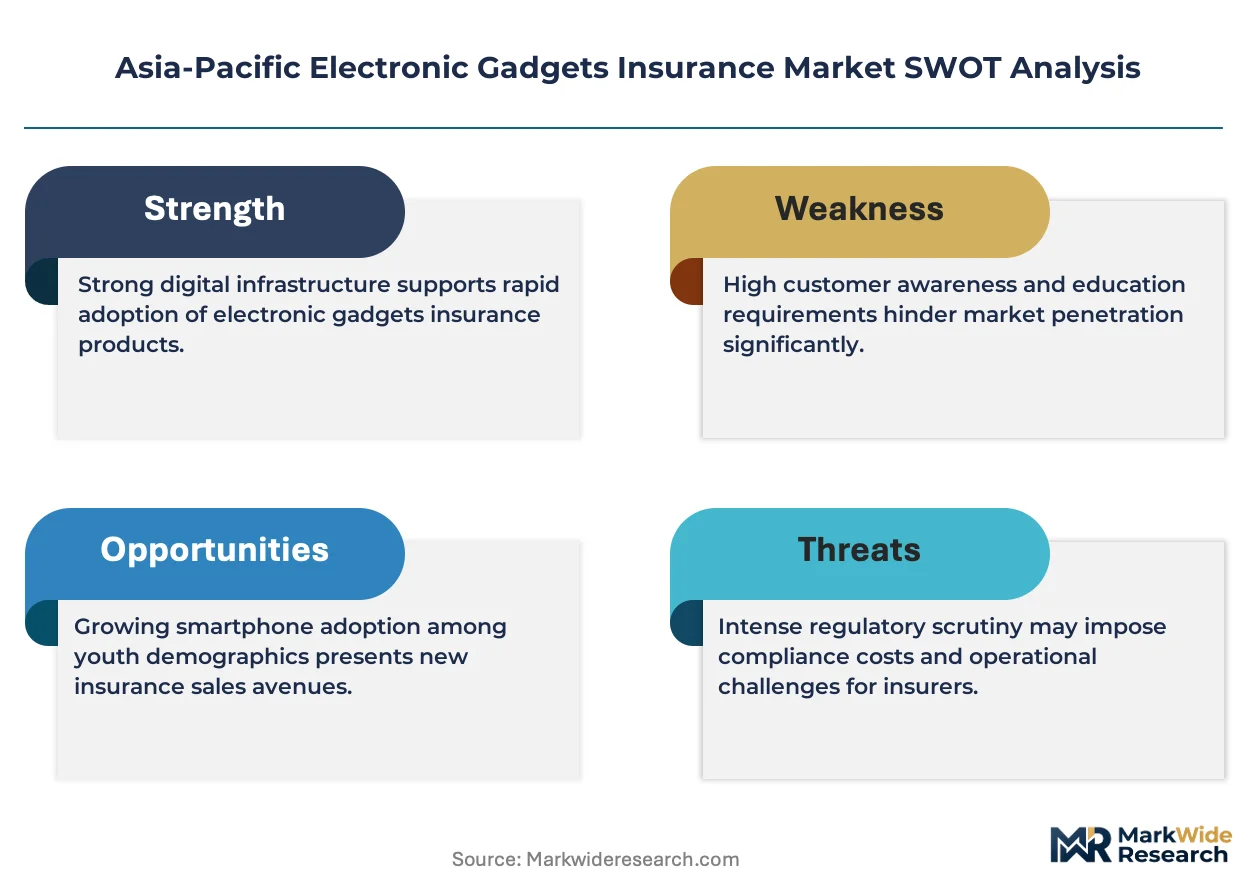
India's IRDAI governs product filing and consumer protection standards for gadget policies, while Australia's ASIC enforces disclosure regimes under the Corporations Act that shape distributor compliance costs. Japan's FSA applies solvency requirements to gadget underwriters writing mobile-device policies through carrier partnerships. Stakeholders must monitor how India's BIS certification mandates for refurbished parts affect claims-fulfillment economics and customer retention.
Market Dynamics
India's Production-Linked Incentive scheme for electronics manufacturing is compressing device replacement cycles and elevating insurance attach rates across the region's largest addressable market.
Growth Catalysts
- PLI scheme acceleration:India's electronics manufacturing subsidies expand device penetration and create parallel demand for protection products in tier-2 and tier-3 urban centers.
- Gig economy smartphone dependency:Southeast Asian delivery and ride-hailing platforms generate concentrated risk pools among device-dependent workers seeking breakage coverage.
- Refurbished parts certification:India's BIS mandates for certified replacement components improve claims-fulfillment reliability and reduce customer churn.
Market Restraints
- Claims volatility concentration:Accidental damage policies absorb unpredictable loss frequency from liquid ingress and screen fractures, compressing underwriting margins.
- Depreciation schedule disputes:Policyholders in Australia challenge carrier-calculated residual values under ASIC disclosure requirements, elevating dispute-resolution costs.
- Component supply bottlenecks:Semiconductor lead times for specialized smartphone parts extend claims settlement windows beyond contracted SLAs.
Strategic Opportunities
- Wearables protection white space:Fitness-tracker and smartwatch penetration across South Korea and Japan outpaces dedicated coverage product development.
- Carrier-embedded distribution:Japan's FSA-supervised mobile network partnerships enable point-of-activation policy attachment with minimal acquisition friction.
- Corporate fleet commercialization:Enterprise device deployments in Australian logistics and healthcare sectors remain underpenetrated by standalone commercial policies.
Industry Challenges
- Actuarial data scarcity:Limited historical claims experience for foldable smartphone form factors complicates premium pricing and reserve adequacy.
- Cross-border fulfillment complexity:Policy servicing across Southeast Asian markets with divergent consumer protection regimes strains operational infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Electronic Gadgets Insurance Market |
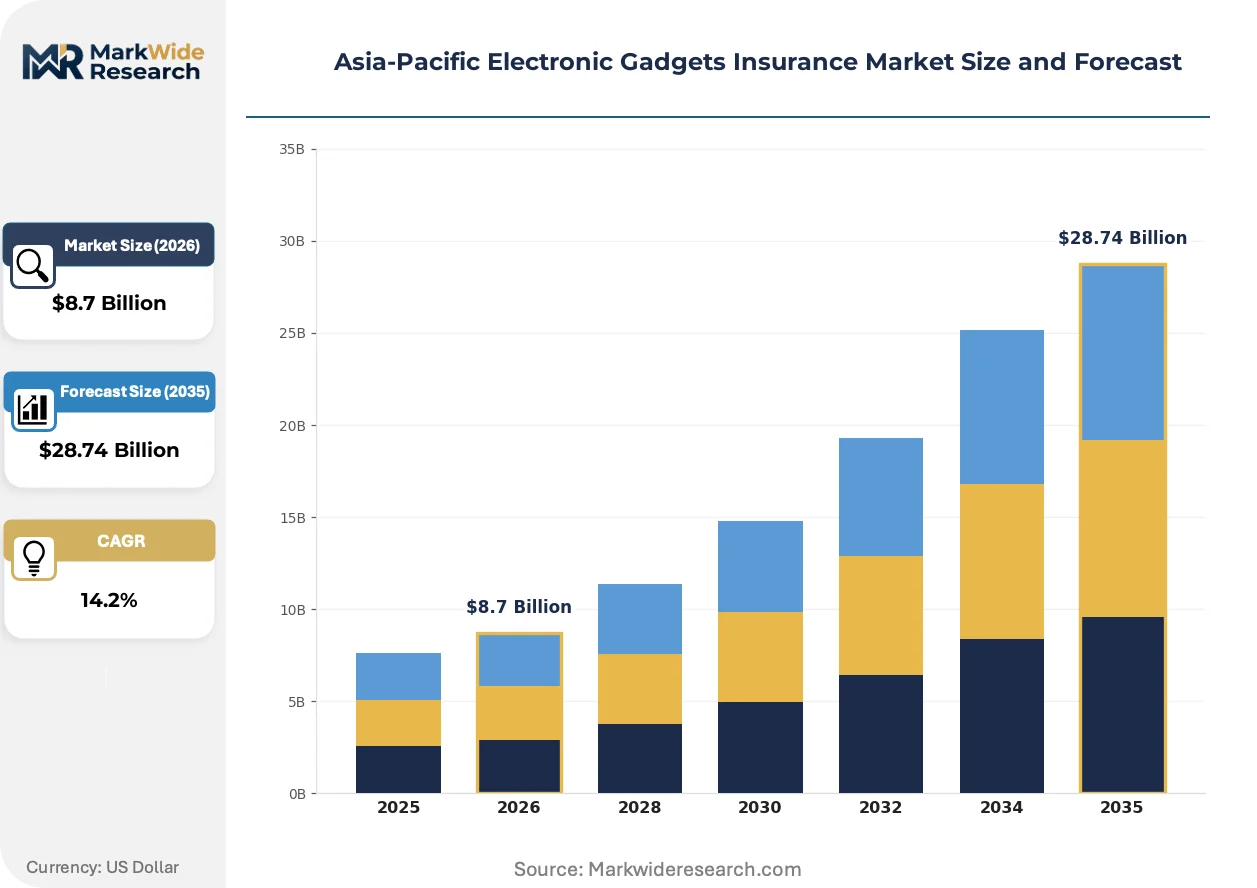
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Laptops, Tablets, Wearables Coverage Type: Accidental Damage, Theft, Liquid Damage, Extended Warranty End User: Consumers, Businesses, Educational Institutions, Nonprofits Distribution Channel: Online, Retail, Direct, Affinity Partnerships |
| Companies Covered | Apple Care+, Samsung Premium Care, Safeware, Syska Gadget Secure, Warranty Asia, The Digital Insurer, Allianz Insurance, Gadget Cover, Brightstar Corp., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Electronic Gadgets Insurance Market Strategic Shifts
Embedded insurance distribution is displacing standalone retail channels across the Asia-Pacific gadget protection landscape, compressing customer acquisition costs while elevating carrier dependency on OEM and telecom partnerships.
AI-powered claims triage is fragmenting traditional loss assessment workflows. Computer vision algorithms now evaluate device damage from customer-submitted imagery, reducing claims cycle times from days to hours. Australian carriers and Japanese mobile network operators deploy these systems at scale, compressing operational expenditure while enabling real-time settlement authorization that was previously impossible.
India's IRDAI has tightened product filing requirements for gadget policies, mandating standardized disclosure formats and cooling-off periods that extend product development timelines. The regulatory friction elevates compliance costs for new market entrants while favoring established underwriters with dedicated regulatory affairs infrastructure. Domestic Indian carriers with existing IRDAI relationships capture disproportionate share of newly approved product categories.
Subscription-based protection models are displacing one-time extended warranty purchases in metro Indian electronics retail. Retail chains in Mumbai, Delhi, and Bangalore bundle monthly protection fees with device financing, converting upfront margin into recurring revenue streams. This shift compresses customer lifetime value visibility while reducing price sensitivity at point of sale.
Asia-Pacific Electronic Gadgets Insurance Market Segmentation
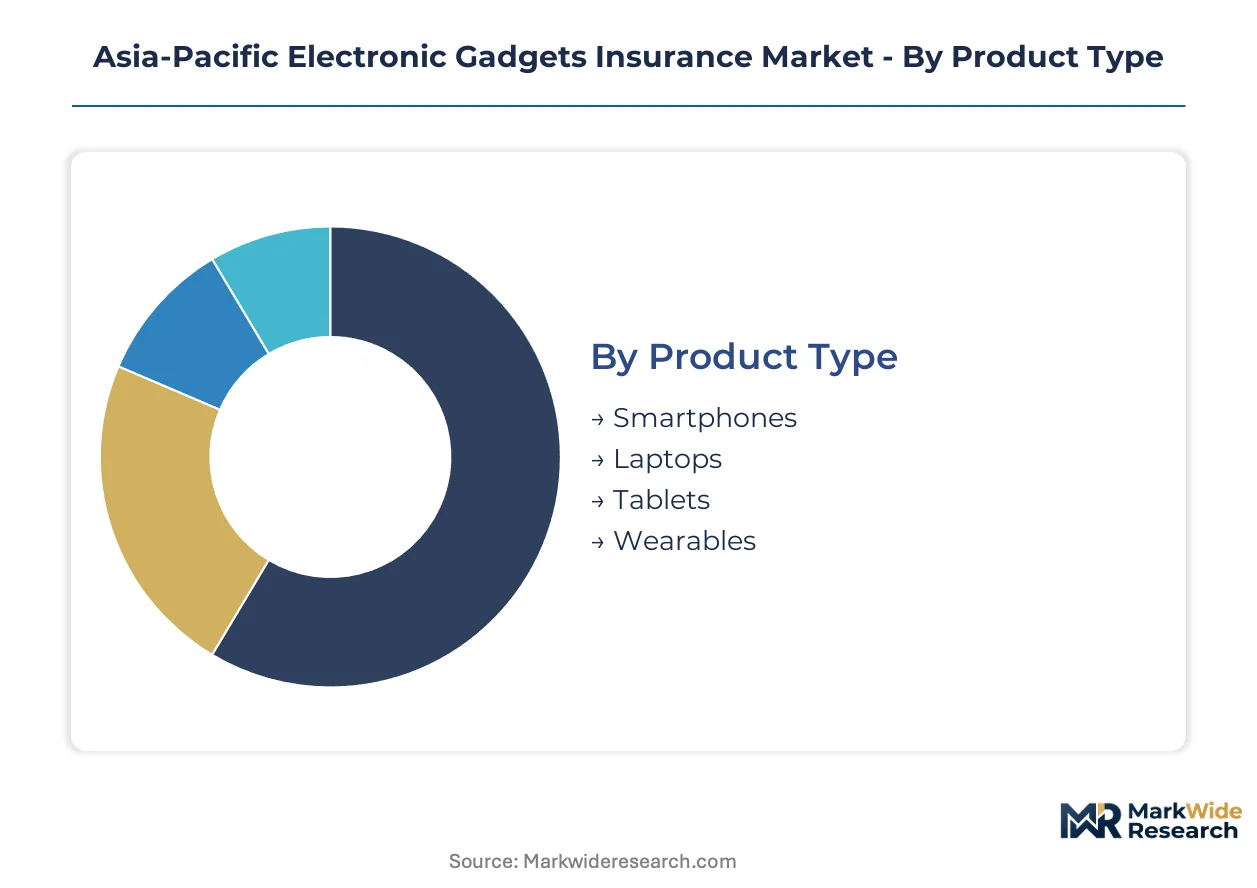
Segmentation in Asia-Pacific electronic gadgets insurance reveals how risk profiles, distribution economics, and customer acquisition costs vary across device categories and buyer types. Underwriters calibrate pricing models and claims reserves differently for each segment, with smartphone coverage commanding distinct actuarial treatment compared to emerging wearables lines.
Product Type:
Margin pools concentrate most densely in high-frequency breakage categories where replacement costs justify premium loading, while emerging device formats present pricing opacity that compresses near-term underwriting returns.
- Smartphones:Screen fracture and liquid ingress dominate claims frequency, with foldable form factors introducing actuarial uncertainty due to limited historical loss data. Demand clusters heaviest in Indian metro corridors where urban replacement cycles compress and protection-plan uptake accelerates among gig-economy workers dependent on device functionality.
- Wearables:Fitness-tracker and smartwatch coverage absorbs lower per-incident severity but exhibits climbing attach rates as South Korean and Japanese penetration deepens. Premium volume remains constrained by device price points, though recurring subscription models in Tokyo and Seoul retail chains are converting one-time warranty purchases into sustained revenue streams.
- Laptops:Commercial fleet deployments in Australian logistics and healthcare sectors drive structured policy demand with predictable loss patterns.
- Tablets:Educational procurement in Indian tier-2 cities generates seasonal volume spikes aligned with academic calendar purchasing.
The dominant share belongs to Smartphones, while Wearables is closing the gap fastest.
Coverage Type:
Cost tier differentiation separates stable-margin extended warranty pools from volatile accidental damage lines where claims frequency fluctuates with seasonal humidity and urban crime patterns.
- Extended Warranty:Manufacturer defect coverage beyond standard terms delivers the most predictable actuarial profiles with minimal claims volatility. Australian carriers favor this structure under ASIC disclosure regimes that penalize opaque depreciation schedules, while Japanese underwriters embed these policies through METI-supervised carrier partnerships with minimal friction.
- Accidental Damage:Screen fractures, impact damage, and operational failure from drops absorb the highest loss frequency and compress underwriting margins. Indian regulators through IRDAI mandate standardized cooling-off periods for these policies, elevating compliance costs while protecting consumer recourse against disputed claim denials.
- Theft:Coverage concentrates in Southeast Asian urban centers where device-dependent gig workers face elevated loss exposure during delivery operations.
- Liquid Damage:Humidity-related ingress claims spike during monsoon seasons across Indian coastal metros, requiring seasonal reserve adjustments.
Extended Warranty captures the steadiest margin flow, though Accidental Damage generates the largest gross premium volume despite its volatility burden.
End User:
Customer type determines policy structure complexity, with individual consumers demanding simple bundled protection while commercial buyers negotiate fleet-rated terms with customized deductibles.
- Consumers:Individual policyholders purchase through retail-affinity channels or embedded point-of-sale bundles, with Indian electronics chains in Mumbai and Delhi converting upfront warranty purchases into monthly subscription fees. IRDAI-mandated disclosure formats extend product development timelines but reduce post-sale dispute volume.
- Businesses:Corporate fleet deployments in Australian logistics and Japanese healthcare sectors require standalone commercial policies with negotiated SLAs and dedicated claims handlers. Allianz Insurance anchors this segment through tailored coverage for device-dependent field operations.
- Educational Institutions:Bulk procurement in Indian tier-2 and tier-3 cities aligns with PLI scheme device penetration, generating seasonal demand concentration.
- Nonprofits:Grant-funded device programs in Southeast Asian markets absorb donated equipment protection through simplified policy structures with minimal underwriting scrutiny.
Consumers retain the largest policy count, yet Businesses deliver superior loss-ratio performance through risk-pooled fleet rating.
Distribution Channel:
Volume flows increasingly through embedded partnerships that compress customer acquisition costs, though direct channels retain importance for complex commercial negotiations requiring customized terms.
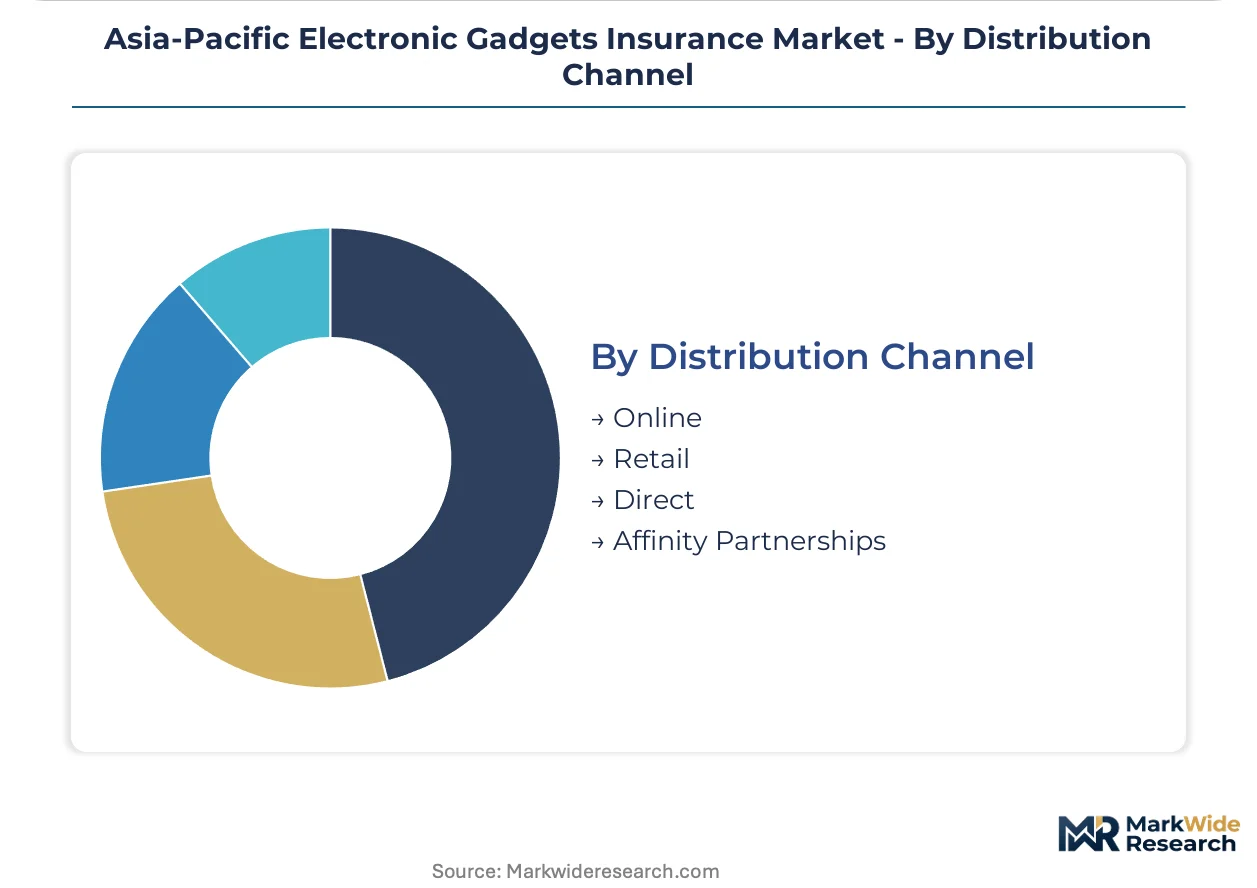
- Affinity Partnerships:OEM and telecom bundling dominates Southeast Asian and Japanese markets where Samsung Premium Care and mobile network operators attach protection at device activation. Japan's FSA supervision of these partnerships ensures solvency compliance while enabling real-time policy issuance with minimal friction.
- Online:Direct digital distribution gains traction among tech-savvy Indian consumers in Bangalore and Hyderabad who comparison-shop coverage terms across carrier portals. Syska Gadget Secure leverages this channel for retail-affinity model extension beyond physical electronics chains.
- Retail:Metro Indian electronics chains in Delhi and Mumbai anchor point-of-sale attachment with financing-integrated subscription models.
- Direct:Commercial brokers serve Australian and Japanese enterprise accounts requiring bespoke fleet coverage with negotiated claims protocols.
Affinity Partnerships command the widest reach, while Online channels are expanding most quickly among digitally native buyer cohorts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's electronics manufacturing surge exports protection-plan demand to Southeast Asian gig-economy corridors. Device-dependent delivery platforms in Indonesia and Vietnam absorb coverage products calibrated to Indian actuarial models.
India
Urban smartphone replacement cycles compress to 18-24 months in Mumbai and Delhi, elevating attach rates for protection plans. The PLI scheme for electronics manufacturing accelerates device penetration into tier-2 and tier-3 centers. Bangalore's retail chains convert upfront warranty purchases into monthly subscription fees, embedding insurance into device financing.
Japan
Mobile network operators bundle protection at point of activation through carrier-embedded distribution. The FSA applies solvency requirements to underwriters writing mobile-device policies through these partnerships. Tokyo and Osaka metro areas anchor real-time policy issuance with minimal acquisition friction.
Australia
Corporate fleet deployments in logistics and healthcare sectors drive demand for standalone commercial policies with negotiated SLAs. ASIC enforces disclosure regimes under the Corporations Act that shape distributor compliance costs. Sydney and Melbourne concentrate enterprise device coverage with dedicated claims handlers.
South Korea
Fitness-tracker and smartwatch penetration outpaces dedicated coverage product development, creating wearables protection white space. Recurring subscription models in Seoul retail chains convert one-time warranty purchases into sustained revenue streams. The MFDS regulatory framework shapes device certification standards that indirectly affect claims-fulfillment reliability.
Indonesia
Smartphone-toting gig workers on delivery and ride-hailing platforms generate concentrated risk pools seeking breakage coverage. Humidity-related liquid damage claims spike during monsoon seasons in Jakarta and Surabaya, requiring seasonal reserve adjustments. Carrier partnerships replicate Japanese embedded distribution models with localized actuarial calibration.
Asia-Pacific Electronic Gadgets Insurance Market Competitive Environment
Listed leaders compete with private specialists across distribution channel control and customer acquisition economics. The vendor base concentrates around three structural tiers: OEM-embedded programs, carrier-partnered underwriters, and retail-affinity specialists. Strategic archetypes include manufacturing-origin bundlers, telecom-channel anchors, and electronics-chain affiliates. Dominant competitive moves center on point-of-sale integration and subscription-model conversion of one-time purchases.
Within the OEM-embedded tier, Samsung Premium Care and Apple Care+ exemplify manufacturing-origin bundlers that leverage device production scale for protection-plan attachment. Allianz Insurance occupies a position among carrier-partnered commercial underwriters serving fleet-rated enterprise accounts. Syska Gadget Secure sits within the retail-affinity specialist archetype, anchoring metro Indian electronics chain distribution with financing-integrated subscription models.
| Leading Market Players |
|---|
| Apple Care+ |
| Samsung Premium Care |
| Safeware |
| Syska Gadget Secure |
| Warranty Asia |
| The Digital Insurer |
| Allianz Insurance |
| Gadget Cover |
| Brightstar Corp. |
| Others |
Value Chain & Pricing Dynamics
India's BIS certification mandates for refurbished components gate both claims-fulfillment reliability and premium tiering across the Asia-Pacific gadget insurance landscape. IRDAI-mandated disclosure formats and standardized cooling-off periods simultaneously elevate compliance costs for new entrants and create price differentiation between established underwriters with regulatory affairs infrastructure and challengers without.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in commercial fleet deployments. Premium tiers attach through carrier-embedded distribution with minimal friction, while standard tiers dominate retail-affinity channels with financing-integrated subscriptions. Price differentiation stems from claims-fulfillment SLAs and deductible calibration. Cost compression in economy tiers is intensifying because semiconductor lead times for specialized components extend settlement windows beyond contracted terms. Gig-economy workers in Southeast Asian delivery platforms exhibit highest price sensitivity, while Japanese corporate fleet buyers show least sensitivity due to bundled carrier partnerships.
Supply Chain Analysis
Strategic stockpiling of certified replacement components dominates over just-in-time preferences as BIS mandates tighten refurbishment standards. Component sourcing concentrates in China, South Korea, and Taiwan for display assemblies and semiconductor modules. Claims fulfillment draws from India-dominated refurbishment ecosystems and Singapore-based logistics hubs. Single-source vulnerability sits with specialized foldable display suppliers concentrated in Korean manufacturing corridors. Distribution runs through carrier partnerships in Japan, retail-affinity chains in India, and direct commercial brokers in Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among gig-economy platforms and corporate fleet deployers, fragmenting individual consumer segments while consolidating volume negotiation leverage among device-dependent employers and logistics operators.
For Market Incumbents: Shield margin pools in extended warranty lines through vertical integration into certified refurbishment networks under BIS compliance. Deepen carrier partnership exclusivity in Japan and Australia before regulatory friction elevates distributor compliance costs. Counter emerging retail-affinity specialists in Indian metro chains by accelerating subscription-model conversion of one-time warranty purchases. For New Entrants and Emerging Players: Anchor in wearables protection white space across South Korean and Japanese fitness-tracker penetration corridors where dedicated coverage product development lags device adoption. Target corporate fleet commercialization in Australian healthcare and logistics sectors with standalone policies featuring negotiated SLAs. Penetrate through direct digital channels among tech-savvy Bangalore and Hyderabad consumers who comparison-shop coverage terms. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across AI-powered claims triage infrastructure as computer vision deployment at scale demands dedicated technology investment. Long-term viability favors underwriters with embedded distribution control and regulatory affairs infrastructure. Monitor carrier partnership renewal rates as inflection indicator for distribution economics deterioration.| Strategic Initiative | Industry Significance |
|---|---|
| Carrier Partnership Expansion | Japan's FSA-supervised mobile network partnerships enable real-time policy issuance with minimal acquisition friction. |
| AI Claims Triage Deployment | Australian carriers and Japanese operators deploy computer vision algorithms that compress claims cycle times from days to hours. |
| Subscription Model Conversion | Mumbai and Delhi retail chains bundle monthly protection fees with device financing, converting upfront margin into recurring revenue. |
| Refurbishment Certification Investment | India's BIS mandates for certified replacement components improve claims-fulfillment reliability and reduce customer churn. |
| Wearables Product Development | Seoul and Tokyo retail chains convert one-time warranty purchases into sustained revenue streams for fitness-tracker coverage. |
Study Parameters
Operator-level perspectives from claims operations directors, carrier partnership managers, retail electronics chain buyers, and IRDAI regulatory affairs leads anchored the qualitative base. Primary interview data combined with secondary validation from IRDAI product filings, ASIC disclosure regime documentation, Japan FSA solvency reports, and customs data on electronics component trade flows. Bottom-up policy volume estimates triangulated against top-down macro device penetration projections.
Sensitivity analysis tested premium volume assumptions across device category splits, coverage type attach rates, and distribution channel mix shifts over the projection horizon. Segmentation dimensions modeled include product type, coverage tier, end-user archetype, and distribution channel structure. CAGRs derived from fitted growth curves calibrated to PLI scheme acceleration timelines and gig-economy platform expansion trajectories. Forecast inputs incorporated seasonal humidity patterns affecting liquid damage claim frequency and semiconductor lead time volatility.
Material uncertainties — regulatory filing delays, carrier partnership renegotiations, and component supply disruptions — sit outside the modeled envelope. Forecasts reflect assumptions about PLI scheme continuation and embedded insurance adoption curves. Revision becomes warranted when BIS certification mandate enforcement intensity or foldable device breakage frequency crosses thresholds beyond historical calibration ranges.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Endowment Insurances Market
Insurance
Data Analytics in Insurance Market
Insurance
USA Travelers Insurance Market
Insurance
Commercial Cyber Insurance Market
Insurance
United Kingdom Parametric Insurance Market
Insurance
Singapore Business Income Insurance Market
Insurance
Europe Bancassurance Market
Insurance
Japan Liability Insurance Market
Insurance
North America Liability Insurance Market
Insurance
Business Travel Insurance Market
Insurance
Saudi Arabia Travel Insurance Market
Insurance
United Kingdom Health and Medical Insurance Market
Insurance
Asia-Pacific Critical Illness Insurance Market
Insurance
Horse Insurance Market
Insurance
Asia-Pacific Livestock Insurance Market
Insurance
Family Floater Health Insurance Market