
 Singapore Business Income Insurance Market | 2026-2036
Singapore Business Income Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Business Income Insurance Market Insights
Actuarial talent scarcity is bifurcating the Singapore business income insurance landscape into technology-augmented underwriters and traditional risk-assessment models. NTUC Income Insurance Co-operative leverages its cooperative structure to sustain member-focused pricing across SME segments. Great Eastern Life anchors its market presence through bancassurance partnerships with regional banking networks. AIA Singapore Pte Ltd differentiates via integrated digital platforms that streamline contingent business interruption quoting.
Singapore business income insurance indemnifies policyholders against lost revenue, fixed operational costs, and extra expenses triggered by insured perils that suspend normal commercial activities; policies typically specify indemnity periods of 12 to 36 months and require proof of actual loss through audited financial statements. Business Interruption policies dominate premium pools as established manufacturing and logistics clients renew long-term contracts, while Contingent Business Interruption coverage is expanding fastest among semiconductor and pharmaceutical supply chain participants exposed to regional supplier failures. Distribution through Brokers controls mid-market and large corporate placements due to complex coverage structuring needs, though Online Platforms are capturing Small Enterprises seeking standardized Named Perils policies with rapid issuance.
The Monetary Authority of Singapore enforces risk-based capital requirements that shape insurer reserving practices and product pricing transparency, while Singapore's Personal Data Protection Act constrains digital distribution channel data utilization for customer targeting. Enterprise Singapore promotes business continuity planning adoption through grant schemes that indirectly stimulate insurance awareness among qualifying firms. Stakeholders must monitor how climate risk disclosure mandates from the central bank reshape coverage exclusions and premium adequacy across industrial zones.
Market Dynamics
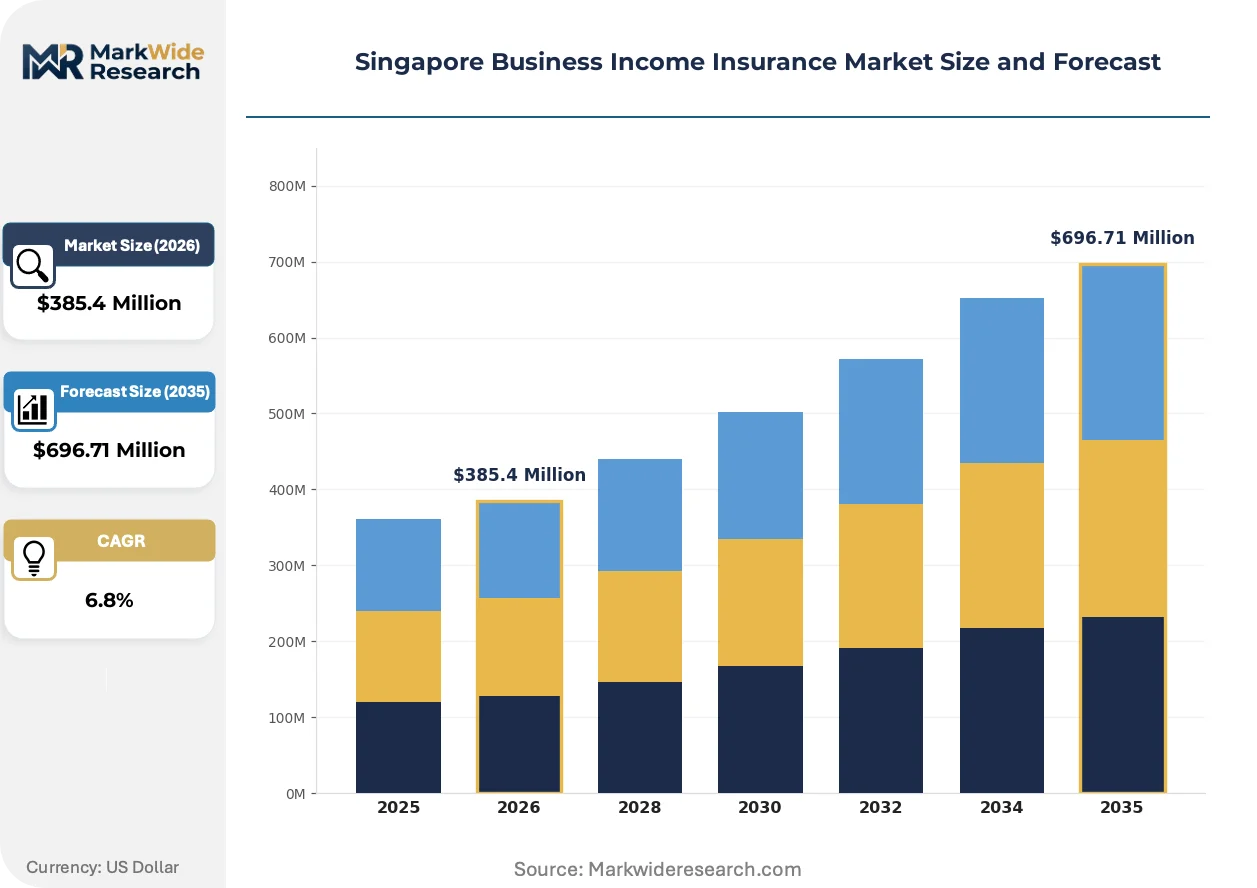
The Monetary Authority of Singapore's risk-based capital framework is compressing insurer capital buffers while simultaneously elevating reserving standards, forcing carriers to recalibrate pricing models and product structures across SME and corporate segments.
Growth Catalysts
- Semiconductor supply chain vulnerability:Contingent business interruption demand from pharmaceutical and chip manufacturing participants exposed to regional supplier failures is accelerating policy uptake.
- Enterprise Singapore grant schemes:Business continuity planning subsidies for qualifying firms are indirectly stimulating insurance awareness and formal coverage adoption.
- Digital platform distribution:Online platforms are capturing small enterprises seeking standardized named perils policies with rapid issuance cycles.
Market Restraints
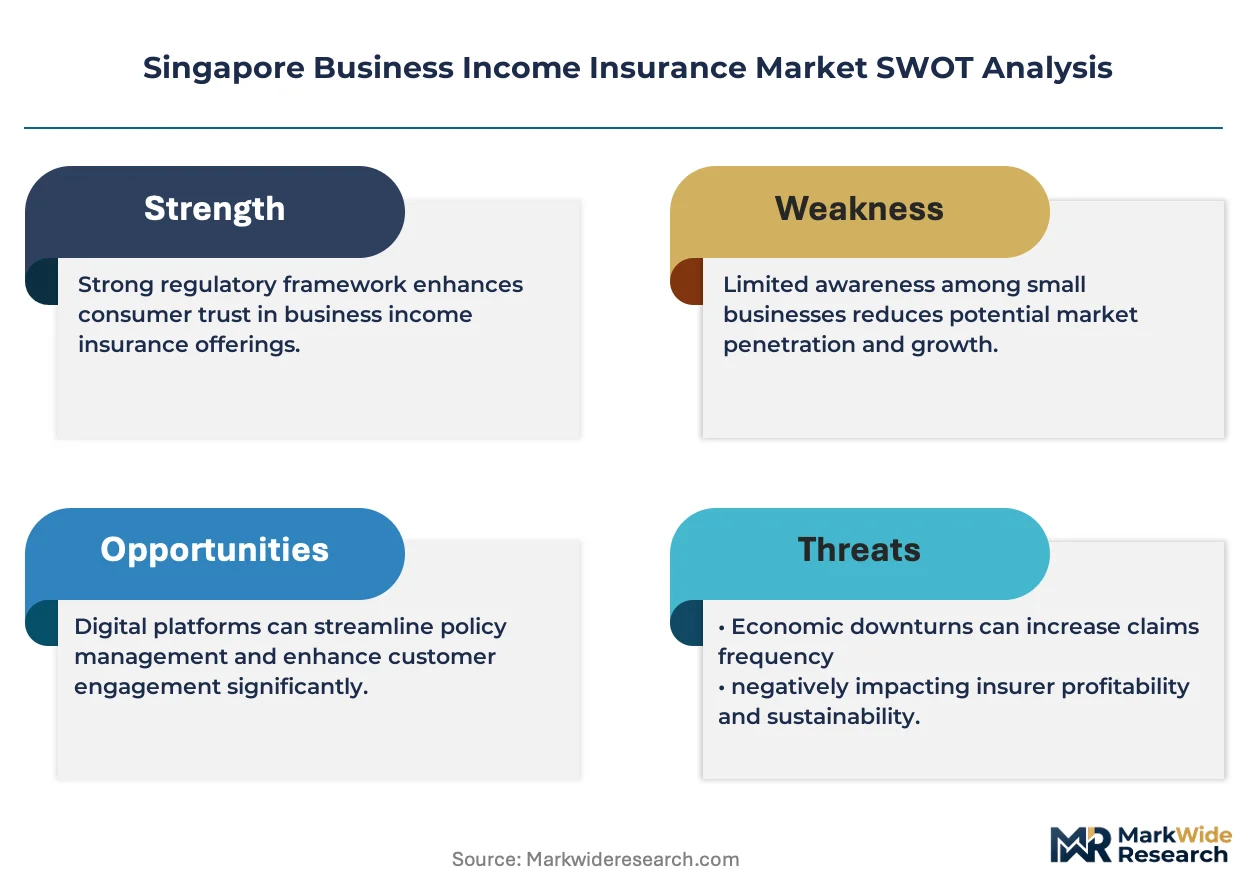
- Actuarial talent scarcity:Bifurcation between technology-augmented underwriters and traditional risk-assessment models is constraining product innovation velocity.
- Central Business District concentration risk:Demand clustering in the CBD and Jurong Island industrial corridor creates geographic exposure correlation.
- Personal Data Protection Act constraints:Digital distribution channel data utilization for customer targeting faces regulatory friction.
Strategic Opportunities
- Contingent business interruption expansion:Supply chain participants in semiconductor and pharmaceutical verticals represent underpenetrated white space.
- Bancassurance channel deepening:Regional banking network partnerships offer distribution leverage for standardized product tiers.
- Climate risk disclosure mandates:Central bank requirements are reshaping coverage exclusions and premium adequacy calculations.
Industry Challenges
- Actuarial capability gaps:Talent scarcity in predictive modeling and catastrophe risk quantification is delaying product development cycles.
- Legacy system integration:Core policy administration platforms require substantial reconfiguration to support real-time digital quoting.
- Proof-of-loss documentation:Audited financial statement requirements create friction in claims settlement for SME policyholders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Business Income Insurance Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Business Interruption, Contingent Business Interruption, Rental Income, Gross Profit End User: Small Enterprises, Medium Enterprises, Large Corporations, Non-Profit Organizations Coverage Type: Named Perils, All Risks, Comprehensive, Minimum Premium Distribution Channel: Direct Sales, Brokers, Online Platforms, Agents |
| Companies Covered | NTUC Income Insurance Co-operative, Great Eastern Life, AIA Singapore Pte Ltd, Prudential Assurance Company Singapore, Manulife (Singapore), Singlife with Aviva, HSBC Life Singapore, Tokio Marine Life Insurance Singapore, China Taiping Insurance (Singapore), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Business Income Insurance Market Trends and Innovations
Digital underwriting infrastructure and regulatory disclosure mandates are restructuring how Singapore carriers assess, price, and distribute business income protection across divergent risk segments.
Parametric triggers linked to predefined business interruption indices are displacing traditional indemnity-based settlement structures. Semiconductor and pharmaceutical supply chain participants are adopting these instruments fastest. The shift compresses claims adjustment timelines from months to days.
Singapore's central bank climate risk disclosure requirements are mandating scenario analysis for industrial zone exposures. Insurers must now model physical risk transmission into revenue interruption. Manufacturing and logistics clients in Jurong Island face elevated scrutiny.
Small enterprises are consolidating purchasing through embedded insurance offerings within accounting and ERP software platforms. Brokers retain mid-market and large corporate placements where complex coverage structuring demands advisory input. This bifurcation is most visible among CBD-based professional services firms.
Singapore Business Income Insurance Market Segmentation
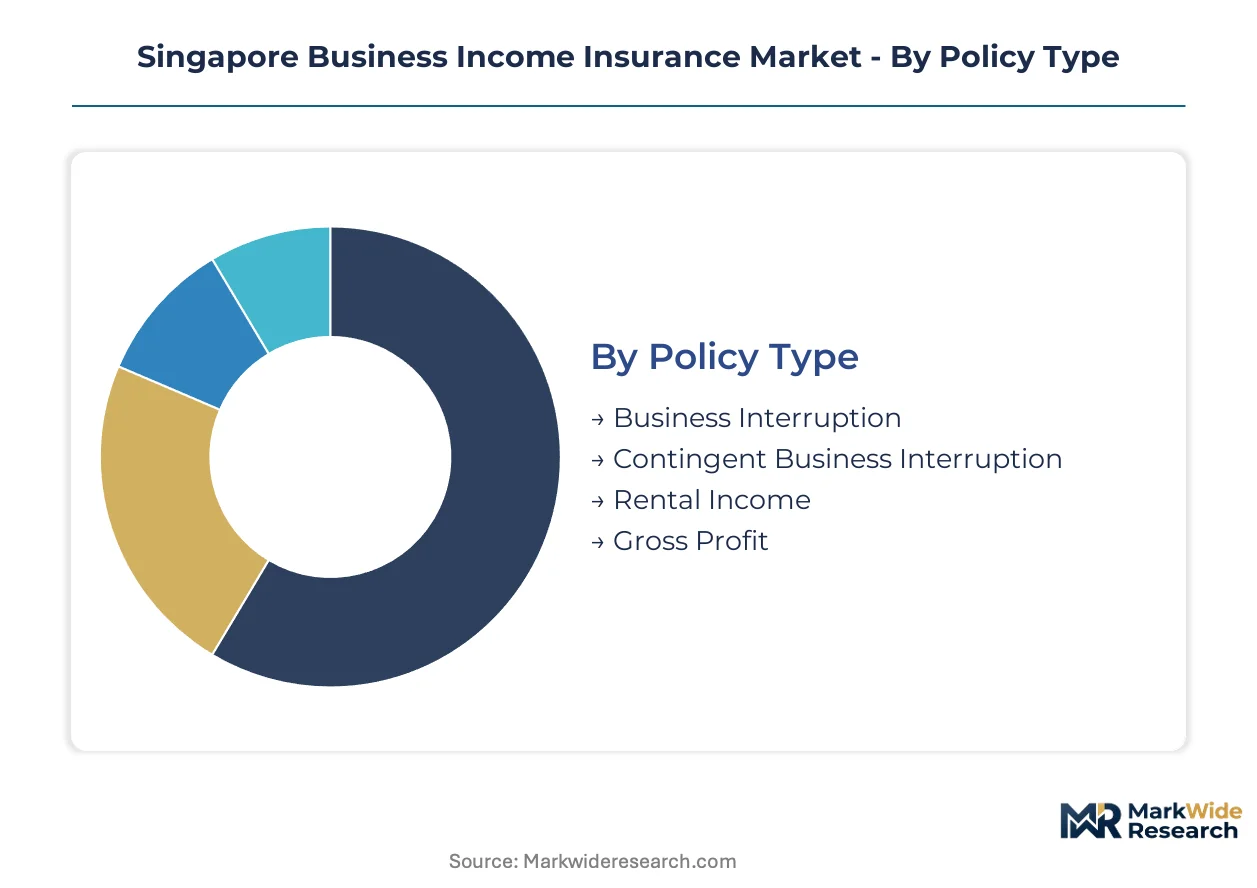
Singapore's business income insurance segmentation reflects divergent risk appetites across policy structures, buyer scale, and channel economics. The Monetary Authority of Singapore's risk-based capital framework compresses margins on standardized products while rewarding complexity in corporate placements.
Policy Type:
The Monetary Authority of Singapore applies differentiated capital charges based on policy duration and peril breadth, compressing pricing on short-tail indemnity structures while elevating reserving requirements for contingent exposures.
- Business Interruption:Traditional indemnity policies covering lost revenue and fixed costs during operational suspension. Manufacturing and logistics clients in Jurong Island industrial corridor sustain renewal demand for 12-to-36-month indemnity periods with audited financial proof requirements.
- Contingent Business Interruption:Coverage triggered by supplier or customer facility failures outside the insured's direct control. Semiconductor and pharmaceutical supply chain participants in Singapore's Central Business District are accelerating adoption fastest amid regional supplier vulnerability.
- Rental Income:Protects commercial property owners against tenant default or lease interruption. Singapore's REIT sector and private commercial landlords utilize this coverage for CBD and suburban retail assets.
- Gross Profit:Indemnifies lost gross margin rather than top-line revenue, favored by trading houses and commodity distributors with high variable cost structures.
Business Interruption handles the majority of throughput; Contingent Business Interruption is expanding most quickly on share.
End User:
Premium adequacy varies sharply across enterprise scale, with SME segments subsidizing acquisition costs through digital self-service while large corporate placements absorb substantial underwriting labor.
- Small Enterprises:Standardized Named Perils purchasers through online platforms and embedded ERP distribution. Enterprise Singapore grant eligibility for business continuity planning indirectly stimulates formal coverage adoption among qualifying firms.
- Medium Enterprises:Broker-mediated placements requiring advisory structuring for industry-specific peril definitions. Manufacturing and professional services clusters in Jurong and the CBD dominate this tier.
- Large Corporations:Complex multi-location programs with customized indemnity periods and sub-limits. These placements absorb disproportionate actuarial and legal review capacity.
- Non-Profit Organizations:Donation-dependent revenue structures require specialized proof-of-loss documentation; coverage penetration remains limited outside healthcare and education subsectors.
Small Enterprises generate the highest policy count; Large Corporations concentrate the premium pool.
Coverage Type:
Regulatory disclosure mandates on climate risk transmission are reshaping exclusion language and premium adequacy calculations across peril breadth categories.
- Named Perils:Specified-cause coverage with explicit enumeration of insured events. Small enterprises favor this structure for premium predictability and rapid digital issuance.
- All Risks:Broad-form coverage inverting the burden of proof to the insurer for exclusion applicability. Large corporate placements in semiconductor and logistics verticals demand this tier.
- Comprehensive:Bundled programs combining business interruption with property and liability extensions. Regional banking networks distribute standardized comprehensive tiers through bancassurance partnerships.
- Minimum Premium:Entry-level coverage with capped limits and restricted indemnity periods. Micro-enterprises and sole proprietors utilize this for contractual compliance rather than genuine risk transfer.
Named Perils dominates policy issuance volume; All Risks commands the steepest expansion trajectory in premium terms.
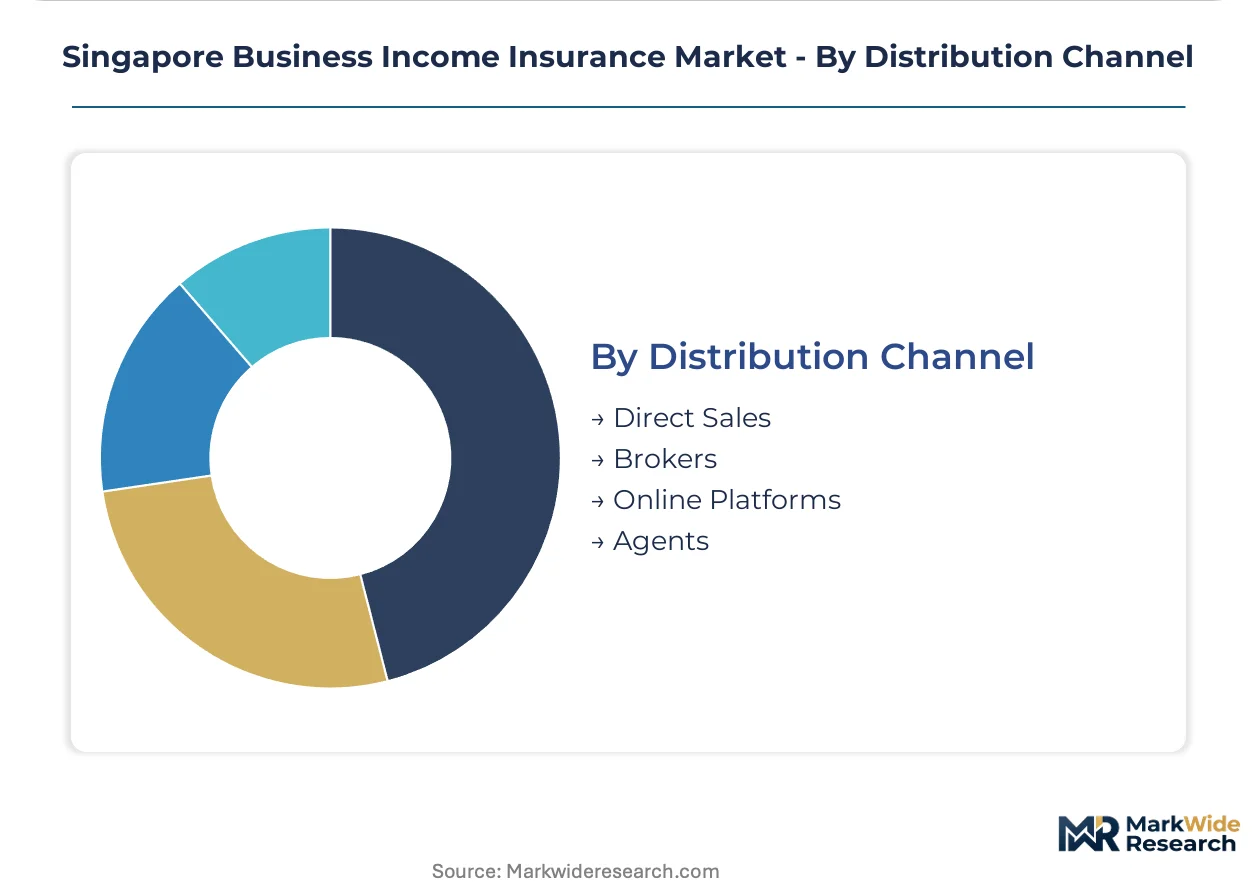
Distribution Channel:
Channel economics bifurcate between high-touch advisory requirements for complex placements and automated underwriting for standardized risk profiles.
- Direct Sales:Carrier-employed teams targeting large corporate accounts with multi-year program structures. Great Eastern Life and NTUC Income maintain captive direct sales forces for relationship-intensive placements.
- Brokers:Independent intermediaries controlling mid-market and large corporate segments through coverage structuring expertise. Complex indemnity period negotiations and sub-limit design absorb substantial broker labor.
- Online Platforms:Digital distribution capturing small enterprises with parametric triggers and rapid issuance. AIA Singapore's integrated platforms streamline contingent business interruption quoting for standardized exposures.
- Agents:Tied representatives focusing on personal lines cross-sell and micro-enterprise introductions. Channel share is compressing amid digital platform expansion.
Brokers intermediate the majority of premium value; Online Platforms are climbing the fastest on policy count.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns in Singapore diverge from regional peers through heavy concentration in contingent business interruption for supply chain exposures, whereas neighboring markets emphasize traditional property-linked coverage for manufacturing assets.
Central Business District
Financial services and professional services firms drive demand for contingent business interruption policies triggered by supplier failures. The Monetary Authority of Singapore's risk-based capital framework shapes product pricing transparency. Marina Bay and Raffles Place clusters concentrate premium placement activity through broker-mediated channels.
Jurong Island
Petrochemical and specialty chemical operators sustain renewal demand for 12-to-36-month indemnity periods with complex sub-limit structures. Enterprise Singapore grant schemes for business continuity planning indirectly stimulate formal coverage adoption. The industrial corridor's integrated energy and chemicals hub generates concentrated exposure correlation.
Tampines Regional Centre
Logistics and distribution facilities anchor traditional business interruption demand for operational suspension coverage. The Personal Data Protection Act constrains digital distribution channel data utilization for customer targeting. Last-mile warehousing clusters face elevated scrutiny under emerging climate risk disclosure mandates.
One-North and Buona Vista
Biomedical sciences and infocommunications companies accelerate adoption of contingent business interruption for regional supplier vulnerability. Small enterprises consolidate purchasing through embedded insurance offerings within accounting and ERP software platforms. The research and innovation precinct represents underpenetrated white space for parametric trigger products.
Singapore Business Income Insurance Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Singapore's business income insurance market. Cooperative and mutual structures compete alongside stock insurers with regional banking network partnerships. Three archetypes dominate: cooperative underwriters with member-focused pricing, bancassurance-anchored carriers with standardized product tiers, and digitally integrated platforms with rapid issuance capabilities. Competitive moves concentrate on bancassurance channel deepening and parametric product development.
Within the cooperative tier, NTUC Income Insurance Co-operative represents member-owned structures sustaining competitive positioning across SME segments. Great Eastern Life and AIA Singapore Pte Ltd exemplify contrasting distribution strategies—regional banking partnerships versus integrated digital platforms—each occupying distinct positions in the competitive architecture.
| Leading Market Players |
|---|
| NTUC Income Insurance Co-operative |
| Great Eastern Life |
| AIA Singapore Pte Ltd |
| Prudential Assurance Company Singapore |
| Manulife (Singapore) |
| Singlife with Aviva |
| HSBC Life Singapore |
| Tokio Marine Life Insurance Singapore |
| China Taiping Insurance (Singapore) |
| Others |
Pricing and Supply Chain Analysis
Parametric trigger mechanisms replacing traditional indemnity-based settlement structures are simultaneously compressing claims adjustment timelines and redistributing pricing power toward carriers with real-time data infrastructure. This substitution dynamic concentrates margin capture with digitally integrated platforms while forcing legacy underwriters to absorb reconfiguration costs.
Pricing Analysis
Long-term offtake contracts dominate premium pools as manufacturing and logistics clients in Jurong Island renew multi-year programs with audited financial proof requirements. Price differentiation rests on indemnity period length and peril breadth, with 12-month structures commanding tighter margins than 36-month alternatives. Cost compression in standardized Named Perils tiers is intensifying because digital platforms automate underwriting labor. Small enterprises exhibit highest price sensitivity, while large corporations absorb complexity premiums for customized sub-limit structures.
Supply Chain Analysis
Extended lead times for actuarial talent placement are constraining product development velocity across Singapore's carrier landscape. Geographic supply concentration draws from the United Kingdom, Australia, and India for catastrophe modeling expertise. Raw material dependencies include proprietary risk scoring algorithms, cloud computing infrastructure, and regulatory compliance software. Single-source vulnerability sits with predictive modeling platform providers. Distribution runs through broker-mediated channels for mid-market placements and direct digital platforms for SME segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore's business income insurance market sits in early-cycle expansion, with contingent business interruption penetration among semiconductor supply chain participants providing structural tailwinds for premium growth.
For Market Incumbents: Secure actuarial capability through targeted recruitment in catastrophe risk quantification and predictive modeling. Deepen bancassurance partnerships with regional banking networks to lock in standardized product distribution. The threat of technology-augmented underwriters capturing SME segments demands accelerated legacy system modernization. For New Entrants and Emerging Players: Embedded insurance integration within accounting and ERP software platforms represents the most penetrable white space, as incumbent carriers under-serve small enterprises consolidating purchasing through these channels. Target One-North and Buona Vista biomedical sciences clusters with parametric trigger products for regional supplier vulnerability. A direct digital go-to-market angle leveraging rapid issuance capabilities bypasses broker-mediated friction. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed insurtech platforms possessing parametric product infrastructure but lacking carrier licenses. Long-term viability over a 5-10 year window hinges on regulatory approval for novel settlement structures. The signal to watch is Monetary Authority of Singapore guidance on climate risk disclosure mandates reshaping coverage exclusions.| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Product Development | Compresses claims adjustment timelines from months to days for semiconductor clients. |
| Bancassurance Channel Deepening | Regional banking networks provide distribution leverage for standardized SME tiers. |
| Actuarial Talent Acquisition | Predictive modeling expertise addresses capability gaps delaying product cycles. |
| Climate Risk Disclosure Compliance | Monetary Authority of Singapore mandates reshape exclusion language and pricing. |
| Embedded Insurance Integration | ERP platform partnerships capture small enterprise purchasing consolidation. |
Research Methodology
A standing panel of underwriters, claims adjusters, broker operations heads, and regulatory compliance officers provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation from Monetary Authority of Singapore circulars, Enterprise Singapore grant documentation, and insurer financial disclosures. Bottom-up policy issuance data triangulated against top-down premium pool estimates derived from regulatory filings.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include policy type, enterprise scale, coverage breadth, and distribution channel complexity. CAGRs were derived from historical trajectory analysis and forward-looking scenario weighting. Industry-specific forecast inputs incorporated semiconductor supply chain vulnerability indices and climate risk transmission modeling for industrial zone exposures.
Underlying assumptions cover regulatory stability in risk-based capital requirements, with deviation risk concentrated in actuarial talent availability and climate disclosure mandate timing. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Asia-Pacific Usage-Based Insurance Market
Insurance
North America Family Floater Health Insurance Market
Insurance
Parametric Insurance Market
Insurance
Liability Insurance Market
Insurance
Vietnam Private Health Insurance Market
Insurance
Bancassurance in ASEAN Market
Insurance
Marine Freight Insurance Market
Insurance
Green Insurance Market
Insurance
Trade Credit Insurance Market
Insurance
Middle East Business Income Insurance Market
Insurance
Business Insurance Market
Insurance
Mobile Phone Insurance Market
Insurance
United Kingdom Health and Medical Insurance Market
Insurance
Asia-Pacific Electronic Gadgets Insurance Market
Insurance
Global Mobile Phone Insurance Ecosystem Market
Insurance
France Car Insurance Market