
 Japan Liability Insurance Market | 2026-2036
Japan Liability Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Liability Insurance Market Insights
Project finance and leasing arrangements for commercial fleet portfolios is fragmenting traditional capital requirements across smaller underwriting participants. Tokio Marine & Nichido Fire Insurance Co., Ltd. leverages its marine heritage to dominate industrial liability placements. MS&AD Insurance Group Holdings, Inc. anchors its position through multi-line corporate bundling. Aioi Nissay Dowa Insurance Co., Ltd. competes in mid-market professional liability through specialized broker networks.
Liability insurance constitutes risk-transfer instruments that indemnify policyholders against third-party claims for bodily injury, property damage, or financial loss arising from insured operations, with premium calculations reflecting claims history, exposure limits, and retroactive date parameters. The policy type dimension shows professional liability outpacing general liability in premium growth as Japan's service economy expands, while the distribution channel segment reveals online platforms capturing share from traditional agent networks among small enterprise purchasers. Coverage scope stratification indicates international policies commanding wider margins despite thinner volumes.
METI's industrial safety directives and the Financial Services Agency's solvency regulation jointly determine capital reserving requirements and product filing standards for domestic carriers. Japan's PL Law and associated cabinet ordinances mandate product liability coverage thresholds that shape manufacturer purchasing patterns. Stakeholders must track how climate litigation precedents will recast long-tail exposure assumptions in directors and officers coverage.
Market Dynamics
METI's contractor safety directives are compressing coverage procurement cycles across Japanese construction, while product liability mandates in Osaka's manufacturing corridor reshape carrier-retailer relationships.
Growth Catalysts
- Industrial Safety Mandates:METI's tightened contractor obligations force construction firms to expand liability purchases ahead of project commencement deadlines.
- Professional Services Expansion:Japan's service economy growth accelerates errors and omissions coverage demand among consulting and IT services clusters in Tokyo and Osaka.
- Climate Litigation Exposure:Emerging precedents in directors and officers coverage recast long-tail assumptions, prompting corporate buyers to secure higher-limit policies.
Market Restraints
- Capital Reserving Burden:Financial Services Agency solvency regulations impose stringent capital requirements on domestic carriers, compressing underwriting capacity for mid-market risks.
- Long-Tail Uncertainty:Product liability claims under Japan's PL Law extend across multi-decade horizons, distorting pricing models for Osaka manufacturing corridor underwriters.
- Interest Rate Compression:Sustained low yields on investment portfolios constrain carrier profitability independent of underwriting performance.
Strategic Opportunities
- Online Platform Penetration:Digital distribution channels capture share from traditional agent networks among small enterprise purchasers in regional prefectures.
- Multi-Line Corporate Bundling:Cross-selling property and liability coverage to mid-market manufacturers creates stickier relationships and reduces acquisition costs.
- International Policy Margins:Coverage extending beyond domestic jurisdiction commands wider underwriting margins despite thinner transaction volumes.
Industry Challenges
- Actuarial Talent Scarcity:Shortage of professionals skilled in climate risk modeling complicates pricing for emerging environmental liability exposures.
- Legacy System Integration:Incumbent carriers face friction modernizing policy administration platforms to support real-time digital quoting.
- Broker Network Fragmentation:Specialized intermediaries in professional liability segments resist standardization, complicating carrier distribution economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Liability Insurance Market |
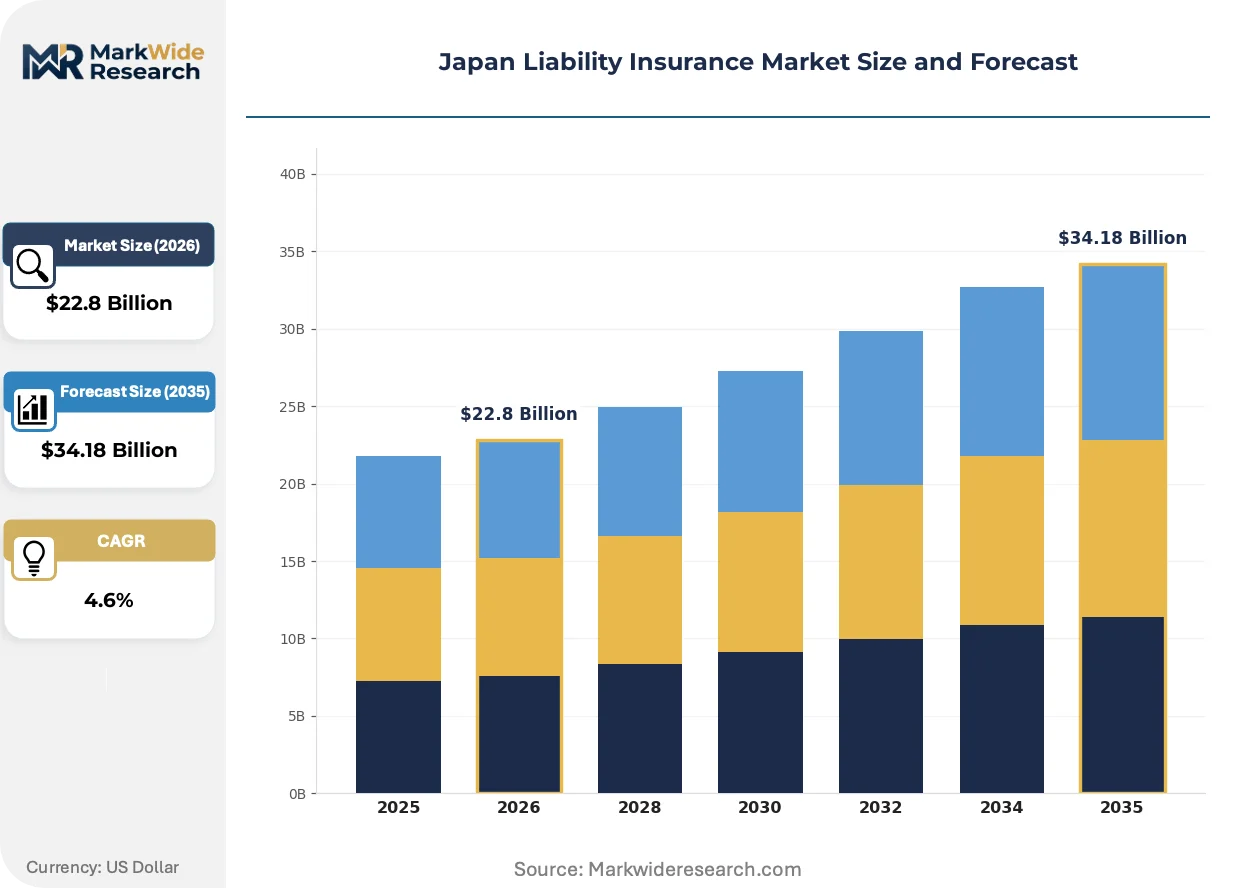
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $34.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Auto Liability, General Liability, Professional Liability, Product Liability Client Type: Small Enterprises, Corporations, Non-Profits, Government Entities Coverage Scope: Local, National, International, Umbrella Distribution Channel: Direct Sales, Brokers, Online Platforms, Agents |
| Companies Covered | Sompo Japan Insurance Inc., Rakuten General Insurance Co., Ltd., Tokio Marine & Nichido Fire Insurance Co., Ltd., Tokio Marine Holdings, Nisshin Fire & Marine Insurance Co., Ltd., MS&AD Insurance Group Holdings, Inc., Aioi Nissay Dowa Insurance Co., Ltd., Sompo Holdings Inc., Mitsui Sumitomo Insurance Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Liability Insurance Market Trends and Innovations
Digital underwriting platforms and climate risk analytics are restructuring how Japanese carriers assess and price liability exposures across industrial and professional segments.
Telematics-enabled fleet monitoring is digitizing commercial auto liability underwriting for logistics operators. Major trucking consortiums in Kanto and Kansai regions deploy real-time driver behavior tracking. This sensor infrastructure is digitizing traditional actuarial models, enabling dynamic premium adjustments based on actual risk exposure rather than historical classifications.
METI's industrial safety directives now mandate documented contractor coverage verification before project authorization. Construction firms must submit carrier-issued certificates of insurance to prefectural labor bureaus. Heavy civil engineering contractors in Tokyo Bay redevelopment zones face compressed procurement timelines as these filing requirements take effect.
Small enterprises increasingly bypass traditional agent networks for direct online policy binding. Digital platforms now aggregate quotes from multiple domestic carriers for general liability and professional coverage. This channel migration concentrates among IT services and professional consulting firms with standardized risk profiles.
Japan Liability Insurance Market Segmentation
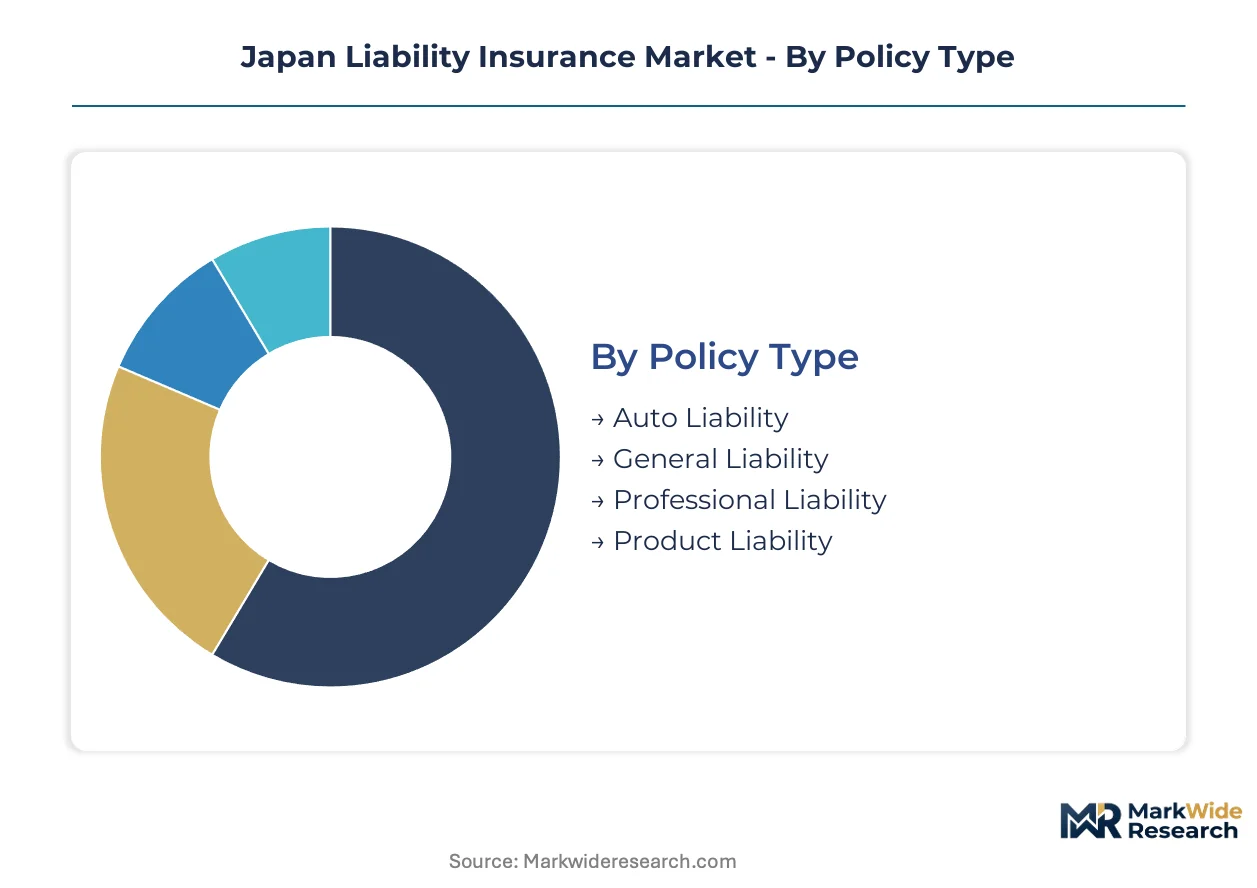
Liability coverage in Japan stratifies across policy structures, purchaser scale, geographic scope, and distribution pathways. Each dimension shapes premium calculations, capital reserving requirements, and carrier competitive positioning within METI-regulated markets.
Policy Type:
Cost tier differentiation separates basic statutory coverage from specialized professional and product liability instruments with elevated limits.
- Auto Liability:Statutory coverage mandated under Japan's Automobile Liability Security Law. Fleet operators in Kanto logistics corridors drive volume concentration as telematics-enabled underwriting spreads.
- General Liability:Broad-spectrum protection against third-party bodily injury and property damage claims. Construction firms in Tokyo Bay redevelopment zones expand purchases ahead of METI contractor safety filing deadlines.
- Professional Liability:Errors and omissions coverage for service-sector exposures. IT consulting clusters in Osaka and Tokyo accelerate demand as service economy output expands.
- Product Liability:PL Law-mandated protection for manufacturing defects. Osaka's manufacturing corridor concentrates purchasing as multi-decade claim horizons complicate carrier pricing models.
Professional Liability holds installed capacity. Product Liability is rotating up the share rankings.
Client Type:
Purchaser scale determines coverage complexity, with corporate buyers demanding multi-line bundling and small enterprises migrating to streamlined digital channels.
- Corporations:Large enterprises with complex, multi-jurisdictional exposures. Heavy civil engineering contractors and automotive manufacturers anchor premium volume through umbrella and international policy structures.
- Small Enterprises:Mid-market firms with standardized risk profiles. IT services and professional consulting firms in regional prefectures increasingly bypass traditional agent networks for direct online binding.
- Government Entities:Public-sector purchasers with statutory procurement requirements. Prefectural infrastructure bureaus mandate documented coverage verification before project authorization.
- Non-Profits:Limited segment with constrained purchasing power. Social service organizations and cultural institutions represent thin premium contribution.
Corporations command premium concentration. Small Enterprises are gaining share fastest through digital channel migration.
Coverage Scope:
Geographic reach stratifies margin profiles, with domestic-local coverage carrying volume and international extension capturing wider underwriting spreads.
- International:Cross-border protection for Japanese multinationals with overseas operations. Export-oriented manufacturers in Osaka and Nagoya manufacturing belts drive demand despite thinner transaction volumes.
- Umbrella:Excess liability layers sitting above primary policies. Large corporate purchasers in Tokyo secure higher limits as climate litigation exposure recasts long-tail assumptions for directors and officers coverage.
- National:Japan-wide protection without overseas extension. Mid-market manufacturers favor this tier for operational simplicity and lower premium outlay.
- Local:Prefecture-restricted coverage for small enterprises with concentrated geographic footprints. Regional construction subcontractors and retail operators represent core demand.
International commands margin leadership. Umbrella is climbing the fastest as litigation exposure escalates.
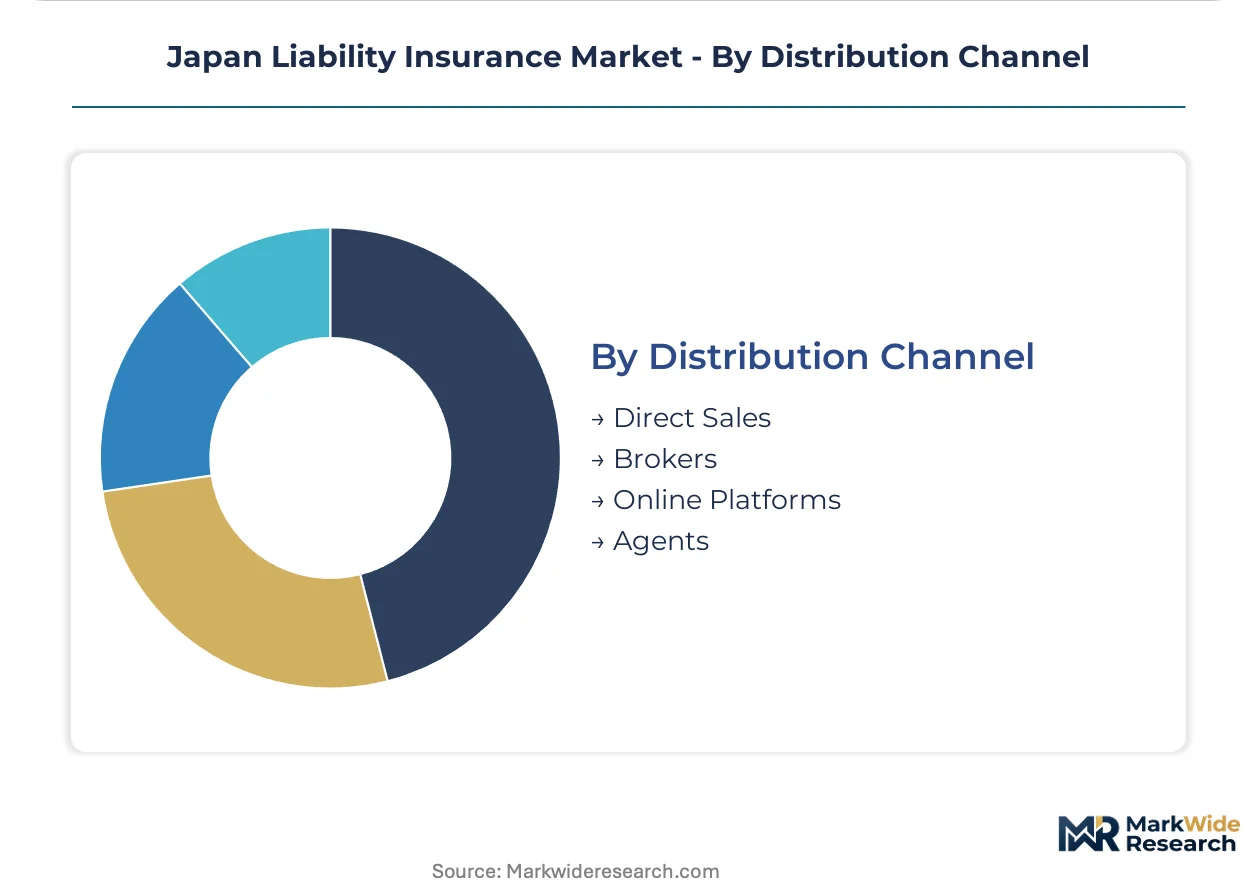
Distribution Channel:
Channel selection reflects purchaser sophistication, with traditional intermediaries retaining corporate relationships and digital platforms capturing small enterprise migration.
- Brokers:Specialized intermediaries managing complex corporate placements. Industrial liability and professional coverage segments resist standardization, preserving broker centrality.
- Agents:Traditional tied-agent networks with localized relationships. Regional prefectures retain agent dominance where digital literacy and platform access remain uneven.
- Online Platforms:Digital aggregators enabling multi-carrier quote comparison. Small enterprises with standardized risk profiles drive channel growth as real-time binding capabilities expand.
- Direct Sales:Carrier-owned channels for large corporate accounts. Tokio Marine and MS&AD deploy dedicated relationship managers for multi-line bundling opportunities.
Brokers retain corporate account control. Online Platforms are expanding most quickly among small enterprise purchasers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI's contractor safety directives are reshaping liability coverage procurement across Japan's major economic zones, with prefectural labor bureaus now mandating documented insurance verification before project authorization.
Kanto/Tokyo
Heavy civil engineering contractors in Tokyo Bay redevelopment zones face compressed procurement timelines under METI's filing requirements. The Financial Services Agency's solvency regulations govern carrier capital reserving for domestic placements. IT consulting clusters in central Tokyo accelerate errors and omissions coverage demand as service economy output expands.
Kansai/Osaka
Osaka's manufacturing corridor concentrates product liability purchasing under Japan's PL Law mandates. Multi-decade claim horizons complicate carrier pricing models for industrial underwriters. Automotive and electronics manufacturers in the Osaka-Kobe industrial belt drive umbrella policy demand as climate litigation exposure escalates.
Chubu/Nagoya
Export-oriented manufacturers in Nagoya's automotive and aerospace supply chains secure international policy extensions despite thinner transaction volumes. METI's industrial safety directives apply to contractor networks serving Toyota City and surrounding production hubs. Regional construction subcontractors adapt to digitized coverage verification systems.
Kyushu
Semiconductor fabrication facilities in Kumamoto and Fukuoka prefectures expand professional liability purchases for technology E&O exposures. The country's national financial regulator oversees carrier solvency for policies covering advanced manufacturing risks. Regional logistics operators deploy telematics-enabled fleet monitoring for commercial auto liability underwriting.
Hokkaido
Agricultural processing and cold-chain logistics operators in Hokkaido seek specialized product liability coverage for food safety exposures. Prefectural infrastructure bureaus mandate documented coverage verification for public works contractors. Sapporo-based construction firms navigate compressed procurement cycles under METI's tightened safety obligations.
Japan Liability Insurance Market Competitive Landscape
On the supply side, the industry is consolidated around a tiered structure where integrated insurance groups dominate premium volume while specialized subsidiaries and digital entrants capture niche segments. Three strategic archetypes define competitive positioning: multi-line corporate bundlers leveraging cross-selling scale, marine heritage specialists anchoring industrial liability placements, and mid-market professional liability competitors utilizing broker network specialization. Dominant competitive moves include multi-line bundling to reduce acquisition costs and digital platform expansion to capture small enterprise migration.
Within the integrated group tier, Tokio Marine & Nichido Fire Insurance Co., Ltd., MS&AD Insurance Group Holdings, Inc., and Aioi Nissay Dowa Insurance Co., Ltd. represent the three archetypal competitive positions. Tokio Marine occupies the marine heritage specialist role, MS&AD exemplifies the multi-line corporate bundling strategy, and Aioi Nissay Dowa sits within the mid-market professional liability segment through specialized distribution relationships.
| Leading Market Players |
|---|
| Sompo Japan Insurance Inc. |
| Rakuten General Insurance Co., Ltd. |
| Tokio Marine & Nichido Fire Insurance Co., Ltd. |
| Tokio Marine Holdings |
| Nisshin Fire & Marine Insurance Co., Ltd. |
| MS&AD Insurance Group Holdings, Inc. |
| Aioi Nissay Dowa Insurance Co., Ltd. |
| Sompo Holdings Inc. |
| Mitsui Sumitomo Insurance Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Tokyo's insurance underwriting cluster concentrates capacity among three integrated groups, creating pricing power asymmetries that downstream purchasers navigate through multi-line bundling negotiations. METI's solvency requirements and FSA capital reserving rules shape cost structures that carriers pass through premium calculations for construction and manufacturing clients.
Pricing Analysis
Policy limit tiers and retroactive date parameters create the primary spread between standard general liability and specialized professional coverage. Premium calculations rest on claims history, exposure limits, and coverage scope, with international extensions capturing wider margins despite thinner volumes. Cost compression in mid-market professional liability is intensifying because broker network fragmentation complicates carrier distribution economics. Small enterprises migrating to online platforms exhibit highest price sensitivity, while large corporate purchasers with complex multi-jurisdictional exposures prioritize coverage breadth over premium minimization.
Supply Chain Analysis
Tokio Marine, MS&AD, and Aioi Nissay Dowa anchor domestic underwriting capacity, with specialized subsidiaries and digital entrants occupying niche segments. Risk capital draws from reinsurance treaties with European and Bermudian markets, while actuarial talent and climate risk modeling capabilities feed from London and Singapore specialist pools. Single-source vulnerability concentrates in legacy policy administration systems that resist real-time digital quoting integration. Distribution runs through broker networks for complex corporate placements, with online platforms and direct sales channels capturing standardized small enterprise risks.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's liability insurance market sits in early-cycle expansion as METI's contractor safety mandates force coverage procurement ahead of project deadlines, accelerating penetration among construction firms previously operating with minimal protection.
For Market Incumbents: Insulate core corporate relationships through multi-line bundling that embeds property and liability coverage into stickier contractual structures. Deepen vertical integration into climate risk analytics capabilities to address emerging environmental liability exposures before actuarial talent scarcity widens pricing disadvantages. Prioritize legacy system modernization to support real-time digital quoting demanded by small enterprise purchasers.
For New Entrants and Emerging Players: Build out specialized professional liability offerings targeting IT consulting clusters in Osaka and Tokyo where service economy expansion outpaces incumbent product development cycles. Regional prefectures outside Kanto and Kansai present underpenetrated small enterprise segments where digital platform aggregation can bypass established agent networks. Lead with telematics-enabled fleet monitoring partnerships to capture commercial auto liability share from logistics operators.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory tailwind play because METI's industrial safety directives and climate litigation precedents structurally expand addressable coverage requirements across Japanese manufacturing and construction. Target acquisition profiles center on mid-market professional liability specialists with established broker network relationships and digital quoting infrastructure. The signal to watch is FSA solvency regulation adjustments that could release trapped capital and reshape competitive capacity allocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Climate Risk Analytics Investment | Addresses emerging environmental liability exposures before actuarial talent scarcity widens pricing gaps. |
| Digital Platform Expansion | Captures small enterprise migration from traditional agent networks in regional prefectures. |
| Multi-Line Corporate Bundling | Creates stickier relationships with heavy civil engineering contractors facing METI filing deadlines. |
| Telematics Fleet Partnership | Enables dynamic premium adjustments for Kanto and Kansai logistics operators. |
| International Policy Extension | Commands wider underwriting margins for Osaka-Nagoya export manufacturers despite thinner volumes. |
Research Methodology
A spread of perspectives from underwriting executives at domestic carriers, specialized liability brokers, construction firm risk managers, and manufacturing procurement leads converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through FSA solvency filings, METI industrial safety directives, Japan PL Law cabinet ordinances, and corporate insurance procurement disclosures. Bottom-up policy volume estimates and top-down premium market sizing were triangulated to establish baseline figures.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation modeling across policy type, client scale, coverage scope, and distribution channel dimensions. CAGRs were derived from trend extrapolation of professional liability expansion against general liability maturation, incorporating climate litigation exposure escalation and service economy output growth as industry-specific forecast inputs.
Stress conditions across interest rate compression, long-tail claim horizon extension, and reinsurance capacity contraction were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about METI regulatory enforcement intensity and digital platform adoption curves. Quarterly review of construction project authorization timelines and climate litigation precedent development is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Event Insurance Market
Insurance
Musical Instrument Insurance Market
Insurance
Japan Property and Casualty Insurance Market
Insurance
Netherlands Property and Casualty Insurance Market
Insurance
India Electronic Gadget Insurance Market
Insurance
Specialty Insurance Market
Insurance
Switzerland Reinsurance Market
Insurance
Extended Warranty Agreement Market
Insurance
Auto Extended Warranty Market
Insurance
Insurance Third Party Administrators Market
Insurance
Europe Bancassurance Market
Insurance
Canada House Insurance Market
Insurance
North America Family Floater Health Insurance Market
Insurance
US Homeowner's Insurance Market
Insurance
Asia-Pacific Group Health Insurance Market
Insurance
USA Travelers Insurance Market