
 United Kingdom Health and Medical Insurance Market | 2026-2036
United Kingdom Health and Medical Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Health and Medical Insurance Market Analytics
Subscription-based wellness add-ons is rebalancing core policy economics away from pure claims coverage. Bupa leverages its clinic network to anchor integrated care propositions. VitalityHealth differentiates through behavior-linked reward structures. WPA competes on niche professional and affinity group channels.
United Kingdom health and medical insurance constitutes risk-pooled financial protection against private medical treatment costs, typically underwriting surgical procedures, diagnostic imaging, and specialist consultations with defined annual benefit limits and excess thresholds. Its primary commercial purpose is to reduce National Health Service waiting list exposure for policyholders while enabling provider choice. Individual Plans occupy the fastest-growing structural position as gig-economy and self-employed workers seek portable coverage outside employer schemes. Value-Based Care payment models concentrate margin pools through outcome-linked contracts with private hospital networks.
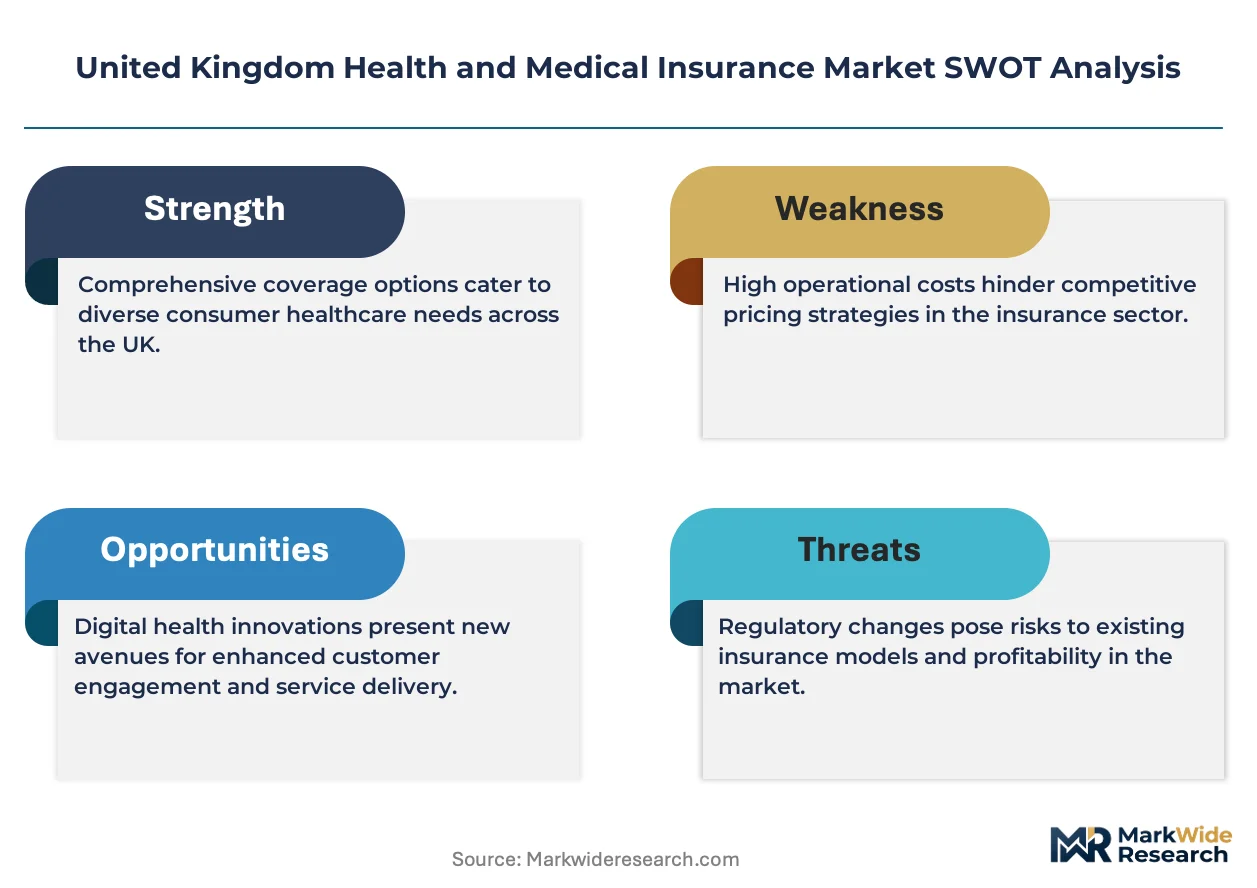
The Financial Conduct Authority's Consumer Duty mandates fair value assessments across distribution chains, while the Prudential Regulation Authority governs insurer solvency and capital adequacy. Competition and Markets Authority scrutiny of broker commission structures shapes direct-to-consumer channel economics. Stakeholders must monitor how NHS backlog reduction targets alter the relative value proposition of supplementary private coverage.
Market Dynamics
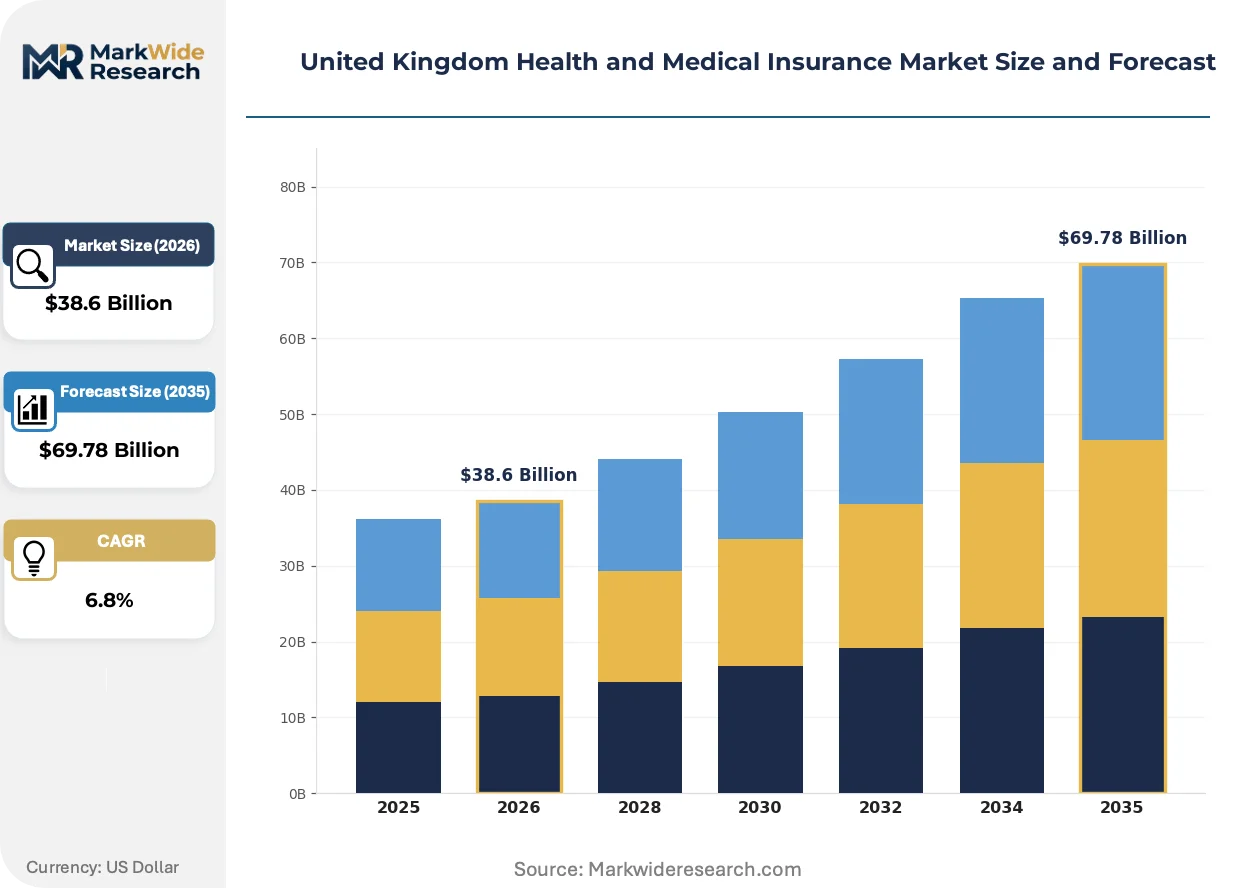
The Financial Conduct Authority's Consumer Duty is compressing distribution margins and forcing product redesign across UK health insurers, while NHS waiting list persistence sustains underlying demand for supplementary private coverage.
Growth Catalysts
- FCA Consumer Duty Implementation:The regulator's fair value requirements are stripping opaque commission structures from broker channels. Direct-to-consumer platforms gain volume as price transparency becomes enforceable.
- Self-Employed Professional Expansion:Gig-economy workers across Greater Manchester and Birmingham seek portable individual plans outside employer schemes. This segment now drives fastest-growing policy issuance.
- Value-Based Care Contracts:Outcome-linked payment models with private hospital networks concentrate margin pools. Insurers capture savings from reduced readmission rates and bundled procedure pricing.
Market Restraints
- Medical Cost Inflation:Private hospital input costs, particularly specialist nursing wages and pharmaceutical procurement, outpace premium rate adjustments. Margin compression hits standard-tier products first.
- London Market Concentration:Financial services firms dominate group coverage purchasing. Geographic demand clustering limits scalable distribution infrastructure for rural and northern England expansion.
- NHS Backlog Reduction Targets:Government elective recovery programs threaten the core value proposition of queue-jumping. Policy lapse risk rises if waiting times compress materially.
Strategic Opportunities
- Wellness Subscription Integration:Behavior-linked reward structures attach wearable data and preventive services to core medical coverage. VitalityHealth's model demonstrates attach-rate potential for mental health and fitness modules.
- Affinity Group Channel Development:Professional associations and sector-specific collectives remain underpenetrated. Niche brokers in medical, legal, and technology professions offer scalable acquisition economics.
- Diagnostic Imaging Pre-authorization:AI-assisted triage tools reduce unnecessary specialist referrals. Early-stage pilots with private hospital networks show claims cost reduction without member abrasion.
Industry Challenges
- Legacy System Integration:Core policy administration platforms require multimillion-pound replacement to support real-time wellness data ingestion. Mid-tier insurers face build-versus-partner decisions with compressed timelines.
- Actuarial Talent Scarcity:Pricing functions lack expertise in behavior-linked product design. Competition with fintech and general insurance sectors elevates compensation costs for predictive modeling specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Health and Medical Insurance Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Individual Plans, Family Plans, Group Plans, Corporate Plans Policy Coverage: Outpatient Care, Inpatient Services, Preventive Care, Catastrophic Coverage Payment Model: Fee-for-Service, Capitation, Value-Based Care, Hybrid Model Customer Segment: Individuals, Families, Employers, Self-Employed |
| Companies Covered | VitalityHealth, Benenden Health, Bupa, Freedom Health Insurance, The Exeter, AXA Health, WPA, Allianz, Aviva, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Health and Medical Insurance Market Evolving Landscape
Digital health infrastructure is collapsing traditional boundaries between insurance, diagnostics, and acute care delivery. Technology convergence and regulatory pressure are accelerating product architecture redesign.
Telemedicine platforms are unifying primary care access with insurance policy administration. Corporate group schemes now mandate virtual GP services as standard benefits. This compression eliminates friction between symptom onset and specialist referral authorization.
The Prudential Regulation Authority's solvency stress-testing requirements are elevating capital adequacy standards for health insurers writing long-term care riders. Product development teams must embed lapse risk and morbidity trend assumptions into pricing models. Standard-tier individual plans face the steepest reserve requirement adjustments.
Employer procurement patterns are fragmenting across sector-specific needs. Financial services firms in London demand executive wellness packages with international evacuation coverage. Manufacturing employers in the West Midlands prioritize occupational injury and rapid-return-to-work rehabilitation services. Channel specialization now outperforms generalized group broking.
United Kingdom Health and Medical Insurance Market Segmentation
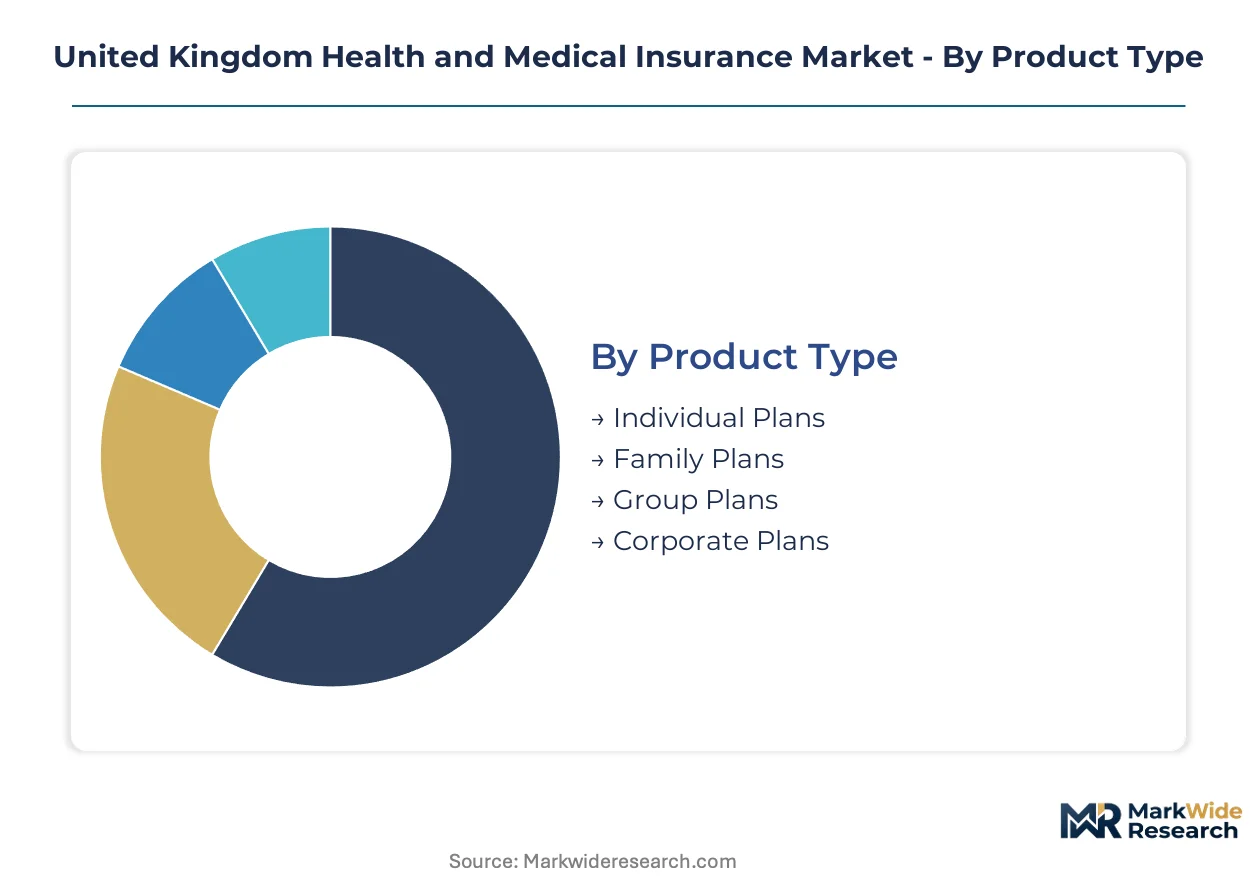
Segmentation in UK health insurance reveals how product architecture must align with divergent risk appetites and purchasing authority. Individual portability demands, employer procurement scale, and NHS interaction patterns each reshape policy design and distribution economics.
Product Type:
Volume concentrates in employer-sponsored schemes while premium rate expansion favors individual portability.
- Individual Plans:Portable coverage purchased directly by policyholders outside employer schemes. Demand clusters among self-employed professionals in Greater Manchester and Birmingham seeking flexibility amid gig-economy workforce expansion.
- Family Plans:Multi-life policies covering dependents under unified underwriting and excess thresholds. London-based financial services households drive concentration, prioritizing pediatric specialist access and maternity pathway choice.
- Group Plans:Small-to-medium employer schemes with standardized benefit tiers and collective pricing. Regional professional services firms outside the capital utilize affinity structures to access risk-pooled rates.
- Corporate Plans:Large-scale enterprise procurement with bespoke benefit design and wellness integration. National headquarters procurement teams negotiate outcome-linked contracts with private hospital networks.
Today's leader: Corporate Plans. Tomorrow's challenger: Individual Plans.
Policy Coverage:
Cost tier differentiation separates routine access products from catastrophic financial protection.
- Outpatient Care:Coverage for specialist consultations, diagnostic imaging, and day-case procedures without overnight admission. Birmingham's private hospital corridor sees concentration as NHS diagnostic backlogs persist.
- Inpatient Services:Surgical admission and overnight facility costs with defined consultant choice rights. London financial services group schemes mandate comprehensive inpatient as baseline coverage.
- Preventive Care:Wellness screenings, vaccination programs, and lifestyle intervention benefits. VitalityHealth's behavior-linked reward structure demonstrates attach-rate potential for this tier.
- Catastrophic Coverage:High-excess protection against major illness costs with premium savings versus comprehensive products. Self-employed segments in northern England favor this cost-controlled entry point.
Core revenue still flows through Inpatient Services. Preventive Care is climbing the fastest as subscription wellness models rebase policy economics.
Payment Model:
Customer type determines whether fee certainty or outcome accountability governs provider contracting.
- Fee-for-Service:Itemized reimbursement for each procedure, consultation, and facility day. Traditional private hospital networks retain this model for standard-tier individual policyholders.
- Capitation:Fixed per-member-per-month payments to provider networks regardless of utilization volume. Bupa's clinic network leverages captive capacity to absorb utilization risk.
- Value-Based Care:Outcome-linked contracts tying reimbursement to readmission rates, complication thresholds, and bundled episode pricing. Insurers capture margin through reduced length-of-stay and procedure standardization.
- Hybrid Model:Blended structures combining capitation for primary access with fee-for-service for complex specialty care. Corporate procurement teams negotiate these arrangements for workforce coverage.
Fee-for-Service still dominates transaction volume. Value-Based Care offers the steepest expansion trajectory as actuarial capabilities mature.
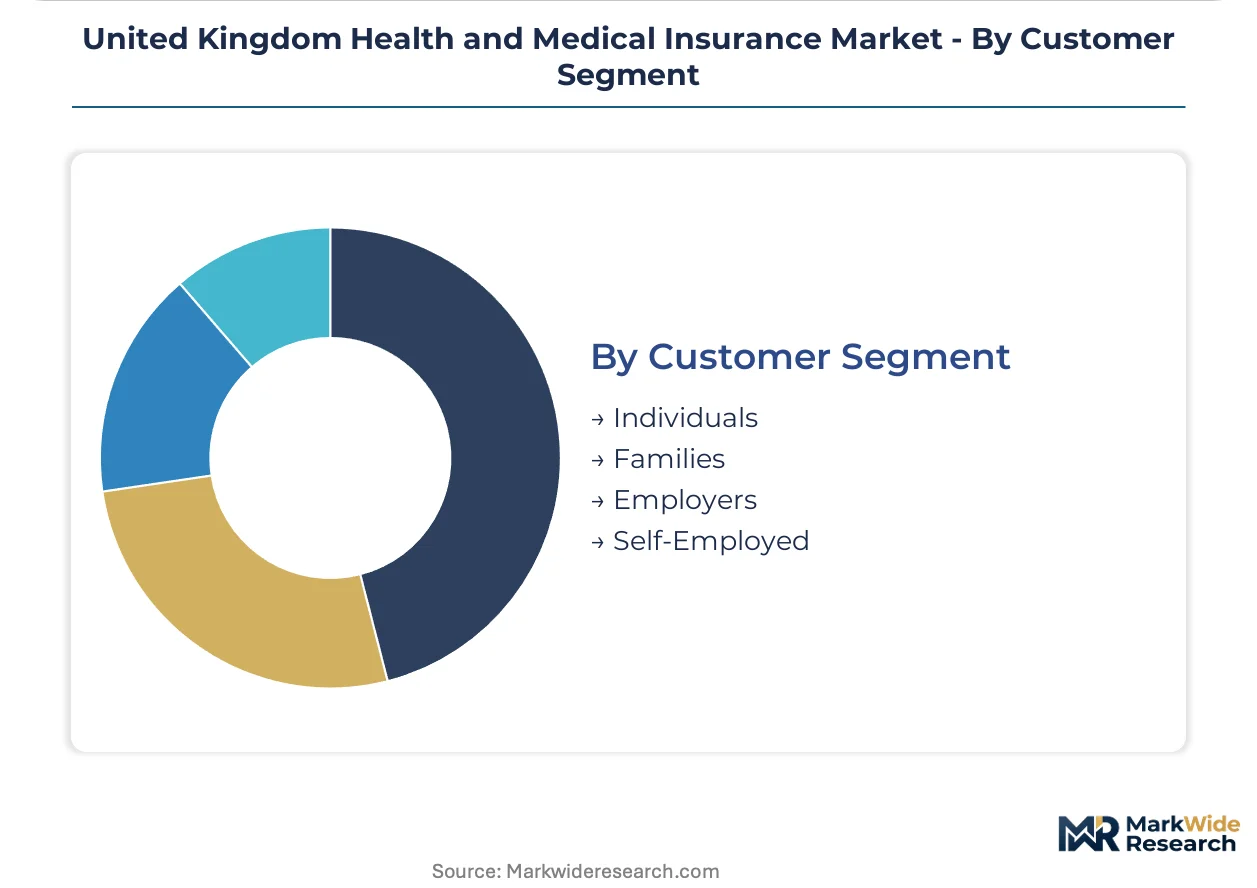
Customer Segment:
Geography and employment status fragment purchasing authority and benefit priorities.
- Individuals:Direct purchasers seeking portable coverage with defined excess preferences. Digital-native platforms capture this segment through price-transparent comparison tools.
- Families:Multi-life household decisions prioritizing dependent coverage and pediatric network breadth. Affinity channels through professional associations penetrate this segment efficiently.
- Employers:Organizational procurement with scale-negotiated rates and workforce productivity objectives. Financial services firms in London demand executive wellness packages with international evacuation coverage.
- Self-Employed:Gig-economy and freelance workers outside traditional employment benefit structures. This segment is expanding most quickly as portable individual plan design improves.
Employers command current premium volume. Self-Employed policy issuance is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United Kingdom health insurance demand patterns diverge sharply from continental European social insurance models, while London's financial services concentration creates purchasing power density unmatched elsewhere in northern Europe.
London and Southeast England
Financial services firms headquartered in the City and Canary Wharf drive corporate plan procurement at scale. The Financial Conduct Authority's Consumer Duty rules reshape broker commission structures across this corridor. Westminster and Southwark host the densest concentration of specialist health insurance intermediaries serving executive wellness mandates.
Midlands
Greater Birmingham anchors self-employed professional demand for portable individual plans outside employer schemes. NHS England elective recovery programs target backlog reduction at University Hospitals Birmingham NHS Foundation Trust. Solihull and Coventry private hospital clusters absorb diagnostic imaging overflow from persistent NHS waiting lists.
North England
Manchester's professional services expansion fuels affinity group channel development for legal and technology sector workers. NHS waiting list persistence sustains supplementary private coverage uptake across Greater Manchester Integrated Care Board territory. Leeds and Sheffield manufacturing employers prioritize occupational injury and rapid-return-to-work rehabilitation benefits.
Scotland
Edinburgh's fund management and insurance sector concentrates corporate group scheme purchasing. NHS Scotland performance targets for elective procedures influence private coverage lapse risk calculations. Glasgow's private hospital capacity expansion addresses Central Belt demand for queue-jumping surgical access.
Wales
Cardiff's professional services growth lags English counterparts in private health insurance penetration. NHS Wales waiting list metrics remain elevated relative to England, sustaining core value propositions for supplementary coverage. Newport and Swansea corridor development attracts individual plan marketing from digital-native distribution platforms.
United Kingdom Health and Medical Insurance Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated health services providers commanding premium positioning while affinity channel specialists capture niche professional verticals. Market structure tilts toward consolidation among three national-scale underwriters with captive provider networks, mid-tier insurers competing through direct-to-consumer digital platforms, and specialist mutuals retaining professional association distribution lock-in. Strategic archetypes include clinic-integrated health services conglomerates, behavior-linked wellness reward platforms, and niche affinity group channel specialists. Capacity expansion through private hospital network partnerships and portfolio diversification into subscription wellness modules dominate competitive moves.
Within the integrated health services tier, Bupa anchors clinic-networked propositions through captive facility ownership. VitalityHealth and WPA exemplify divergent specialization vectors—behavior-linked reward structures versus professional affinity channel depth. These three occupy distinct positioning territories without direct feature overlap.
| Leading Market Players |
|---|
| VitalityHealth |
| Benenden Health |
| Bupa |
| Freedom Health Insurance |
| The Exeter |
| AXA Health |
| WPA |
| Allianz |
| Aviva |
| Others |
Value Network & Pricing Analysis
Specialist nursing wage indices and pharmaceutical procurement benchmarks cascade through UK health insurance pricing tiers, compressing margins on standard-tier products while premium segments absorb cost pass-through via wellness bundling. The Financial Conduct Authority's Consumer Duty accelerates price transparency, stripping opaque broker commissions and forcing direct-to-consumer platforms to compete on disclosed value metrics.
Pricing Analysis
Capacity additions in Greater Manchester and Birmingham private hospital corridors are reshaping price floors for diagnostic imaging and day-case procedures. Three-tier pricing structure across premium, standard, and economy levels separates corporate wellness-integrated plans from self-employed catastrophic coverage and NHS top-up products. Cost compression in standard tiers intensifies because medical cost inflation outpaces premium adjustments, with self-employed segments in northern England exhibiting highest price sensitivity while London financial services firms show lowest.
Supply Chain Analysis
Refurbished medical equipment flows and remanufactured diagnostic device programs are emerging as secondary supply channels for mid-tier insurers seeking capital expenditure relief. Geographic supply concentration rests on domestic private hospital networks in England, imported pharmaceutical APIs from Switzerland and Ireland, and medical device manufacturing from Germany and the Netherlands. Single-source vulnerability attaches to specialist nursing labor pools in London and Southeast England. Distribution runs through broker-intermediated channels, direct-to-consumer digital platforms, and affinity group professional associations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through value-based care contract penetration and wellness subscription attach-rate growth, with outcome-linked provider payments reducing claims cost volatility.
For Market Incumbents: To counter NHS backlog reduction programs threatening queue-jumping value propositions, anchor retention through integrated care propositions leveraging captive clinic networks, and deepen outcome-linked contracting with private hospital networks to capture shared savings pools. For New Entrants and Emerging Players: Enter via affinity group channels targeting legal and technology sector professional associations in Greater Manchester, where portable individual plan demand outstrips specialized distribution capacity, using digital-native price comparison tools as primary acquisition mechanics. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier insurers lack capital reserves for core policy administration platform replacement, favoring acquisition targets with established direct-to-consumer digital infrastructure and behavior-linked product design capabilities; monitor NHS elective recovery program performance metrics as inflection indicator for supplementary coverage lapse risk.| Strategic Initiative | Industry Significance |
|---|---|
| Value-Based Care Contracting | Outcome-linked payments with private hospital networks concentrate margin pools through readmission reduction. |
| Wellness Subscription Integration | Behavior-linked reward structures attach wearable data and preventive services to core medical coverage. |
| Direct-to-Consumer Platform Investment | FCA Consumer Duty compliance accelerates price-transparent digital channel economics. |
| Affinity Group Channel Development | Professional association distribution lock-in captures scalable acquisition economics in underserved verticals. |
| Diagnostic Imaging Pre-authorization | AI-assisted triage tools reduce unnecessary specialist referrals without member abrasion. |
Research Methodology
Bottom-up employer and individual policyholder modeling reconciled against top-down private hospital capacity and insurer premium tracking forms the analytical core of this study. Primary interviews with health insurance product development executives, private hospital network contracting officers, broker channel principals, and Financial Conduct Authority policy specialists combined with secondary validation against Prudential Regulation Authority solvency filings, NHS England waiting list statistics, and Competition and Markets Authority market studies. Triangulation across these sources ensures segment-level volume and pricing estimates reflect operational reality.
Historical trendline analysis of policy issuance patterns, premium rate movements, and claims cost trajectories informed projection modeling across the analysis window. Segmentation dimensions include product architecture, policy coverage tier, payment model structure, and customer employment status. CAGRs derive from fitted trend extrapolation adjusted for regulatory intervention effects and NHS performance scenario weighting. Forecast inputs incorporate private hospital wage inflation assumptions and wellness module attach-rate penetration curves.
The model holds under persistent NHS waiting list conditions and stable regulatory enforcement intensity; deviation in elective recovery program success or Consumer Duty implementation scope would shift volume and value projections. Forecasts reflect documented assumptions about morbidity trends and lapse rate behavior. Practitioners should monitor NHS backlog reduction metrics and FCA supervisory activity levels for early signals of value proposition erosion or distribution channel restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
India Parametric Insurance Market
Insurance
Asia-Pacific Livestock Insurance Market
Insurance
New Zealand Property and Casualty Insurance Market
Insurance
Singapore Property and Casualty Insurance Market
Insurance
Norway Property and Casualty Insurance Market
Insurance
Saudi Arabia Health Insurance Market
Insurance
Bancassurance in ASEAN Market
Insurance
Agriculture Insurance Market
Insurance
Employee Benefit Broker Market
Insurance
Spain Parametric Insurance Market
Insurance
Digital Innovation in Insurance Market
Insurance
Business Travel Insurance Market
Insurance
Business Income Insurance Market
Insurance
UK Commercial Insurance Market
Insurance
Consumer Electronics Extended Warranty Market
Insurance
Insurance Protection Products Market