
 Asia-Pacific Livestock Insurance Market | 2026-2036
Asia-Pacific Livestock Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Livestock Insurance Market Analytics
Multi-source underwriting partnerships is decoupling from traditional single-carrier models across the Asia-Pacific livestock insurance sector. ICICI Lombard General Insurance Company Limited leverages its rural branch network to reach smallholder farmers in Maharashtra and Gujarat. The New India Assurance Co. Ltd anchors the public-sector segment through government-mandated livestock schemes. HDFC ERGO General Insurance Company Limited differentiates via digitized claims assessment tools for remote pastoral regions.
Livestock insurance constitutes risk-transfer instruments covering mortality, disease, and production losses across bovine, avian, and porcine populations, with policies typically structured around indemnity triggers or indexed weather parameters to compensate agricultural enterprises for biological asset depletion. Cattle coverage dominates premium volumes given herd sizes and unit values across India and Australia, while indexed products represent the fastest-growing policy structure as parametric payouts reduce claims adjustment costs. Disease protection coverage commands elevated margins relative to standard death coverage due to veterinary verification requirements and outbreak response protocols.
India's PMFBY framework and Australia's Department of Agriculture, Fisheries and Forestry guidelines shape product design and subsidy eligibility across their respective jurisdictions. BIS standards and India's CEA directives influence policy documentation and disclosure norms for domestic insurers. Stakeholders must monitor evolving climate-index trigger calibration as drought frequency intensifies across the region's rangelands.
Market Dynamics
Parametric weather-index triggers are displacing traditional indemnity structures across Asia-Pacific livestock insurance, compressing claims adjustment timelines from months to days while requiring recalibration of actuarial models for intensifying drought frequency.
Growth Catalysts
- PMFBY subsidy framework:India's Pradhan Mantri Fasal Bima Yojana channels public funds into livestock coverage, expanding policy penetration across Maharashtra and Gujarat dairy cooperatives.
- Remote sensing integration:Satellite-based pasture monitoring enables automated forage-loss triggers, reducing field verification costs for Australian cattle station underwriters.
- Commercial herd expansion:Southeast Asian integrated poultry operations are scaling mortality coverage purchases as biosecurity regulations tighten.
Market Restraints
- Veterinary verification bottlenecks:Disease outbreak confirmation requires BIS-compliant laboratory protocols, extending payout timelines during contagious episodes.
- Actuarial data scarcity:Smallholder mortality records remain fragmented across India's informal dairy sector, inflating premium loadings for non-commercial policies.
- Climate index basis risk:Grid-based weather stations poorly correlate with localized pasture conditions in Australia's Northern Territory rangelands.
Strategic Opportunities
- Indonesia's underpenetrated archipelago:Small ruminant coverage in Eastern Indonesia remains below 5 percent penetration, creating first-mover positioning for mobile-enabled distribution.
- CEA-mandated disclosure standardization:India's Central Electricity Authority directives on documentation norms are streamlining policy comparison platforms.
- Blockchain-IoT convergence:Ear-tag sensor data paired with distributed ledger verification is enabling real-time mortality confirmation for high-value breeding stock.
Industry Challenges
- Veterinary epidemiologist shortages:Field verification capacity constraints in India's dairy belt states delay outbreak response and claims processing.
- Legacy core system integration:Established insurers face middleware complexity when connecting parametric payout engines to existing policy administration platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Livestock Insurance Market |
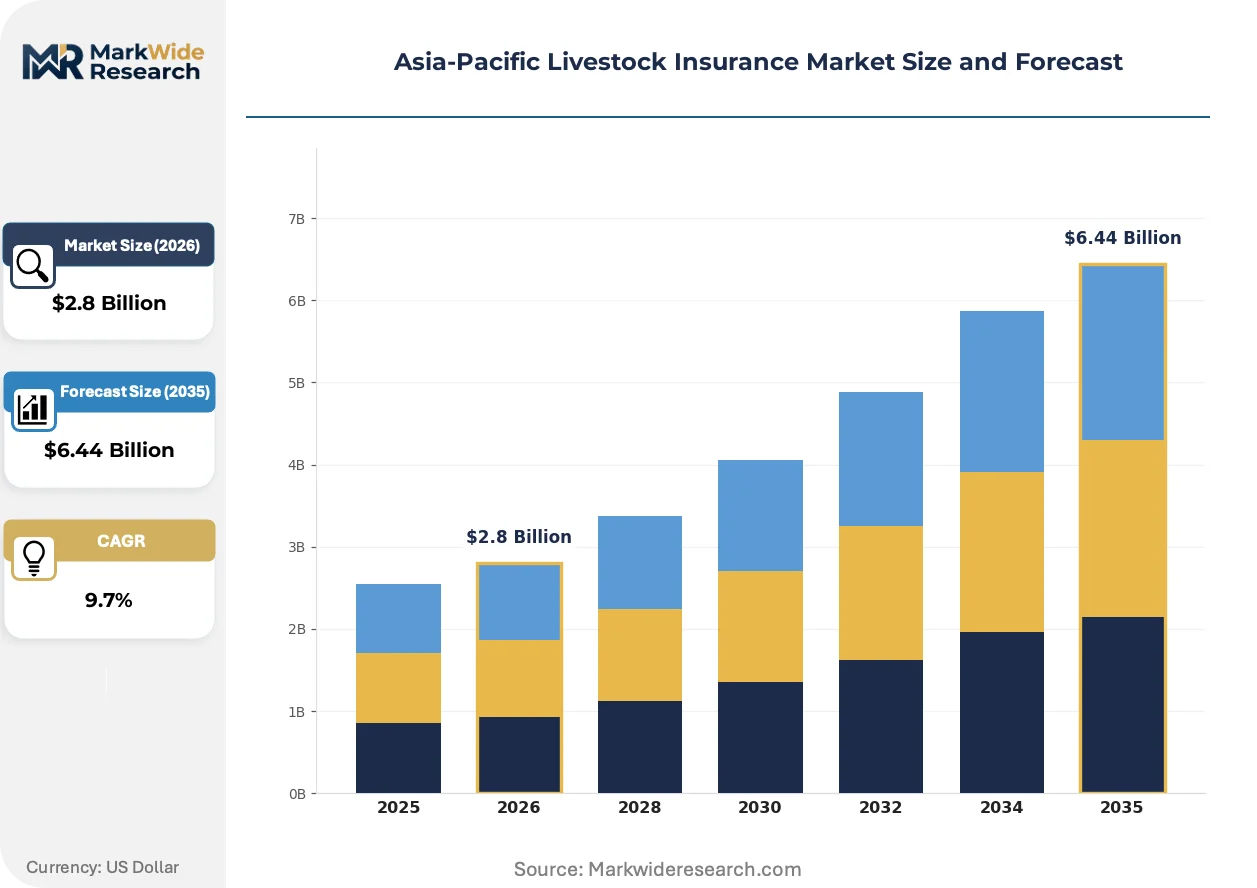
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.44 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cattle, Poultry, Swine, Goats Coverage Type: Production Loss, Disease Protection, Property Damage, Death Coverage End User: Farmers, Breeders, Cooperatives, Livestock Companies Policy Structure: Indemnity, Indexed, Multi-Peril, Named Peril |
| Companies Covered | AXA XL, The New India Assurance Co. Ltd, The Oriental Insurance Company Limited, HDFC ERGO General Insurance Company Limited, ICICI Lombard General Insurance Company Limited, Future Generali India Insurance Company Ltd, Tata AIG General Insurance Company Limited, Reliance General Insurance, Royal Sundaram General Insurance Co. Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Livestock Insurance Market Evolving Landscape
Digital infrastructure is compressing the distance between risk origination and payout execution across Asia-Pacific livestock insurance, enabling new entrants to bypass traditional branch networks entirely.
Remote sensing technology is integrating satellite-derived normalized difference vegetation index (NDVI) data with automated trigger mechanisms. Australian cattle station underwriters are adopting these tools fastest, with pilot programs now operational across Queensland and Northern Territory leaseholds. This capability is integrating directly into reinsurance pricing models, collapsing the traditional separation between risk assessment and capital allocation functions.
India's CEA disclosure directives are mandating standardized policy documentation formats for domestic insurers. The industrial consequence is accelerated platform consolidation, as smaller regional carriers lack compliance infrastructure. Dairy cooperatives in Gujarat and Punjab are most affected, responding by migrating coverage procurement to digitally intermediated group policies.
Cooperative purchasing collectives are displacing individual farmer transactions across India's dairy belt. Dairy cooperative societies in Maharashtra and Karnataka are aggregating smallholder exposure into single master policies, replacing direct insurer relationships. This pattern is most visible in Gujarat's Amul-linked procurement networks, where volume concentration is extracting preferential premium terms from underwriters.
Asia-Pacific Livestock Insurance Market Segmentation
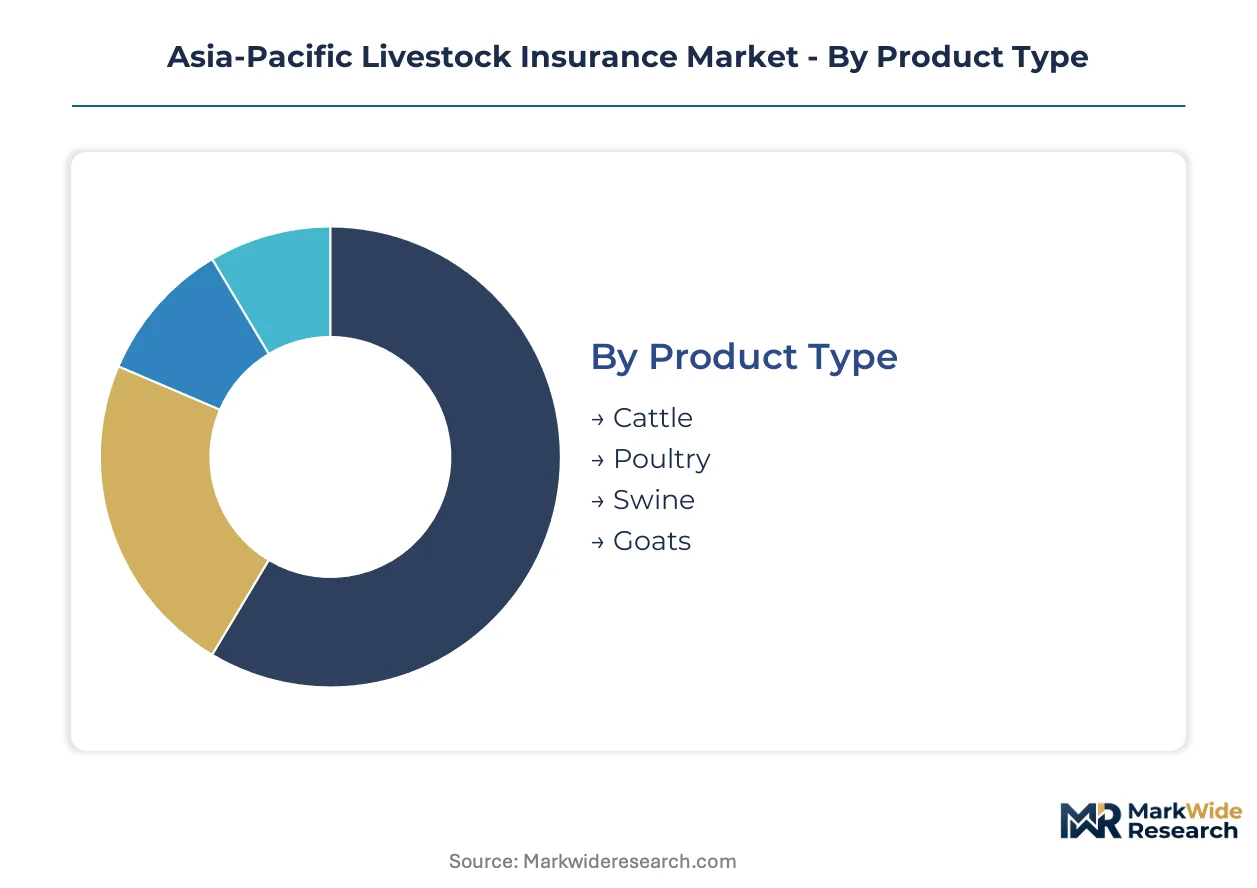
Segmentation in Asia-Pacific livestock insurance reveals divergent risk profiles across species, coverage triggers, and buyer sophistication. Underwriters calibrate pricing models and distribution channels around these structural differences rather than treating livestock as a uniform risk class.
Product Type:
Species selection correlates directly with unit economics and veterinary infrastructure density across the region.
- Cattle:Policies cover mortality and disease in dairy and beef herds, with sum insured values reflecting breed pedigree and milk yield history. Premium volumes concentrate in India's Maharashtra and Gujarat dairy belt, where cooperative procurement networks aggregate smallholder exposure into master policies.
- Poultry:Avian influenza outbreaks and heat stress mortality drive coverage design for layer and broiler operations. Southeast Asian integrated producers in Thailand and Vietnam are scaling mortality purchases as biosecurity regulations tighten and export certification demands intensify.
- Swine:African swine fever exposure shapes policy exclusions and premium loadings across East Asian pork production clusters.
- Goats:Small ruminant coverage remains underdeveloped in Eastern Indonesia and Papua New Guinea, with mobile distribution pilots targeting pastoral communities.
Volume sits with cattle; growth tilts toward poultry.
Coverage Type:
Risk transfer mechanisms diverge based on loss verification feasibility and outbreak response protocols.
- Death Coverage:Standard mortality policies indemnify confirmed livestock losses through veterinary certification or sensor-based confirmation. Australian cattle stations favor this structure for breeding stock, where individual animal value justifies per-head documentation.
- Disease Protection:Outbreak-triggered policies cover culling costs and movement restrictions under BIS-compliant laboratory protocols. Margins exceed standard mortality coverage due to epidemiologist verification requirements and government response coordination.
- Production Loss:Milk yield shortfall and weight gain deficiency policies require longitudinal productivity records, limiting penetration to commercial operations with digitized herd management.
- Property Damage:Barn, fencing, and equipment coverage attaches to livestock policies in cyclone-prone Queensland and typhoon-exposed Philippine provinces.
Death coverage dominates premium flow; disease protection commands the steepest expansion trajectory.
End User:
Buyer scale determines policy structure, premium negotiation leverage, and claims servicing channels.
- Cooperatives:Dairy societies in Gujarat and Karnataka aggregate smallholder exposure, extracting volume discounts and standardized terms from underwriters. Amul-linked procurement networks exemplify this concentration.
- Livestock Companies:Integrated poultry and pork producers in Thailand and Vietnam purchase enterprise-level coverage with captive retention layers, bypassing traditional retail distribution.
- Farmers:Individual smallholders in India's informal dairy sector face premium loadings due to fragmented mortality records and asymmetric information.
- Breeders:High-value genetic stock operations require specialized mortality confirmation through blockchain-IoT ear-tag verification.
Cooperative purchasing concentrates volume; corporate livestock operations are expanding coverage fastest.
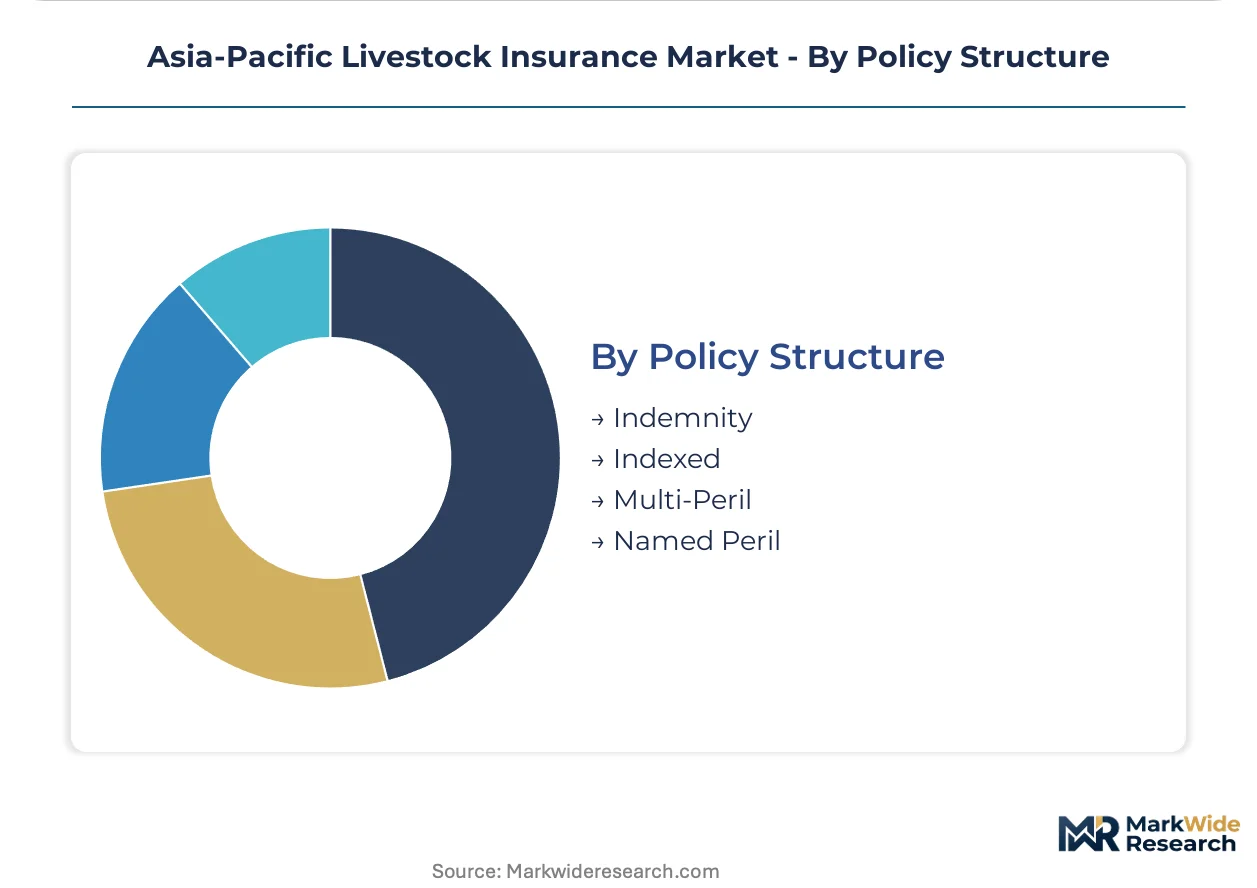
Policy Structure:
Claims settlement mechanics separate traditional indemnity from parametric innovation.
- Indexed:Weather-index and NDVI-triggered policies automate payouts based on satellite-derived pasture conditions or temperature thresholds. Queensland and Northern Territory leaseholds are adopting these tools fastest, collapsing claims adjustment from months to days.
- Indemnity:Loss verification through field assessment remains standard for high-value breeding stock where individual animal identification justifies per-head documentation costs.
- Multi-Peril:Bundled coverage combining mortality, disease, and weather exposure appeals to diversified livestock operations seeking administrative simplicity.
- Named Peril:Specific-risk policies targeting flood, drought, or cyclone exposure dominate in Philippine and Indonesian coastal provinces with concentrated hazard profiles.
Indemnity structures retain volume dominance; indexed products are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India and Australia concentrate premium volumes through divergent mechanisms: India's PMFBY subsidy channels and Australia's extensive cattle station networks. Southeast Asian commercial operations are accelerating coverage purchases as biosecurity frameworks tighten.
India
Dairy cooperatives in Maharashtra and Gujarat aggregate smallholder exposure into master policies through Amul-linked procurement networks. The PMFBY framework channels public subsidies into livestock coverage, accelerating policy penetration across the dairy belt. Veterinary epidemiologist shortages in Karnataka and Punjab delay outbreak response and compress margins for disease protection products.
Australia
Queensland and Northern Territory cattle stations favor indemnity structures for high-value breeding stock where individual animal identification justifies documentation costs. The Department of Agriculture, Fisheries and Forestry guidelines shape product design and subsidy eligibility for pastoral leaseholds. Satellite-derived NDVI triggers are operational across extensive rangelands, collapsing claims adjustment timelines from months to days.
Thailand
Integrated poultry producers scale mortality coverage purchases as export certification demands intensify and biosecurity regulations tighten. The country's national agricultural regulator mandates laboratory protocols for avian influenza outbreak confirmation. Bangkok-based livestock operations are consolidating procurement through enterprise-level policies with captive retention layers.
Indonesia
Small ruminant coverage in Eastern Indonesia remains below five percent penetration, creating positioning opportunities for mobile-enabled distribution pilots targeting pastoral communities. The archipelago's fragmented veterinary infrastructure extends payout timelines during disease episodes. Sulawesi and Nusa Tenggara clusters are testing cooperative purchasing models adapted from Indian dairy society templates.
Vietnam
Commercial pork producers purchase enterprise-level coverage as African swine fever exposure shapes policy exclusions and premium loadings. The national livestock development framework influences subsidy eligibility for disease protection products. Mekong Delta integrated operations are migrating from individual farmer transactions to volume-aggregated master policies.
Asia-Pacific Livestock Insurance Market Competitive Landscape
Multi-source underwriting partnerships dominate the current landscape, decoupling from traditional single-carrier models. The sector exhibits a tiered structure: public-sector anchors, private-sector generalists with rural networks, and digitized specialists targeting remote regions. Three archetypes define positioning: government-mandated scheme administrators, branch-network generalists, and parametric technology integrators. Portfolio diversification into indexed products and geographic expansion through cooperative procurement networks represent the dominant competitive vectors.
Within the public-sector tier, The New India Assurance Co. Ltd anchors government-mandated livestock schemes through established administrative infrastructure. ICICI Lombard General Insurance Company Limited and HDFC ERGO General Insurance Company Limited exemplify private-sector archetypes: the former leverages rural branch density in Maharashtra and Gujarat, while the latter occupies a position in digitized claims assessment for remote pastoral regions. AXA XL represents the international reinsurance and specialty risk segment, sitting within the parametric and large-commercial tier. These three entities collectively illustrate the competitive segmentation between subsidy-dependent public provision, network-driven retail distribution, and technology-enabled specialty underwriting.
| Leading Market Players |
|---|
| AXA XL |
| The New India Assurance Co. Ltd |
| The Oriental Insurance Company Limited |
| HDFC ERGO General Insurance Company Limited |
| ICICI Lombard General Insurance Company Limited |
| Future Generali India Insurance Company Ltd |
| Tata AIG General Insurance Company Limited |
| Reliance General Insurance |
| Royal Sundaram General Insurance Co. Limited |
| Others |
Value Network & Pricing Analysis
Captive distribution through dairy cooperative networks anchors both supply positioning and premium-setting power across India's livestock insurance sector. Maharashtra and Gujarat's Amul-linked procurement societies aggregate smallholder exposure into master policies, extracting volume discounts that individual farmers cannot access and compressing margins for direct-to-farmer retail channels.
Pricing Analysis
Warranty-style bundling of veterinary services with mortality coverage separates premium tiers across the Asia-Pacific livestock insurance sector. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade of underwriting partner and volume scale of cooperative procurement. Cost compression in standard tiers is intensifying because satellite-based parametric triggers reduce claims adjustment overhead. Individual smallholders in India's informal dairy sector exhibit highest price sensitivity; integrated poultry operations in Thailand demonstrate lowest sensitivity due to export certification requirements.
Supply Chain Analysis
Reverse-logistics flows for policy documentation and claims verification create distribution chokepoints across remote pastoral regions. Insurance product development concentrates in India, Australia, and Singapore; reinsurance capacity draws from London and Bermuda markets. Actuarial modeling rests on fragmented mortality databases and satellite-derived NDVI feeds. Single-source vulnerability sits with India's PMFBY subsidy administration infrastructure. Distribution runs through cooperative procurement networks in dairy belts and direct enterprise sales for commercial livestock operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
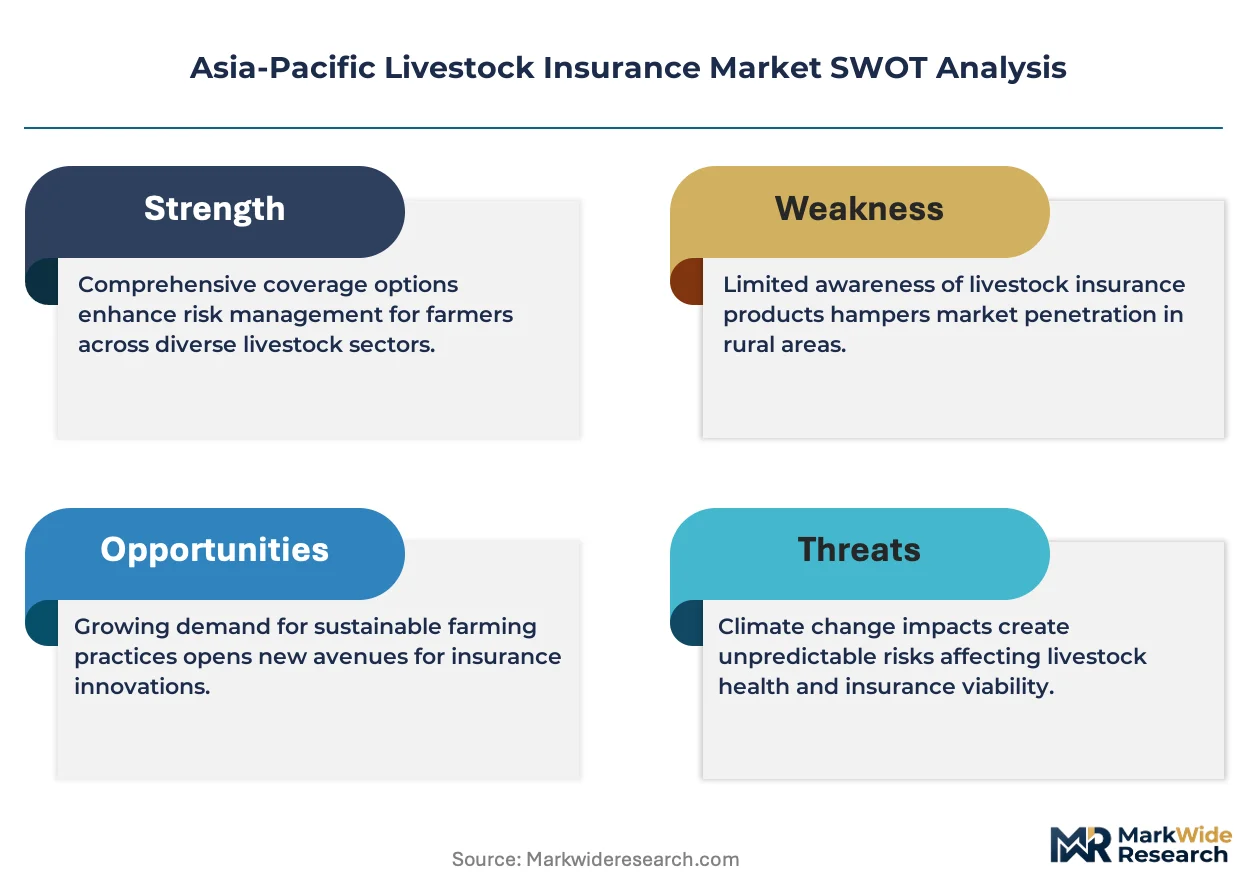
Asia-Pacific livestock insurance is consolidating around technology-enabled underwriters capable of parametric product deployment, with legacy carriers lacking digitized claims infrastructure facing displacement.
For Market Incumbents: Acquire satellite-data analytics capabilities to compress claims adjustment timelines from months to days. HDFC ERGO's digitized assessment tools for remote pastoral regions demonstrate defensive positioning against parametric specialists. Backward integration into veterinary verification networks addresses epidemiologist shortage bottlenecks in Karnataka and Punjab. Channel control through exclusive dairy cooperative partnerships in Gujarat and Maharashtra protects premium flow from new entrants. For New Entrants and Emerging Players: PMFBY subsidy framework in India opens a window for mobile-enabled distribution targeting Eastern Indonesia's underpenetrated small ruminant markets below five percent coverage penetration. Blockchain-IoT ear-tag verification for high-value breeding stock represents the most penetrable segment, bypassing legacy field assessment infrastructure. Go-to-market execution should anchor in cooperative purchasing collectives adapted from Indian dairy society templates. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by reinsurance platforms seeking direct risk origination capabilities. Long-term viability favors carriers with demonstrated parametric product deployment and satellite-data integration. Target acquisition profile centers on digitized specialists with operational NDVI-trigger programs across Australian rangelands. Practitioners should monitor CEA-mandated disclosure standardization enforcement as consolidation trigger signal.| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Product Launch | NDVI-triggered policies collapse Queensland claims timelines from months to days. |
| Cooperative Network Expansion | Amul-linked procurement aggregation extracts volume discounts from underwriters in Gujarat. |
| Blockchain-IoT Integration | Ear-tag sensor verification enables real-time mortality confirmation for breeding stock. |
| Mobile Distribution Pilot | Eastern Indonesia pastoral communities access coverage through smartphone-enabled platforms. |
| Reinsurance Partnership Restructuring | Multi-source underwriting decouples from single-carrier models across Southeast Asia. |
Research Methodology
Regulatory filings, customs and trade databases, and veterinary epidemiology reports formed the secondary backbone of this analysis. Primary interviews with livestock insurance underwriters, dairy cooperative procurement managers, satellite-data analytics specialists, and BIS compliance officers combined with secondary validation. Bottom-up and top-down triangulation anchored market sizing across species, coverage type, and policy structure segments.
Bottom-up modeling aggregated individual country premium flows while top-down cross-checks validated against reinsurance market capacity disclosures. Segmentation dimensions spanned species selection, coverage trigger mechanism, buyer sophistication tier, and regional regulatory cluster across the projection horizon. CAGRs derived from actuarial loss ratio trends and subsidy framework expansion trajectories. Forecast inputs incorporated PMFBY enrollment data and Australian pastoral leasehold satellite monitoring adoption rates.
The model assumes a particular technology adoption path; alternative pathways for blockchain-IoT mortality verification would alter the outlook. Forecasts reflect assumptions around subsidy continuity and parametric trigger calibration accuracy. Practitioners should monitor drought frequency indices and veterinary epidemiologist capacity constraints for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Germany Reinsurance Market
Insurance
US Homeowner's Insurance Market
Insurance
Asia-Pacific AI in Insurance Market
Insurance
Global SME Insurance Market
Insurance
Jewelry Insurance Market
Insurance
Asia-Pacific Family Floater Health Insurance Market
Insurance
Fire Insurance Market
Insurance
Event Insurance Market
Insurance
Agricultural Insurance Market
Insurance
Switzerland Reinsurance Market
Insurance
Business Income Insurance Market
Insurance
Title Insurance Market
Insurance
Usage-Based Insurance for Automotive Market
Insurance
Cannabis Crop Insurance Market
Insurance
Global Boats and Yacht Insurance Market
Insurance
Credit Insurance Market