
 Commercial Cyber Insurance Market | 2026-2036
Commercial Cyber Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Cyber Insurance Market Insights
The United States is narrowing the protection gap between traditional property coverage and digital asset exposure as ransomware frequency escalates. Chubb Limited leverages its excess-and-surplus lines infrastructure to serve hard-to-place cyber risks in middle-market manufacturing. AIG anchors the high-segment corporate market with integrated crisis response services bundled into standalone policies. Beazley differentiates through its London market specialty focus, dominating media and technology professional liability adjacencies.
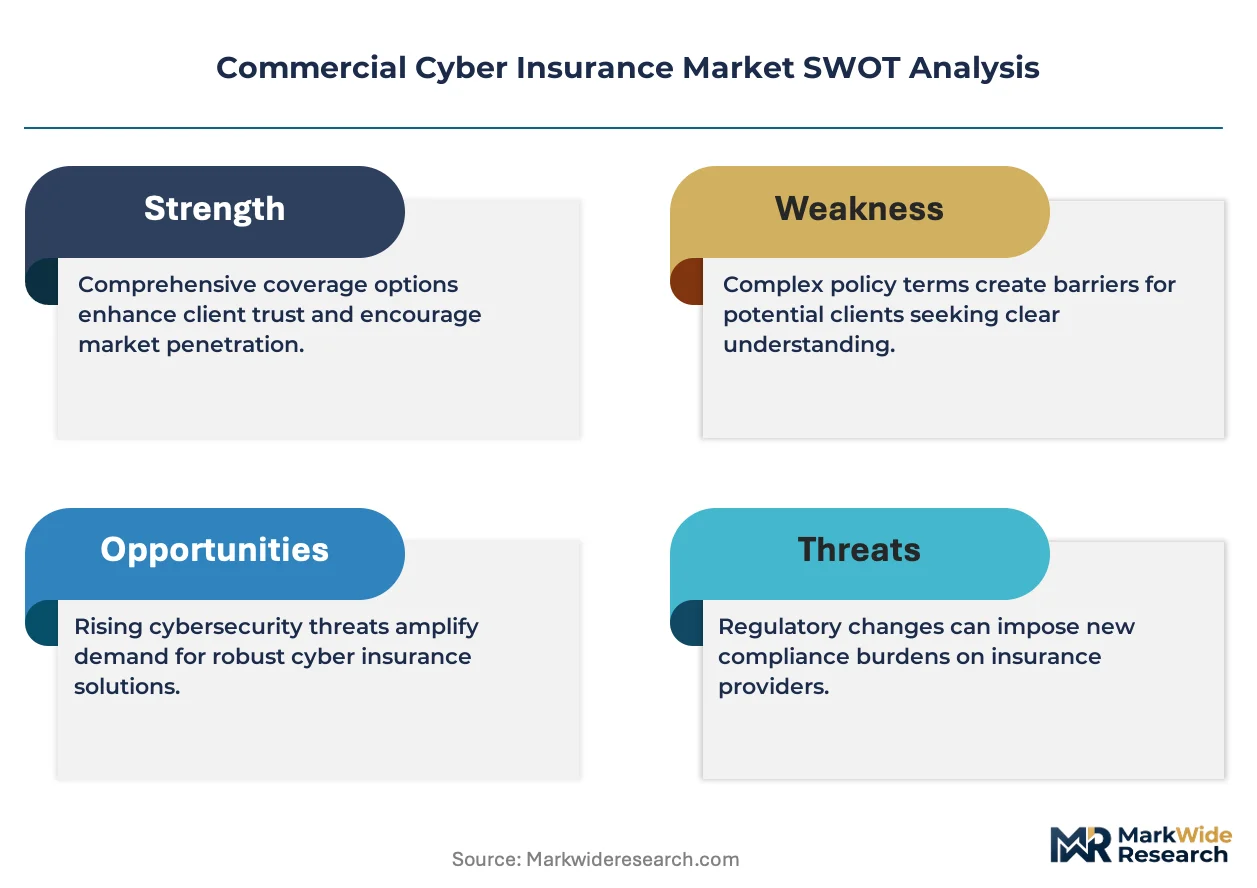
Commercial cyber insurance is a risk transfer mechanism indemnifying organizations against financial losses stemming from data breaches, network security failures, and operational technology disruptions; policies typically specify sublimits for social engineering fraud and waiting periods before business interruption indemnity triggers. The primary industrial purpose is restoring cash flow continuity after malicious cyber events disable revenue-generating systems. First-party coverage leads premium volume as organizations prioritize direct loss recovery over litigation defense, while third-party liability retains tighter underwriting margins due to unpredictable class-action exposure. Network security policies represent the fastest-growing policy type as remote work architectures expand attack surfaces beyond traditional perimeter defenses. Small enterprises show the steepest demand acceleration among organization sizes, though large corporations still command the deepest premium pools per account.
The SEC mandates four-day disclosure windows for material cyber incidents, compelling boards to procure coverage with forensic investigation riders rather than bare indemnity shells. Lloyd's of London mandates systematic risk aggregation controls across its syndicates, reshaping how underwriters price catastrophic cyber scenarios. The EU's Digital Operational Resilience Act extends similar compliance burdens to financial entities operating across member states. Stakeholders must monitor whether regulatory fragmentation between disclosure regimes produces coverage form standardization or jurisdictional policy fragmentation.
Market Dynamics
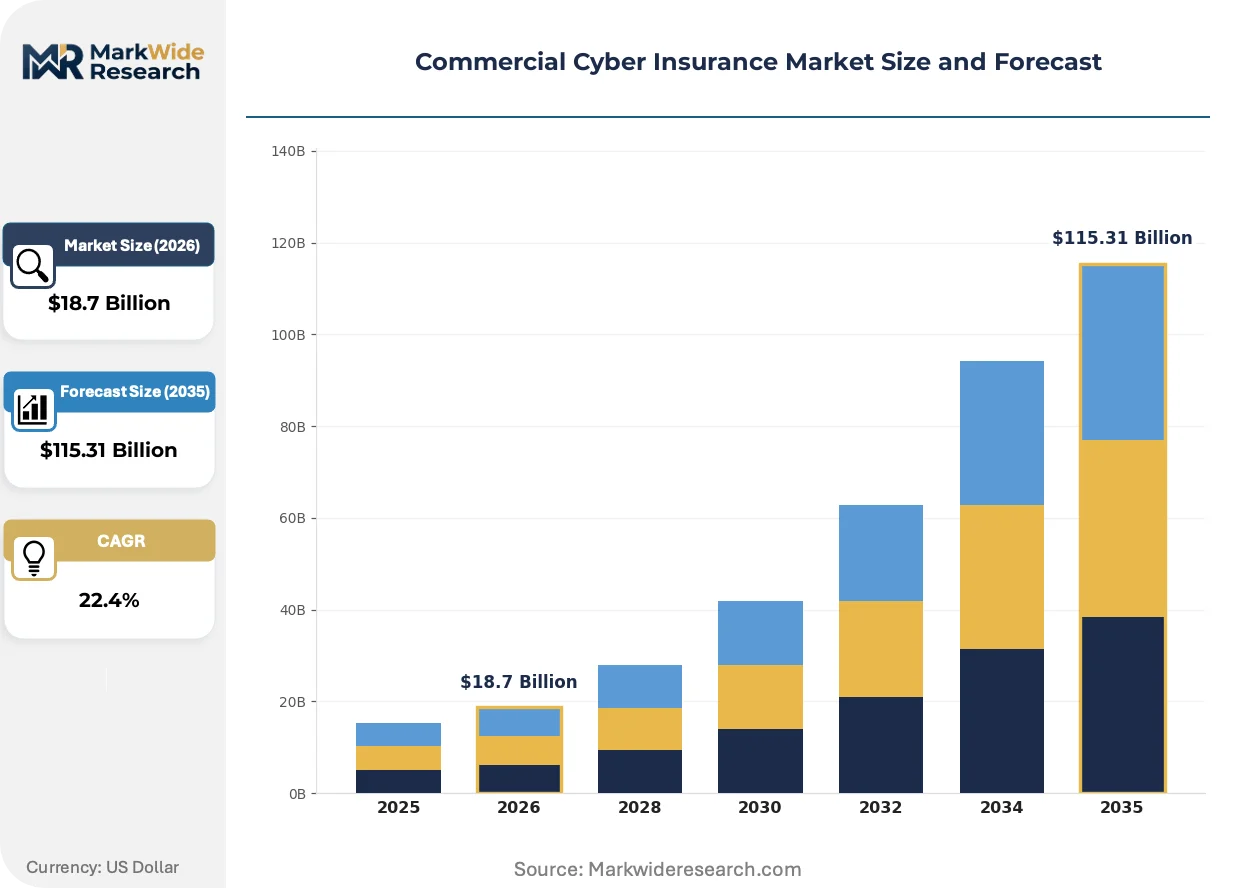
Ransomware frequency is compressing policy renewal cycles and forcing carriers to reprice catastrophic loss models faster than actuarial tables allow. The SEC's four-day disclosure mandate now sits at the center of underwriting conversations, reshaping what organizations buy and when they trigger coverage.
Growth Catalysts
- SEC Cyber Disclosure Rules:Material incident reporting windows compel boards to upgrade from bare indemnity shells to forensic investigation riders. This regulatory pressure expands policy attachment rates among publicly traded entities.
- Healthcare System Vulnerability:Hospital networks and clinical software vendors face intensifying ransomware campaigns against patient data repositories. Coverage purchases accelerate as operational technology exposures multiply.
- Remote Work Architecture:Distributed endpoints extend attack surfaces beyond traditional perimeter defenses. Network security policies capture this demand as organizations prioritize first-party loss recovery.
Market Restraints
- Actuarial Data Scarcity:Limited historical loss experience for systemic cyber events prevents accurate catastrophic scenario modeling. Lloyd's of London mandates systematic risk aggregation controls that constrain capacity deployment.
- Reinsurance Capacity Tightening:Retrocession markets in Bermuda and London have reduced cyber treaty participation. Primary carriers absorb more peak risk than capital models prefer.
- Social Engineering Sublimits:Fraudulent transfer coverage remains capped below actual loss severity. Policyholders retain significant uninsured exposure on wire transfer deception claims.
Strategic Opportunities
- Operational Technology Coverage:Manufacturing and energy infrastructure operators lack tailored policies for industrial control system breaches. Products bridging IT and OT risk represent unpenetrated white space.
- EU Digital Operational Resilience Act:Financial entities across member states face harmonized compliance burdens. Pan-European policy standardization creates distribution efficiency for carriers with London market infrastructure.
- Parametric Triggers:Index-based settlement mechanisms using external threat intelligence feeds reduce claims adjustment friction. Early adopters include cloud-dependent middle-market software vendors.
Industry Challenges
- Cyber Actuarial Talent Scarcity:Underwriters with combined technical security expertise and traditional pricing experience command premium compensation. Carriers compete for limited personnel capable of evaluating attack chain probabilities.
- Legacy System Integration:Policy administration platforms built for property-casualty lines require expensive retrofitting for dynamic cyber risk monitoring. Implementation timelines stretch 18-24 months for major carriers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Cyber Insurance Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: First-Party Coverage, Third-Party Liability, Data Breach, Network Security, Business Interruption, Cyber Extortion Organization Size: Small Enterprises, Mid-sized Companies, Large Corporations, Multinational Firms Industry Sector: Information Technology, Financial Services, Manufacturing, Telecommunications, Educational Institutions, Government Agencies Distribution Channel: Direct Sales, Brokers, Online Platforms, Bancassurance, Insurance Agents |
| Companies Covered | Chubb Limited, AIG, AXA XL, Travelers Group, Fairfax Financial, Beazley, Zurich Insurance, Liberty Mutual, AXIS Capital, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Cyber Insurance Market Trends and Innovations
Artificial intelligence is infiltrating underwriting workflows and claims triage, compressing decision cycles while raising questions about algorithmic bias in risk selection. Carriers experiment with continuous monitoring partnerships that replace point-in-time assessments.
Security posture telemetry is hybridizing traditional underwriting with real-time vulnerability scanning. Mid-market manufacturing buyers now submit continuous endpoint data in exchange for dynamic premium adjustments. This convergence collapses the distinction between risk transfer and risk mitigation services.
The EU's Digital Operational Resilience Act mandates incident reporting and resilience testing for financial entities across member states. National regulators in Germany, France, and the Netherlands must transpose these requirements into local enforcement frameworks. Banks and insurers operating cross-border are consolidating vendor panels to simplify compliance demonstration.
Enterprise buyers increasingly unbundle crisis response services from standalone policies and contract directly with forensic firms and legal counsel. This disintermediation pressures carrier margins on high-segment accounts in London and New York. Middle-market purchasers retain bundled offerings where vendor coordination costs exceed savings.
Commercial Cyber Insurance Market Segmentation
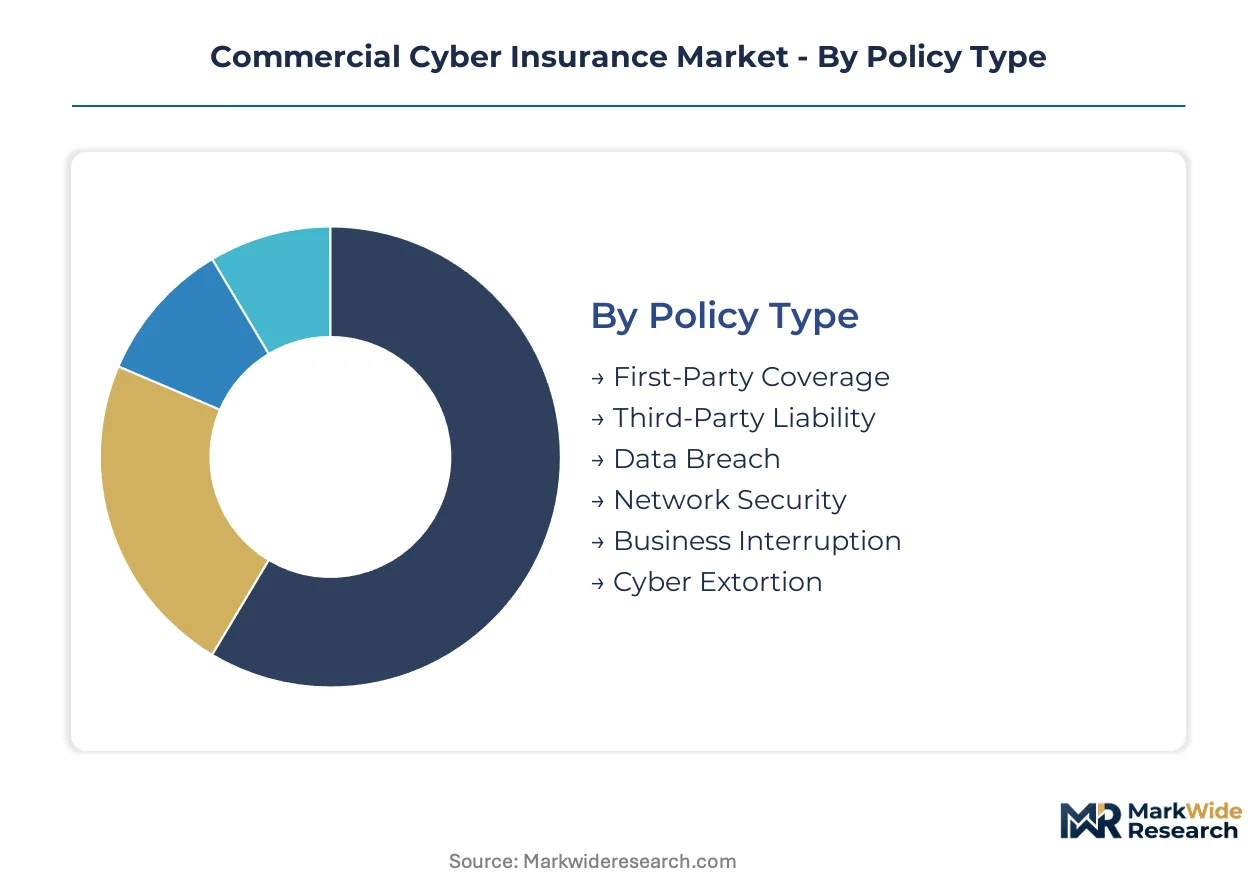
Commercial cyber insurance segmentation reflects divergent risk transfer priorities across organizational sophistication levels. Underwriters calibrate pricing models and coverage limits differently for each category, producing distinct margin profiles and renewal dynamics.
Policy Type:
Mature indemnity structures dominate premium volume, while emerging parametric and hybrid products reshape competitive positioning.
- First-Party Coverage:Direct loss recovery for data restoration, forensic investigation, and business interruption. Large financial institutions in London and New York prioritize this coverage as ransomware frequency escalates.
- Third-Party Liability:Litigation defense and settlement costs arising from privacy breaches or network security failures. Regulatory scrutiny from the SEC's four-day disclosure mandate tightens underwriting margins here.
- Data Breach:Notification costs, credit monitoring, and regulatory fines following unauthorized data access.
- Network Security:Fastest-expanding policy type as remote work architectures multiply endpoint vulnerabilities beyond traditional perimeter defenses.
- Business Interruption:Revenue replacement during system downtime with specified waiting periods before indemnity triggers.
- Cyber Extortion:Ransom payments and negotiation services, typically sublimited below actual loss severity on social engineering claims.
First-Party Coverage handles the majority of throughput; Network Security is climbing the fastest on share.
Organization Size:
Customer type determines attachment rates, with smallest entities showing steepest demand acceleration despite thinnest per-account economics.
- Small Enterprises:Accelerating purchases driven by ransomware awareness and vendor contract requirements. Healthcare clinics and professional services firms in the United States represent concentrated demand.
- Mid-sized Companies:Manufacturing and technology operators seeking tailored operational technology endorsements. Chubb Limited targets this segment through excess-and-surplus lines infrastructure.
- Large Corporations:Deepest premium pools per account with integrated crisis response services. AIG anchors this high-segment market with bundled forensic and legal counsel.
- Multinational Firms:Complex cross-border exposures requiring harmonized policy wording across Lloyd's of London syndicates and Bermuda capacity.
Large Corporations retain the deepest premium concentration; Small Enterprises are expanding most quickly on volume.
Industry Sector:
Application-specific risk profiles drive divergent coverage specifications and pricing tiers.
- Information Technology:Cloud service providers and software vendors with systemic aggregation exposure. Beazley dominates this segment through London market specialty focus on media and technology professional liability.
- Financial Services:Banks and insurers facing EU Digital Operational Resilience Act compliance burdens across member states. The SEC's disclosure rules compound regulatory pressure for US-domiciled entities.
- Manufacturing:Industrial control system breaches create unpenetrated white space for IT-OT bridging products.
- Telecommunications:Critical infrastructure designation elevates regulatory scrutiny and mandatory coverage thresholds.
- Educational Institutions:Budget-constrained buyers with legacy system vulnerabilities and dispersed endpoint populations.
- Government Agencies:Federally mandated coverage requirements with specialized procurement vehicles and sovereign immunity complications.
Financial Services commands the densest regulatory overlay; Manufacturing is gaining share fastest on emerging risk recognition.
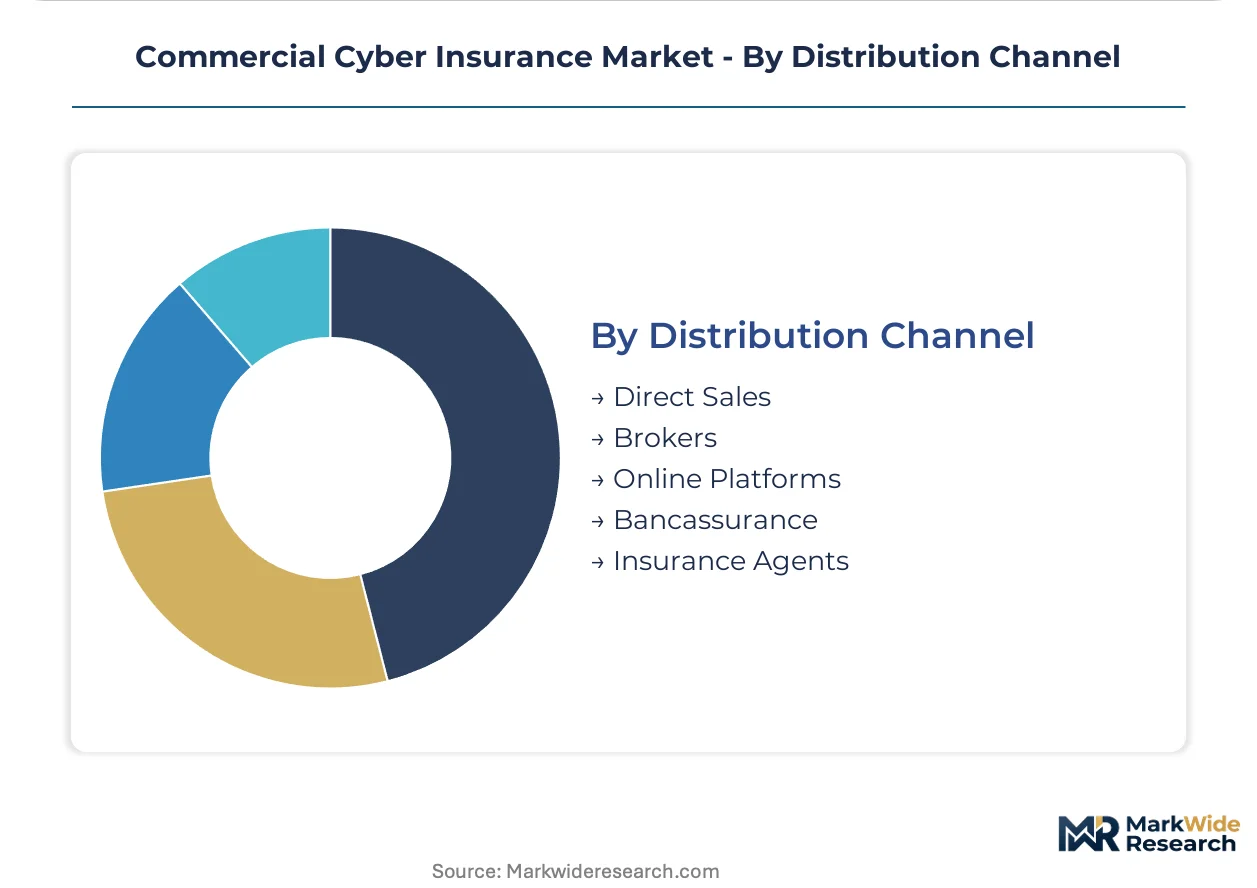
Distribution Channel:
Cost tier differentiation shapes how carriers deploy capital and control acquisition expenses.
- Direct Sales:Carrier-controlled relationships with largest accounts enabling customized policy construction and dynamic premium adjustments.
- Brokers:Dominant placement mechanism for middle-market and complex risks across London and New York trading floors.
- Online Platforms:Automated quoting for standardized small commercial risks with compressed decision cycles.
- Bancassurance:Bank-distributed products leveraging existing commercial lending relationships for attachment.
- Insurance Agents:Local market presence serving regional enterprises with bundled property-casualty cross-sell opportunities.
Brokers intermediate the majority of premium flow; Online Platforms are expanding most quickly on small enterprise penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Underwriting capacity concentrates in London and New York, where Lloyd's syndicates and Bermuda reinsurers price catastrophic cyber scenarios. Carrier capital deployment favors jurisdictions with established specialty insurance infrastructure and regulatory clarity on digital asset exposure.
United States
Publicly traded entities drive policy attachment rates as the SEC mandates four-day disclosure windows for material cyber incidents. Healthcare systems and financial institutions in Manhattan and Chicago expand first-party coverage purchases. Forensic investigation riders now displace bare indemnity shells in board procurement conversations.
United Kingdom
Lloyd's of London mandates systematic risk aggregation controls across its syndicates, constraining capacity deployment for systemic cyber events. Beazley and specialty underwriters dominate media and technology professional liability adjacencies from the City. The Prudential Regulation Authority scrutinizes insurer solvency against catastrophic loss models.
Germany
Industrial manufacturing clusters in Bavaria and North Rhine-Westphalia seek operational technology endorsements bridging IT and OT risk. The Federal Financial Supervisory Authority (BaFin) implements EU Digital Operational Resilience Act requirements for banks and insurers. Frankfurt-based financial entities consolidate vendor panels for cross-border compliance demonstration.
France
The French Prudential Supervision and Resolution Authority (ACPR) transposes EU resilience mandates for financial entities operating from Paris and Île-de-France. Cyber extortion coverage accelerates among mid-market professional services firms. The CNIL enforces data breach notification standards that tighten third-party liability underwriting.
Switzerland
Zurich and Geneva host reinsurance capital that absorbs peak cyber risk from primary carriers. Swiss financial institutions face harmonized EU equivalence requirements on operational resilience. The Swiss Financial Market Supervisory Authority (FINMA) mandates incident reporting timelines that mirror SEC disclosure pressure.
Commercial Cyber Insurance Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with targeted risk selection. The market structures around three capacity layers: global multiline carriers with balance sheet depth, London market syndicates with specialty focus, and regional mutuals with captive-like attachment. Strategic moves concentrate on parametric trigger development and continuous monitoring partnerships that collapse the distinction between risk transfer and mitigation.
Among London market specialists, Beazley occupies a position exemplifying media and technology professional liability integration. Chubb Limited represents the excess-and-surplus lines archetype serving hard-to-place middle-market manufacturing risks. AIG anchors the high-segment corporate tier where bundled crisis response services differentiate standalone policies.
| Leading Market Players |
|---|
| Chubb Limited |
| AIG |
| AXA XL |
| Travelers Group |
| Fairfax Financial |
| Beazley |
| Zurich Insurance |
| Liberty Mutual |
| AXIS Capital |
| Others |
Pricing and Supply Chain Analysis
Bermuda reinsurance capital concentration feeds directly into where primary carriers extract margin from cyber coverage. London and New York trading floors intermediate capacity allocation, while retrocession availability determines how far downmarket carriers can price competitively.
Pricing Analysis
The SEC's four-day disclosure mandate dictates the pricing tier structure across the commercial cyber insurance landscape. Premium-mid-economy pricing differentiation separates large financial institutions with integrated crisis response bundles from middle-market manufacturing buyers accepting dynamic adjustments via continuous monitoring partnerships. Cost compression in the small enterprise tier is intensifying because automated underwriting platforms reduce acquisition expenses. Healthcare clinics show the highest price sensitivity; multinational firms with cross-border exposures demonstrate the least.
Supply Chain Analysis
Actuarial modeling talent and threat intelligence feeds constitute the upstream feedstock that carriers draw from to construct coverage. Bermuda, London, and Zurich concentrate reinsurance capacity that absorbs peak cyber risk from primary underwriters. Lloyd's syndicates, Bermuda retrocession markets, and Zurich-based reinsurers hinge on cybersecurity vendor partnerships and forensic investigation networks. Single-source vulnerability in threat intelligence providers creates systemic exposure. Distribution runs through broker intermediaries on London and New York trading floors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial cyber insurance sits in early-cycle expansion as ransomware frequency accelerates first-party coverage attachment among healthcare and financial institutions previously reliant on bare indemnity shells.
For Market Incumbents: Entrench through backward integration into continuous monitoring partnerships that collapse risk transfer and mitigation service boundaries. Add forensic investigation capacity in London and New York to defend against disintermediation by standalone crisis response vendors. Chubb Limited's excess-and-surplus lines infrastructure demonstrates how middle-market manufacturing risks can be captured before competitors deploy capital.
For New Entrants and Emerging Players: German industrial manufacturing clusters in Bavaria and North Rhine-Westphalia offer the most penetrable white space for operational technology endorsements bridging IT and OT risk. Target mid-sized energy infrastructure operators lacking tailored policies for industrial control system breaches. Lead with parametric trigger products using external threat intelligence feeds to reduce claims adjustment friction against incumbent indemnity structures.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed cybersecurity vendors possessing threat intelligence platforms suitable for underwriting integration. Long-term viability centers on carriers that successfully hybridize risk transfer with continuous monitoring services rather than pure indemnity shells. Watch for inflection when Lloyd's of London relaxes risk aggregation controls, signaling capacity expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Trigger Development | Index-based settlement mechanisms reduce claims friction for cloud-dependent software vendors. |
| Continuous Monitoring Partnership | Real-time vulnerability scanning collapses distinctions between risk transfer and mitigation services. |
| Operational Technology Coverage Launch | IT-OT bridging products capture unpenetrated manufacturing and energy infrastructure demand. |
| Forensic Investigation Capacity Buildout | Integrated crisis response services defend against enterprise buyer disintermediation trends. |
| EU Digital Operational Resilience Act Compliance Product | Pan-European policy standardization leverages London market infrastructure for distribution efficiency. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, carrier statutory statements, and threat intelligence industry reports. Underwriting executives at Lloyd's syndicates and Bermuda reinsurers, brokerage placement specialists in London and New York, and chief information security officers at healthcare and financial institutions provided qualitative inputs. Secondary validation drew from SEC disclosure filings, Lloyd's market returns, EU regulatory transposition documents, and cyber incident databases. Bottom-up policy count estimates and top-down premium volume assessments were triangulated against carrier-reported segment disclosures.
Forecast inputs span policy type segmentation, organization size tiers, industry vertical exposure profiles, and geographic regulatory clusters across the analysis window. Modeled dimensions include first-party versus third-party coverage splits, small enterprise versus large corporation attachment rates, and financial services versus manufacturing sector penetration. CAGRs were derived from regression against historical premium growth and forward projection of regulatory mandate implementation timelines. Ransomware frequency trajectories and retrocession market capacity availability served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by insurtech entrants with AI-native underwriting platforms would shift outcomes. Regulatory fragmentation between SEC disclosure rules and EU Digital Operational Resilience Act implementation timelines could accelerate or compress premium growth. Cross-checking against Lloyd's of London syndicate capacity deployment announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Business Insurance Market
Insurance
Japan Parametric Insurance Market
Insurance
Saudi Arabia Travel Insurance Market
Insurance
United States Dental Insurance Market
Insurance
New Zealand Property and Casualty Insurance Market
Insurance
South Africa Property and Casualty Insurance Market
Insurance
Self Funded Insurance Market
Insurance
Global Livestock Insurance Market
Insurance
Russia Property and Casualty Insurance Market
Insurance
Middle East Business Income Insurance Market
Insurance
Cloud Computing in Insurance Market
Insurance
Business Travel Accident Insurance Market
Insurance
Global Fine Art Insurance Market
Insurance
Germany Electronic Gadgets Insurance Market
Insurance
China Parametric Insurance Market
Insurance
Event Insurance Market