
 Endowment Insurances Market | 2026-2036
Endowment Insurances Market Size, Share, and Industry Trends Forecast 2026-2036
Endowment Insurances Market Insights
Solvency II is rebalancing the capital reserve requirements for European endowment products, forcing carriers to hold higher risk-adjusted reserves against long-duration liabilities. Prudential Financial Inc. leverages its mutual structure to sustain pricing advantages in participating whole life segments. China Life Insurance Co. Ltd. anchors its distribution through state-affiliated banking channels, dominating premium flow in tier-two and tier-three cities.
Endowment insurance combines life coverage with a savings mechanism that matures at a fixed date or upon death, with cash values accumulating through guaranteed interest, declared dividends, or linked investment returns. The product serves primarily as a tax-advantaged wealth accumulation vehicle for households and a fiduciary liability management tool for corporate pension sponsors. Traditional and participating policy types retain the largest premium share due to their guaranteed return floors and conservative risk profiles, while unit-linked structures are gaining fastest in markets with liberalized investment rules and equity-literate customer bases. Premium payment through regular installments generates the most persistent liability streams, though single-premium products command wider margins per dollar collected.
The EU's Solvency II regime, China's NMPA and CBIRC oversight of insurer asset-liability matching, and the US state-level NAIC reserving standards collectively shape product design, capital intensity, and cross-border market access. Regulatory divergence between risk-based capital frameworks and prescriptive guaranteed-return ceilings directly determines which policy structures carriers can profitably offer in each jurisdiction. Stakeholders must monitor pending revisions to the EU's Insurance Distribution Directive and China's evolving dual-carbon-linked investment eligibility rules for insurer portfolios.
Market Dynamics
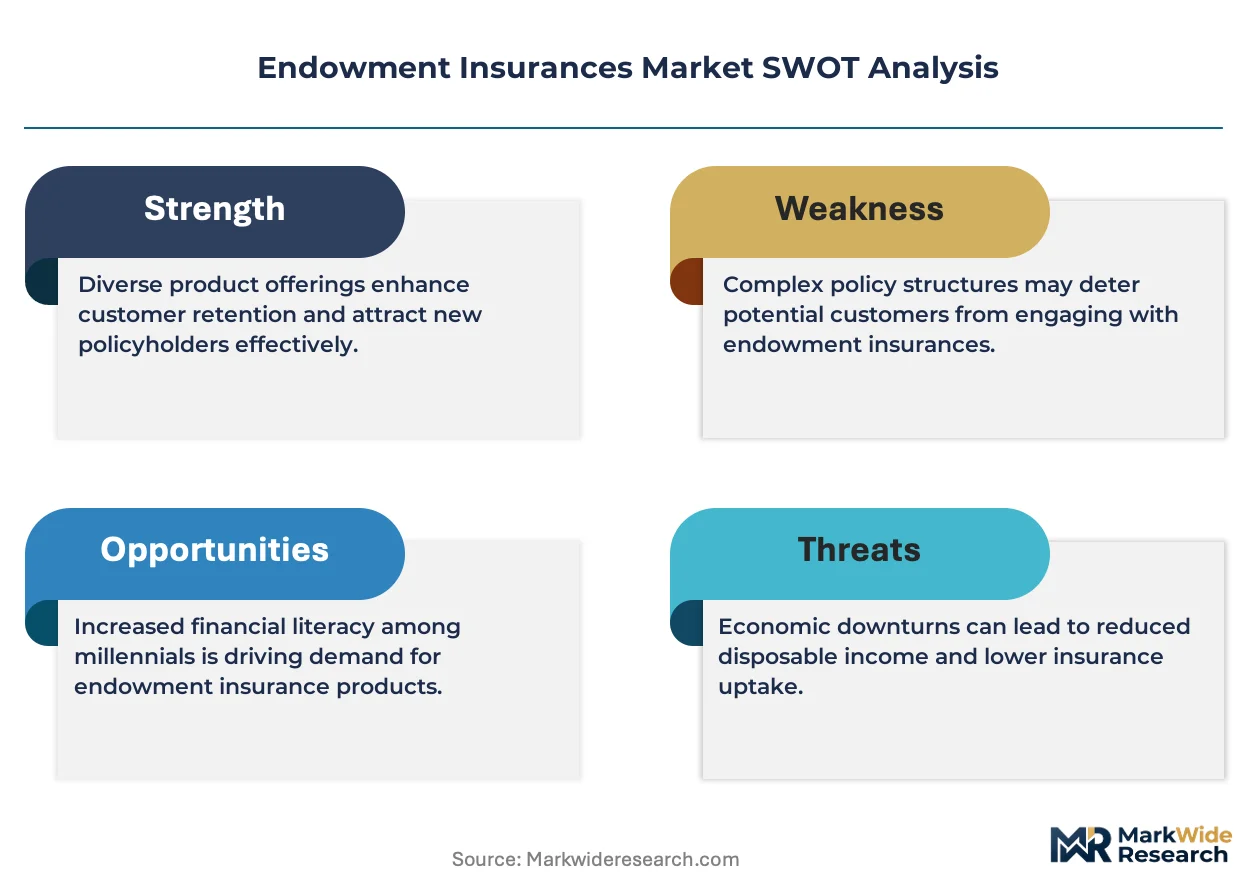
Solvency II capital requirements are forcing European carriers to restructure reserve methodologies for long-duration endowment liabilities, compressing guaranteed-return product margins while accelerating unit-linked adoption.
Growth Catalysts
- Corporate employee benefit mandates:Large employers in Germany and Japan are expanding fiduciary coverage for defined-benefit pension shortfalls through group endowment structures.
- REACH-aligned ESG investment frameworks:EU insurers are redirecting unit-linked portfolios toward green bonds and transition infrastructure, attracting climate-conscious retail savers.
- China's CBIRC liberalization of equity-linked caps:Domestic insurers now allocate higher proportions of policyholder funds to A-share markets, boosting projected returns for middle-income buyers.
Market Restraints
- Sovereign bond yield compression:German Bund and Japanese JGB rates near zero floor eliminate risk-free backing for traditional guaranteed-return products.
- Actuarial talent scarcity:Retirement of experienced pricing actuaries in the UK and Netherlands lengthens product development cycles for complex participating policies.
- NAIC reserving standard divergence:US state-by-state variation in captive reinsurance recognition fragments capital efficiency for cross-border carriers.
Strategic Opportunities
- India's BIS-aligned pension portability rules:Regulatory harmonization between EPFO and private insurers creates white space for portable endowment-linked retirement accounts.
- Embedded distribution through neobank platforms:Partnerships with digital-first banks in Brazil and Mexico bypass legacy agent networks for millennial customer acquisition.
- Convergence of AI-driven underwriting with biometric data:Real-time mortality scoring via wearable integrations enables dynamic premium adjustment for health-linked endowment variants.
Industry Challenges
- Legacy policy administration system migration:Core platform modernization for in-force books diverts IT resources from new product development.
- Dual-carbon disclosure compliance timelines:China's MEE and EU CSRD overlapping reporting requirements strain ESG data infrastructure for multinational carriers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endowment Insurances Market |
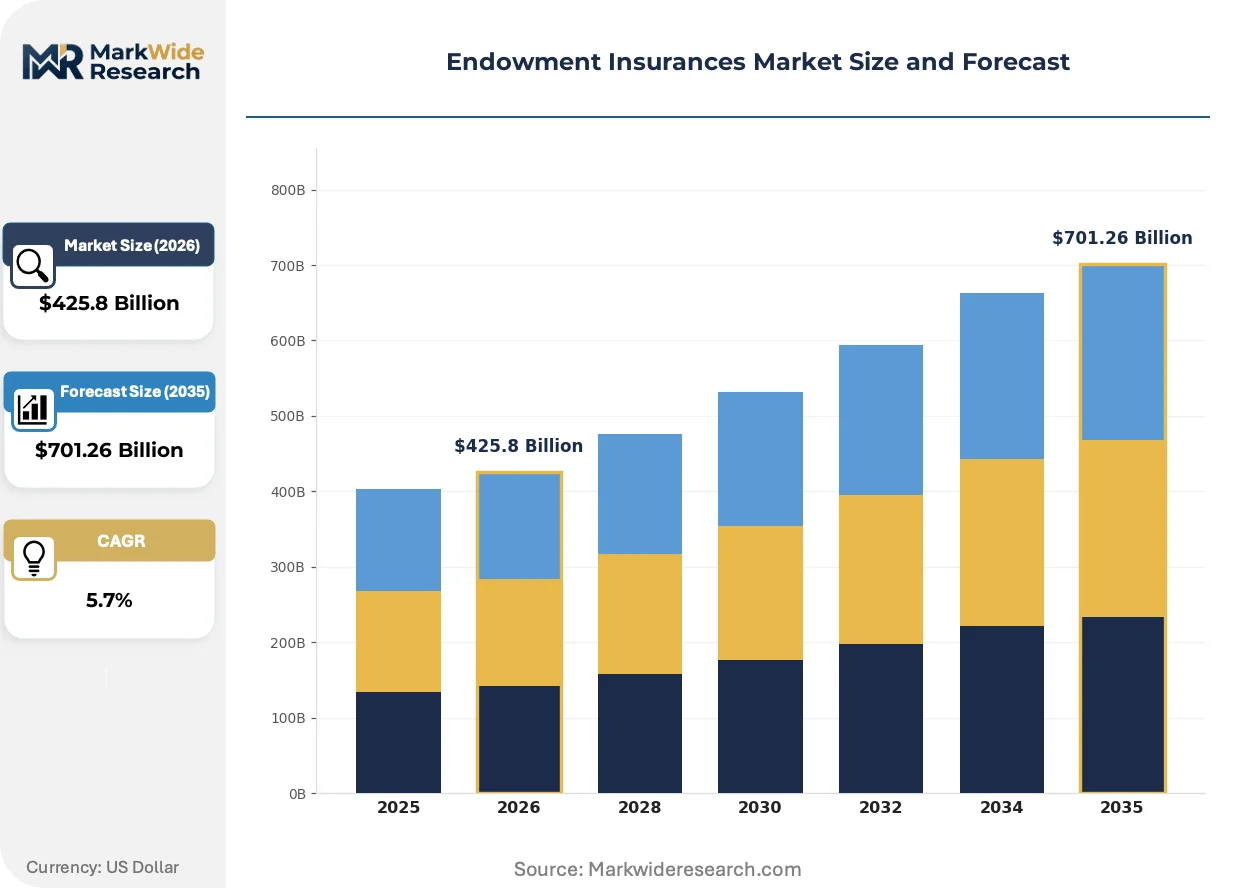
| Market Size in 2026 | $425.8 Billion |
| Market Size in 2035 | $701.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Traditional, Unit-Linked, Participating, Non-Participating Target Customer: Individuals, Corporates, Institutions, Families Premium Payment Mode: Lump Sum, Regular Installments, Single Premium, Limited Premium Coverage Duration: Short-Term, Medium-Term, Long-Term, Flexible |
| Companies Covered | Prudential Financial Inc., MetLife Inc., China Life Insurance Co. Ltd., Ping An Insurance (Group) Co. of China Ltd., Allianz SE, Manulife Financial, New York Life, Massachusetts Mutual, American International Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endowment Insurances Market Trends and Innovations
Digital distribution infrastructure and algorithmic asset allocation are compressing the traditional agent-intermediated sales model while expanding addressable customer segments previously excluded by minimum premium thresholds.
Blockchain-enabled smart contract architecture is absorbing policy issuance, premium collection, and claims settlement into automated, self-executing protocols. InsurTech platforms in Singapore and Switzerland are piloting these systems for single-premium endowment products. The technology is absorbing back-office functions previously requiring manual reconciliation, reducing operational expense ratios by eliminating intermediary verification steps.
The EU's Insurance Distribution Directive revision is tightening suitability assessment requirements for complex unit-linked products. Carriers must now document explicit customer understanding of investment risk before contract execution. German and French regulators are prioritizing enforcement against misselling in bank-assurance channels, prompting product simplification and standardized disclosure templates.
Subscription-style micro-premium accumulation is displacing traditional annual payment schedules among younger policyholders in South Korea and Australia. Mobile-first insurers offer weekly automated deductions linked to spending round-ups or gig-economy income streams. This behavioral shift is most visible in metropolitan markets where traditional agent relationships have weakened and digital financial management tools dominate daily money management.
Endowment Insurances Market Segmentation
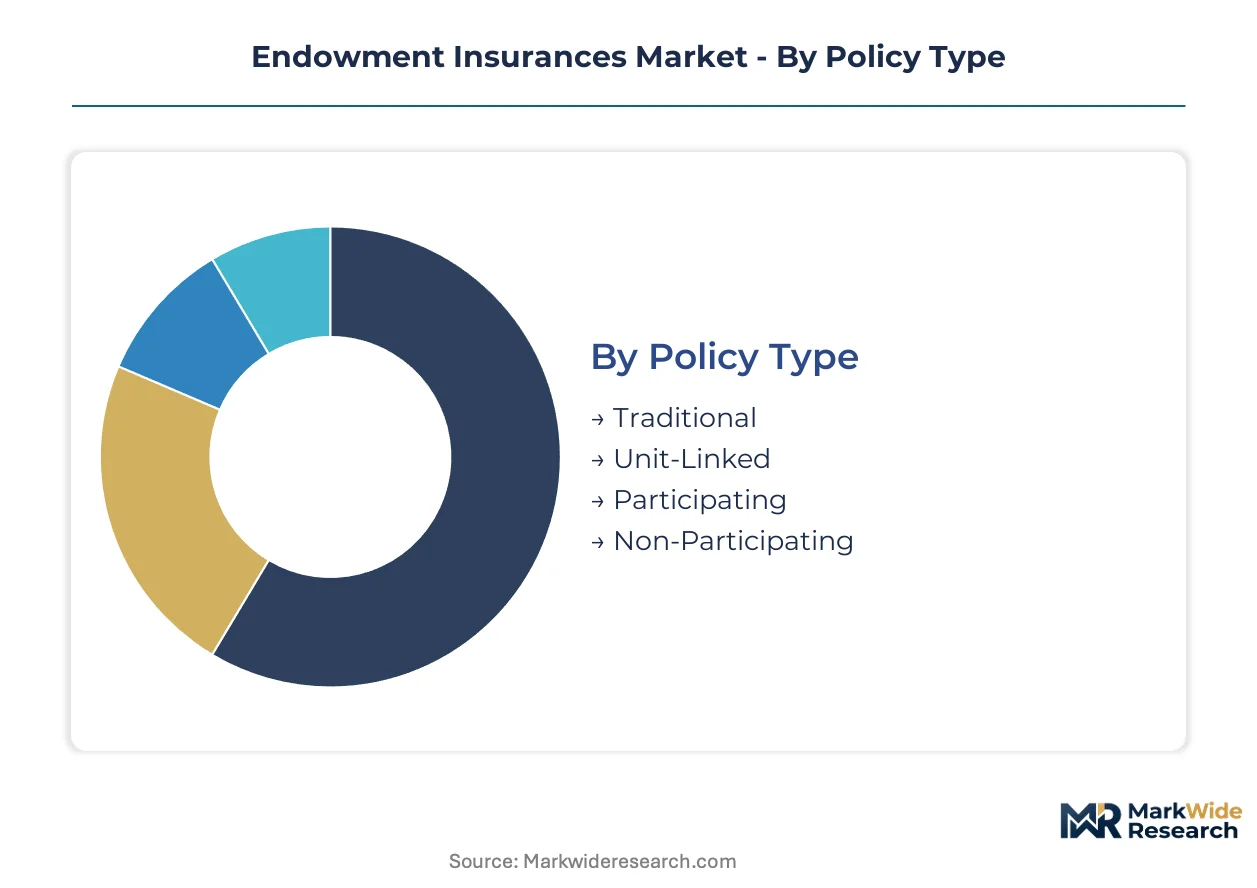
Endowment insurance carriers segment their product architecture across four structural axes to match liability duration, capital efficiency, and customer acquisition economics. Each segmentation layer determines reserve methodology, distribution channel selection, and regulatory capital treatment.
Policy Type:
Product mechanics distinguish guaranteed-return structures from investment-linked variants, with capital requirements and customer risk appetite driving portfolio composition.
- Traditional:Fixed interest rates and guaranteed maturity values define the contract structure. German and Japanese carriers deploy these products for corporate pension fiduciary coverage where liability matching takes precedence over yield optimization.
- Unit-Linked:Policyholder funds track segregated investment portfolios with equity, bond, or mixed-asset exposure. China's CBIRC liberalization of A-share allocation caps is accelerating demand among equity-literate middle-income households in tier-two cities.
- Participating:Contracts blend guaranteed floors with discretionary dividends tied to insurer surplus and investment performance. Prudential Financial leverages mutual ownership structures to sustain pricing advantages through direct profit participation.
- Non-Participating:Pure guaranteed-return products with no dividend variability. These structures dominate in markets with prescriptive guaranteed-return ceilings where carriers cannot offer surplus sharing.
Traditional products lead on scale; unit-linked products lead on momentum.
Target Customer:
Customer archetype determines policy design complexity, premium scale, and servicing infrastructure requirements.
- Individuals:Retail policyholders purchasing tax-advantaged wealth accumulation vehicles. South Korean and Australian mobile-first insurers are capturing this segment through subscription-style micro-premium deductions linked to spending round-ups.
- Corporates:Employers structuring group endowment coverage for defined-benefit pension shortfalls. German large employers are expanding fiduciary mandates through this channel.
- Institutions:Pension funds and asset managers seeking liability-driven investment wrappers. These buyers prioritize Solvency II capital efficiency and ALM matching precision.
- Families:Multi-generational wealth transfer vehicles with estate planning features. Demand concentrates among high-net-worth segments in Singapore and Switzerland where trust structures integrate with insurance wrappers.
Individual policies dominate premium volume; corporate mandates are climbing the fastest.
Premium Payment Mode:
Payment structure shapes liability persistency, margin per dollar collected, and customer lifetime value calculations.
- Lump Sum:Single capital deployment at contract inception. Brazilian and Mexican neobank partnerships are streamlining acquisition for this high-margin variant.
- Regular Installments:Periodic premium flows generating persistent liability streams. This mode anchors carrier cash flow predictability across European and Asian markets.
- Single Premium:One-time payment with immediate cash value accumulation. Blockchain-enabled smart contract pilots in Singapore target this structure for operational expense reduction.
- Limited Premium:Payment obligations concentrated in early policy years with extended coverage duration. These products appeal to pre-retirees seeking to complete funding obligations before income cessation.
Regular installments lead on scale; single premium products lead on margin per dollar.
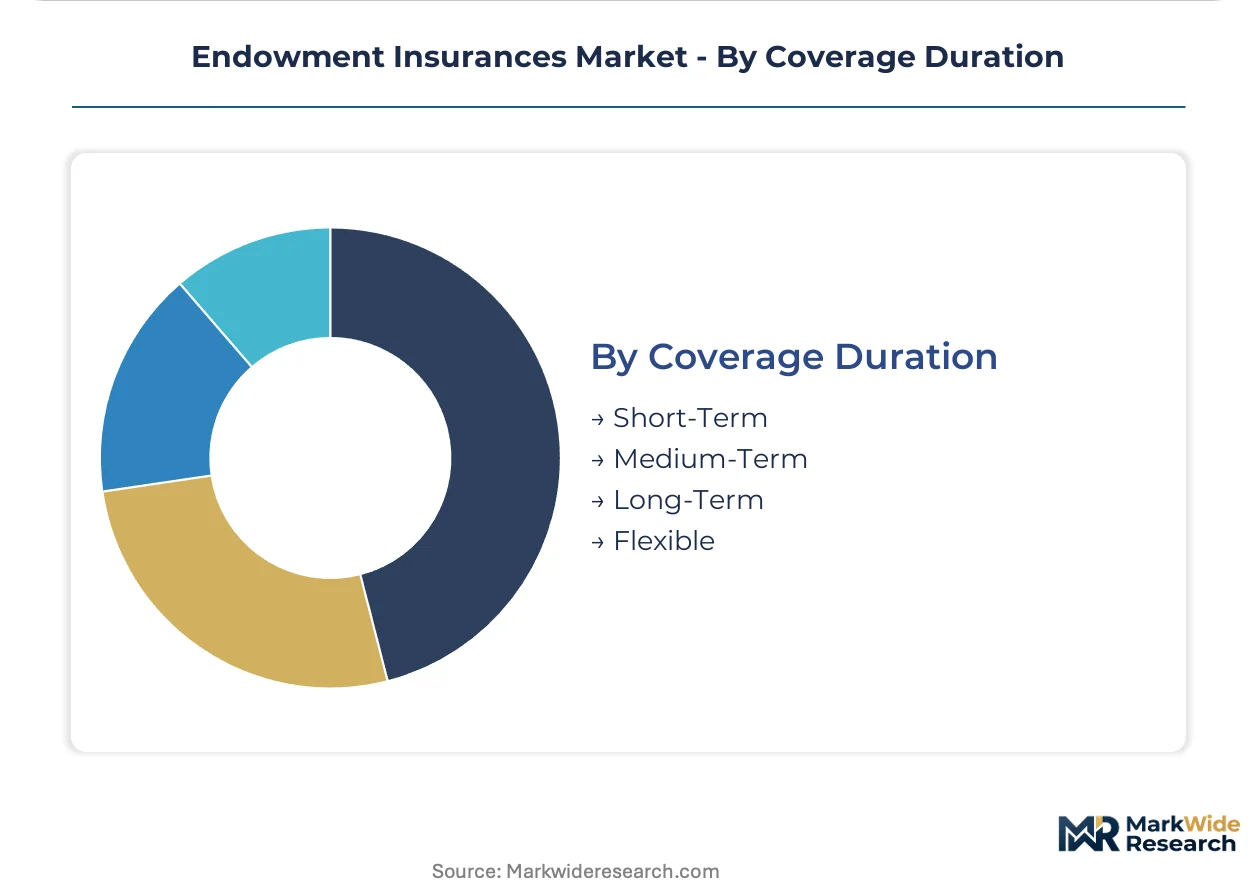
Coverage Duration:
Maturity horizon determines reserve methodology, asset-liability matching strategy, and Solvency II risk margin calculations.
- Short-Term:Maturities under five years with limited cash value accumulation. These products face yield compression pressure from near-zero German Bund and Japanese JGB rates.
- Medium-Term:Five-to-fifteen year horizons balancing liquidity access with accumulation potential. China's domestic insurers are scaling unit-linked offerings in this band for middle-income buyers.
- Long-Term:Extended durations beyond fifteen years maximizing compound growth and tax deferral. Solvency II capital requirements are forcing European carriers to restructure reserve methodologies for these liabilities.
- Flexible:Adjustable maturity dates responsive to policyholder life events. Wearable-integrated biometric underwriting pilots enable dynamic premium adjustment for these variants.
Long-term coverage leads on premium scale; flexible duration products are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Actuarial talent clusters in London, Frankfurt, and Singapore anchor product development capacity for complex participating policies. Solvency II specialists concentrate in European financial centers, while China's state-affiliated banking channels dominate distribution infrastructure in tier-two and tier-three cities.
United States
Corporate pension sponsors drive group endowment adoption for defined-benefit shortfall coverage. NAIC state-level reserving standards fragment capital efficiency, with captive reinsurance recognition varying by jurisdiction. New York and Boston house legacy mutual insurers leveraging participating structures for pricing advantages.
Germany
Large employers expand fiduciary mandates through group endowment structures for pension liability management. Solvency II capital requirements compress guaranteed-return product margins while accelerating unit-linked adoption. Frankfurt's banking-insurance nexus concentrates product innovation and regulatory compliance expertise.
China
Middle-income households in tier-two cities scale unit-linked uptake following CBIRC liberalization of A-share allocation caps. NMPA and CBIRC oversight enforces strict asset-liability matching rules on domestic carriers. Shanghai and Shenzhen anchor distribution through state-affiliated banking channels capturing premium flow.
Japan
Corporate employee benefit mandates expand coverage for defined-benefit pension shortfalls through group structures. METI guidelines and FSA oversight maintain conservative reserve requirements for guaranteed-return products. Tokyo's insurance corridor concentrates actuarial talent for long-duration liability pricing.
Singapore
High-net-worth families utilize multi-generational wealth transfer vehicles with integrated trust structures. MAS regulatory framework permits flexible unit-linked portfolio construction for accredited investors. The city-state's private banking cluster attracts blockchain-enabled smart contract pilots for single-premium operational efficiency.
Endowment Insurances Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across product architecture and distribution reach. The market exhibits tiered concentration, with mutual structures and state-affiliated carriers commanding distinct capital advantages. Three archetypes dominate: mutual insurers leveraging profit participation, state-backed carriers with banking channel control, and global diversified groups with cross-border ALM capabilities. Competitive moves center on digital distribution partnerships and legacy platform modernization for in-force administration.
Within the mutual structure tier, Prudential Financial Inc. and Massachusetts Mutual occupy positions emphasizing policyholder surplus sharing. China Life Insurance Co. Ltd. anchors the state-affiliated archetype with distribution through government-linked banking networks. Allianz SE represents the diversified global group model, spanning multiple regulatory jurisdictions with integrated asset-liability management capabilities.
| Leading Market Players |
|---|
| Prudential Financial Inc. |
| MetLife Inc. |
| China Life Insurance Co. Ltd. |
| Ping An Insurance (Group) Co. of China Ltd. |
| Allianz SE |
| Manulife Financial |
| New York Life |
| Massachusetts Mutual |
| American International Group |
| Others |
Pricing and Supply Chain Analysis
Actuarial talent costs in London, Frankfurt, and Singapore flow through to policy pricing tiers, with guaranteed-return products carrying heavier reserve methodology expenses than unit-linked alternatives. Sovereign bond yield compression in Germany and Japan eliminates risk-free backing floors, forcing carriers to reprice traditional endowments upward or absorb margin erosion.
Pricing Analysis
The bundled-vs-unbundled service split separates advisory-intermediated sales from direct digital distribution, with embedded neobank partnerships commanding lower acquisition costs than legacy agent networks. Three-tier pricing structure across premium, standard, and economy levels reflects Solvency II capital intensity, distribution channel depth, and policy complexity. Pricing pressure stems from near-zero German Bund and Japanese JGB rates eliminating guaranteed-return product viability. Corporate pension sponsors show lowest price sensitivity due to fiduciary liability matching requirements; retail micro-premium buyers exhibit highest elasticity.
Supply Chain Analysis
Workforce availability constraints in UK and Netherlands actuarial clusters lengthen product development cycles for complex participating policies. Supply concentrates in Germany, Japan, and China for long-duration liability pricing expertise and state-affiliated distribution infrastructure. Raw material dependencies include sovereign debt instruments for guaranteed-return backing, equity market access for unit-linked portfolios, and biometric data streams for wearable-integrated underwriting. Single-source vulnerability runs through state-affiliated banking channels in China's tier-two cities. Distribution runs through captive agent networks, bancassurance partnerships, and emerging neobank platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Demand is concentrating in unit-linked products with ESG-aligned investment frameworks as retail buyers prioritize transparency over guaranteed floors.
For Market Incumbents: Anchor capital efficiency through legacy platform modernization that diverts IT resources from in-force administration to new product development. Defend against InsurTech entrants by securing exclusive neobank distribution partnerships in Brazil and Mexico before channel saturation. Prioritize Solvency II compliance automation as the lever for preserving guaranteed-return product margins. For New Entrants and Emerging Players: Mobile-first millennials in South Korea and Australia represent the most penetrable buyer archetype given weakened traditional agent relationships and dominance of digital financial management tools. White space exists in subscription-style micro-premium accumulation with weekly automated deductions linked to gig-economy income streams. Go-to-market angle: wearable-integrated biometric underwriting for dynamic premium adjustment variants. For Investors and Strategic Acquirers: Consolidation pressure builds where legacy policy administration system migration costs exceed standalone carrier IT budgets. Long-term viability favors carriers with mutual ownership structures enabling direct profit participation or state-affiliated banking channel control. Target acquisition archetype: mid-tier insurers with in-force books but outdated core platforms. Signal to watch: CBIRC liberalization of equity-linked caps spreading beyond A-shares to broader alternative asset classes.| Strategic Initiative | Industry Significance |
|---|---|
| Legacy Platform Modernization | Core system upgrades free IT resources from in-force administration toward new product development pipelines. |
| Neobank Distribution Partnership | Embedded acquisition through Brazil and Mexico digital-first banks bypasses legacy agent network cost structures. |
| Blockchain Smart Contract Pilot | Automated policy issuance and claims settlement reduces operational expense ratios for single-premium products. |
| ESG Investment Framework Alignment | REACH-compliant green bond portfolios attract climate-conscious retail savers in EU unit-linked segments. |
| Wearable Biometric Integration | Real-time mortality scoring enables dynamic premium adjustment for flexible duration health-linked variants. |
Research Methodology
Multiple input streams — actuarial pricing executives, regulatory compliance officers, bancassurance channel heads, and InsurTech platform engineers — were reconciled against secondary validation from NAIC reserving standard filings, Solvency II regulatory disclosures, CBIRC policy circulars, and insurer statutory financial statements. Bottom-up policy-level data aggregation and top-down market sizing triangulation were cross-referenced to establish segment boundaries.
Historical premium flow patterns were cross-referenced against panel input from distribution strategists to model trajectory across the analysis window. Segmentation dimensions included policy type mechanics, target customer archetype, premium payment mode structure, and coverage duration horizon. CAGRs were derived from fitted growth curves calibrated to regulatory regime change timelines and sovereign yield environment assumptions.
Inputs from European Insurance and Occupational Pensions Authority consultations were available through the study window; gaps in real-time biometric mortality data introduce uncertainty bands around wearable-integrated product forecasts. Forecasts reflect documented assumptions regarding CBIRC liberalization pace and Solvency II reserve methodology revision timelines. Material deviation in German Bund yield floors or China's dual-carbon investment eligibility rules warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
B2B2C Insurance Market
Insurance
Saudi Arabia Health Insurance Market
Insurance
Canada Cyber (Liability) Insurance Market
Insurance
Asia-Pacific Travel Insurance Market
Insurance
Gap Insurance Market
Insurance
Agricultural Insurance Market
Insurance
Insurance Aggregators Market
Insurance
Earthquake Insurance Market
Insurance
India Health Insurance Market
Insurance
Logistics Insurance Market
Insurance
Canada Parametric Insurance Market
Insurance
Income Protection Insurance Market
Insurance
India Liability Insurance Market
Insurance
Property and Casualty Insurance Market
Insurance
Financial Guarantee Market
Insurance
EV Insurance Market