
 Family Floater Health Insurance Market | 2026-2036
Family Floater Health Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Family Floater Health Insurance Market Foresight
Pay-per-use reinsurance and asset-light captive structures is reconfiguring capital deployment across the family floater segment, allowing regional carriers to challenge legacy balance sheets. UnitedHealth Group leverages its integrated care networks to sustain pricing power in employer-sponsored family plans. Allianz SE anchors its competitive position through specialized underwriting engines for multi-generational households. AXA SA differentiates via direct digital distribution that bypasses traditional agent commissions.
Family floater health insurance pools coverage for multiple family members under a single shared sum insured, with premiums calculated on the age of the oldest member and typically offering restoration benefits once the base coverage exhausts. The product structure allocates one deductible across all insured lives, reducing administrative overhead for nuclear families compared to individual policies. Comprehensive Plans dominate premium volume due to their inclusion of outpatient and maternity riders, while Top-Up Plans represent the fastest-expanding category as employers shift to high-deductible base policies. Coverage Type segmentation reveals Inpatient Care as the mature margin pool, whereas Preventive Care benefits are expanding fastest under wellness-linked premium discounts.
IRDAI mandates minimum hospitalization coverage standards and free-look periods that shape product design and disclosure requirements across Indian family floater offerings. The Insurance Regulatory and Development Authority of India also governs solvency ratios and commission caps that determine distributor economics and market access tiers. Stakeholders must monitor how regulator-mandated portability rules alter customer lifetime value calculations and retention investment thresholds.
Market Dynamics
Digital distribution infrastructure and IRDAI-mandated portability rules are compressing customer acquisition costs while fragmenting loyalty pools across India's family floater segment.
Growth Catalysts
- IRDAI Portability Mandates:Policyholders in India now switch insurers without losing accumulated benefits, forcing carriers to invest in retention infrastructure and product differentiation.
- Urban Nuclear Household Concentration:Mumbai, Delhi, and Bangalore generate disproportionate premium volume as dual-income families prioritize single-policy convenience over individual coverage.
- Restoration Benefit Standardization:Automatic sum-insured reinstatement post-claim exhaustion is migrating from premium-tier products to mid-market offerings, expanding addressable demand.
Market Restraints
- Adverse Selection Concentration:Older household members drive premium calculations while younger lives subsidize utilization, compressing margins in multi-generational policies.
- Claims Cost Volatility:Hospitalization inflation in Indian metro centers outpaces premium adjustment cycles, eroding loss ratios for Comprehensive Plans.
- Commission Cap Compression:IRDAI limits on distributor payouts reduce agent incentive alignment, slowing penetration in tier-two and tier-three cities.
Strategic Opportunities
- Top-Up Plan White Space:Employer-sponsored high-deductible base policies create attach-rate opportunities for supplemental family coverage in Bangalore's technology sector.
- Preventive Care Integration:Wellness-linked premium discounts tied to biometric screening are expanding fastest among Delhi's salaried professionals.
- Telemedicine Rider Convergence:Virtual consultation benefits bundled with inpatient coverage address outpatient cost anxiety for Mumbai's time-constrained households.
Industry Challenges
- Legacy Core System Integration:Regional carriers struggle to connect policy administration platforms with real-time claims adjudication networks, delaying digital-first product launches.
- Actuarial Talent Scarcity:Specialized underwriting expertise for multi-generational risk pooling concentrates with established players, constraining new entrant product sophistication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Family Floater Health Insurance Market |
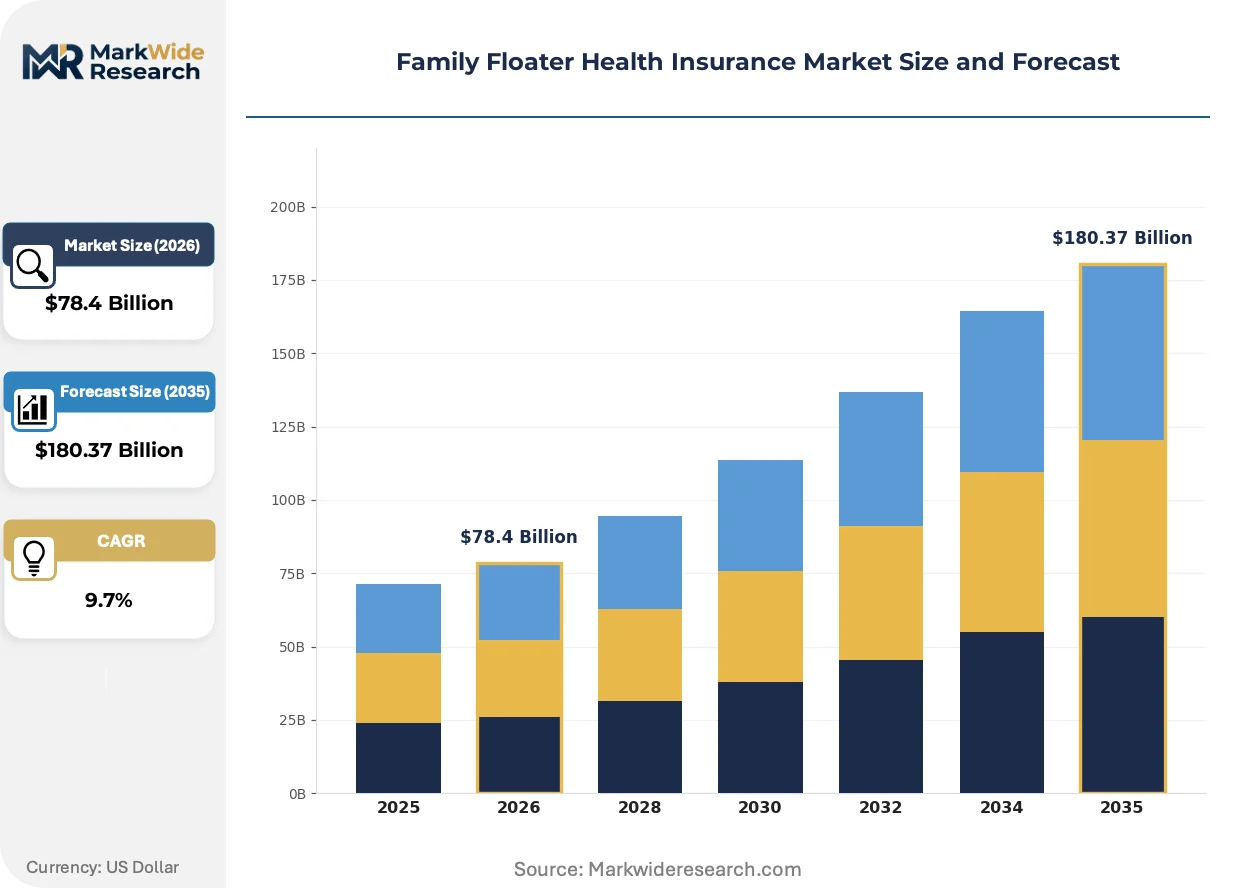
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $180.37 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Comprehensive Plans, Catastrophic Plans, Critical Illness Plans, Top-Up Plans Coverage Type: Inpatient Care, Outpatient Services, Preventive Care, Maternity Coverage Policy Term: Annual, Biennial, Lifetime, Short-Term Premium Range: Low Cost, Mid Tier, High End, Customizable Plans |
| Companies Covered | UnitedHealth Group, Elevance Health, CVS Health, Kaiser Foundation Group, Cigna, Allianz SE, AXA SA, Bupa, Humana Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Family Floater Health Insurance Market Shifts & Advancements
Artificial intelligence and behavioral data analytics are compressing underwriting cycles while enabling dynamic premium adjustments based on real-time health metrics.
AI-powered claims triage is migrating from retrospective fraud detection to pre-authorization automation, reducing hospital cashless settlement timelines from days to hours. Tier-one Indian carriers are deploying these engines across family floater portfolios to manage restoration benefit utilization patterns. The technology is migrating from cost-center efficiency plays to competitive differentiation tools that determine policyholder retention rates.
IRDAI's 2020 guidelines on standardization of exclusions and waiting periods have forced product homogenization at the base coverage layer. Carriers now compete through rider packaging and service-level guarantees rather than core benefit differentiation. Preventive Care riders and wellness program integrations are absorbing the competitive energy previously directed at inpatient sum-insured levels.
Direct-to-consumer digital distribution is displacing agent-mediated sales for renewal transactions among India's metro nuclear families. Policyholders in Delhi and Mumbai now compare portability options through aggregator platforms, compressing switching costs. This channel rotation is most visible among employer-sponsored group-to-individual conversions at policy expiration.
Family Floater Health Insurance Market Segmentation
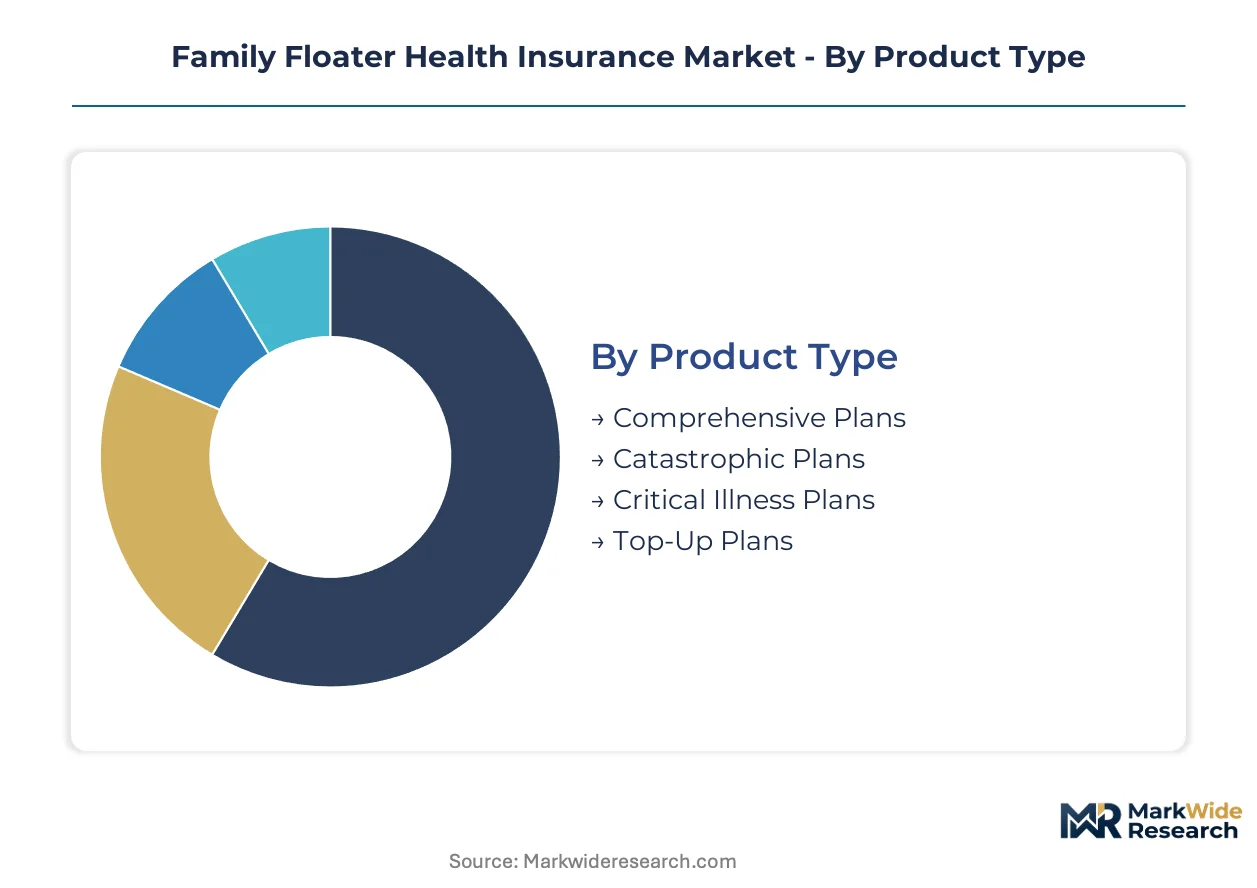
Family floater health insurance segmentation reflects divergent risk appetites across India's urban household structures. Product architects must balance premium affordability against restoration benefit depth across multi-generational coverage pools.
Product Type:
Use-case spectrum spans emergency-only protection through comprehensive multi-year coverage with wellness integration.
- Comprehensive Plans:These products bundle inpatient hospitalization with outpatient consultations, maternity riders, and preventive screenings under one sum insured. Mumbai's dual-income nuclear households drive disproportionate demand for single-policy convenience that eliminates coordination across multiple individual covers.
- Top-Up Plans:Supplemental coverage activates only after base policy exhaustion, enabling employers to shift to high-deductible primary structures. Bangalore's technology sector employers are expanding attach rates for these products as group coverage conversions accelerate at policy expiration.
- Catastrophic Plans:High-deductible products targeting extreme medical events with lower premiums for budget-constrained households.
- Critical Illness Plans:Lump-sum payouts upon diagnosis of specified conditions, often purchased as riders to base floater structures.
The dominant share belongs to Comprehensive Plans, while Top-Up Plans are closing the gap fastest.
Coverage Type:
Margin profiles diverge sharply between mature inpatient categories and emerging preventive benefit layers.
- Inpatient Care:Hospitalization coverage remains the core risk transfer mechanism, with cashless network access determining carrier competitiveness. Delhi's salaried professionals prioritize this segment for emergency cardiac and surgical interventions.
- Preventive Care:Wellness-linked biometric screenings and annual health checkups now absorb competitive differentiation energy previously directed at sum-insured levels. This category is expanding most quickly among metro households seeking premium discounts through lifestyle verification.
- Outpatient Services:Consultation and diagnostic coverage addressing chronic condition management outside hospitalization events.
- Maternity Coverage:Delivery and newborn care benefits, increasingly standardized across mid-market offerings following IRDAI guideline harmonization.
Inpatient Care commands the established premium base, though Preventive Care is gaining share fastest through wellness-linked pricing models.
Policy Term:
Duration selection reflects household liquidity constraints against long-term rate-locking preferences.
- Annual:Single-year contracts dominate transaction volume, enabling portability utilization under IRDAI-mandated switching rules. This structure concentrates in price-sensitive segments comparing aggregator platform options at each renewal cycle.
- Lifetime:Guaranteed renewable products with age-capped premiums attract multi-generational households seeking rate predictability. These contracts are climbing fastest as nuclear families lock in insurability before age-driven premium escalations.
- Biennial:Two-year terms offering modest premium discounts for commitment duration.
- Short-Term:Temporary coverage bridging employment transitions or waiting periods.
Annual policies retain volume leadership, while Lifetime products are expanding most quickly among households prioritizing rate certainty.
Premium Range:
Pricing tiers stratify across household income brackets and risk tolerance thresholds.
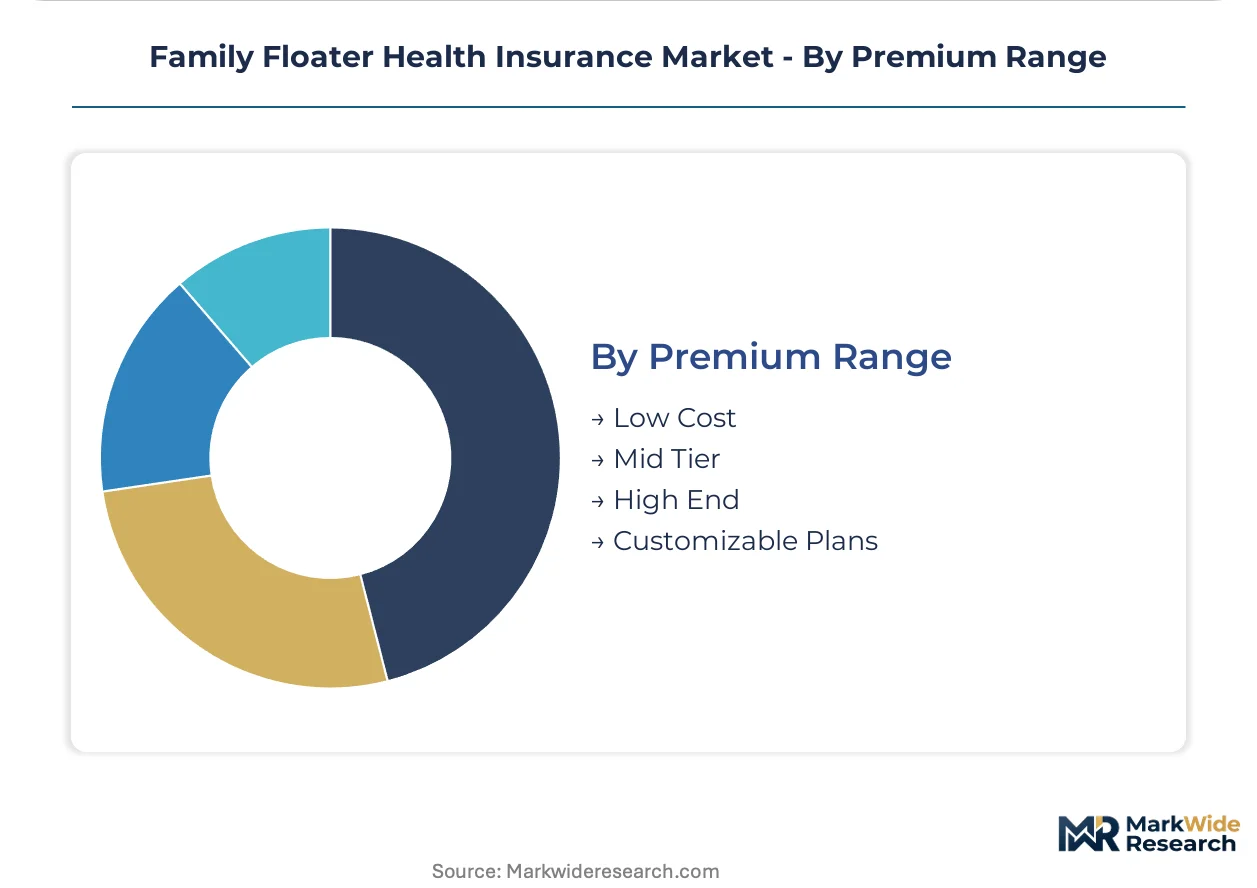
- Mid Tier:Products balancing restoration benefits with moderate deductibles capture the addressable middle. This segment concentrates in Bangalore and Hyderabad's technology corridors where employer-sponsored base coverage creates attach opportunities for supplemental family layers.
- Customizable Plans:Modular structures allowing riders for specific conditions, wellness programs, or international coverage attract Delhi and Mumbai's high-net-worth households seeking tailored protection.
- Low Cost:Entry-level products with restricted hospital networks and higher co-payment requirements.
- High End:Premium offerings with zero deductibles, international coverage, and concierge claim management.
Mid Tier products hold the dominant position, though Customizable Plans are closing the gap fastest through modular rider attachment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's family floater segment operates as a net importer of reinsurance capacity, with domestic carriers ceding risk to global markets while premium retention concentrates in tier-one urban centers. Cross-border capital flows from European reinsurers sustain loss-absorbing capacity for multi-generational policies. Regulatory arbitrage between IRDAI-mandated solvency requirements and international accounting standards shapes capital deployment efficiency.
United States
Employer-sponsored family coverage anchors commercial premium volume, with integrated care networks capturing disproportionate margin pools. HIPAA portability provisions and Affordable Care Act dependent coverage mandates through age 26 expand addressable household bases. The Dallas-Fort Worth metroplex concentrates regional carrier headquarters competing for mid-market employer accounts.
Germany
Statutory health insurance family coverage creates baseline demand, while private supplemental floaters capture affluent dual-income households seeking elective procedure access. BfArM medical device reimbursement classifications and BaFin solvency supervision shape product design parameters. Munich's insurance cluster hosts reinsurance treaty negotiation for multi-national family portfolios.
United Kingdom
NHS waiting list pressures drive private family coverage adoption among professional households, with cash-plan products bridging outpatient cost gaps. FCA conduct rules and PRA capital requirements govern distribution transparency and reserving adequacy. London's fintech corridor incubates digital-first family policy aggregators compressing acquisition costs.
China
Urban household registration restrictions fragment family floater penetration, with commercial products supplementing basic medical insurance gaps for migrant worker families. NMPA digital health platform registrations and CBIRC internet insurance regulations constrain direct distribution channel expansion. Shanghai's Pudong district concentrates foreign joint-venture carriers piloting wellness-linked premium models.
Australia
Lifetime Health Cover loading penalties and Medicare Levy Surcharge thresholds accelerate family policy uptake among thirty-something households. APRA prudential standards and PHIAC premium rating restrictions limit risk-based pricing differentiation. Sydney's northern suburbs concentrate high-income families driving demand for comprehensive obstetric and pediatric coverage tiers.
Family Floater Health Insurance Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in risk selection and niche underwriting engines. The family floater market structures around three archetypes: integrated care networks bundling delivery with financing, reinsurance-backed primary carriers leveraging balance sheet scale, and digital-native distributors stripping acquisition costs from legacy commission structures. Consolidation pressures concentrate among mid-tier regional underwriters unable to fund restoration benefit standardization. Vertical integration into captive primary care networks and strategic partnerships with telemedicine platforms constitute the dominant competitive moves reshaping value chain capture.
Within the integrated network tier, UnitedHealth Group and Kaiser Foundation Group exemplify care-delivery-cum-insurance models that compress medical loss ratios through utilization management. European reinsurance-backed carriers include Allianz SE and AXA SA, which occupy positions bridging global capital pools with localized underwriting expertise for multi-generational household risk. These named entities represent strategic archetypes rather than exhaustive market coverage, with each anchoring distinct competitive vectors—UnitedHealth through employer channel dominance, Kaiser through geographic concentration, Allianz through specialized household engines, and AXA through direct digital distribution bypassing traditional agent economics.
| Leading Market Players |
|---|
| UnitedHealth Group |
| Elevance Health |
| CVS Health |
| Kaiser Foundation Group |
| Cigna |
| Allianz SE |
| AXA SA |
| Bupa |
| Humana Group |
| Others |
Supply & Pricing Matrix
Mumbai's insurance distribution cluster concentrates captive agent networks and direct-to-consumer platforms, channeling premium volume toward carriers with scale advantages in restoration benefit deployment. This geographic concentration of underwriting capacity enables tier-one insurers to extract pricing power from regional competitors struggling with IRDAI-mandated solvency requirements.
Pricing Analysis
Employer-sponsored buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium differentiation hinges on restoration benefit depth and cashless hospital network tier, with IRDAI commission caps compressing distributor margins and forcing price competition toward policy features. Pricing pressure stems from hospitalization inflation in Delhi and Bangalore outpacing premium adjustment cycles. Price-sensitive households in tier-two cities gravitate toward economy tiers with restricted networks, while Mumbai's dual-income professionals absorb premium tiers for concierge claim management.
Supply Chain Analysis
Cross-border reinsurance treaty restrictions under IRDAI's foreign investment caps limit capital flow velocity into domestic risk pools. Supply concentration centers on India, Germany, and Switzerland for treaty capacity, with Munich and Zurich hosting primary negotiation hubs for multi-generational household portfolios. Raw material dependencies include actuarial talent pools, digital claims infrastructure, and hospital network access agreements. Single-source vulnerability concentrates in legacy core system vendors serving regional carriers. Distribution runs through captive agent networks, direct digital platforms, and employer-sponsored group-to-individual conversion channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Self-insured employer health plans represent the substitution threat that incumbent family floater carriers must neutralize through product differentiation and channel control.
For Market Incumbents: Insulate core employer-sponsored relationships by embedding restoration benefits as standard features rather than premium-tier differentiators. Deepen backward integration into telemedicine platforms to capture outpatient cost management and reduce claims leakage. Neutralize self-insured plan substitution by offering administrative-only services with stop-loss attachment points that retain customer relationships. For New Entrants and Emerging Players: Establish a beachhead in Bangalore's technology sector employer conversions, where high-deductible base policies create attach-rate opportunities for supplemental family coverage. Target Delhi's salaried professionals with wellness-linked premium discount products that bypass legacy agent economics. Deploy direct digital distribution through aggregator platforms to compress customer acquisition costs below incumbent commission structures. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors carriers with AI-powered claims adjudication engines and integrated care network contracts. Long-term viability hinges on underwriting sophistication for multi-generational risk pools and regulatory navigation of IRDAI portability mandates. Watch for consolidation signals among mid-tier regional underwriters unable to fund restoration benefit standardization or digital core system migration.| Strategic Initiative | Industry Significance |
|---|---|
| Restoration Benefit Standardization | Migration from premium-tier to mid-market offerings expands addressable demand across Mumbai and Delhi nuclear households. |
| Telemedicine Platform Integration | Virtual consultation bundling with inpatient coverage addresses outpatient cost anxiety for time-constrained professionals. |
| Direct Digital Distribution Buildout | Aggregator platform partnerships compress switching costs and accelerate group-to-individual conversion capture. |
| AI Claims Triage Deployment | Pre-authorization automation reduces cashless settlement timelines from days to hours, driving retention. |
| Wellness Program Partnership | Biometric screening integration enables premium discounting that differentiates beyond core inpatient sum-insured levels. |
Research Methodology
The analysis maps family floater product tiers, coverage types, and policy term structures, each validated through actuarial directors, health insurance product managers, and hospital network contracting officers. Primary interviews with IRDAI regulatory specialists and reinsurance treaty negotiators in Mumbai and Zurich combined with secondary validation from IRDAI circulars, insurance company annual filings, and hospital procurement databases. Bottom-up policy volume estimates triangulated against top-down premium pool assessments across tier-one Indian cities.
Assumptions held fixed include IRDAI solvency ratio requirements and portability mandate enforcement intensity, while hospitalization inflation trajectories and digital adoption curves varied across sensitivity scenarios. Segmentation dimensions modeled encompass product type, coverage category, policy duration, and premium tier, with household structure and geographic concentration as cross-cutting variables. CAGRs derived from trend extrapolation of policy issuance velocity and sum-insured growth patterns, calibrated against employer-sponsored coverage conversion rates and telemedicine rider attachment trends.
Macroeconomic conditions sit as an overlay; deviation in household disposable income growth or urban nuclear family formation rates would shift the trajectory. Forecasts reflect assumptions of continued IRDAI regulatory stability and reinsurance capacity availability. Material shifts in hospitalization cost inflation or digital distribution platform consolidation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
China Parametric Insurance Market
Insurance
UK Cyber (Liability) Insurance Market
Insurance
Social Media Analytics-Based Insurance Market
Insurance
Online Insurance Market
Insurance
Marine Cargo Insurance Market
Insurance
Austria Property and Casualty Insurance Market
Insurance
Solar Panel Warranty Insurance Market
Insurance
Liability Insurance Market
Insurance
India Travel Insurance Market
Insurance
Self Funded Insurance Market
Insurance
Japan Bancassurance Market
Insurance
Canada House Insurance Market
Insurance
Sri Lanka Cyber (Liability) Insurance Market
Insurance
USA Travelers Insurance Market
Insurance
Cancer Insurance Market
Insurance
Takaful Market