
 Asia-Pacific Wireless Electric Vehicle Charging Market | 2026-2036
Asia-Pacific Wireless Electric Vehicle Charging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Wireless Electric Vehicle Charging Market Analytics
Modular charging pad configurations is decoupling hardware from installation services, reshaping procurement patterns across fleet electrification programs. Toyota Motor Corporation leverages its hybrid-electric heritage to anchor wireless charging R&D in Japanese automotive corridors. BYD Co. Ltd. dominates commercial vehicle applications through vertical integration into battery and power electronics manufacturing. WiTricity Corporation specializes in magnetic resonance licensing, positioning its intellectual property across multiple Asian OEM partnerships.
Asia-Pacific wireless electric vehicle charging transfers electrical energy across air gaps through electromagnetic induction or resonant coupling, typically operating at frequencies between 20-100 kHz with coil-to-coil distances of 100-300 millimeters. The technology eliminates conductive connectors, reducing wear in high-frequency fleet turnaround environments while enabling automated charging sequences. Static charging pads currently occupy the largest installed base due to lower infrastructure complexity, though dynamic charging systems along roadways represent the fastest-growing segment as pilot projects expand in China and South Korea. Fleet operators command disproportionate margin pools versus residential users because volume procurement agreements and standardized vehicle specifications reduce deployment friction.
China's MIIT issues GB standards governing electromagnetic compatibility and efficiency thresholds for wireless power transfer in automotive applications. Japan's METI and South Korea's MFDS coordinate bilateral standards alignment through IEC working groups, streamlining cross-border equipment certification. India's CEA and BIS are developing localized testing protocols for tropical climate resilience and grid integration. Stakeholders must monitor which regulatory body secures de facto standard-setting authority across ASEAN harmonization talks.
Market Dynamics
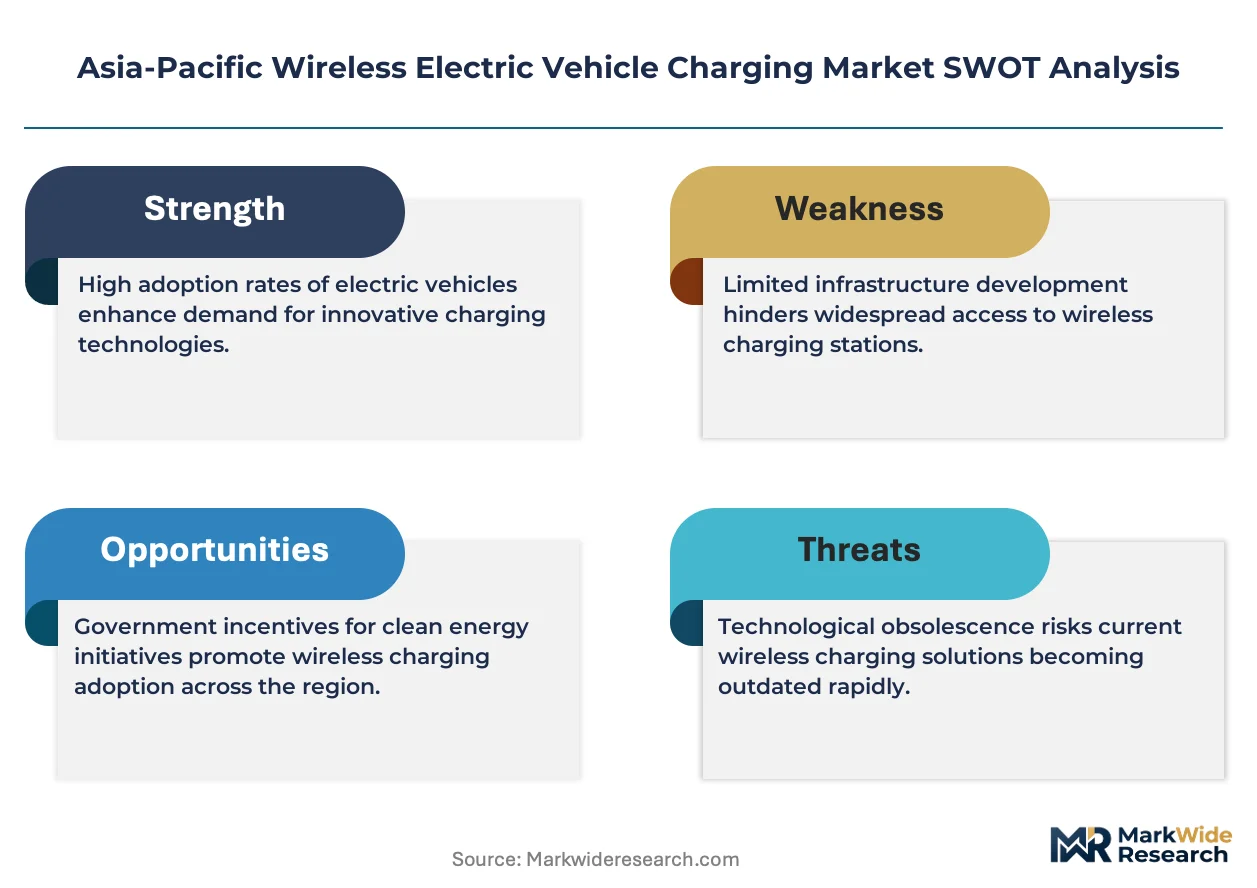
Japan's METI efficiency mandates are compressing standardization timelines across the Asia-Pacific wireless electric vehicle charging landscape, forcing supply chain reconfiguration toward unified coil architectures before 2030 deployment windows.
Growth Catalysts
- MIIT GB Standards:China's electromagnetic compatibility thresholds for automotive wireless power transfer create enforceable efficiency baselines that accelerate OEM platform consolidation.
- Fleet Electrification:Municipal bus operators in Guangdong province are mandating automated charging sequences to eliminate connector wear in high-turnaround depot environments.
- Magnetic Resonance Maturation:Coil-to-coil distances extending beyond 200 millimeters are absorbing infrastructure complexity costs into vehicle-side electronics.
Market Restraints
- Ferrite Core Supply Concentration:Rare-earth magnetic material processing clusters in Jiangsu province create single-point vulnerability for pad manufacturer input costs.
- Frequency Allocation Friction:South Korea's MFDS and Japan's METI maintain divergent 85 kHz band licensing protocols that fragment cross-border equipment certification.
- Conductive Fast Charging Substitution:350 kW conductive systems at highway corridors threaten to capture long-haul commercial vehicle charging volume.
Strategic Opportunities
- Dynamic Roadway Integration:Pilot projects along Shanghai's expressway corridors are validating in-motion power transfer for heavy-duty logistics corridors.
- India Tropical Climate Protocols:CEA and BIS testing frameworks for humidity and dust resilience open first-mover positioning in ASEAN expansion paths.
- Inductive-Autonomous Convergence:Automated parking alignment systems from robotics suppliers are compressing interoperability gaps between vehicle positioning and pad activation.
Industry Challenges
- Electromagnetic Compatibility Certification:MIIT testing timelines for GB standard compliance extend 14-18 months, freezing product launch cycles.
- Power Electronics Talent Scarcity:RF coil design and resonant converter engineering expertise concentrates in Tokyo-Osaka automotive corridors, constraining supplier scaling.
- Legacy Grid Integration:Distribution network capacity limitations in Jiangsu manufacturing zones force concurrent substation upgrades with pad deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Wireless Electric Vehicle Charging Market |
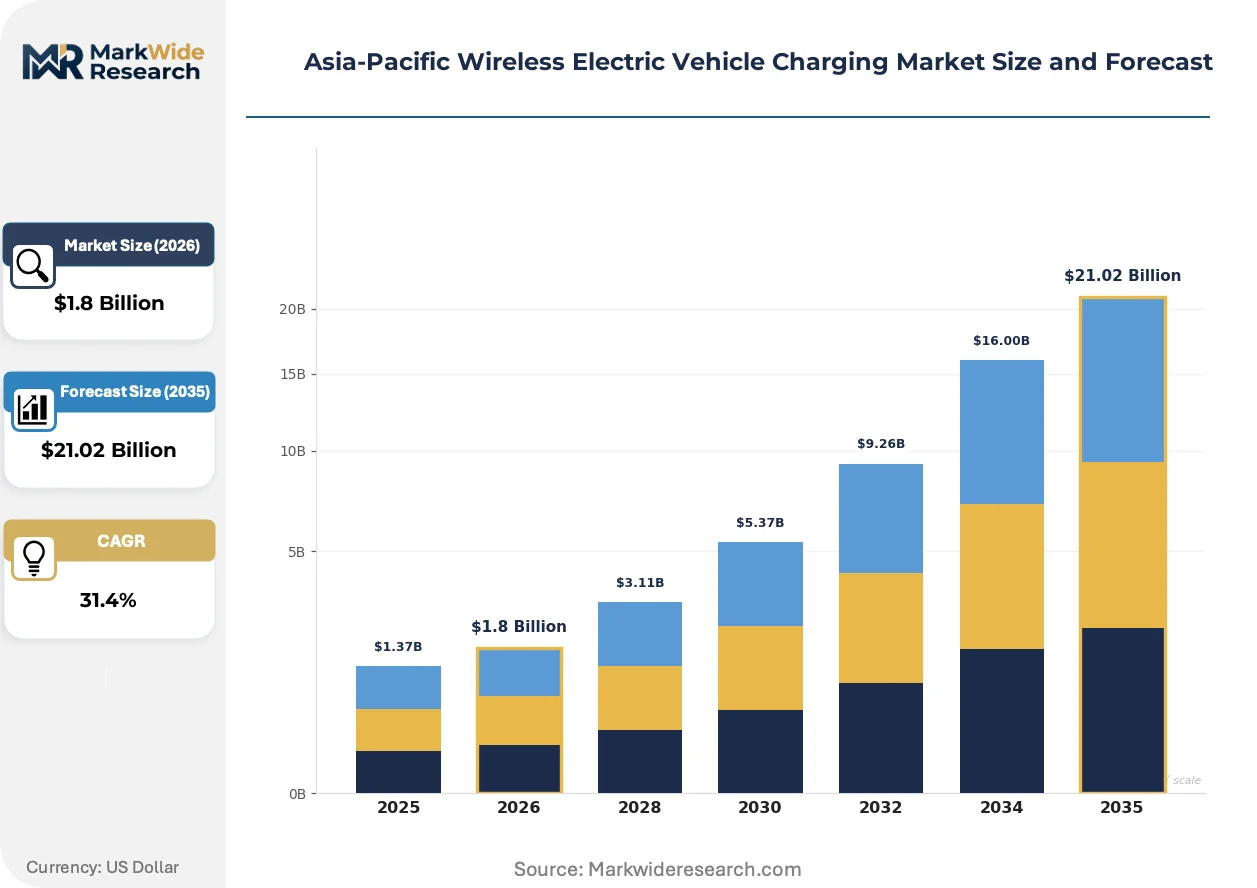
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $21.02 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static Charging Pads, Dynamic Charging Systems, Portable Chargers, Infrastructure Solutions End User: Fleet Operators, Public Transport Providers, Residential Users, Commercial Vehicles Technology: Inductive Charging, Resonant Charging, Capacitive Charging, Magnetic Resonance Installation: Surface-Mounted, In-Ground, Overhead Systems, Integrated Solutions |
| Companies Covered | Toyota Motor Corporation, BYD Co. Ltd., Nissan Motor Co., Ltd, Delta Electronics, WiTricity Corporation, Qualcomm Technologies, Bombardier, OLEV Technologies, Star Charge, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Wireless Electric Vehicle Charging Market Evolving Landscape
Resonant coupling architectures are absorbing infrastructure investment cycles across Asia-Pacific fleet electrification programs, compressing the traditional hardware-installation-service procurement sequence into unified platform contracts.
Magnetic resonance systems operating at 85 kHz are absorbing the complexity premium previously assigned to dynamic charging installations. Fleet operators in South Korea's Incheon logistics corridor are adopting standardized coil geometries across 40-foot bus platforms. This frequency consolidation is absorbing regulatory fragmentation costs into vehicle-side power electronics design.
METI and MFDS bilateral alignment through IEC working groups is dissolving cross-border equipment certification barriers. Japanese automotive suppliers are consolidating testing protocols to single-lab validation for dual-market entry. The harmonization is absorbing timeline risk for OEMs targeting simultaneous China and South Korea commercial vehicle launches.
Bus procurement departments are consolidating charging infrastructure decisions into vehicle purchase contracts, eliminating separate RFP processes for pad installation. Municipal operators in Guangdong are bundling 10-year service agreements with hardware acquisition. This bundling is absorbing margin compression from hardware commoditization into captive maintenance revenue streams.
Asia-Pacific Wireless Electric Vehicle Charging Market Segmentation
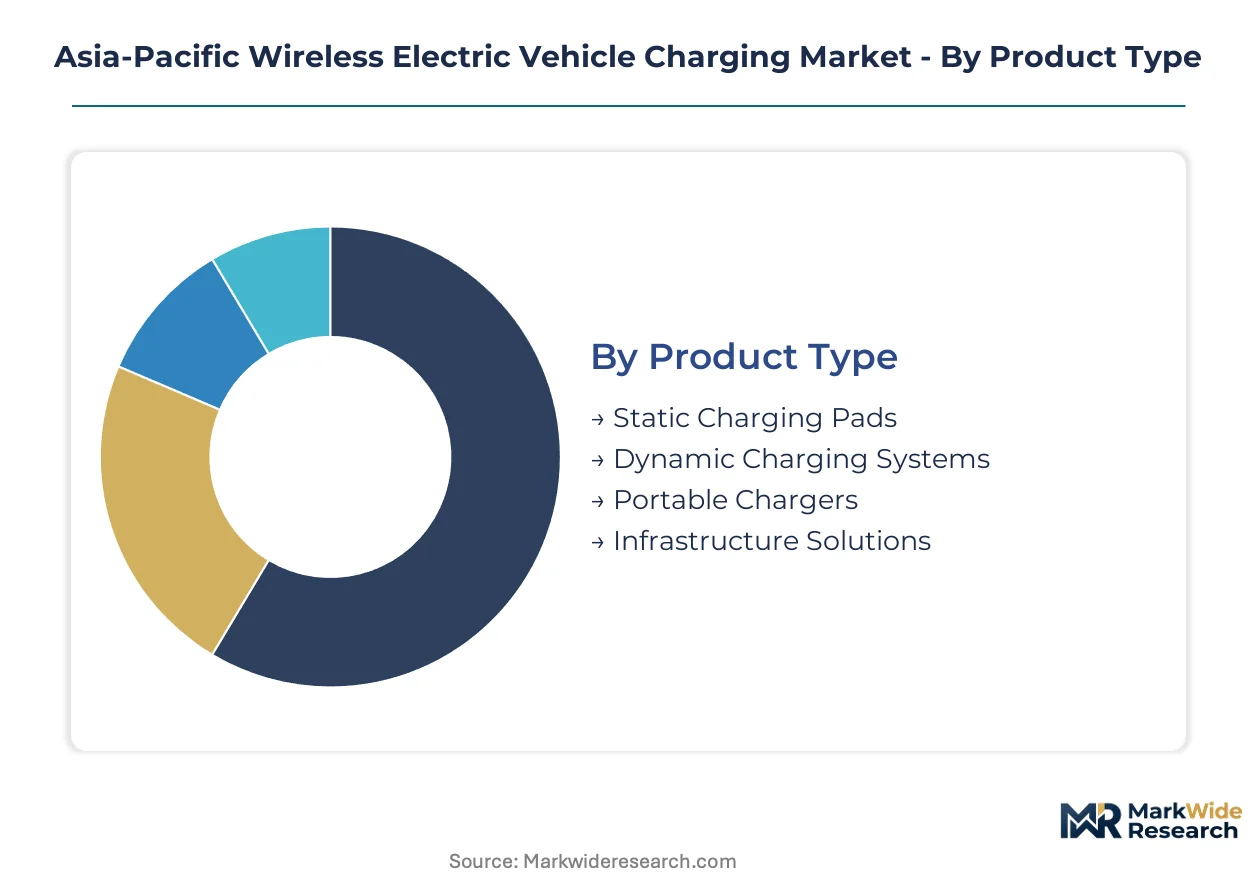
Segmentation in Asia-Pacific wireless electric vehicle charging reveals how procurement authority, technical specifications, and infrastructure constraints fragment addressable revenue pools across fleet electrification programs.
Product Type:
Cost tier differentiation separates capital-intensive infrastructure plays from deployable hardware units in procurement cycles across Guangdong and Jiangsu manufacturing zones.
- Static Charging Pads:Fixed-position ground-embedded or surface-mounted coil assemblies operating at 85 kHz with 100-200 millimeter air gaps dominate depot-based fleet deployments. Municipal bus operators in Guangdong province mandate these configurations for overnight charging sequences, absorbing standardization costs into volume procurement agreements.
- Dynamic Charging Systems:Roadway-embedded transmitter segments enable in-motion power transfer across extended coil arrays. Pilot corridors along Shanghai expressways validate heavy-duty logistics applications where conductive charging downtime disrupts route economics.
- Portable Chargers:Mobile pad units with integrated power electronics serve intermittent-use commercial vehicle segments in distributed fleet operations.
- Infrastructure Solutions:Grid-interconnection packages encompassing substations, metering, and cloud-based load management anchor turnkey deployment contracts.
Static charging pads lead volumes today; dynamic charging systems are gaining share fastest.
End User:
Volume concentration and margin capture diverge sharply between standardized fleet specifications and fragmented residential deployment economics.
- Fleet Operators:Municipal and commercial vehicle fleet managers command disproportionate margin pools through centralized procurement of standardized coil geometries. Bus operators in South Korea's Incheon corridor bundle 10-year service agreements with hardware acquisition, absorbing margin compression into captive maintenance revenue.
- Public Transport Providers:State-owned transit authorities in China drive GB standard compliance requirements through electromagnetic compatibility mandates from MIIT.
- Residential Users:Individual vehicle owners face installation complexity premiums and fragmented parking ownership structures across Japanese urban corridors.
- Commercial Vehicles:Logistics and delivery fleet segments prioritize interoperability across multiple OEM platforms.
Fleet operators anchor revenue concentration today; public transport providers are expanding procurement fastest.
Technology:
Maturity curves and frequency standardization timelines fragment R&D allocation across electromagnetic coupling architectures.
- Inductive Charging:Near-field electromagnetic induction at sub-100 kHz frequencies with tight coil alignment tolerances dominates installed base in Japanese automotive corridors. METI efficiency mandates compress standardization timelines toward unified architectures before deployment windows.
- Resonant Charging:Magnetic resonance systems operating at 85 kHz extend coil-to-coil distances beyond 200 millimeters, absorbing infrastructure complexity costs into vehicle-side electronics design across South Korean logistics pilots.
- Capacitive Charging:Electric field coupling through plate electrodes rather than coils serves niche applications with strict electromagnetic interference constraints.
- Magnetic Resonance:High-efficiency resonant coupling with extended spatial tolerance enables dynamic roadway integration architectures.
Inductive charging leads installed base today; resonant charging is climbing the fastest.
Installation:
Site preparation requirements and civil engineering intensity fragment deployment velocity across manufacturing and logistics corridors.
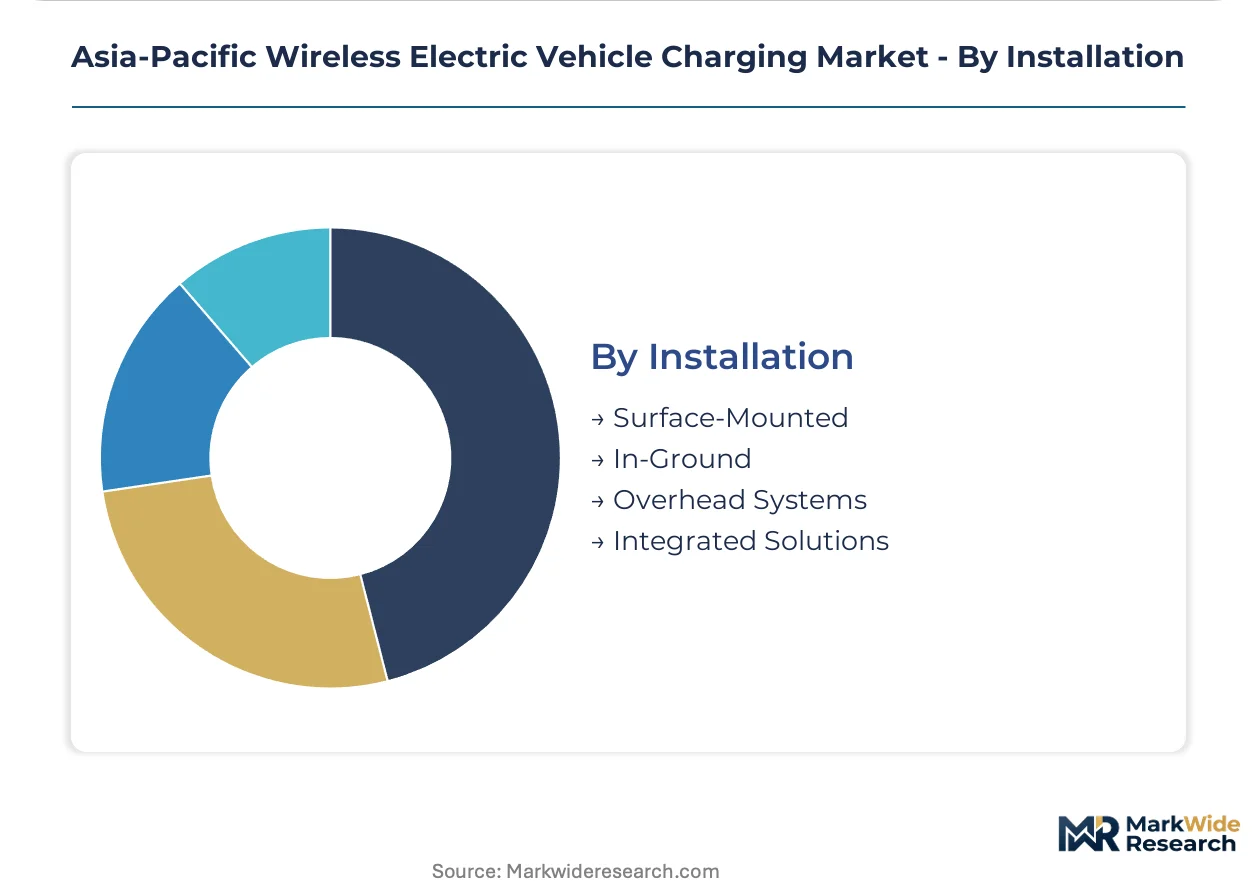
- Surface-Mounted:Above-ground pad assemblies with minimal civil works enable rapid retrofit deployment in existing depot environments across Jiangsu province manufacturing clusters.
- In-Ground:Flush-mounted subgrade installations with reinforced housing withstand heavy vehicle loading in high-frequency turnaround environments.
- Overhead Systems:Suspended transmitter arrays serve specialized applications with ground space constraints.
- Integrated Solutions:Factory-installed vehicle-side receiver and transmitter packages embedded during OEM assembly streamline deployment friction.
Surface-mounted installations lead deployment velocity today; in-ground systems are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Inductive charging technology first achieved commercial scale in Japanese automotive corridors during the early 2010s, with METI-funded pilot programs establishing the technical foundations that now propagate across Asia-Pacific manufacturing zones.
China
Guangdong and Jiangsu provinces anchor regional supply chains through dense automotive electronics manufacturing clusters. MIIT's GB standards for electromagnetic compatibility enforce efficiency baselines that accelerate OEM platform consolidation. Municipal bus operators in Shenzhen mandate automated charging sequences to eliminate connector wear in high-turnaround depot environments.
Japan
Tokyo-Osaka automotive corridors concentrate RF coil design expertise and resonant converter engineering talent. METI efficiency mandates compress standardization timelines toward unified coil architectures before 2030 deployment windows. Toyota Motor Corporation leverages hybrid-electric heritage to anchor wireless charging R&D in Aichi prefecture manufacturing zones.
South Korea
Incheon logistics corridor fleet operators adopt standardized coil geometries across 40-foot bus platforms. MFDS maintains 85 kHz band licensing protocols that fragment cross-border equipment certification with Japan. Seoul Capital Area suppliers consolidate testing protocols to single-lab validation for dual-market entry with China.
India
Delhi-NCR and Maharashtra manufacturing zones drive demand for tropical climate resilience testing. CEA and BIS develop localized protocols for humidity and dust resilience that open first-mover positioning in ASEAN expansion paths. Distribution network capacity limitations force concurrent substation upgrades with pad deployment in Gujarat industrial corridors.
Australia
New South Wales and Victoria pilot dynamic roadway integration along heavy-duty logistics corridors. State-level transport authorities evaluate electromagnetic compatibility against existing grid infrastructure. Sydney and Melbourne metropolitan procurement departments bundle long-term service agreements with hardware acquisition for municipal fleet electrification.
Asia-Pacific Wireless Electric Vehicle Charging Market Competitive Landscape
Premium-margin players sit above commodity-margin players across intellectual property licensing and captive manufacturing integration. The vendor base stratifies into three tiers: automotive OEMs with captive charging divisions, pure-play technology licensors, and component fabricators supplying standardized coil assemblies. Consolidation pressure intensifies as fleet procurement departments bundle charging infrastructure decisions into vehicle purchase contracts. Dominant competitive moves include technology licensing partnerships and backward integration into ferrite core processing.
Within the automotive OEM tier, Toyota Motor Corporation and BYD Co. Ltd. exemplify divergent strategic positions. Toyota leverages hybrid-electric heritage to anchor R&D investment in Japanese regulatory corridors. BYD represents vertical integration archetypes through in-house production of battery and power electronics manufacturing. WiTricity Corporation occupies the pure-play licensor position, positioning intellectual property across multiple Asian OEM partnerships without captive vehicle manufacturing.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| BYD Co. Ltd. |
| Nissan Motor Co., Ltd |
| Delta Electronics |
| WiTricity Corporation |
| Qualcomm Technologies |
| Bombardier |
| OLEV Technologies |
| Star Charge |
| Others |
Value Network & Pricing Analysis
China's dual carbon goals gate qualified supply and premium-tier pricing access for wireless charging infrastructure, filtering pad manufacturers through GB standard compliance timelines while concentrating margin capture among METI-certified Japanese suppliers serving fleet procurement programs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement contracts, with GB certification grade and volume scale driving price differentiation. Cost compression in economy-tier static pads is intensifying because Jiangsu province ferrite core suppliers are consolidating. Fleet operators in Guangdong demonstrate lowest price sensitivity due to bundled 10-year service agreements, while residential users in Japanese urban corridors face highest sensitivity from fragmented parking ownership.
Supply Chain Analysis
GB standard certification gates supply chain participation, with coil assembly production concentrating in China, Japan, and South Korea. Ferrite core processing draws from rare-earth magnetic material clusters in Jiangsu province, while power electronics sourcing rests on Tokyo-Osaka automotive corridors. Single-source vulnerability in ferrite core supply creates structural risk. Distribution runs through OEM captive channels and fleet procurement departments bundling hardware with vehicle acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific wireless electric vehicle charging market operates as a stable compounder, with METI-MIIT regulatory harmonization driving steady fleet electrification procurement cycles across municipal bus networks.
For Market Incumbents: Deepen backward integration into ferrite core processing to defend against Jiangsu province supply concentration risk. Expand 85 kHz coil platform standardization across Guangdong and Incheon fleet corridors before 2030 deployment windows compress. Prioritize GB standard pre-certification investments to compress MIIT testing timeline exposure.
For New Entrants and Emerging Players: Municipal fleet procurement departments represent the most penetrable channel partner type for white-space entry, particularly in India CEA tropical climate protocol development. Target Delhi-NCR bus electrification programs where distribution network capacity limitations force concurrent infrastructure investment. Pursue licensing partnerships with established power electronics suppliers to bypass RF coil design talent scarcity.
For Investors and Strategic Acquirers: Roll-up economics work for pure-play magnetic resonance IP licensors because automotive OEMs are outsourcing coil architecture development to focus on vehicle integration. Five-to-ten year viability hinges on dynamic charging pilot validation along Shanghai expressway corridors. Watch for MFDS-METI frequency band alignment completion as inflection signal for cross-border equipment certification acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | 85 kHz frequency consolidation across South Korean and Japanese OEMs reduces regulatory fragmentation costs. |
| Battery Supply Agreement | BYD's captive cell production secures power electronics integration for commercial vehicle wireless charging. |
| Charging Infrastructure Partnership | WiTricity's multi-OEM licensing network accelerates magnetic resonance deployment across ASEAN markets. |
| Geographic Manufacturing Footprint | Tokyo-Osaka corridor concentration of RF engineering talent anchors resonant converter R&D investment. |
| Software-Defined Vehicle Investment | Automated parking alignment systems from robotics suppliers compress interoperability gaps with pad activation. |
Research Methodology
Bottom-up fleet operator procurement modeling reconciled against top-down coil manufacturer capacity tracking forms the analytical core. Primary interviews with municipal transit procurement directors, OEM platform engineers, power electronics R&D leads, and ferrite core suppliers combine with secondary validation from MIIT GB standard filings, METI efficiency mandate documentation, IEA electric vehicle deployment databases, and customs trade records for magnetic component flows. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of inductive charging pilot deployments in Japanese automotive corridors informs projection trajectories across the analysis window. Segmentation dimensions include product type, end user archetype, technology maturity curve, and installation site preparation intensity. CAGRs derive from fitted growth curves against fleet electrification mandate timelines. Forecast inputs incorporate MIIT testing timeline distributions and METI-MFDS harmonization probability assessments.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to dynamic charging pilot validation results and ASEAN regulatory harmonization progress. Assumptions reflect current GB standard enforcement intensity and fleet procurement bundling trends. A model refresh is warranted upon material change in MIIT electromagnetic compatibility certification timelines or ferrite core supply chain restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Sweden Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Solar Carport Charging Station Market
Electric Vehicle Charging
HVAC Electronically Commutated Motor (ECM) Market
Electric Vehicle Charging
Portable Charging Units Market
Electric Vehicle Charging
Integrated EV Chargers Market
Electric Vehicle Charging
EV Smart Charge Controller Market
Electric Vehicle Charging
Smart EV Battery Charger Market
Electric Vehicle Charging
Europe EV Charging Stations Market
Electric Vehicle Charging
Electric Bus Charging Infrastructure Market
Electric Vehicle Charging
Germany EV Charging Infrastructure Market
Electric Vehicle Charging
Italy Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle Charging Station Market
Electric Vehicle Charging
Spain Electric Vehicle (EV) Charging Equipment Market
Electric Vehicle Charging
Germany Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle Rapid Charger Market
Electric Vehicle Charging
Electric Vehicle Public Charging Pile Market