
 Oman EV Charging Station Market | 2026-2036
Oman EV Charging Station Market Size, Share, and Industry Trends Forecast 2026-2036
Oman EV Charging Station Market Insights
DC fast-charging capability is collapsing the price-performance gap that once favored slower AC installations for fleet and commercial use. Siemens anchors its position through utility-scale grid integration expertise, while ABB competes with modular hardware architectures suited to Oman's coastal climate conditions. Schneider Electric differentiates through energy management software that optimizes demand charges for commercial operators.
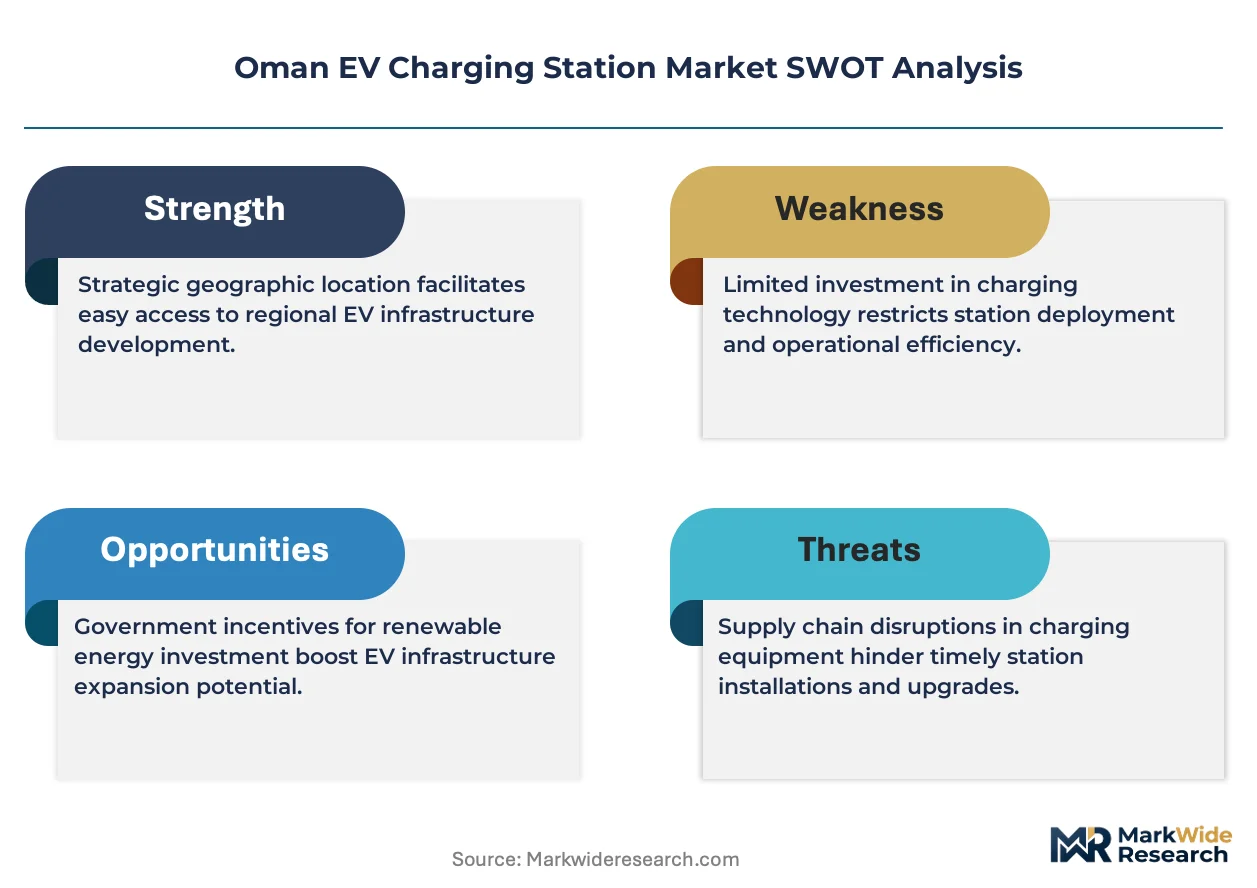
An EV charging station is an electromechanical system that converts grid electricity to standardized DC or AC output at power levels ranging from 3.7 kW residential units to 350 kW ultra-fast dispensers, enabling battery electric vehicles to replenish stored energy. Its primary commercial purpose is to extend vehicle operational range while generating revenue through energy sales, subscription fees, or demand-response grid services. AC charger deployments still occupy the largest installed base across residential and workplace settings, yet DC fast charger installations represent the fastest-growing segment as fleet operators and highway corridor developers prioritize turnaround speed over capital economy. Smart charging connectivity is where margin pools concentrate, since software-enabled load balancing and grid-interactive controls command recurring service revenue beyond hardware margins.
Oman's Authority for Electricity Regulation and the Ministry of Transport, Communications and Information Technology shape deployment rules through interconnection standards and public charging network licensing requirements. The country's national EV strategy and building code amendments for new commercial developments are mandating pre-wired charging readiness, which expands addressable market volume without requiring immediate hardware purchases. Stakeholders must monitor how utility tariff restructuring and carbon pricing mechanisms alter the business case for destination charging versus fleet-dedicated hubs.
Market Dynamics
DC fast-charging hardware is collapsing the capital-efficiency advantage that AC installations held for fleet operators, forcing a wholesale reconfiguration of deployment economics across Oman's commercial charging infrastructure.
Growth Catalysts
- National EV Strategy:Oman's Authority for Electricity Regulation mandates pre-wired charging readiness in new commercial developments, expanding addressable infrastructure volume without immediate hardware procurement.
- Fleet electrification commitments:Logistics operators and public transport agencies are accelerating depot charging installations to align with government emission reduction timelines.
- Utility tariff restructuring:Demand-response rate designs enable charging station operators to monetize grid services beyond energy sales, improving project returns.
Market Restraints
- Grid interconnection bottlenecks:Rural transmission capacity constraints outside Muscat and Salalah corridors limit high-power installation feasibility.
- Copper and silicon carbide supply concentration:Power electronics component sourcing depends on concentrated Asian manufacturing, exposing capex timelines to input volatility.
- Building code enforcement gaps:Pre-wiring mandates lack consistent inspection protocols across Oman's governorates, creating compliance uncertainty.
Strategic Opportunities
- Dhofar and Al Batinah corridor development:Highway-adjacent land in underpenetrated southern and coastal regions offers first-mover positioning for corridor fast-charging networks.
- Vehicle-to-grid integration:Bidirectional charging capability convergence with battery storage systems creates new revenue streams from frequency regulation services.
- Workplace destination charging:Corporate sustainability programs are funding Level 2 installations at employment clusters, bypassing public infrastructure capex constraints.
Industry Challenges
- Power electronics engineering scarcity:Specialized talent for high-voltage converter design and thermal management remains concentrated in European and East Asian labor markets.
- Multi-vendor interoperability certification:Oman's adoption of combined CCS and CHAdeMO standards requires complex testing protocols that extend commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oman EV Charging Station Market |
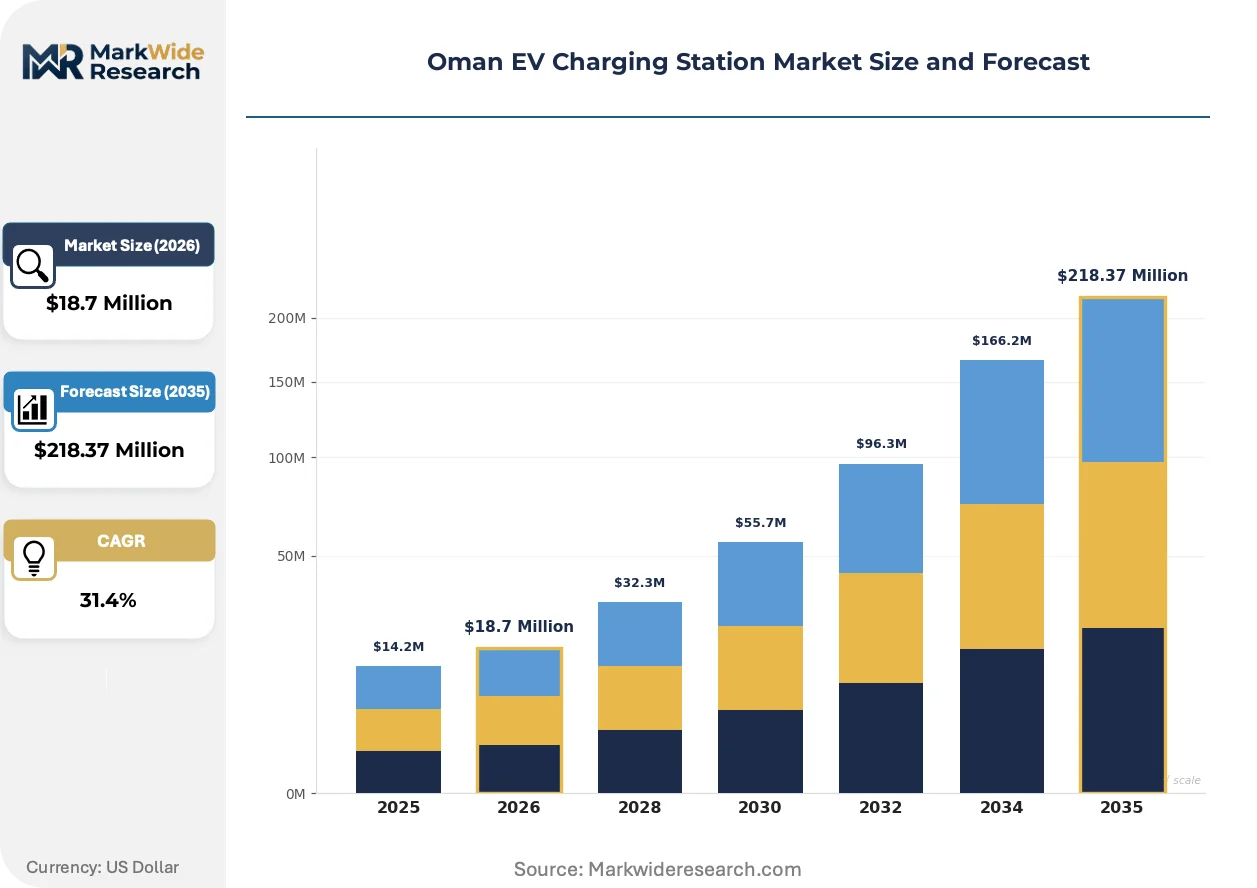
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $218.37 Million |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Charger, DC Fast Charger, Wireless Charger, Portable Charger End User: Residential, Commercial, Government, Fleet Operators Installation Type: On-Street, Off-Street, Private Property, Destination Charging Connectivity: Smart Charging, Basic Charging, Networked Charging, Open Standards |
| Companies Covered | Electric Vehicles One LLC, CITA group, Legend Green Energy Solutions LLC, OOMCO, Siemens, ABB, Schneider Electric, Shell Charge Solutions, ZEROVA Technologies Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oman EV Charging Station Market Trends and Innovations
Hardware commoditization is compressing equipment margins while software-defined energy management becomes the primary value capture mechanism for charging network operators.
Modular power electronics architectures are fragmenting the traditional integrated charger supply chain. These systems separate power conversion from dispenser interfaces, enabling field-upgradeable capacity scaling. Fleet operators in Sohar and Nizwa industrial zones are adopting this approach to match infrastructure investment to vehicle deployment phases. The technology is fragmenting vendor lock-in patterns that previously tied operators to single manufacturers for decade-long asset lifecycles.
Oman's Authority for Electricity Regulation is implementing interconnection standards derived from IEC 61851 and ISO 15118 protocols. These frameworks mandate plug-and-charge authentication and secure communication between vehicles and infrastructure. Commercial operators must now integrate cybersecurity compliance into hardware procurement specifications, affecting vendor selection criteria for new Muscat metropolitan deployments.
Facility managers are unbundling charging infrastructure from building energy contracts, negotiating direct utility interconnection for large-scale installations. This pattern displaces the traditional landlord-tenant model where property owners controlled electrical capacity allocation. The shift is most visible in new commercial developments across Seeb and Al Khuwair, where pre-wired readiness enables independent metered service arrangements.
Oman EV Charging Station Market Segmentation
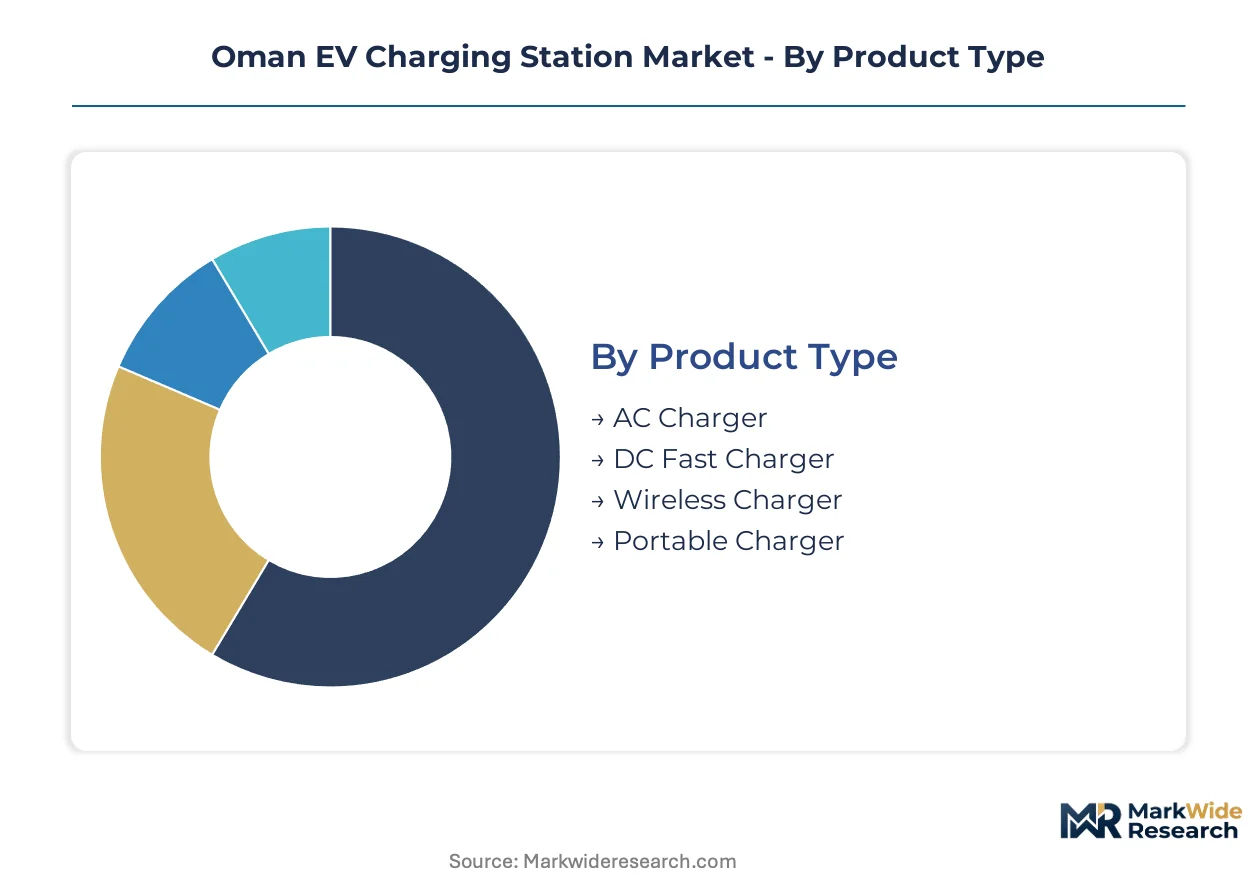
Segmentation in Oman's EV charging market reveals how regulatory mandates, utility tariff structures, and fleet operator procurement patterns create distinct investment profiles across hardware categories and deployment models. Understanding these divides enables stakeholders to align capital allocation with actual revenue concentration zones rather than assumed technology trajectories.
Product Type:
Oman's Authority for Electricity Regulation distinguishes charging infrastructure by power delivery architecture, with interconnection standards and grid impact assessments varying substantially across AC and DC systems.
- AC Charger:These units deliver alternating current at 3.7-22 kW through onboard vehicle rectifiers, making them cost-effective for residential garages and workplace installations with extended dwell times. Demand concentrates in Muscat's new commercial developments where pre-wiring mandates create immediate addressable volume without requiring high-power grid upgrades. Building code enforcement gaps across governorates slow deployment outside the capital corridor.
- DC Fast Charger:Direct current dispensers bypass onboard conversion, delivering 50-350 kW for sub-30-minute charging cycles essential for highway corridors and fleet depot operations. Fleet operators in Sohar and Nizwa industrial zones are prioritizing these installations to match government emission reduction timelines, though rural transmission capacity constraints limit feasibility in Dhofar's interior.
- Wireless Charger:Inductive pad systems transfer power across air gaps at 3-11 kW, eliminating connector wear in high-frequency fleet applications.
- Portable Charger:Mobile cable-and-adapter units provide emergency backup charging for residential users lacking fixed infrastructure.
Established volume favors AC Charger; emerging adoption favors DC Fast Charger.
End User:
Customer archetypes in Oman diverge sharply by procurement authority, with government entities and fleet operators commanding multi-station deployments while residential users drive unit economics through distributed scale.
- Residential:Single-family homeowners and apartment dwellers purchase Level 1-2 units for overnight charging, typically funding installations through personal capital rather than financing structures. Muscat metropolitan demand outpaces supply as pre-wired readiness in new developments outstrips actual hardware procurement, creating a lagged revenue recognition pattern for equipment vendors.
- Commercial:Retail, hospitality, and office property owners deploy destination charging to capture dwell-time revenue and sustainability credentials. Seeb and Al Khuwair developments are unbundling charging from building energy contracts, enabling direct utility interconnection that improves project returns through demand-response rate participation.
- Government:Municipal and ministry procurement drives public network expansion along highway corridors and municipal facilities.
- Fleet Operators:Logistics and public transport agencies electrify depot operations with dedicated high-capacity installations.
Procurement scale concentrates with Fleet Operators; installation velocity runs through Commercial.
Installation Type:
Physical deployment configurations determine grid interconnection complexity, with on-street installations requiring municipal coordination while private property arrangements bypass public right-of-way permitting.
- On-Street:Curbside dispensers integrated into urban infrastructure serve vehicles without dedicated parking, demanding coordination with Muscat Municipality for electrical trenching and metered service arrangements. These installations face extended commissioning timelines due to multi-vendor interoperability certification requirements under combined CCS and CHAdeMO standards.
- Off-Street:Parking garage and lot deployments offer simplified permitting through private landowner agreements, with capacity scaling matched to actual utilization patterns. Al Batinah coastal corridor developers are securing highway-adjacent land for first-mover positioning in underpenetrated regions.
- Private Property:Residential and corporate campus installations operate outside public network licensing requirements.
- Destination Charging:Hotel, retail, and entertainment venue deployments leverage extended visitor dwell times for slower charging economics.
Permitting efficiency favors Off-Street; network accessibility expansion depends on On-Street.
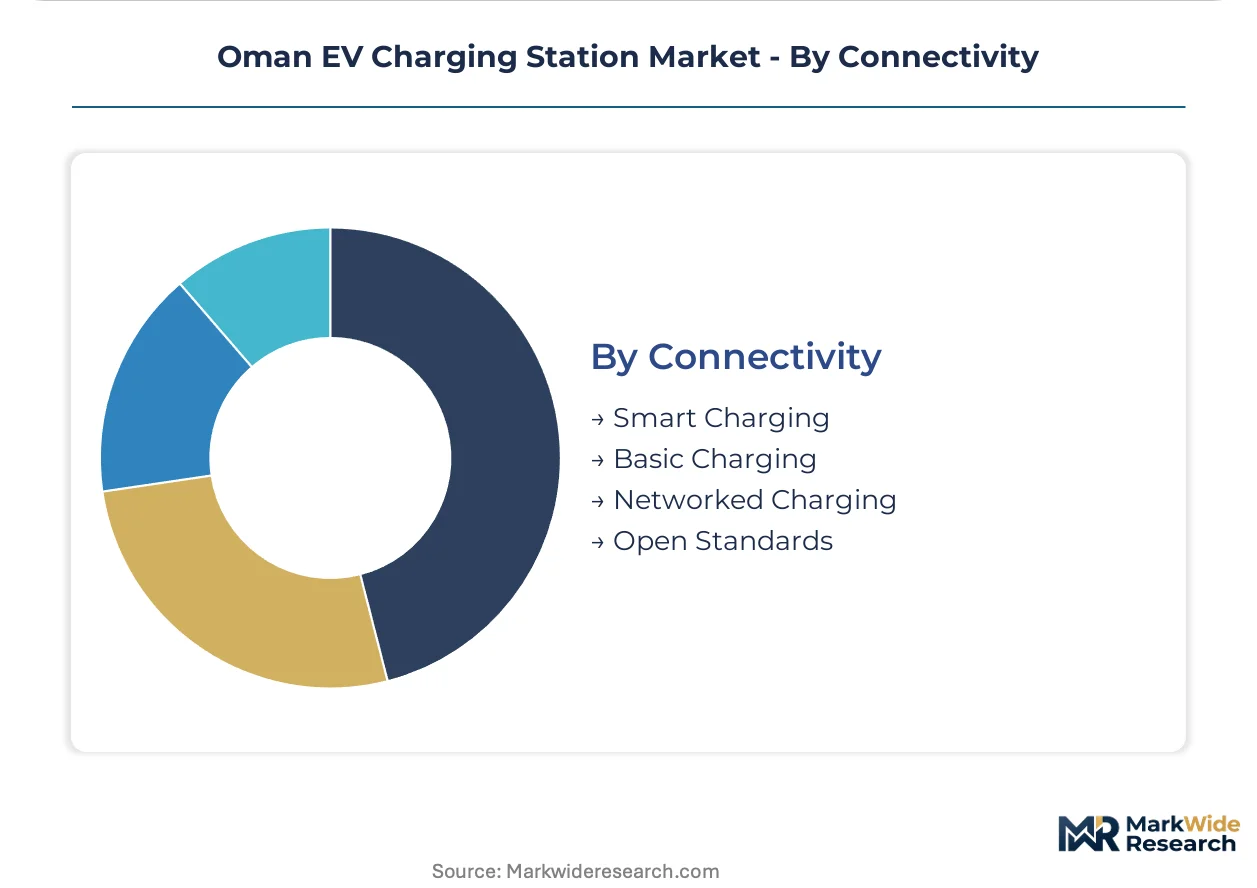
Connectivity:
Communication architecture tiers separate basic hardware from software-enabled revenue streams, with Oman's IEC 61851 and ISO 15118 protocol mandates creating compliance-based market segmentation.
- Smart Charging:Bidirectional communication enables load balancing, time-of-use optimization, and grid-interactive demand response, commanding recurring service revenue beyond equipment margins. Commercial operators in Muscat metropolitan deployments must now integrate cybersecurity compliance into procurement specifications, affecting vendor selection criteria and extending sales cycles.
- Basic Charging:Unconnected dispensers provide power delivery without remote monitoring or dynamic pricing capabilities, occupying the lowest hardware cost tier.
- Networked Charging:Cloud-connected systems enable centralized fleet management and payment processing without full grid-interactive functionality.
- Open Standards:Protocol-agnostic interoperability ensures multi-vendor compatibility and reduces long-term vendor lock-in risk.
Margin capture concentrates in Smart Charging; hardware commoditization pressures Basic Charging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates in Oman's northern corridor where transmission infrastructure and commercial density intersect. The Authority for Electricity Regulation's pre-wiring mandates create deployment asymmetry between governorates.
Muscat Governorate
Corporate sustainability programs and new commercial developments drive workplace charging installations across Seeb and Al Khuwair. The Authority for Electricity Regulation mandates pre-wired charging readiness in all new commercial buildings. Grid interconnection for large-scale installations is unbundling from building energy contracts, enabling independent metered service arrangements.
Al Batinah North and South
Highway corridor developers secure land for fast-charging networks connecting Muscat to the UAE border. The Ministry of Transport prioritizes this coastal route for public charging expansion. Sohar's industrial zone hosts fleet depot electrification projects aligned with government emission timelines.
Dhofar Governorate
Salalah's port logistics and tourism infrastructure create concentrated demand for destination charging. Rural transmission constraints limit high-power installation feasibility in interior regions. Coastal highway-adjacent land offers first-mover positioning for corridor network completion.
Ad Dakhiliyah Governorate
Nizwa's industrial zone attracts fleet operators adopting modular power electronics for phased infrastructure investment. The governorate's building code enforcement gaps slow pre-wiring compliance relative to Muscat. Commercial developments here lag metropolitan readiness mandates by 18-24 months.
Ash Sharqiyah North
Sur's maritime and fishing industry clusters generate niche commercial vehicle electrification demand. Grid capacity outside the coastal strip remains insufficient for DC fast-charging deployment. Local authorities coordinate with the Authority for Electricity Regulation on interconnection standards for harbor-adjacent installations.
Oman EV Charging Station Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Oman's charging infrastructure market. The vendor base spans integrated industrial conglomerates, specialized power electronics firms, and energy majors diversifying into mobility services. Three strategic archetypes dominate: utility-scale grid integrators, modular hardware specialists, and software-defined energy managers. Competitive moves center on utility partnership structures and corridor land pre-positioning rather than direct price competition.
Among European-based industrial groups, Siemens and ABB occupy positions anchored in power systems expertise, while Schneider Electric exemplifies the software-centric archetype. These three represent divergent approaches to the same regulatory environment shaped by IEC 61851 and ISO 15118 protocol mandates. Local entities including Electric Vehicles One LLC and Legend Green Energy Solutions LLC sit within the regional deployment specialist tier, concentrating on site acquisition and permitting velocity rather than hardware manufacturing.
| Leading Market Players |
|---|
| Electric Vehicles One LLC |
| CITA group |
| Legend Green Energy Solutions LLC |
| OOMCO |
| Siemens |
| ABB |
| Schneider Electric |
| Shell Charge Solutions |
| ZEROVA Technologies Inc. |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Asian power electronics foundries anchors both supply concentration and price floors for Oman's charging infrastructure procurement. Fleet operators and commercial developers face divergent cost structures as hardware commoditization compresses equipment margins while software-enabled service tiers command recurring revenue premiums.
Pricing Analysis
Oman's Authority for Electricity Regulation mandates pre-wiring readiness standards that dictate the pricing tier structure across deployment categories. Three-tier pricing structure across premium, standard, and economy levels separates DC fast-charging systems with grid-interactive controls from basic AC units and unconnected dispensers. Cost compression in standard-tier hardware is intensifying because modular power electronics architectures fragment vendor lock-in patterns. Fleet operators exhibit the highest price sensitivity due to multi-station procurement scale, while corporate sustainability programs funding workplace charging show lowest sensitivity to upfront capital outlays.
Supply Chain Analysis
Inventory lead times for silicon carbide MOSFETs and high-voltage capacitors extend procurement cycles for Oman's charging station deployments. Manufacturing concentration in China, South Korea, and Taiwan feeds power conversion modules and dispenser assemblies to regional integrators. Copper winding supply from Chile and transformer core materials from India create multi-source dependencies vulnerable to commodity price volatility. Distribution runs through authorized industrial distributors rather than direct OEM relationships, with local entities like Electric Vehicles One LLC and Legend Green Energy Solutions LLC managing site logistics and commissioning coordination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oman's EV charging infrastructure represents a substitution defense against hydrogen fuel cell corridor networks and battery swapping systems for commercial fleets. Incumbents must navigate technology transition risk while locking in utility partnership structures that emerging alternatives cannot replicate.
For Market Incumbents: Compound grid integration expertise through utility-scale demand-response rate participation that hydrogen infrastructure cannot match. Secure corridor land positions in Dhofar and Al Batinah before battery swapping operators establish depot-scale alternatives. Deepen backward integration into power electronics assembly to offset silicon carbide supply volatility from concentrated Asian sources. For New Entrants and Emerging Players: Cybersecurity compliance gaps in ISO 15118 protocol implementation create white-space for specialized software vendors serving Muscat metropolitan deployments. Target fleet depot electrification in Nizwa and Sohar industrial zones where modular hardware architectures enable phased investment matching vehicle deployment timelines. Pursue direct utility interconnection arrangements that bypass traditional landlord-tenant energy contract structures. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors software-defined energy managers over pure-play hardware manufacturers across the analysis window. Long-term viability rests on recurring service revenue capture rather than equipment margin extraction. Monitor utility tariff restructuring announcements as the primary inflection indicator for destination charging versus fleet-dedicated hub investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Utility Partnership Structuring | Demand-response rate designs with Oman's Authority for Electricity Regulation enable grid services monetization beyond energy sales. |
| Corridor Land Pre-Positioning | Highway-adjacent acquisitions in Dhofar and Al Batinah secure first-mover positioning for fast-charging network completion. |
| Modular Hardware Architecture | Field-upgradeable power electronics match infrastructure investment to fleet vehicle deployment phases in Sohar industrial zones. |
| Cybersecurity Compliance Integration | IEC 61851 and ISO 15118 protocol mandates extend sales cycles while creating vendor selection barriers for new entrants. |
| Direct Utility Interconnection | Independent metered service arrangements in Seeb and Al Khuwair unbundle charging from building energy contracts. |
Research Methodology
Desk research of regulatory filings, utility tariff schedules, and industrial procurement databases preceded structured interviews with fleet operations directors, commercial property developers, power electronics procurement managers, and Authority for Electricity Regulation officials. Primary fieldwork validated deployment timelines and interconnection bottlenecks across Muscat, Sohar, Nizwa, and Salalah corridors. Secondary sources included Oman's national EV strategy documents, Ministry of Transport corridor development plans, and IEC protocol implementation guidelines. Bottom-up installation forecasts triangulated against top-down infrastructure investment commitments from government and utility partners.
Variance decomposition across product type, end user, installation configuration, and connectivity tier informed the analytical framework over the projection horizon. CAGRs derived from segment-level adoption curves weighted by fleet electrification commitments and commercial development pipelines. Modeling incorporated grid interconnection capacity constraints, copper and silicon carbide supply lead times, and building code enforcement velocity across governorates as industry-specific forecast inputs.
Forecasts assume regulatory continuity in Oman's national EV strategy and Authority for Electricity Regulation interconnection standards; material policy shifts would require re-modeling deployment timelines and revenue recognition patterns. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Electric Vehicle AC Charging Pile Market
Electric Vehicle Charging
Electric Vehicle Charging Facilities Market
Electric Vehicle Charging
Electric Vehicle (EV) Public Charging Station Market
Electric Vehicle Charging
Integrated EV Chargers Market
Electric Vehicle Charging
DC Chargers Market
Electric Vehicle Charging
Public EV Charging Pile Market
Electric Vehicle Charging
Netherlands Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle Public Charging Pile Market
Electric Vehicle Charging
Thermal Conductive Polymer Material for Electric Vehicles Market
Electric Vehicle Charging
Global Electric Vehicle (EV) Charging Service Market
Electric Vehicle Charging
Europe Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
Western Europe Electric Vehicle (EV) Charging Equipment Market
Electric Vehicle Charging
US Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Electric Vehicle Rapid Charger Market
Electric Vehicle Charging
Smart EV Charger Market
Electric Vehicle Charging
E-Bike Charging Station Market