
 South Korea Electric Vehicle Charging Equipment Market | 2026-2036
South Korea Electric Vehicle Charging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Electric Vehicle Charging Equipment Market Insights
Aftermarket service revenue is fragmenting across South Korea's charging equipment landscape as hardware commoditization pushes margin pools toward software and maintenance contracts. SK Signet leverages its domestic manufacturing scale to anchor high-volume DC fast charger production for highway corridor networks. Hyundai KEFICO sustains vertical integration advantages through captive supply relationships within the Hyundai Motor Group ecosystem. Chaevi competes on platform licensing, extending its charging network management software to third-party operators seeking turnkey deployment capabilities.
South Korea electric vehicle charging equipment encompasses power conversion systems, connector assemblies, and communication modules engineered to deliver controlled electrical energy from grid infrastructure to battery electric vehicles, with DC fast chargers typically operating at outputs exceeding 50 kW using liquid-cooled cable assemblies to manage thermal loads during sustained high-current sessions. The primary commercial purpose centers on reducing vehicle downtime through rapid energy replenishment while enabling grid-stabilizing bidirectional power flows. AC charger deployments dominate residential and workplace installations where dwell times accommodate slower overnight or daytime charging cycles. DC fast charger infrastructure leads capital allocation along expressway corridors and urban commercial hubs where throughput velocity determines station economics. Wireless charger adoption remains nascent but occupies strategic positioning for autonomous vehicle readiness and premium fleet automation applications.
MFDS electrical safety certifications, KTL performance standards, and Ministry of Environment subsidy eligibility criteria collectively shape product design requirements and market access conditions for equipment vendors serving South Korean buyers. The Korea Energy Agency's demand response protocols and KEPCO time-of-use tariff structures further influence charging station control software architecture and site selection economics. Stakeholders must monitor regulatory trajectory around V2G grid interconnection standards and dynamic electricity pricing mechanisms to align product roadmaps with evolving network operator requirements.
Market Dynamics
Hardware commoditization across South Korea's charging equipment sector is compressing manufacturer margins and redirecting competitive advantage toward software-defined energy management platforms and long-term service contracts. This structural shift is forcing incumbent suppliers to reconfigure their revenue models around recurring maintenance streams rather than upfront equipment sales.
Growth Catalysts
- Ministry of Environment subsidy programs:Direct capital grants for DC fast charger deployment along expressway corridors reduce payback periods for private operators and accelerate network density targets in the capital region.
- Hyundai Motor Group fleet electrification:Captive demand from affiliated logistics and ride-hailing subsidiaries creates guaranteed offtake for high-power depot charging infrastructure in metropolitan hubs.
- K-Charger standardization mandates:Unified connector and communication protocols eliminate interoperability friction, lowering deployment costs for multi-brand charging networks serving heterogeneous vehicle fleets.
Market Restraints
- Power electronics import concentration:IGBT modules and high-frequency transformers sourced primarily from Chinese and Taiwanese suppliers expose domestic assemblers to shipping cost volatility and geopolitical supply interruptions.
- Grid connection queue delays:KEPCO substation upgrade timelines frequently extend 18-24 months for high-capacity DC installations, freezing site development schedules in dense urban districts.
- Silicon carbide MOSFET scarcity:Next-generation power semiconductor shortages constrain 350 kW ultra-fast charger production ramps, capping output for premium highway corridor equipment.
Strategic Opportunities
- Busan-Ulsan industrial corridor underpenetration:Heavy manufacturing zones in Gyeongsang province currently lack sufficient high-power charging density to support electrified freight corridors connecting port facilities to inland distribution centers.
- V2G bidirectional integration:Korea Energy Agency demand response protocols enable fleet operators to monetize stationary vehicle batteries as grid stabilization assets during peak load events.
- Wireless inductive charging pilots:Autonomous shuttle routes in Sejong City and Songdo present testbed environments for dynamic charging infrastructure eliminating plug-in dwell time constraints.
Industry Challenges
- MFDS electrical safety certification timelines:Multi-stage testing protocols for liquid-cooled cable assemblies and enclosure ingress protection ratings extend product launch cycles by 8-12 months.
- Power systems engineering talent scarcity:Shortages of specialists combining grid interconnection expertise with embedded software development constrain OEM in-house R&D expansion and service team scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Electric Vehicle Charging Equipment Market |
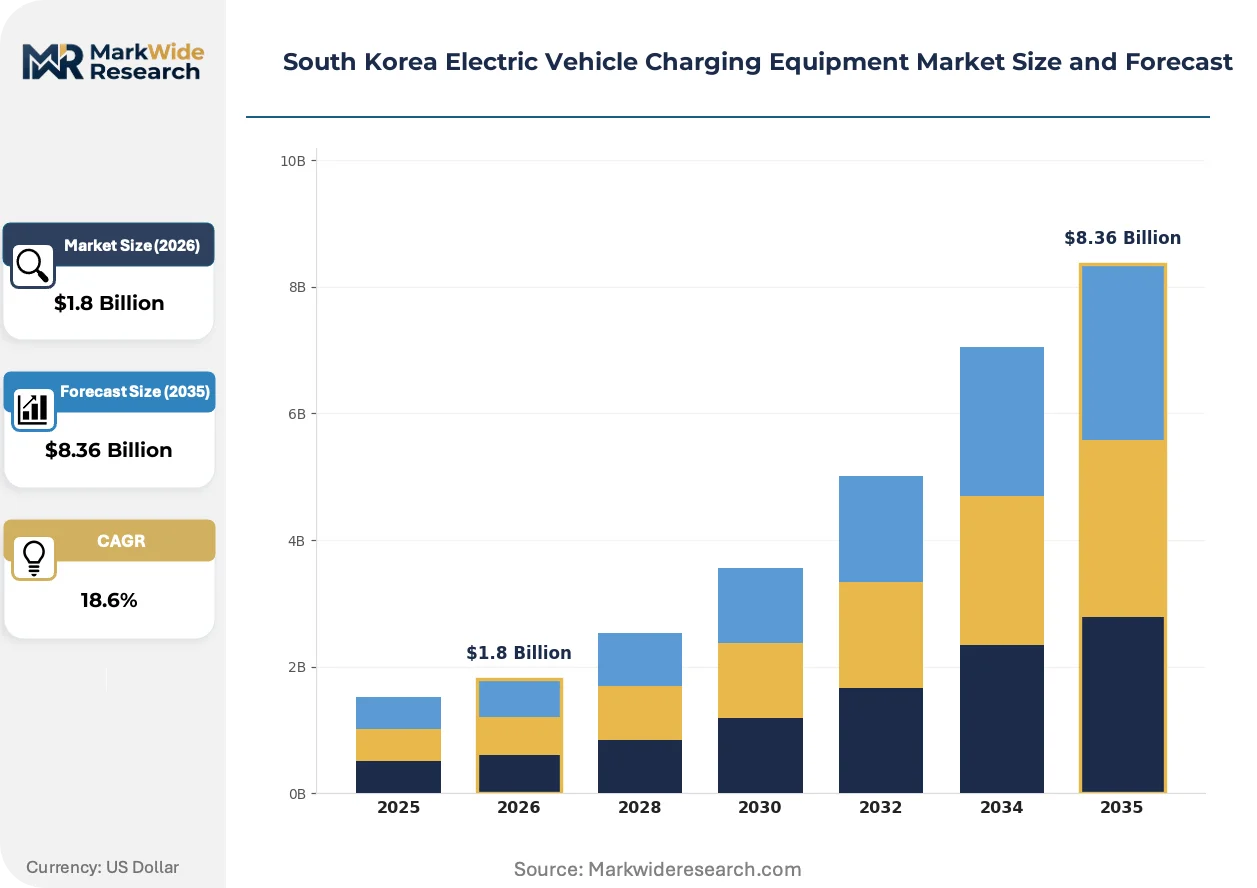
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Charger, DC Fast Charger, Wireless Charger, Portable Charger Installation Type: Residential, Commercial, Fleet, Public Power Output: Level 1, Level 2, Level 3, Ultra-Fast Connectivity: Wi-Fi, Ethernet, Cellular, Bluetooth |
| Companies Covered | SK Signet, Hyundai KEFICO, Chaevi, Evar Corp, PowerCubeKorea, Delta Electronics, ABB, Tesla, Schneider Electric, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Electric Vehicle Charging Equipment Market Trends and Innovations
Power electronics architecture is converging with cloud-native control systems, enabling remote diagnostics and predictive maintenance capabilities that reshape how charging networks are operated and monetized across South Korean metropolitan clusters.
Silicon carbide power conversion technology is hybridizing traditional IGBT-based rectifier designs with wide-bandgap semiconductor topologies that cut thermal losses by half. Tier-1 suppliers serving Seoul's highway corridor operators are adopting these hybrid configurations for 150-350 kW output classes. The resulting efficiency gains are compressing cooling system footprints and enabling higher station density within constrained urban real estate.
K-Charger Phase 2.0 interoperability mandates issued by the Ministry of Environment now require open payment protocols and standardized data exchange formats across all publicly subsidized installations. Equipment vendors must reflash existing controller firmware to comply with authentication and settlement specifications. Highway rest area operators and municipal parking authorities face the steepest compliance costs as they retrofit legacy units installed during earlier subsidy cycles.
Fleet procurement patterns are consolidating around energy-as-a-service contracts that bundle hardware, installation, electricity, and maintenance into per-kilometer pricing structures. Third-party logistics operators and municipal bus agencies in Gyeonggi province are displacing capital purchase models with these operational expenditure arrangements. The shift is most pronounced among mid-sized fleet operators lacking dedicated energy management capabilities or grid interconnection expertise.
South Korea Electric Vehicle Charging Equipment Market Segmentation
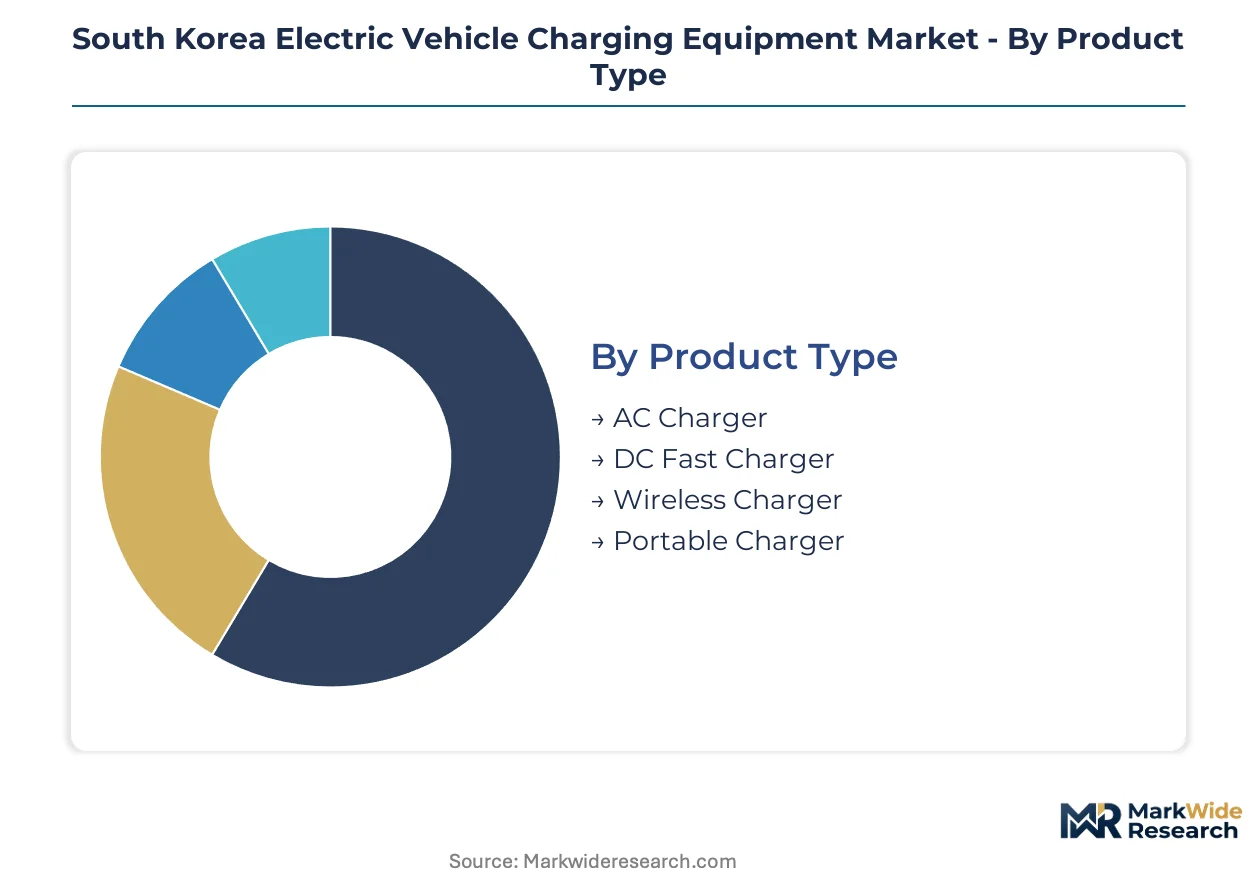
Charging equipment segmentation in South Korea reflects divergent infrastructure economics across metropolitan corridor networks and industrial depot clusters. Equipment specifications align with K-Charger standardization mandates while varying sharply between highway throughput stations and overnight residential installations.
Product Type:
Use-case spectrum spans overnight residential replenishment through highway corridor rapid turnaround and autonomous vehicle readiness pilots.
- AC Charger:Single-phase and three-phase alternating current units operating at 7-22 kW dominate apartment complex parking structures and workplace installations where dwell times accommodate 4-8 hour charging cycles. Demand concentrates in Seoul's dense residential districts where grid connection limitations favor lower-power infrastructure and MFDS electrical safety certifications prioritize enclosure ingress protection for semi-outdoor deployments.
- DC Fast Charger:Direct current rectifier systems delivering 50-350 kW through liquid-cooled cable assemblies anchor expressway rest area economics and metropolitan commercial hub throughput. Highway corridor operators in the capital region prioritize these installations where station utilization rates determine payback periods under Ministry of Environment subsidy programs.
- Wireless Charger:Inductive power transfer systems operating through magnetic resonance coupling occupy pilot deployment status in Sejong City autonomous shuttle routes.
- Portable Charger:Mobile emergency units with onboard battery storage serve roadside assistance fleets and rural coverage gaps in Gangwon province mountain corridors.
Established volume favors AC Charger; emerging adoption favors DC Fast Charger.
Installation Type:
Cost tier stratification separates capital-intensive depot infrastructure from subsidized public networks and consumer-funded residential units.
- Residential:Wall-mounted or pedestal units installed in single-family homes and apartment designated parking spaces, typically AC-based with smart metering integration for KEPCO time-of-use tariff optimization. Gyeonggi province multi-unit housing complexes drive volume through mandatory EV-ready parking regulations.
- Commercial:Retail and workplace installations serving customer and employee dwell periods, mixing AC and lower-power DC configurations. Busan shopping district operators favor these for customer retention metrics alongside parking revenue.
- Fleet:High-power depot systems serving logistics, ride-hailing, and municipal bus operators with guaranteed offtake and centralized energy management. Hyundai Motor Group captive demand anchors this segment through affiliated logistics subsidiary electrification mandates.
- Public:Government-subsidized highway and urban corridor installations requiring open payment protocol compliance under K-Charger Phase 2.0 mandates.
Procurement scale concentrates in Fleet; subsidy dependence shapes Public economics.
Power Output:
Application urgency determines power tier selection across passenger vehicle, commercial freight, and emergency service duty cycles.
- Level 1:120V single-phase residential outlets delivering under 2 kW serve legacy apartment buildings lacking dedicated EV infrastructure and emergency backup charging scenarios.
- Level 2:240V residential and commercial installations at 7-19 kW represent the volume baseline for workplace and overnight charging where silicon carbide MOSFET scarcity has minimal impact.
- Level 3:50-150 kW DC fast charging enables 30-60 minute replenishment for intercity travel and commercial fleet mid-route recovery.
- Ultra-Fast:150-350 kW liquid-cooled systems target premium passenger segments and heavy-duty freight corridors where thermal management engineering commands supplier differentiation.
Technology maturity favors Level 2; infrastructure investment flows toward Ultra-Fast.
Connectivity:
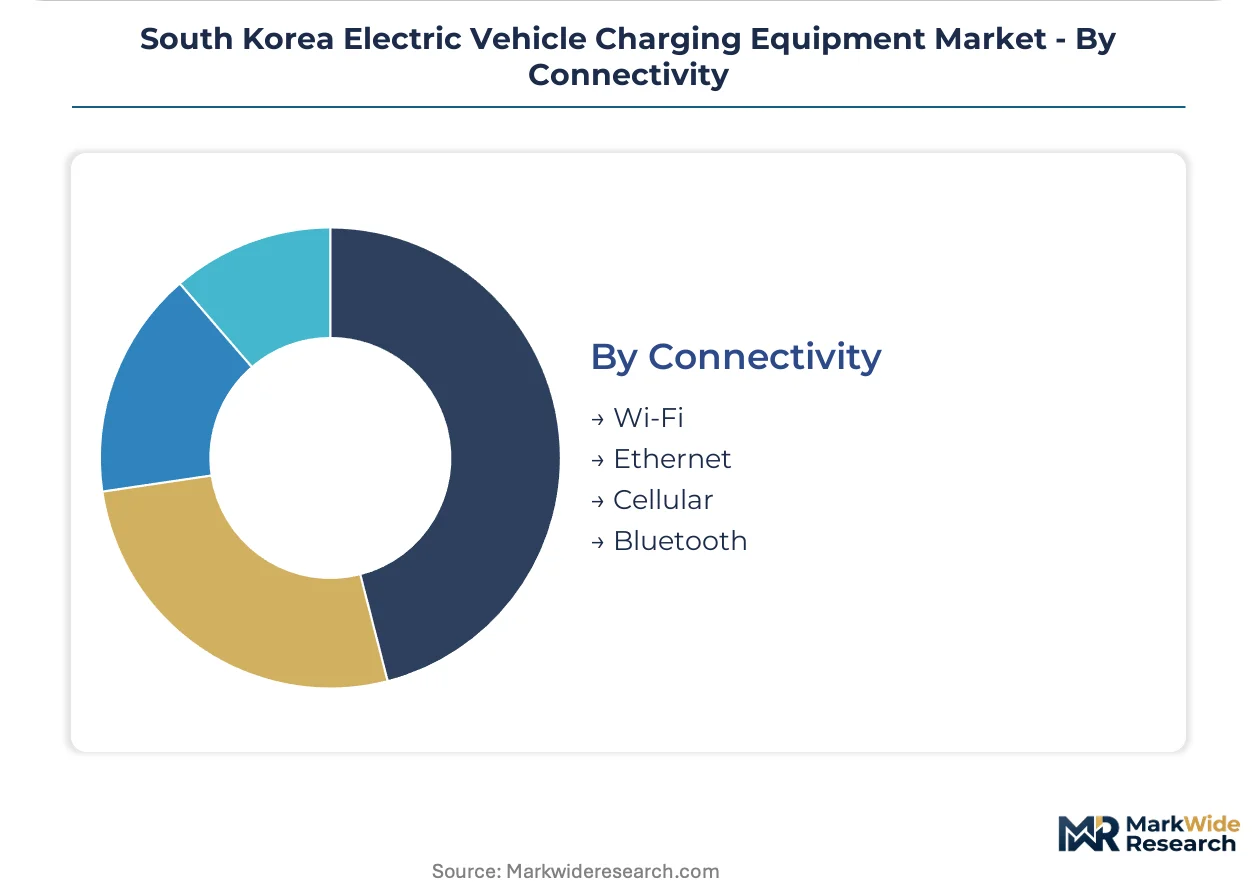
Data transmission reliability requirements vary across centralized fleet management, consumer payment authentication, and remote diagnostic platforms.
- Wi-Fi:Short-range wireless protocol dominant in residential and workplace installations with reliable local network infrastructure, enabling smartphone app integration for charging session scheduling.
- Ethernet:Wired connectivity securing high-bandwidth data exchange for fleet depot management systems and highway corridor payment processing where cybersecurity compliance is paramount.
- Cellular:4G and emerging 5G modules enabling standalone public station operation without local network dependency, critical for remote highway rest area deployments.
- Bluetooth:Proximity-based authentication and initial device pairing for consumer-facing installations.
Deployment flexibility favors Cellular; cost optimization drives Wi-Fi preference.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Seoul Capital Area exhibit lowest price elasticity for premium DC fast chargers, while Gwangju-Honam operators remain acutely sensitive to per-unit hardware costs. This demand-elasticity gradient shapes subsidy allocation and vendor pricing power across South Korean metropolitan corridors.
Seoul Capital Area
Hyundai Motor Group captive fleet demand and dense expressway corridor networks drive premium DC fast charger procurement. Ministry of Environment subsidies prioritize Gyeonggi province installations under K-Charger Phase 2.0 mandates. Incheon port electrification and Songdo smart city pilots anchor high-power depot infrastructure for logistics subsidiaries.
Busan-Ulsan
Heavy manufacturing zones and container port freight electrification create concentrated demand for 350 kW ultra-fast systems. Korea Energy Agency demand response protocols enable fleet operators to monetize V2G grid services during peak load events. Ulsan automotive industrial complex hosts captive charging networks serving Hyundai Motor Group manufacturing logistics.
Daegu-Gyeongbuk
Textile and electronics manufacturing clusters generate mid-tier AC and DC charger demand for employee parking and light commercial fleets. KEPCO grid connection queue delays extend 18-24 months for high-capacity installations, slowing site development. Daegu metropolitan government accelerates urban corridor deployment through municipal subsidy stacking with national programs.
Daejeon-Sejong
Administrative capital relocation and Sejong City autonomous shuttle pilots drive wireless inductive charging testbed investments. Korea Energy Agency smart grid integration mandates influence control software architecture for publicly subsidized stations. Daejeon research institutes anchor power electronics engineering talent pools for domestic OEM R&D expansion.
Gwangju-Honam
Agricultural logistics and dispersed population density sustain price-sensitive demand for lower-power AC infrastructure and portable emergency units. MFDS electrical safety certification timelines constrain product launch cycles for regional assemblers. Honam Expressway corridor operators prioritize cost-optimized 50 kW DC installations over premium ultra-fast systems.
South Korea Electric Vehicle Charging Equipment Market Competitive Landscape
Capability concentration sits with domestic power electronics specialists; scale advantage sits with conglomerate-affiliated manufacturers and multinational industrial equipment suppliers. The vendor base stratifies across three tiers: captive suppliers serving affiliated automotive groups, independent domestic champions leveraging K-Charger standardization, and multinational technology licensors. Dominant competitive moves include strategic partnerships for silicon carbide supply security and software platform licensing to third-party network operators.
Within the domestic specialist tier, SK Signet anchors high-volume DC fast charger production for highway corridor networks. Hyundai KEFICO occupies a position exemplifying captive supply integration within the Hyundai Motor Group ecosystem. Chaevi represents the platform licensing archetype, extending charging network management software capabilities to third-party operators seeking turnkey deployment solutions.
| Leading Market Players |
|---|
| SK Signet |
| Hyundai KEFICO |
| Chaevi |
| Evar Corp |
| PowerCubeKorea |
| Delta Electronics |
| ABB |
| Tesla |
| Schneider Electric |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese IGBT module fabrication is compressing margin structures for South Korean DC fast charger assemblers while simultaneously extending supplier payment terms to 90-120 days. This utilization dynamic forces domestic equipment vendors to absorb working capital strain or pass through cost reductions to fleet operators bidding on Ministry of Environment-subsidized corridor installations.
Pricing Analysis
After-sales service contracts and predictive maintenance subscriptions now generate lifetime value exceeding upfront hardware margins for established DC fast charger suppliers. Three-tier pricing structure across premium liquid-cooled systems, standard air-cooled units, and economy AC chargers reflects K-Charger certification tier and thermal management complexity. Cost compression in economy AC tiers is intensifying because apartment complex developers prioritize lowest capital expenditure for mandatory EV-ready parking mandates. Municipal bus agencies exhibit lowest price elasticity due to energy-as-a-service contract structures, while independent highway rest area operators remain acutely sensitive to per-kilowatt hardware costs.
Supply Chain Analysis
Extended payment terms from Taiwanese and Chinese power semiconductor suppliers are tightening working capital constraints for South Korean equipment assemblers competing on Ministry of Environment subsidy timelines. IGBT modules and silicon carbide MOSFETs draw from fabrication concentration in China, Taiwan, and Japan, while liquid-cooled cable assemblies source from specialized German and Italian connector specialists. Single-source vulnerability around 350 kW ultra-fast charger power stacks exposes domestic vendors to allocation priority shifts during automotive OEM demand surges. Distribution runs through Hyundai Motor Group captive procurement channels for affiliated fleet operators and open tender processes for municipal highway corridor deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
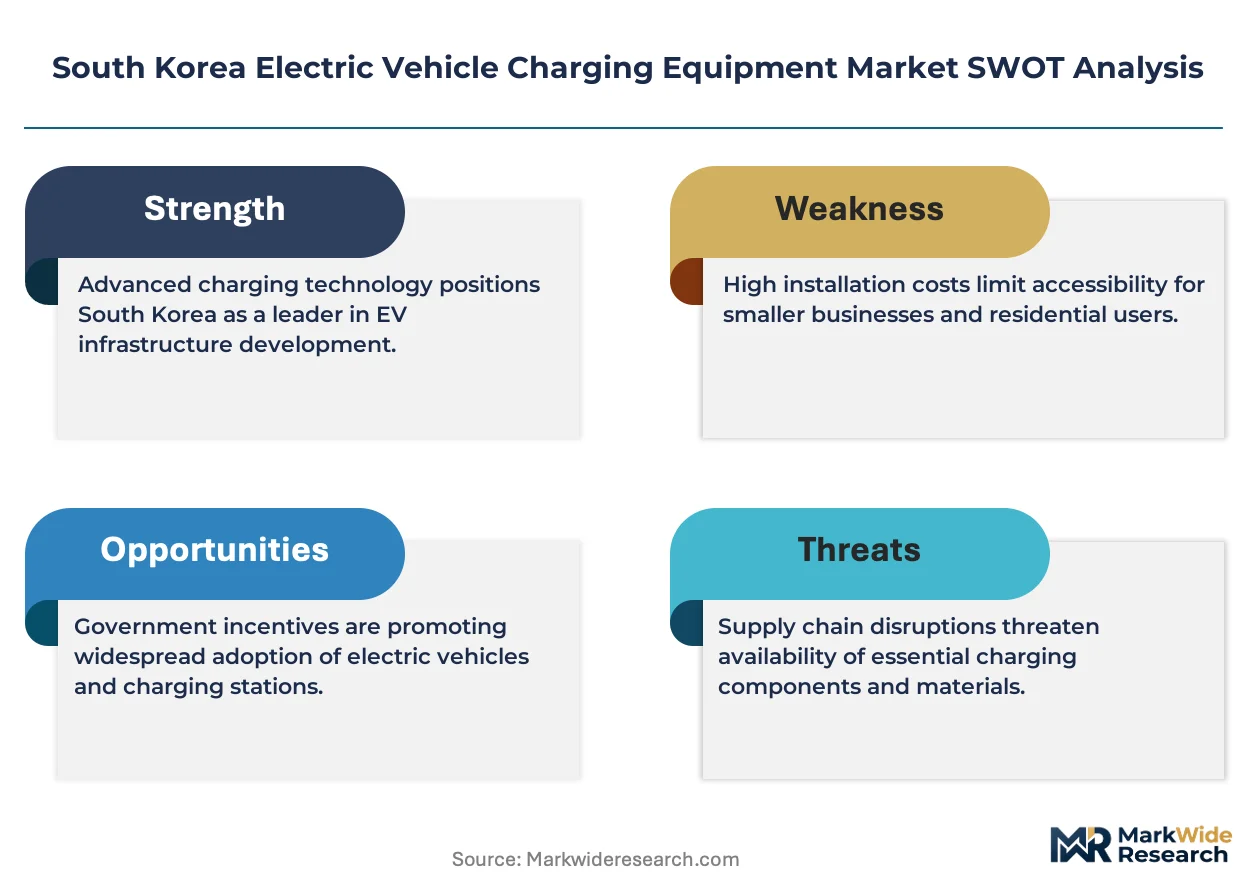
The South Korea electric vehicle charging equipment market rewards specialists who control power electronics engineering talent pools and K-Charger certification pathways, while generalist assemblers face margin erosion from hardware commoditization and import dependency.
For Market Incumbents: Pre-empt silicon carbide supply disruption by securing long-term offtake agreements with Japanese and Taiwanese foundries before automotive OEMs lock capacity for next-generation vehicle platforms. Anchor backward integration into liquid-cooled cable assembly production to defend margin structures against German connector specialists expanding direct sales to Korean fleet operators. Certification investment in MFDS electrical safety pre-approval testing capabilities will compress rival product launch cycles by 4-6 months. For New Entrants and Emerging Players: Pursue the Busan-Ulsan industrial corridor where heavy manufacturing electrification lacks sufficient 350 kW ultra-fast charging density for freight corridors connecting port facilities to inland distribution centers. Target municipal bus agencies in Gyeonggi province with energy-as-a-service contract proposals that bundle hardware, installation, and maintenance into per-kilometer operational expenditure structures. A software-first go-to-market angle emphasizing V2G grid integration and demand response monetization differentiates against incumbent hardware-centric positioning. For Investors and Strategic Acquirers: Capital is best deployed toward domestic power electronics specialists with captive K-Charger certification expertise and established KEPCO grid interconnection relationships rather than pure-play hardware assemblers exposed to Chinese import volatility. Long-term viability over the next decade hinges on software-defined energy management platform ownership and recurring service revenue streams displacing transactional equipment sales. Watch for Ministry of Environment announcements expanding V2G bidirectional subsidy eligibility as the inflection signal for grid services monetization potential.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Supply Security Partnership | Secures wide-bandgap semiconductor allocation ahead of automotive OEM demand surges from TSMC and Rohm. |
| K-Charger Phase 2.0 Compliance Reflash Program | Enables legacy highway corridor station retrofitting for open payment protocol mandates under Ministry of Environment timelines. |
| V2G Bidirectional Integration Development | Aligns product roadmaps with Korea Energy Agency demand response protocols for fleet grid services monetization. |
| Energy-as-a-Service Contract Structuring | Captures municipal bus agency procurement shifting from capital purchase to per-kilometer operational expenditure models. |
| Power Electronics Engineering Talent Acquisition | Addresses specialist scarcity constraining OEM in-house R&D expansion and service team scaling in Daejeon-Sejong clusters. |
Research Methodology
A spread of perspectives from DC fast charger procurement directors at fleet operators, power electronics engineering leads at domestic OEMs, KEPCO grid interconnection planners, and Ministry of Environment subsidy program administrators converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against Korea Energy Agency demand response filings, MFDS electrical safety certification databases, and KEPCO time-of-use tariff structure disclosures. Bottom-up equipment shipment tallies by power output tier and installation type triangulated against top-down Ministry of Environment subsidy allocation records.
Demand-supply balance modeling across the projection horizon incorporated fleet electrification mandates from Hyundai Motor Group affiliates, K-Charger standardization compliance timelines, and silicon carbide MOSFET availability constraints from Taiwanese foundry allocation patterns. Segmentation dimensions span product type, installation category, power output tier, and connectivity protocol. CAGRs were derived from unit economics modeling of station utilization rates under varying subsidy intensity scenarios, with expressway corridor throughput velocity and depot charging guaranteed offtake serving as primary forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese power electronics suppliers or accelerated V2G regulatory mandates would shift outcomes beyond modeled ranges. Macroeconomic deviation in electricity pricing, regulatory modification to subsidy eligibility criteria, or technological disruption in wireless inductive charging efficiency would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Electric Vehicle (EV) Charging Station Infrastructure Market
Electric Vehicle Charging
Asia-Pacific Portable EV Charger Market
Electric Vehicle Charging
Heavy-Duty Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Battery Liquid Cooling Plates for Electric Vehicle Market
Electric Vehicle Charging
Electric Vehicle 800-Volt Charging Pile Market
Electric Vehicle Charging
US Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
EV Charging System Test and Certification Equipment Market
Electric Vehicle Charging
Electric Vehicle Charging Management Software Market
Electric Vehicle Charging
EV Charging Station Market
Electric Vehicle Charging
Second Life Electric Vehicle Battery Market
Electric Vehicle Charging
Electric Vehicle Charger and Charging Station Market
Electric Vehicle Charging
AC Electric Vehicle Charging Station Market
Electric Vehicle Charging
Public EV Charging Pile Market
Electric Vehicle Charging
India Electric Vehicle Charging Station Market
Electric Vehicle Charging
Airport Charging Stations Market
Electric Vehicle Charging
Electric Vehicle Charging Facilities Market