
 DC Chargers Market | 2026-2036
DC Chargers Market Size, Share, and Industry Trends Forecast 2026-2036
DC Chargers Market Outlook
The EU Green Deal is restructuring the DC charger procurement landscape across European member states, mandating standardized payment interoperability and minimum power thresholds at public stations. ABB leverages its manufacturing scale to dominate high-power charging hardware for highway corridors. Tesla sustains proprietary network advantages through integrated vehicle-charger software architecture. Siemens AG anchors European grid integration projects, competing on bidirectional charging capabilities.
DC chargers convert alternating current from electrical grids into direct current suitable for electric vehicle battery packs, typically delivering outputs from 50 kW to over 350 kW through rectifier assemblies and liquid-cooled cable systems designed to minimize thermal losses during high-amperage transfer. Ultra-fast chargers command premium positioning as OEMs design 800-volt architectures requiring 150+ kW sustained delivery. Fleet chargers represent the fastest-expanding end-user category, with logistics operators prioritizing depot-based overnight replenishment over public infrastructure dependency. CCS technology leads connector standardization outside Asia, while GB/T retains dominance in China's domestic market.
The US Department of Transportation coordinates National Electric Vehicle Infrastructure formula funding with state-level public utility commission rate-case approvals, creating a dual-layer compliance environment for charging network operators. China's MIIT enforces GB/T protocol updates and grid interconnection standards that shape product development cycles for hardware manufacturers. Stakeholders must monitor evolving ISO 15118-20 plug-and-charge mandates and local grid capacity constraints as simultaneous fleet and consumer demand strains distribution infrastructure.
Market Dynamics
The 800-volt vehicle architecture transition is compressing charger power thresholds upward, forcing hardware manufacturers to abandon 50 kW designs and retool liquid-cooled cable assemblies for sustained 350 kW delivery cycles.
Growth Catalysts
- Fleet Electrification Mandates:The EU Green Deal's transport decarbonization targets compel logistics operators to electrify heavy-duty corridors. Germany's autobahn charging infrastructure receives federal priority funding, accelerating depot-based DC installation.
- GB/T Protocol Dominance:China's MIIT enforces updated grid interconnection standards that shape product development cycles for domestic hardware manufacturers serving the world's largest EV fleet.
- Battery Chemistry Evolution:Lithium iron phosphate and silicon-anode cell formulations now tolerate 4C charging rates without thermal degradation, validating 350 kW dispenser investments.
Market Restraints
- Copper and Rare Earth Volatility:Rectifier assemblies depend on copper busbars and neodymium-doped magnetic components. Price swings in these inputs compress hardware margins unpredictably.
- Grid Interconnection Queues:Distribution utility capacity constraints in dense urban centers delay commercial commissioning by 12-18 months regardless of equipment readiness.
- CCS-GB/T Fragmentation:Connector protocol bifurcation between European/North American CCS markets and China's GB/T ecosystem forces redundant SKU proliferation for multinational suppliers.
Strategic Opportunities
- Bidirectional Charging Integration:ISO 15118-20 plug-and-charge mandates enable vehicle-to-grid revenue streams. Fleet operators in California and Texas pilot peak-shaving arbitrage models.
- Depot-First Deployment Models:Underpenetrated commercial real estate segments—warehousing, last-mile distribution hubs—offer captive demand with predictable utilization curves absent public infrastructure risk.
- Renewable Coupling Requirements:The US IRA production tax credits incentivize solar-plus-storage co-location at charging sites, creating integrated energy service contracts.
Industry Challenges
- Power Electronics Talent Scarcity:Design of gallium nitride and silicon carbide inverter topologies requires specialized semiconductor physics expertise concentrated at a handful of research institutions.
- Multi-Protocol Certification Timelines:Simultaneous UL 2594, IEC 61851, and GB/T compliance testing extends product launch cycles by 8-14 months.
- Legacy Grid Infrastructure Compatibility:Rural distribution transformers installed in the 1970s-1980s lack capacity for 350 kW simultaneous draws, forcing expensive substation upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DC Chargers Market |
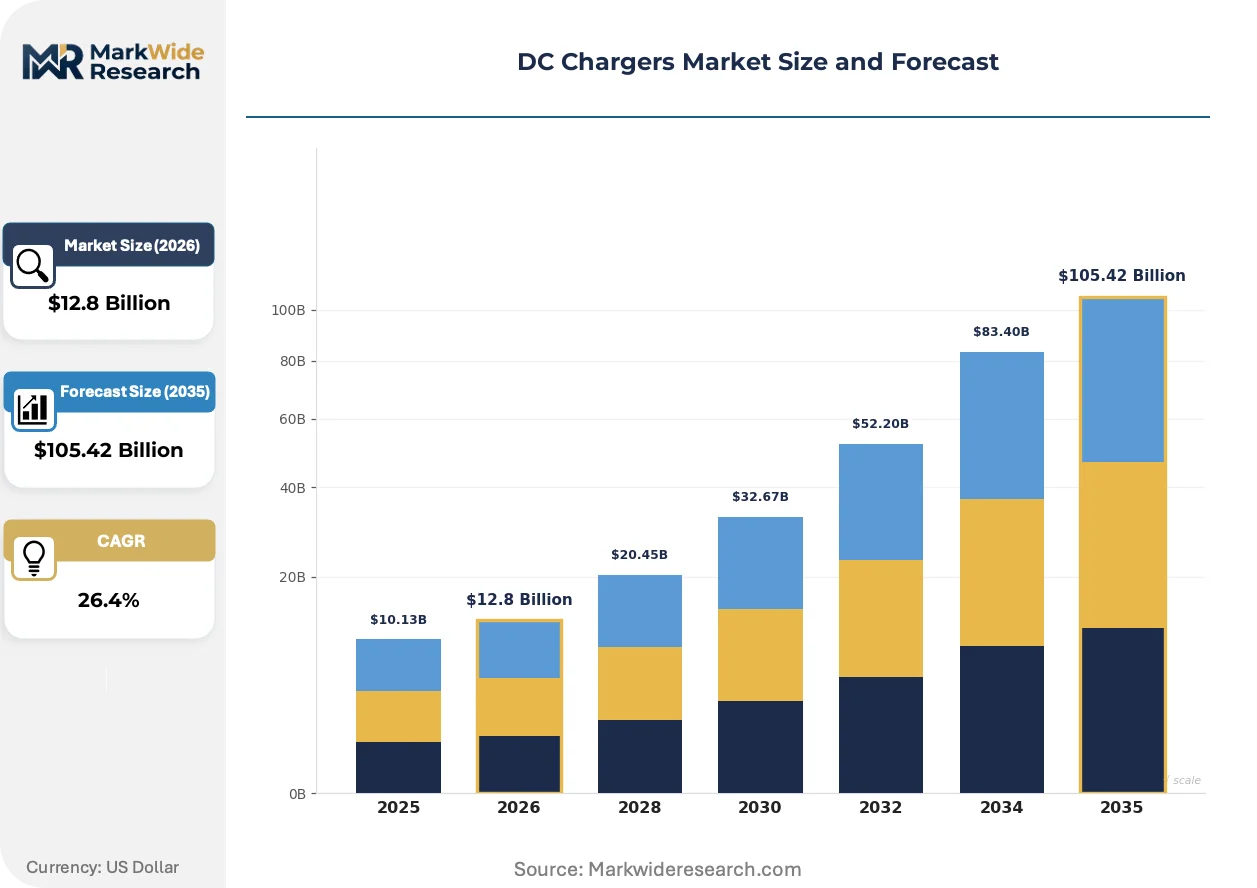
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $105.42 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted Chargers, Portable Chargers, Ultra-Fast Chargers, Fleet Chargers Technology: CHAdeMO, CCS, Tesla Supercharger, GB/T End User: Residential Users, Commercial Fleets, Charging Station Operators, Municipal Services Installation: Public Charging, Private Charging, On-Street Charging, Destination Charging |
| Companies Covered | ABB, Tesla, Siemens AG, ChargePoint, Delta Electronics, EVBox, Eaton Corporation, Alpitronic, Tritium, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DC Chargers Market Strategic Shifts
Solid-state power electronics and intelligent thermal management are converging to redefine charger power density benchmarks. These advances compress footprint requirements while extending operational lifespans under continuous-duty cycles.
Silicon carbide MOSFETs is electrifying rectifier efficiency curves, cutting switching losses by half compared to silicon IGBT predecessors. Tier-1 suppliers now specify SiC for all 150 kW-plus designs. This semiconductor transition enables compact 350 kW dispensers in standard parking bay footprints, eliminating the concrete pad expansions legacy installations required.
The EU Green Deal's Alternative Fuels Infrastructure Regulation mandates payment interoperability and minimum power thresholds at public stations. Member states must deploy 150 kW stations every 60 kilometers along core transport corridors by 2025. Highway corridor operators in France, Spain, and Poland are consolidating procurement to meet these mandates, favoring hardware with integrated ISO 15118-20 plug-and-charge capability.
Logistics operators now bundle charging infrastructure into total cost of ownership calculations for electric truck procurement, displacing the historical separation of vehicle and energy decisions. Fleet managers negotiate 10-year power purchase agreements alongside vehicle leases. This bundling is most visible in Germany and the Netherlands, where dedicated e-truck charging depots now anchor new warehouse development site selection.
DC Chargers Market Segmentation
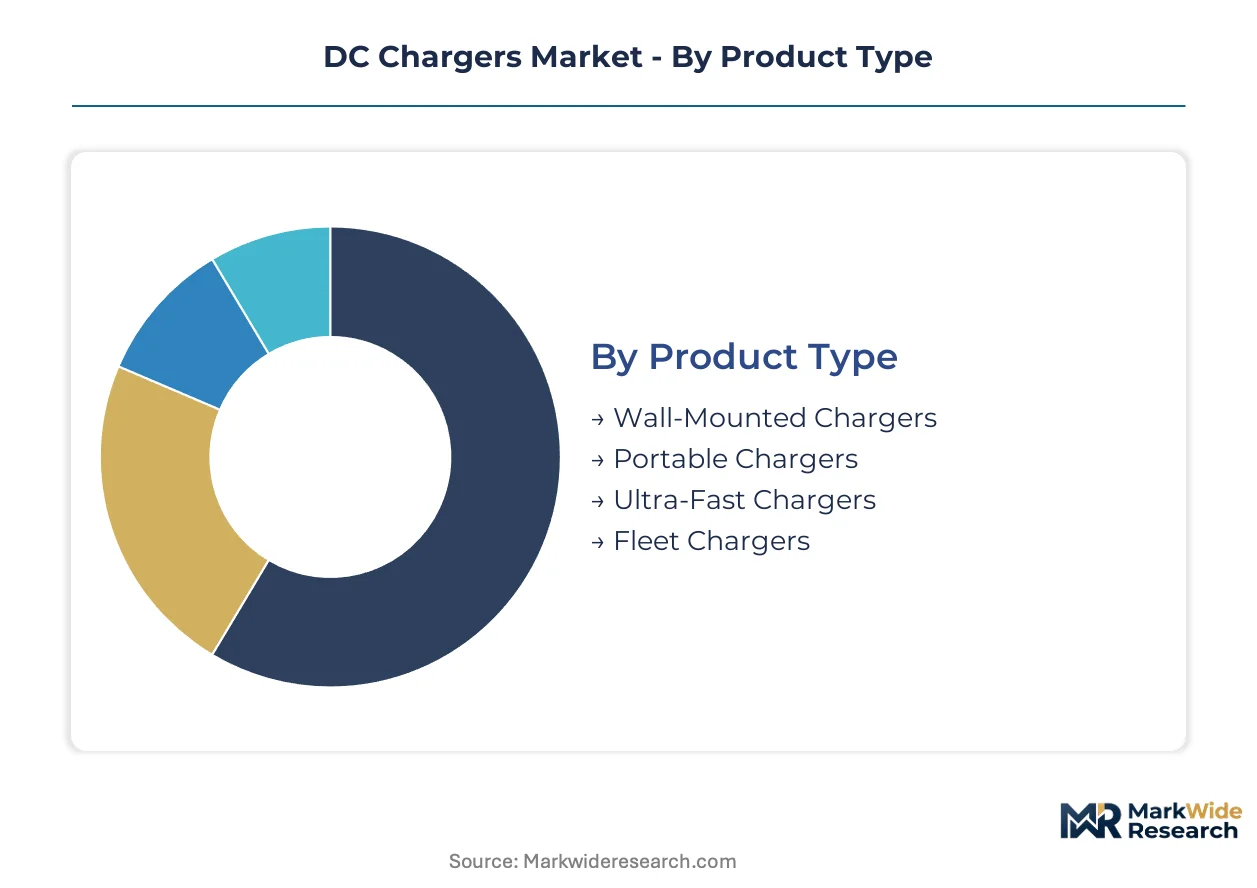
Hardware procurement patterns in the DC charger market diverge sharply by deployment context and power requirement. Fleet operators prioritize depot-based installations with predictable duty cycles, while highway corridor operators optimize for throughput and connector interoperability. Understanding segment-specific upgrade cycles reveals where capital deployment accelerates.
Product Type:
Replacement cycles vary dramatically by power class, with liquid-cooled cable assemblies requiring earlier refresh than passive air-cooled units. German autobahn operators now specify 350 kW minimums, rendering 50 kW designs obsolete before end-of-life.
- Ultra-Fast Chargers:These systems deliver sustained 150-350 kW output through silicon carbide rectifier topologies and liquid-cooled charging cables. Demand concentrates along Germany's federal highway corridors where the EU Green Deal mandates 150 kW stations every 60 kilometers, forcing hardware refresh ahead of amortization schedules.
- Fleet Chargers:Depot-based installations prioritize overnight replenishment with 150-350 kW dispensers configured for sequential rather than simultaneous vehicle service. Logistics operators in the Netherlands anchor new warehouse development around dedicated e-truck charging infrastructure, bundling energy costs into vehicle lease agreements.
- Wall-Mounted Chargers:Compact 50-150 kW units serve constrained urban footprints with reduced installation complexity.
- Portable Chargers:Mobile emergency units address temporary deployment needs for events and roadside assistance fleets.
Volume placements concentrate in Fleet Chargers; the faster expansion belongs to Ultra-Fast Chargers.
Technology:
Protocol selection locks operators into connector ecosystems with divergent certification timelines and regional regulatory backing. China's MIIT enforces GB/T updates that reshape product development cycles for domestic manufacturers.
- CCS:The Combined Charging System dominates European and North American public infrastructure through IEC 61851-23 compliance and ISO 15118-20 plug-and-charge integration. French and Spanish highway operators consolidate procurement around CCS2 hardware to meet EU Alternative Fuels Infrastructure Regulation deadlines.
- GB/T:China's domestic standard retains exclusive regulatory backing from MIIT, with updated grid interconnection standards shaping rectifier designs for the world's largest EV fleet. Domestic manufacturers face no protocol competition within China's protected procurement environment.
- CHAdeMO:Japanese-origin standard retains niche presence in legacy installations and bidirectional charging pilots.
- Tesla Supercharger:Proprietary network advantages persist through integrated vehicle-charger software architecture and NACS connector transition.
Procurement volumes favor CCS in European markets; GB/T commands the steepest expansion trajectory within its protected domestic sphere.
End User:
Customer type determines utilization curves and revenue model selection, with captive fleet demand offering predictability absent from public infrastructure economics.
- Commercial Fleets:Logistics operators calculate charging infrastructure within total cost of ownership for electric truck procurement, negotiating decade-long power purchase agreements alongside vehicle leases. California and Texas pilots explore vehicle-to-grid arbitrage under ISO 15118-20 mandates.
- Charging Station Operators:Highway corridor specialists face dual-layer compliance from US Department of Transportation formula funding and state utility commission rate-case approvals, compressing margin structures.
- Residential Users:Single-family installations rarely exceed 50 kW given distribution transformer constraints.
- Municipal Services:Transit agencies and public works departments specify standardized procurement for predictable maintenance scheduling.
Revenue concentration sits with Commercial Fleets; Charging Station Operators are expanding most quickly as NEVI funding disperses.
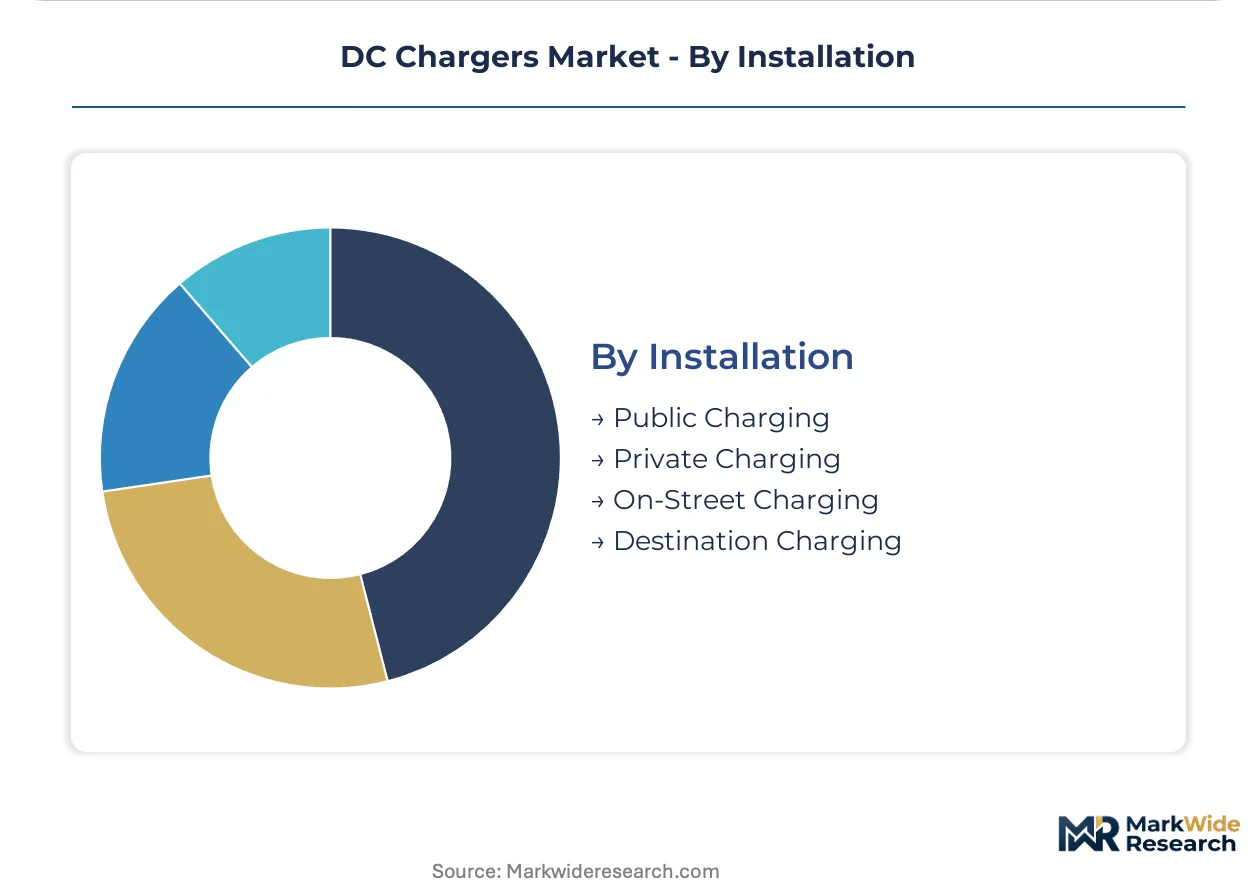
Installation:
Site classification shapes grid interconnection complexity and permitting duration, with urban density extending utility queue timelines.
- Public Charging:Highway-adjacent installations face 12-18 month distribution utility queues regardless of equipment readiness, particularly in dense German and Dutch urban centers where legacy transformers lack 350 kW capacity.
- Private Charging:Corporate and depot installations bypass public infrastructure risk with captive utilization curves and direct utility negotiation.
- On-Street Charging:Curbside deployment requires municipal coordination for right-of-way access and trenching permits.
- Destination Charging:Retail and hospitality sites prioritize dwell-time alignment over power maximization.
Capital deployment clusters in Private Charging; On-Street Charging gains share fastest as municipalities electrify curbside parking inventory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Department of Transportation's National Electric Vehicle Infrastructure formula funding creates a federal tax-incentive zone concentrating charger deployment along interstate corridors. Germany's autobahn charging infrastructure receives federal priority funding under EU Green Deal mandates. China's MIIT enforces GB/T protocol standards that shape domestic manufacturing concentration.
United States
Commercial fleet operators in California and Texas pilot vehicle-to-grid arbitrage models under ISO 15118-20 mandates. The US Department of Transportation coordinates NEVI formula funding with state utility commission rate-case approvals. Highway corridor installations face 12-18 month distribution utility queues in dense urban centers where legacy transformers lack 350 kW capacity.
Germany
Logistics operators in the Netherlands and Germany anchor new warehouse development around dedicated e-truck charging infrastructure. The EU Green Deal's Alternative Fuels Infrastructure Regulation mandates 150 kW stations every 60 kilometers along core transport corridors by 2025. German autobahn operators now specify 350 kW minimums, rendering 50 kW designs obsolete before end-of-life.
China
Domestic manufacturers face no protocol competition within China's protected procurement environment serving the world's largest EV fleet. China's MIIT enforces updated GB/T grid interconnection standards that reshape product development cycles. The dual carbon goals accelerate DC fast-charging corridor deployment across provincial highway networks.
France
French highway operators consolidate procurement around CCS2 hardware to meet EU Alternative Fuels Infrastructure Regulation deadlines. The EU Green Deal mandates standardized payment interoperability and minimum power thresholds at public stations. Charging infrastructure clusters along the Rhine-Alpine corridor connecting Lyon to Mediterranean ports.
Netherlands
Dedicated e-truck charging depots now anchor new warehouse development site selection in logistics corridors. The EU Green Deal's transport decarbonization targets compel logistics operators to electrify heavy-duty corridors. Rotterdam-Eindhoven logistics belt concentrates depot-based DC installation with decade-long power purchase agreements.
DC Chargers Market Competitive Environment
European producers anchor one tier; Asian specialists hold manufacturing scale advantages in power electronics. The vendor base concentrates among diversified industrial conglomerates with grid integration capabilities and pure-play charging hardware specialists. Two strategic archetypes dominate: integrated energy service providers bundling solar-plus-storage with charging infrastructure, and component-focused suppliers specializing in silicon carbide rectifier assemblies. Competitive moves center on backward integration into semiconductor supply chains and geographic expansion through certification harmonization.
Within the diversified industrial tier, ABB and Siemens AG exemplify European engineering conglomerates with grid integration project capabilities. Tesla occupies a position as a vertically integrated network operator with proprietary vehicle-charger software architecture. These three companies represent contrasting strategic postures: hardware manufacturing scale, grid infrastructure anchoring, and closed-loop ecosystem control.
| Leading Market Players |
|---|
| ABB |
| Tesla |
| Siemens AG |
| ChargePoint |
| Delta Electronics |
| EVBox |
| Eaton Corporation |
| Alpitronic |
| Tritium |
| Others |
Value Chain & Pricing Dynamics
Power electronics engineering talent concentrated in Germany's Aachen-Dresden corridor and Taiwan's Hsinchu Science Park feeds labor-cost differentials that widen pricing-tier spreads between premium silicon carbide designs and economy silicon IGBT alternatives.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to liquid-cooled cable assemblies and gallium nitride rectifier modules facing extended factory queues. Three-tier pricing structure across premium, standard, and economy levels separates ISO 15118-20 plug-and-charge certified hardware from base IEC 61851 units and unbranded white-label imports. Cost compression in economy tiers is intensifying because Chinese manufacturers are flooding GB/T protocol markets with undifferentiated 50 kW designs. Fleet operators exhibit lowest price sensitivity due to decade-long power purchase agreement bundling, while municipal procurement offices show highest sensitivity to upfront capital expenditure.
Supply Chain Analysis
Certification timelines spanning UL 2594, IEC 61851, and GB/T compliance gates filter supplier participation and elongate order-to-delivery cycles for multinational hardware vendors. Manufacturing concentrates in China for rectifier assemblies, Germany for precision power electronics, and Taiwan for silicon carbide wafer sourcing. Copper busbars, neodymium-doped magnetic components, and liquid-cooled cable jackets constitute critical input dependencies. Single-source vulnerability in silicon carbide substrate supply threatens production continuity for 350 kW dispenser programs. Distribution runs through integrated energy service providers bundling hardware with installation and maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon carbide wafer fabrication capacity constraints prop pricing premiums for 150 kW-plus hardware, creating supply-constrained market conditions that favor incumbents with captive semiconductor relationships.
For Market Incumbents: Anticipate margin compression from Chinese GB/T specialists by securing long-term silicon carbide supply agreements with substrate manufacturers. Anchor defensive positioning through backward integration into gallium nitride inverter topology design capabilities concentrated at RWTH Aachen and Fraunhofer research networks. Prioritize certification investment in ISO 15118-20 plug-and-charge interoperability to lock fleet operator procurement specifications before EU Alternative Fuels Infrastructure Regulation deadlines. For New Entrants and Emerging Players: Capture depot-based fleet charging installations in Poland and Spain where EU Green Deal corridor mandates outpace local supplier presence. Target underpenetrated last-mile distribution hubs in the Netherlands' Rotterdam-Eindhoven logistics belt where warehouse developers seek bundled energy infrastructure partners. Deploy solar-plus-storage co-location go-to-market positioning to access US IRA production tax credit economics alongside charging hardware sales. For Investors and Strategic Acquirers: Re-rating potential sits with pure-play silicon carbide rectifier specialists given OEM 800-volt architecture transition timelines. Long-term viability over the next decade favors vendors with demonstrated grid integration project execution and bidirectional charging firmware stacks. Monitor California and Texas vehicle-to-grid pilot program expansion as the signal to watch for regulatory validation of revenue-stacking business models.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Rectifier Scale-Up | Enables compact 350 kW dispensers meeting German autobahn minimum specifications. |
| ISO 15118-20 Certification Investment | Locks fleet procurement preferences under EU plug-and-charge mandates. |
| Solar-Plus-Storage Co-location | Captures US IRA tax credits while securing grid interconnection priority queue positioning. |
| GB/T Protocol Manufacturing Expansion | Serves China's protected domestic market under MIIT grid interconnection standards. |
| Bidirectional Charging Firmware Development | Opens vehicle-to-grid revenue streams for California and Texas fleet arbitrage pilots. |
Study Parameters
Independent corroboration across charging network operators, semiconductor procurement directors, and utility interconnection planners underwrites the qualitative findings. Primary interviews with hardware engineering leads at Tier 1 suppliers, fleet energy managers at logistics operators, and grid integration specialists at European engineering conglomerates combined with secondary validation. Secondary sources include US Department of Transportation NEVI funding disclosures, China's MIIT GB/T standard updates, EU Alternative Fuels Infrastructure Regulation filings, and SEC 10-K equipment supplier disclosures. Bottom-up unit deployment estimates triangulate against top-down infrastructure investment forecasts.
Historical deployment patterns across the analysis window anchor forward projections through segmented growth rate derivation. Segmentation dimensions modeled include power class tier, connector protocol type, end-user category, and installation context. CAGRs emerge from curve-fitting observed adoption velocities against policy mandate timelines and vehicle fleet turnover schedules. Silicon carbide cost-down curves and distribution utility queue duration assumptions constitute key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to copper and rare earth commodity volatility, grid interconnection regulatory shifts, and 800-volt vehicle architecture adoption velocity. Forecasts reflect documented assumptions on OEM platform rollout schedules and federal funding disbursement pacing. A model refresh is warranted upon material change in EU Green Deal transport corridor mandate enforcement or China's dual carbon goal acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Electric Vehicle Charging Systems Testing Market
Electric Vehicle Charging
Battery Swap Station Market
Electric Vehicle Charging
Australia Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle Battery Charger Market
Electric Vehicle Charging
South Korea Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
EV Charge Controller Market
Electric Vehicle Charging
North America EV Charging Stations Market
Electric Vehicle Charging
Two Wheel Electric Vehicle Charger Market
Electric Vehicle Charging
EV Charging Infrastructure Market
Electric Vehicle Charging
Europe EV Charging Stations Market
Electric Vehicle Charging
Denmark Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
Electric Vehicle Charging Station Raw Materials Market
Electric Vehicle Charging
EV DC Fast Charger Market
Electric Vehicle Charging
Second Life Electric Vehicle Battery Market
Electric Vehicle Charging
Electric Vehicle Charging Pile Cables Market