
 Asia-Pacific Decor Paper Market | 2026-2036
Asia-Pacific Decor Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Decor Paper Market Outlook
Skilled press operators with gravure and digital calibration expertise are in short supply across the region, and this labor scarcity is unwinding planned capacity additions at several mills. Ahlstrom-Munksjö Oyj leverages its Nordic technical heritage to sustain premium base-paper supply chains into East Asian laminate producers. Felix Schoeller India anchors its position through captive coating capabilities that dominate India's domestic decor-paper segment. Oji Holdings competes by controlling integrated pulp-to-paper logistics across Japan and export corridors into Southeast Asia.
Decor paper refers to specialty cellulose-based sheets, typically 30–80 gsm, impregnated with melamine or urea-formaldehyde resins and printed with wood-grain or abstract patterns for lamination onto particleboard or MDF substrates. The resin absorption rate and colorfastness under hot-press conditions determine suitability for flooring, furniture, and wall-panel applications. Printed paper segments lead volume due to their ubiquity in mass-market laminate flooring, while laminated paper categories capture disproportionate margin pools from high-pressure decorative panel specifications. Digital printing technology is displacing offset in short-run custom orders as furniture manufacturers demand shorter lead times for seasonal surface designs.
China's SAMR enforces GB standards for formaldehyde emission classification in wood-based panels, directly shaping resin formulation and base-paper sourcing decisions across domestic supply chains. India's BIS certification requirements for laminate-grade decor paper create compliance barriers that favor established mills with testing laboratory relationships. Japan's METI promotes JIS standards for interior air quality that elevate specifications for low-emission overlay papers in commercial building projects. Stakeholders must monitor how divergent national certification regimes fragment procurement standards and force regional suppliers to maintain multiple product grades.
Market Dynamics
Digital printing adoption is compressing lead times for seasonal laminate designs while China's GB forestry certification rules force pulp sourcing restructuring across East Asian mills.
Growth Catalysts
- Residential construction acceleration:Southeast Asian laminate flooring manufacturers are scaling decorative overlay paper orders as housing starts expand across Vietnam and Indonesia.
- GB standards compliance:China's tightened forestry product certification rules under GB standards are redirecting mills toward certified pulp supply chains.
- Digital gravure hybridization:Short-run custom furniture orders are pulling investment into digital printing lines that enable rapid pattern turnaround.
Market Restraints
- Certified pulp cost premiums:FSC and PEFC certified pulp inputs carry 15-25% price premiums over conventional alternatives, squeezing margin structures for mid-tier mills.
- Skilled operator scarcity:Gravure and digital calibration expertise shortages are delaying planned capacity additions at multiple regional facilities.
- Formaldehyde emission thresholds:China's SAMR enforcement of stricter GB classification limits is forcing resin reformulation investments that extend product development cycles.
Strategic Opportunities
- India western corridor expansion:Gujarat and Maharashtra furniture clusters are building pressed-wood capacity that requires localized decor paper supply.
- JIS commercial building standards:Japan's METI promotion of low-emission overlay specifications creates premium positioning for compliant suppliers.
- Digital-analog workflow convergence:Hybrid printing systems combining gravure base layers with digital customization are opening short-run architectural panel applications.
Industry Challenges
- Calibration technician deficits:Press operators capable of managing color consistency across hot-press temperature variations remain in critically short supply.
- BIS laboratory access bottlenecks:India's certification requirements for laminate-grade decor paper create testing queue delays that disadvantage newer market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Decor Paper Market |
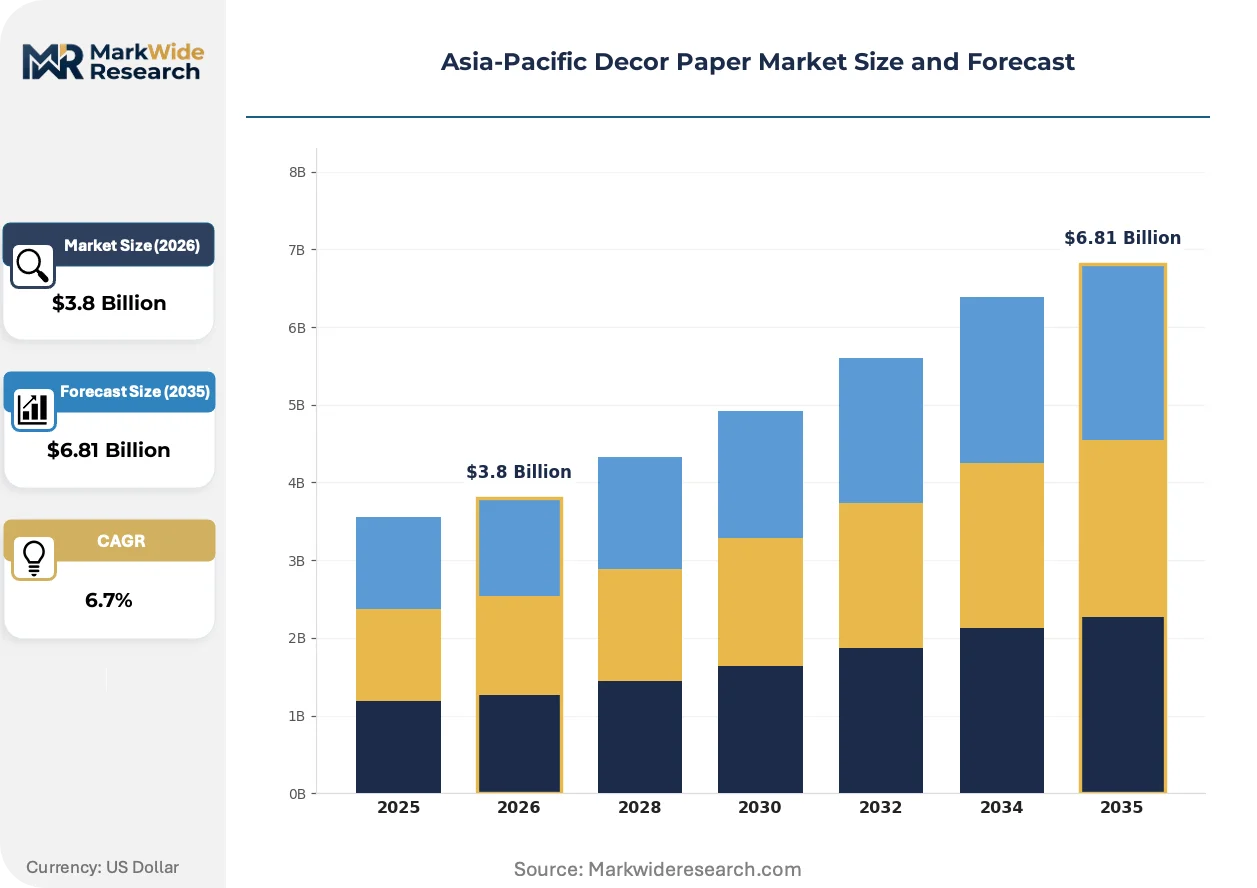
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Adhesive Paper, Laminated Paper, Printed Paper, Embossed Paper End User: Furniture Manufacturers, Interior Designers, Retail Outlets, Packaging Industry Technology: Digital Printing, Offset Printing, Flexographic Printing, Screen Printing Material: PVC, Paperboard, Coated Paper, Others |
| Companies Covered | ITC Limited, I.DECOR Exp.Imp Co., Ltd, Fakirsons Papchem Pvt Ltd, Shah International, Ahlstrom-Munksjö Oyj, Felix Schoeller India, Oji Holdings, JK Paper Limited, Tanish Industries Pvt. Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Decor Paper Market Strategic Shifts
Technology substitution, regulatory divergence, and procurement compression are simultaneously reshaping competitive requirements across the Asia-Pacific decor paper value chain.
Water-based ink systems are displacing solvent-based formulations in digital decor printing lines. Flooring manufacturers in South Korea and Thailand are adopting these systems to meet indoor air quality specifications. The transition is compressing equipment replacement cycles while elevating capital requirements for coating line retrofits.
China's SAMR enforcement of GB/T 39600-2021 formaldehyde emission classifications is restructuring resin formulation protocols. Domestic panel producers must now source base papers with controlled absorption rates that align with E0 and ENF grade targets. This regulatory pressure is fragmenting procurement standards and forcing regional suppliers to maintain multiple product grades.
Consolidated buying by large laminate flooring groups is compressing supplier negotiation leverage. Major manufacturers in Vietnam and Malaysia are consolidating purchase orders to secure volume pricing and technical service commitments. This concentration is most visible in the residential flooring segment, where procurement teams now demand just-in-time delivery with color-matching guarantees.
Asia-Pacific Decor Paper Market Segmentation
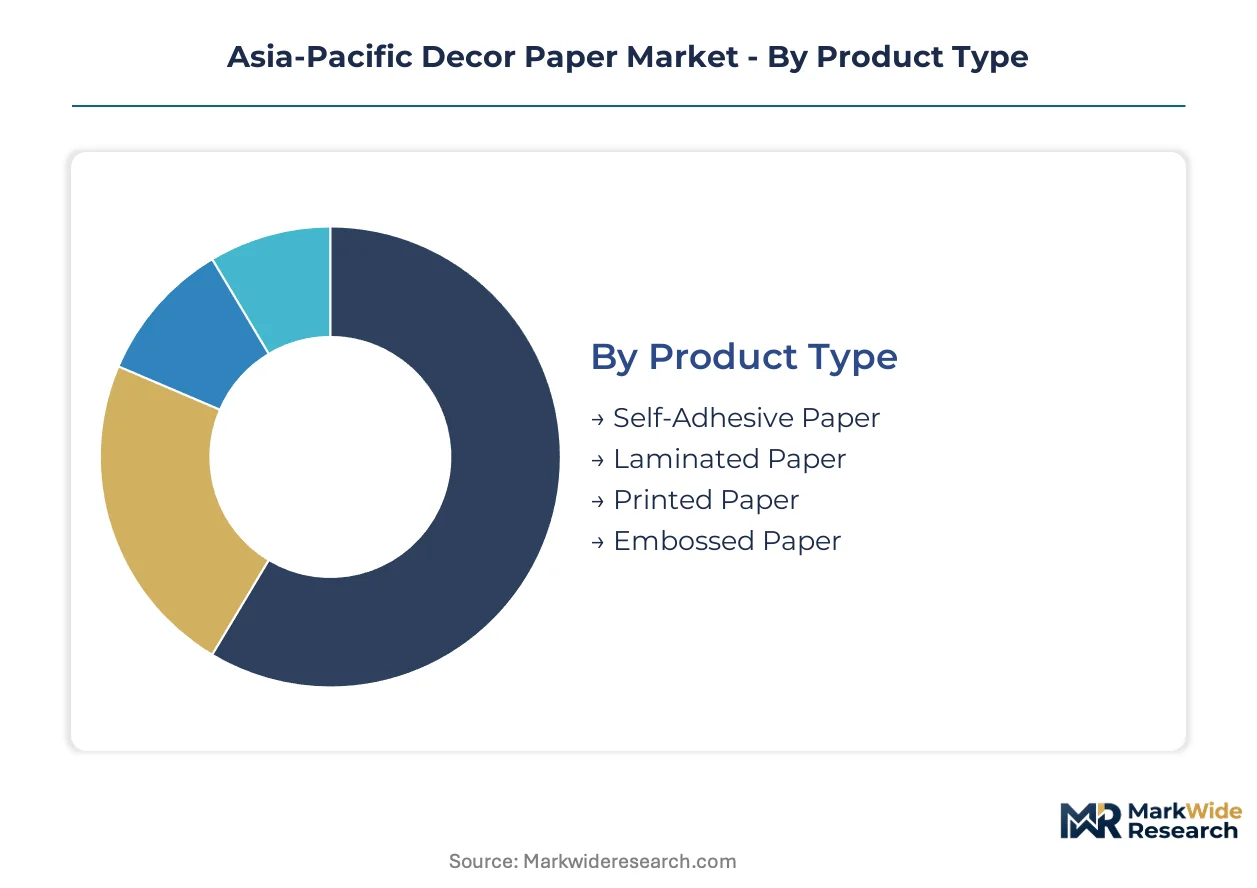
Segmentation in the Asia-Pacific decor paper market reflects divergent certification requirements across national boundaries. China's GB standards, India's BIS mandates, and Japan's JIS specifications each favor different product grades and printing technologies. Procurement teams must navigate this regulatory fragmentation when specifying materials for cross-border laminate production.
Product Type:
Regulatory differentiation across the region favors specific paper constructions based on formaldehyde emission thresholds and forestry certification requirements.
- Printed Paper:Cellulose sheets in the 30–80 gsm range receive rotogravure or digital pattern application for direct lamination onto particleboard substrates. Demand concentrates in Vietnam and Indonesia where residential flooring manufacturers scale orders for wood-grain surface designs; China's SAMR enforcement of GB/T 39600-2021 E0 and ENF classifications forces mills to control resin absorption rates precisely.
- Laminated Paper:Multi-layer constructions combining base sheets with protective overlays withstand high-pressure decorative panel specifications. Gujarat and Maharashtra furniture clusters in India's western corridor are expanding pressed-wood capacity that requires these premium-grade materials; BIS certification for laminate-grade decor paper creates compliance barriers favoring established suppliers with laboratory relationships.
- Self-Adhesive Paper:Pressure-sensitive decorative films serving temporary wall coverings and retail display applications.
- Embossed Paper:Textured surface papers providing tactile dimension for premium furniture and architectural panel segments.
Established volume favors printed paper; emerging adoption favors laminated paper.
End User:
Cost tier stratification separates specification-grade buyers from mass-market procurement patterns.
- Furniture Manufacturers:Pressed-wood producers across Southeast Asia drive the core demand base for decorative overlay papers. Laminate flooring manufacturers in Vietnam and Malaysia consolidate purchase orders to secure volume pricing; just-in-time delivery requirements with color-matching guarantees compress supplier margins.
- Interior Designers:Custom specification work demands short-run pattern flexibility and rapid turnaround capabilities. Digital printing adoption is compressing lead times for seasonal designs; South Korean and Thai flooring manufacturers are adopting water-based ink systems to meet indoor air quality specifications.
- Retail Outlets:Point-of-sale and fixture applications requiring durable surface finishes with visual impact.
- Packaging Industry:Specialty decorative wraps for premium consumer goods presentation.
Volume concentration sits with furniture manufacturers; margin expansion favors interior designers.
Technology:
Application requirements determine the technology mix, with flooring and furniture segments imposing distinct speed and customization demands.
- Digital Printing:Inkjet and electrophotographic systems enable rapid pattern changeover for short-run custom orders. Furniture manufacturers demanding shorter lead times for seasonal surface designs are pulling investment into these lines; water-based ink displacement of solvent formulations elevates capital requirements for coating line retrofits.
- Offset Printing:High-volume rotogravure remains dominant for mass-market laminate flooring production. Skilled press operators with gravure calibration expertise are in short supply across the region; this labor scarcity is unwinding planned capacity additions at several mills.
- Flexographic Printing:Continuous roll-to-roll processing for large-format architectural panel applications.
- Screen Printing:Heavy ink deposition for specialty textured and metallic finish effects.
Offset printing anchors current volume; digital printing is climbing the fastest.
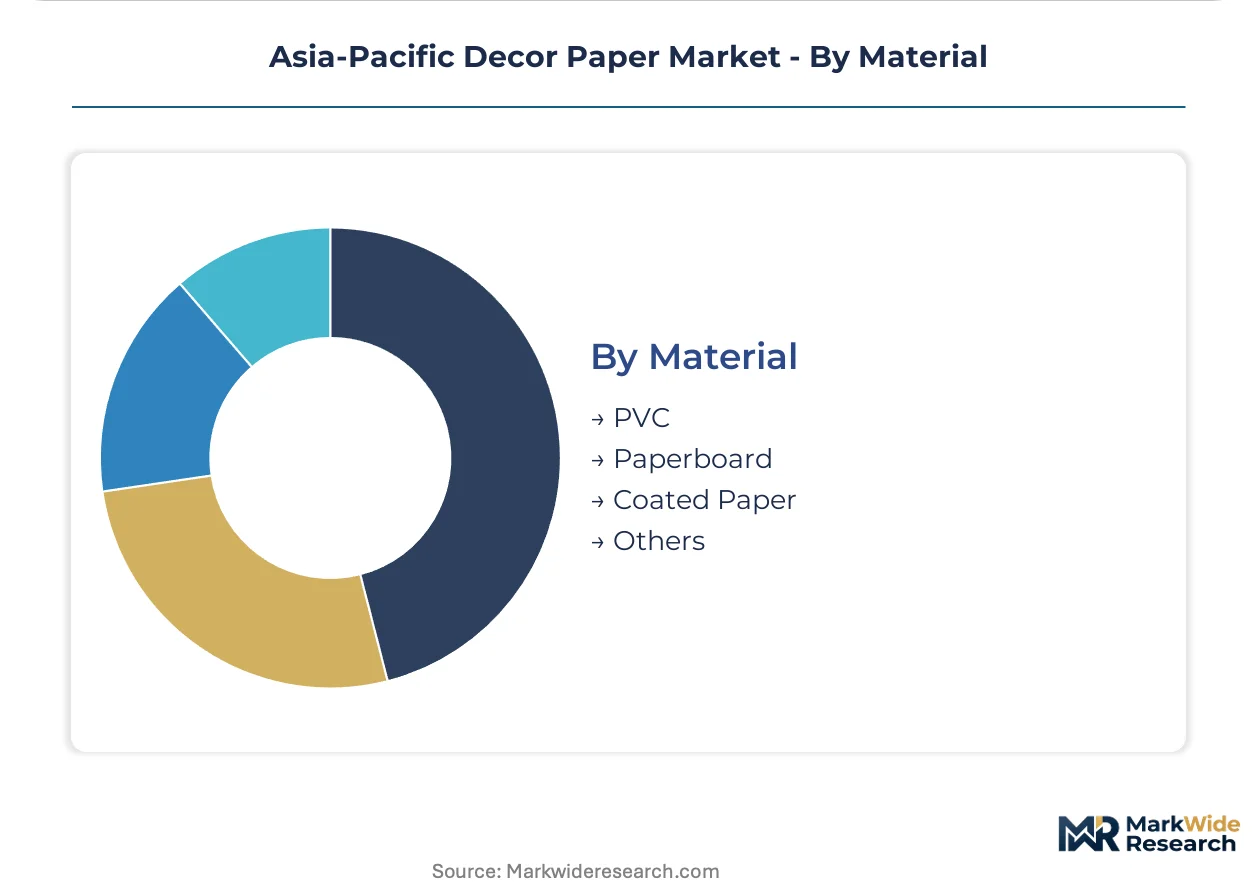
Material:
Supply concentration around certified pulp sources is restructuring material availability across the region.
- Coated Paper:Surface-treated cellulose sheets engineered for controlled resin absorption and colorfastness under hot-press conditions. China's tightened forestry product certification rules under GB standards are pushing mills toward FSC and PEFC certified pulp sourcing; these certified inputs carry 15-25% price premiums over conventional alternatives.
- Paperboard:Rigid substrate constructions for structural laminate applications requiring dimensional stability.
- PVC:Synthetic alternatives serving moisture-resistant and exterior-grade specifications.
- Others:Emerging bio-based and recycled content materials responding to sustainability procurement criteria.
Coated paper dominates specification work; paperboard is gaining share fastest in structural applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR enforcement of GB/T 39600-2021 formaldehyde classifications is restructuring pulp sourcing across Chinese mills and redirecting supply chain investments toward certified forestry inputs. This regulatory pressure cascades through neighboring markets as regional exporters adapt to divergent national certification regimes.
China
Residential flooring manufacturers in Zhejiang and Jiangsu provinces are scaling decorative overlay paper orders as housing construction rebounds. SAMR's tightened GB forestry certification rules are forcing mills toward FSC and PEFC certified pulp supply chains. The Yangtze River Delta furniture cluster is expanding pressed-wood capacity that requires localized base-paper supply with controlled resin absorption rates.
India
Gujarat and Maharashtra furniture clusters are building pressed-wood capacity that requires localized decor paper supply with BIS certification compliance. The Bureau of Indian Standards mandates testing laboratory relationships that favor established mills over newer entrants. Mumbai-Pune industrial corridor laminate flooring manufacturers are consolidating purchase orders to secure volume pricing and technical service commitments.
Japan
METI promotion of JIS standards for interior air quality is elevating specifications for low-emission overlay papers in commercial building projects across Tokyo and Osaka. Kanto region architectural panel producers demand premium-grade laminated paper constructions. Chubu-Nagoya manufacturing belt suppliers are adapting product grades to meet these stringent emission thresholds.
Vietnam
Residential construction acceleration in Ho Chi Minh City and Hanoi is pulling decorative overlay paper demand from laminate flooring manufacturers. Vietnamese mills face pressure to align with Chinese GB certification standards for export-oriented production. Southern industrial zones are attracting regional suppliers seeking to bypass China's pulp sourcing cost premiums.
Indonesia
Jakarta-Bandung furniture manufacturing corridor is expanding melamine-faced particleboard capacity that requires printed paper imports and domestic production. Indonesian producers navigate between Chinese GB standards and European procurement requirements for export markets. Java-based laminate flooring groups are consolidating supplier relationships to secure just-in-time delivery with color-matching guarantees.
Asia-Pacific Decor Paper Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the Asia-Pacific decor paper market. The upper tier controls captive pulp sourcing and coating capabilities that insulate margin structures from certified input cost premiums. Specialist players concentrate on digital printing customization and short-run architectural panel applications. Competitive moves center on backward integration into certified pulp supply chains and hybrid printing system investments that combine gravure base layers with digital pattern flexibility.
Among Nordic-heritage integrated producers, Ahlstrom-Munksjö Oyj occupies a position exemplifying premium base-paper supply chain control into East Asian laminate markets. Felix Schoeller India represents the captive coating specialist archetype dominating India's domestic decor-paper segment through western corridor proximity. Oji Holdings anchors the integrated pulp-to-paper logistics model across Japan and export corridors into Southeast Asia, illustrating how upstream control over forestry certification compliance creates defensive positioning against regulatory fragmentation.
| Leading Market Players |
|---|
| ITC Limited |
| I.DECOR Exp.Imp Co., Ltd |
| Fakirsons Papchem Pvt Ltd |
| Shah International |
| Ahlstrom-Munksjö Oyj |
| Felix Schoeller India |
| Oji Holdings |
| JK Paper Limited |
| Tanish Industries Pvt. Ltd. |
| Others |
Value Chain & Pricing Dynamics
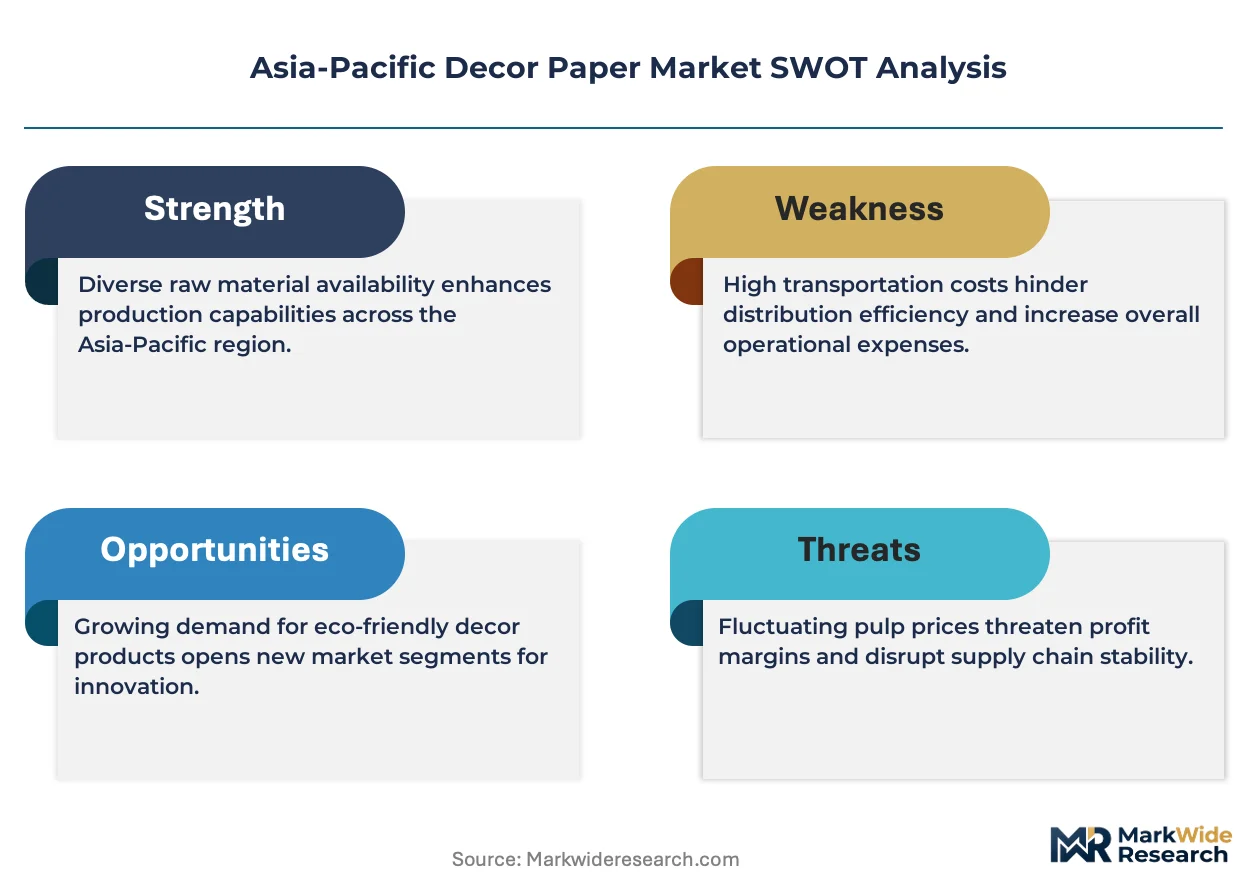
China's SAMR enforcement of GB/T 39600-2021 formaldehyde classifications gates both supply qualification and price differentiation simultaneously, forcing mills to maintain parallel product grades while certified pulp premiums compress margin structures across mid-tier producers.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between Vietnamese laminate flooring manufacturers and regional mills, though spot purchasing persists for short-run custom orders. Price differentiation hinges on FSC/PEFC certification tier and volume scale, with large flooring groups extracting favorable terms through consolidated purchasing. Cost compression in the standard-grade segment is intensifying because certified pulp inputs carry substantial premiums over conventional alternatives. Mass-market furniture manufacturers exhibit highest price sensitivity, while Japanese commercial building specifiers show lowest sensitivity due to JIS compliance mandates.
Supply Chain Analysis
Just-in-time inventory strategies dominate procurement relationships as Vietnamese and Malaysian flooring manufacturers demand color-matching guarantees with compressed lead times. Supply concentrates in China, Japan, and India, with Indonesian mills emerging as alternative sources for export-oriented production. Raw material dependencies center on FSC-certified softwood pulp, melamine-formaldehyde resins, and water-based ink formulations. Single-source vulnerability runs through China's Yangtze River Delta pulp processing corridor. Distribution runs through direct mill-to-factory relationships for large accounts, with regional distributors serving smaller furniture clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and color-matching guarantee programs are expanding faster than base-paper volume as flooring manufacturers outsource pattern calibration and press-line optimization.
For Market Incumbents: Shield margin structures by deepening captive coating capabilities that insulate against certified pulp cost volatility, while securing BIS laboratory relationships in India's western corridor to block newer entrants. Digital gravure hybridization investments will defend against pure-play digital specialists eroding short-run architectural panel share. For New Entrants and Emerging Players: After-sales press-line calibration services represent an under-served layer where incumbents under-serve mid-tier Vietnamese furniture manufacturers lacking skilled operator benches. Target Indonesia's Jakarta-Bandung corridor through partnerships with local distributors possessing established just-in-time logistics networks. Lead with water-based ink system retrofits as the go-to-market wedge. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across digital printing line installations as coating equipment replacement cycles compress. Long-term viability favors integrated producers controlling pulp-to-paper logistics rather than pure converters exposed to input cost volatility. Watch for BIS certification queue delays exceeding six months as the signal that regulatory bottlenecks are structurally advantaging established laboratory relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Pulp Sourcing | FSC and PEFC chain-of-custody control neutralizes 15-25% input cost premiums squeezing mid-tier competitors. |
| Digital-Gravure Hybrid Line Installation | Combines rotogravure base-layer speed with digital customization for short-run architectural panel applications. |
| BIS Testing Laboratory Partnership | Direct Bureau of Indian Standards access collapses certification queues blocking newer market entrants in Gujarat and Maharashtra. |
| Technical Service Contract Expansion | Press-line calibration and color-matching guarantees capture recurring revenue faster than commodity paper sales. |
| Indonesia Distribution Network Establishment | Java-based just-in-time logistics bypass China's pulp sourcing cost premiums for export-oriented production. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, mill production disclosures, and national certification registry records. Press operators, procurement managers at laminate flooring manufacturers, BIS laboratory technical directors, and resin formulation chemists provided operational perspective. Bottom-up capacity assessments triangulated against top-down consumption estimates derived from particleboard and MDF production statistics.
Segmentation dimensions modeled include product type, end-use application, printing technology, material construction, and national regulatory cluster across the analysis window. CAGRs derive from trend extrapolation of housing starts, furniture production indices, and certification adoption curves. Forecast inputs incorporate SAMR enforcement intensity assumptions and digital printing line installation rates.
Forecasts assume regulatory continuity in China's GB standards, India's BIS mandates, and Japan's JIS specifications; material policy shifts would require re-modeling. Certified pulp availability disruptions or formaldehyde threshold tightening beyond current E0/ENF classifications represent primary revision triggers. Revision becomes warranted when BIS laboratory queue durations exceed thresholds that structurally alter competitive entry economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
ASEAN UPVC Doors and Windows Market
Homecare and Decor
Frame for Painting Market
Homecare and Decor
Pillow Market
Homecare and Decor
North America Sustainable Home Decor Market
Homecare and Decor
Global Decorative Laminates Market
Homecare and Decor
Europe Mattress Market
Homecare and Decor
US Wallcovering Market
Homecare and Decor
Wall Art Market
Homecare and Decor
India Interior Design Market
Homecare and Decor
Smart Bed Mattress Market
Homecare and Decor
Home Decor and Accessories Market
Homecare and Decor
Bifold Door Market
Homecare and Decor
Bookends Market
Homecare and Decor
Hearth Market
Homecare and Decor
Middle East and Africa Christmas Tree Market
Homecare and Decor
Fireplace and Stove Market