
 Smart Bed Mattress Market | 2026-2036
Smart Bed Mattress Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Bed Mattress Market Insights
Subscription-based leasing models for clinical-grade smart mattresses are reshaping capital deployment across healthcare systems. Sleep Number Corporation leverages direct-to-consumer channel control to sustain premium positioning in residential segments. Stryker Corporation anchors its competitive stance through R&D intensity in pressure-relief algorithms for acute care settings. Hill-Rom Holdings Inc. dominates North American hospital procurement through backward integration into sensor hardware manufacturing.
A smart bed mattress integrates electromechanical actuators, biometric sensors, and microprocessor-controlled foam or air-chamber systems to enable real-time sleep monitoring, automated firmness adjustment, and temperature modulation. These systems typically incorporate pressure-mapping arrays with sensitivity thresholds below 10 mmHg and communicate via Bluetooth or Wi-Fi protocols to companion applications for longitudinal sleep-health analytics. Adjustable mattress and hybrid mattress categories lead current revenue contribution due to established manufacturing scale and consumer familiarity, while gel mattress segments compete on thermal-performance differentiation in hospitality and senior living channels. Smart sensors and sleep tracking technologies concentrate margin pools through recurring software-license structures, whereas adjustable firmness hardware remains more exposed to component-cost volatility.
The FDA's 510(k) clearance pathway for software-as-medical-device functionality shapes product development timelines and clinical-channel access for US manufacturers. EMA's Medical Device Regulation and Japan's PMDA software validation standards create parallel compliance burdens for companies seeking multi-country hospital procurement contracts. REACH restrictions on certain flame-retardant chemistries and California's TB 117-2013 smolder standards constrain foam formulation choices across residential and commercial product lines. Stakeholders must monitor how divergent cybersecurity frameworks for connected health devices evolve across FDA, EMA, and Japan's Ministry of Health, Labour and Welfare, as patch-management obligations will increasingly determine warranty costs and liability exposure.
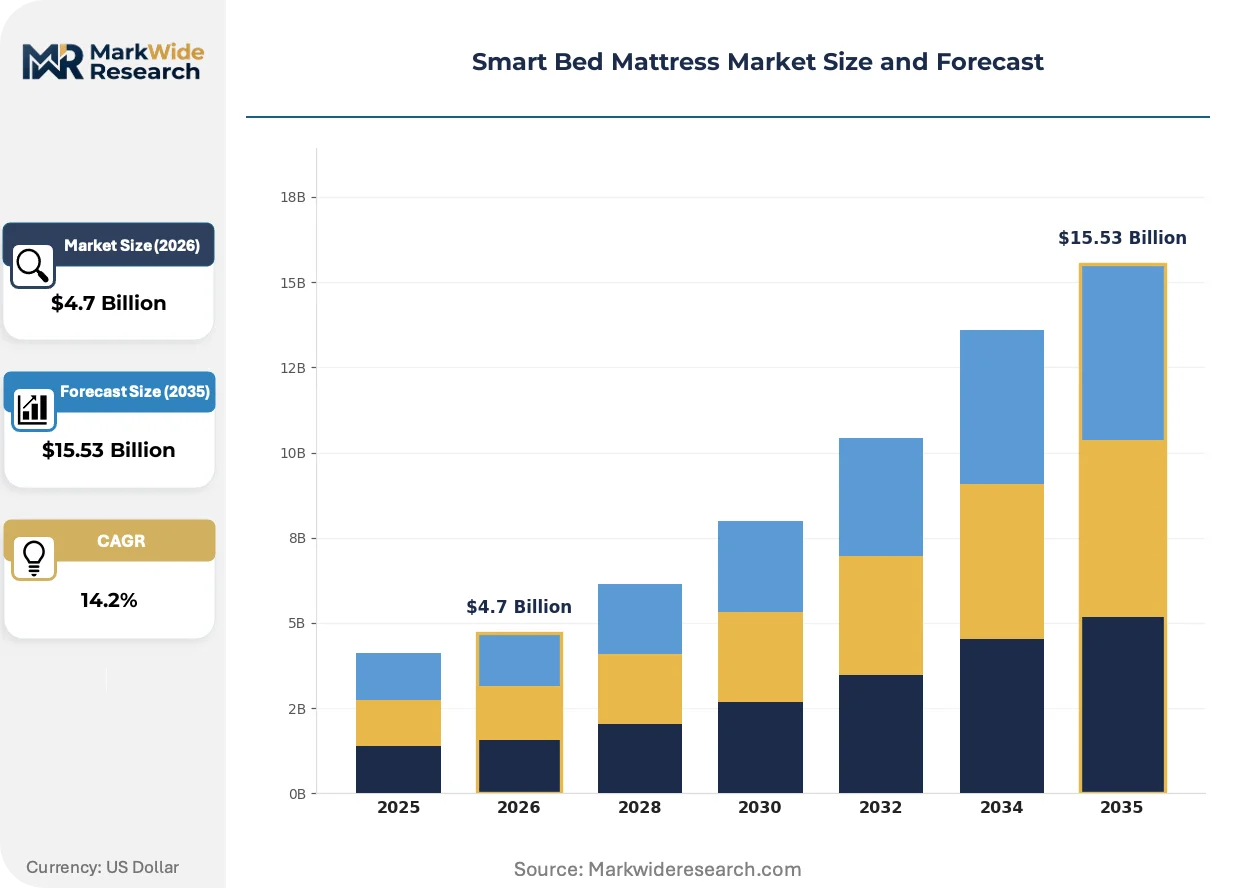
Market Dynamics
Sensor-embedded sleep systems are restructuring competitive boundaries as hardware commoditization pressures force manufacturers toward software-defined differentiation and recurring revenue architectures.
Growth Catalysts
- FDA Class II Medical Device Pathway:Hospital procurement channels in the United States now require 510(k) clearance for patient-monitoring mattresses, accelerating clinical-grade product development timelines and filtering out non-compliant suppliers.
- Germany's Dual-Channel Demand:Hospital networks and luxury hospitality chains in Germany are simultaneously upgrading sleep infrastructure, creating concentrated volume pools for pressure-mapping and thermal-modulation systems.
- Pressure-Relief Algorithm Advances:Real-time pressure-mapping arrays with sub-10 mmHg sensitivity thresholds are enabling automated firmness adjustment that prevents pressure ulcers in acute care settings.
Market Restraints
- Memory Foam Input Volatility:Polyurethane foam formulations face cost pressure from petrochemical feedstock fluctuations and REACH restrictions on legacy flame-retardant chemistries.
- Sensor Hardware Supply Concentration:Pressure-mapping array manufacturing clusters in East Asian electronics corridors create single-source vulnerability for North American and European mattress assemblers.
- Cybersecurity Patch-Management Burden:Divergent FDA, EMA, and Japan PMDA frameworks for connected health devices impose overlapping firmware-validation obligations that inflate warranty costs.
Strategic Opportunities
- Subscription Leasing Models:Healthcare systems are deploying capital-light mattress-as-a-service contracts that shift revenue recognition from unit sales to recurring software-license streams.
- Senior Living Thermal Differentiation:Gel mattress segments compete on temperature modulation in assisted-living facilities where thermoregulatory dysfunction drives product selection criteria.
- Bluetooth-to-Wi-Fi Protocol Migration:Companion application ecosystems are consolidating around cloud-native architectures that enable longitudinal sleep-health analytics and third-party API integration.
Industry Challenges
- Software-as-Medical-Device Validation Timelines:FDA 510(k) clearance for algorithm-driven pressure-relief functionality extends product development cycles and delays hospital channel entry.
- Biometric Sensor Integration Complexity:Legacy hospital IT infrastructure requires custom middleware development to ingest real-time mattress data into electronic health record systems.
- Multi-Jurisdiction Compliance Fragmentation:Parallel EMA Medical Device Regulation and Japan PMDA software validation standards force redundant documentation for manufacturers seeking multi-country procurement contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Bed Mattress Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $15.53 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adjustable Mattress, Hybrid Mattress, Memory Foam Mattress, Gel Mattress Technology: Smart Sensors, Sleep Tracking, Temperature Regulation, Adjustable Firmness End User: Residential, Hospitality, Healthcare Facilities, Senior Living Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Wholesale |
| Companies Covered | Sleep Number Corporation, Stryker Corporation, Hill-Rom Holdings Inc., Paramount Bed Co., Ltd., Arjo AB, Invacare Corporation, LINET Group SE, Tempur Sealy International Inc., Eight Sleep, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Bed Mattress Market Trends and Innovations
Electromechanical sleep systems are converging with clinical monitoring infrastructure, blurring residential and healthcare product categories while regulatory frameworks scramble to keep pace.
Capacitive pressure-sensing technology is migrating from discrete sensor arrays to woven textile-integrated architectures. Hospital procurement teams in the United States are specifying seamless sensing surfaces for infection-control compliance. This shift is compressing hardware margins for legacy sensor-module suppliers while rewarding textile-electronics hybrid manufacturers.
EMA's Medical Device Regulation now captures software-driven firmness-adjustment algorithms as Class IIa medical devices. European hospital networks are demanding CE-marked technical documentation for connected mattresses entering tender processes. German procurement consortiums have responded by pre-qualifying only suppliers with notified-body certification for algorithmic pressure-relief functionality.
Direct-to-consumer channel control is displacing traditional retail mattress distribution in residential segments. Sleep Number Corporation's owned-channel strategy demonstrates how bypassing wholesale intermediaries preserves premium positioning and captures first-party biometric data. This pattern is most visible in United States metropolitan markets where showroom density and digital acquisition costs have reached equilibrium.
Smart Bed Mattress Market Segmentation
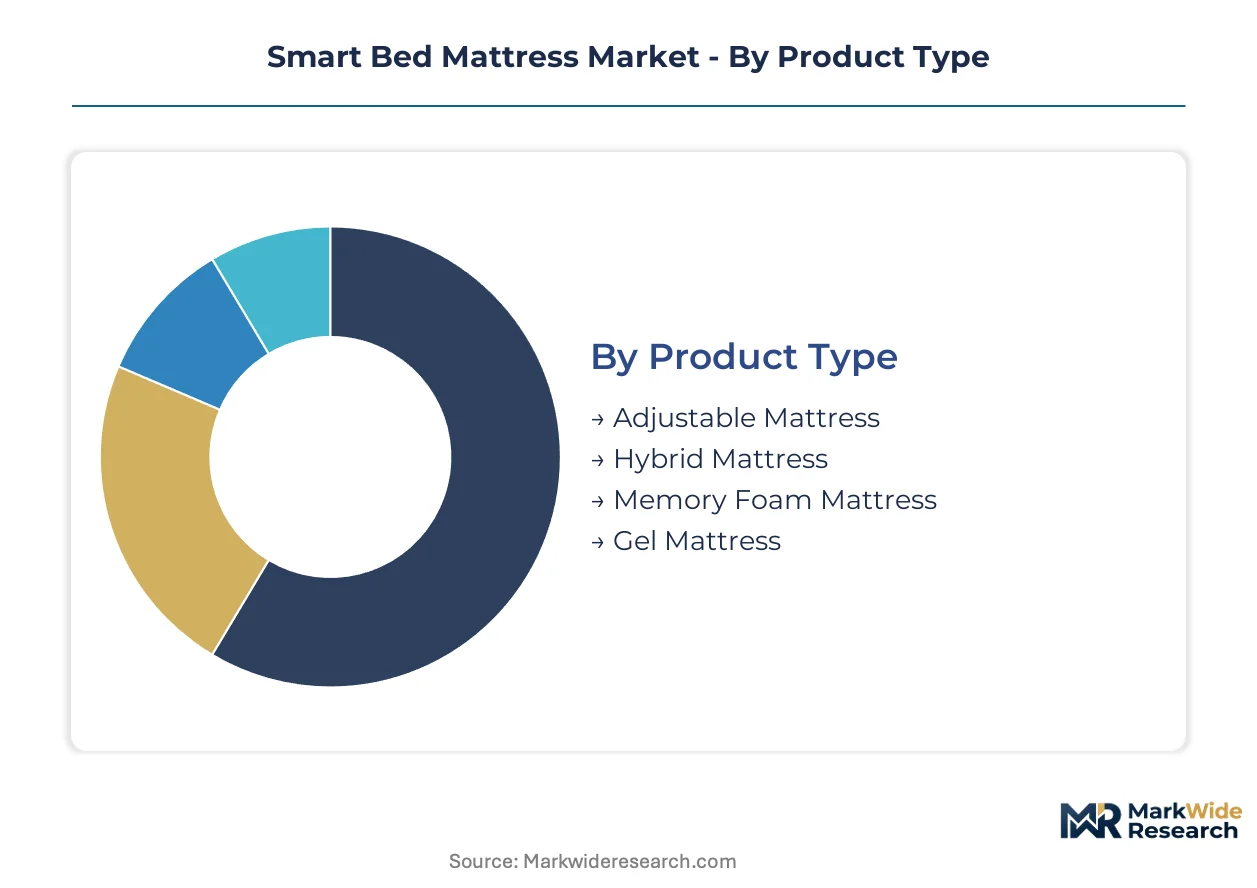
Smart bed mattress segmentation reveals divergent service intensity requirements across product architectures. Clinical-grade installations demand firmware-update subscriptions and sensor-calibration protocols that residential channels rarely match.
Product Type:
After-sales service intensity escalates sharply with electromechanical complexity and sensor-embedded architectures.
- Adjustable Mattress:Electromechanical actuators with air-chamber or segmented foam systems enable real-time firmness modulation through microprocessor-controlled pneumatic or electric motors. Healthcare facilities in the United States specify these for pressure-ulcer prevention protocols, driving preventive maintenance contracts and remote diagnostics integration.
- Hybrid Mattress:Layered construction combining innerspring coils with foam or latex comfort layers accommodates sensor-embedding without sacrificing traditional sleep-feel familiarity. Demand concentrates in German luxury hospitality chains upgrading guest-room infrastructure with discreet monitoring capabilities.
- Memory Foam Mattress:Viscoelastic polyurethane formulations face REACH flame-retardant compliance burdens and petrochemical input volatility.
- Gel Mattress:Thermally conductive gel-infused layers compete on temperature modulation in senior living facilities.
Adjustable mattress holds the largest share; momentum sits with hybrid mattress.
Technology:
Cost tier stratification separates premium sensor-integrated systems from basic electromechanical adjusters.
- Smart Sensors:Capacitive pressure-mapping arrays with sub-10 mmHg sensitivity woven into textile surfaces enable seamless infection-control compliance. United States hospital procurement teams specify these for patient-monitoring integration, with FDA 510(k) clearance extending replacement-cycle planning and validation-documentation obligations.
- Sleep Tracking:Biometric monitoring through accelerometry, heart-rate variability, and respiratory pattern analysis generates longitudinal health analytics. Residential demand clusters in direct-to-consumer channels where first-party data capture drives recurring software-license revenue.
- Temperature Regulation:Active heating-cooling elements or phase-change materials address thermoregulatory dysfunction in aging populations.
- Adjustable Firmness:Pneumatic or electromechanical firmness control without biometric feedback faces hardware-margin compression from component-cost volatility.
Sleep tracking commands premium pricing; smart sensors are climbing the fastest.
End User:
Application-specific certification requirements fragment procurement specifications across verticals.
- Residential:Direct-to-consumer channel control and showroom-based personalization dominate, with biometric data capture enabling subscription software revenue. Sleep Number Corporation's owned-channel strategy in United States metropolitan markets demonstrates premium positioning preservation through bypassing wholesale intermediaries.
- Healthcare Facilities:FDA Class II medical device classification mandates 510(k) clearance for patient-monitoring mattresses, filtering procurement to validated suppliers with software-validation documentation. United States hospital networks now require firmware patch-management protocols in tender specifications.
- Hospitality:German luxury chains drive pressure-mapping and thermal-modulation specifications for guest-experience differentiation.
- Senior Living:Assisted-living facilities prioritize gel-based temperature modulation for residents with thermoregulatory dysfunction.
Healthcare facilities generate the highest service attach rates; senior living shows steepest expansion trajectory.
Distribution Channel:
Customer-type concentration separates capital-light subscription models from traditional unit-sales economics.
- Direct Sales:Manufacturer-owned channels capture first-party biometric data and sustain premium positioning through controlled customer experience. United States metropolitan markets demonstrate equilibrium between showroom density and digital acquisition costs.
- Online Retail:E-commerce platforms aggregate comparison-shopping traffic for standardized adjustable and hybrid configurations without clinical-grade certification requirements.
- Specialty Stores:Mattress retail intermediaries face margin compression as direct-to-consumer brands displace wholesale relationships.
- Wholesale:Bulk procurement contracts for hospitality and healthcare channels concentrate volume with tiered pricing structures.
Direct sales captures margin premiums; online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's 510(k) clearance pathway for patient-monitoring mattresses has accelerated clinical-grade procurement across United States hospital networks. Germany's hospital consortiums and luxury hospitality chains are simultaneously upgrading sleep infrastructure, creating concentrated demand pools for pressure-mapping systems.
United States
Hospital procurement teams specify FDA-cleared sensor-embedded mattresses for pressure-ulcer prevention protocols. The 510(k) pathway mandates software-validation documentation that filters supplier pools to validated manufacturers. Boston-area medical device clusters host firmware development operations for acute-care monitoring systems.
Germany
Hospital networks and luxury hospitality chains drive dual-channel demand for thermal-modulation and pressure-mapping mattresses. EMA's Medical Device Regulation captures algorithm-driven firmness-adjustment as Class IIa devices, requiring notified-body certification. Bavarian textile-electronics manufacturers supply woven capacitive sensing surfaces for infection-control compliance.
Japan
Aging demographics and senior living facility expansion generate demand for thermoregulatory dysfunction solutions. PMDA software validation standards impose firmware-documentation burdens for connected health devices. Tokyo-Osaka corridor hosts pressure-mapping array integration operations for regional hospital procurement.
China
Domestic hospital network modernization and luxury hospitality development create parallel demand channels. NMPA medical device classification for patient-monitoring functionality shapes product registration timelines. Yangtze River Delta manufacturing clusters produce electromechanical actuator components for adjustable mattress systems.
United Kingdom
NHS procurement frameworks specify pressure-relief mattresses for acute care and community health settings. MHRA medical device regulations align with EMA standards for software-driven therapeutic functionality. London-Southeast corridor concentrates direct-to-consumer brand operations and digital sleep-health analytics development.
Smart Bed Mattress Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. Direct-to-consumer operators bypass wholesale intermediaries to capture first-party biometric data and sustain premium positioning. Clinical-grade suppliers anchor hospital procurement through regulatory certification depth. Technology licensors and component integrators occupy mid-tier positions. Dominant competitive moves include backward integration into sensor hardware manufacturing and subscription-based revenue model deployment.
Among United States-based operators, Sleep Number Corporation exemplifies channel-control archetypes through owned-retail footprint concentration. Stryker Corporation and Hill-Rom Holdings Inc. represent clinical-grade certification depth required for FDA-cleared hospital procurement. Japanese manufacturer Paramount Bed Co., Ltd. anchors Asia-Pacific regulatory positioning through PMDA-compliant product architectures.
| Leading Market Players |
|---|
| Sleep Number Corporation |
| Stryker Corporation |
| Hill-Rom Holdings Inc. |
| Paramount Bed Co., Ltd. |
| Arjo AB |
| Invacare Corporation |
| LINET Group SE |
| Tempur Sealy International Inc. |
| Eight Sleep |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in East Asian pressure-mapping array fabrication is compressing margins for North American and European mattress assemblers while elevating pricing power among textile-electronics hybrid manufacturers supplying FDA-cleared sensing surfaces. This utilization imbalance forces downstream buyers into longer-term offtake commitments to secure component allocation, reshaping procurement economics across clinical-grade product tiers.
Pricing Analysis
Certification level creates the primary spread between clinical-grade and residential product tiers, with FDA 510(k)-cleared mattresses commanding substantial premiums over uncertified adjustable systems. Three-tier pricing structure across premium, standard, and economy levels reflects software-validation depth, after-sales service bundling, and sensor calibration protocol inclusion. Pricing pressure stems from polyurethane foam input volatility and REACH compliance costs in European markets. Healthcare facilities exhibit lowest price sensitivity due to reimbursement-linked procurement frameworks, while residential direct-to-consumer channels face acute comparison-shopping pressure from online retail aggregators.
Supply Chain Analysis
Polyurethane foam feedstock draws from petrochemical complexes in the United States, Germany, and China, with specialty gel formulations concentrated in Japanese and South Korean chemical corridors. Capacitive pressure-mapping arrays rely on Taiwanese and Chinese textile-electronics manufacturing clusters, while electromechanical actuators source from precision motor suppliers in Japan and Germany. Single-source vulnerability in East Asian sensor module production creates procurement risk for Western assemblers seeking FDA-cleared component documentation. Distribution runs through manufacturer-direct channels for premium clinical and residential segments, with wholesale intermediaries retaining relevance in hospitality bulk procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is exiting a capital-investment trough as hospital infrastructure modernization cycles converge with senior living facility expansion, creating a cyclical recovery anchored in healthcare real estate deployment.
For Market Incumbents: Insulate firmware development capabilities through captive engineering teams in Boston-area medical device clusters, where FDA 510(k) clearance expertise concentrates. Deepen backward integration into sensor hardware manufacturing to reduce single-source exposure from Taiwanese textile-electronics suppliers. Prioritize subscription leasing model deployment across United States hospital networks to lock in recurring revenue streams before competitive entrants achieve regulatory certification parity.
For New Entrants and Emerging Players: Senior living thermal-modulation segments in Japan and Germany represent the most penetrable white-space opportunity, as aging demographics outpace incumbent capacity expansion. Target direct-to-consumer channel control in United States metropolitan markets where showroom density and digital acquisition costs have reached equilibrium, enabling premium positioning without wholesale margin dilution. Pursue white-label partnerships with Bavarian textile-electronics manufacturers to bypass sensor hardware development timelines.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among clinical-grade suppliers with FDA-cleared software-as-medical-device architectures and hospital system leasing contracts. Long-term viability favors acquisition targets combining notified-body certification depth with backward-integrated sensor manufacturing. Monitor EMA Medical Device Regulation enforcement intensity as the primary inflection indicator for European hospital procurement consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Unlocks United States hospital procurement channels and validates software-driven pressure-relief algorithms for reimbursement. |
| CE Marking Pathway | Enables EMA Medical Device Regulation compliance for algorithmic firmness-adjustment in German hospital consortium tenders. |
| Hospital System Partnership | Secures multi-year mattress-as-a-service contracts with firmware-update subscriptions and remote diagnostics integration. |
| Software Companion Development | Captures first-party biometric data for longitudinal sleep-health analytics and recurring license revenue in residential channels. |
| Reimbursement Strategy | Aligns pressure-ulcer prevention protocols with Medicare and private payer coverage criteria for clinical-grade installations. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearance databases, hospital procurement contract registries, and EMA Medical Device Regulation technical documentation. The analysis draws from structured interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and textile-electronics manufacturing specialists. Secondary validation incorporates SEC filings from publicly traded mattress manufacturers, customs records for polyurethane foam and sensor component trade flows, and CMS Medicare reimbursement data for pressure-relief device categories. Bottom-up segment sizing triangulates against top-down macroeconomic indicators.
Forecast inputs include electromechanical component cost trajectories, regulatory certification timeline assumptions, and healthcare capital expenditure patterns across the analysis window. The analytical framework models product type segmentation by after-sales service intensity, technology tier by software-license attach rates, end user vertical by certification requirements, and distribution channel by customer-type concentration. CAGRs derive from regression analysis of historical procurement volumes against demographic and infrastructure investment drivers. Industry-specific inputs encompass REACH flame-retardant compliance cost evolution and Bluetooth-to-Wi-Fi protocol migration timelines.
Practitioners should monitor FDA cybersecurity guidance updates, EMA notified-body capacity constraints, and East Asian sensor manufacturing utilization rates for early signals of forecast revision. Cross-checking against hospital procurement database benchmarks and GPO contract award volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Door Stopper Market
Homecare and Decor
Global Wallpaper Market
Homecare and Decor
India Sustainable Home Decor Market
Homecare and Decor
Middle East Revolving Doors Market
Homecare and Decor
Composite Doors and Windows Market
Homecare and Decor
Garden Sheds Market
Homecare and Decor
Asia-Pacific Interior Doors Market
Homecare and Decor
Interior Design Services Market
Homecare and Decor
Fragrant Drawer Liners Market
Homecare and Decor
Hearth Market
Homecare and Decor
US Wallcovering Market
Homecare and Decor
Terracotta Pots Market
Homecare and Decor
Wall Decor Market
Homecare and Decor
Mattresses and Accessories Market
Homecare and Decor
MDF Decorative Overlays Market
Homecare and Decor
India Wallpapers Market