
 India Interior Design Market | 2026-2036
India Interior Design Market Size, Share, and Industry Trends Forecast 2026-2036
India Interior Design Market Outlook
Gujarat's furniture manufacturing corridor is reshaping supply dynamics for interior fit-outs across western India. Livspace leverages its technology platform to standardize modular kitchen deliveries across tier-1 and tier-2 cities. Design Cafe anchors its growth in Bangalore's startup ecosystem with full-stack residential renovation services. Studio Lotus differentiates through sustainable material sourcing and heritage restoration expertise.
Interior design encompasses the planning, specification, and coordination of spatial layouts, surface finishes, lighting systems, and built-in furnishings to optimize functional performance and aesthetic outcomes in enclosed environments. The discipline integrates structural constraints with ergonomic parameters, material science, and visual composition to serve residential, commercial, and institutional occupants. Residential design dominates service-type revenue as urban nuclear families seek turnkey solutions for compact apartments in dense metros. Hospitality design occupies the fastest-expanding margin pool as boutique hotel chains and co-living operators commission differentiated spatial identities. Modern and minimalist styles are displacing ornate traditional formats among corporate end users prioritizing maintenance efficiency and flexible floor plates.
BIS certification requirements for plywood, laminates, and fire-retardant fabrics govern material sourcing and installation standards across Indian states. GRIHA and IGBC green building ratings are mandating low-VOC coatings, recycled content thresholds, and daylight optimization in commercial and institutional projects. State-level RERA enforcement in Maharashtra, Karnataka, and Tamil Nadu is formalizing developer handover standards for interior specifications. Stakeholders must monitor evolving state-level building code harmonization and the pace of green certification adoption in tier-2 city developments.
Market Dynamics
India's interior design sector is reconfiguring around BIS certification mandates for plywood and laminates, which are compressing informal supply channels and elevating compliant manufacturers into preferred vendor status for institutional buyers.
Growth Catalysts
- RERA Handover Standards:Maharashtra, Karnataka, and Tamil Nadu enforcement is formalizing interior specification documentation, creating recurring demand for certified documentation and inspection services from developers.
- GRIHA Rating Penetration:Commercial developers pursuing green building certification are mandating low-VOC coatings and daylight-optimized layouts, pulling specification-grade materials into mainstream projects.
- Nuclear Family Density:Urban household compaction in Mumbai and Bangalore is generating turnkey renovation demand as time-constrained professionals outsource complete fit-out coordination.
Market Restraints
- Plywood Price Volatility:Import dependency on Malaysian and Indonesian veneer logs exposes finished goods manufacturers to currency fluctuation and shipping cost spikes.
- Artisan Labor Scarcity:Kerala's premium woodwork segment faces generational skill attrition as younger workers migrate to manufacturing employment in Gujarat's furniture corridors.
- Formalization Friction:Unorganized contractors operating below GST thresholds undercut compliant firms on residential renovation bids, compressing margin recovery for tax-registered service providers.
Strategic Opportunities
- Tier-2 City Expansion:Ahmedabad, Pune, and Hyderabad present underpenetrated demand for modular kitchen standardization as organized retail formats establish presence.
- Co-Living Spatial Identity:Purpose-built rental housing operators are commissioning differentiated interior concepts to reduce tenant churn and command rental premiums.
- Heritage Restoration Incentives:State tourism department grants for adaptive reuse of colonial structures are creating specialized demand for conservation-grade material sourcing and craftsmanship.
Industry Challenges
- Project Management Talent Gap:Scarcity of professionals capable of coordinating MEP integration with finish schedules is delaying handovers and eroding developer margins.
- Certification Timeline Compression:GRIHA documentation requirements are extending pre-construction phases, straining working capital for design-build firms operating on milestone payments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Interior Design Market |
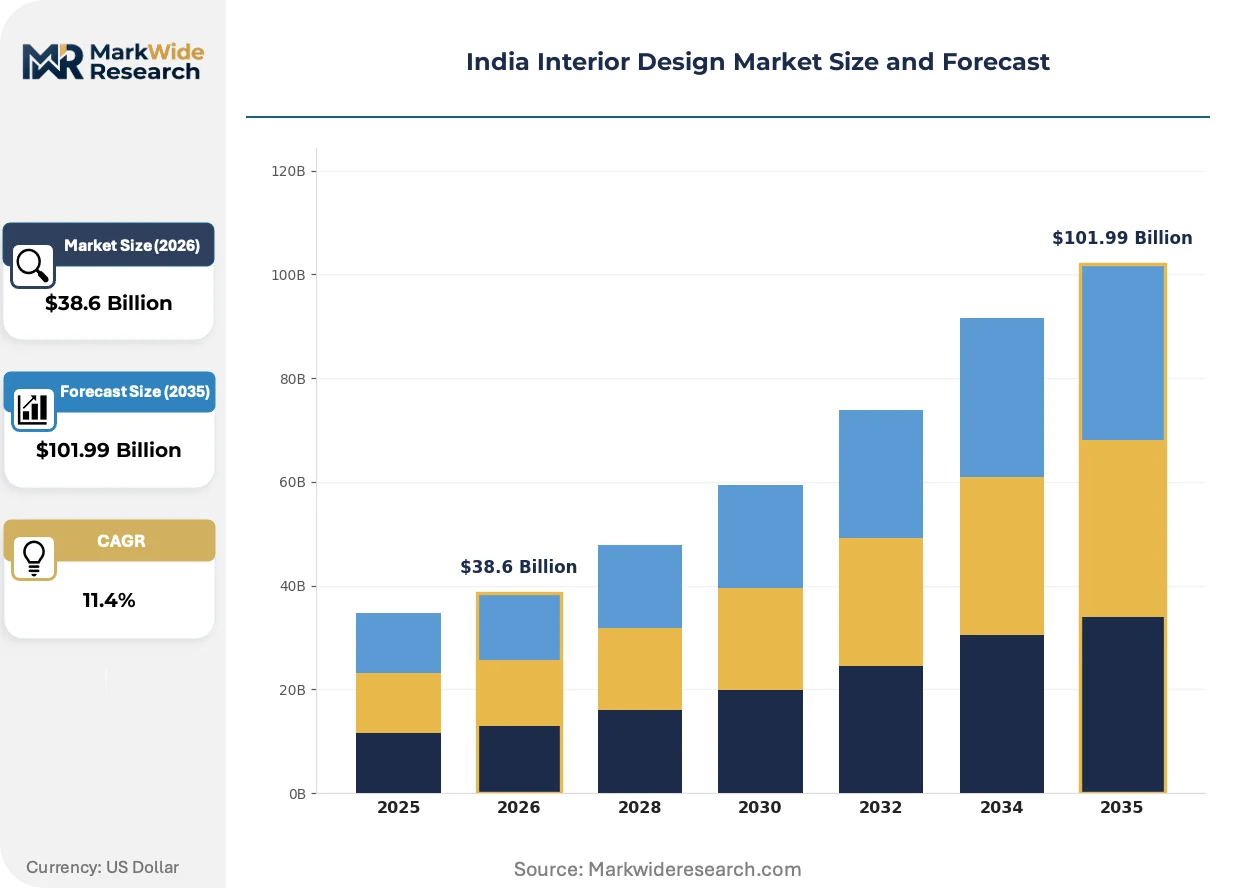
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $101.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Residential Design, Commercial Design, Institutional Spaces, Hospitality Design End User: Homeowners, Corporates, Educational Institutions, Hotel Chains Style: Modern, Traditional, Minimalist, Rustic Material: Wood, Metal, Glass, Fabric |
| Companies Covered | Design Cafe, The BNK Group, Livspace, Bonito Designs, D’LIFE Interiors, HomeLane, Talati & Partners, SKF Contractor, Studio Lotus, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Interior Design Market Strategic Shifts
Digital specification tools and parametric design software are compressing the concept-to-execution cycle, while regulatory tightening on material emissions is filtering vendor panels faster than procurement departments can requalify suppliers.
Building Information Modeling (BIM) integration is rendering obsolete two-dimensional AutoCAD workflows for commercial interior documentation. Large-format retail developers and hospital chains are mandating clash-detection protocols before construction mobilization. This technology shift is compressing change-order incidence and elevating firms with in-house modeling capability into preferred contractor status.
BIS certification enforcement for fire-retardant fabrics and structural plywood is eliminating uncertified imports from project specifications. The Bureau of Indian Standards laboratory testing backlog is creating supply bottlenecks for boutique hotel developers with fixed opening dates. Hospitality projects in Goa and Rajasthan are responding by pre-qualifying domestic manufacturers with established testing relationships.
Turnkey service bundling is consolidating previously fragmented vendor relationships into single-point accountability contracts. Nuclear families in Bangalore and Mumbai are displacing material-plus-labor procurement with fixed-price renovation packages. This preference consolidation is most visible in the modular kitchen segment, where technology-enabled platforms are capturing specification authority from traditional carpentry networks.
India Interior Design Market Segmentation
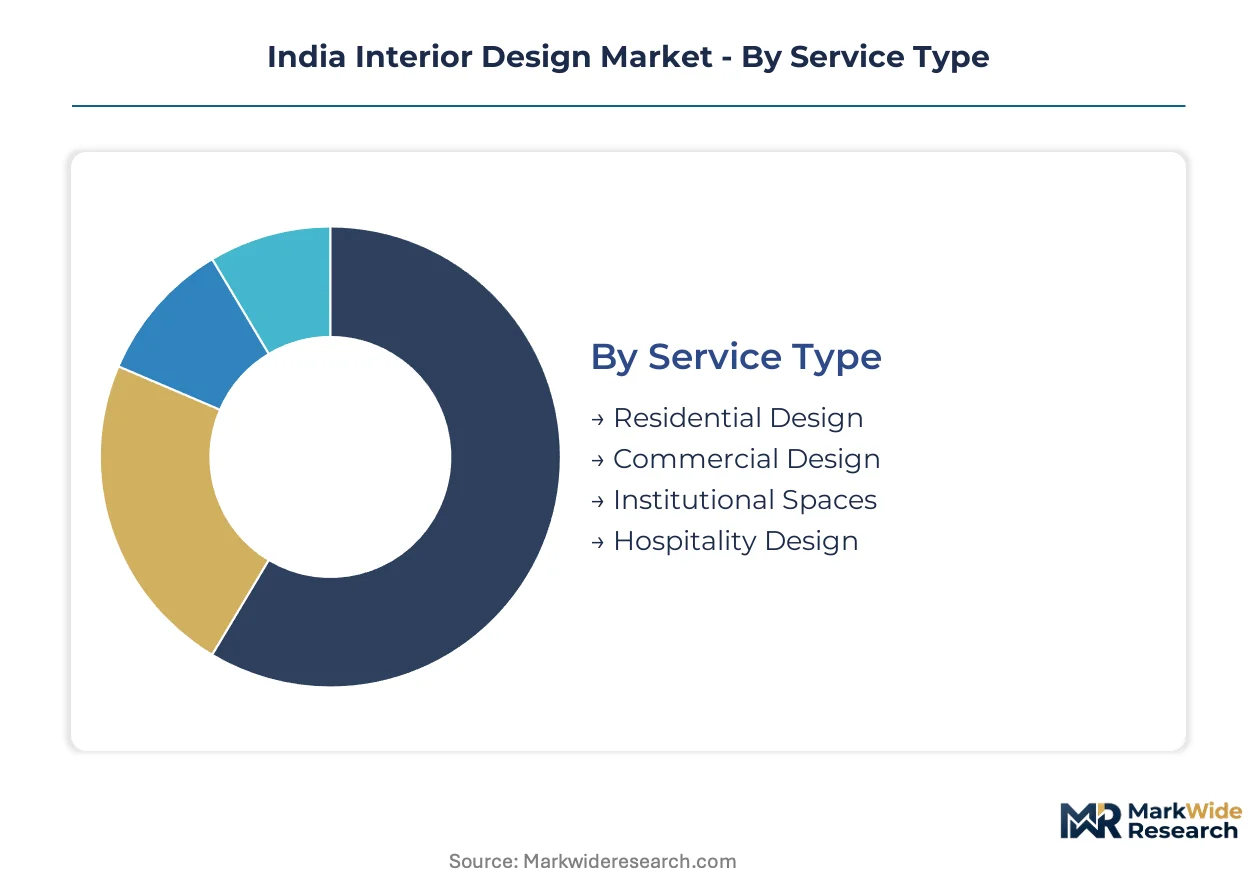
Interior design in India fragments across service delivery models, end-user procurement maturity, aesthetic positioning, and material specification tiers. Each dimension carries distinct margin profiles and regulatory exposure that shape vendor selection and project economics.
Service Type:
Application focus determines project scale, documentation burden, and recurring revenue potential for design firms.
- Residential Design:Turnkey fit-out coordination for compact urban apartments dominates service revenue. Mumbai and Bangalore nuclear families drive specification consolidation as time-constrained professionals outsource complete execution to single-point contractors.
- Hospitality Design:Boutique hotel chains and co-living operators commission differentiated spatial identities to reduce tenant churn. Goa and Rajasthan developers face BIS laboratory testing backlogs for fire-retardant fabrics, forcing pre-qualification of domestic manufacturers with established certification relationships.
- Commercial Design:Corporate fit-outs prioritize maintenance efficiency and flexible floor plates over ornate formats. Modern and minimalist styles displace traditional aesthetics as lease structures shorten.
- Institutional Spaces:Healthcare and educational facilities mandate GRIHA-compliant low-VOC coatings and daylight-optimized layouts. Documentation requirements extend pre-construction phases, straining working capital for design-build firms on milestone payments.
Residential design commands the established base. The steepest expansion runs through hospitality design.
End User:
Customer procurement maturity separates price-sensitive fragmented demand from specification-grade institutional purchasing.
- Corporates:Large-format retail developers and hospital chains mandate BIM clash-detection protocols before construction mobilization. In-house modeling capability elevates firms into preferred contractor status.
- Homeowners:Technology-enabled platforms capture specification authority from traditional carpentry networks. Fixed-price renovation packages displace material-plus-labor procurement in Bangalore and Mumbai.
- Hotel Chains:Purpose-built rental housing operators commission differentiated interior concepts to command rental premiums. Fixed opening dates create supply bottlenecks when BIS certification timelines compress.
- Educational Institutions:State-level RERA enforcement in Maharashtra, Karnataka, and Tamil Nadu formalizes interior specification documentation. Recurring demand emerges for certified documentation and inspection services.
Homeowners anchor volume concentration. Corporates generate the fastest margin expansion.
Style:
Aesthetic positioning correlates with maintenance economics and generational preference shifts among urban consumers.
- Modern:Clean lines and functional minimalism dominate corporate end-user specifications. Maintenance efficiency drives selection over ornate alternatives.
- Minimalist:Reduced visual complexity aligns with compact apartment spatial constraints. Young professionals in dense metros favor this format for perceived spaciousness.
- Traditional:Ornate woodwork and heritage motifs concentrate in Kerala's artisan-led premium segment. Generational skill attrition threatens supply continuity as younger workers migrate to Gujarat manufacturing employment.
- Rustic:Natural material exposure and weathered finishes appear in boutique hospitality adaptive reuse projects. State tourism grants for colonial structure restoration create specialized demand.
Modern styling holds the mainstream position. Minimalist applications are climbing the fastest among urban nuclear families.
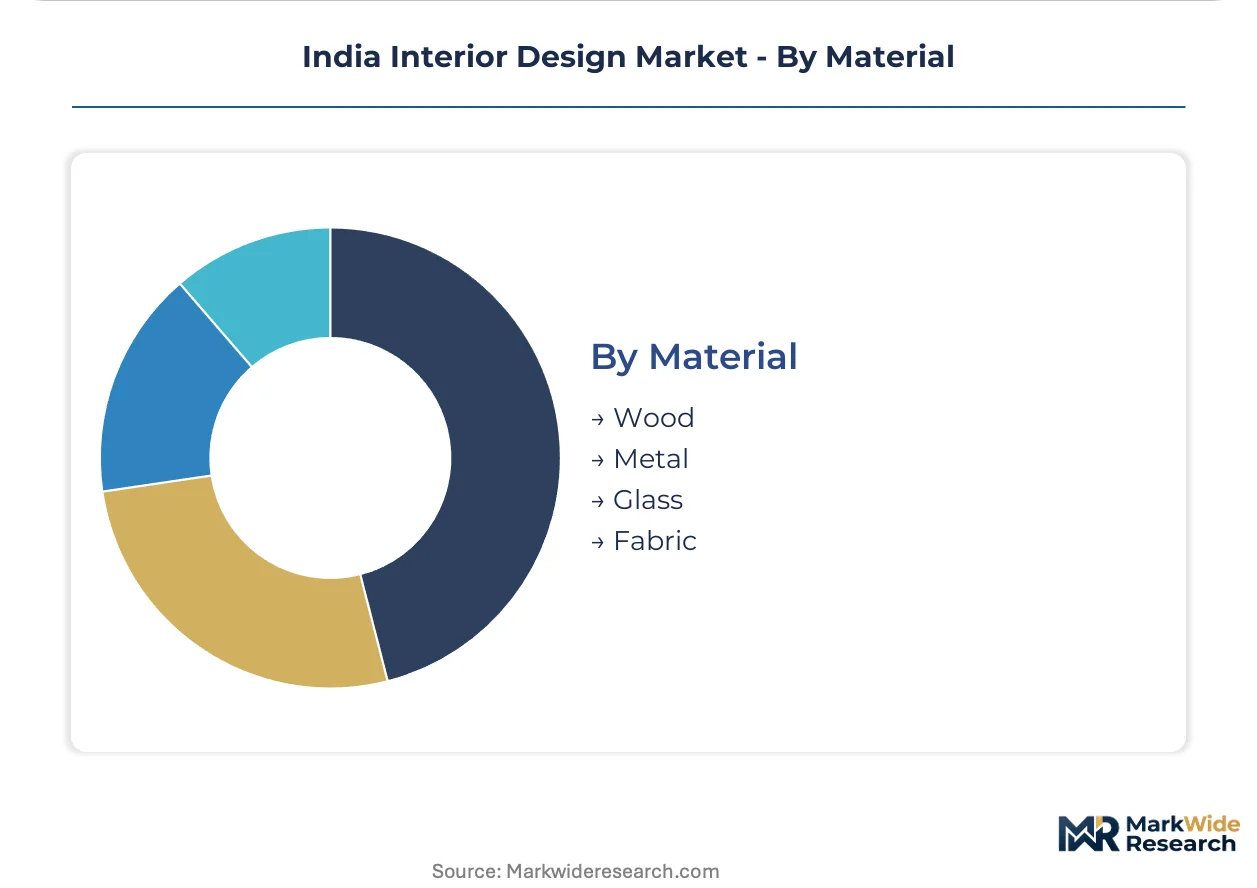
Material:
Specification grade separates compliant institutional supply from informal residential procurement channels.
- Wood:BIS certification mandates for plywood and structural timber compress informal supply channels. Import dependency on Malaysian and Indonesian veneer logs exposes manufacturers to currency fluctuation and shipping cost spikes.
- Metal:Fire-retardant and structural steel specifications govern commercial and institutional safety compliance. Gujarat furniture manufacturing clusters integrate metal fabrication with wood finishing capabilities.
- Glass:Daylight optimization requirements under GRIHA ratings pull specification-grade glazing into mainstream commercial projects. Large-format retail developers mandate performance testing documentation.
- Fabric:Fire-retardant textile certification eliminates uncertified imports from hospitality specifications. Boutique hotel developers in Goa and Rajasthan respond by pre-qualifying domestic manufacturers with established BIS testing relationships.
Wood retains the deepest specification history. Metal and glass composites are gaining share fastest in commercial and institutional segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's furniture manufacturing corridor and Kerala's artisan networks anchor supply-side capacity for interior fit-outs across western and southern India. Maharashtra, Karnataka, and Tamil Nadu concentrate demand from luxury residential and commercial developers. State-level regulatory enforcement and green building mandates are redistributing competitive advantage toward compliant regional clusters.
Maharashtra
Mumbai's luxury apartment developers are expanding fit-out budgets for branded residences as nuclear families seek turnkey solutions. State-level RERA enforcement formalizes interior specification documentation, creating recurring demand for certified inspection services. The Mumbai-Pune corridor concentrates technology-enabled platforms standardizing modular kitchen deliveries.
Gujarat
Ahmedabad and Surat furniture manufacturing clusters are reshaping supply dynamics for interior fit-outs across western India. BIS certification mandates for plywood and laminates compress informal supply channels, elevating compliant manufacturers into preferred vendor status. Gujarat's integrated metal fabrication and wood finishing capabilities capture specification-grade commercial project demand.
Karnataka
Bangalore's startup ecosystem generates full-stack residential renovation demand from time-constrained technology professionals. State RERA enforcement mandates developer handover standards for interior specifications. The city's co-living operators commission differentiated spatial identities to reduce tenant churn and command rental premiums.
Kerala
Kochi and Thiruvananthapuram anchor India's artisan-led premium woodwork segment for heritage restoration and luxury residential projects. Generational skill attrition threatens supply continuity as younger workers migrate to manufacturing employment in Gujarat. State tourism department grants for adaptive reuse of colonial structures create specialized demand for conservation-grade craftsmanship.
Tamil Nadu
Chennai's commercial developers pursuing GRIHA certification mandate low-VOC coatings and daylight-optimized layouts. State-level RERA enforcement formalizes interior specification documentation for institutional buyers. The city's healthcare and educational facilities extend pre-construction phases with green building documentation requirements.
India Interior Design Market Competitive Environment
Technology platforms and full-stack service providers split the market between standardized modular delivery and bespoke renovation coordination. The vendor base concentrates around three strategic archetypes: technology-enabled aggregators, artisan-anchored premium specialists, and design-build generalists. Competitive moves center on geographic expansion into tier-2 cities and turnkey service bundling to capture specification authority from fragmented carpentry networks.
Within the technology-aggregator tier, Livspace and HomeLane exemplify platform-driven standardization of modular kitchen and residential fit-out delivery. Design Cafe occupies a position bridging technology enablement with full-stack project execution for Bangalore's professional demographic. Studio Lotus anchors the premium-specialist archetype through sustainable material sourcing and heritage restoration expertise, representing differentiation strategies resistant to platform commoditization.
| Leading Market Players |
|---|
| Design Cafe |
| The BNK Group |
| Livspace |
| Bonito Designs |
| D'LIFE Interiors |
| HomeLane |
| Talati & Partners |
| SKF Contractor |
| Studio Lotus |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Gujarat's furniture manufacturing corridor is compressing supplier margins while elevating compliant manufacturers into preferred vendor status for institutional buyers. This utilization dynamic feeds directly into pricing posture, as BIS-certified producers command premium positioning while informal operators undercut on residential renovation bids.
Pricing Analysis
BIS certification mandates dictate the pricing tier structure across plywood, laminates, and fire-retardant fabric segments. Three-tier pricing separates GRIHA-compliant specification-grade materials from standard BIS-certified products and uncertified economy alternatives. Price differentiation hinges on certification level and volume scale, with bulk procurement by Mumbai luxury developers securing favorable terms. Cost compression in the economy tier is intensifying because unorganized contractors operating below GST thresholds undercut compliant firms. Homeowners in tier-1 cities show highest price sensitivity, while corporate and hospitality buyers prioritize certification compliance over cost.
Supply Chain Analysis
Extended payment terms from large-format retail developers and hospital chains are straining working capital for design-build firms operating on milestone receipts. Geographic supply concentration centers on India, Malaysia, and Indonesia, with veneer log imports feeding Gujarat's manufacturing clusters. Raw material dependencies rest on Malaysian and Indonesian timber, domestic plywood processing, and imported fire-retardant chemical treatments. Single-source vulnerability runs through the BIS laboratory testing backlog, which bottlenecks certified material availability. Distribution runs through technology-enabled platforms capturing specification authority alongside traditional carpentry networks in tier-2 cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The interior design sector is approaching a platform-economics inflection as technology-enabled aggregators consolidate fragmented vendor relationships into single-point accountability contracts. Interoperability between BIM documentation systems and procurement platforms is reshaping competitive advantage toward firms with integrated digital capabilities.
For Market Incumbents: Build certification moats through accelerated BIS testing relationships and GRIHA documentation expertise to defend against technology platforms commoditizing modular kitchen delivery. Incumbents should deepen backward integration into plywood manufacturing to control input costs amid currency volatility. Channel control through exclusive retail partnerships in tier-2 cities represents a second defensive lever against aggregator expansion.
For New Entrants and Emerging Players: Ahmedabad, Pune, and Hyderabad present underpenetrated demand for standardized modular kitchen delivery as organized retail formats establish presence. Heritage restoration services for colonial adaptive reuse projects offer a specialized white-space target with grant-backed demand visibility. A go-to-market angle anchored in co-living spatial identity design addresses purpose-built rental housing operators seeking tenant retention through differentiated interiors.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because regulatory formalization is systematically eliminating informal operators and elevating compliant regional platforms. Acquisition targets should emphasize design-build firms with established BIS manufacturer relationships and in-house BIM capability. The signal to watch is state-level RERA enforcement harmonization, which would accelerate specification-grade material adoption and compress informal market share.
| Strategic Initiative | Industry Significance |
|---|---|
| Technology Platform Integration | Livspace and HomeLane demonstrate how digital specification tools capture market share from traditional carpentry networks. |
| Certification Investment | BIS laboratory testing relationships eliminate supply bottlenecks for boutique hotel developers with fixed opening dates. |
| Tier-2 Geographic Expansion | Ahmedabad and Hyderabad present underpenetrated demand for modular kitchen standardization as retail formats mature. |
| Heritage Restoration Capability | Studio Lotus anchors premium positioning through conservation-grade craftsmanship for state tourism department grants. |
| Turnkey Service Bundling | Fixed-price renovation packages displace material-plus-labor procurement among Bangalore and Mumbai nuclear families. |
Study Parameters
A spread of perspectives from interior design firm principals, plywood manufacturing procurement leads, commercial developer project managers, and BIS certification specialists converged on the working assumptions driving this analysis. Primary interviews with these stakeholders were cross-referenced against secondary validation from RERA compliance documentation, GRIHA rating databases, customs import records for Malaysian and Indonesian veneer logs, and state-level building code harmonization notices. Bottom-up project pipeline analysis and top-down sectoral expenditure estimates were triangulated to establish market sizing.
Demand-supply balance dynamics across residential renovation, hospitality fit-out, and commercial interior segments anchored the analytical framework over the projection horizon. Segmentation dimensions modeled include service type, end-user procurement maturity, aesthetic positioning, and material specification tier alongside regional regulatory cluster intensity. CAGRs were derived from trend extrapolation of project commencement data and certification penetration rates. Industry-specific forecast inputs incorporated co-living operator expansion plans and state tourism department heritage restoration grant allocations.
The forecast holds incumbent behavior within observed patterns; aggressive platform expansion by technology aggregators or accelerated BIS enforcement timelines would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
China Sustainable Home Decor Market
Homecare and Decor
Global Wallpaper Market
Homecare and Decor
Europe Commercial Blinds and Shades Market
Homecare and Decor
Louvre Windows Market
Homecare and Decor
India Wall Decor Market
Homecare and Decor
India Furniture Hardware Market
Homecare and Decor
Christmas Tree Market
Homecare and Decor
North America Sustainable Home Decor Market
Homecare and Decor
United States Wall Coverings Market
Homecare and Decor
Bamboo Panels Market
Homecare and Decor
Europe Mattress Market
Homecare and Decor
Wall Decor Market
Homecare and Decor
Asia-Pacific Wall Covering Market
Homecare and Decor
Pillow Cases Market
Homecare and Decor
Smart Bed Mattress Market
Homecare and Decor
Wall Covering Products Market