
 North America Sustainable Home Decor Market | 2026-2036
North America Sustainable Home Decor Market Size, Share, and Industry Trends Forecast 2026-2036
North America Sustainable Home Decor Market Analytics
Canadian certified-wood producers is expanding production capacity for FSC-certified furniture to serve cross-border demand. West Elm leverages its in-house sustainable sourcing program to control material provenance across upholstered goods. MillerKnoll sustains a leadership position in commercial-grade eco-furnishings through its Living Office sustainability framework. The Citizenry differentiates by anchoring artisan partnerships in Oaxaca and Rajasthan for direct-trade home accessories.
Sustainable home decor encompasses furnishings, lighting, textiles, and accessories manufactured with certified renewable, recycled, or low-emission materials such as FSC-certified hardwood, GOTS organic cotton, and water-based finishes, serving residential and commercial spaces seeking verified environmental performance. Furniture dominates product-type revenue due to higher unit values and replacement cycles, while textiles represent the fastest-expanding category as consumers prioritize organic bedding and non-toxic upholstery. Bamboo and recycled metal lead material adoption, with organic cotton gaining share in soft goods as supply chain transparency improves.
EPA Safer Choice standards, California Air Resources Board formaldehyde regulations, and FTC Green Guides collectively mandate substantiated environmental claims and restrict volatile organic compound thresholds in finished goods. Health Canada and the USDA BioPreferred program add cross-border compliance layers for biobased content certification. Stakeholders must monitor evolving state-level extended producer responsibility proposals and third-party certification fragmentation to maintain market access and consumer trust.
Market Dynamics
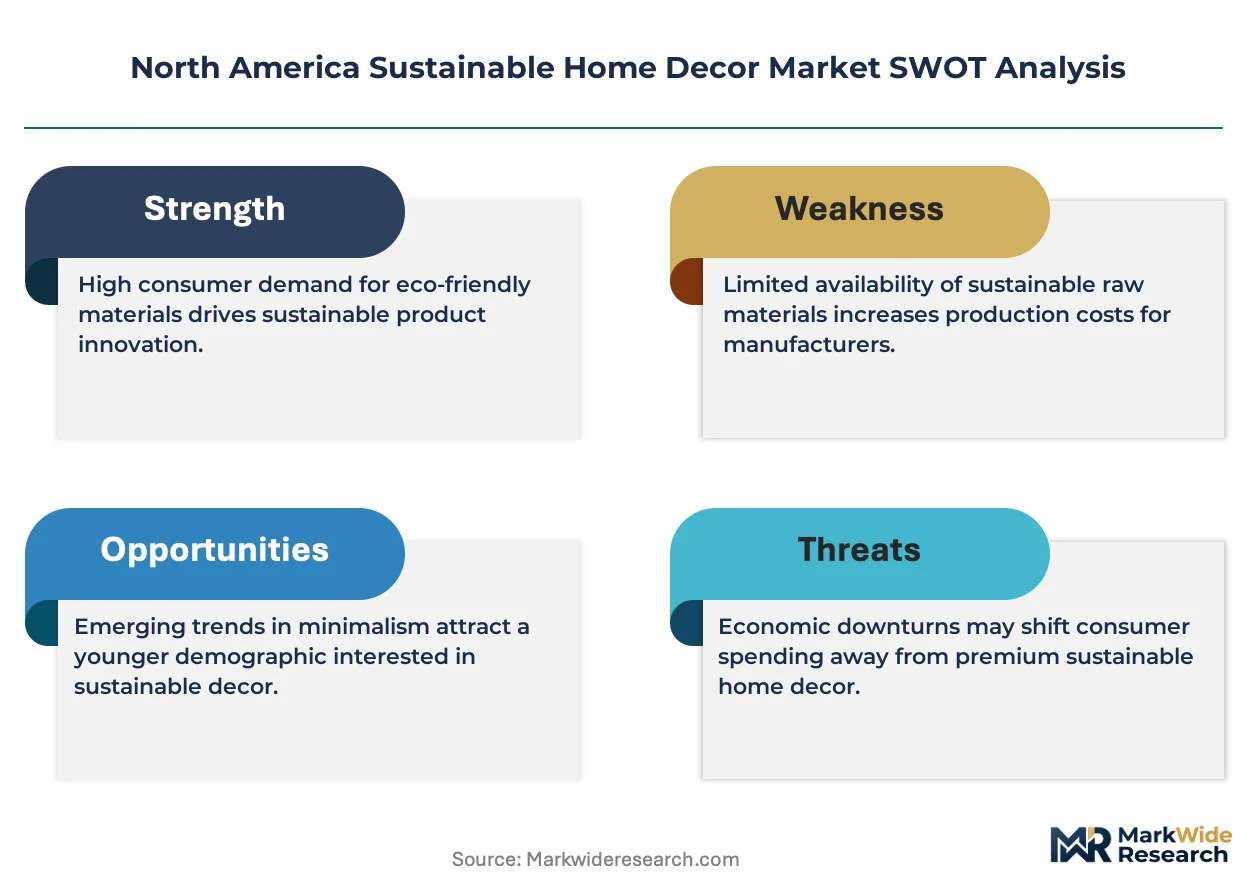
California's formaldehyde emission standards and EPA Safer Choice labeling requirements are compressing material sourcing options while concentrating supplier qualification costs among larger manufacturers with dedicated compliance infrastructure.
Growth Catalysts
- EPA Safer Choice Certification:Federal labeling for low-VOC finishes accelerates retailer shelf placement and consumer recognition across big-box channels.
- Millennial Homeownership Cycles:First-time buyers in the Pacific Northwest prioritize FSC-certified hardwood furnishings during initial household formation.
- Municipal Green Building Codes:Vancouver and Portland mandate recycled content thresholds in public procurement, creating anchored demand for certified textiles.
Market Restraints
- FSC-Certified Timber Supply Concentration:British Columbia and Pacific Northwest sawmill capacity constraints create input volatility for solid wood furniture producers.
- Cross-Border Certification Friction:Divergent USDA BioPreferred and Health Canada biobased content thresholds force dual testing protocols for unified North American product lines.
- Natural Fiber Performance Limitations:Organic cotton and hemp textiles exhibit lower abrasion resistance versus synthetic alternatives, restricting commercial upholstery applications.
Strategic Opportunities
- Extended Producer Responsibility Expansion:Ontario and Quebec legislative proposals for furniture take-back programs create circular economy service revenue streams.
- Direct-to-Consumer Artisan Platforms:Digital marketplaces bypass traditional wholesale markups while capturing margin from provenance storytelling.
- Water-Based Finish Chemistry Convergence:UV-curable and bio-based coating technologies reduce drying energy and eliminate solvent handling infrastructure.
Industry Challenges
- Third-Party Certification Fragmentation:Competing standards from FSC, SFI, and PEFC create supplier audit duplication and consumer confusion at point of sale.
- Skilled Upholstery Labor Scarcity:Traditional craft training programs in North Carolina and Mississippi have contracted, constraining domestic production scaling for certified organic furniture lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Sustainable Home Decor Market |
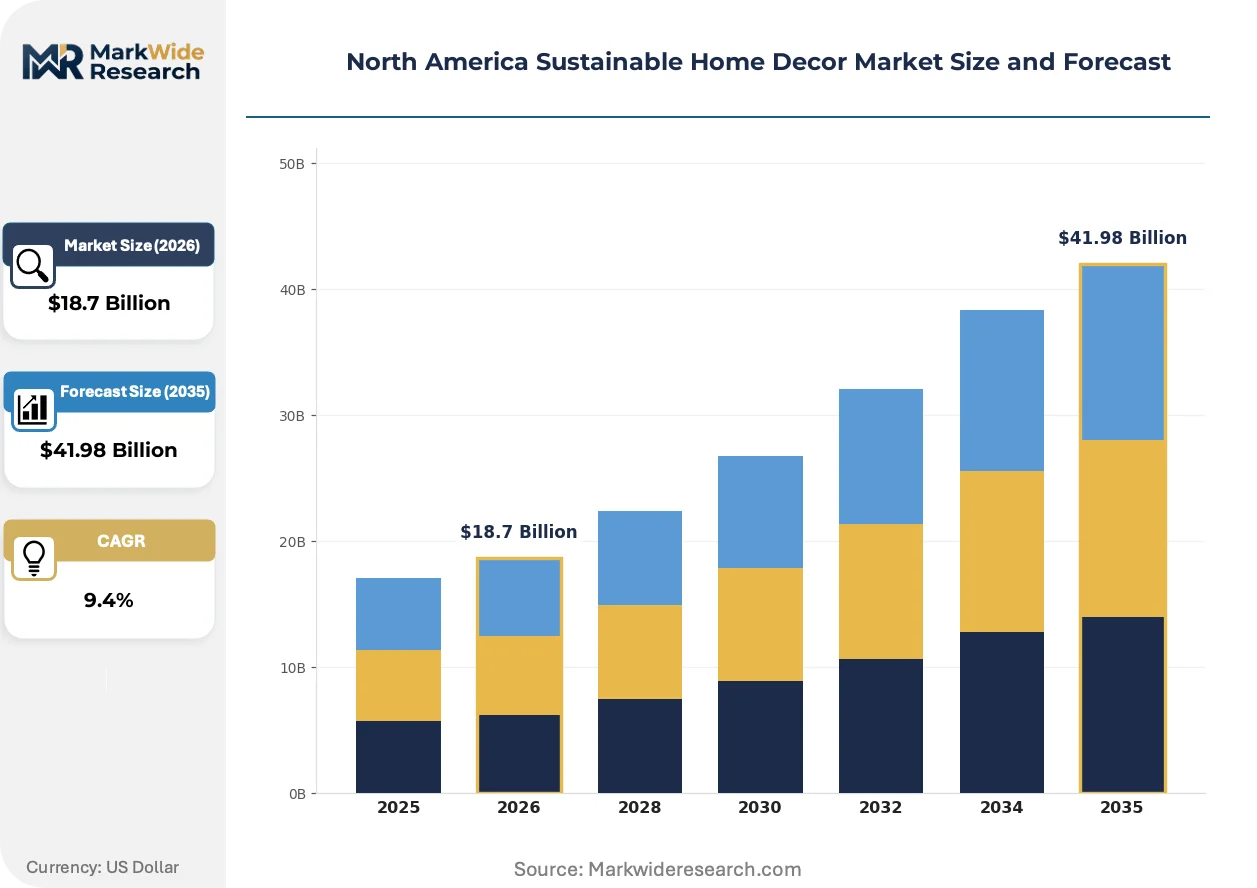
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Furniture, Lighting, Textiles, Accessories Material: Bamboo, Recycled Metal, Organic Cotton, Glass End User: Retail Consumers, Hospitality, Eco-Friendly Businesses, Interior Designers Distribution Channel: Online Stores, Specialty Retailers, Home Improvement Chains, Marketplaces |
| Companies Covered | Quince, Woven, The Citizenry, GOODEE, House of Leon, West Elm, Ten Thousand Villages, Uncommon Goods, MillerKnoll, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Sustainable Home Decor Market Evolving Landscape
Material provenance verification and finish chemistry transparency are restructuring competitive advantage away from styling alone toward documented supply chain accountability.
Bio-based polyurethane foam derived from algae and plant oils is integrating into cushioning applications across mid-market upholstery lines. West Coast furniture retailers are specifying these foams for bedroom and living room collections. This substitution is integrating renewable feedstocks into supply chains previously dependent on petroleum-derived inputs.
California Air Resources Board Phase 2 formaldehyde standards are tightening emission thresholds for composite wood products used in case goods and shelving. Manufacturers serving the California market must reformulate adhesives or source CARB-compliant substrates. Upholstered furniture with exposed engineered wood frames faces the steepest compliance redesign requirements.
Certification-driven purchasing is compressing traditional brand loyalty cycles as buyers prioritize visible eco-labels over heritage positioning. Independent specialty retailers in Austin and Denver are curating exclusively certified collections, displacing conventional mixed-assortment merchandising. This pattern concentrates most intensely among Gen Z renters furnishing first apartments in urban coastal markets.
North America Sustainable Home Decor Market Segmentation
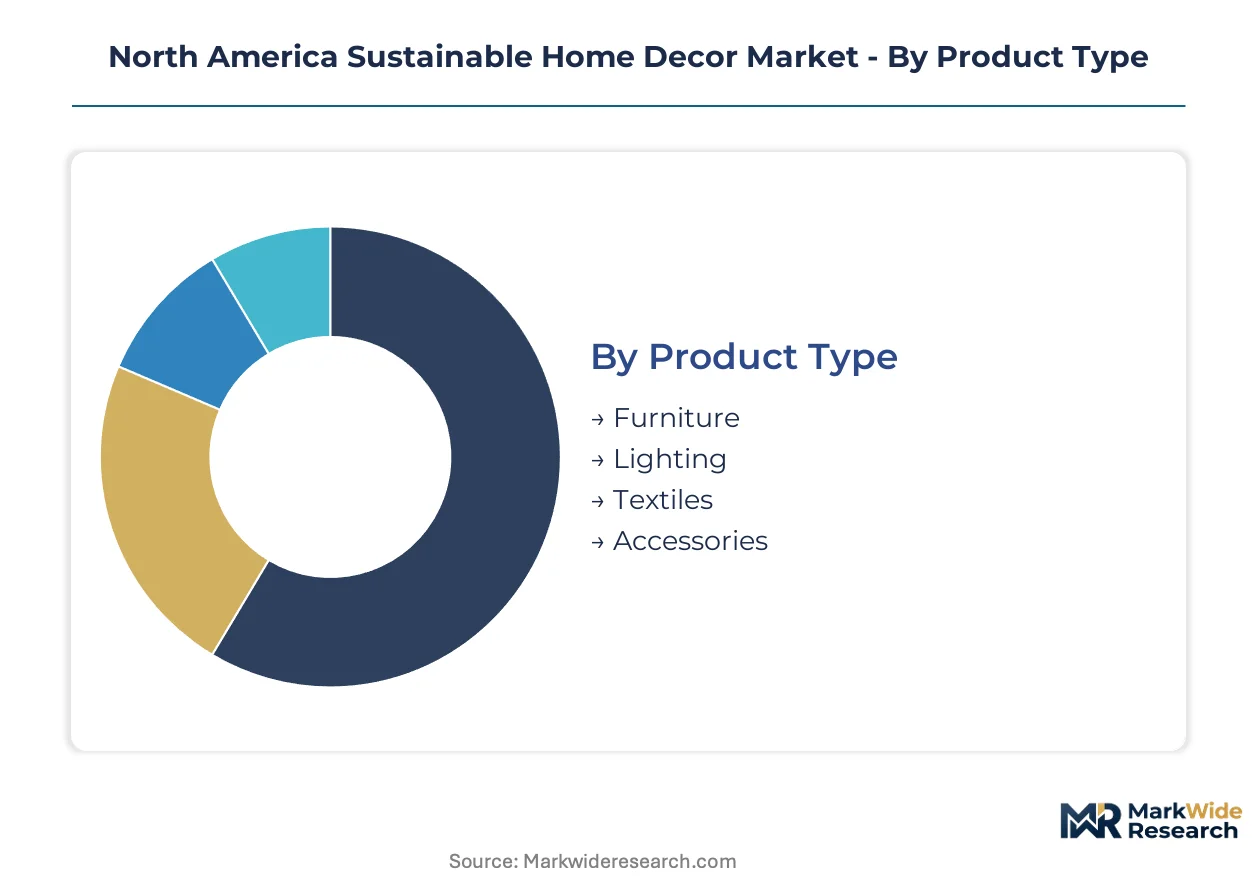
Segmentation in sustainable home decor reveals divergent purchasing logics across buyer types and material preferences. Product mix and channel selection vary sharply between first-time millennial homeowners and commercial hospitality specifiers. Understanding these fault lines allows manufacturers to align certification investments with actual decision criteria rather than assumed green sentiment.
Product Type:
Buyers in this category sort by replacement cycle length and unit economics, not environmental concern alone.
- Furniture:Solid wood and upholstered pieces carry the highest unit values and longest replacement horizons in residential settings. Pacific Northwest municipalities specify FSC-certified case goods for public procurement, anchoring commercial demand independent of consumer trends.
- Textiles:Organic cotton bedding and non-toxic upholstery fabrics are expanding most quickly as supply chain transparency improves and California formaldehyde standards tighten. First-time renters in Austin and Denver prioritize visible GOTS certification over heritage brand names.
- Lighting:LED-integrated fixtures with recycled metal housings serve energy code compliance and aesthetic goals simultaneously.
- Accessories:Small-format items with artisan provenance stories command direct-to-consumer premiums.
Furniture leads volumes today; textiles are climbing the fastest.
Material:
Cost tier and performance trade-offs separate specification-grade from mass-market adoption.
- Bamboo:Rapid-renewable grass species achieve hardwood-comparable density for flooring and furniture frames. Oregon and British Columbia retailers specify bamboo for price-sensitive sustainable lines where FSC hardwood costs prove prohibitive.
- Recycled Metal:Post-consumer aluminum and steel feed lighting housings and furniture frames with lower embodied energy than virgin ore. Portland municipal procurement mandates recycled content thresholds, creating anchored demand for certified metal suppliers.
- Organic Cotton:GOTS-certified fiber eliminates synthetic pesticide residues in bedding and upholstery applications.
- Glass:Recycled content lighting lenses and decorative objects serve transparency and circular economy messaging.
Bamboo dominates unit volumes; recycled metal shows the steepest specification growth.
End User:
Procurement authority and certification requirements fragment this category into incompatible buying processes.
- Retail Consumers:Individual purchasers rely on visible eco-labels and retailer curation rather than independent verification. Gen Z first-time buyers in urban coastal markets prioritize EPA Safer Choice and FSC logos over established brand heritage.
- Hospitality:Hotel and restaurant chains specify certified materials for LEED compliance and guest-facing sustainability narratives. West Coast boutique properties anchor demand for artisan-crafted accessories with documented supply chain accountability.
- Eco-Friendly Businesses:Corporate office fit-outs prioritize Living Building Challenge and WELL certification compliance in furniture selection.
- Interior Designers:Specification professionals balance client sustainability mandates with budget constraints and lead-time requirements.
Retail consumers drive absolute volume; hospitality delivers the highest certified-material premiums.
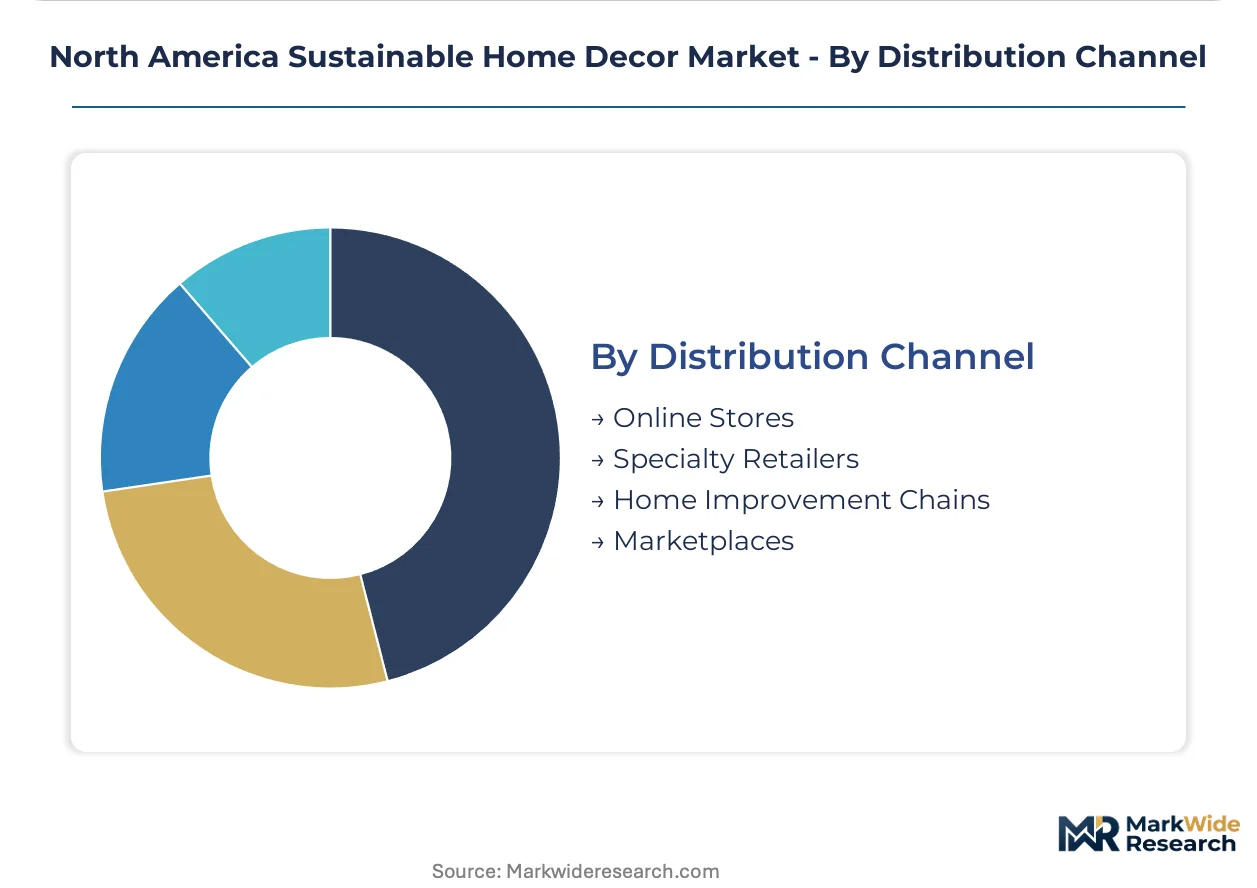
Distribution Channel:
Channel selection determines which certification standards receive visibility at point of decision.
- Online Stores:Digital-native retailers leverage detailed provenance storytelling and third-party certification badges to overcome absence of physical inspection. Direct-to-consumer platforms bypass wholesale markups while capturing margin from artisan partnership narratives.
- Specialty Retailers:Curated independent stores in Austin, Denver, and Portland stock exclusively certified collections, displacing conventional mixed-assortment merchandising. These operators function as de facto certifiers for time-constrained consumers.
- Home Improvement Chains:Big-box channels prioritize EPA Safer Choice labeling for shelf placement efficiency and consumer recognition.
- Marketplaces:Platform aggregators expose buyers to fragmented certification standards, creating confusion and audit duplication risks.
Specialty retailers concentrate certified-product margins; online stores are expanding reach most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward jurisdictions with harmonized certification standards, compressing compliance costs for cross-border suppliers. Manufacturers in British Columbia and the Pacific Northwest exploit proximity advantages to serve California's stringent emission requirements. Regulatory arbitrage diminishes as EPA Safer Choice and CARB standards diffuse across state lines.
United States
California's CARB Phase 2 formaldehyde standards and municipal green building codes in Portland and Austin concentrate demand for certified furnishings. EPA Safer Choice labeling accelerates retailer shelf placement in big-box channels. The Pacific Northwest cluster anchors domestic FSC-certified hardwood processing for cross-border supply.
Canada
Ontario and Quebec legislative proposals for furniture take-back programs create circular economy service revenue opportunities. Health Canada's biobased content thresholds add compliance layers for unified North American product lines. British Columbia sawmill capacity constraints generate input volatility for solid wood furniture producers serving US markets.
Mexico
Artisan craft traditions in Oaxaca and Jalisco supply direct-trade home accessories to US direct-to-consumer platforms. Cross-border logistics integration enables small-batch producers to bypass traditional wholesale markups. Mexico City Metro retailers curate certified collections for expatriate and upper-income segments.
North America Sustainable Home Decor Market Competitive Landscape
United States producers anchor the mass-market tier; Canadian and Mexican specialists hold artisan and certified-material niches. The vendor base fragments across direct-to-consumer platforms, specialty retailers, and legacy furniture houses with sustainability frameworks. Three archetypes dominate: digital-native provenance storytellers, legacy manufacturers with compliance infrastructure, and artisan-cooperative aggregators. Competitive moves concentrate on strategic partnerships with certified suppliers and portfolio diversification into bio-based material lines.
Within the digital-native tier, Quince and GOODEE exemplify direct-to-consumer platforms leveraging detailed supply chain transparency to capture margin from provenance narratives. West Elm occupies a position among legacy retailers with in-house sustainable sourcing programs controlling material provenance across upholstered goods. MillerKnoll anchors the commercial-grade segment through sustainability frameworks serving corporate fit-out demand. The Citizenry represents the artisan-aggregator archetype, anchoring direct-trade partnerships in craft regions for home accessories.
| Leading Market Players |
|---|
| Quince |
| Woven |
| The Citizenry |
| GOODEE |
| House of Leon |
| West Elm |
| Ten Thousand Villages |
| Uncommon Goods |
| MillerKnoll |
| Others |
Value Network & Pricing Analysis
First-time millennial homeowners in the Pacific Northwest anchor demand for certified furnishings, creating a pricing structure where visible eco-labels command measurable premiums over heritage brand positioning. Retailer markups concentrate margin capture at the specialty retail tier, while direct-to-consumer platforms compress wholesale layers to fund supply chain transparency investments.
Pricing Analysis
Retailer markup layers in specialty channels absorb 45-60 points above manufacturer cost to fund curation and certification verification services. Price differentiation hinges on certification grade—FSC Pure versus FSC Mixed—and geographic delivery distance from British Columbia sawmill clusters. Cost compression in mass-market upholstered goods intensifies as petroleum-derived foam feedstock volatility squeezes converter margins. Hospitality specifiers show lowest price sensitivity, prioritizing LEED compliance and documented chain-of-custody over unit economics.
Supply Chain Analysis
Skilled upholstery labor scarcity in North Carolina and Mississippi constrains domestic scaling for certified organic furniture lines, forcing manufacturers to anchor production in Mexico and Central America. Raw material sourcing draws from FSC-certified British Columbia timber, GOTS-certified Indian and Turkish organic cotton, and Chinese-engineered bamboo substrates. Single-source vulnerability concentrates in Pacific Northwest sawmill capacity for solid hardwood frames. Distribution runs through specialty retailer networks in Austin, Denver, and Portland, with direct-to-consumer platforms capturing fastest-growing share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America sustainable home decor market functions as a stable compounder, with regulatory ratchet effects from EPA Safer Choice and CARB Phase 2 standards creating durable demand for certified materials across replacement cycles.
For Market Incumbents: Hedge against FSC-certified timber supply concentration by anchoring long-term offtake agreements with British Columbia sawmill operators and diversifying into bamboo and recycled metal frame construction. Certification investment in GOTS textile lines and bio-based polyurethane foam chemistry protects margin position as California formaldehyde standards tighten further. For New Entrants and Emerging Players: Launch via direct-to-consumer platforms targeting Gen Z first-time renters in urban coastal markets, where visible eco-labels displace brand heritage in purchase decisions. White-space concentration sits in artisan-crafted accessories with documented Oaxaca and Rajasthan provenance, bypassing wholesale markups through digital-native storytelling. For Investors and Strategic Acquirers: Specialty retailers with exclusive certified collections are the most active acquirer in this space, consolidating independent Austin and Denver operators into regional platforms. Acquisition target archetypes include digital-native provenance storytellers with established artisan partnerships and legacy manufacturers with compliant CARB infrastructure. Signal to watch: Ontario and Quebec extended producer responsibility legislation passage as circular economy revenue inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Infrastructure Investment | CARB Phase 2 compliance locks in California market access for case goods manufacturers. |
| Direct-to-Consumer Platform Launch | Provenance storytelling captures margin from artisan partnerships in Oaxaca and Rajasthan. |
| Bio-Based Material Integration | Algae-derived polyurethane foam substitutes petroleum feedstocks in mid-market upholstery lines. |
| Extended Producer Responsibility Preparation | Ontario take-back program proposals create circular economy service revenue streams. |
| Artisan Partnership Expansion | Direct-trade relationships with Jalisco craftspeople bypass traditional wholesale markups. |
Research Methodology
Direct dialogue with furniture brand sustainability officers, specialty retail buyers in Portland and Austin, FSC chain-of-custody auditors, and organic textile procurement managers grounded qualitative assessment. Secondary validation drew from EPA Safer Choice product listings, CARB Phase 2 compliance databases, GOTS-certified facility registries, and customs records of FSC-labeled wood product flows. Bottom-up shipment data from British Columbia sawmills and top-down furniture spending patterns were triangulated against certification body audit statistics.
Bottom-up modeling aggregated unit economics across product categories—furniture, textiles, lighting, accessories—calibrated to certified-material premiums observed in specialty retail channels. Segmentation dimensions included product type, material certification tier, end-user procurement authority, and distribution channel control. CAGRs were derived from regression analysis of historical certification adoption curves and regulatory diffusion patterns. Forecast inputs incorporated municipal green building code adoption timelines and biobased content threshold harmonization assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged British Columbia sawmill capacity constraints or accelerated extended producer responsibility legislation in Canadian provinces. Forecasts reflect assumptions about EPA Safer Choice label recognition rates and CARB Phase 2 enforcement intensity. Material deviation in FSC supply availability or cross-border certification friction warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Global Decorative Panels Market
Homecare and Decor
Fireplace and Stove Market
Homecare and Decor
Global Homeware Market
Homecare and Decor
Asia-Pacific Decorative Laminates Market
Homecare and Decor
US Wallpaper Market
Homecare and Decor
Hospital Bedsheet and Pillow Cover Market
Homecare and Decor
Middle East Revolving Doors Market
Homecare and Decor
India Interior Design Market
Homecare and Decor
Vinyl Wallpaper Market
Homecare and Decor
Pillow Cases Market
Homecare and Decor
Revolving Doors Market
Homecare and Decor
Bifold Door Market
Homecare and Decor
Decorations and Inclusions Market
Homecare and Decor
New Zealand Window Covering Market
Homecare and Decor
Wall Covering Products Market
Homecare and Decor
Plantation Shutters Market