
 Bifold Door Market | 2026-2036
Bifold Door Market Size, Share, and Industry Trends Forecast 2026-2036
Bifold Door Market Intelligence
The International Energy Conservation Code (IECC) is realigning the cost-of-entry calculus for manufacturers by mandating superior thermal insulation and air leakage standards. This shift favors firms with advanced engineering capabilities and robust R&D investment. Andersen Corporation leverages its extensive distribution network to serve the mainstream residential sector with compliant products. In contrast, NanaWall specializes in high-performance, custom-engineered systems for luxury commercial and residential applications, where thermal performance is a key differentiator.
A bifold door consists of multiple hinged panels that concertina and stack together when opened, operating on either top-hung or bottom-rolling track systems. Its primary function is to create large, unobstructed openings, seamlessly connecting indoor and outdoor environments or dividing interior spaces. Aluminum-framed doors dominate the commercial complexes segment due to their structural integrity and slim sightlines. In residential buildings, timber and composite materials represent a growing category, valued for superior thermal insulation and aesthetic versatility.
Regulatory frameworks like the CE marking in Europe and the EPA's ENERGY STAR program in the United States set stringent performance benchmarks for thermal efficiency and air infiltration. These standards directly influence material selection and design, compelling manufacturers to innovate in glazing and frame technology. Global standards from ISO further govern manufacturing quality and durability testing. Consequently, vendor success depends on navigating this complex web of regional certifications to achieve broad market access.
Market Dynamics
The bifold door market is shaped by the convergence of stringent energy conservation mandates and architectural demand for expansive, flexible spaces. Regulatory frameworks like the EU's Energy Performance of Buildings Directive are elevating the technical requirements for fenestration, directly influencing material science and product engineering across the industry.
Growth Catalysts
- Architectural Trends:Demand for seamless indoor-outdoor living, particularly in the luxury residential and hospitality sectors, drives adoption. Bifold doors are specified to create large, unobstructed openings that enhance natural light, ventilation, and spatial flow in venues like hotels, restaurants, and high-end homes.
- Energy Efficiency Mandates:Stricter building codes globally, including the International Energy Conservation Code (IECC), compel the use of high-performance fenestration. This creates a powerful catalyst for doors with superior thermal insulation, low U-factors, and minimal air leakage, favoring advanced materials and glazing.
- Material Innovation:Advances in aluminum, timber, and composite frame technologies are expanding design possibilities. Slimmer, stronger aluminum profiles appeal to commercial projects, while thermally efficient composites and engineered timber gain traction in residential applications for their aesthetic versatility and insulating properties.
Market Restraints
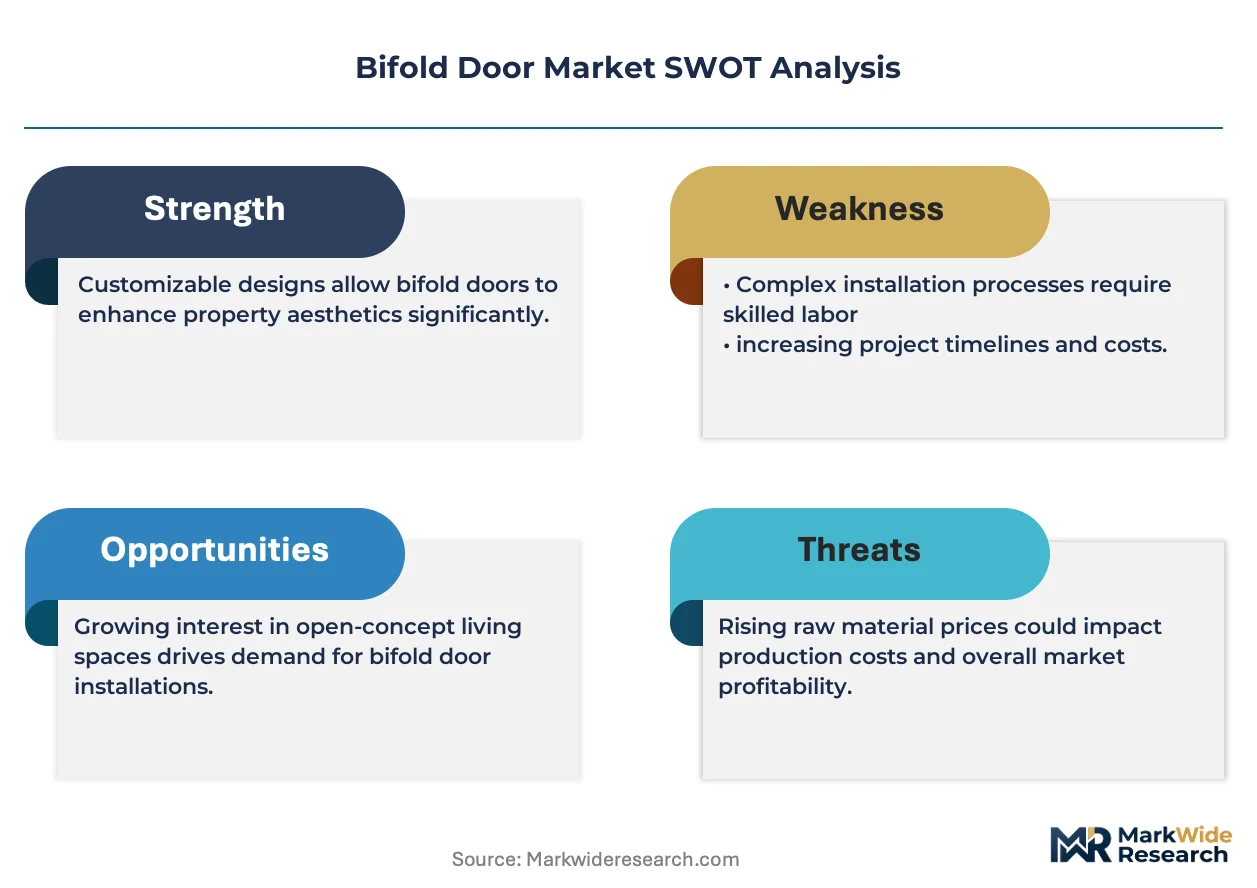
- High Initial Cost:The significant upfront investment for bifold door systems, especially custom-engineered and high-performance variants, remains a primary barrier. This cost can be prohibitive for mid-range residential construction and renovation projects, limiting market penetration beyond luxury and commercial segments.
- Structural Requirements:Installation requires precise engineering and often substantial structural modifications to the building envelope. Top-hung systems demand robust overhead lintels to bear the panel weight, while bottom-rolling systems need perfectly level and strong sills, complicating retrofits in existing structures.
- Substitution by Alternatives:Multi-panel sliding doors and lift-and-slide systems present a strong substitution threat. These alternatives can create similarly large openings with different operational mechanics, often at a lower price point or with less demanding structural prerequisites, appealing to cost-sensitive projects.
Strategic Opportunities
- Smart Home Integration:Incorporating automation and IoT connectivity represents a significant growth avenue. Opportunities exist in developing motorized systems with remote operation via mobile apps, integration with home security, and sensors for automatic closing in response to weather conditions, appealing to the high-end residential market.
- Expansion in Commercial Interiors:Beyond exterior walls, there is an untapped opportunity for bifold systems as flexible interior space dividers. Applications in corporate offices for adaptable meeting rooms, in retail for dynamic storefronts, and in educational institutions for multi-purpose spaces are growing.
- Emerging Market Construction:New luxury residential and hospitality construction projects in regions like the Middle East and Southeast Asia offer new geographic frontiers. These markets have a strong appetite for modern architectural features that emphasize openness and connection to outdoor environments.
Industry Challenges
- Installation Skill Gap:A shortage of technicians trained in the precise installation of complex bifold door systems poses a significant operational challenge. Improper installation can lead to air and water leakage, operational failure, and compromised thermal performance, risking brand reputation.
- Certification Complexity:Navigating the fragmented landscape of regional and national performance certifications, such as CE marking in Europe and ENERGY STAR in the U.S., is a major hurdle. Achieving compliance for multiple markets requires substantial investment in testing and documentation for each product line.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bifold Door Market |
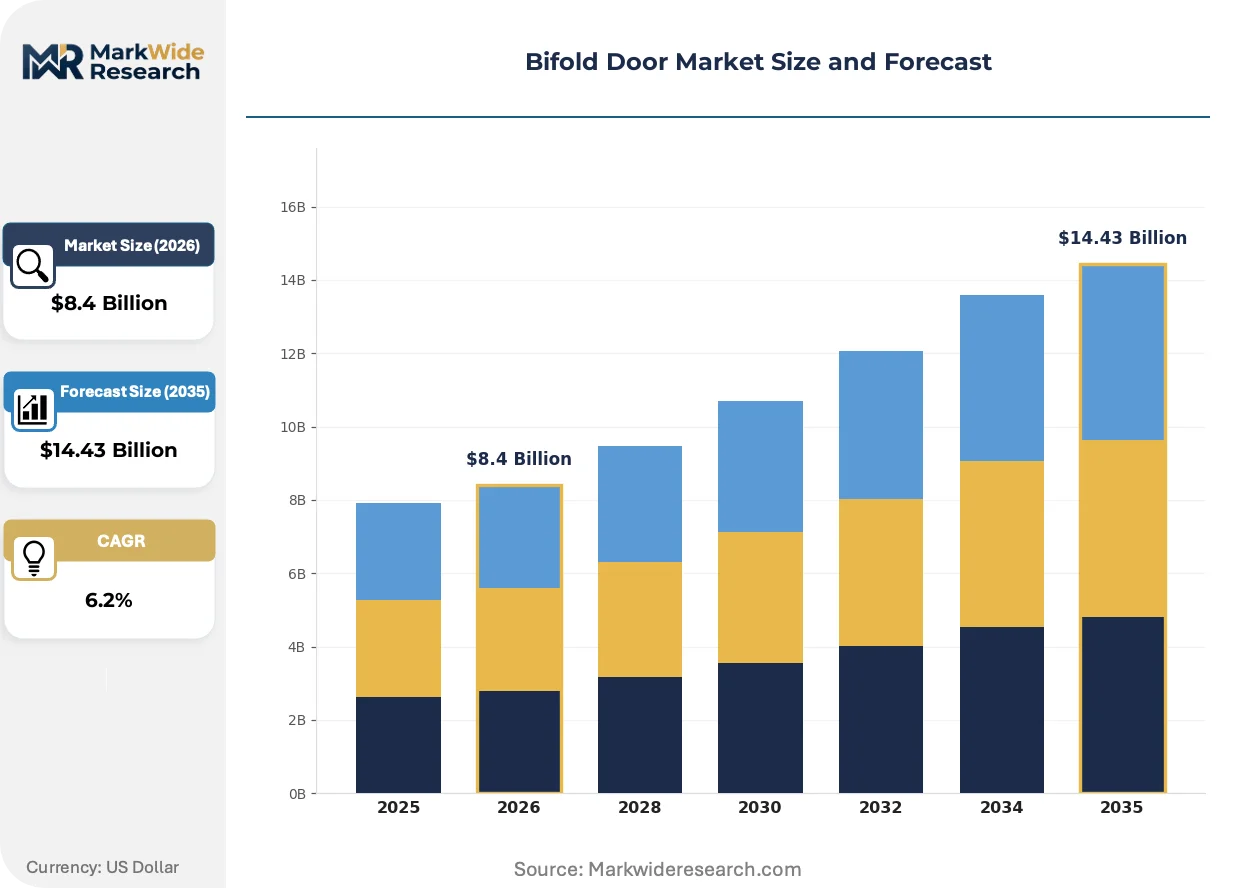
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Timber, UPVC, Steel, Composite Application: Residential Buildings, Commercial Complexes, Hospitality Venues, Educational Institutions, Recreational Centers Installation Type: Indoor, Outdoor, Semi-Outdoor, Partition walls, Conservatories End User: Property Developers, Homeowners, Facility Managers, Architects, Contractors |
| Companies Covered | Marvin, NanaWall, Andersen Corporation, Origin Global, AG Millworks, Pella Corporation, LaCantina Doors, Solarlux, JELD-WEN Holding, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bifold Door Market Strategic Shifts & Innovations
Product evolution is increasingly driven by the need to reconcile minimalist aesthetics with rigorous thermal performance standards. This dynamic compels manufacturers to innovate in both material science and systems engineering, balancing consumer desire for slim sightlines with regulatory demands for energy efficiency.
Advanced composite materials, which blend polymers with reinforcing agents like fiberglass, provide a combination of structural rigidity and superior thermal insulation. The luxury residential segment is adopting these materials for their ability to support large glass panels with minimal frame dimensions, offering a premium alternative to traditional timber or aluminum. The development of such frame technology is unifying the previously distinct objectives of aesthetic versatility and the thermal performance required by codes like the IECC.
Regulatory frameworks are progressively tightening performance benchmarks for fenestration products. The EPA's ENERGY STAR program, for example, sets stringent criteria for thermal transmittance (U-factor) and solar heat gain, influencing product design across North America. This forces manufacturers to accelerate the adoption of technologies like triple-pane glazing, low-emissivity coatings, and thermally broken frames to remain compliant and competitive, particularly within the mainstream residential replacement market.
A notable shift in buyer behavior is the move from procuring individual components to specifying complete, integrated opening systems. This trend disrupts the traditional sales channel, favoring manufacturers who can provide a holistic solution that includes matching screens, integrated blinds, and consistent hardware across a project. This preference is most visible in the high-end custom home market, where architects seek a single source of responsibility for the entire wall opening to ensure aesthetic cohesion and performance integrity.
Bifold Door Market Segmentation
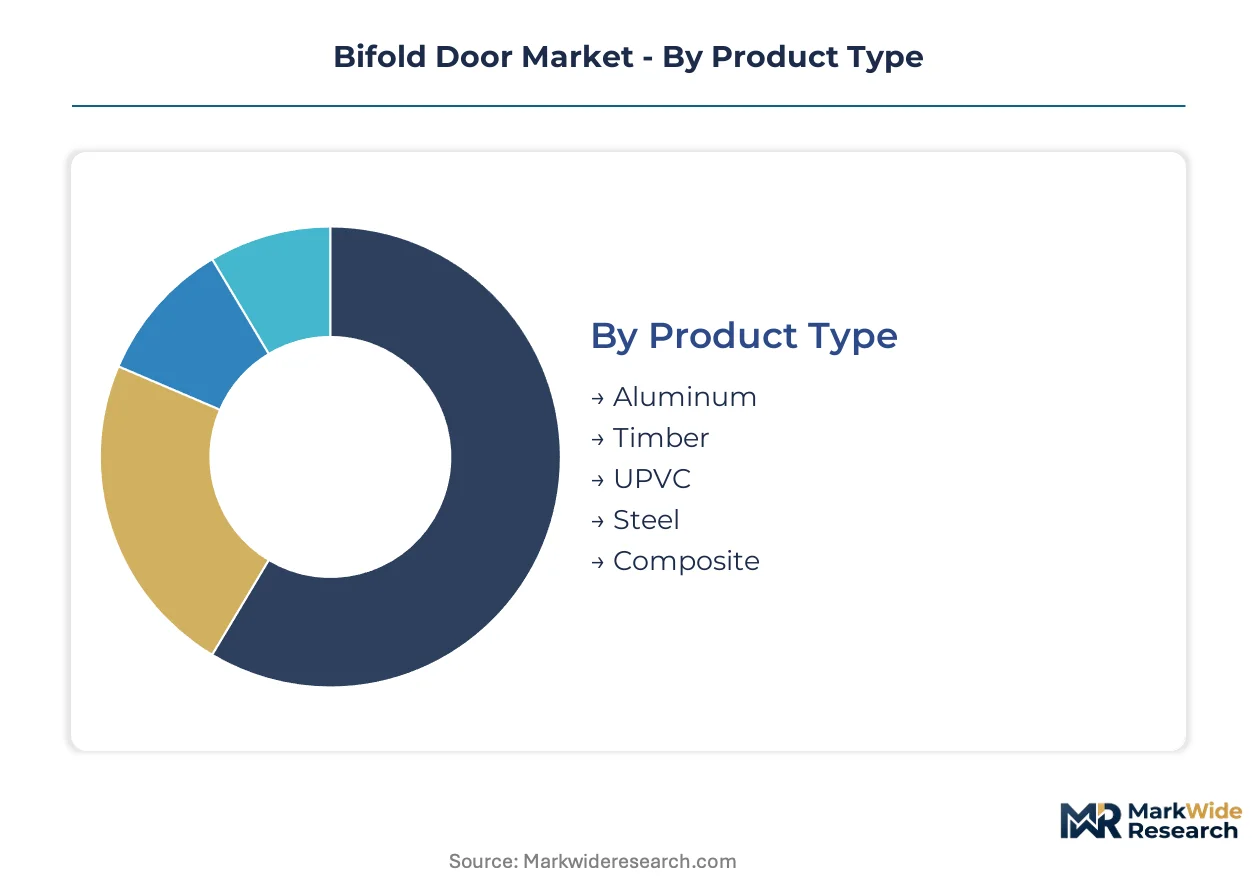
Segmentation of the bifold door market clarifies diverse product requirements and user preferences across various applications. Manufacturers leverage these distinctions to tailor material specifications, design aesthetics, and performance characteristics for specific market niches. Understanding these segments helps firms optimize product development and sales strategies.
Product Type:
The product type segmentation highlights the trade-offs between volume production and premium performance within the bifold door market.
- Aluminum:These doors feature lightweight yet strong frames, enabling large glass panels and slim sightlines. Demand concentrates in commercial complexes and high-end residential projects due to their structural integrity and modern aesthetic.
- Timber:Timber bifold doors offer natural insulation properties and aesthetic versatility, appealing to traditional and luxury residential applications.
- UPVC:UPVC frames provide a cost-effective solution with reasonable thermal performance, often specified in mainstream residential renovations.
- Steel:Steel bifold doors offer exceptional strength and security, making them suitable for industrial or highly secure commercial installations.
- Composite:These products combine multiple materials, such as a timber core with an aluminum exterior, for superior thermal efficiency and durability. Demand grows in energy-conscious residential markets where stringent U-factor requirements drive material innovation.
Mature deployment sits with Aluminum products. Newer deployment is concentrated in Composite materials.
Application:
The application segmentation illustrates the functional diversity and specific design requirements for bifold door systems across different building types.
- Residential Buildings:Bifold doors in homes create expansive openings, fostering indoor-outdoor living and enhancing natural light. Demand is strong in luxury homes and renovation projects, driven by architectural trends for open-plan designs.
- Commercial Complexes:These applications prioritize durability, security, and aesthetic appeal for storefronts, office partitions, and common areas. Demand concentrates in urban developments where adaptable spaces and robust fenestration are critical.
- Hospitality Venues:Hotels and restaurants utilize bifold doors for flexible event spaces and seamless transitions to outdoor dining areas.
- Educational Institutions:Schools and universities employ these systems for adaptable classrooms and multi-purpose halls, maximizing space utilization.
- Recreational Centers:Gyms and community centers use bifold doors to connect indoor activity zones with outdoor facilities, enhancing user experience.
The largest volume consumption is observed in Residential Buildings. Fastest share expansion is seen in Hospitality Venues.
Installation Type:
The installation type segmentation differentiates bifold door uses based on their primary function and exposure to environmental elements.
- Indoor:These installations primarily serve as aesthetic dividers within interior spaces, offering flexibility without direct weather exposure.
- Outdoor:Outdoor bifold doors form part of the building envelope, requiring robust weather sealing, thermal performance, and security features. Demand is highest in regions with emphasis on seamless indoor-outdoor living, such as Australia and California.
- Semi-Outdoor:These installations bridge covered outdoor spaces, like patios or balconies, to interior rooms, needing moderate weather resistance.
- Partition walls:Bifold systems here create flexible interior divisions in offices or public spaces, allowing for quick reconfiguration of layouts. Demand is growing in corporate environments seeking adaptable meeting rooms and collaborative zones.
- Conservatories:These doors integrate into glass structures, requiring specialized framing and glazing to maintain thermal efficiency in sunrooms.
Functional priority for weather resistance defines Outdoor installations. Interior flexibility drives demand for Partition walls.
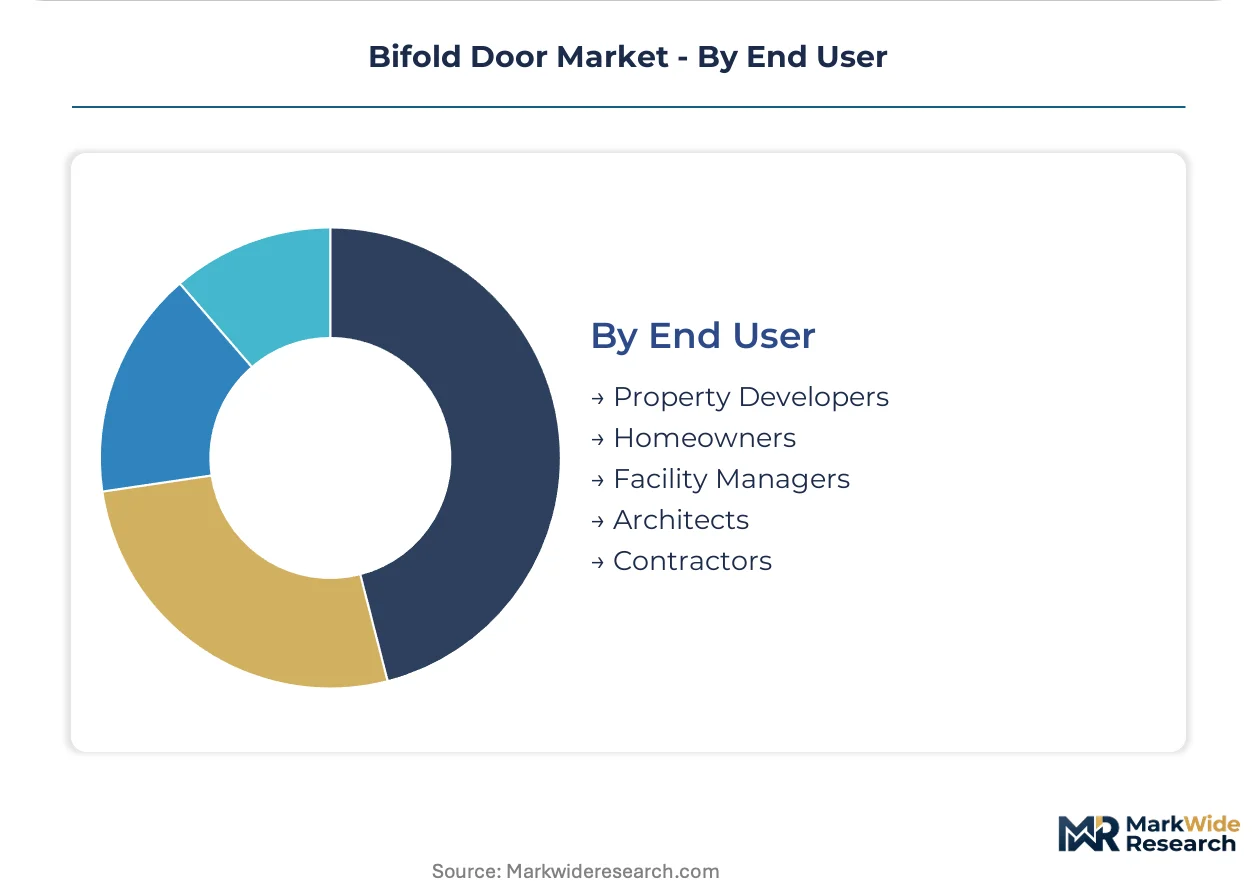
End User:
The end user segmentation outlines the distinct purchasing behaviors and decision-making priorities across the bifold door value chain.
- Property Developers:These entities specify bifold doors for new construction projects, balancing cost, aesthetics, and market appeal for residential or commercial properties. Their decisions are influenced by project scale and target demographics.
- Homeowners:Individual homeowners purchase bifold doors for renovation or custom home builds, prioritizing aesthetic integration, energy efficiency, and operational ease. Their choices often reflect personal design preferences and long-term value.
- Facility Managers:These professionals oversee maintenance and upgrades for commercial or institutional buildings, focusing on durability and operational reliability.
- Architects:Architects select bifold systems based on design vision, structural integration, and performance specifications for client projects. Their influence is critical for high-end and custom installations.
- Contractors:Contractors manage the procurement and installation process, emphasizing ease of installation, timely delivery, and cost-effectiveness for projects.
Strategic influence in project specification rests with Property Developers. Technical product selection is heavily guided by Architects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Luxury development zones across the Middle East are driving significant concentration in bifold door demand for high-end hospitality and residential projects. These areas prioritize modern architectural features and expansive openings. This focus on premium construction elevates the market for sophisticated fenestration solutions.
Australia
Australian demand for bifold doors stems from a strong cultural preference for seamless indoor-outdoor living and contemporary architectural designs. National building codes increasingly influence material selection for thermal performance. Coastal cities like Sydney and Melbourne exhibit high concentrations of luxury residential projects specifying these systems.
United States
United States demand for bifold doors is strong in luxury residential construction and renovation, driven by desires for expansive, natural light-filled spaces. The International Energy Conservation Code (IECC) and EPA's ENERGY STAR program mandate superior thermal performance. High-end custom home markets in California and Florida show significant adoption of these premium systems.
Germany
German market expansion for bifold doors reflects Europe's stringent energy efficiency mandates and a preference for aesthetically versatile building solutions. The EU's Energy Performance of Buildings Directive and CE marking require advanced thermal performance. Urban developments in major cities like Berlin and Munich often feature these systems for adaptable commercial and residential spaces.
United Arab Emirates
Construction activity in the United Arab Emirates' hospitality and luxury residential sectors fuels significant bifold door demand for expansive, modern architectural designs. Local building regulations increasingly incorporate green building initiatives, promoting energy-efficient fenestration solutions. Major construction hubs in Dubai and Abu Dhabi are prime markets for high-performance bifold door installations.
China
China's rapid urbanization and growth in commercial complexes and high-end residential projects create substantial demand for bifold doors. GB standards and local energy efficiency codes increasingly influence material selection. Major construction activity in the Yangtze River Delta region and Pearl River Delta drives significant product specification.
Bifold Door Market Key Industry Players
North American producers anchor one tier of the bifold door market; European specialists hold another, defined by advanced engineering and regulatory compliance. The market exhibits tiered consolidation, with a few large manufacturers dominating mainstream residential and commercial segments. Strategic archetypes include high-volume manufacturers, custom solution providers, and niche players focusing on specific material innovations. Competitive moves often involve portfolio diversification to meet varied thermal performance standards and geographic expansion into emerging construction markets.
Within the high-volume mainstream residential sector, Andersen Corporation and Pella Corporation exemplify manufacturers leveraging extensive distribution networks to deliver compliant products. These firms prioritize broad market access and cost-effective solutions for standard residential applications. Conversely, NanaWall, a specialist in high-performance, custom-engineered systems, occupies a distinct position serving luxury commercial and residential applications. This company emphasizes advanced thermal performance and bespoke design capabilities for projects requiring premium fenestration solutions. The competitive landscape thus includes players focused on scale and accessibility alongside those dedicated to specialized, high-end market segments.
| Leading Market Players |
|---|
| Marvin |
| NanaWall |
| Andersen Corporation |
| Origin Global |
| AG Millworks |
| Pella Corporation |
| LaCantina Doors |
| Solarlux |
| JELD-WEN Holding |
Cost & Logistics Intelligence
The cost of specialized glass, a critical component, significantly influences the final price of bifold door systems across all market tiers. This upstream input cost cascades through the manufacturing process, affecting pricing strategies for both high-volume and custom-engineered products.
Pricing Analysis
Premium pricing for bifold door systems with short lead times reflects expedited manufacturing and delivery capabilities. The dominant pricing model is project-based, where costs are tailored to specific architectural requirements and performance specifications. Price differentiation stems from the level of customization, the specific certification grade achieved (e.g., CE marking, ENERGY STAR), and the brand's reputation for advanced engineering. Pricing pressure stems from the availability of lower-cost alternatives, particularly in mid-range residential segments. Homeowners in renovation projects exhibit the highest price sensitivity, while architects specifying for luxury commercial projects are less sensitive to initial investment.
Supply Chain Analysis
The availability of skilled labor in specialized manufacturing facilities across Germany, the United States, and China impacts bifold door production capacity. The supply chain draws heavily from global sources for aluminum profiles, specialized low-emissivity glass, and high-performance sealing systems. Regulatory restrictions, such as evolving thermal performance mandates, represent a structural risk requiring constant material and design adaptation. Distribution runs primarily through specialist dealer networks and direct-to-project sales channels, particularly for custom commercial and luxury residential installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bifold door market is supply-constrained by the intricate manufacturing processes required for high-performance, compliant fenestration. This complexity in production capacity props up pricing for advanced systems.
For Market Incumbents:Acquire specialized engineering firms focused on advanced glazing and frame technologies to deepen R&D capabilities. Invest in automated manufacturing lines to scale production of thermally broken frames and integrated systems, countering margin pressure from rising material costs. Strengthen distribution networks by forming strategic partnerships with certified installation contractors, mitigating the threat of improper installation and ensuring product performance. Focus on expanding market access by proactively meeting diverse regional certification standards.
For New Entrants and Emerging Players:Launch into niche segments like interior partition walls for corporate offices via direct-to-architect sales channels. Target emerging market construction in the Middle East with highly energy-efficient systems, capitalizing on growing green building initiatives. Develop smart home integrated bifold doors featuring automated operation and sensor-based weather response, appealing to the high-end residential market. Offer bespoke solutions that combine aesthetic versatility with superior thermal performance.
For Investors and Strategic Acquirers:Widespread adoption of smart home integration features in new bifold door product lines is the leading indicator that signals market maturation. The long-term viability of this market hinges on sustained demand for flexible, energy-efficient building envelopes. Identify acquisition target archetypes among niche manufacturers specializing in composite materials or advanced glazing technologies, particularly those with established certification portfolios. Material deviation in named triggers warrants pause and re-evaluation.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Manufacturing | Enhances thermal performance, reduces production costs, and improves compliance with stringent building codes. |
| Expand Certification Portfolio | Unlocks broader market access in regions with diverse regulatory requirements like Europe and North America. |
| Integrate Smart Home Features | Appeals to luxury residential consumers seeking automation and advanced climate control capabilities. |
| Target Emerging Market Projects | Captures growth in new luxury hospitality and residential construction in regions like the UAE. |
| Acquire Specialist Installation Firms | Ensures high-quality product deployment, maintains brand reputation, and expands service offerings. |
Research Approach
Independent corroboration across building code databases, industry association reports, and fenestration product certifications underwrites the qualitative findings of this analysis. Primary interviews were conducted with key industry stakeholders, including architects, property developers, facility managers, and contractors. This comprehensive approach ensured a balanced perspective, triangulating insights from both supply-side manufacturers and demand-side specifiers.
Historical data was anchored to comparable reference periods, establishing a baseline for future projections across the modeling period. The analytical framework modeled market dynamics across segmentation dimensions such as product type, application, installation type, end user, and regional regulatory compliance. Compound Annual Growth Rates (CAGRs) were derived from a synthesis of historical growth trends and anticipated market shifts. Key forecast inputs included building permits, construction spending, and energy efficiency policy adoption rates.
Economic downturns, material price volatility, and sudden regulatory changes are the dominant revision risks to market forecasts. Forecasts reflect assumptions regarding sustained architectural trends and consistent regulatory enforcement. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Wall Covering and Wall Decor Market
Homecare and Decor
Europe Flower Pots and Planters Market
Homecare and Decor
Pillow Market
Homecare and Decor
MDF Decorative Overlays Market
Homecare and Decor
Global Decorative Laminates Market
Homecare and Decor
India Wall Decor Market
Homecare and Decor
Window Blinds Market
Homecare and Decor
Wall Decor Market
Homecare and Decor
Fireplace and Stove Market
Homecare and Decor
Fragrant Drawer Liners Market
Homecare and Decor
Composite Doors and Windows Market
Homecare and Decor
Online Home Decor Market
Homecare and Decor
Interior Design Market
Homecare and Decor
Asia-Pacific Sustainable Home Decor Market
Homecare and Decor
France Steam Rooms Market
Homecare and Decor
India Interior Design Market