
 Fireplace and Stove Market | 2026-2036
Fireplace and Stove Market Size, Share, and Industry Trends Forecast 2026-2036
Fireplace and Stove Market Foresight
Aftermarket service revenue is narrowing as manufacturers bundle installation and maintenance into initial equipment contracts. Hearth & Home Technologies dominates direct-to-builder channels across North America. Napoleon leverages vertical integration into metal fabrication to control component costs. Kingsman Fireplaces specializes in custom gas fireplace assemblies for luxury residential developers.
Fireplaces and stoves are enclosed heating appliances designed to contain solid fuel, gas, or electric combustion while radiating thermal energy into interior spaces, typically constructed from cast iron, steel, or refractory ceramic liners rated for continuous temperatures exceeding 1,100°F. Their primary purpose centers on zone heating, architectural ambiance, and supplemental warmth in residential, hospitality, and outdoor environments. Gas fireplace installations lead value generation across the product type dimension due to higher unit economics and simpler venting requirements, while pellet stoves represent the fastest-expanding fuel-based category as biomass incentives expand in Scandinavia and North America. Smart technology integration within the technology dimension is displacing traditional manual controls as WiFi-enabled thermostatic modulation becomes standard in premium residential specifications.
EPA Phase IV emissions standards in the United States mandate particulate output below 2.0 grams per hour for cordwood stoves, compelling engineering redesigns of combustion chambers and secondary air injection systems. The EU Ecodesign Directive and related F-Gas Regulation shape product eligibility for European market access, particularly for gas-fired units with sealed combustion. Stakeholders must monitor evolving carbon-border adjustment mechanisms and building-code electrification mandates that threaten to bifurcate addressable markets between fossil-fuel and electric heating alternatives.
Market Dynamics
Residential electrification mandates and EPA Phase IV emissions standards are bifurcating product development pipelines between fossil-fuel combustion systems and electric alternatives, forcing manufacturers to maintain dual R&D tracks while retrofit demand concentrates in subsidy-rich renovation markets.
Growth Catalysts
- Building Renovation Subsidies:Germany's federal efficiency programs accelerate replacement cycles for aging heating infrastructure, directing consumer spending toward certified low-emission appliances.
- Biomass Incentive Expansion:Scandinavian national energy agencies extend pellet stove deployment grants, stimulating demand for automated feed systems and thermal storage integration.
- Smart Thermostatic Controls:WiFi-enabled modulation technology is displacing manual dampers in premium residential specifications, creating attach-rate opportunities for connected home ecosystems.
Market Restraints
- Steel and Cast Iron Input Volatility:Foundry-grade metal price fluctuations compress margin buffers for manufacturers lacking backward integration into raw material sourcing.
- Refractory Ceramic Supply Concentration:European kiln-liner production clusters in Poland and the Czech Republic expose the value chain to single-source disruption risks.
- Electrification Substitution Threat:Heat pump deployment in new construction reduces addressable market for combustion-based zone heating in residential segments.
Strategic Opportunities
- Outdoor Living Extension:Gas fire pit and patio heater categories capture underpenetrated demand in Australian and Canadian recreational property markets.
- EU F-Gas Regulation Tailwind:Sealed-combustion gas fireplace architectures gain eligibility preference as the regulation phases down hydrofluorocarbon-dependent alternatives.
- Direct-to-Builder Channel Innovation:National homebuilders consolidate procurement around single-source fireplace suppliers, compressing traditional distributor intermediaries.
Industry Challenges
- Combustion Engineering Talent Scarcity:EPA certification testing protocols require specialized expertise in particulate measurement and air-injection modeling that outpaces vocational training pipeline output.
- Dual-Certification Timeline Compression:Simultaneous UL and CSA safety approvals for North American cross-border distribution extend product launch cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fireplace and Stove Market |
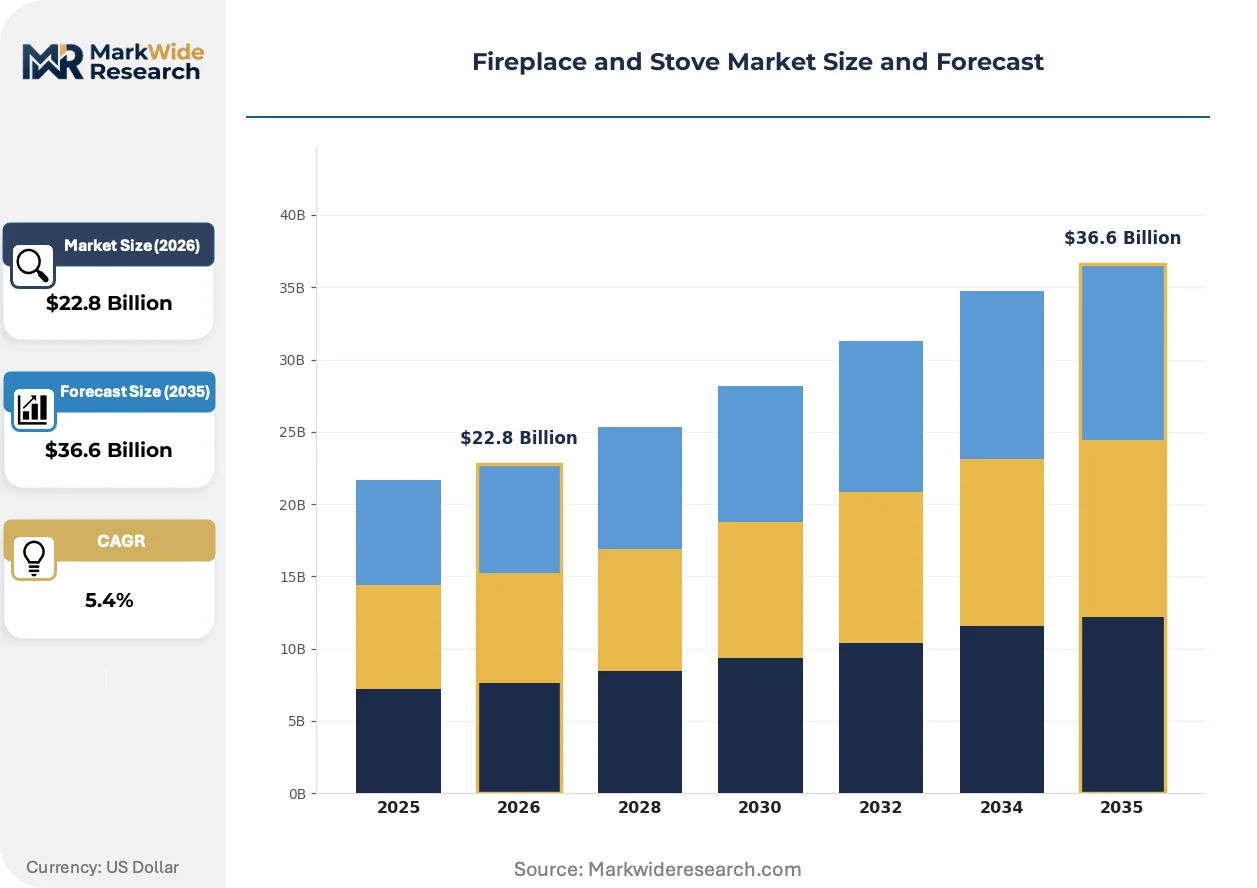
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $36.6 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wood Stove, Gas Fireplace, Pellet Stove, Electric Heater Technology: Traditional, Modern, Smart, Ventless Fuel Type: Wood, Natural Gas, Propane, Electricity End User: Residential, Commercial, Industrial, Outdoor |
| Companies Covered | Harman, Heat & Glo, Hearth & Home Technologies (HHT), Planika, Kingsman Fireplaces, Napoleon, Regency, Dimplex, Majestic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fireplace and Stove Market Shifts & Advancements
Product architecture is converging around connected control systems and modular fuel flexibility, while regulatory pressure on emissions intensifies engineering investment in combustion optimization and sealed-system designs.
Dual-fuel gas-wood fireplace inserts is hybridizing residential heating infrastructure by enabling homeowners to switch between pipeline natural gas and cordwood based on seasonal pricing and availability. Custom home developers in the Mountain West United States specify these systems at accelerating rates. The technology is hybridizing market segmentation by collapsing distinct product categories into single-appliance solutions.
EPA Phase IV particulate standards mandate cordwood stove emissions below 2.0 grams per hour, compelling wholesale redesign of firebox geometry and secondary combustion air injection. Engineering teams must validate designs through extended burn-cycle testing. Wood stove manufacturers in the Pacific Northwest and New England regions are prioritizing catalytic converter integration to achieve certification thresholds.
Builder procurement consolidation around turnkey fireplace packages is compressing aftermarket service revenue pools and redirecting margin capture toward initial equipment contracts. National production homebuilders in Texas and Florida now specify complete hearth systems including venting and finishing materials. This pattern is most visible in the southeastern United States where labor scarcity drives preference for pre-engineered installation bundles.
Fireplace and Stove Market Segmentation
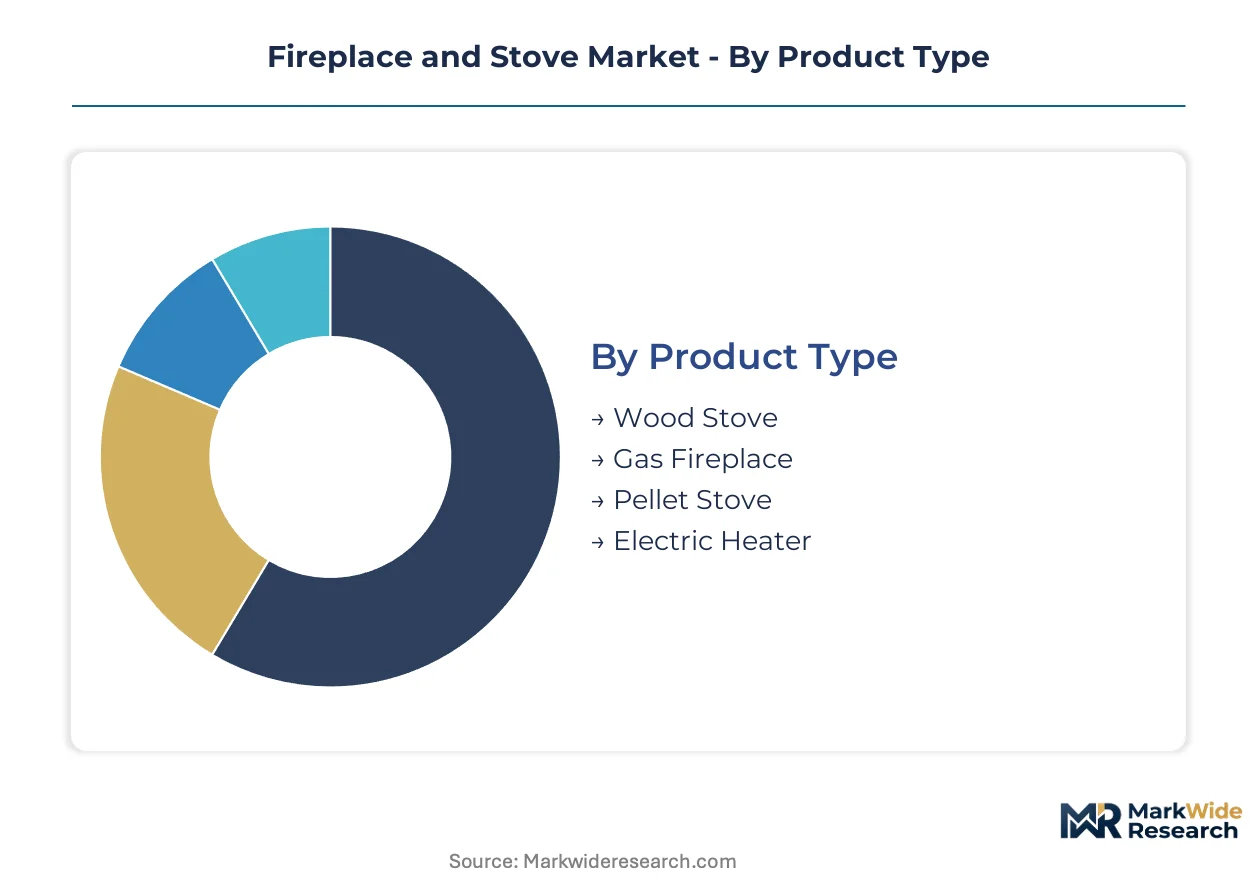
Product differentiation in the fireplace and stove market follows distinct technical and regulatory fault lines. Each segmentation dimension carries specific compliance burdens and margin implications that reshape competitive positioning across installation channels.
Product Type:
Mature combustion appliances dominate installed base volumes while emerging electric formats capture renovation-driven substitution.
- Gas Fireplace:Sealed-combustion architectures with direct-vent or power-vent configurations achieve higher unit economics through simplified installation protocols. Demand concentrates in Texas and Florida production homebuilder specifications where turnkey hearth packages compress distributor margins. EPA venting exemptions for natural gas units reduce certification timeline compression versus wood-burning alternatives.
- Wood Stove:Cast iron and steel firebox constructions with secondary air injection systems must achieve EPA Phase IV particulate thresholds below 2.0 grams per hour. Pacific Northwest and New England manufacturers prioritize catalytic converter integration to meet certification standards. Cordwood price volatility and emissions testing costs constrain margin expansion for non-integrated producers.
- Pellet Stove:Automated feed systems with thermal storage integration gain deployment grants from Scandinavian national energy agencies.
- Electric Heater:Ceramic element and infrared panel configurations bypass venting requirements entirely, accelerating penetration in multi-family residential retrofits.
Gas fireplace handles the majority of throughput; pellet stove is the fastest mover on share.
Technology:
Cost tier stratification separates premium connected systems from economy manual controls, with mid-market hybrid formats capturing renovation flexibility.
- Smart:WiFi-enabled thermostatic modulation with mobile application integration and voice-assistant compatibility commands premium attach rates in custom residential specifications. Kingsman Fireplaces and Hearth & Home Technologies bundle these controls with builder procurement contracts. Data logging capabilities for usage optimization and remote diagnostics create recurring service revenue pools.
- Modern:Clean-face designs with linear burners and media beds prioritize architectural integration over thermal output maximization. Luxury residential developers in Colorado and Utah mountain markets specify these units for aesthetic dominance in great room configurations. Sealed combustion chambers with ceramic glass fronts achieve efficiency ratings that qualify for federal tax credit programs.
- Traditional:Masonry fireplace inserts and open-hearth constructions retain installed base dominance in heritage property renovations.
- Ventless:Catalytic and oxygen-depletion sensor-equipped units access markets with restrictive venting infrastructure, particularly in older urban housing stock.
Modern technology handles the majority of throughput; smart controls are expanding most quickly on share.
Fuel Type:
Application-driven fuel selection bifurcates between pipeline-dependent infrastructure and distributed biomass sourcing.
- Natural Gas:Pipeline-connected systems with electronic ignition and millivolt standing pilot options dominate suburban residential new construction. Builder procurement consolidation around single-source suppliers in Texas and Florida accelerates specification capture. FERC-regulated pipeline access and local utility rebate programs shape regional penetration patterns.
- Wood:Cordwood and manufactured firelog combustion requires EPA-certified emissions performance for retail distribution eligibility. Rural property owners in Maine and Vermont maintain strong replacement demand despite electrification headwinds. Seasonal pricing arbitrage against heating oil and propane sustains economic viability in forest-resource-proximate markets.
- Propane:Tank-fed systems serve off-grid residential and recreational property applications with equivalent combustion efficiency to natural gas.
- Electricity:Resistance and infrared element configurations align with building-code electrification mandates in jurisdictions restricting fossil-fuel combustion.
Natural gas handles the majority of throughput; electricity is climbing the fastest on share.
End User:
Customer type concentration varies sharply across installation complexity and specification authority structures.
- Residential:Single-family and multi-family zone heating applications generate the core revenue base through both new construction and retrofit replacement cycles. German federal efficiency programs and Scandinavian biomass incentives accelerate certified appliance adoption. Homeowner specification authority varies between production builder selections and custom architect-driven procurement.
- Outdoor:Gas fire pits, patio heaters, and outdoor fireplace installations capture underpenetrated demand in Australian recreational property and Canadian cottage markets. Seasonal usage patterns and weather exposure requirements drive stainless steel construction specifications and specialized venting configurations.
- Commercial:Hospitality, restaurant, and lodging applications prioritize aesthetic impact and code compliance over thermal efficiency optimization.
- Industrial:Workshop, warehouse, and agricultural space heating represents a marginal volume segment with severe price competition from forced-air alternatives.
Residential handles the majority of throughput; outdoor is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German homeowners favor sealed-combustion gas inserts for renovation subsidies, while Scandinavian consumers gravitate toward automated pellet systems with thermal storage. Australian recreational property owners drive stainless steel outdoor fire pit demand distinct from North American builder-specification patterns.
United States
Production homebuilders in Texas and Florida consolidate procurement around turnkey hearth packages that include venting and finishing materials. EPA Phase IV emissions standards mandate cordwood stove particulate output below 2.0 grams per hour, compelling catalytic converter integration. Pacific Northwest manufacturers cluster around Portland and Seattle, prioritizing secondary air injection engineering for certification compliance.
Germany
Federal efficiency programs accelerate replacement cycles for aging heating infrastructure, directing consumer spending toward certified low-emission appliances. The EU Ecodesign Directive and F-Gas Regulation shape product eligibility for market access, particularly for sealed-combustion gas units. Industrial concentration centers in Bavaria and North Rhine-Westphalia, where foundries supply cast iron firebox components to regional OEMs.
Canada
Cottage and recreational property markets in Ontario and Quebec sustain demand for propane-fed outdoor heating systems with weather-resistant stainless construction. Health Canada and PMRA coordinate with EPA on cross-border emissions alignment, though CSA safety approvals extend product launch timelines. Manufacturing activity clusters in Quebec and Ontario provinces, serving both domestic specification and US export channels.
Sweden
National energy agencies extend pellet stove deployment grants, stimulating demand for automated feed systems and thermal storage integration. REACH and F-Gas Regulation compliance requirements filter product portfolios toward low-emission biomass combustion. Engineering expertise concentrates in Stockholm and Gothenburg metropolitan areas, where vocational programs supply combustion optimization specialists to domestic manufacturers.
Australia
Recreational property owners in New South Wales and Victoria drive underpenetrated demand for gas fire pits and patio heaters with specialized venting for coastal exposure. The country's national building code regulator enforces efficiency mandates that favor electric alternatives in multi-family new construction. Distribution networks center on Melbourne and Sydney, importing pre-finished hearth systems from Asian manufacturing hubs.
Fireplace and Stove Market Competitive Landscape
Capability concentration sits with engineering-intensive specialists; scale advantage sits with diversified heating equipment conglomerates. The vendor base stratifies into three tiers: premium custom-specification houses, mid-market production builders, and value-oriented import distributors. Consolidation pressure intensifies as national homebuilders compress traditional distributor intermediaries through direct procurement contracts. Dual-certification timelines for UL and CSA approvals extend product launch cycles, favoring incumbents with established testing relationships.
Within the premium custom-tier, Kingsman Fireplaces and Napoleon occupy positions anchored to luxury residential developer specifications. Hearth & Home Technologies exemplifies the scale-driven archetype through consolidated direct-to-builder channel penetration. These three entities represent distinct competitive vectors: custom fabrication specialization, backward integration into metal fabrication, and national distribution infrastructure respectively.
| Leading Market Players |
|---|
| Harman |
| Heat & Glo |
| Hearth & Home Technologies (HHT) |
| Planika |
| Kingsman Fireplaces |
| Napoleon |
| Regency |
| Dimplex |
| Majestic |
| Others |
Supply & Pricing Matrix
Polish and Czech kiln-liner production clusters anchor refractory ceramic supply for European fireplace manufacturers, concentrating margin capture with foundries possessing captive sourcing agreements while compressing price flexibility for assembly-tier competitors.
Pricing Analysis
Long-term offtake contracts dominate procurement between national homebuilders and turnkey hearth suppliers, displacing spot-market transactions in Texas and Florida production specifications. Pricing stratifies across premium smart-enabled systems, standard direct-vent configurations, and economy ventless alternatives based on certification grade and installation complexity. Cost compression in economy tiers intensifies as import distributors from Asian manufacturing hubs undercut regional foundries on cast iron firebox components. Production homebuilders exhibit highest price sensitivity, while luxury residential developers prioritize specification authority over unit cost.
Supply Chain Analysis
Foundry-grade steel and cast iron feedstock draws from German, Italian, and Chinese metallurgical suppliers, with Bavarian and North Rhine-Westphalia industrial clusters maintaining regional dominance for OEM component sourcing. Refractory ceramic liners, electronic ignition systems, and catalytic converter substrates constitute critical input dependencies. Single-source vulnerability concentrates in Polish and Czech kiln-liner production, exposing downstream manufacturers to disruption risk from energy cost volatility or export restriction. Distribution runs through direct-to-builder channels, national distributor networks, and specialized hearth retailers serving renovation-driven replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from WiFi-enabled diagnostics and remote maintenance protocols is expanding faster than hardware sales, creating recurring margin pools that justify upfront equipment discounting strategies.
For Market Incumbents: Insulate certification pipelines by accelerating EPA Phase IV and EU Ecodesign pre-approvals ahead of regulatory tightening, while consolidating direct-to-builder procurement relationships in Texas and Florida to forestall distributor disintermediation. Backward integration into metal fabrication secures margin buffers against steel price volatility.
For New Entrants and Emerging Players: Build out outdoor living product portfolios targeting Australian recreational property markets and Canadian cottage segments, where stainless steel gas fire pit demand remains underpenetrated relative to North American builder channels. Channel partnerships with national patio furniture retailers offer lower-friction market entry than competing for production homebuilder specifications.
For Investors and Strategic Acquirers: Capital is best deployed toward engineering-intensive specialists with established UL and CSA testing relationships, as dual-certification timeline compression favors incumbents and extends product launch cycles for resource-constrained competitors. Acquisition candidates should demonstrate sealed-combustion gas fireplace architectures eligible under EU F-Gas Regulation phase-down schedules. The signal to watch is builder procurement consolidation velocity in southeastern United States markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Control Platform Integration | WiFi-enabled thermostatic modulation creates recurring service revenue and builder specification lock-in. |
| Sealed-Combustion Architecture Development | EU F-Gas Regulation compliance secures market access as hydrofluorocarbon-dependent alternatives phase down. |
| Direct-to-Builder Channel Expansion | National homebuilder procurement consolidation compresses distributor margins and captures turnkey installation bundles. |
| Backward Integration into Foundry Operations | Captive steel and cast iron sourcing insulates margin buffers from commodity price volatility. |
| Outdoor Living Product Line Extension | Gas fire pit and patio heater categories access underpenetrated Australian and Canadian recreational property demand. |
Research Methodology
Initial hypotheses were tested against primary input from hearth product engineering directors, national homebuilder procurement officers, distributor channel managers, and aftermarket service technicians, and refined through secondary validation against EPA certification databases, EU Ecodesign Directive compliance registries, customs trade records for cast iron and steel imports, and foundry industry association production statistics. Bottom-up unit shipment estimates by product type and fuel category were triangulated against top-down market value reconstructions.
Demand-supply balance dynamics across the analysis window were modeled through segmentation by product architecture, fuel type, technology tier, and end-use application, with particular attention to electrification substitution effects on combustion-based zone heating demand. CAGRs were derived from installed base replacement cycle analysis, renovation subsidy program trajectories, and new construction specification trends. Industry-specific forecast inputs included EPA Phase IV certification timeline data and Scandinavian national energy agency pellet stove deployment grant allocations.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Asian manufacturing hubs or accelerated heat pump substitution in residential new construction would shift outcomes beyond modeled ranges. Cross-checking against national building permit data and utility rebate program disbursement records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
United States Home Decor Market
Homecare and Decor
Removable Wallpaper Market
Homecare and Decor
Hearth Market
Homecare and Decor
Smart Curtain Market
Homecare and Decor
India Wallpapers Market
Homecare and Decor
Japan Sustainable Home Decor Market
Homecare and Decor
Asia-Pacific Interior Doors Market
Homecare and Decor
Terracotta Pots Market
Homecare and Decor
US Steam Rooms Market
Homecare and Decor
Garden Sheds Market
Homecare and Decor
United States Decorative Laminates Market
Homecare and Decor
Interior Design Services Market
Homecare and Decor
United States Wall Covering and Wall Decor Market
Homecare and Decor
India Wall Decor Market
Homecare and Decor
India Home Furnishing Market
Homecare and Decor
China Sustainable Home Decor Market