
 North America Laminate Flooring Market | 2026-2036
North America Laminate Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
North America Laminate Flooring Market Intelligence
The buyer base for laminate flooring is broadening beyond production homebuilders toward independent remodeling contractors and direct-to-consumer channels. Mohawk Industries leverages its captive resin and substrate operations to control input costs across multiple price tiers. Shaw Industries anchors its position through extensive distributor relationships and private-label partnerships with big-box retailers. Mannington Mills differentiates via specialty textures and domestically manufactured cores that appeal to regionally concentrated contractor networks.
Laminate flooring comprises a multi-layer synthetic product with a high-density fiberboard core, decorative melamine-impregnated paper, and aluminum oxide wear layer, engineered to replicate hardwood or stone aesthetics at lower installed cost. High-pressure laminate dominates commercial specifications due to superior impact resistance and dimensional stability under rolling loads. Waterproof laminate represents the fastest-expanding product category as homeowners prioritize moisture tolerance for kitchens, basements, and multifamily units. The 12mm thickness segment sustains premium positioning through enhanced acoustic performance and underfoot feel that narrows the gap with engineered hardwood.
CARB Phase 2 and EPA TSCA Title VI govern formaldehyde emissions from composite wood substrates, compelling manufacturers to certify supply chains or face market exclusion from California and states adopting identical standards. The U.S. Consumer Product Safety Commission and FloorScore certification program shape indoor air quality expectations that influence architect and specifier decisions. Stakeholders must monitor evolving state-level adoption of California's regulatory framework and the pace at which waterproof core technologies achieve cost parity with traditional high-density fiberboard constructions.
Market Dynamics
Waterproof core technology is compressing the performance gap between laminate and engineered hardwood, redirecting renovation spending toward synthetic alternatives that withstand moisture exposure in basements and kitchens.
Growth Catalysts
- CARB Phase 2 compliance:California's formaldehyde emissions standards have created a certification moat that rewards domestic substrate producers with verified supply chains.
- Millennial renovation cycles:First-time homeowners in Texas and Florida are replacing flooring at shorter intervals than previous generations, expanding replacement demand beyond new construction.
- High-pressure laminate specifications:Commercial property managers specify HPL for retail and hospitality spaces requiring dimensional stability under rolling loads.
Market Restraints
- Resin input volatility:Urea-formaldehyde and melamine resin prices fluctuate with natural gas feedstock costs, compressing margins for non-integrated manufacturers.
- Southeast Asian substrate concentration:High-density fiberboard core supply concentrates in Thai and Vietnamese mills, exposing North American brands to container freight rate spikes.
- Engineered hardwood substitution:Falling prices for oak and maple engineered products narrow the installed-cost advantage of premium laminate thicknesses.
Strategic Opportunities
- Waterproof core cost parity:Stone-plastic composite and rigid core technologies approaching price equivalence with traditional HDF will unlock multifamily and hospitality specifications.
- Direct-to-consumer channels:Sample-to-door logistics and virtual room visualization tools are disintermediating distributor networks in suburban renovation markets.
- Title 24 building standards:California's energy efficiency mandates for residential construction create specification pull for thermally efficient flooring assemblies.
Industry Challenges
- Floorscore certification timelines:Third-party indoor air quality testing adds 8-12 weeks to product launch schedules, delaying seasonal collection releases.
- Legacy distributor integration:Big-box retail private-label programs require ERP system compatibility and just-in-time inventory protocols that strain regional flooring distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Laminate Flooring Market |
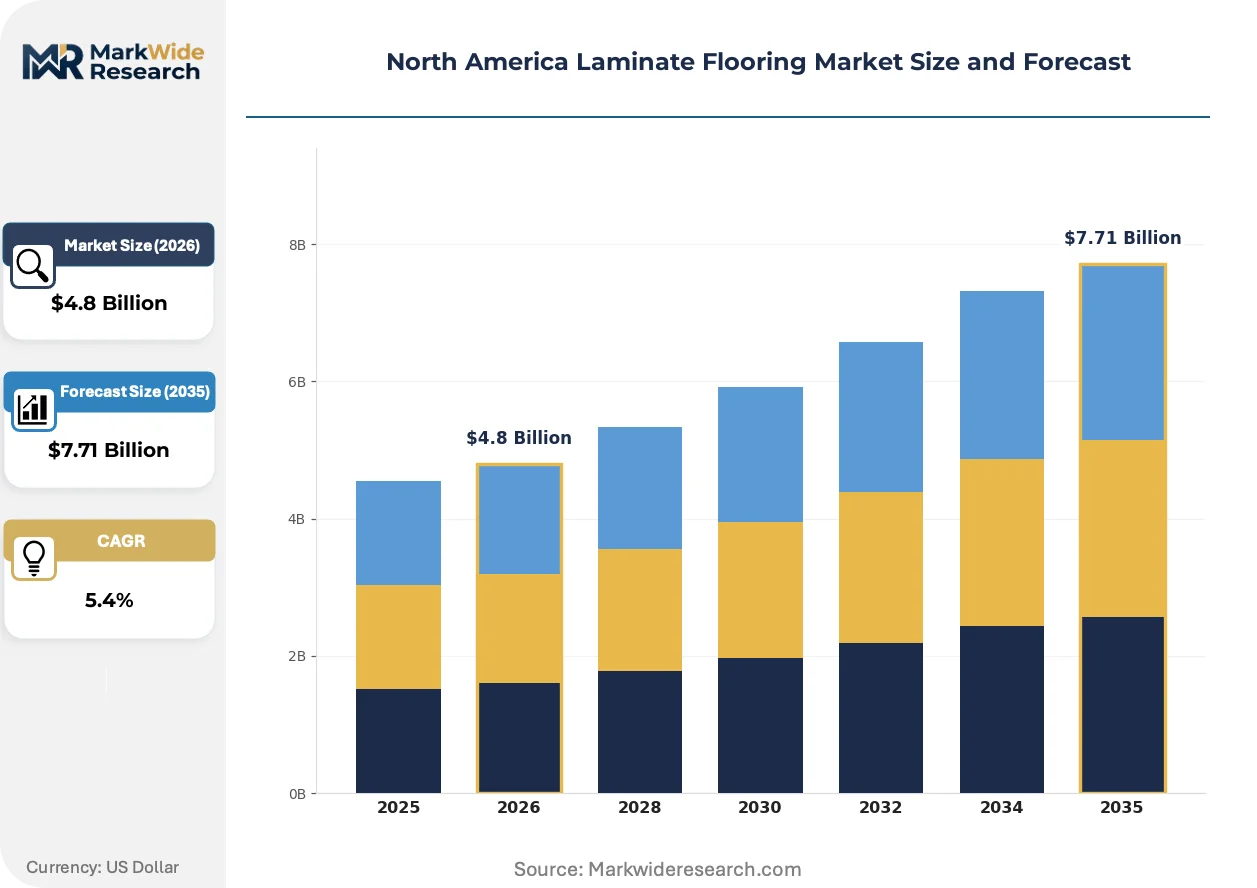
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.71 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Pressure Laminate, Direct-Pressure Laminate, Waterproof Laminate, Acoustic Laminate End User: Residential, Commercial, Institutional, Hospitality Thickness: 8mm, 10mm, 12mm, 14mm Texture: Smooth, Textured, Embossed, Hand-Scraped |
| Companies Covered | Mohawk Industries, Shaw Industries, Armstrong Flooring, Mannington Mills, Tarkett, Pergo, Formica Group, Kronospan, Swiss Krono Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Laminate Flooring Market Strategic Shifts & Innovations
Digital printing and rigid core engineering are collapsing the traditional trade-offs between cost, durability, and aesthetic authenticity that once segmented flooring categories.
Waterproof laminate constructions incorporating stone-plastic composite cores are decentralizing category boundaries between traditional laminate, vinyl plank, and engineered hardwood. Multifamily developers in Florida and Georgia specify these products for ground-floor units previously reserved for tile or luxury vinyl. The technology is decentralizing how flooring categories compete for moisture-prone applications.
EPA TSCA Title VI formaldehyde standards are tightening substrate sourcing requirements across state-level adoptions of California's regulatory framework. Manufacturers must maintain chain-of-custody documentation from particleboard mills through finished goods. Laminate products targeting architect-specified commercial projects face the most stringent documentation burdens.
Independent remodeling contractors are consolidating material procurement through pro-focused digital platforms that bundle flooring with installation accessories and underlayment. These platforms displace traditional two-step distribution through regional flooring wholesalers. Texas and Florida metropolitan areas exhibit the fastest contractor adoption of consolidated procurement portals.
North America Laminate Flooring Market Segmentation
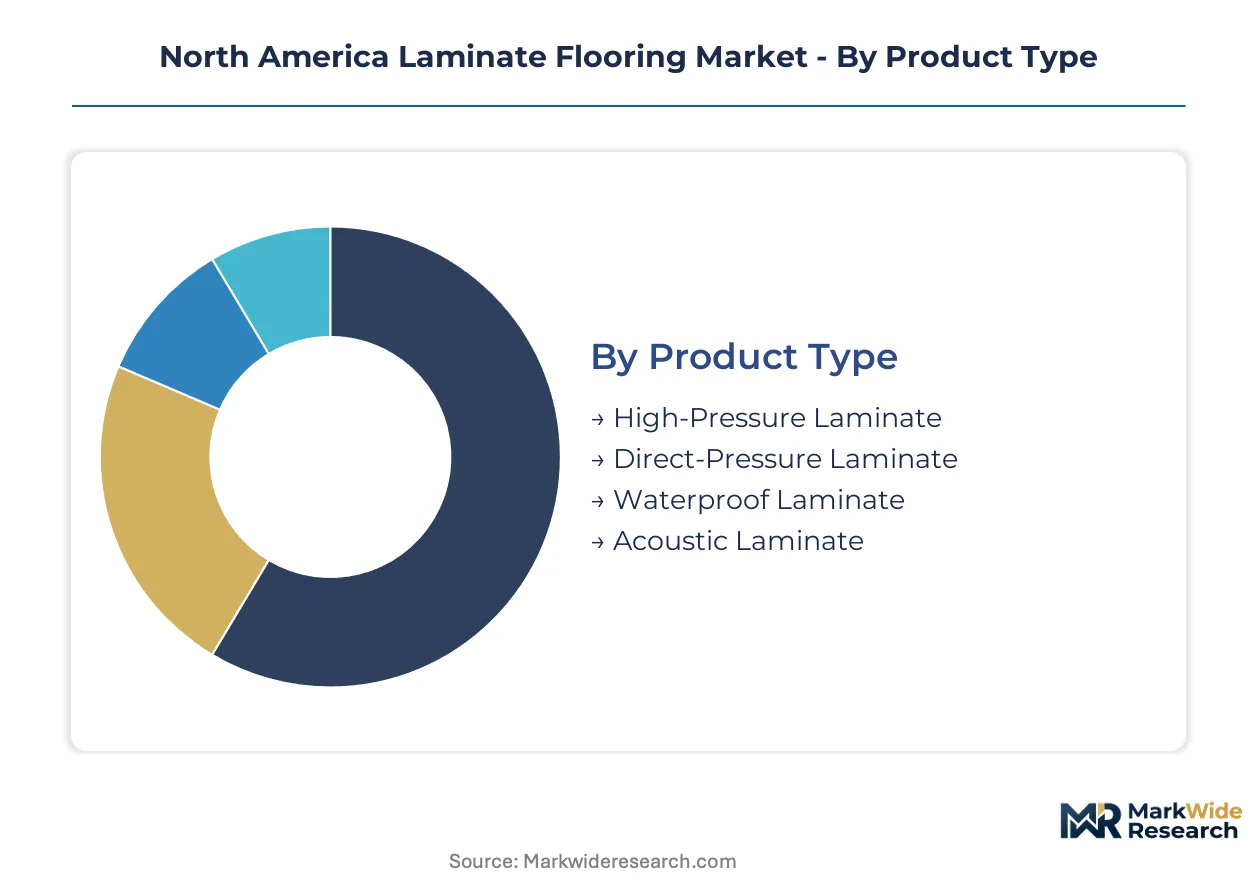
Segmentation in the North American laminate flooring market reveals how certification requirements, performance specifications, and installation contexts fragment demand across distinct buyer workflows. Manufacturers configure product portfolios to match the compliance burdens and performance thresholds that govern each segment's specification process.
Product Type:
High-pressure laminate carries the heaviest FloorScore and CARB Phase 2 documentation burdens, while waterproof variants face emerging moisture-resistance testing protocols that lack federal standardization.
- High-Pressure Laminate:Constructed under sustained heat and pressure exceeding 1,000 psi, yielding superior impact resistance and dimensional stability. Demand concentrates in Texas retail corridors and Florida hospitality renovations where rolling loads and humidity cycles punish lesser constructions.
- Waterproof Laminate:Incorporates stone-plastic composite or rigid polymer cores that eliminate fiberboard swelling. Georgia multifamily developers specify these for ground-floor units previously reserved for tile, as shorter replacement cycles justify premium material costs.
- Direct-Pressure Laminate:Manufactured under lower pressure for residential applications with lighter traffic loads.
- Acoustic Laminate:Features integrated cork or foam underlayment layers targeting California Title 24 sound transmission requirements.
High-pressure laminate sits at the top of the volume ranking, with waterproof laminate climbing the fastest.
End User:
Cost tier stratification separates specification-driven commercial buyers from price-sensitive residential renovators, with hospitality occupying a middle ground where aesthetic differentiation commands premium positioning.
- Residential:Millennial homeowners in Florida and Texas drive replacement cycles shorter than previous generations, prioritizing moisture tolerance and click-lock installation speed over maximum wear-layer thickness.
- Commercial:Property managers specify high-pressure laminate for retail and office corridors requiring 15-year wear warranties, with FloorScore certification mandatory for LEED-aspiring developments.
- Institutional:Schools and healthcare facilities face stringent indoor air quality mandates that restrict substrate sourcing to verified low-emission supply chains.
- Hospitality:Boutique hotel developers in Georgia and California balance acoustic performance with rapid renovation turnaround, favoring 12mm thicknesses with pre-attached underlayment.
Residential commands the dominant revenue share, though hospitality applications are expanding most quickly as boutique properties proliferate across southeastern metropolitan corridors.
Thickness:
Margin structure concentrates in thicker segments where acoustic underlayment integration and premium wear layers justify price escalation, while 8mm products compete primarily on installed-cost minimization.
- 12mm:Delivers engineered hardwood-competitive underfoot feel and sound dampening through denser fiberboard cores. California contractors specify this tier for condominium renovations where HOA noise restrictions elevate acoustic performance requirements.
- 8mm:Dominates big-box retail volume through aggressive price positioning, though thinner cores amplify subfloor imperfection transmission and shorten product lifespans in high-traffic zones.
- 10mm:Occupies the standard-grade middle market where residential renovation budgets constrain specification.
- 14mm:Targets premium residential and light commercial applications requiring maximum dimensional stability.
12mm thickness holds the revenue premium, with 14mm gaining share fastest among custom home builders seeking hardwood alternatives.
Texture:
Supply concentration in digital printing equipment shapes which surface treatments achieve cost-competitive scale, with hand-scraped finishes requiring specialized tooling that limits domestic production capacity.
- Embossed:Synchronized grain patterns replicate hardwood texture through precision roller embossing synchronized to decorative paper printing. Texas and Florida distributors stock this finish most heavily for residential replacement jobs where visual authenticity influences homeowner selection.
- Hand-Scraped:Artisanal surface variation commands premium positioning in rustic and farmhouse aesthetic segments, with domestic manufacturing concentrated at specialty mills in the Southeast.
- Smooth:Dominates commercial specifications where maintenance simplicity outweighs aesthetic replication concerns.
- Textured:Generic surface treatments occupying mid-market positioning between smooth and embossed alternatives.
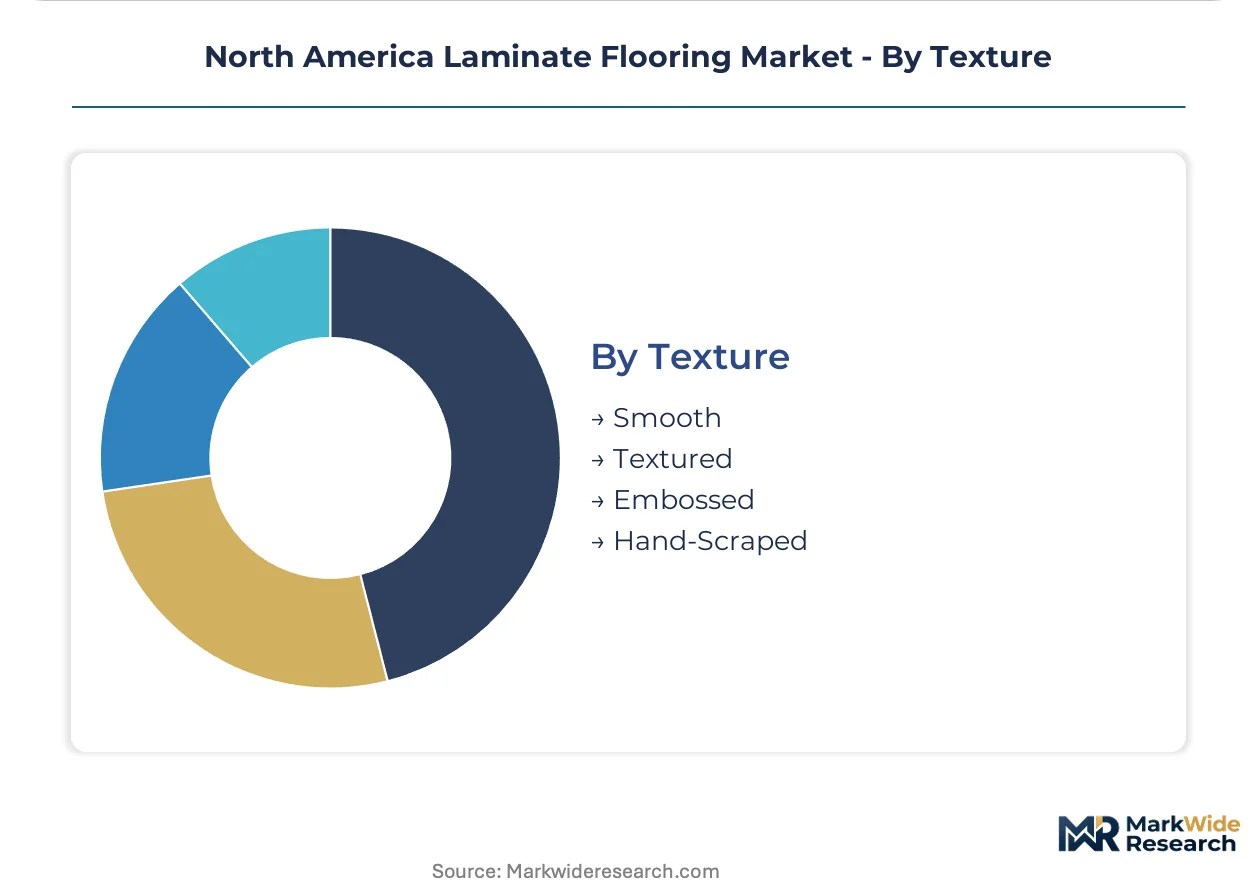
Embossed textures lead volume shipments, while hand-scraped finishes are ascending fastest as farmhouse aesthetics penetrate suburban renovation markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands substantially greater laminate flooring volume than Canada, though Mexican manufacturing capacity is expanding to serve cross-border renovation demand. Both countries face distinct regulatory compliance burdens and supply chain configurations.
United States
Texas and Florida metropolitan corridors drive replacement demand as millennial homeowners complete shorter renovation cycles than prior generations. EPA TSCA Title VI formaldehyde standards govern substrate sourcing across state-level adoptions of California's regulatory framework. The Southeast industrial corridor spanning Georgia and the Carolinas hosts densified fiberboard mills supplying domestic laminate producers.
Canada
Ontario and Quebec renovation markets prioritize moisture-resistant constructions for basement applications in older housing stock. Health Canada and PMRA oversee indoor air quality guidelines that align with California CARB Phase 2 emission thresholds. The Greater Toronto Area concentrates distribution infrastructure serving both domestic demand and re-export to US border states.
Mexico
Nuevo León and Jalisco manufacturing clusters leverage integrated resin production and proximity to Texas construction markets. Mexican federal environmental standards under SEMARNAT govern industrial emissions from composite wood substrate facilities. The Bajío Region is attracting laminate finishing operations seeking to reduce cross-border logistics exposure for US-bound shipments.
North America Laminate Flooring Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across a market structure that rewards vertical control over resin and substrate supply chains. Three to five major manufacturers anchor the landscape alongside regional fabricators serving contractor networks. Strategic archetypes include integrated resin-to-finish producers, distributor-centric brands, and specialty texture developers. Dominant competitive moves center on captive substrate capacity expansion and private-label partnerships with big-box retail channels.
Among US-based manufacturers, Mohawk Industries and Shaw Industries exemplify scale-driven integrated producers with captive supply chain control, while Mannington Mills occupies a position within the specialty texture tier serving regionally concentrated contractor networks.
| Leading Market Players |
|---|
| Mohawk Industries |
| Shaw Industries |
| Armstrong Flooring |
| Mannington Mills |
| Tarkett |
| Pergo |
| Formica Group |
| Kronospan |
| Swiss Krono Group |
| Others |
Cost & Logistics Intelligence
Certification-tier divergence between CARB Phase 2-compliant domestic substrates and imported fiberboard creates parallel supply chains with distinct cost structures and pricing power. Premium waterproof laminates command material premiums through verified low-emission supply chains, while commodity-grade products compete on container freight arbitrage from Southeast Asian mills.
Pricing Analysis
Capacity additions in Mexico and the southeastern United States are reshaping price floors for mid-tier laminate products. Three-tier pricing structure across premium waterproof, standard high-pressure, and economy direct-pressure levels stratifies the market. Price differentiation rests on FloorScore certification status and captive resin production. Cost compression in the 8mm economy tier is intensifying because of Thai and Vietnamese substrate competition. Big-box retail procurement teams exhibit the highest price sensitivity, while architect-specified commercial projects tolerate premium positioning for documented compliance.
Supply Chain Analysis
Single-source vulnerability sits with Thai and Vietnamese high-density fiberboard mills supplying North American laminate producers. Manufacturing concentrates in China, Thailand, and Vietnam for decorative paper and wear-layer components. Raw material dependencies include urea-formaldehyde resins, melamine-impregnated papers, and aluminum oxide abrasives. Tariff exposure on Chinese decorative paper imports threatens margin stability for non-integrated brands. Distribution runs through regional flooring wholesalers in Texas and Florida, with direct-to-consumer channels displacing traditional two-step networks in suburban renovation markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waterproof core technology maturation offers margin expansion as stone-plastic composite production scales toward cost parity with traditional fiberboard. Premium-tier shift toward 12mm and 14mm thicknesses with integrated acoustic underlayment supports pricing power in California and southeastern condominium markets.
For Market Incumbents: Extend captive substrate capacity in Georgia and the Carolinas to defend against Southeast Asian freight volatility. Secure FloorScore certification moats ahead of broader EPA TSCA Title VI state adoptions. Backward integration into melamine resin production anchors margin control across multiple price tiers. Reinforce distributor relationships in Texas and Florida through just-in-time inventory protocols compatible with big-box retail private-label programs. For New Entrants and Emerging Players: The gap between premium waterproof laminate and economy direct-pressure products creates white-space opportunity in the standard-grade 10mm segment. Target Georgia and Florida multifamily developers seeking moisture-resistant specifications without luxury vinyl pricing. Pursue specialty texture differentiation through digital printing investments that replicate hand-scraped aesthetics at scale. Leverage pro-focused digital procurement platforms to bypass entrenched wholesale distribution in metropolitan contractor markets. For Investors and Strategic Acquirers: Consolidation pressure builds where regional fabricators lack CARB Phase 2 verification and face exclusion from California-adjacent state markets. Long-term viability favors integrated producers with captive resin operations and domestic substrate mills over import-dependent assemblers. Acquisition target archetype: mid-cap Southeast manufacturers with verified supply chains and underutilized waterproof core capacity. Watch EPA TSCA Title VI adoption velocity across northeastern and midwestern states as inflection indicator for regulatory-driven market concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Waterproof Core Capacity Expansion | Stone-plastic composite scale-up unlocks multifamily specifications in Florida and Georgia ground-floor units. |
| CARB Phase 2 Certification Investment | Verified low-emission supply chains secure access to California and adopting state markets. |
| Direct-to-Consumer Channel Development | Sample-to-door logistics disintermediate regional distributors in Texas and Florida renovation markets. |
| Backward Integration into Resin Production | Captive urea-formaldehyde and melamine supply insulates margins from natural gas feedstock volatility. |
| Acoustic Underlayment Integration | Pre-attached cork and foam layers address California Title 24 sound transmission mandates in condominium renovations. |
Research Approach
Bottom-up residential and commercial flooring demand modeling reconciled against top-down substrate production tracking forms the analytical core. Primary interviews with laminate product managers, regional distributor owners, big-box retail category buyers, and independent remodeling contractors combined with secondary validation. Secondary sources include EPA TSCA Title VI certification databases, CARB composite wood product listings, FloorScore indoor air quality registries, and customs trade data on HDF substrate imports. Triangulation between installation volume estimates and mill production capacity ensures coherence across supply and demand sides.
Historical trendline analysis of replacement cycle frequencies and new construction flooring specifications established baseline growth patterns across the analysis window. Segmentation dimensions modeled include product type, thickness tier, end-use application, and regional regulatory cluster. CAGRs were derived from regression analysis against housing start data and renovation spending indices. Industry-specific forecast inputs include millennial homeownership rates in Texas and Florida, and state-level adoption timelines for California's formaldehyde emissions framework.
Caveats apply where container freight rate spikes, resin feedstock volatility, or accelerated EPA enforcement could materially shift the outlook. Forecasts reflect documented assumptions about waterproof core cost convergence and state regulatory adoption trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
China Laminate Flooring Market
Flooring, Carpets, and Rugs
Brazil Floor Covering Market
Flooring, Carpets, and Rugs
US Terrazzo Market
Flooring, Carpets, and Rugs
Carpets and Rugs Market
Flooring, Carpets, and Rugs
Global Flooring and Carpet Market
Flooring, Carpets, and Rugs
US Resilient Flooring Market
Flooring, Carpets, and Rugs
US Wood Flooring Market
Flooring, Carpets, and Rugs
Saudi Arabia Floor Covering Market
Flooring, Carpets, and Rugs
India Wood Flooring Market
Flooring, Carpets, and Rugs
Hardwood Flooring Market
Flooring, Carpets, and Rugs
Global Luxury Vinyl Tile Floor Covering Market
Flooring, Carpets, and Rugs
Canada Terrazzo Flooring Market
Flooring, Carpets, and Rugs
United States Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
India Floor Covering Market
Flooring, Carpets, and Rugs
Wood Flooring Market
Flooring, Carpets, and Rugs
GCC Floor Covering Market