
 Home Decor and Accessories Market | 2026-2036
Home Decor and Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Home Decor and Accessories Market Analysis
Premium-grade sustainable certification is reorganizing supplier hierarchies across the home decor sector. Inter IKEA Systems B.V. leverages its captive forest stewardship and flat-pack logistics to sustain margin efficiency at scale. Herman Miller Inc. anchors its position through ergonomic design patents and commercial contract channels. Williams-Sonoma Inc. differentiates via artisan-sourced collections and direct-to-consumer digital infrastructure.
Home decor and accessories comprise movable ornamental and functional objects—including textiles, lighting fixtures, wall coverings, and furniture—typically manufactured through CNC machining, hand-weaving, blown-glass forming, or upholstery fabrication, with specifications governing fire resistance, VOC emissions, and dimensional tolerances for residential and hospitality interiors. Wood and fabric materials dominate current production volumes, though metal and glass are gaining share in lighting and accent categories where industrial and modern style preferences are accelerating. The distribution channel structure shows online platforms capturing transaction frequency while specialty stores retain higher-margin custom and vintage segments.
EPA regulates formaldehyde emissions in composite wood products under TSCA Title VI, while ECHA REACH restricts hazardous substances in textile and metal finishes sold across Europe; California's Air Resources Board maintains stricter state-level VOC thresholds that de facto shape national product specifications. India's BIS certification requirements for furniture safety and flammability are tightening import conditions. Stakeholders must monitor evolving chemical disclosure mandates and carbon-border adjustment mechanisms to preserve market access and avoid stranded inventory in cross-border supply chains.
Market Dynamics
EU Green Deal compliance deadlines and ECHA REACH chemical restrictions are forcing residential real estate developers to requalify entire supplier bases before 2027 certification renewals.
Growth Catalysts
- EU Green Deal procurement mandates:Residential developers in Germany, France, and the Netherlands now require FSC-certified wood and OEKO-TEX textiles in bulk furnishing contracts.
- CNC machining automation:Furniture manufacturers in Vietnam and Poland deploy robotic cutting systems to reduce dimensional tolerance defects and accelerate custom order turnaround.
- Urban middle-class expansion:Household formation in Mumbai, Delhi, and Bangalore drives premium furniture adoption as apartment sizes shrink and multi-functional designs gain preference.
Market Restraints
- Volatile engineered wood input costs:MDF and particleboard prices fluctuate with resin and timber feedstock availability, compressing margins for flat-pack furniture producers.
- Supply concentration in Chinese glassblowing:Hand-blown lighting fixture production clusters in Guangdong province, creating single-source risk for artisan-grade pendant collections.
- Substitution by vintage resale platforms:Online marketplaces for pre-owned designer furniture capture price-sensitive segments seeking authenticated second-hand pieces.
Strategic Opportunities
- Underpenetrated Saudi residential fit-out:Riyadh and Jeddah luxury apartment developments lack certified sustainable furnishing suppliers, creating first-mover openings for EU-compliant manufacturers.
- Modular upholstery systems:Component-based sofa platforms allow consumers to replace worn sections rather than discard entire units, aligning with circular economy frameworks.
- India BIS flammability certification:Tightening import safety standards for upholstered furniture creates localized production incentives for domestic manufacturers meeting IS 1891 specifications.
Industry Challenges
- Artisan weaving skill scarcity:Hand-loom textile production for wall coverings and rugs faces generational talent gaps in traditional manufacturing regions of India and Morocco.
- Multi-certification timeline compression:Simultaneous EPA TSCA Title VI, ECHA REACH, and California CARB compliance documentation extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Decor and Accessories Market |
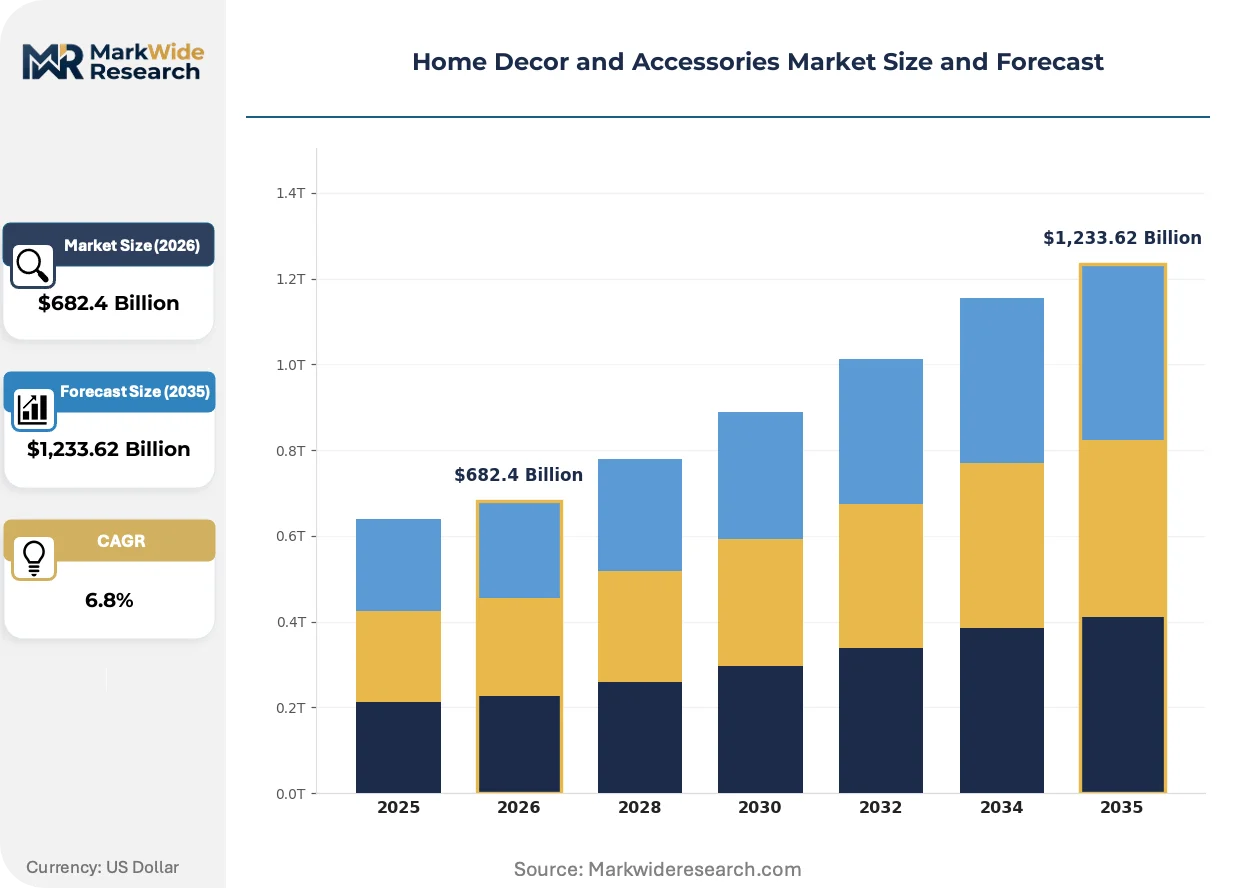
| Market Size in 2026 | $682.4 Billion |
| Market Size in 2035 | $1,233.62 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall Art, Rugs, Lighting, Furniture Material: Wood, Metal, Fabric, Glass Style: Modern, Vintage, Rustic, Industrial Distribution Channel: Online, Offline, Specialty Stores, Mass Retailers |
| Companies Covered | West Elm, Herman Miller Inc., Inter IKEA Systems B.V., Safavieh Couture, Bernhardt, Williams-Sonoma Inc., Ethan Allen Global, Four Hands, Ashley Furniture Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Decor and Accessories Market Emerging Trajectories
Digital fabrication and material traceability systems are reorganizing how home decor specifications travel from designer intent to finished product, compressing traditional quality assurance stages.
Parametric design software is decomposing conventional furniture prototyping workflows. Interior design studios in Copenhagen and Milan adopt algorithmic form-generation tools to produce limited-run customizable pieces. This capability is decomposing the barrier between mass production and bespoke manufacturing, enabling mid-size manufacturers to offer made-to-order economics at near-standard price points.
ECHA REACH Annex XVII restrictions on chromium VI in leather tanning entered full enforcement across EU member states in late 2024. Tanneries in Italy and Spain have retrofitted wastewater treatment systems to comply, passing compliance costs to upholstery suppliers. Premium leather furniture lines now carry extended chemical testing documentation, with hospitality procurement teams in Portugal and Greece demanding batch-level certificates of conformity.
Direct-to-consumer digital showrooms displace traditional wholesale furniture buying. Urban millennials in São Paulo and Mexico City browse AR-enabled product visualizations before purchasing, bypassing brick-and-mortar intermediaries. This channel compression is most visible in lighting and accent furniture categories where shipping logistics favor parcel-scale dimensions over freight-dependent case goods.
Home Decor and Accessories Market Segmentation
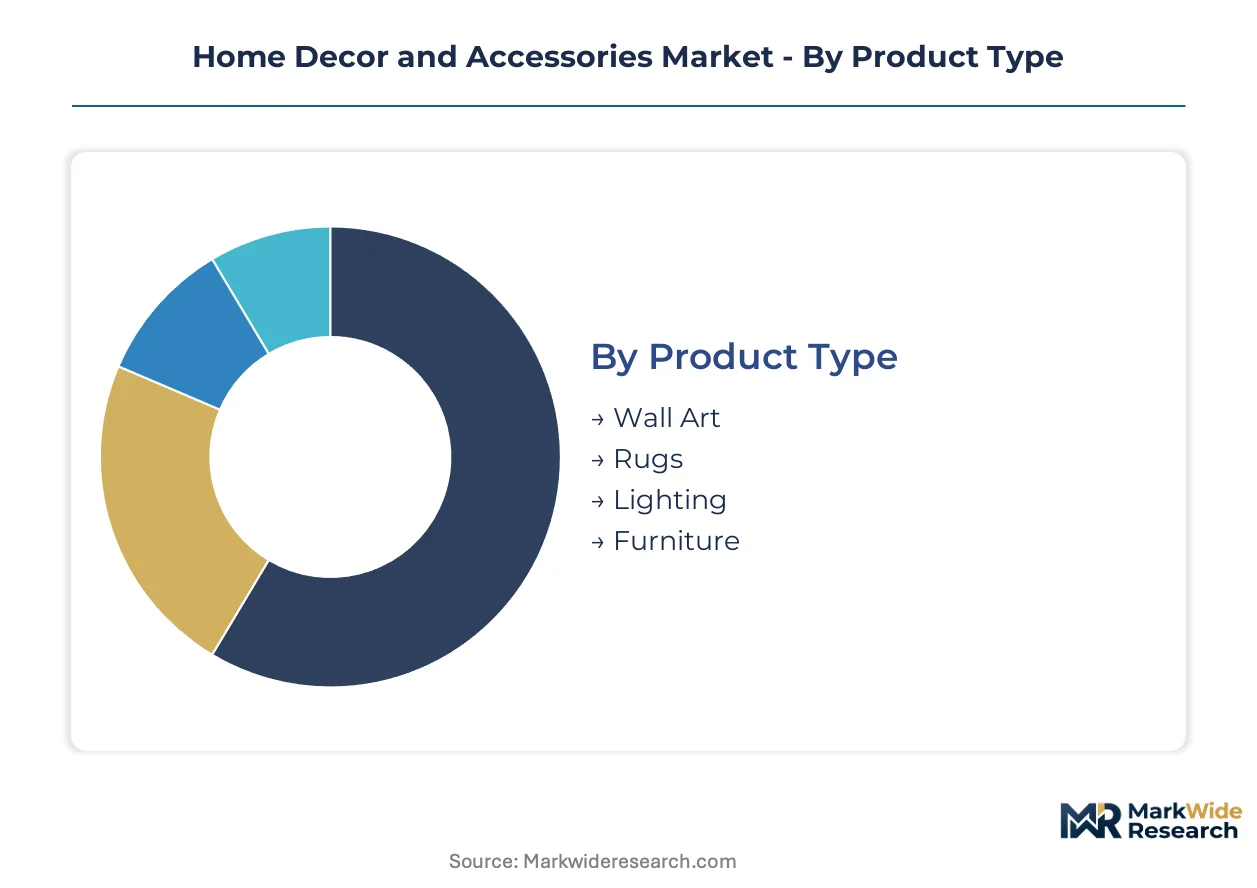
Segmentation in home decor and accessories reveals how channel economics, material specifications, and style preferences fragment procurement patterns across residential and hospitality buyers. Understanding these divides exposes where margin compression concentrates and where premium positioning remains defensible.
Product Type:
Channel mix varies sharply across product categories—furniture commands freight-dependent logistics while wall art and lighting travel through parcel networks that favor digital intermediaries.
- Wall Art:Canvas prints, framed photography, and mixed-media installations dominate. Demand concentrates in urban apartment markets where renters seek non-permanent decorative solutions; direct-to-consumer platforms capture transaction frequency through AR visualization tools.
- Rugs:Hand-knotted wool, machine-tufted synthetics, and flat-weave cotton constructions span price tiers. Hospitality procurement in Portugal and Greece drives certified sustainable sourcing as ECHA REACH compliance tightens chemical documentation requirements.
- Lighting:Pendant, floor, and table fixtures in blown glass and machined metal.
- Furniture:Seating, storage, and surface products across residential and contract applications.
By volume, furniture leads. By growth pace, lighting is expanding most quickly.
Material:
Cost tier stratification separates certified sustainable inputs from commodity alternatives, with regulatory compliance adding premium capture for traceable supply chains.
- Wood:Solid hardwood, engineered composites, and FSC-certified timber. Residential developers in Germany and the Netherlands mandate chain-of-custody documentation; EU Green Deal procurement deadlines compress supplier qualification timelines.
- Metal:Wrought iron, aluminum extrusions, and brass castings for frame and accent applications. Industrial style preference in São Paulo accelerates demand for raw-finish steel and aged patina treatments.
- Fabric:Natural and synthetic textiles for upholstery and soft goods.
- Glass:Hand-blown and molded forms for lighting and decorative objects.
By volume, wood leads. By margin expansion, metal is climbing the fastest.
Style:
Application context determines style selection—hospitality contracts favor cohesive aesthetic programming while residential purchases fragment across individual taste.
- Modern:Clean lines, minimal ornamentation, and neutral palettes characterize this segment. CNC machining automation in Vietnam and Poland enables cost-efficient production of geometric forms; urban middle-class households in Mumbai and Delhi drive adoption as apartment sizes shrink.
- Vintage:Reproduction and authenticated period pieces. Online resale platforms capture price-sensitive demand; authentication services create margin opportunities for specialty retailers.
- Rustic:Distressed finishes, natural textures, and farmhouse-influenced forms.
- Industrial:Exposed hardware, raw materials, and utilitarian aesthetics.
By volume, modern leads. By channel shift, vintage is gaining share fastest.
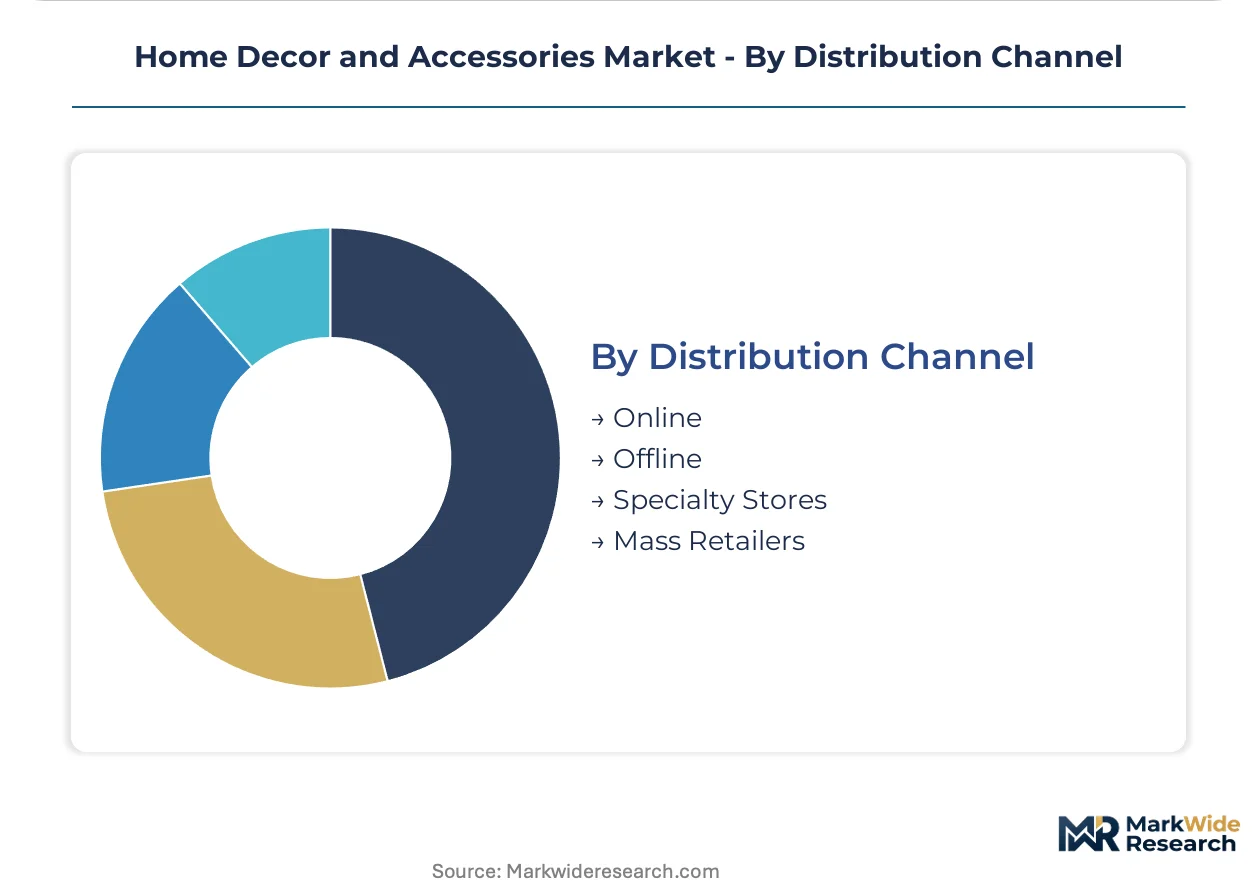
Distribution Channel:
Customer type and purchase occasion fragment across channels—impulse accent purchases favor digital convenience while investment furniture retains showroom dependency.
- Online:Digital marketplaces and direct-to-consumer brand sites. AR-enabled visualization drives conversion among millennials in Mexico City; logistics constraints limit penetration to parcel-scale products.
- Offline:Traditional brick-and-mortar retail including furniture galleries and department stores. Custom upholstery and case goods retain showroom requirements; higher touch service justifies premium pricing.
- Specialty Stores:Curated assortments targeting design professionals and affluent consumers.
- Mass Retailers:Volume-oriented distribution through big-box and hypermarket channels.
By transaction frequency, online leads. By margin retention, specialty stores are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flat-pack furniture production clusters in Poland and Vietnam now feed EU and North American demand through automated CNC machining corridors. Chemical compliance documentation requirements fragment supplier access across jurisdictions.
Germany
Residential developers in Berlin and Munich mandate FSC-certified timber and OEKO-TEX textiles under EU Green Deal procurement deadlines. ECHA REACH Annex XVII restrictions on chromium VI in leather tanning force upholstery suppliers to retrofit wastewater systems. The North Rhine-Westphalia furniture belt concentrates automated panel processing for flat-pack distribution.
United States
EPA TSCA Title VI formaldehyde emission rules and California CARB stricter thresholds shape national composite wood specifications. Direct-to-consumer digital showrooms displace wholesale buying among urban millennials. The Southeast manufacturing corridor—North Carolina and Virginia—hosts upholstered furniture production serving hospitality procurement.
India
Urban middle-class household formation in Mumbai, Delhi, and Bangalore drives premium multi-functional furniture adoption as apartment sizes contract. BIS certification requirements for furniture safety and flammability tighten import conditions under IS 1891 specifications. The Jodhpur-Miraj hand-loom belt faces generational weaving talent gaps in rug and textile production.
China
Hand-blown lighting fixture production concentrates in Guangdong province, creating single-source risk for artisan-grade pendant collections. The country's dual carbon goals pressure energy-intensive glassblowing and metal finishing operations. Yangtze River Delta furniture exporters navigate EU carbon-border adjustment mechanism documentation requirements.
Saudi Arabia
Riyadh and Jeddah luxury apartment developments lack certified sustainable furnishing suppliers, creating first-mover openings for EU-compliant manufacturers. SFDA and SASO conformity assessment programs extend product registration timelines for imported case goods. The NEOM giga-project corridor is specifying modular upholstery systems for residential fit-out.
Home Decor and Accessories Market Vendor Landscape
Concentration sits with scale-driven flat-pack specialists and premium artisan-curators. The vendor base separates into three strategic archetypes: captive forest-stewardship operators with integrated logistics, ergonomic design patent holders serving commercial contract channels, and direct-to-consumer digital infrastructure builders. Competitive moves center on supplier base requalification for chemical compliance and parametric design software deployment for made-to-order economics.
Among scale-driven furniture systems operators, Inter IKEA Systems B.V. exemplifies captive supply chain control through forest stewardship certification and flat-pack logistics efficiency. Herman Miller Inc. occupies a position within the ergonomic commercial contract tier, anchored by design patent portfolios. Williams-Sonoma Inc. represents the artisan-sourced digital infrastructure archetype, curating collections through direct-to-consumer platforms.
| Leading Market Players |
|---|
| West Elm |
| Herman Miller Inc. |
| Inter IKEA Systems B.V. |
| Safavieh Couture |
| Bernhardt |
| Williams-Sonoma Inc. |
| Ethan Allen Global |
| Four Hands |
| Ashley Furniture Industries |
| Others |
Supply Flow & Price Mechanics
Engineered wood substitution for solid timber in flat-pack furniture simultaneously shifts production gravity toward Poland and Vietnam while compressing margin structures for manufacturers lacking captive resin supply or automated panel processing capabilities.
Pricing Analysis
ECHA REACH and EPA TSCA Title VI dictate the pricing tier structure across the home decor sector. Three-tier pricing stratifies across FSC-certified premium collections, standard CARB-compliant mid-market lines, and economy-grade untreated imports. Price differentiation rests on certification documentation depth and chain-of-custody traceability. Cost compression in particleboard and MDF tiers is intensifying because resin feedstock volatility and EU carbon-border adjustment documentation requirements are layering compliance overhead onto landed costs. Hospitality procurement teams in Portugal and Greece show the least price sensitivity, demanding batch-level chemical certificates, while urban millennial renters in São Paulo and Mexico City drive digital marketplace price transparency.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes are reshaping inbound logistics economics for hand-blown lighting fixtures and machined metal components. Production concentrates in China for artisan glassblowing, Vietnam and Poland for CNC-machined flat-pack furniture, and India for hand-loom textiles. Raw material dependencies encompass timber feedstocks from Baltic and Southeast Asian forests, resin binders for engineered panels, and chromium-free leather tanning inputs. Single-source vulnerability concentrates in Guangdong province lighting clusters. Distribution runs through direct-to-consumer digital platforms for parcel-scale accents and specialty retail galleries for freight-dependent case goods.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The home decor market operates as a certification-moat arena where regulatory entrenchment creates switching costs for hospitality and residential developers facing compressed supplier requalification timelines.
For Market Incumbents: Secure captive forest stewardship certification and automated CNC machining corridors in Vietnam and Poland to defend against margin compression from volatile engineered wood input costs. Deepen backward integration into resin supply or OEKO-TEX textile finishing to preserve documentation advantages as EU Green Deal procurement deadlines tighten. For New Entrants and Emerging Players: BIS flammability certification fast-tracks unlock first-mover positioning in India's tightening import safety environment under IS 1891 specifications. Target modular upholstery systems for Saudi Arabia's NEOM corridor and Riyadh luxury fit-out gaps where EU-compliant sustainable furnishing suppliers remain scarce. Pursue direct-to-consumer AR-enabled digital showrooms to bypass wholesale intermediaries in São Paulo and Mexico City. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed flat-pack logistics operators and artisan-curated digital platform builders. Five-to-ten year viability hinges on parametric design software deployment and chemical compliance documentation depth. Monitor ECHA REACH Annex XVII expansion coverage and EPA formaldehyde threshold tightening as inflection signals for stranded inventory risk and acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| FSC Certification Fast-Track | EU Green Deal procurement mandates in Germany and the Netherlands require chain-of-custody documentation for residential developer contracts. |
| CNC Machining Automation | Robotic cutting systems in Vietnam and Poland reduce dimensional tolerance defects and accelerate custom furniture turnaround. |
| Direct-to-Consumer Digital Launch | AR-enabled product visualization captures urban millennial demand in São Paulo and Mexico City while bypassing wholesale intermediaries. |
| Modular Upholstery Platform | Component-based sofa systems align with circular economy frameworks and specify into Saudi Arabia's NEOM residential fit-out. |
| Artisan Weaving Skill Pipeline | Generational talent gaps in India's Jodhpur-Miraj belt threaten hand-loom rug and textile supply continuity. |
Methodological Framework
A spread of perspectives from residential real estate procurement directors, hospitality furnishing specifiers, CNC machining plant managers, chemical compliance officers, and direct-to-consumer platform operators converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against customs records, EPA TSCA filings, ECHA REACH registration databases, and BIS certification registries. Bottom-up volume modeling and top-down value triangulation anchored the analytical framework.
Segmentation dimensions modeled encompass product type, material specification, style category, and distribution channel across the projection horizon. CAGRs derived from trend extrapolation of urban household formation rates, regulatory compliance cost trajectories, and digital channel penetration curves. Industry-specific forecast inputs include EU Green Deal procurement deadline schedules and India BIS flammability standard implementation phases.
Underlying assumptions cover sustained EU regulatory enforcement, stable Asia-Europe container capacity, and India urban middle-class expansion, with deviation risk concentrated in ECHA REACH chemical restriction scope expansion and engineered wood feedstock price volatility. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Window Covering Market
Homecare and Decor
United States Home Decor Market
Homecare and Decor
US Halloween Decorations Market
Homecare and Decor
Middle East and Africa Christmas Tree Market
Homecare and Decor
Flush Door Market
Homecare and Decor
Door Stopper Market
Homecare and Decor
India Decorative Laminates Market
Homecare and Decor
Wall Clock Market
Homecare and Decor
Rift Sawn Lumber Market
Homecare and Decor
US Wallpaper Market
Homecare and Decor
Mattresses and Accessories Market
Homecare and Decor
Europe Decorative Laminates Market
Homecare and Decor
Fireplace and Stove Market
Homecare and Decor
United Arab Emirates Interior Design Market
Homecare and Decor
Plantation Shutters Market
Homecare and Decor
Asia-Pacific Interior Doors Market