
 Frame for Painting Market | 2026-2036
Frame for Painting Market Size, Share, and Industry Trends Forecast 2026-2036
Frame for Painting Market Insights
Chinese wood-processing clusters in Zhejiang and Jiangsu provinces is consolidating upstream access to paulownia and pine stock for stretcher bar production. PEBEO leverages its European distribution network to sustain brand recognition among professional ateliers. Winsor&Newton anchors the premium artist segment through specialized archival-grade frame offerings. Jiangsu High Hope International Group competes on manufacturing scale, supplying bulk orders to North American and European retailers.
A frame for painting is a rigid structural support system, typically constructed from kiln-dried wood profiles joined with mortise-and-tenon or V-nail corners, designed to stretch and hold canvas or mount rigid substrates for display and preservation. The assembly must maintain dimensional stability within ±0.5 mm per meter to prevent substrate warping over decades of exhibition. Wood material dominates commercial volume due to established craft workflows and repairability, while composite segments are gaining fastest among conservation framers seeking moisture resistance. Contemporary frame types command margin pools in the contract interior segment, where architects specify custom dimensions for hospitality and corporate installations.
EPA regulations in the United States restrict formaldehyde emissions from composite wood products, directly affecting particleboard and MDF core options used in economy framing lines. ECHA's REACH framework in Europe governs chemical content in surface coatings, compelling finish suppliers to reformulate stains and sealants for the EU market. Stakeholders must monitor evolving substance restrictions across multiple jurisdictions to determine where reformulation investments yield durable market access versus product line retirement.
Market Dynamics
REACH compliance is consolidating European finish suppliers around water-based systems while Chinese wood-processing clusters in Zhejiang and Jiangsu provinces tighten upstream control over paulownia stock, reshaping how manufacturers source dimensional stability for archival-grade assemblies.
Growth Catalysts
- Residential interior design expansion:North American design programs are scaling purchases of gallery-ready framing systems for staging and installation projects.
- REACH chemical reformulation:ECHA's substance restrictions are accelerating manufacturer migration toward low-VOC adhesives and compliant surface coatings.
- Integrated cluster economies:Zhejiang and Jiangsu wood-processing hubs are capturing scale efficiencies that serve both domestic art supply chains and export orders.
Market Restraints
- Formaldehyde emission caps:EPA restrictions on composite wood products limit particleboard and MDF core options for economy framing lines.
- Raw material concentration risk:Kiln-dried paulownia supply concentrates in specific Chinese provincial clusters, exposing buyers to localized disruption.
- Dimensional stability tolerance:The ±0.5 mm per meter specification for warp prevention demands precision milling that raises production costs.
Strategic Opportunities
- Conservation framer composite adoption:Moisture-resistant synthetic substrates are penetrating the professional preservation segment as archival alternatives.
- Contract interior specification growth:Hospitality and corporate installation architects are sourcing custom-dimension contemporary frames for built environments.
- Water-based finish technology:Reformulated stains and sealants are opening durable market access for compliant suppliers across EU member states.
Industry Challenges
- Mortise-and-tenon craft scarcity:Traditional joinery skills required for premium corner construction are diminishing among production workforces.
- Multi-jurisdiction substance tracking:Manufacturers must monitor evolving EPA, ECHA, and emerging regulatory restrictions to determine reformulation ROI versus product retirement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frame for Painting Market |
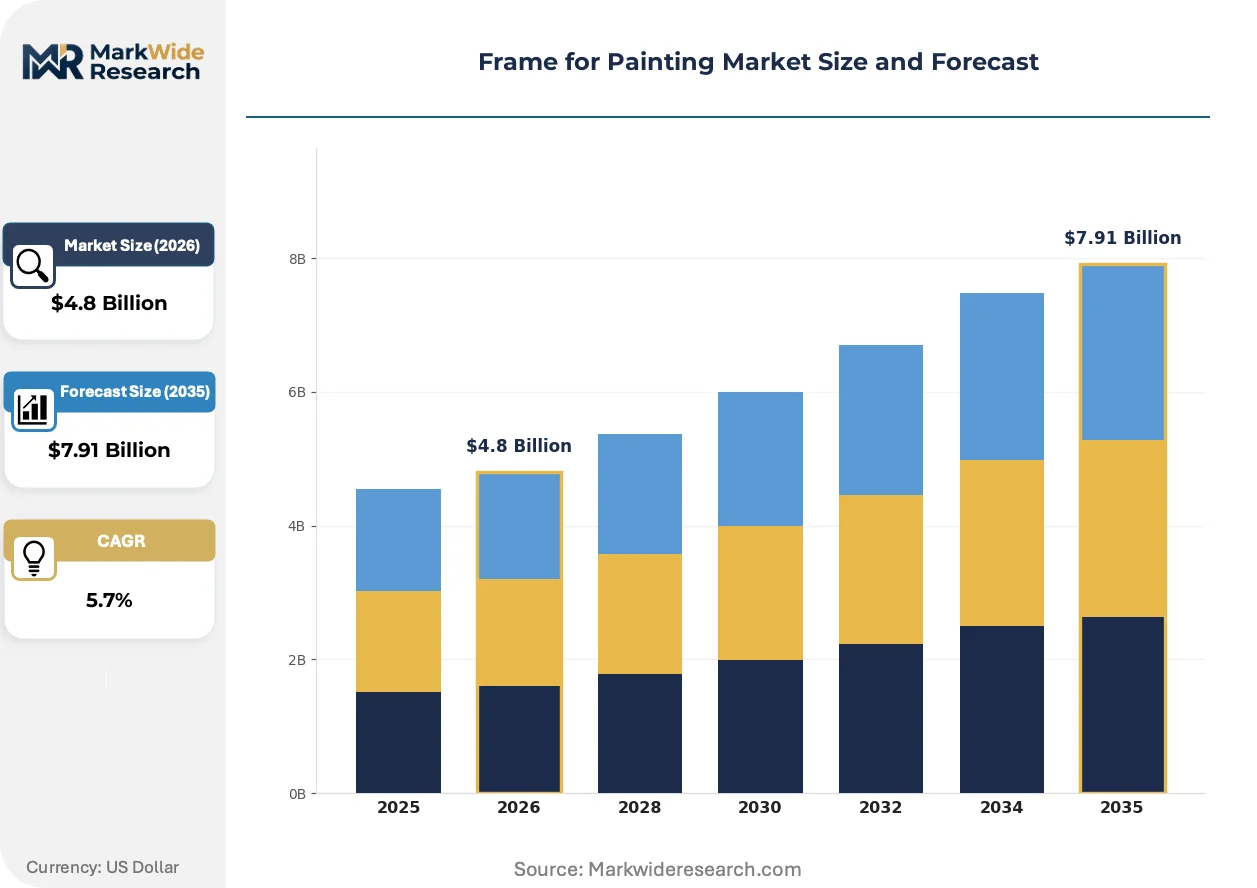
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Frame Type: Traditional, Contemporary, Floating, Canvas Material: Wood, Metal, Plastic, Composite Style: Classic, Modern, Rustic, Vintage Size: Small, Medium, Large, Custom |
| Companies Covered | Phoenix Arts Group, YINYING SPORT & STATIONERY, Langer, Anhui Zhongsheng, CONDA Group, Jiangsu High Hope International Group, PEBEO, Winsor&Newton, Shuyang Sundy Art & Craft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frame for Painting Market Trends and Innovations
Active reformulation of surface coatings and substrate materials is compressing legacy supply relationships while opening technical pathways for moisture-resistant archival systems.
Composite stretcher bar technology is consolidating moisture management capabilities into rigid support systems for conservation framers. Museum and gallery preservation departments are adopting these substrates at accelerating rates for climate-vulnerable installations. This material shift is consolidating supplier relationships around specialized polymer compounders and away from traditional hardwood mills.
ECHA's REACH framework is compelling finish suppliers to phase out solvent-based stains and sealants across EU distribution channels. Industrial coating manufacturers are retooling production lines to maintain market access under substance restriction schedules. The professional atelier segment bears the highest compliance burden as archival certification requirements intersect with reformulation timelines.
Direct procurement from integrated wood-processing clusters is replacing layered distributor relationships for volume buyers. North American retailers are establishing direct supply contracts with Zhejiang and Jiangsu manufacturers, compressing traditional import channels. This channel restructuring is most visible among residential interior design programs seeking cost efficiency on bulk gallery-ready orders.
Frame for Painting Market Segmentation
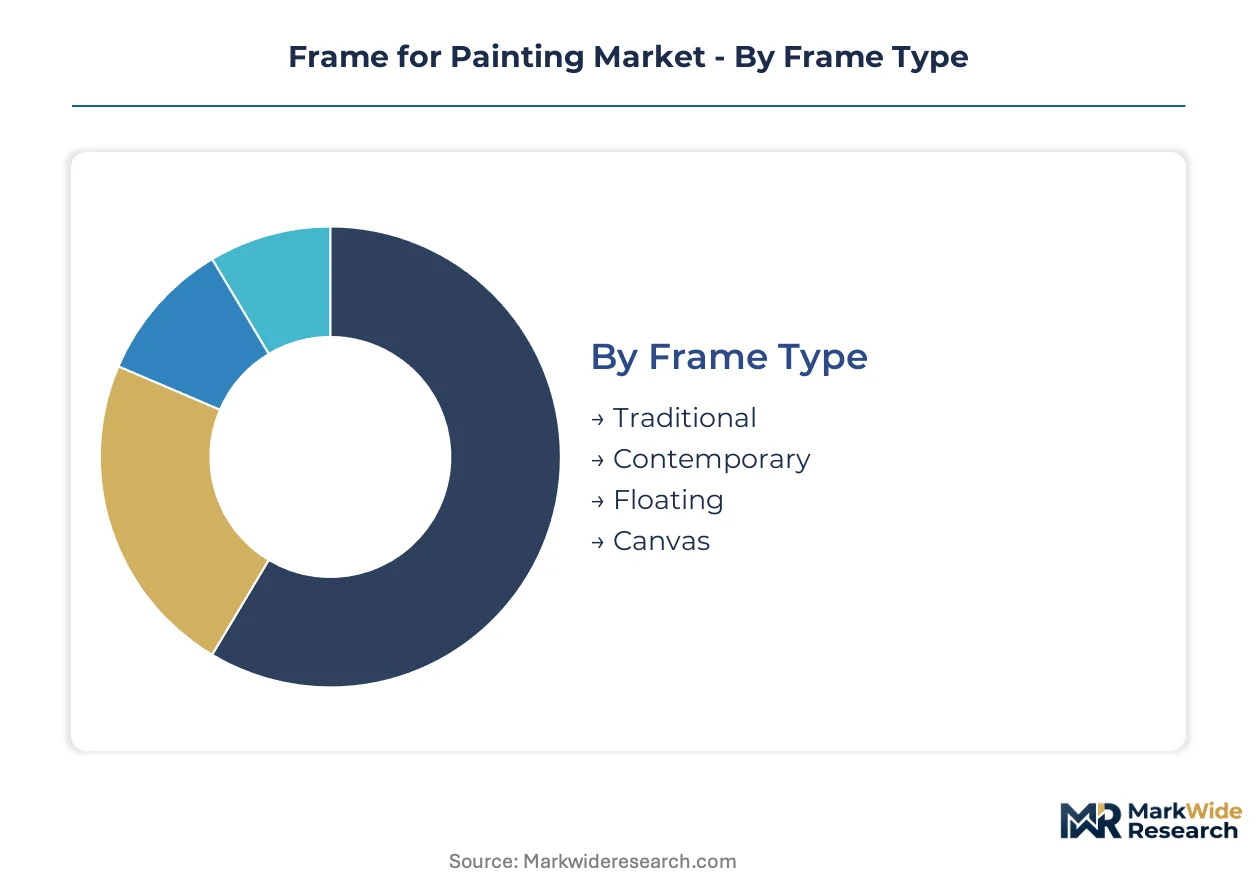
Frame segmentation determines manufacturing workflows, margin structures, and distribution channels. Material specifications drive regulatory compliance requirements. Style and size categories shape procurement patterns across residential, commercial, and institutional buyers.
Frame Type:
Construction geometry dictates substrate compatibility and installation protocols for different display environments.
- Traditional:Ornate molded profiles with gilded or stained finishes accommodate stretched canvas and panel paintings in formal residential and museum contexts. Conservation framers specify these assemblies for period-appropriate restoration projects requiring historically accurate sight lines and rabbet depths.
- Contemporary:Clean rectilinear profiles with minimal ornamentation serve contract interior specifications for hospitality and corporate installations. Architects source custom dimensions from Zhejiang and Jiangsu manufacturers for built environment projects requiring precise dimensional coordination with wall systems and lighting.
- Floating:Shadow-box construction suspends artwork within the frame perimeter, creating visual depth for gallery presentations.
- Canvas:Stretcher bar systems without applied molding provide structural support for unframed exhibition of painted surfaces.
Mature deployment sits with Traditional frames in institutional preservation. Newer deployment is concentrated in Contemporary specifications for commercial interiors.
Material:
Substrate selection governs dimensional stability, moisture resistance, and regulatory compliance across manufacturing geographies.
- Wood:Kiln-dried hardwood and softwood profiles from paulownia and pine stock dominate commercial volume through established craft workflows and repairability. REACH compliance is consolidating European finish suppliers around water-based systems for wooden frame surface treatments.
- Metal:Extruded aluminum and steel profiles provide structural rigidity for large-format and outdoor installations.
- Plastic:Injection-molded polymers serve economy framing lines with standardized dimensions.
- Composite:Moisture-resistant synthetic substrates are gaining share fastest among conservation framers seeking archival alternatives to traditional wood in climate-vulnerable installations.
Wood retains the highest volume concentration. Composite formulations are climbing the fastest in professional preservation segments.
Style:
Aesthetic categorization aligns inventory management with interior design program procurement patterns and retail merchandising.
- Classic:Ornate profiles with decorative molding reference historical European framing traditions for period interiors.
- Modern:Minimalist geometries with flat or beveled profiles coordinate with contemporary residential and commercial architecture.
- Rustic:Distressed finishes and natural wood grain presentations serve farmhouse and lodge aesthetic specifications.
- Vintage:Reproduction patinas and reclaimed material appearances target retro-styled residential installations.
Modern styling dominates contract interior procurement. Rustic styling is expanding fastest among North American residential design programs.
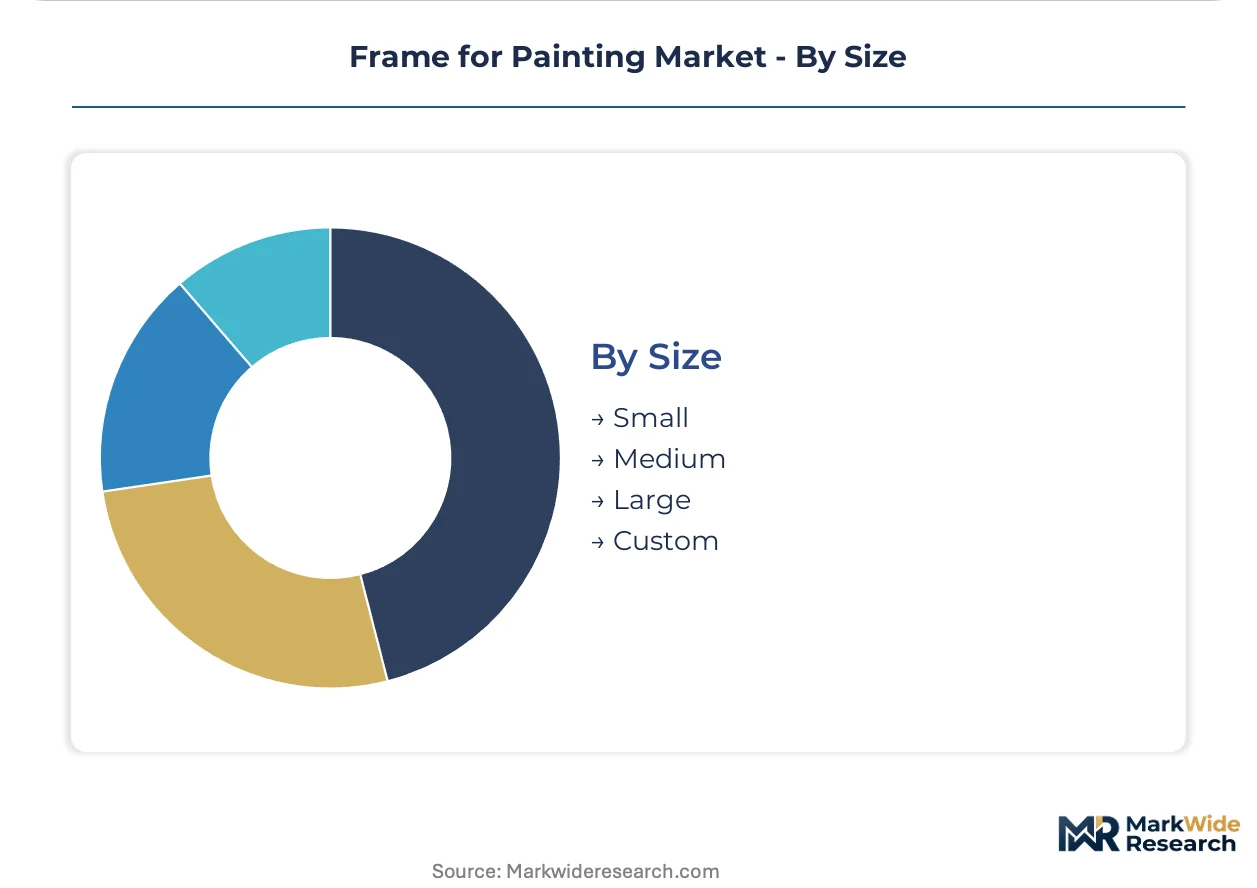
Size:
Dimension categories determine manufacturing equipment requirements, shipping logistics, and price positioning across customer segments.
- Small:Standardized dimensions under 300mm on the short side serve retail art supply and consumer photography markets.
- Medium:Mid-range formats accommodate most residential artwork and commercial print installations.
- Large:Oversized assemblies require reinforced joinery and specialized handling for gallery and corporate statement pieces.
- Custom:Non-standard dimensions specified by architects and interior designers command premium positioning through made-to-order production workflows.
Medium sizes anchor inventory turnover for volume retailers. Custom dimensions generate the steepest margin expansion for specialized manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kiln-dried paulownia stock concentrates in specific Chinese provincial clusters, anchoring upstream supply for dimensional stability in archival-grade assemblies. This geographic concentration shapes procurement patterns for manufacturers serving North American and European distribution channels.
United States
Residential interior design programs in California and New York Metro are scaling purchases of gallery-ready framing systems for staging projects. EPA formaldehyde emission caps restrict particleboard and MDF core options for economy framing lines. Dallas-Fort Worth distribution hubs are consolidating direct import relationships with Zhejiang manufacturers.
Germany
Professional ateliers in Berlin-Brandenburg and Bavaria sustain demand for archival-grade frame assemblies. ECHA REACH substance restrictions compel finish suppliers to reformulate stains and sealants for compliant surface coatings. Hamburg-area distributors are retooling logistics networks to handle water-based product lines.
China
Integrated wood-processing clusters in Zhejiang and Jiangsu provinces capture scale efficiencies serving domestic art supply chains and export orders. MIIT industrial standards govern composite substrate specifications for moisture-resistant applications. Ningbo and Suzhou manufacturing zones are tightening upstream control over paulownia and pine stock.
United Kingdom
London/Southeast conservation framers are adopting moisture-resistant synthetic substrates for climate-vulnerable museum installations. CE marking requirements coordinate with ECHA substance restrictions for surface coating compliance. Midlands craft workshops are experiencing diminished mortise-and-tenon joinery skills among production workforces.
France
Professional ateliers in Île-de-France maintain brand recognition for specialized archival-grade offerings. ANSM and CNIL frameworks intersect with ECHA chemical content governance for finish formulations. Lyon-area suppliers are consolidating water-based system distribution for EU market access.
Frame for Painting Market Competitive Landscape
Global majors compete with regional champions across manufacturing scale and distribution reach. The vendor base organizes into three tiers: integrated wood-processing conglomerates with captive raw material access, European heritage brands with atelier relationships, and specialized conservation-framing suppliers. Strategic moves concentrate on direct procurement channel establishment and water-based finish technology licensing.
Within the integrated manufacturing tier, Jiangsu High Hope International Group and Anhui Zhongsheng exemplify scale-driven positions anchored to Chinese provincial wood-processing clusters. Among heritage European suppliers, PEBEO occupies a position sustained by professional atelier distribution networks. Winsor&Newton represents the premium archival-grade segment. Phoenix Arts Group sits within the specialized conservation-framing archetype.
| Leading Market Players |
|---|
| Phoenix Arts Group |
| YINYING SPORT & STATIONERY |
| Langer |
| Anhui Zhongsheng |
| CONDA Group |
| Jiangsu High Hope International Group |
| PEBEO |
| Winsor&Newton |
| Shuyang Sundy Art & Craft |
| Others |
Pricing and Supply Chain Analysis
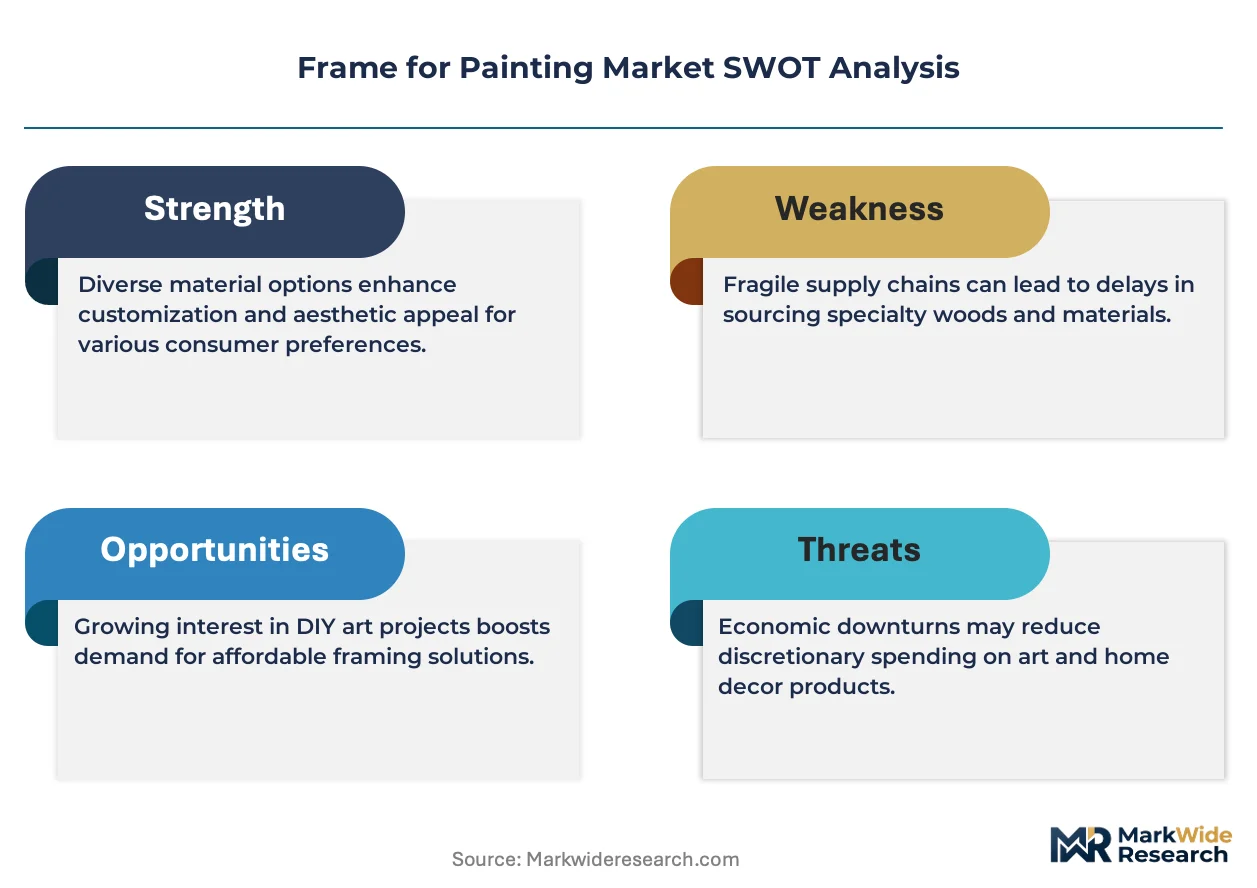
Residential interior design programs in California and New York Metro anchor volume procurement for gallery-ready framing systems, compressing margins through consolidated bulk purchasing while fragmenting pricing power across specialized archival-grade suppliers. This buyer concentration forces manufacturers to unbundle finishing services from structural components, creating transparent tiered pricing that separates stretcher bar assemblies from surface treatment workflows.
Pricing Analysis
Warranty coverage for dimensional stability and archival certification drives the dominant pricing structure, with premium tiers bundling lifetime warp guarantees and conservation-grade documentation while economy lines strip these protections to hit retail price points. Price differentiation rests on REACH compliance status and kiln-dried hardwood grade, with ECHA-certified water-based finishes commanding substantial premiums over solvent-based alternatives. Cost compression in the economy tier intensifies as MDF core options face EPA formaldehyde restrictions, forcing reformulation investments that squeeze already thin margins. Contract interior buyers exhibit lowest price sensitivity due to specification-driven procurement, while mass-market retailers drive hardest bargain on standardized medium-format frames.
Supply Chain Analysis
Skilled mortise-and-tenon joiners are thinning across Jiangsu and Zhejiang manufacturing zones, constraining output expansion for premium corner assemblies even as automated V-nail production scales. Raw material flows draw from Chinese paulownia plantations, Canadian pine forests, and German beech reserves, with kiln-dried stock commanding priority allocation from integrated clusters. Single-source vulnerability concentrates in Zhejiang's paulownia processing corridor, where weather disruptions or MIIT enforcement actions could interrupt dimensional stability supply for archival-grade production. Distribution runs through direct procurement contracts between North American retailers and Chinese manufacturers, bypassing traditional import distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The frame for painting market sits in active material transition, with moisture-resistant composite substrates displacing traditional hardwood in conservation applications and water-based finishes supplanting solvent systems under ECHA pressure.
For Market Incumbents: Extend water-based finish technology licensing across EU distribution networks before REACH substance restrictions harden, locking in compliant supplier status. Backward integration into paulownia kiln-drying operations in Jiangsu secures dimensional stability supply against raw material concentration risk. Defensive positioning requires rapid certification of archival-grade composite stretcher bars before conservation framers complete supplier consolidation around polymer compounders. For New Entrants and Emerging Players: Launch via direct e-commerce channels targeting North American residential interior design programs with customizable contemporary frame specifications, bypassing established retail distribution. White-space concentration sits in climate-vulnerable museum installations seeking moisture-resistant archival alternatives, where incumbent wood-centric suppliers carry legacy product inertia. The most penetrable entry point combines made-to-order contemporary geometries with REACH-compliant water-based finishing workflows. For Investors and Strategic Acquirers: The window for entry favors specialized conservation-framing suppliers with composite substrate capabilities and established atelier relationships in Germany or France. Long-term viability hinges on positioning upstream of regulatory compliance curves rather than downstream of commodity wood processing. The signal to watch is acceleration of direct procurement contracts between North American retailers and Chinese integrated manufacturers, which would compress margin pools for intermediary distributors.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Finish Technology Licensing | ECHA REACH compliance secures durable EU market access for coating suppliers. |
| Direct Procurement Channel Establishment | North American retailers bypass distributors to contract Zhejiang manufacturers directly. |
| Composite Stretcher Bar Certification | Museum preservation departments accelerate adoption of moisture-resistant archival substrates. |
| Paulownia Upstream Integration | Kiln-drying capacity in Jiangsu clusters locks in dimensional stability supply security. |
| Contemporary Frame Customization Platform | Architects specify precise dimensions for hospitality and corporate installation projects. |
Research Methodology
Document review covered customs and trade flow databases, MIIT industrial standards filings, and ECHA substance restriction schedules, complemented by interviews with frame manufacturers, conservation framers, and residential interior design program procurement leads. Primary fieldwork engaged plant managers at Jiangsu and Zhejiang wood-processing clusters, distribution channel partners in Hamburg and Dallas-Fort Worth, and technical R&D directors at European finish suppliers. Secondary validation drew from SEC 10-K disclosures of listed art supply companies, EPA formaldehyde emission regulatory filings, and CE marking documentation. Bottom-up demand modeling triangulated against top-down market sizing across material, frame type, and regional segments.
Segment-level outputs across material categories, frame geometries, and end-use applications were generated through structured demand decomposition. The analytical framework modeled price-volume relationships by buyer archetype, with CAGRs derived from trend extrapolation of regulatory compliance timelines and material substitution patterns. Key forecast inputs included REACH substance restriction phase-in schedules, EPA formaldehyde cap enforcement intensity, and composite substrate adoption curves among professional preservation departments.
Tariff escalation on Chinese wood products, sudden ECHA substance ban expansions, and accelerated composite technology breakthroughs are the dominant revision risks to modeled demand trajectories. Forecasts embed assumptions about regulatory enforcement continuity and material substitution elasticities that could shift under policy or technological disruption. A compact set of compliance and innovation triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Online Home Decor Market
Homecare and Decor
Plantation Shutters Market
Homecare and Decor
Terracotta Pots Market
Homecare and Decor
Middle East Revolving Doors Market
Homecare and Decor
Garden Sheds Market
Homecare and Decor
Global Homeware Market
Homecare and Decor
Wall Covering and Wall Decor Market
Homecare and Decor
India Sustainable Home Decor Market
Homecare and Decor
Asia-Pacific Decor Paper Market
Homecare and Decor
North America Sustainable Home Decor Market
Homecare and Decor
Corner Pads Market
Homecare and Decor
ASEAN UPVC Doors and Windows Market
Homecare and Decor
Digital Printed Wallpaper Market
Homecare and Decor
Hearth Market
Homecare and Decor
Europe Wall Coverings Market
Homecare and Decor
Removable Wallpaper Market