
 Global Decorative Laminates Market | 2026-2036
Global Decorative Laminates Market Size, Share, and Industry Trends Forecast 2026-2036
Global Decorative Laminates Market Foresight
Skilled resin chemist availability is redrawing competitive boundaries across the decorative laminates supply base. Wilsonart LLC leverages captive kraft paper pulping to sustain margin control across North American operations. Greenlam Industries Limited anchors its position through integrated melamine impregnation lines serving India's furniture export corridor. FunderMax GmbH differentiates via compact laminate specialization for exterior facade systems.
Decorative laminates are multi-layer composite sheets manufactured by impregnating decorative paper and core layers with thermosetting resins under controlled heat and pressure, typically achieving thicknesses from 0.5 mm to 25 mm depending on pressure class and intended structural load. These surfacing materials deliver abrasion resistance, moisture protection, and aesthetic consistency for interior and exterior architectural applications. High-pressure laminates dominate value capture due to superior durability specifications in commercial environments, while melamine-faced panels gain volume traction in mass residential furniture production where cost efficiency outweighs extended service life requirements. Flooring applications show structural momentum as rigid core hybrid formats displace traditional vinyl in renovation cycles.
EPA formaldehyde emission standards under TSCA Title VI constrain resin formulation choices for US-bound production, while ECHA REACH restrictions on phenol derivatives reshape European supply chemistry. China's GB standards for interior decoration materials enforce volatile organic compound thresholds that filter import access. India's BIS certification mandate for laminates creates compliance friction for unqualified regional suppliers. Stakeholders must monitor regulatory divergence between emission testing protocols as a determinant of cross-border manufacturing footprint decisions.
Market Dynamics
Resin chemistry constraints from tightening formaldehyde emission protocols are forcing capacity reallocation across the decorative laminates supply base. Manufacturers must reformulate thermosetting systems while maintaining surface performance specifications.
Growth Catalysts
- Commercial furniture retrofit cycles:Office renovation demand in India and Southeast Asia sustains volume throughput for high-pressure laminate grades.
- REACH-compliant resin systems:ECHA restrictions on phenol derivatives accelerate low-emission melamine-formaldehyde adoption across European specification channels.
- Exterior facade cladding:Compact laminate weathering performance specifications expand addressable square footage in institutional building envelopes.
Market Restraints
- Kraft paper pulp concentration:North American pulp supply tightness elevates core layer input costs for non-integrated producers.
- GB standard compliance barriers:China's volatile organic compound thresholds for interior decoration materials filter import access for uncertified suppliers.
- Digital printing surface threat:Large-format ceramic and sintered stone slabs capture premium kitchen countertop specification share.
Strategic Opportunities
- Rigid core hybrid flooring:SPC and WPC substrate compatibility opens renovation-driven specification for thin decorative laminate overlays.
- BIS certification arbitrage:India's mandatory quality standards create compliance moats for qualified domestic manufacturers against unverified imports.
- Antimicrobial surface integration:Silver-ion and copper-additive chemistry convergence addresses healthcare and foodservice hygiene specifications.
Industry Challenges
- Melamine resin formulation expertise:Skilled chemist scarcity constrains product development velocity for mid-tier producers.
- Multi-jurisdiction certification timelines:Divergent EPA TSCA Title VI, ECHA REACH, and BIS testing protocols extend product launch cycles.
- Legacy press line retrofit costs:Short-cycle lamination equipment upgrades for low-emission curing demand capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Decorative Laminates Market |
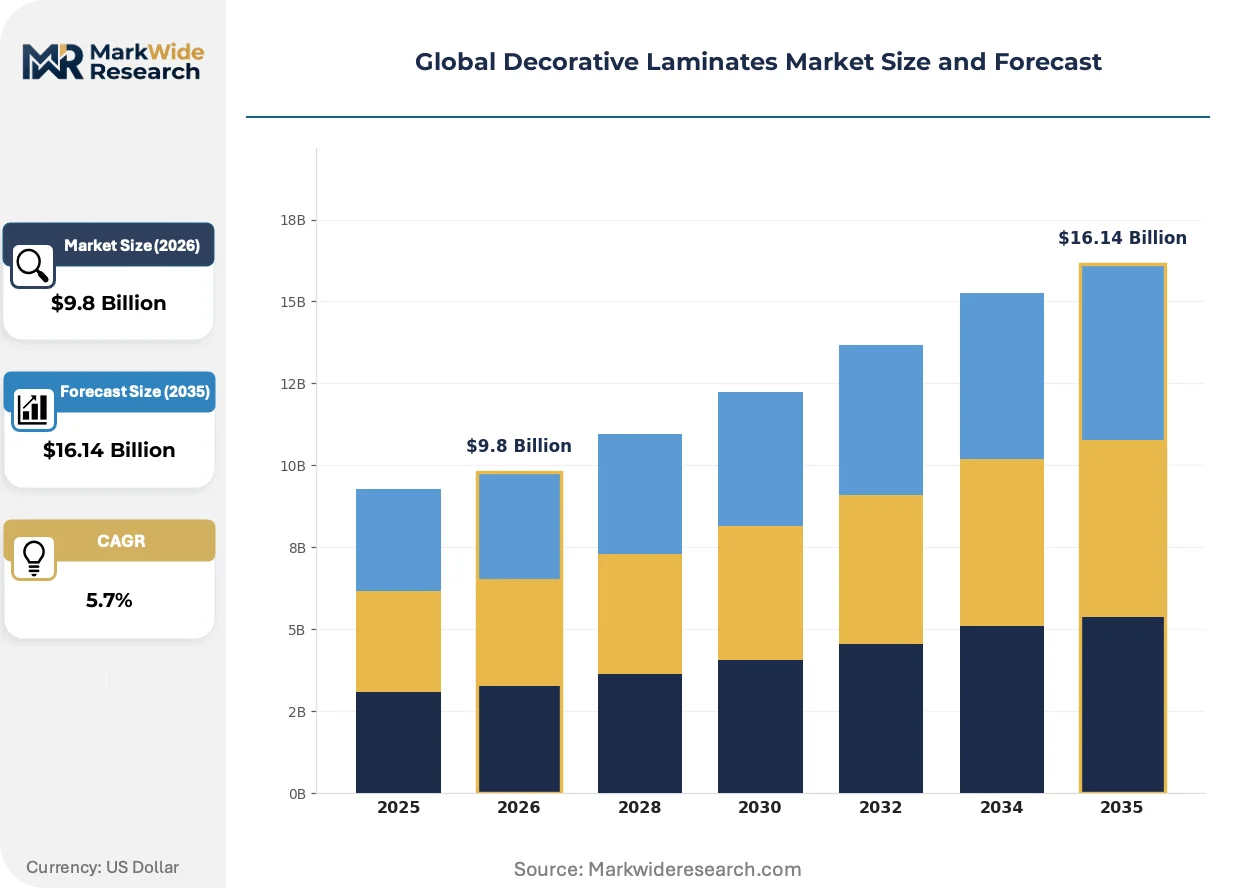
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $16.14 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Pressure Laminates, Low-Pressure Laminates, Medium-Pressure Laminates, Melamine-faced Panels Application: Furniture Finishing, Wall Cladding, Flooring, Ceiling Panels End User: Interior Designers, Builders, Commercial Establishments, Educational Institutions Distribution Channel: Direct Sales, Distributors, Online Retailers, Specialty Stores |
| Companies Covered | Wilsonart LLC, Greenlam Industries Limited, Merino Laminates Ltd, Stylam Industries Limited, Abet Laminati SpA, FunderMax GmbH, Panolam Industries International, Inc., Fletcher Building Limited, Archidply Industries Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Decorative Laminates Market Shifts & Advancements
Surface engineering advances and regulatory chemistry mandates are compressing traditional manufacturing assumptions. Three developments are restructuring competitive capability requirements.
Digital inkjet decoration is decomposing the conventional gravure-printed paper supply chain. Flooring and furniture manufacturers adopt print-on-demand surface patterning to compress SKU proliferation costs. This technology is decomposing minimum order quantity economics for regional laminate converters.
ECHA REACH restrictions on formaldehyde-releasing substances are tightening impregnation resin specifications. European laminate producers reformulate melamine-urea systems to maintain emission compliance without sacrificing press cycle efficiency. Commercial interior specification channels in Germany and France now demand third-party emission certification as a baseline qualification.
Buyer consolidation among pan-European furniture retail chains concentrates procurement leverage. National distributors lose volume share to direct mill relationships as scale buyers negotiate specification-grade supply contracts. This concentration is most visible in kitchen cabinet and built-in wardrobe verticals serving the German and Benelux markets.
Global Decorative Laminates Market Segmentation
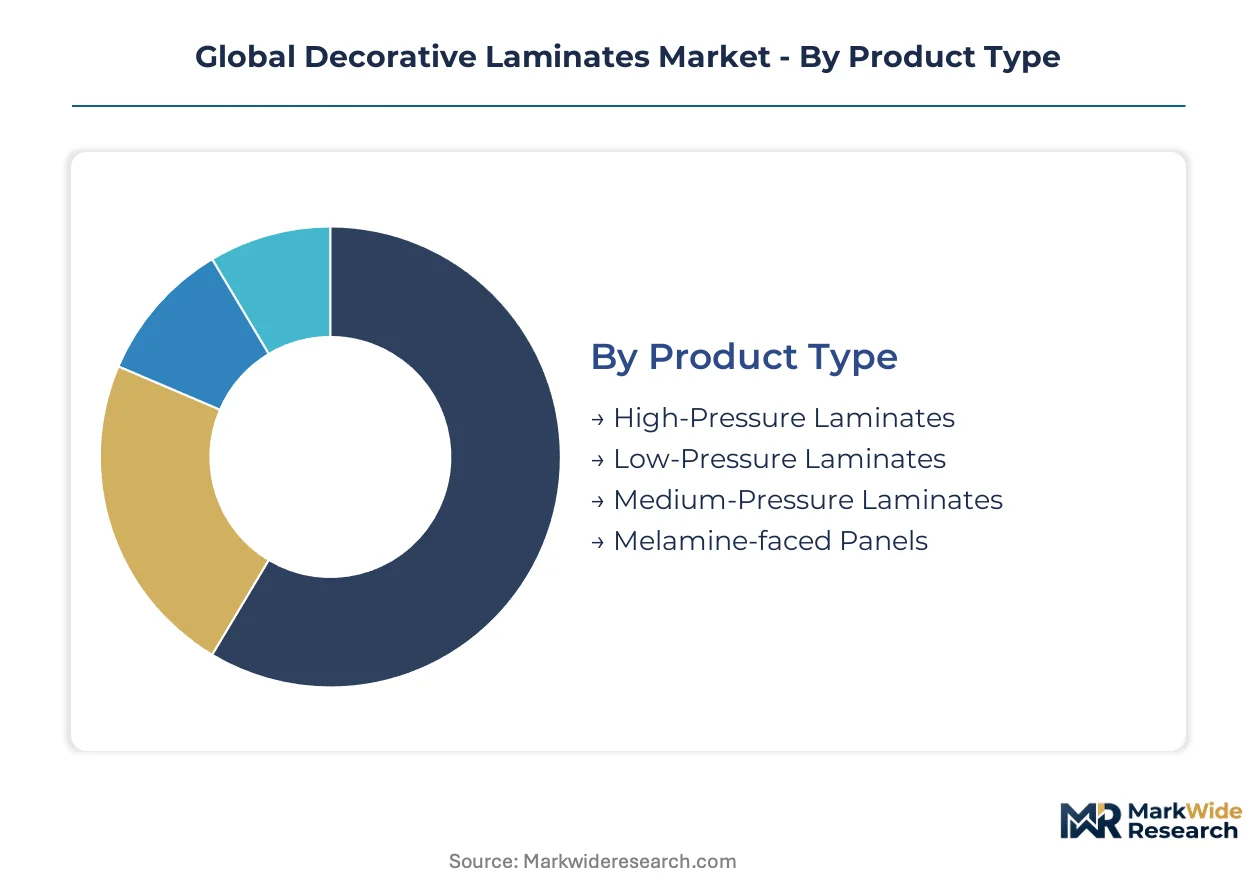
Product architecture and specification tiers determine margin capture and geographic reach for laminate manufacturers. Segment boundaries shift as resin chemistry constraints and end-use certification requirements redefine competitive positioning across specification channels.
Product Type:
High-pressure laminates dominate export-oriented production from Germany and India, while melamine-faced panels concentrate in domestic-serving Chinese mills optimized for mass furniture output.
- High-Pressure Laminates:Multi-layer sheets manufactured under pressures exceeding 5 MPa deliver superior abrasion resistance and dimensional stability for commercial furniture and healthcare environments. German and Indian producers command premium specification channels serving Benelux and Middle East project markets, though EPA TSCA Title VI compliance costs constrain US-bound volume expansion.
- Low-Pressure Laminates:Short-cycle press production at 1-2 MPa enables cost-efficient surfacing for residential cabinetry and retail fixtures. Chinese manufacturing clusters supply domestic renovation demand and Southeast Asian export markets where GB standard certification filters import access.
- Medium-Pressure Laminates:Intermediate density grades serve regional European distributors seeking performance differentiation without high-pressure laminate pricing.
- Melamine-faced Panels:Pre-laminated particleboard substrates from integrated European producers streamline kitchen cabinet assembly for pan-European retail chains.
High-Pressure Laminates commands the established base. The steepest expansion runs through Melamine-faced Panels.
Application:
Specification intensity varies sharply across end-uses, with facade and flooring applications demanding certified supply chains while furniture finishing tolerates broader sourcing.
- Furniture Finishing:Worktops, cabinet doors, and wardrobe surfaces consume the majority of decorative laminate volume globally. Indian furniture export corridors drive specification-grade demand, with Greenlam and Merino laminates serving Dubai and Riyadh project markets.
- Wall Cladding:Compact laminate exterior facade systems from Austrian and German producers penetrate institutional building envelopes in Switzerland and Scandinavia, where weathering performance specifications justify premium positioning.
- Flooring:Rigid core hybrid compatibility opens renovation-driven specification for thin decorative laminate overlays in US and Canadian residential replacement cycles.
- Ceiling Panels:Acoustic-rated laminates serve healthcare and education verticals in France and Germany where ECHA REACH emission compliance is mandatory.
Furniture Finishing absorbs the dominant share. Flooring is climbing the fastest as rigid core displacement accelerates.
End User:
Procurement sophistication separates specification-grade channels from commodity volume, with certified supply relationships concentrating among design-led and institutional buyers.
- Commercial Establishments:Hotels, restaurants, and corporate offices specify high-pressure laminates through direct mill relationships, bypassing traditional distribution. German kitchen retail chains and Dubai hospitality developers concentrate procurement leverage.
- Builders:Residential construction and renovation contractors in India and Vietnam source through distributor networks where BIS certification creates compliance moats against unverified imports.
- Interior Designers:Specification consultants in Milan and Paris influence surface selection for premium residential projects, prioritizing emission-certified European supply.
- Educational Institutions:Durability-focused procurement in US K-12 and university systems favors high-pressure laminate lockers and laboratory surfaces.
Commercial Establishments anchor value capture. Builders are gaining share fastest as residential construction accelerates in South and Southeast Asia.
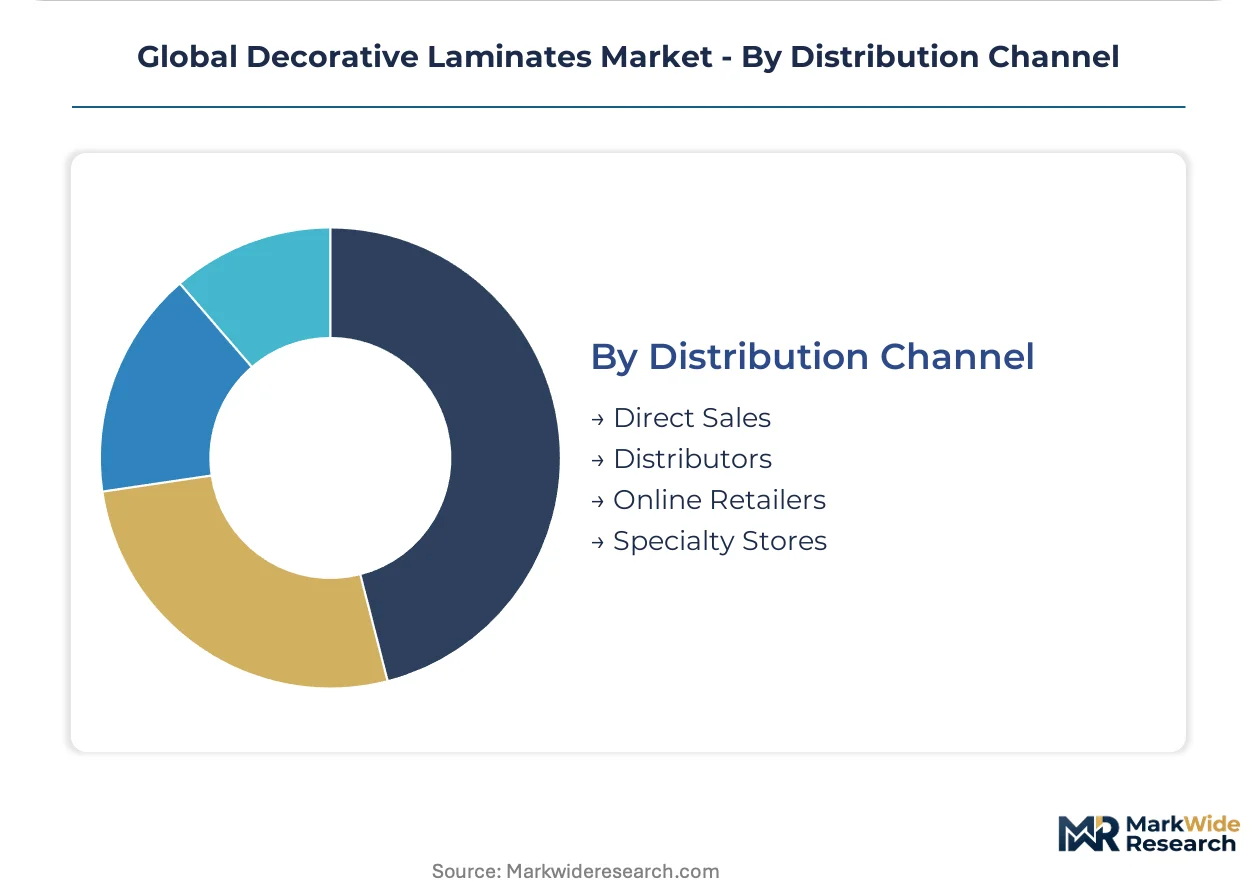
Distribution Channel:
Channel structure reflects buyer scale and specification complexity, with direct relationships displacing intermediaries among volume purchasers.
- Distributors:Regional stockists in India, Germany, and Brazil maintain inventory breadth for mid-tier furniture manufacturers and renovation contractors.
- Direct Sales:Pan-European furniture retail chains and large-scale hospitality developers negotiate specification-grade contracts directly with Wilsonart, FunderMax, and Greenlam production facilities.
- Specialty Stores:Surface material showrooms in Milan, Paris, and Mumbai serve architect and designer specification sampling.
- Online Retailers:E-commerce penetration remains limited to standard-grade residential renovation products in North American and European markets.
Distributors retain the volume base. Direct Sales is expanding most quickly as buyer consolidation concentrates procurement leverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German specification-grade laminates command pricing premiums exceeding Indian domestic grades by substantial margins, while Chinese mass-production output undercuts both on volume throughput. This asymmetry shapes manufacturing footprint decisions across the decorative laminates supply base.
United States
Commercial furniture retrofit cycles and residential renovation demand sustain volume throughput for high-pressure laminate grades. EPA TSCA Title VI formaldehyde emission standards constrain resin formulation choices for domestic production. Manufacturing clusters in Texas and North Carolina host integrated producers serving hospitality and healthcare specification channels.
Germany
Pan-European kitchen retail chains and institutional facade projects drive specification-grade demand for compact laminate systems. ECHA REACH restrictions on phenol derivatives reshape impregnation resin chemistry across European production. Industrial concentration in North Rhine-Westphalia anchors export-oriented capacity serving Benelux and Swiss project markets.
China
Mass residential furniture production and domestic renovation cycles absorb melamine-faced panel volume from short-cycle press operations. GB standards for interior decoration materials enforce volatile organic compound thresholds that filter import access. Manufacturing gravity in Guangdong and Zhejiang provinces supplies Southeast Asian export corridors.
India
Furniture export corridors to Dubai and Riyadh project markets sustain specification-grade laminate demand from domestic producers. BIS certification mandate for laminates creates compliance friction for unverified imports. Industrial clusters in Gujarat and Maharashtra host integrated melamine impregnation lines serving regional distribution networks.
United Arab Emirates
Hospitality development and commercial interior fit-out projects specify high-pressure laminates through direct mill relationships. MOHAP building material standards influence surface material procurement for healthcare environments. Dubai's specification consultant community channels European and Indian supply into premium residential and commercial projects.
Global Decorative Laminates Market Competitive Landscape
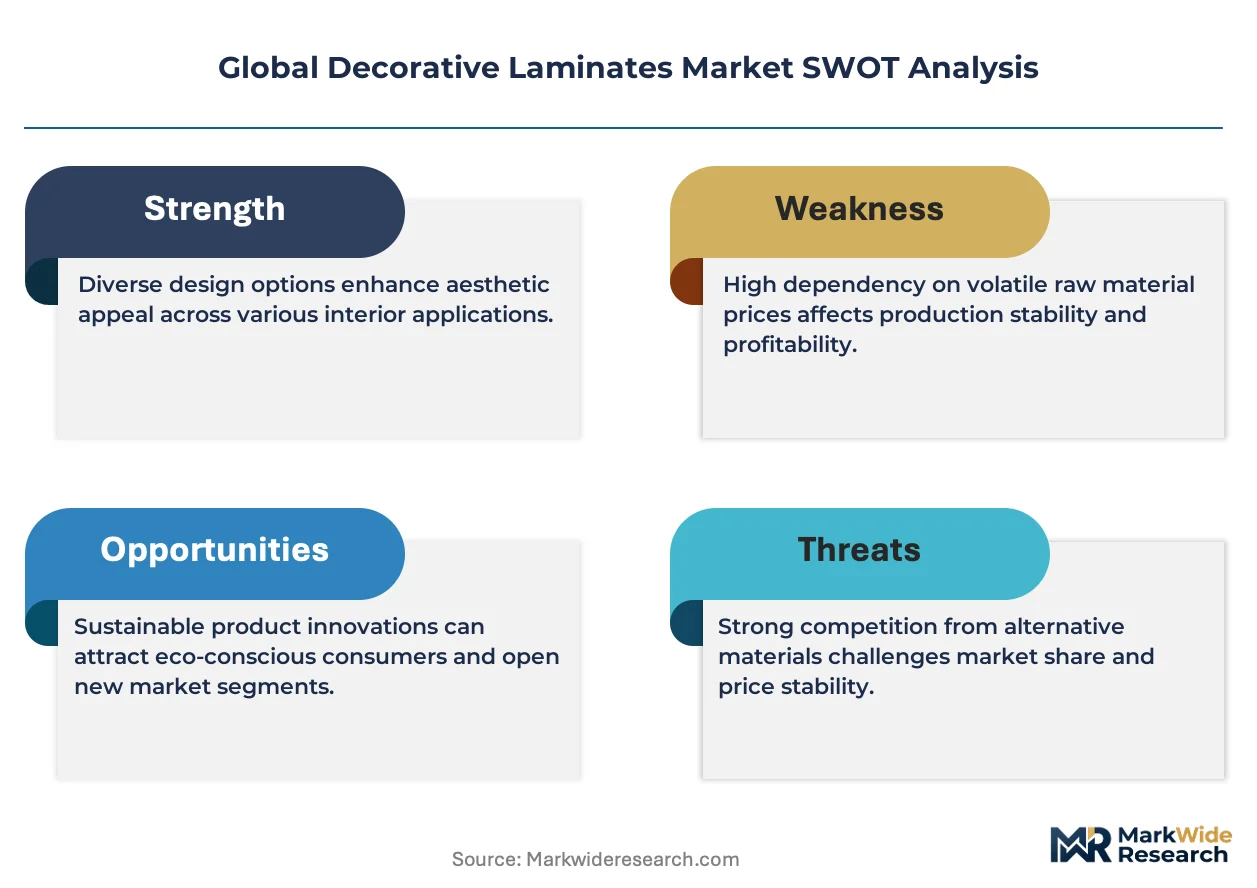
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure across the decorative laminates market. German and Austrian specialists command premium positioning through compact laminate weathering performance, while Indian and Chinese integrated producers capture volume share via short-cycle cost efficiency. The market structure separates into three strategic archetypes: specification-grade system suppliers, mass-market panel integrators, and regional conversion specialists. Dominant competitive moves include backward integration into kraft paper pulping and direct mill relationships with pan-European furniture retail chains.
Within the specification-grade tier, Wilsonart LLC and FunderMax GmbH represent technology-led positioning, while Greenlam Industries Limited exemplifies integrated cost leadership serving export corridors. These three companies anchor distinct competitive vectors: Wilsonart's captive pulp integration, FunderMax's facade specialization, and Greenlam's melamine impregnation scale. Each occupies a position reflecting regional manufacturing advantages and specification channel access rather than overlapping market pursuit.
| Leading Market Players |
|---|
| Wilsonart LLC |
| Greenlam Industries Limited |
| Merino Laminates Ltd |
| Stylam Industries Limited |
| Abet Laminati SpA |
| FunderMax GmbH |
| Panolam Industries International, Inc. |
| Fletcher Building Limited |
| Archidply Industries Limited |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between pan-European kitchen retail chains and German laminate producers lock in both kraft paper supply access and price visibility across multi-year procurement cycles. These arrangements insulate specification-grade manufacturers from spot pulp volatility while binding buyers to volume commitments that sustain press line utilization.
Pricing Analysis
Configured-to-order pricing for compact laminate facade systems commands substantial premiums over standard-grade melamine-faced panel stock. Three-tier pricing structure across premium, standard, and economy levels separates emission-certified European supply from GB-compliant Chinese output and uncertified regional production. Pricing pressure stems from digital printing surface technologies capturing premium countertop specification share. Residential renovation contractors in India exhibit highest price sensitivity, while Dubai hospitality developers tolerate premium positioning for certified supply.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for decorative paper and resin chemical imports. Manufacturing gravity centers on Germany, India, and China, with each hub serving distinct specification tiers. Kraft paper pulp, melamine resin, and thermosetting chemicals constitute critical input dependencies. Single-source vulnerability runs through North American pulp supply concentration. Distribution runs through direct mill relationships for volume buyers and regional stockists for mid-tier furniture manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer consolidation among pan-European furniture retail chains is redrawing procurement leverage, compressing distributor margins and favoring producers with direct specification relationships.
For Market Incumbents: Fortify backward integration into captive kraft paper pulping to defend margin position against North American pulp supply tightness. Invest in EPA TSCA Title VI and ECHA REACH dual-certification capacity to capture cross-border specification opportunities as regulatory divergence intensifies. Prioritize press line retrofit deployment for low-emission curing chemistry before compliance deadlines filter uncertified competitors. For New Entrants and Emerging Players: Lead with rigid core hybrid flooring compatibility as the most penetrable white-space segment in US and Canadian renovation cycles. Target India's BIS-certified supply gap through domestic melamine impregnation partnerships that circumvent import compliance friction. Establish direct relationships with specification consultants in Dubai and Riyadh project markets to bypass entrenched distributor networks. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated producers with captive resin formulation expertise and multi-jurisdiction certification assets. Acquisition targets should demonstrate sustained access to German or Indian specification-grade production capacity. Watch for BIS enforcement acceleration in India as the inflection signal indicating compliance-moat widening against unverified imports.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraft Paper Pulping | Wilsonart's captive pulp operations insulate margin control from North American supply tightness. |
| Dual-Jurisdiction Certification Investment | Simultaneous EPA TSCA Title VI and ECHA REACH compliance unlocks cross-border specification access. |
| Compact Laminate Capacity Expansion | FunderMax's facade specialization captures institutional building envelope growth in Switzerland and Scandinavia. |
| Direct Mill Relationship Development | Greenlam's bypass of Indian distributors to Dubai hospitality developers concentrates procurement leverage. |
| Antimicrobial Surface Chemistry Integration | Silver-ion additive systems address healthcare and foodservice hygiene specifications in German and French markets. |
Research Methodology
The analysis maps high-pressure laminates, low-pressure laminates, melamine-faced panels, and compact laminate systems, each validated through procurement managers at pan-European furniture retail chains, resin formulation chemists, specification consultants in Dubai and Mumbai, and distribution channel partners in Germany and India. Primary interview insights triangulate against customs trade data, SEC 10-K filings from listed building materials producers, BIS certification registries, and ECHA REACH substance restriction updates. Bottom-up volume modeling from press line capacity and utilization rates converges with top-down demand estimation from furniture production and construction completion data.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework segments by product architecture, application intensity, end-user procurement sophistication, and distribution channel structure. CAGRs derive from regression analysis of historical capacity expansion, regulatory compliance cost trajectories, and substitution elasticity between laminate grades and competing surface materials. Forecast inputs incorporate kraft paper pulp price indices and formaldehyde emission standard evolution timelines.
The analysis sits within stated boundaries; outcomes outside sustained REACH and GB standard enforcement trajectories would require recalibration. Forecasts reflect assumptions regarding resin chemistry reformulation feasibility, press line retrofit capital availability, and continued buyer consolidation among European kitchen retail chains. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Corner Pads Market
Homecare and Decor
Flush Door Market
Homecare and Decor
North America Sustainable Home Decor Market
Homecare and Decor
Wall Art Market
Homecare and Decor
Curtains and Window Blinds Market
Homecare and Decor
Louvre Windows Market
Homecare and Decor
Fireplace and Stove Market
Homecare and Decor
Mattress Pads Market
Homecare and Decor
Wall Covering Market
Homecare and Decor
Japan Sustainable Home Decor Market
Homecare and Decor
China Sustainable Home Decor Market
Homecare and Decor
Composite Doors and Windows Market
Homecare and Decor
Mattress Topper Market
Homecare and Decor
Fragrant Drawer Liners Market
Homecare and Decor
United States Home Decor Market
Homecare and Decor
Revolving Doors Market