
 US Wallcovering Market | 2026-2036
US Wallcovering Market Size, Share, and Industry Trends Forecast 2026-2036
US Wallcovering Market Analytics
Market Context
The capital-intensity gap between integrated manufacturers and boutique design houses is bifurcating competitive outcomes in the US wallcovering sector. York Wallcoverings Inc. leverages in-house printing and archival design libraries to dominate heritage residential channels. Brewster Home Fashions anchors mass-market distribution through big-box retail partnerships and rapid SKU turnover. F. Schumacher & Co. differentiates via designer-exclusive collections and showroom-based specification services for high-end commercial interiors.
Technical Definition and Segment Structure
Wallcovering encompasses decorative surfacing materials applied to interior vertical substrates, typically manufactured from paper pulp, vinyl resins, textile fibers, or non-woven synthetics in roll formats ranging from twenty-one to fifty-four inches width, serving both aesthetic enhancement and surface protection functions in built environments. Non-woven substrates command expanding share in residential renovation due to strippable installation and breathability advantages over traditional PVC, while peel-and-stick formats capture fastest growth among DIY consumers and multifamily property managers seeking reduced labor costs. The hospitality end-user segment concentrates margin pools in custom digital-print and antimicrobial vinyl specifications for hotel chains.
Regulatory Framework
EPA regulations under the Toxic Substances Control Act govern phthalate content in vinyl wallcoverings, while California Air Resources Board standards enforce stringent VOC emission thresholds that shape product formulation decisions for national distribution. OSHA workplace safety requirements influence installer exposure protocols for solvent-based adhesives in commercial projects. Stakeholders must monitor evolving state-level extended producer responsibility proposals and federal procurement preferences for bio-based content that could redirect R&D investment toward cellulose and plant-derived polymer alternatives.
Market Dynamics
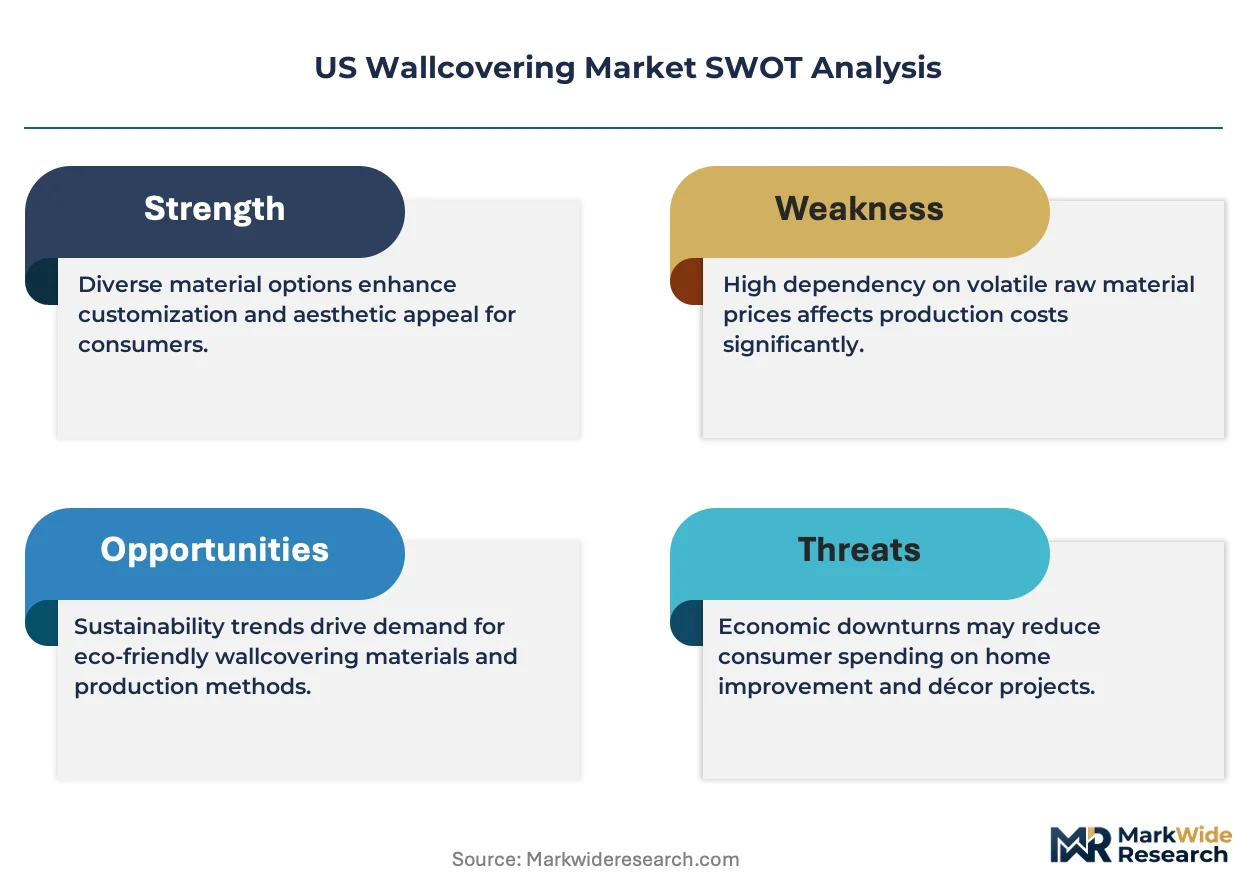
California's Title 24 energy standards and EPA VOC emission limits are compressing formulation options for vinyl wallcovering suppliers while simultaneously accelerating non-woven substrate adoption across residential renovation channels.
Growth Catalysts
- Texas and Florida Construction Concentration:Multifamily residential and hotel development in these states outpaces national averages, pulling specification volume toward digitally printed and textured finishes.
- EPA Phthalate Restrictions:Toxic Substances Control Act enforcement is forcing PVC reformulation toward bio-based plasticizers, opening premium positioning for compliant suppliers.
- Non-woven Breathability:Strippable installation properties and moisture management advantages are displacing traditional paper substrates in renovation-heavy Northeast and Midwest housing stock.
Market Restraints
- Petrochemical Input Volatility:Vinyl resin and plasticizer costs fluctuate with ethylene and propylene feedstock markets, compressing margin predictability for integrated manufacturers.
- California CARB Compliance Burden:Stringent VOC emission thresholds require separate product lines for state distribution, fragmenting production scale economies.
- Paint Substitution Pressure:Zero-VOC paint formulations and application robotics are capturing surface-finishing budgets in commercial new construction.
Strategic Opportunities
- Peel-and-stick Channel Expansion:Big-box retail and e-commerce platforms are creating direct-to-consumer pathways for DIY renovators and multifamily property managers.
- Antimicrobial Hospitality Specifications:Hotel chains are mandating silver-ion or copper-infused vinyl for guest room and corridor applications.
- Federal Bio-based Procurement Preferences:USDA BioPreferred program requirements are redirecting R&D investment toward cellulose and plant-derived polymer substrates.
Industry Challenges
- Installer Skill Shortage:Commercial solvent-based adhesive application requires OSHA-compliant training protocols that few contractors maintain.
- Digital Print Color Matching:Custom hospitality specifications demand calibrated proofing workflows that strain boutique design house production systems.
- Extended Producer Responsibility Proposals:State-level take-back mandates threaten to impose reverse logistics costs on roll-format suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Wallcovering Market |
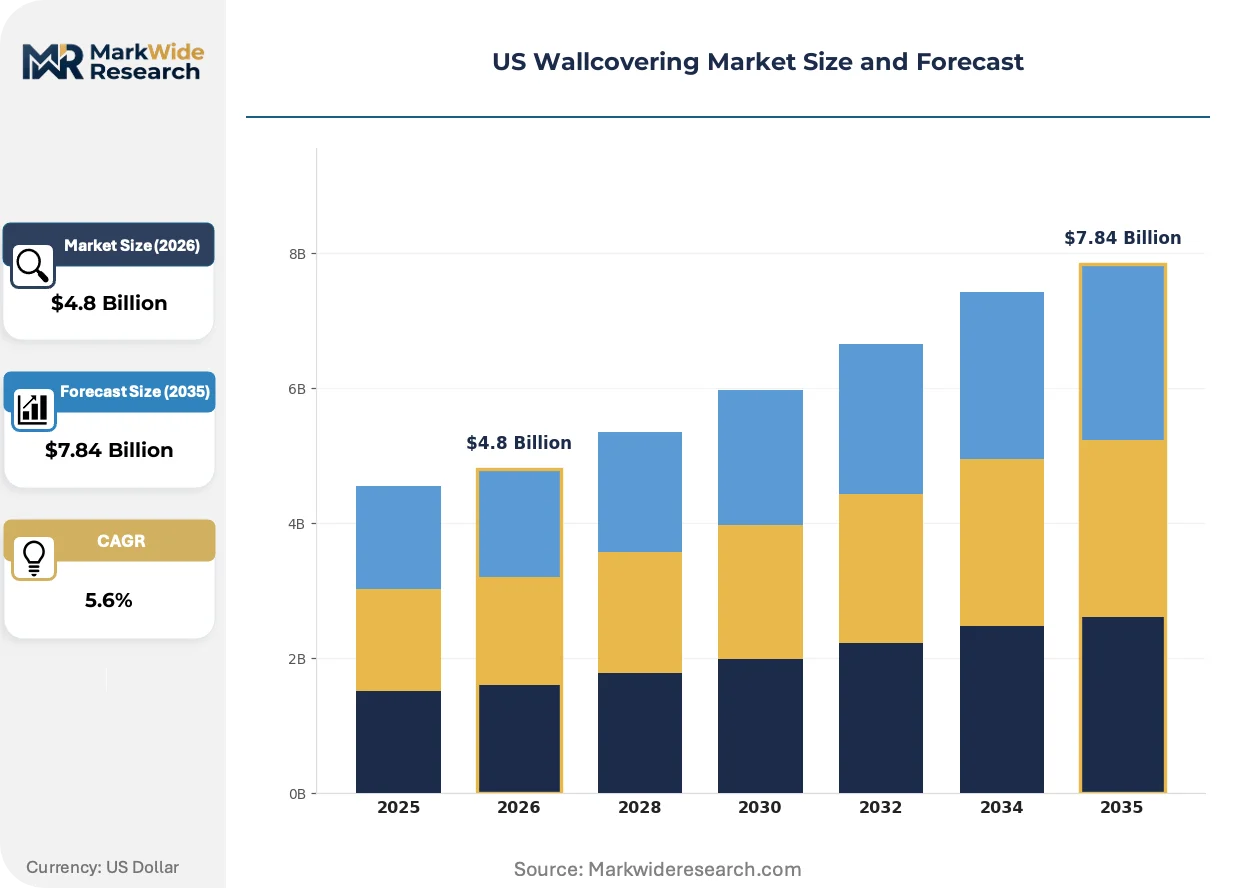
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PVC, Non-Woven, Vinyl Coated, Fabric End User: Residential, Commercial, Institutional, Hospitality Installation Method: Peel and Stick, Traditional Paste, Self-Adhesive, Pre-Pasted Design Style: Modern, Traditional, Rustic, Abstract |
| Companies Covered | York Wallcoverings Inc., Brewster Home Fashions, F. Schumacher & Co., Benjamin Moore & Co., Crossville Inc., Sherwin-Williams Company, Georgia-Pacific, Mohawk Industries Inc., Len-Tex Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Wallcovering Market Evolving Landscape
Digital printing infrastructure and bio-based material science are converging to reshape product architecture and specification workflows across residential and commercial channels.
Drop-on-demand inkjet systems capable of 600+ dpi resolution on non-woven substrates are displacing gravure and flexographic printing for short-run custom hospitality specifications. Hotel chains with accelerated renovation cycles now demand 500- to 2,000-yard production lots with 48-hour turnaround. This capability is compressing minimum order quantities and enabling just-in-time inventory models that reduce working capital for property owners.
California Air Resources Board (CARB) Phase 2 standards for formaldehyde and VOC emissions are forcing national distributors to maintain dual inventory streams. Manufacturers serving California must reformulate adhesives and topcoats, adding 8-12% to production costs. The compliance burden falls heaviest on mass-market vinyl suppliers, while boutique houses with existing low-VOC portfolios capture specification share in Los Angeles and San Francisco commercial interiors.
Property management companies and hospitality procurement teams are consolidating specification authority into centralized purchasing platforms. Marriott and Hilton have shifted wallcovering selection to national master agreements, displacing individual property-level discretion. This concentration rewards suppliers with digital asset libraries and rapid sample fulfillment capabilities. Texas and Florida development pipelines show the fastest adoption of centralized procurement, compressing local distributor margins.
US Wallcovering Market Segmentation
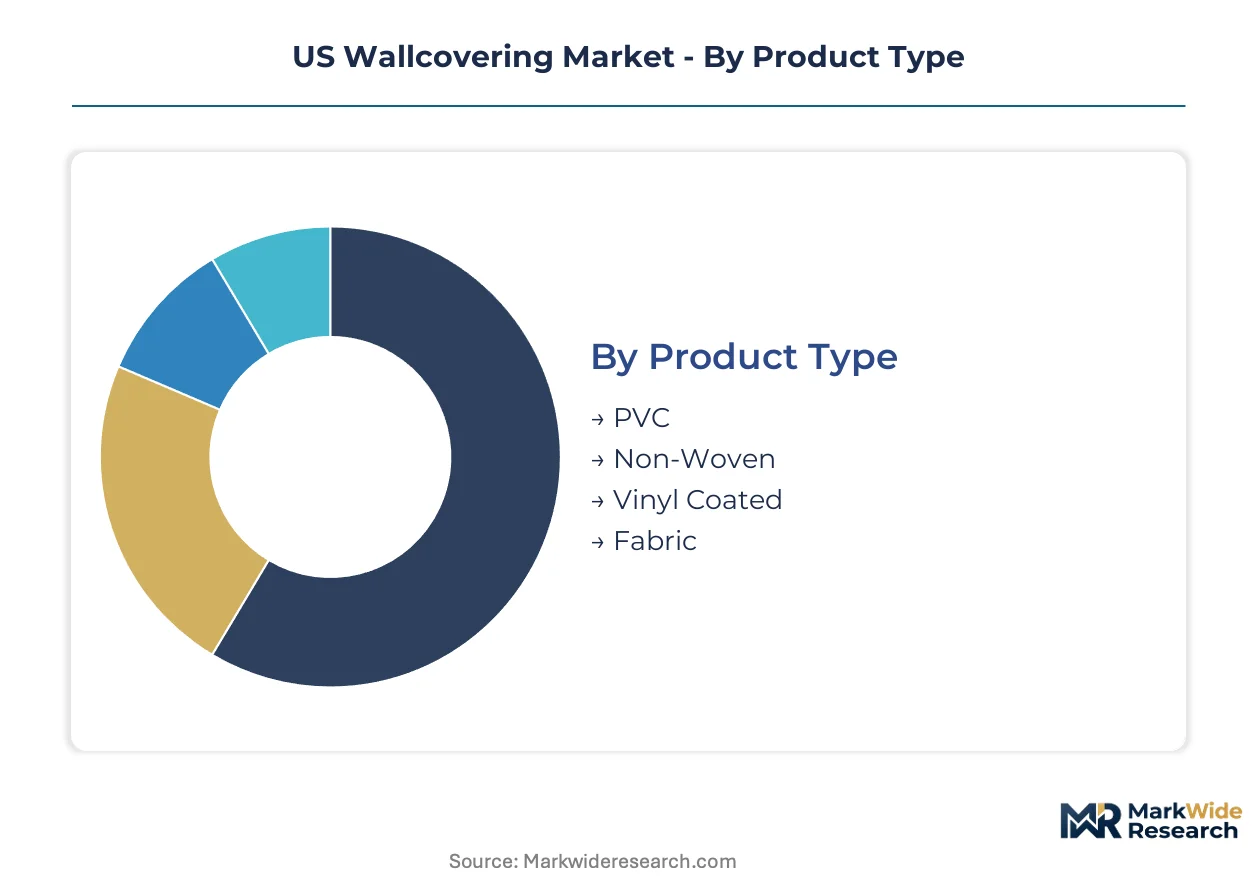
Wallcovering suppliers configure production lines around substrate chemistry and installation physics that determine distribution channel access. Specification authority concentrates differently across residential renovation, commercial new construction, and hospitality procurement, requiring distinct margin architectures.
Product Type:
PVC and non-woven substrates capture divergent margin pools, with compliance-driven reformulation shifting value toward breathable synthetics.
- Non-Woven:Manufactured from synthetic fibers bonded without woven structure, enabling strippable removal and moisture vapor transmission. Demand concentrates in Northeast and Midwest residential renovation where aging housing stock requires breathability to prevent mold. CARB Phase 2 compliance gives non-woven suppliers pricing power in California distribution.
- PVC:Polyvinyl chloride resin combined with plasticizers and topcoats for durability and washability. Hospitality chains in Texas and Florida specify antimicrobial PVC for high-traffic corridors, though EPA phthalate restrictions under TSCA are forcing bio-based plasticizer migration.
- Vinyl Coated:Paper or fabric substrates with protective vinyl layer balancing cost and performance. Budget commercial interiors in secondary markets favor this hybrid construction.
- Fabric:Natural or synthetic textile wallcoverings delivering acoustic dampening and tactile luxury. Boutique hotels and high-end residential specify fabric for feature walls.
PVC holds installed capacity across mass-market distribution. Non-woven is rotating up the share rankings in renovation-heavy geographies.
End User:
Procurement concentration varies sharply, with hospitality chains consolidating specification authority while residential demand fragments across DIY and contractor channels.
- Hospitality:Hotel chains with accelerated renovation cycles demand custom digital-print specifications with 48-hour sample turnaround. Marriott and Hilton national master agreements concentrate volume among suppliers with calibrated proofing workflows and rapid fulfillment infrastructure.
- Residential:Single-family renovation and new construction split between big-box retail DIY purchases and contractor-specified premium grades. Peel-and-stick formats capture multifamily property manager demand for reduced labor costs in Texas and Florida.
- Commercial:Office and retail interiors specify for durability and code compliance, with paint substitution pressure intensifying in new construction budgets.
- Institutional:Healthcare and education facilities prioritize antimicrobial properties and scrubbability, often under public procurement protocols favoring lowest compliant bid.
Hospitality commands specification premiums through centralized procurement. Residential is expanding most quickly via e-commerce and big-box retail channels.
Installation Method:
Labor cost sensitivity and installer skill availability determine method selection, with adhesive chemistry subject to OSHA workplace exposure protocols.
- Peel and Stick:Pressure-sensitive adhesive backing enables DIY application without professional installation. Multifamily property managers in high-turnover markets favor this format for unit refresh cycles.
- Traditional Paste:Solvent-based or water-based adhesive applied separately to substrate or wall surface. Commercial projects requiring dimensional stability and longevity specify this method despite OSHA training requirements for solvent exposure.
- Self-Adhesive:Factory-applied adhesive requiring moisture activation or peel release. Balances convenience with performance for light commercial applications.
- Pre-Pasted:Dry adhesive coating activated by water immersion. Residential renovation channels favor this method for moderate durability without professional labor.
Traditional paste retains specification in commercial durability segments. Peel and stick is climbing the fastest in residential and multifamily channels.
Design Style:
Digital printing infrastructure has collapsed minimum order quantities, enabling style fragmentation without inventory risk.
- Modern:Clean lines, geometric patterns, and solid colors dominating hospitality and commercial specifications. Digital print capability enables rapid trend response without cylinder engraving costs.
- Traditional:Damasks, florals, and heritage patterns anchored by York Wallcoverings archival libraries. Aging housing stock in Northeast and Midwest sustains renovation demand.
- Rustic:Textured surfaces mimicking natural materials like wood, stone, or plaster. Lodge and resort hospitality in mountain and coastal markets specify this aesthetic.
- Abstract:Non-representational patterns and color fields enabled by high-resolution inkjet. Boutique commercial interiors and designer residential specify for differentiation.
Traditional maintains legacy volume through heritage channels. Modern is gaining share fastest as hospitality procurement centralizes around contemporary brand standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across US sub-regions, with Sun Belt developers prioritizing cost-efficient peel-and-stick formats while Northeast heritage renovators absorb premiums for archival pattern libraries and breathable non-woven substrates.
Texas
Multifamily residential construction and hotel development in Dallas-Fort Worth and Houston generate concentrated demand for digitally printed vinyl and antimicrobial specifications. EPA phthalate restrictions under TSCA are forcing PVC reformulation toward bio-based plasticizers among suppliers serving Austin and San Antonio corridors. Dallas anchors the state's largest distribution hub for hospitality procurement teams managing centralized national agreements.
Florida
Accelerated hospitality renovation cycles in Miami and Orlando pull specification volume toward textured finishes and moisture-resistant substrates suited to humid coastal conditions. CARB Phase 2 compliance requirements create dual inventory complexity for distributors serving Tampa and Jacksonville markets. Miami-Dade County's building energy amendments are tightening vapor barrier specifications for multifamily developments.
California
Los Angeles and San Francisco commercial interiors command premium positioning for low-VOC non-woven suppliers with CARB-compliant portfolios. Title 24 energy standards are reshaping material selection for new construction across San Diego and Sacramento corridors. The state's extended producer responsibility proposals threaten reverse logistics costs on roll-format suppliers serving Bay Area renovation markets.
Northeast Corridor
Aging housing stock in Boston and Philadelphia sustains renovation demand for strippable non-woven substrates that prevent mold in century-old masonry structures. OSHA workplace safety requirements influence installer training protocols for solvent-based adhesive applications in New York commercial projects. Brooklyn and Queens multifamily property managers are adopting peel-and-stick formats for rapid unit turnover.
Pacific Northwest
Seattle and Portland residential markets prioritize breathable wallcovering systems compatible with moisture management in marine climate zones. USDA BioPreferred program awareness is redirecting specification toward cellulose-based substrates among municipal procurement officers. Vancouver, Washington, and Tacoma industrial clusters support regional distribution for cross-border Canadian hospitality developments.
US Wallcovering Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with capital-intensity gaps bifurcating competitive outcomes across heritage residential and mass-market retail channels. The upper tier commands in-house printing infrastructure and archival design libraries, while mid-scale players anchor big-box distribution through rapid SKU turnover. Two dominant competitive moves are reshaping positioning: consolidation of specification authority into centralized hospitality procurement platforms, and backward integration into digital print workflows to compress custom order turnaround.
Within the heritage-pattern archetype, York Wallcoverings Inc. occupies a position defined by archival depth and residential channel concentration. Brewster Home Fashions exemplifies the mass-market velocity model, anchoring big-box retail partnerships. F. Schumacher & Co. represents the designer-exclusive tier, with showroom-based specification services for high-end commercial interiors.
| Leading Market Players |
|---|
| York Wallcoverings Inc. |
| Brewster Home Fashions |
| F. Schumacher & Co. |
| Benjamin Moore & Co. |
| Crossville Inc. |
| Sherwin-Williams Company |
| Georgia-Pacific |
| Mohawk Industries Inc. |
| Len-Tex Corporation |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between hospitality procurement consortia and integrated wallcovering manufacturers lock in both vinyl resin supply access and price visibility across volatile petrochemical feedstock cycles. These contracts insulate Texas and Florida developers from spot-market ethylene cost swings while compressing margin flexibility for boutique design houses lacking captive resin sourcing.
Pricing Analysis
After-sales specification support and archival pattern licensing drive lifetime value for heritage residential suppliers. Three-tier pricing structure across premium designer collections, standard commercial grades, and economy vinyl-coated lines stratifies the market. Price differentiation rests on CARB Phase 2 certification status and digital print customization capability. Cost compression in mass-market PVC tiers is intensifying because EPA phthalate restrictions under TSCA mandate bio-based plasticizer migration. Multifamily property managers exhibit highest price sensitivity, while hospitality procurement teams absorb premiums for rapid-turnaround custom specifications.
Supply Chain Analysis
Inventory cycles stretching from vinyl resin production to finished roll distribution create 8-14 week lead times for custom hospitality specifications. Manufacturing concentrates in the United States, China, and Germany, with domestic producers anchoring heritage pattern libraries and Asian suppliers feeding mass-market vinyl volume. Raw material dependencies center on ethylene-derived PVC resin, titanium dioxide pigments, and paper pulp substrates. Single-source vulnerability in specialty plasticizer formulations poses structural risk as TSCA enforcement accelerates. Distribution runs through big-box retail partnerships, regional distributor networks, and direct-to-property-manager e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US wallcovering market functions as a service-attach opportunity where specification consulting and rapid sample fulfillment expand faster than substrate manufacturing. Recurring revenue from designer-exclusive licensing and hospitality procurement platform subscriptions outpaces hardware growth in consolidated channels.
For Market Incumbents: Consolidate specification authority by deepening backward integration into digital print workflows and capturing hospitality national master agreement renewals. Defend against paint substitution pressure in commercial new construction by embedding antimicrobial performance guarantees into vinyl product lines. Prioritize CARB-compliant adhesive formulation R&D to maintain California distribution access without dual inventory fragmentation. For New Entrants and Emerging Players: Lead with peel-and-stick format innovation targeting multifamily property managers in Texas and Florida high-turnover markets. The most penetrable white space sits in e-commerce direct-to-consumer channels underserved by legacy distributor networks. Pursue USDA BioPreferred certification as a go-to-market angle to capture federal procurement preference momentum. For Investors and Strategic Acquirers: Boutique design houses with calibrated digital proofing infrastructure and existing low-VOC portfolios represent the most attractive acquisition target archetype. Long-term viability hinges on consolidation of hospitality procurement platforms and backward integration into inkjet printhead technology. Watch EPA enforcement intensity on phthalate restrictions as the inflection indicator for PVC reformulation capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Print Infrastructure Investment | 600+ dpi inkjet capability compresses hospitality sample turnaround below 48 hours. |
| Bio-based Plasticizer Migration | TSCA-compliant PVC reformulation opens premium positioning in California distribution. |
| Peel-and-Stick Channel Expansion | Big-box retail partnerships capture DIY renovator and multifamily property manager demand. |
| Antimicrobial Specification Development | Silver-ion and copper-infused vinyl meets Hilton and Marriott corridor mandates. |
| Centralized Procurement Platform Integration | National master agreement access concentrates volume among rapid-fulfillment suppliers. |
Research Methodology
A spread of perspectives from hospitality procurement directors, multifamily property managers, commercial interior designers, and wallcovering distributor principals converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through EPA TSCA filing databases, CARB emission standard documentation, and SEC 10-K disclosures from integrated manufacturers. Bottom-up demand modeling across substrate types, installation methods, and end-user segments triangulated against top-down construction spending forecasts from Census Bureau and Dodge Construction Network data.
Segmentation dimensions modeled include substrate chemistry, installation physics, end-user procurement concentration, and regional regulatory compliance tiers across the projection horizon. CAGRs derive from trend extrapolation of digital print adoption curves, hospitality renovation cycle compression, and non-woven substrate displacement rates. Industry-specific forecast inputs incorporate Title 24 energy standard amendment trajectories and extended producer responsibility proposal status in California and New York.
Underlying assumptions cover petrochemical feedstock price stability, TSCA enforcement continuity, and hospitality development pipeline execution, with deviation risk concentrated in vinyl resin cost volatility and state-level take-back mandate adoption. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Wall Clock Market
Homecare and Decor
Digital Printed Wallpaper Market
Homecare and Decor
MDF Decorative Overlays Market
Homecare and Decor
China Sustainable Home Decor Market
Homecare and Decor
Window Blinds Market
Homecare and Decor
Online Home Decor Market
Homecare and Decor
Europe Wall Coverings Market
Homecare and Decor
Saudi Arabia Interior Design Market
Homecare and Decor
Global Homeware Market
Homecare and Decor
Asia-Pacific Decorative Laminates Market
Homecare and Decor
Japan Sustainable Home Decor Market
Homecare and Decor
New Zealand Window Covering Market
Homecare and Decor
North America Sustainable Home Decor Market
Homecare and Decor
Wall Covering and Wall Decor Market
Homecare and Decor
Asia-Pacific Interior Doors Market
Homecare and Decor
United Arab Emirates Interior Design Market