
 Wall Art Market | 2026-2036
Wall Art Market Size, Share, and Industry Trends Forecast 2026-2036
Wall Art Market Outlook
Print-on-demand licensing is reshaping margin distribution across the Wall Art Market, shifting value from inventory-heavy wholesale operations toward digital fulfillment networks. Wayfair leverages its logistics infrastructure to control last-mile delivery for oversized pieces. Society6 specializes in artist-platform economics, capturing recurring revenue from independent creator uploads. Minted anchors its position through crowdsourced design competitions that feed limited-edition collections.
Wall art encompasses decorative visual objects produced for interior enhancement, spanning painted surfaces, printed substrates, dimensional sculptures, and mixed-media assemblies typically mounted or displayed in residential, commercial, and institutional environments. Canvas and print segments dominate volume throughput due to scalable digital reproduction workflows, while sculpture commands premium positioning through material intensity and fabrication complexity. Online stores represent the fastest-expanding distribution channel, displacing legacy gallery intermediation through direct-to-consumer algorithms and virtual room-visualization tools.
The Consumer Product Safety Commission enforces substrate flammability standards for textile-mounted pieces, while California's Proposition 65 mandates chemical disclosure for metal alloys and colored pigments used in framed works. The Federal Trade Commission monitors environmental marketing claims around sustainably sourced wood and recycled metal content, pressuring suppliers toward verified chain-of-custody documentation. Stakeholders must track evolving state-level right-to-repair and extended producer responsibility frameworks that could impose take-back obligations on mass-produced decorative goods.
Market Dynamics
Print-on-demand infrastructure is compressing inventory cycles across wall art supply chains, forcing legacy wholesale distributors to restructure fulfillment networks or cede share to algorithm-driven direct-to-consumer platforms.
Growth Catalysts
- UV-curable ink systems:These formulations enable same-day turnaround on canvas and acrylic substrates, eliminating solvent-based drying bottlenecks that previously constrained order-to-delivery timelines.
- Hospitality interior specifications:Hotel renovation cycles and boutique property development in design corridors are absorbing large-format commissions that carry higher margin profiles than residential retail.
- California Proposition 65 enforcement:Chemical disclosure mandates for metal alloys and pigments are accelerating supplier consolidation toward certified material streams that command premium positioning.
Market Restraints
- Linen and cotton substrate volatility:Textile input costs fluctuate with agricultural yield cycles, compressing margin predictability for canvas-dominant producers.
- Chinese substrate manufacturing concentration:Over half of global canvas and engineered wood panel supply originates from three coastal provinces, creating geopolitical and logistics risk exposure.
- Dimensional shipping constraints:Oversized sculpture and framed works face freight classification penalties that erode price competitiveness against flat-pack alternatives.
Strategic Opportunities
- Healthcare facility art programming:Evidence-based design contracts for hospitals and wellness centers represent an underpenetrated vertical with multi-year installation cycles and maintenance revenue potential.
- Extended Producer Responsibility frameworks:Emerging state-level take-back mandates for decorative goods will favor producers with established reverse-logistics infrastructure.
- Augmented reality visualization:Spatial computing integration with e-commerce platforms is collapsing the sampling phase of commercial procurement, accelerating decision velocity for contract interior designers.
Industry Challenges
- Master printer skill scarcity:Color calibration expertise for wide-format digital systems remains concentrated among aging technicians, constraining quality consistency at scaled operations.
- FTC greenwashing enforcement:Environmental marketing claims around sustainably sourced wood require verified chain-of-custody documentation that many mid-tier suppliers lack.
- Platform algorithm dependency:Artist-marketplace economics tie creator income to opaque ranking systems, generating supply-side instability for print-on-demand aggregators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wall Art Market |
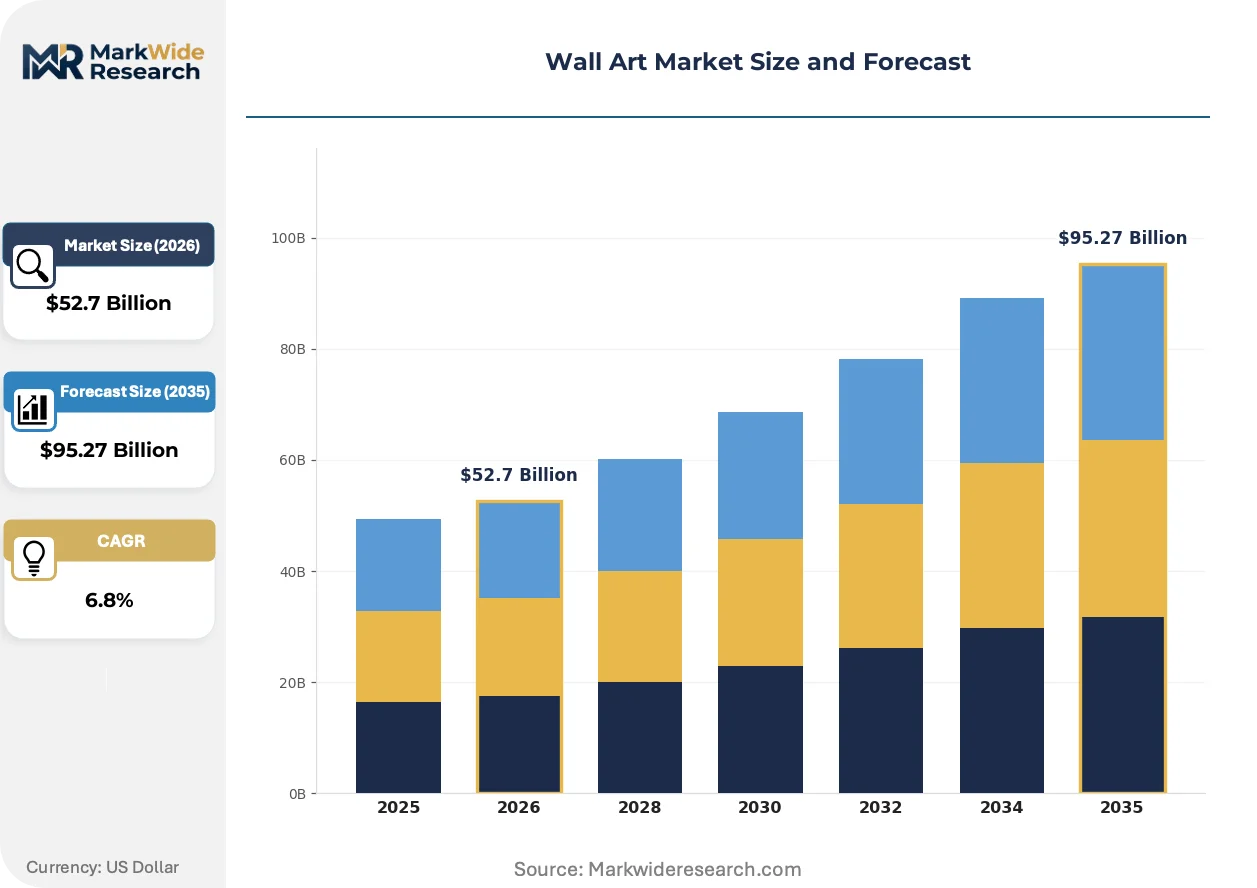
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Art Type: Painting, Print, Canvas, Sculpture Material: Wood, Metal, Textile, Glass Style: Abstract, Contemporary, Vintage, Minimalist Distribution Channel: Online Stores, Galleries, Home Decor Shops, Auctions |
| Companies Covered | IKEA, Wayfair, Society6, Etsy, Art.com, Saatchi Art, Minted, Redbubble, Fine Art America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wall Art Market Strategic Shifts
Digital reproduction workflows are fragmenting production geography while concentrating value capture in fulfillment software layers, a structural inversion that favors asset-light platform operators over capital-intensive manufacturing facilities.
AI-powered generative design tools are rendering obsolete the traditional artist-representation model for stock imagery and decorative patterns. Hospitality procurement teams now commission algorithmic variations tailored to property-specific palettes, compressing licensing costs and collapsing the role of intermediary agencies that previously curated commercial art catalogs.
REACH chemical restrictions in Europe are forcing reformulation of solvent-based coatings used in protective finishes for metal and wood substrates. Manufacturers serving EU markets must maintain dual inventory streams or absorb certification costs for compliant alternatives, with framed works and mixed-media assemblies bearing the steepest compliance burden.
Corporate art leasing programs are displacing direct purchase models for commercial interiors. Facility managers in United States metropolitan design corridors now favor subscription arrangements that include rotation services and condition maintenance, shifting capital expenditure to operating budgets and concentrating supplier relationships among integrated service providers with dedicated installation crews.
Wall Art Market Segmentation
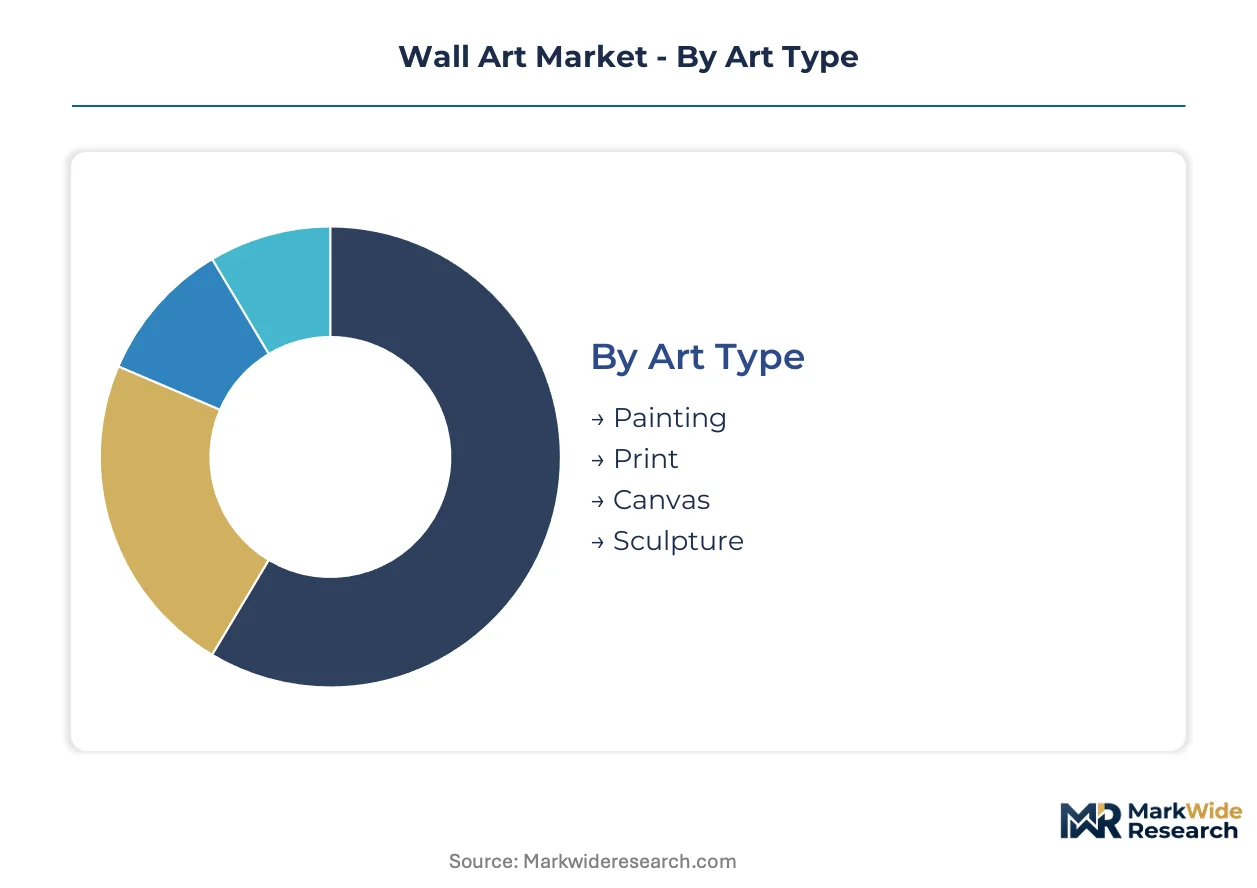
Wall art procurement patterns diverge sharply across aesthetic preference, substrate durability, and fulfillment velocity. Understanding these fault lines reveals where margin pools concentrate and which technology investments reshape competitive position.
Art Type:
Cost tier stratification separates mass-reproducible formats from fabrication-intensive originals, with production economics dictating channel placement and margin structure.
- Painting:Hand-applied pigment on prepared substrates commands premium positioning through provenance documentation and artist attribution. Demand concentrates in New York and Los Angeles residential renovations where interior designers specify statement pieces above entry thresholds.
- Print:Digital reproduction on archival paper or synthetic substrates enables scalable fulfillment through print-on-demand networks. Hospitality procurement teams in Miami design corridors favor large-format prints for cost-efficient property-wide theming.
- Canvas:Inkjet or giclée output on cotton or polyester wraps dominates volume throughput across direct-to-consumer platforms.
- Sculpture:Dimensional works in cast, carved, or assembled forms face freight classification penalties that limit e-commerce penetration.
Print holds installed capacity. Canvas is rotating up the share rankings.
Material:
Supply concentration for raw inputs determines cost volatility exposure and compliance burden across finished goods.
- Wood:Framed works and panel substrates rely on certified lumber streams to satisfy FTC chain-of-custody requirements for environmental marketing claims. California Proposition 65 enforcement accelerates supplier consolidation toward verified material documentation.
- Metal:Aluminum and steel armatures for sculpture and mixed-media assemblies carry chemical disclosure mandates that compress margin predictability for uncertified producers.
- Textile:Linen and cotton canvas wraps face agricultural yield cycle volatility.
- Glass:Protective glazing and decorative fused panels require specialized freight handling that constrains last-mile economics.
Wood maintains dominant procurement volume. Metal is climbing the fastest as hospitality specifications harden against flammability risk.
Style:
Aesthetic category alignment with property type and demographic cohort drives inventory risk for speculative production.
- Abstract:Non-representational forms dominate commercial interiors where procurement teams prioritize palette flexibility over narrative content.
- Contemporary:Current-period works with defined provenance attract institutional and corporate leasing programs.
- Vintage:Period-specific reproductions and authenticated originals serve residential renovation markets.
- Minimalist:Reduced-form compositions align with healthcare facility evidence-based design protocols for stress reduction.
Abstract commands the broadest addressable base. Minimalist is gaining share fastest through wellness-sector penetration.
Distribution Channel:
Fulfillment infrastructure and customer acquisition economics separate asset-light platforms from inventory-heavy intermediaries.
- Online Stores:Algorithm-driven discovery and virtual room visualization collapse sampling friction for residential buyers. Direct-to-consumer platforms capture value through proprietary fulfillment software rather than manufacturing assets.
- Galleries:Physical intermediation persists for high-value originals where provenance verification and condition inspection justify commission structures.
- Home Decor Shops:Big-box and specialty retail chains absorb volume for standardized sizes with immediate availability requirements.
- Auctions:Secondary market clearing for investment-grade works maintains price discovery mechanisms for authenticated pieces.
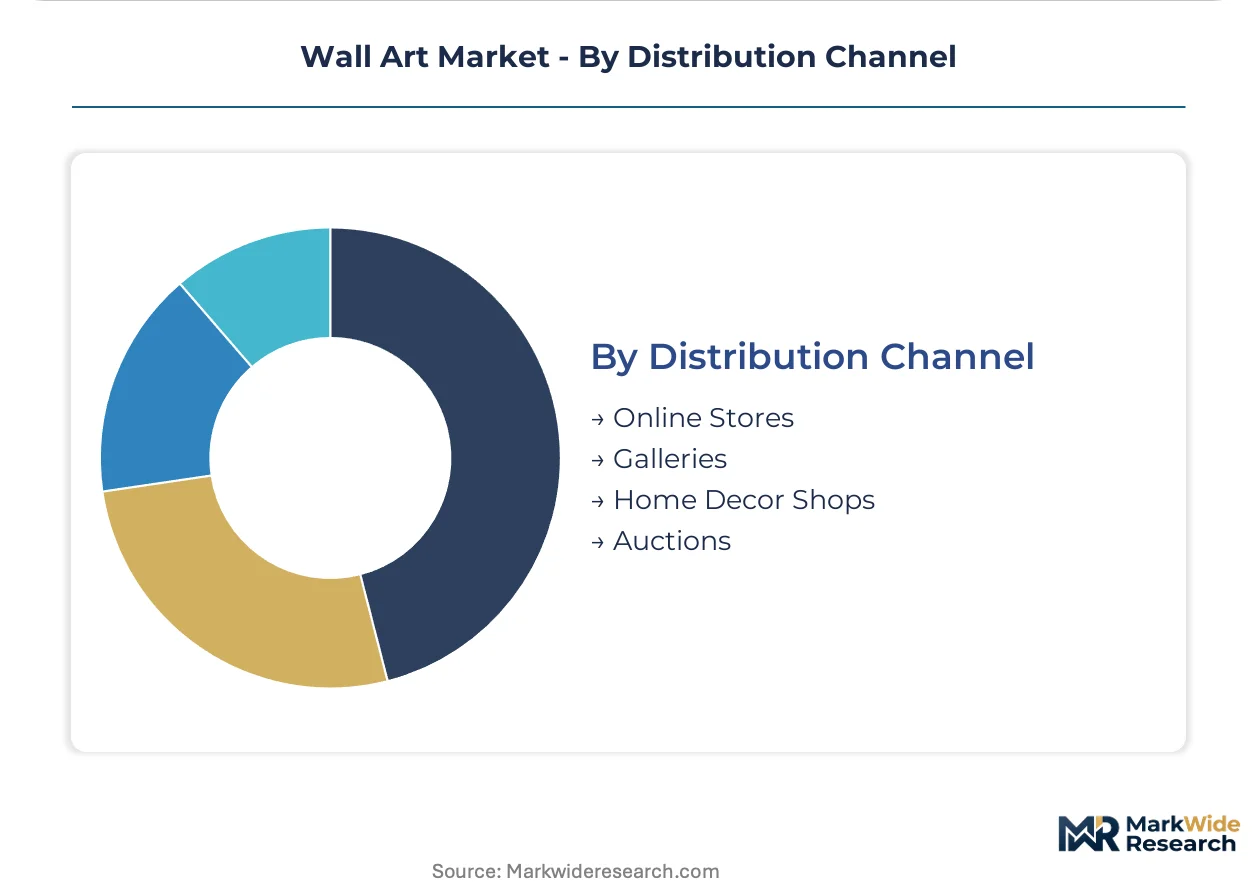
Online stores hold the steepest expansion trajectory. Galleries are defending position through authentication services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wall art demand elasticity varies sharply across geographies, with residential buyers in emerging markets exhibiting acute price sensitivity while hospitality procurement teams in mature design corridors absorb premium positioning for large-format commissions.
United States
Hospitality renovation cycles in Miami and New York design corridors drive large-format print demand, while residential e-commerce penetration concentrates in Los Angeles. The FTC enforces chain-of-custody documentation for environmental marketing claims on sustainably sourced wood. California's Proposition 65 mandates chemical disclosure for metal alloys and pigments used in framed works produced in Los Angeles County manufacturing clusters.
China
Digital printing infrastructure expansion in Guangdong and Zhejiang provinces supplies global canvas and engineered wood panel demand. The Ministry of Ecology and Environment (MEE) enforces dual carbon goals that pressure substrate manufacturers toward energy-efficient curing processes. Three coastal provinces—Jiangsu, Shandong, and Fujian—account for over half of global canvas supply, creating concentrated logistics risk exposure.
Germany
Corporate art leasing programs in Berlin and Munich displace direct purchase models for commercial interiors. ECHA REACH chemical restrictions force reformulation of solvent-based coatings used in protective finishes for metal and wood substrates. The North Rhine-Westphalia industrial corridor hosts specialized wide-format digital printing equipment manufacturers serving EU hospitality specifications.
United Kingdom
London's gallery intermediation persists for high-value originals where provenance verification justifies commission structures. The UK Competition and Markets Authority monitors platform algorithm transparency in artist-marketplace economics. The Southeast England logistics hub supports direct-to-consumer fulfillment networks targeting residential renovation demand across Greater London.
Japan
Healthcare facility evidence-based design protocols in Tokyo and Osaka drive minimalist composition demand for stress reduction applications. METI standards govern substrate flammability for textile-mounted pieces in institutional environments. The Kanto region's precision manufacturing base supplies color calibration expertise for wide-format digital systems serving premium hospitality contracts.
Wall Art Market Competitive Environment
Capability concentration sits with specialized print-on-demand platforms; scale advantage sits with logistics-integrated furniture retailers. The market structures around three tiers: algorithm-driven direct-to-consumer platforms, inventory-heavy wholesale distributors, and artist-centric marketplace aggregators. Dominant competitive moves include fulfillment network restructuring to compress inventory cycles and strategic partnerships with hospitality procurement consortia for multi-year installation contracts.
Within the platform-aggregator tier, Society6 and Redbubble exemplify asset-light models capturing recurring revenue from independent creator uploads, while Wayfair anchors the logistics-integrated segment through last-mile delivery control for oversized pieces. These three companies occupy positions that represent the structural inversion favoring fulfillment software over capital-intensive manufacturing assets.
| Leading Market Players |
|---|
| IKEA |
| Wayfair |
| Society6 |
| Etsy |
| Art.com |
| Saatchi Art |
| Minted |
| Redbubble |
| Fine Art America |
| Others |
Value Chain & Pricing Dynamics
Guangdong Province's digital printing infrastructure expansion feeds global canvas supply, concentrating cost-setting power among substrate manufacturers while downstream print-on-demand platforms compete on fulfillment velocity rather than material sourcing.
Pricing Analysis
Extended maintenance contracts and rotation services drive lifetime value in corporate art leasing programs. Three-tier pricing structure across premium, standard, and economy levels separates hand-applied originals with provenance documentation from giclée canvas wraps and mass-market paper prints. Cost compression in flat-pack alternatives intensifies because dimensional shipping penalties erode sculpture competitiveness. Hospitality procurement teams in Miami and New York design corridors exhibit the least price sensitivity, absorbing premium positioning for large-format commissions, while residential e-commerce buyers concentrate demand in standardized sizes.
Supply Chain Analysis
Cotton and linen agricultural yields, engineered wood panel resins, and UV-curable ink formulations anchor upstream feedstock dependencies. Manufacturing clusters in China, Vietnam, and India draw from concentrated textile and substrate production. Single-source vulnerability concentrates in Jiangsu, Shandong, and Fujian provinces, where over half of global canvas originates. Distribution runs through algorithm-driven direct-to-consumer platforms that capture value in fulfillment software layers rather than captive manufacturing assets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as hospitality procurement teams abandon legacy gallery intermediation for integrated service providers, creating niche openings for specialized healthcare art programming and wellness-sector evidence-based design contractors.
For Market Incumbents: Harden quality consistency by investing in color calibration expertise for wide-format digital systems, addressing master printer skill scarcity that constrains scaled operations. Deepen backward integration into certified lumber streams to satisfy FTC chain-of-custody requirements for environmental marketing claims. Consolidate supplier relationships toward verified material documentation as California Proposition 65 enforcement accelerates.
For New Entrants and Emerging Players: Pursue healthcare facility art programming as an underpenetrated vertical with multi-year installation cycles and maintenance revenue potential. Target evidence-based design protocols for stress reduction applications in Tokyo and Osaka wellness centers. Deploy augmented reality visualization tools to collapse sampling friction for contract interior designers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors asset-light platform operators with proprietary fulfillment software over capital-intensive manufacturing facilities. Long-term viability hinges on reverse-logistics infrastructure readiness for emerging extended producer responsibility frameworks. The signal to monitor is state-level take-back mandate progression for decorative goods.
| Strategic Initiative | Industry Significance |
|---|---|
| Print-on-Demand Platform Integration | Algorithm-driven discovery collapses sampling friction for residential buyers. |
| Healthcare Facility Partnership | Evidence-based design contracts anchor multi-year installation revenue streams. |
| Reverse-Logistics Infrastructure Buildout | Extended producer responsibility frameworks favor established take-back capabilities. |
| UV-Curable Ink System Adoption | Same-day turnaround eliminates solvent-based drying bottlenecks. |
| Certified Material Stream Investment | Proposition 65 compliance accelerates supplier consolidation toward verified documentation. |
Study Parameters
A spread of perspectives from hospitality procurement directors, interior design firm principals, print-on-demand platform operators, substrate manufacturing plant managers, and healthcare facility art program coordinators converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against customs records, SEC 10-K filings, and hospitality renovation contract databases. Bottom-up volume modeling and top-down value triangulation anchored the quantitative framework.
Demand-supply-balance framing structured the analytical approach across the projection horizon. Segmentation dimensions included art type, material substrate, aesthetic style, and distribution channel, with regional regulatory clusters layered as an overlay. CAGRs derived from installed capacity trajectories, hospitality renovation cycle timing, and e-commerce penetration curves. Forecast inputs incorporated UV-curable ink adoption rates and corporate art leasing program expansion.
Macroeconomic conditions sit as an overlay; deviation in residential renovation spending, hospitality capital expenditure cycles, or agricultural yield volatility would shift the trajectory. Forecasts reflect documented assumptions about print-on-demand infrastructure expansion and regulatory enforcement intensity. Cross-checking against hospitality procurement consortium contract awards is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Global Decorative Panels Market
Homecare and Decor
New Zealand Window Covering Market
Homecare and Decor
Interior Design Market
Homecare and Decor
Corner Pads Market
Homecare and Decor
Garden Sheds Market
Homecare and Decor
Hospital Bedsheet and Pillow Cover Market
Homecare and Decor
Asia-Pacific Wall Covering Market
Homecare and Decor
Bookends Market
Homecare and Decor
Door Handles Market
Homecare and Decor
Composite Doors and Windows Market
Homecare and Decor
Window Blinds Market
Homecare and Decor
Balcony Accessories Market
Homecare and Decor
United States Home Decor Market
Homecare and Decor
Soundproof Door Market
Homecare and Decor
Home Decor Market
Homecare and Decor
Digital Printed Wallpaper Market