
 France Furniture Market | 2026-2036
France Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
France Furniture Market Analysis
Mass customization software is fragmenting traditional batch production across French furniture workshops. Roche Bobois leverages its domestic manufacturing footprint to sustain rapid bespoke fulfillment timelines. Maisons du Monde anchors its competitive stance through diversified sourcing networks spanning European and Asian suppliers. Gautier Furniture differentiates via vertical control over its Vendée-based wood processing facilities.
Furniture encompasses movable objects engineered for human support, storage, and spatial organization, typically fabricated through CNC milling, upholstery framing, or metal bending processes with load-bearing tolerances specified per EN 1728 standards. The residential segment dominates volume flows, though hospitality-driven upholstery demand generates disproportionate margin capture. Wood materials retain structural importance in premium positioning, while metal components gain share in commercial and office applications requiring extended duty cycles. Scandinavian styling commands ascending preference among urban consumers in Paris and Bordeaux, displacing traditional ornate formats in new-build residential specifications.
ANSM oversight of chemical emissions in finished goods intersects with REACH substance restrictions administered by ECHA, compelling reformulation of adhesives and surface treatments across French supply chains. The EU Green Deal's embodied carbon reporting requirements, implemented through national adaptation by the French Ministry of Ecological Transition, now shape procurement criteria for public sector furniture contracts. Stakeholders must monitor evolving CSRD disclosure obligations and their downstream pressure on supplier certification tiers.
Market Dynamics
Mass customization software is fragmenting traditional batch production across French furniture workshops, compressing fulfillment timelines from weeks to days while elevating consumer expectations for bespoke configurations at near-mass-market price points.
Growth Catalysts
- Hospitality fit-out expansion:Hotel operators in Paris, Lyon, and Marseille are accelerating procurement cycles for bespoke interior fixtures to capture post-pandemic tourism recovery.
- EU Ecodesign for Sustainable Products Regulation:Material traceability mandates are creating competitive differentiation for domestic manufacturers with verifiable supply chains.
- Île-de-France construction concentration:Commercial and premium residential development in this region continues outpacing national averages, concentrating demand for high-specification fixtures.
Market Restraints
- Timber input cost volatility:Vendée-based wood processors face fluctuating hardwood lumber pricing that compresses margin predictability on solid-wood premium lines.
- Adhesive reformulation costs:ANSM oversight of chemical emissions intersecting with REACH substance restrictions forces costly R&D cycles across French supply chains.
- Import dependency for metal components:Extended duty-cycle office furniture relies on specialized steel and aluminum sourcing that concentrates exposure to Asian supplier lead times.
Strategic Opportunities
- CSRD disclosure tailwinds:Corporate sustainability reporting obligations are elevating procurement criteria for certified domestic suppliers in public sector furniture contracts.
- Scandinavian styling convergence:Urban consumers in Bordeaux and Paris are displacing ornate traditional formats, creating white space for minimalist wood-forward product lines.
- Embodied carbon reporting:French Ministry of Ecological Transition adaptation of EU Green Deal requirements favors localized manufacturing with lower transport emissions.
Industry Challenges
- CNC programming talent scarcity:Mass customization workflows require specialized operators capable of translating bespoke designs into machine-ready code without engineering bottlenecks.
- Dual certification timelines:Products must simultaneously satisfy ANSM chemical standards and EN 1728 load-bearing specifications, extending product development cycles.
- Upholstery framing skill gaps:Traditional hand-tied spring construction expertise is aging out faster than vocational programs replenish qualified craftspeople.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Furniture Market |
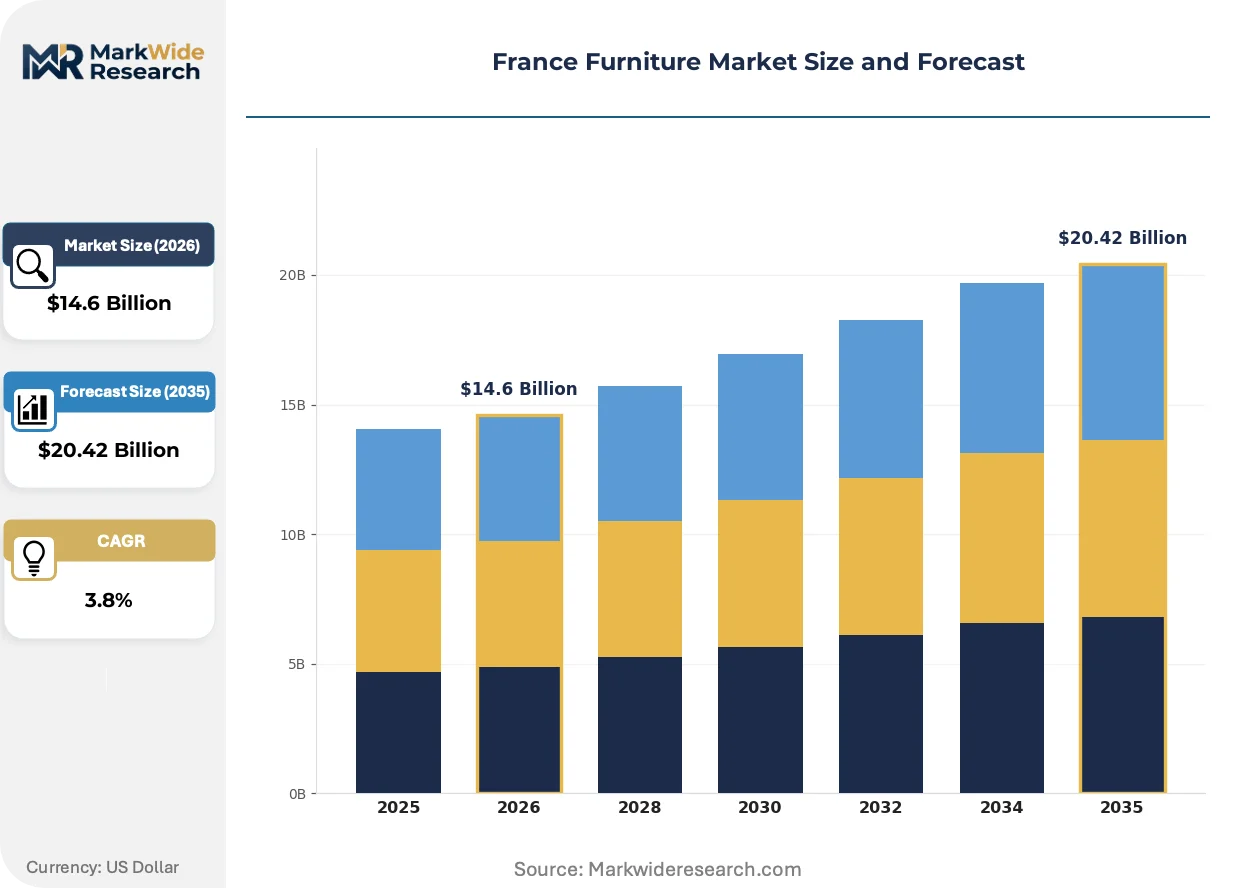
| Market Size in 2026 | $14.6 Billion |
| Market Size in 2035 | $20.42 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Chairs, Tables, Beds Material: Wood, Metal, Plastic, Upholstery Style: Modern, Traditional, Rustic, Scandinavian End User: Residential, Commercial, Hospitality, Office |
| Companies Covered | BoConcept, IKEA, Roche Bobois, Selency, Maisons du Monde, Ligne Roset, Natuzzi, TipToe Design, Gautier Furniture, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Furniture Market Emerging Trajectories
Digital fabrication workflows are compressing the boundary between standardized components and one-off customization, enabling French workshops to compete with mass-market pricing while preserving craft positioning.
CNC milling combined with parametric design software is hybridizing production economics across mid-tier French manufacturers. Hospitality procurement teams in Marseille and Lyon now specify made-to-measure fixtures with seven-day turnaround expectations. This capability compression is forcing traditional batch producers to adopt modular component libraries or cede premium project access.
The EU Green Deal's embodied carbon reporting requirements, implemented through French Ministry of Ecological Transition adaptation, are restructuring public sector tender evaluation criteria. Furniture contracts now weight lifecycle emissions alongside unit pricing, advantaging domestic manufacturers with shorter transport radii. Municipal procurement offices in Paris and Bordeaux have begun disqualifying bids lacking third-party carbon verification.
Specification preferences among urban residential buyers are rotating toward Scandinavian minimalism and away from ornate traditional formats. Interior designers in Bordeaux report accelerating client rejection of carved wood detailing in favor of clean-lined oak and ash configurations. This aesthetic displacement is reshaping showroom inventory decisions and forcing heritage-positioned makers to develop parallel contemporary product architectures.
France Furniture Market Segmentation
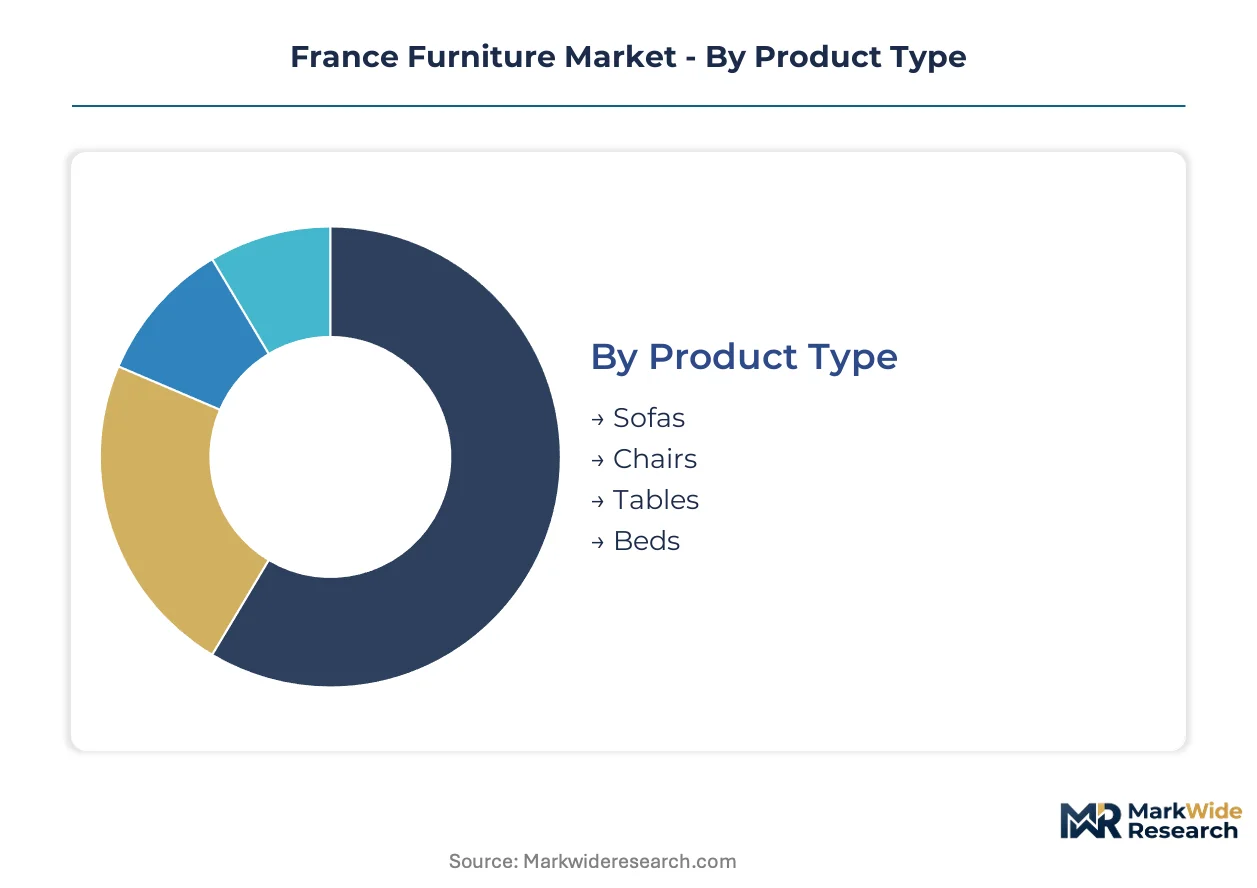
Furniture procurement in France fragments across distinct technical specifications, aesthetic positioning, and duty-cycle requirements. Each segmentation dimension reveals divergent margin structures and supply chain configurations that shape competitive strategy.
Product Type:
Volume concentration across these categories reflects divergent production economics and fulfillment complexity.
- Sofas:Engineered around multi-density foam cores with hardwood framing and suspension systems rated for residential or commercial duty cycles. Hospitality operators in Paris specify bespoke configurations with seven-day turnaround expectations, compressing traditional batch production timelines.
- Chairs:Span dining, accent, and task-oriented formats with load-bearing tolerances certified per EN 1728 standards. Upholstery framing skill gaps in Vendée and Lyon workshops constrain output scaling for premium hand-tied spring construction.
- Tables:CNC-milled surfaces with edge-banding and substrate selection driving cost tier differentiation.
- Beds:Slatted base systems and headboard integration dominate residential procurement in Île-de-France.
Sofas command the established base. The steepest expansion runs through Chairs.
Material:
Raw material selection determines regulatory exposure, carbon footprint verification, and margin predictability across French supply chains.
- Wood:Oak, ash, and beech predominate in premium positioning, with Vendée-based processors facing hardwood lumber price volatility. ANSM chemical emissions oversight intersects with surface treatment formulations, forcing adhesive reformulation cycles.
- Metal:Specialized steel and aluminum components serve extended duty-cycle office applications. Import dependency concentrates exposure to Asian supplier lead times for precision-formed frames.
- Plastic:Polymer formulations face REACH substance restrictions administered by ECHA.
- Upholstery:Fabric, leather, and synthetic coverings complete seating assemblies with divergent maintenance specifications.
Wood retains the dominant revenue share. Metal is climbing the fastest on commercial fit-out demand.
Style:
Aesthetic positioning in France is rotating toward formats that simplify manufacturing complexity while preserving premium pricing power.
- Modern:Clean-lined geometries with minimal ornamentation enable CNC-driven production efficiency. Urban consumers in Bordeaux and Paris displace carved detailing in favor of oak and ash configurations.
- Scandinavian:Light wood tones and functional minimalism align with EU Green Deal embodied carbon preferences for lighter transport loads. Interior designers report accelerating client adoption in new-build residential specifications.
- Traditional:Ornate carved wood and rich upholstery retain heritage positioning but face shrinking new-build specification share.
- Rustic:Distressed finishes and reclaimed material claims serve vacation property segments in Provence and coastal regions.
Traditional formats anchor the installed base. Scandinavian styling is gaining share fastest among urban residential buyers.
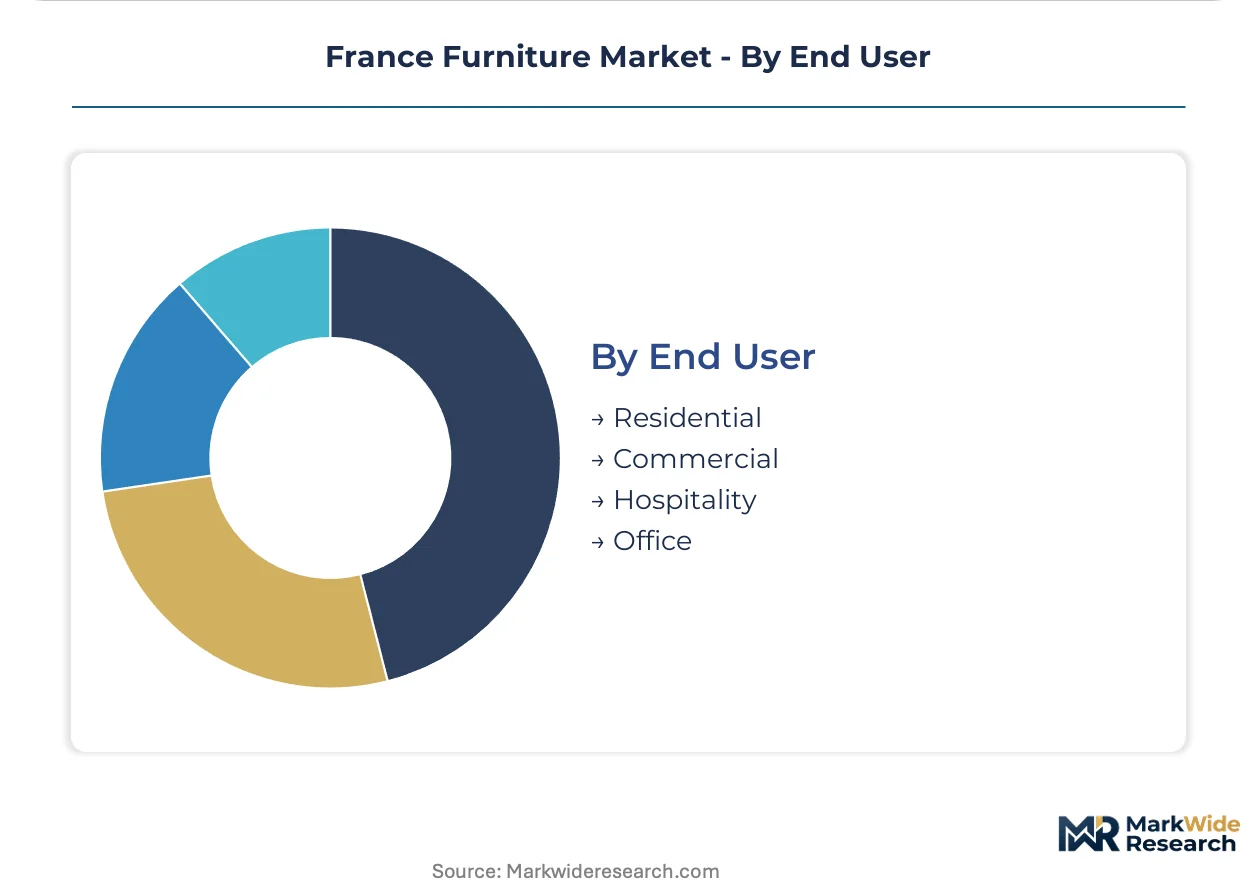
End User:
Customer type determines specification intensity, certification requirements, and procurement cycle length across French markets.
- Residential:Volume-dominant segment spanning mass-market through premium bespoke commissioning. Île-de-France construction concentration outpaces national averages for high-specification fixture demand.
- Hospitality:Hotel operators in Paris, Lyon, and Marseille accelerate procurement for bespoke interior fixtures to capture post-pandemic tourism recovery. This segment generates disproportionate margin capture despite lower unit volumes.
- Commercial:Retail and public-facing spaces require extended duty-cycle performance with standardized maintenance protocols.
- Office:Ergonomic certification and modularity specifications dominate enterprise procurement governed by CSRD disclosure obligations.
Residential commands the established base. Hospitality shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's furniture market concentrates procurement power among hospitality operators in Paris, Lyon, and Marseille alongside premium residential developers in Île-de-France. These buyer archetypes drive specification intensity and compress fulfillment timelines across domestic supply chains.
Île-de-France
Commercial fit-out activity and premium residential development in this region outpace national averages, concentrating demand for high-specification fixtures. ANSM chemical emissions oversight intersects with REACH substance restrictions, compelling reformulation of adhesives among Paris-based manufacturers. Interior designers in the capital report accelerating client adoption of Scandinavian minimalism over traditional ornate formats.
Auvergne-Rhône-Alpes
Lyon anchors hospitality-driven upholstery demand as hotel operators accelerate procurement cycles to capture post-pandemic tourism recovery. The EU Ecodesign for Sustainable Products Regulation tightens material traceability requirements for all furniture placed on the French market. CNC programming talent scarcity constrains output scaling among workshops in the Rhône corridor.
Provence-Alpes-Côte d'Azur
Marseille hospitality operators expand procurement of bespoke interior fixtures with compressed seven-day turnaround expectations. French Ministry of Ecological Transition adaptation of EU Green Deal embodied carbon reporting requirements shapes municipal tender evaluation criteria. Coastal vacation property segments sustain demand for rustic distressed finishes and reclaimed material claims.
Pays de la Loire
Vendée-based wood processors face hardwood lumber price volatility that compresses margin predictability on solid-wood premium lines. ANSM oversight forces costly R&D cycles for surface treatment reformulations across regional supply chains. Vertical control over captive wood processing facilities differentiates domestic manufacturers from import-dependent competitors.
Nouvelle-Aquitaine
Bordeaux urban consumers displace carved wood detailing in favor of clean-lined oak and ash configurations. CSRD disclosure obligations elevate procurement criteria for certified domestic suppliers in public sector furniture contracts. Regional workshops adopt mass customization software to fragment traditional batch production and compress fulfillment timelines.
France Furniture Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base organizes around scale-driven retailers, craft-positioned domestic manufacturers, and digitally native platforms. Three strategic archetypes dominate: vertically integrated wood processors, diversified sourcing networks, and parametric-design-enabled bespoke specialists. Competitive moves concentrate on modular component library development and rapid fulfillment capability investments.
Among Denmark-based contemporary specialists, BoConcept occupies a position exemplifying scalable minimalist design systems. Swedish retailer IKEA anchors the mass-market tier through global sourcing density and flat-pack logistics optimization. French craft-positioned players Roche Bobois and Gautier Furniture sit within the domestic manufacturing archetype, with the latter representing vertical integration into regional wood processing. Maisons du Monde exemplifies diversified sourcing strategies spanning European and Asian supplier networks.
| Leading Market Players |
|---|
| BoConcept |
| IKEA |
| Roche Bobois |
| Selency |
| Maisons du Monde |
| Ligne Roset |
| Natuzzi |
| TipToe Design |
| Gautier Furniture |
| Others |
Supply Flow & Price Mechanics
Hardwood lumber price volatility in Vendée-based wood processing determines both tiered pricing spreads across solid-wood premium lines and the geographic shape of domestic supply chain investments. Cost compression in mid-tier upholstery forces manufacturers to index raw material contracts against commodity benchmarks while restructuring supplier payment terms.
Pricing Analysis
Cost-plus contracts with hardwood lumber indexation anchor pricing structures across French furniture workshops. Premium-mid-economy pricing differentiation separates bespoke hospitality configurations from standardized residential offerings, with certification grade and customization level as primary price drivers. Pricing pressure stems from adhesive reformulation costs under ANSM oversight, with hospitality operators least price-sensitive due to compressed turnaround requirements.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities now structure procurement relationships between domestic manufacturers and Asian metal component suppliers. Precision-formed steel and aluminum frames draw from China, Vietnam, and South Korea, creating single-source vulnerability for extended duty-cycle office furniture. Distribution runs through direct-to-hospitality project channels alongside retail showroom networks anchored in Paris and Lyon.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospitality procurement consolidation across Paris, Lyon, and Marseille has shifted buyer power toward operators demanding seven-day bespoke fulfillment timelines. This concentration fragments margin capture across traditional batch producers.
For Market Incumbents: Build parametric-design-enabled fulfillment moats by investing in CNC programming talent pipelines and modular component libraries. Defensive moves must address upholstery framing skill gaps through vocational partnerships while securing ANSM-compliant adhesive formulations ahead of REACH substance restriction expansions. For New Entrants and Emerging Players: Establish a beachhead in Scandinavian-styled residential segments where Bordeaux and Paris interior designers report accelerating client adoption. White space exists in carbon-verified domestic manufacturing for public sector contracts; go-to-market positioning should emphasize embodied carbon reporting compliance under French Ministry of Ecological Transition adaptation. For Investors and Strategic Acquirers: The market sits at a capability-scarcity phase that favors vertically controlled wood processors with captive Vendée facilities. Long-term viability hinges on backward integration depth rather than sourcing diversification. Watch CSRD disclosure obligation enforcement as the inflection signal elevating certified domestic supplier premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Mass Customization Software Deployment | Parametric design platforms compress fulfillment timelines for hospitality procurement teams in Marseille. |
| Carbon Verification Certification | Third-party lifecycle emissions documentation qualifies bids for municipal contracts in Paris and Bordeaux. |
| Vocational Training Partnerships | Upholstery framing skill pipelines address aging-out craft expertise in Vendée and Lyon workshops. |
| Adhesive Reformulation R&D | ANSM-compliant surface treatments satisfy REACH substance restrictions across French supply chains. |
| Modular Component Library Development | Standardized parts enable rapid bespoke configuration without engineering bottlenecks. |
Methodological Framework
Two parallel data streams informed the analysis: primary field engagement with furniture manufacturing executives, hospitality procurement directors, interior design practitioners, and regional wood processing facility managers; alongside secondary validation through customs trade records, ANSM regulatory filings, EU Ecodesign implementation documents, and French Ministry of Ecological Transition procurement guidelines. Bottom-up production capacity assessments and top-down consumption estimates were triangulated to establish market sizing.
Forecast inputs span product type, material composition, aesthetic positioning, and end-user category across the analysis window. CAGRs were derived from segment-level growth trajectories weighted by construction activity indices in Île-de-France and tourism recovery patterns in Paris, Lyon, and Marseille. Modeled outputs incorporate embodied carbon reporting adoption curves and CSRD disclosure penetration rates among public sector buyers.
Stress conditions across hardwood lumber pricing bands, Asian supplier lead time disruptions, and REACH substance restriction timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding hospitality fit-out expansion continuity and Scandinavian styling preference persistence. Macroeconomic contraction, regulatory acceleration, or mass customization technology disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Global OFF-THE-SHELF Second Hand Furniture Market
Furniture
Russia Home Furniture Market
Furniture
GCC Smart Furniture Market
Furniture
Salon Chairs Market
Furniture
Wood Furniture Market
Furniture
Kids Furniture Market
Furniture
Global Smart Furniture Market
Furniture
Contract Furniture and Furnishing Market
Furniture
Europe Bamboo Furniture Market
Furniture
Middle East and Africa Wood Based Panel Market
Furniture
Europe Sustainable Home Furniture Market
Furniture
Italy Luxury Furniture Market
Furniture
Luxury RTA (Ready-To-Assemble) Furniture Market
Furniture
Middle East and Africa Free Standing Electrical Height-Adjustable Tables Market
Furniture
North America Smart Furniture Market
Furniture
North America Secondary Wood Products Market