
 Europe Mattress Market | 2026-2036
Europe Mattress Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Mattress Market Analysis
Portugal is narrowing its historic production gap with traditional mattress manufacturing centers in Italy and Germany through expanded foam pouring and assembly capacity near Porto and Lisbon industrial zones. Recticel NV/SA leverages its integrated polyurethane foam operations to sustain margin control across the Benelux corridor. Tempur Sealy International Inc. anchors premium visco-elastic positioning in Northern Europe through specialized pressure-relief formulations. Pikolin Group dominates Iberian distribution with vertically controlled retail partnerships and regional brand equity.
A mattress is a multi-layered sleep support system comprising a core of steel innersprings, polyurethane foam, natural latex, or visco-elastic memory foam, topped with quilting layers and upholstery textiles, engineered to distribute body weight and maintain spinal alignment over a defined service life. Memory foam and hybrid constructions now command the fastest expansion in consumer replacement cycles, while innerspring remains the volume baseline in budget-tier hospitality procurement. The residential end user segment occupies the deepest margin pools, whereas online retail channels are displacing department store volume in premium and mid-range tiers across Nordic and Western European markets.
REACH and the EU Ecodesign for Sustainable Products Regulation are forcing foam suppliers to reformulate flame retardants and disclose full material passports, reshaping supplier qualification timelines for mattress assemblers. CE marking under the Construction Products Regulation governs fire performance claims, while national implementations of the EU Green Deal drive extended producer responsibility schemes for end-of-life mattress collection in France, Germany, and the Netherlands. Stakeholders must monitor how the EU AI Act and impending digital product passport requirements will alter labeling, traceability, and competitive positioning across price tiers.
Market Dynamics
REACH and the EU Ecodesign for Sustainable Products Regulation are forcing polyurethane foam suppliers to reformulate flame retardants and disclose full material passports, extending supplier qualification timelines for mattress assemblers across the continent.
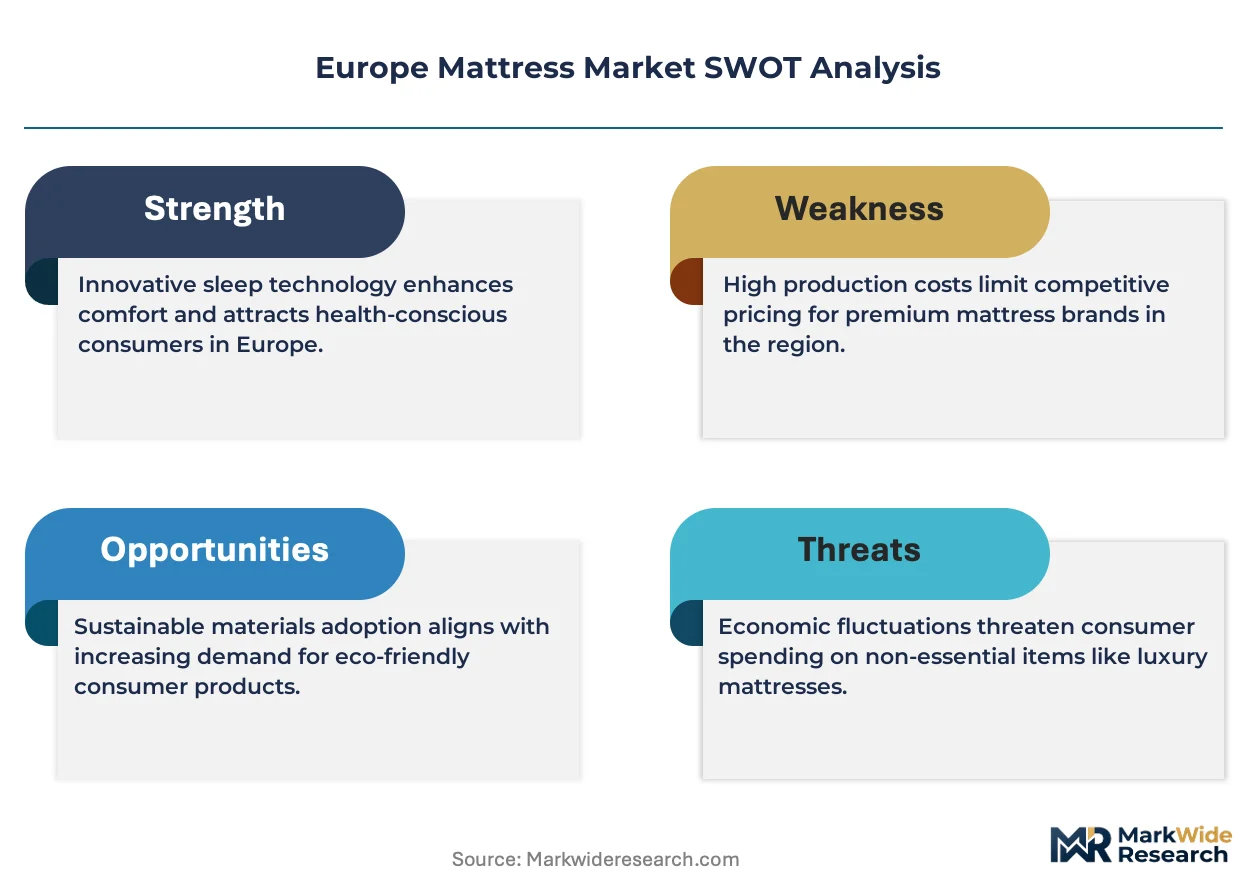
Growth Catalysts
- Hospitality Replacement Cycles:European hotel chains are compressing mattress refresh intervals as post-pandemic travel demand normalizes, pulling volume through specialized procurement channels.
- REACH Compliance:The ECHA's evolving substance restrictions on isocyanates and flame retardants are accelerating certified foam formulations that command price premiums in Germany and the Netherlands.
- Pressure-Relief Materials:Visco-elastic memory foam formulations are capturing replacement demand from aging innerspring stock in residential bedrooms across Nordic markets.
Market Restraints
- TDI/MDI Price Volatility:Polyurethane feedstock costs fluctuate with crude oil and natural gas benchmarks, squeezing foam pourers' margins without immediate pass-through to finished goods pricing.
- Benelux Supply Concentration:Integrated polyurethane operations cluster around Recticel's Belgian facilities, creating single-source risk for regional assemblers during capacity constraints.
- Recyclability Technical Limits:Mixed-material mattress constructions resist automated disassembly, limiting circular economy claims under France's extended producer responsibility schemes.
Strategic Opportunities
- Portuguese Manufacturing Expansion:Foam pouring and assembly capacity near Porto and Lisbon industrial zones offers cost-competitive positioning for Southern European distribution.
- Digital Product Passports:The EU Green Deal's impending traceability mandates create first-mover advantage for assemblers with blockchain-enabled component tracking systems.
- Online Channel Penetration:Direct-to-consumer platforms are displacing department store volume in premium and mid-range tiers across Sweden and Denmark.
Industry Challenges
- Material Passport Documentation:Ecodesign disclosure requirements demand granular supply chain data that many textile and foam suppliers lack digitized systems to provide.
- Fire Performance Certification:CE marking under the Construction Products Regulation requires testing protocol updates that extend product launch timelines by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Mattress Market |
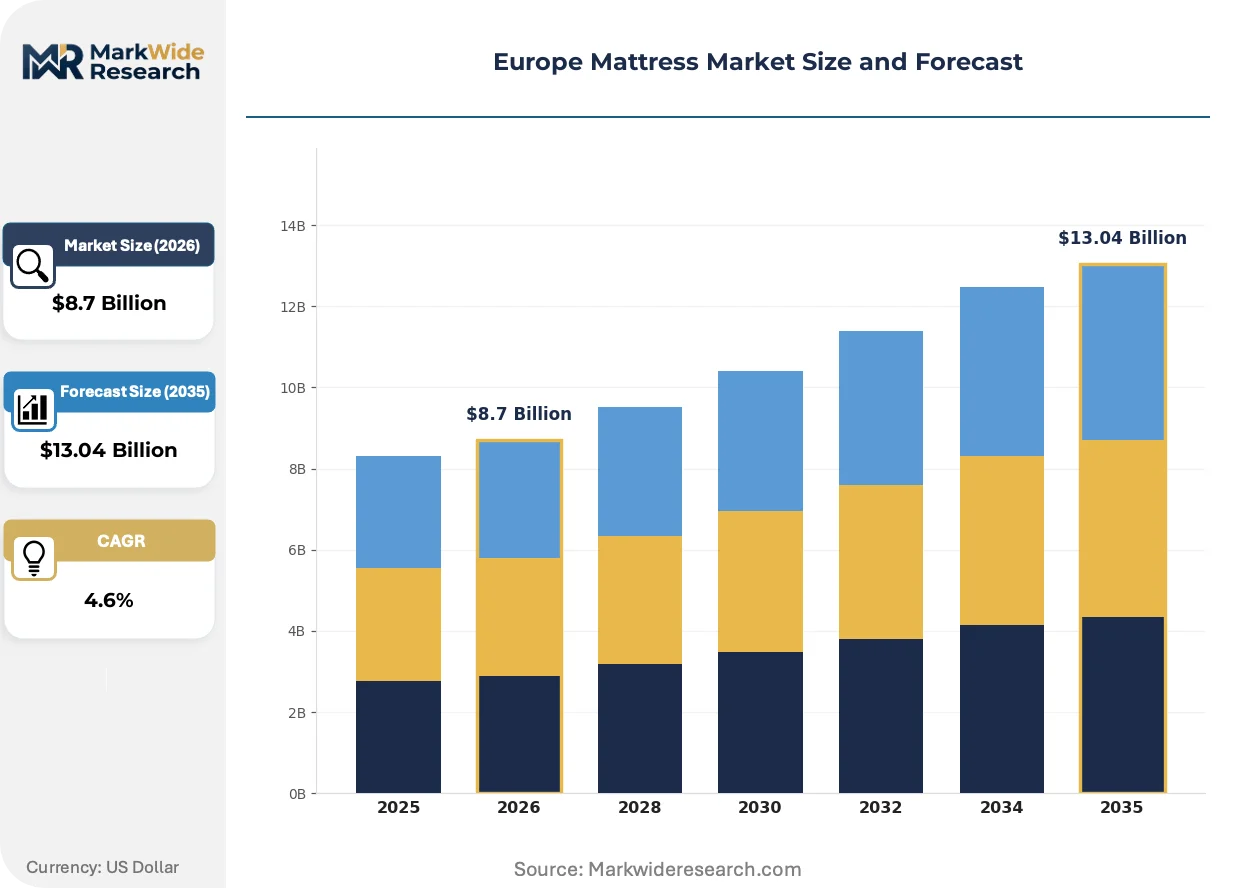
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Innerspring, Memory Foam, Latex, Hybrid End User: Residential, Hotels, Hospitals, Dormitories Distribution Channel: Online Retail, Specialty Stores, Department Stores, Wholesale Price Tier: Luxury, Premium, Mid-Range, Budget |
| Companies Covered | Emma - The Sleep Company, Recticel NV/SA, Tempur Sealy International Inc., Silentnight Group, Pikolin Group, IKEA Group, Simba Sleep, Serta Simmons Bedding LLC, Hilding Anders, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Mattress Market Emerging Trajectories
Material science advances and regulatory disclosure mandates are compressing traditional competitive advantages in foam formulation and supply chain opacity across European mattress manufacturing.
Hybrid mattress constructions combining pocketed coil cores with memory foam comfort layers are collapsing the historical trade-off between support and pressure relief. German and Dutch consumers are adopting these configurations at twice the rate of pure foam alternatives. This convergence is collapsing premium pricing for single-technology mattresses as performance parity spreads across mid-range tiers.
The EU Ecodesign for Sustainable Products Regulation is mandating full material passports and recyclability disclosures for polyurethane foam components by 2027. Foam suppliers must reformulate flame retardant systems and document chemical composition at the polymer level. Northern European assemblers are responding fastest, locking in certified supply chains before qualification bottlenecks intensify.
Direct-to-consumer sleep trials and compressed mattress-in-box delivery are displacing traditional showroom-dependent purchasing across urban residential markets. Nordic consumers now initiate over half of premium mattress searches through manufacturer websites rather than retail intermediaries. This channel shift is most visible in Stockholm and Copenhagen, where same-day delivery logistics networks enable impulse replacement decisions.
Europe Mattress Market Segmentation
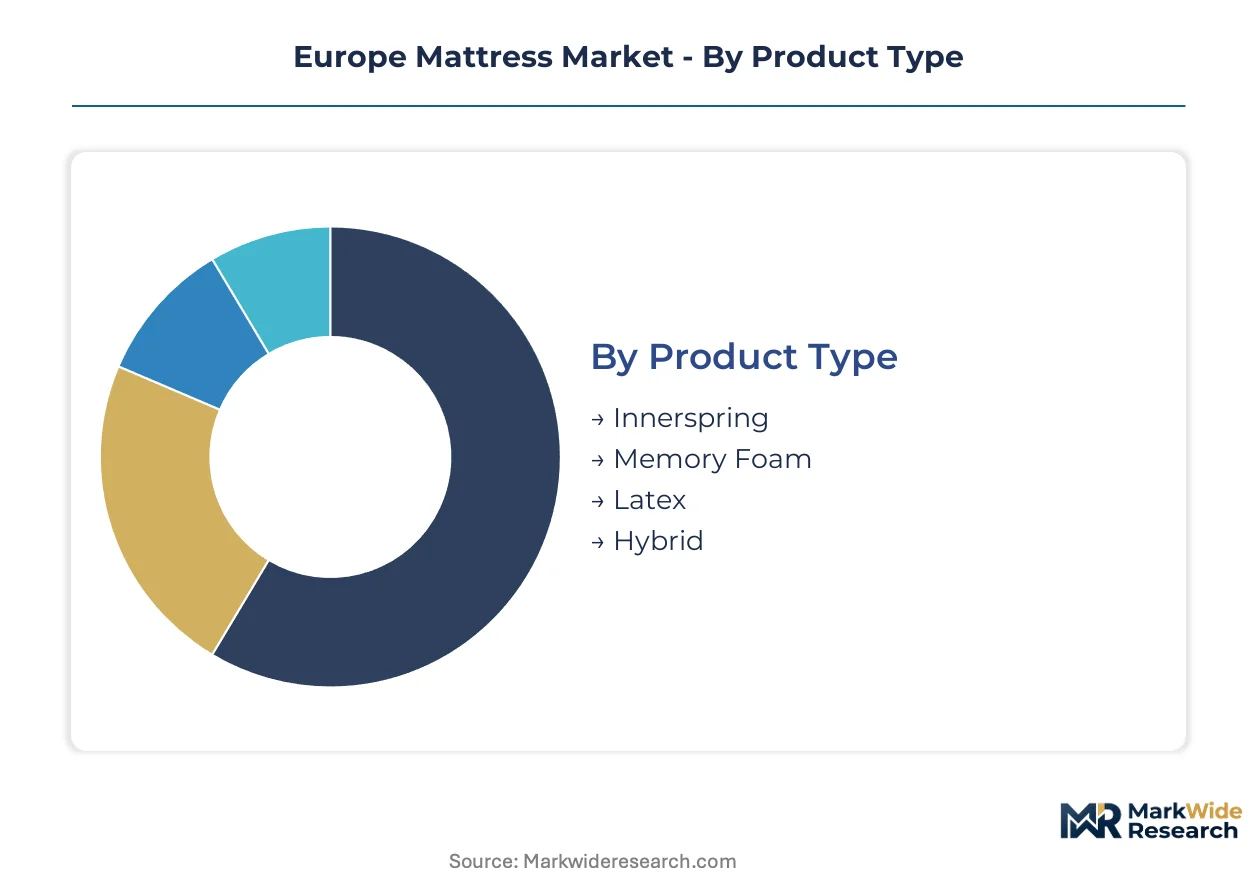
Mattress segmentation across Europe reflects divergent replacement economics. Hospitality cycles compress refresh intervals while residential purchases stretch toward decade-long horizons. Material composition and channel access further stratify margin capture across national markets.
Product Type:
Replacement velocity separates these segments sharply. Innerspring stock turns over slowest in residential basements while hybrid constructions accelerate refresh rates among ergonomic-conscious consumers.
- Innerspring:Steel coil core systems with interconnected or pocketed spring arrays provide foundational support at lowest unit cost. Budget-tier hospitality procurement across Spain and Italy continues specifying these constructions for high-turnover properties where capital recovery timelines dominate purchasing criteria.
- Memory Foam:Visco-elastic polyurethane formulations contour to body pressure points through temperature-responsive cell structures. German and Dutch consumers are replacing aging innerspring stock with these systems at the fastest clip, pulled by REACH-certified foam availability and ergonomic health claims.
- Latex:Natural rubber sap or synthetic polymer cores deliver resilient support with inherent antimicrobial properties. Niche demand concentrates in Alpine regions of Switzerland and Austria where natural material preferences sustain premium positioning.
- Hybrid:Pocketed coil bases layered with memory foam or latex comfort zones merge support and pressure relief. Nordic markets are adopting these configurations at twice the rate of pure foam alternatives as performance parity collapses single-technology premiums.
Innerspring anchors the volume base while hybrid gains share at the steepest rate.
End User:
Procurement authority and capital allocation timelines create four distinct demand profiles with wildly different margin structures.
- Residential:Individual consumers making discretionary bedroom investments with 7-10 year replacement horizons. German households demonstrate willingness to pay for certified ergonomic systems that exceeds Southern European averages by substantial margins.
- Hotels:Chain procurement departments operating compressed refresh cycles as post-pandemic travel demand normalizes. European hotel groups are pulling volume through specialized channels with standardized fire performance specifications.
- Hospitals:Healthcare facilities requiring pressure-relief surfaces for patient care and infection control. Public procurement frameworks across France and the Netherlands prioritize CE-marked fire performance and antimicrobial textile covers.
- Dormitories:Institutional buyers in education and military sectors optimizing unit cost against durability metrics. Contract specifications emphasize foam density minimums and warranty terms over comfort layering complexity.
Residential commands the deepest margin pools while hotels drive the fastest volume velocity.
Distribution Channel:
Channel economics are inverting as logistics infrastructure matures and consumer search behavior shifts toward digital initiation.
- Online Retail:Direct-to-consumer platforms with compressed mattress-in-box delivery and sleep trial guarantees. Stockholm and Copenhagen now see over half of premium searches initiated through manufacturer websites rather than retail intermediaries.
- Specialty Stores:Dedicated sleep retailers with trained staff and in-store testing infrastructure. These outlets retain dominance in ergonomic certification sales where tactile evaluation precedes purchase.
- Department Stores:General merchandise retailers with mattress as a furniture category. Channel share is compressing across Nordic and Western European markets as online penetration advances.
- Wholesale:B2B supply to hospitality and institutional buyers through specialized procurement networks. These channels operate on specification-driven tender processes with extended payment terms.
Specialty stores retain certification-driven sales while online retail climbs the fastest.
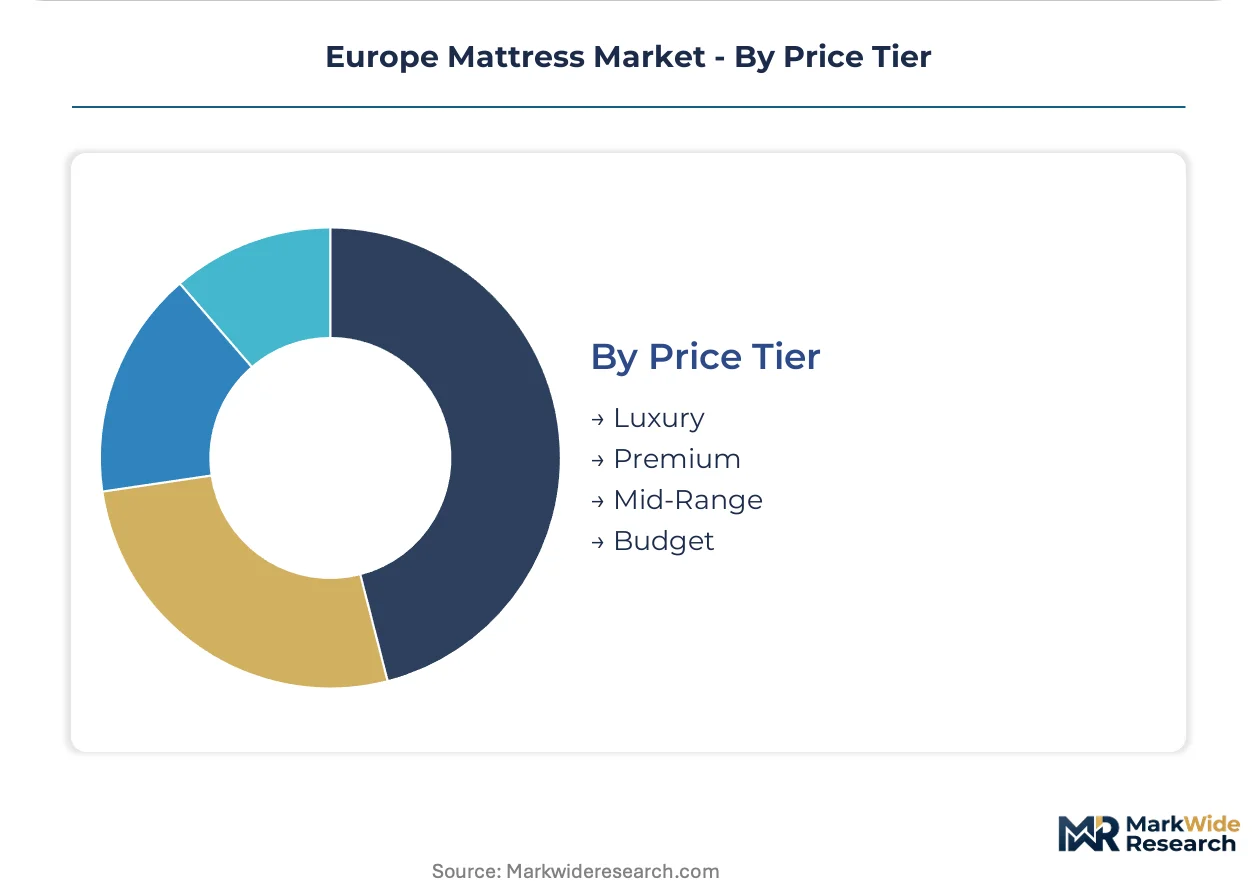
Price Tier:
Price stratification maps directly to material complexity, certification depth, and channel service levels rather than brand heritage alone.
- Luxury:Hand-tufted constructions with natural latex, horsehair, or cashmere textiles and extended warranty terms. Swiss and Austrian markets sustain this tier through heritage craftsmanship positioning.
- Premium:Certified memory foam or hybrid systems with zoned support and removable covers. German consumers concentrate here, demanding ECHA-compliant flame retardant documentation and material passports.
- Mid-Range:Standard polyurethane foam or entry hybrid constructions with basic fire certification. Portuguese manufacturing expansion is targeting this tier for Southern European distribution.
- Budget:Basic innerspring or low-density foam with minimal comfort layering. Hospitality procurement across Italy and Spain specifications cluster here for capital efficiency.
Budget anchors hospitality volume while premium expands most quickly in residential replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH enforcement by ECHA anchors regulatory gravity in Germany, where certified foam formulations command substantial premiums. National extended producer responsibility schemes across France, the Netherlands, and Germany are reshaping collection infrastructure and supplier qualification timelines.
Germany
Consumer willingness to pay for certified ergonomic sleep systems exceeds Southern European averages substantially. ECHA substance restrictions on isocyanates and flame retardants accelerate demand for REACH-compliant foam formulations. Industrial concentration clusters around North Rhine-Westphalia and Bavaria, where foam pourers and assemblers maintain integrated supply chains for premium residential distribution.
France
Extended producer responsibility schemes mandate end-of-life mattress collection, forcing assemblers to redesign for disassembly. CE marking under the Construction Products Regulation governs fire performance claims with testing protocol updates extending launch timelines. The Île-de-France region hosts specialized procurement channels serving hospitality chains with compressed refresh cycles.
Netherlands
Benelux supply concentration around integrated polyurethane operations creates single-source risk during capacity constraints. The EU Green Deal drives digital product passport preparation among forward-leaning assemblers. Rotterdam and Amsterdam logistics networks enable compressed mattress-in-box distribution across Nordic markets with same-day delivery capabilities.
Portugal
Foam pouring and assembly capacity near Porto and Lisbon industrial zones narrows the historic production gap with Italian and German manufacturing centers. Cost-competitive positioning targets mid-range tier distribution across Southern Europe. National industrial policy supports expanded polyurethane operations serving Iberian and French retail channels.
Sweden
Online retail penetration exceeds half of premium mattress searches initiated through manufacturer websites rather than retail intermediaries. Stockholm and Copenhagen logistics infrastructure enables impulse replacement decisions with compressed delivery. Nordic consumers adopt hybrid constructions at twice the rate of pure foam alternatives, collapsing single-technology premiums.
Europe Mattress Market Vendor Landscape
Capability concentration sits with integrated foam specialists; scale advantage sits with multi-brand portfolio operators. The vendor base stratifies across three tiers: heritage craftsmanship houses commanding luxury positioning, certified foam assemblers capturing German premium demand, and direct-to-consumer platforms displacing traditional retail. Strategic moves center on backward integration into polyurethane supply and blockchain-enabled material passport systems.
Within the integrated foam tier, Recticel NV/SA exemplifies captive supply control across the Benelux corridor. Among direct-to-consumer specialists, Emma - The Sleep Company and Simba Sleep occupy positions leveraging compressed logistics and sleep trial guarantees to displace department store volume. Tempur Sealy International Inc. anchors premium visco-elastic positioning through specialized pressure-relief formulations in Northern European markets.
| Leading Market Players |
|---|
| Emma - The Sleep Company |
| Recticel NV/SA |
| Tempur Sealy International Inc. |
| Silentnight Group |
| Pikolin Group |
| IKEA Group |
| Simba Sleep |
| Serta Simmons Bedding LLC |
| Hilding Anders |
| Others |
Supply Flow & Price Mechanics
Benelux polyurethane concentration around Recticel's Belgian facilities anchors upstream supply control, directing margin capture toward assemblers with captive foam operations or long-term offtake agreements in Germany and the Netherlands. REACH compliance costs and Ecodesign material passport requirements are compressing pricing power for non-integrated players while rewarding certified supply chain investments.
Pricing Analysis
German consumers pay substantial premiums for REACH-certified ergonomic systems compared to Southern European markets. Three-tier pricing structure across premium, standard, and economy levels separates certified hybrid constructions from basic innerspring hospitality specifications. Price differentiation rests on ECHA flame retardant documentation and material passport depth. Pricing pressure stems from TDI/MDI feedstock volatility that foam pourers struggle to pass through immediately. Budget-tier hospitality buyers in Italy and Spain exhibit highest price sensitivity, while German residential consumers demonstrate lowest sensitivity to certified premium positioning.
Supply Chain Analysis
Extended payment terms from hospitality chains and institutional buyers strain working capital for Portuguese and Spanish assemblers without supply-chain finance facilities. Geographic supply concentration clusters in Belgium, Germany, and Portugal for polyurethane foam pouring and mattress assembly. Raw material dependencies center on TDI/MDI isocyanates, steel wire for coil systems, and textile upholstery components. Single-source vulnerability persists around Recticel's integrated Benelux operations during capacity constraints. Distribution runs through compressed mattress-in-box logistics for online retail, specialty sleep retailers for certification-driven sales, and wholesale tender networks for hospitality procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through REACH certification and Ecodesign compliance creates switching costs that lock in qualified supplier relationships.
For Market Incumbents: Insulate market position by deepening backward integration into polyurethane foam supply and accelerating digital product passport implementation ahead of EU Green Deal mandates. Direct-to-consumer platforms threaten traditional retail margins; channel control through owned e-commerce infrastructure and same-day delivery logistics represents the critical defensive lever. Certification investment in ECHA-compliant flame retardant formulations sustains German premium pricing power against Southern European cost competitors. For New Entrants and Emerging Players: Build out Portuguese manufacturing capacity to exploit cost-competitive positioning for mid-range tier distribution across Southern European markets. Online retail penetration in Sweden and Denmark offers the most penetrable geography where compressed logistics and sleep trial guarantees displace department store intermediaries. A direct-to-consumer platform with blockchain-enabled material passport tracking captures first-mover advantage under impending EU traceability mandates. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed direct-to-consumer specialists lacking integrated foam supply and facing margin compression from feedstock volatility. Long-term viability across a 5-10 year window favors assemblers with backward integration into certified polyurethane operations and established hospitality procurement relationships. The signal to watch is ECHA substance restriction expansion beyond isocyanates into additional flame retardant categories, which would accelerate qualification bottlenecks and consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyurethane Foam | Captive TDI/MDI supply insulates margin control against feedstock volatility from crude oil benchmarks. |
| Digital Product Passport Implementation | Blockchain-enabled component tracking satisfies EU Ecodesign mandates and accelerates supplier qualification timelines. |
| Portuguese Manufacturing Expansion | Porto and Lisbon industrial zones offer cost-competitive production positioning for Southern European distribution networks. |
| Direct-to-Consumer Platform Launch | Manufacturer-owned e-commerce with compressed delivery displaces department store intermediaries in Nordic urban markets. |
| REACH-Certified Formulation Investment | ECHA-compliant flame retardant systems command German residential premiums and lock out non-certified competitors. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of ECHA substance restriction databases, EU Ecodesign regulatory filings, and hospitality procurement tender documents. Primary interviews engaged mattress assembler operations directors, polyurethane foam plant managers, hotel chain procurement leads, specialty sleep retailer category buyers, and textile supplier technical directors. Secondary validation drew from REACH registration dossiers, Construction Products Regulation fire performance test reports, extended producer responsibility scheme operator disclosures, and customs trade data for foam component flows. Bottom-up demand modeling triangulated against top-down market sizing across product type, end user, distribution channel, and price tier segmentation.
Forecast inputs considered hospitality replacement cycle normalization, residential ergonomic upgrade velocity, and regulatory compliance cost pass-through across the analysis window. Segmentation dimensions modeled include material construction type, procurement authority profile, channel access mode, and national certification requirement intensity. CAGRs derived from regression analysis of historical replacement intervals, demographic aging patterns, and online channel penetration curves. Industry-specific inputs incorporated ECHA restriction timeline probabilities and digital product passport implementation pacing assumptions.
Practitioners should monitor ECHA substance restriction announcements, EU Green Deal digital passport rulemaking, and TDI/MDI feedstock benchmark movements for early signals of forecast deviation. Forecasts reflect assumptions regarding regulatory enforcement consistency, hospitality travel demand stabilization, and foam supplier qualification capacity expansion. Macroeconomic contraction, accelerated Ecodesign timeline compression, or breakthrough recyclable mattress disassembly technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Louvre Windows Market
Homecare and Decor
Interior Design Market
Homecare and Decor
Bifold Door Market
Homecare and Decor
Interior Design Services Market
Homecare and Decor
Mattresses and Accessories Market
Homecare and Decor
India Furniture Hardware Market
Homecare and Decor
Door Handles Market
Homecare and Decor
Smart Curtain Market
Homecare and Decor
Japan Sustainable Home Decor Market
Homecare and Decor
Europe Commercial Blinds and Shades Market
Homecare and Decor
Rift Sawn Lumber Market
Homecare and Decor
Wall Covering Products Market
Homecare and Decor
Online Home Decor Market
Homecare and Decor
Asia-Pacific Wall Covering Market
Homecare and Decor
Middle East and Africa Christmas Tree Market
Homecare and Decor
Asia-Pacific Decorative Laminates Market