
 Fiberglass Fabric Market | 2026-2036
Fiberglass Fabric Market Size, Share, and Industry Trends Forecast 2026-2036
Fiberglass Fabric Market Analysis
Direct-to-turbine-blade supply channels is fragmenting as original equipment manufacturers diversify beyond legacy distributors toward mill-direct arrangements and regional composite converters. Owens Corning leverages its integrated glass-melting and weaving assets to secure long-term supply agreements with wind blade builders across North America. SAERTEX GmbH & Co. KG anchors European demand through specialized heavy-tow multiaxial fabrics optimized for vacuum infusion processes. China Jushi Co., Ltd. dominates cost-competitive roving and woven output, extending its reach through captive logistics networks serving Asian laminate producers.
Fiberglass fabric consists of woven or non-woven textile structures manufactured from drawn glass filaments, typically formulated with E-glass or S-glass compositions and sized with silane coupling agents to ensure resin adhesion during composite fabrication. These fabrics function as structural reinforcement media within polymer matrices, delivering tensile strength, dimensional stability, and corrosion resistance to finished laminates. Woven fabric retains the largest volume position across product categories, though non-woven mat formats are gaining ground in automated spray-up and compression-molding operations where labor reduction drives conversion. Composites applications command the deepest margin pools among end-use categories, while insulation and electrical segments sustain steadier but lower-growth demand trajectories tied to building codes and infrastructure replacement cycles.
The U.S. EPA and OSHA impose workplace exposure limits on respirable glass fiber dust, shaping personal protective equipment mandates and factory ventilation investments for domestic weavers and converters. REACH registration requirements and the EU Green Deal carbon-border adjustment mechanisms constrain imported fabric competitiveness into European markets, favoring local producers with verified lifecycle assessments. Stakeholders must monitor evolving chemical hazard classifications from ECHA and corresponding downstream liability exposure as bio-based resin alternatives alter compatibility requirements for traditional glass sizings.
Market Dynamics
Wind turbine blade scaling above 100-meter lengths is compressing supply timelines for heavy-weight woven reinforcements, forcing fabricators to reconfigure loom capacity and resin compatibility testing protocols.
Growth Catalysts
- EU Green Deal carbon-border adjustments:Domestic European weavers with verified lifecycle assessments gain cost advantage over imported fabric, accelerating local capacity expansion for vacuum infusion-grade materials.
- China wind park buildout:Provincial renewable energy targets in Jiangsu and Guangdong are absorbing record volumes of E-glass roving and multiaxial fabric from integrated domestic suppliers.
- Automated spray-up systems:Non-woven mat formats compatible with robotic deposition are displacing hand-layup woven goods in high-volume automotive panel production.
Market Restraints
- Boron and fluorine feedstock volatility:S-glass formulations depend on concentrated mineral supply from Turkey and the United States, exposing margin stability to extraction quota fluctuations.
- REACH chemical registration burdens:ECHA hazard reclassifications for silane coupling agents are extending compliance timelines for imported fabric into European composite shops.
- Carbon fiber substitution in aerospace:Pressure vessel and satellite structure manufacturers are migrating toward T800-grade carbon prepreg for weight-critical applications above 80°C service temperatures.
Strategic Opportunities
- India PLI scheme for advanced materials:Domestic weaving capacity for wind and electric vehicle battery enclosure fabric remains underdeveloped, creating first-mover positioning for technical textile investors.
- Recyclable thermoplastic resins:Polypropylene and PBT matrices compatible with glass sizing chemistry are enabling closed-loop blade decommissioning protocols demanded by extended producer responsibility frameworks.
- Mill-direct procurement channels:Turbine original equipment manufacturers are bypassing legacy distributors to negotiate long-term offtake agreements with integrated glass-melting and weaving operations.
Industry Challenges
- Vacuum infusion technician scarcity:Composite shops report 18-month training cycles for operators capable of managing permeability variation in heavy-tow multiaxial stacks.
- Dual certification timelines:Fabricators seeking DNV GL and TÜV Rheinland blade material approvals face parallel testing protocols that compress product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiberglass Fabric Market |
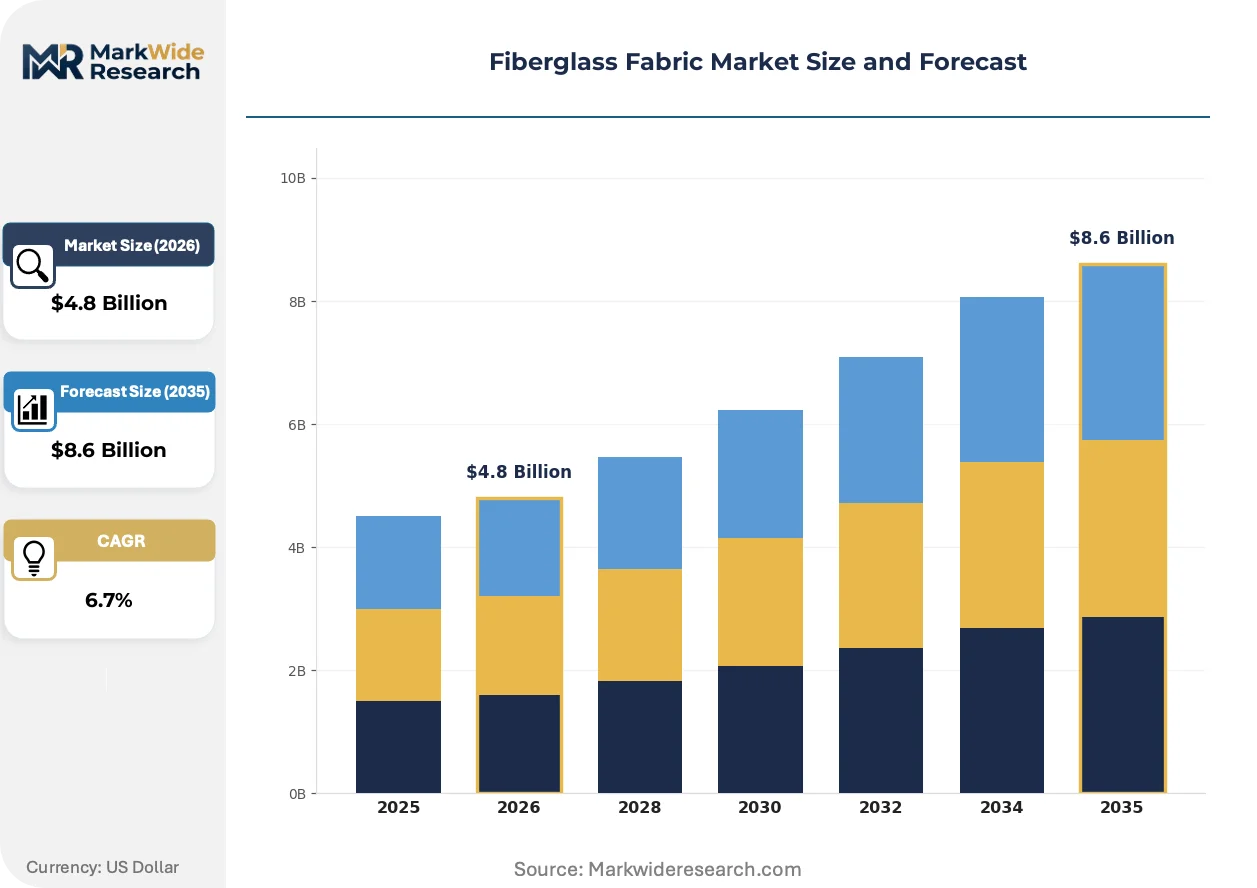
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woven Fabric, Non-Woven Fabric, Mat, Roving End User: Aerospace, Construction, Marine, Automotive Application: Insulation, Composites, Reinforcement, Electrical Technology: Filament Winding, Pultrusion, Hand Layup, Spray Up |
| Companies Covered | Hexcel Corporation, SAERTEX GmbH & Co. KG, Owens Corning, BGF Industries, Chomarat Textile Industries, China Jushi Co., Ltd., Johns Manville, Chongqing Polycomp International (CPIC), Saint-Gobain Vetrotex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiberglass Fabric Market Emerging Trajectories
Process automation and resin chemistry convergence are compressing the traditional segmentation between woven structural reinforcements and non-woven deposition formats.
Thermoplastic-compatible glass sizing chemistry is rendering obsolete the thermal stability limitations of conventional epoxy-optimized fabrics. Wind blade manufacturers in Denmark and Spain are qualifying polyamide and polypropylene matrix systems for root-insert and shear-web applications. The shift eliminates autoclave curing requirements and enables welded joint repair protocols that extend blade service intervals.
REACH registration requirements and the EU Green Deal carbon-border adjustment mechanisms are tightening chemical content documentation for imported reinforcements. European laminate producers are demanding third-party verified lifecycle assessments from Turkish and Egyptian weaving operations to avoid tariff exposure. The compliance burden favors integrated suppliers with captive glass-melting and in-house silane formulation capabilities.
Direct mill procurement is displacing distributor-mediated supply relationships across North American wind supply chains. Vestas and Siemens Gamesa turbine divisions are negotiating volume commitments with Owens Corning and SAERTEX manufacturing sites, compressing working capital cycles for regional composite converters. The channel shift concentrates price negotiation leverage with original equipment manufacturers and erodes margin pools for independent fabric distributors.
Fiberglass Fabric Market Segmentation
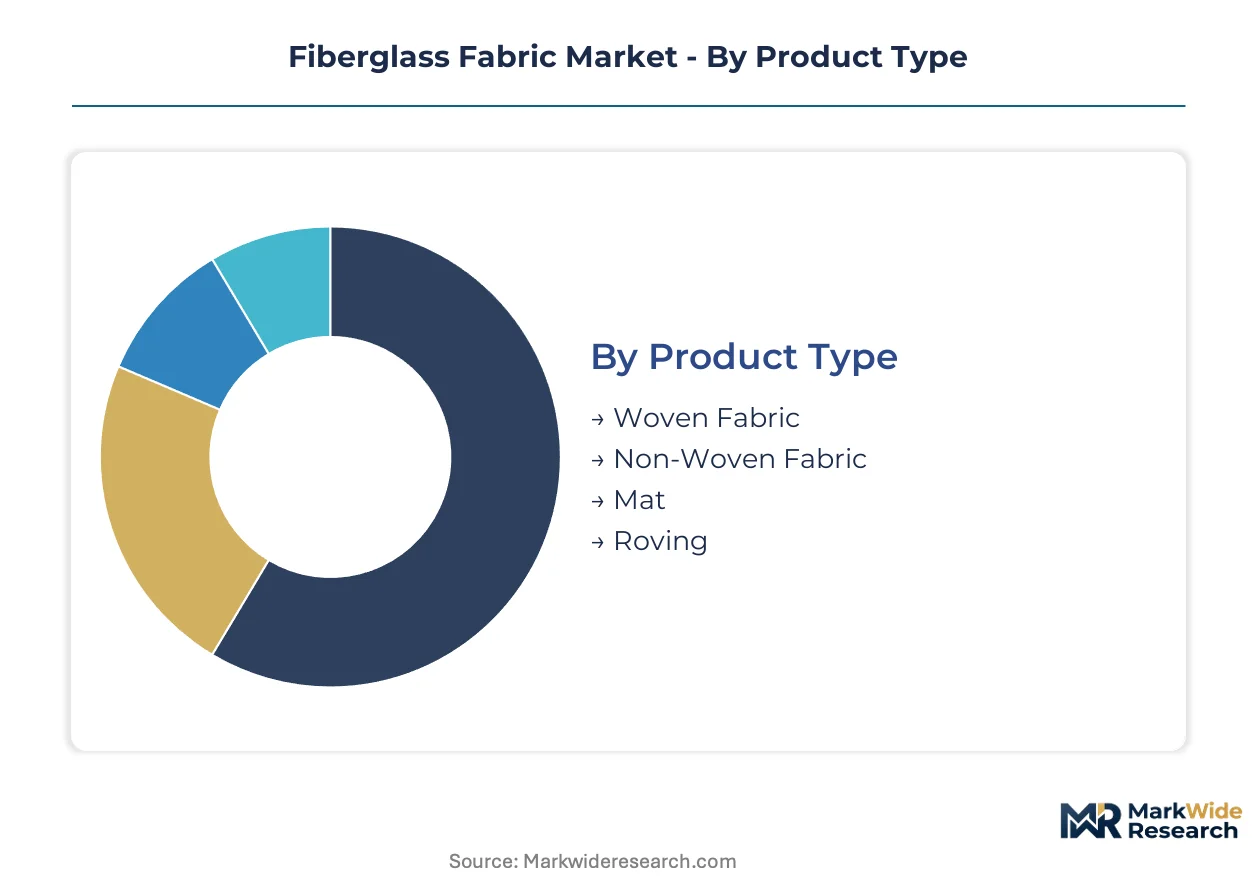
Fiberglass fabric segmentation reveals divergent margin profiles across manufacturing technologies and end-use specifications. Technical support intensity varies dramatically between aerospace certification requirements and construction commodity supply.
Product Type:
After-sales service intensity escalates with fabric complexity, as woven multiaxial grades require resin compatibility troubleshooting while non-woven mats demand minimal technical intervention.
- Woven Fabric:Interlaced E-glass or S-glass filaments in plain, twill, or satin weaves deliver controlled drape and structural precision. Wind blade manufacturers in Denmark and China specify heavy-tow multiaxial weaves for root sections exceeding 100-meter blade lengths, though loom reconfiguration for custom widths extends lead times.
- Non-Woven Fabric:Chopped strand or continuous filament mats bonded with powder or emulsion binders enable rapid deposition in automated spray-up systems. Automotive panel producers in Michigan and Bavaria favor non-woven formats for compression-molding cycle time reduction.
- Mat:Randomly oriented glass strands held by chemical binders serve surfacing and corrosion barrier layers.
- Roving:Untwisted bundles of parallel filaments feed filament winding and pultrusion processes for pipe and profile manufacturing.
By volume, roving leads due to wind energy absorption. By growth pace, non-woven fabric is ahead on automotive automation demand.
End User:
Cost tier stratification separates aerospace qualification premiums from construction commodity pricing, with marine and automotive occupying intermediate positions.
- Aerospace:S-glass and specialized E-glass fabrics meeting flame-smoke-toxicity specifications command stringent lot traceability. Pressure vessel manufacturers in France and California face carbon fiber substitution above 80°C service thresholds.
- Construction:E-glass mesh and scrim reinforce exterior insulation finish systems and gypsum board joints. Building code adoption in Texas and Florida drives specification volume despite thinner margin pools.
- Marine:Vacuum infusion-grade biaxial fabrics serve hull and deck laminates for recreational boat builders in Maine and Queensland.
- Automotive:Lightweight underbody shields and battery enclosure panels absorb thermoplastic-compatible glass mat from Tier 1 suppliers in Stuttgart and Shanghai.
Construction dominates shipment volume. Aerospace maintains the steepest expansion trajectory on satellite structure qualification programs.
Application:
Customer type concentration splits between specification-driven composite engineers and price-sensitive insulation contractors.
- Composites:Structural laminates in wind blades, automotive panels, and marine hulls generate the deepest margin pools through resin system integration. Vestas and Siemens Gamesa turbine divisions negotiate mill-direct offtake agreements bypassing distributors.
- Insulation:Thermal and acoustic batts for residential and commercial building envelopes sustain steadier demand tied to replacement cycles and energy code updates.
- Reinforcement:Geogrids and asphalt overlays utilize coated glass fabrics for infrastructure durability.
- Electrical:Laminates for printed circuit boards and transformer insulation require controlled dielectric properties.
Composites captures the largest revenue share. Insulation provides the most predictable demand baseline across economic cycles.
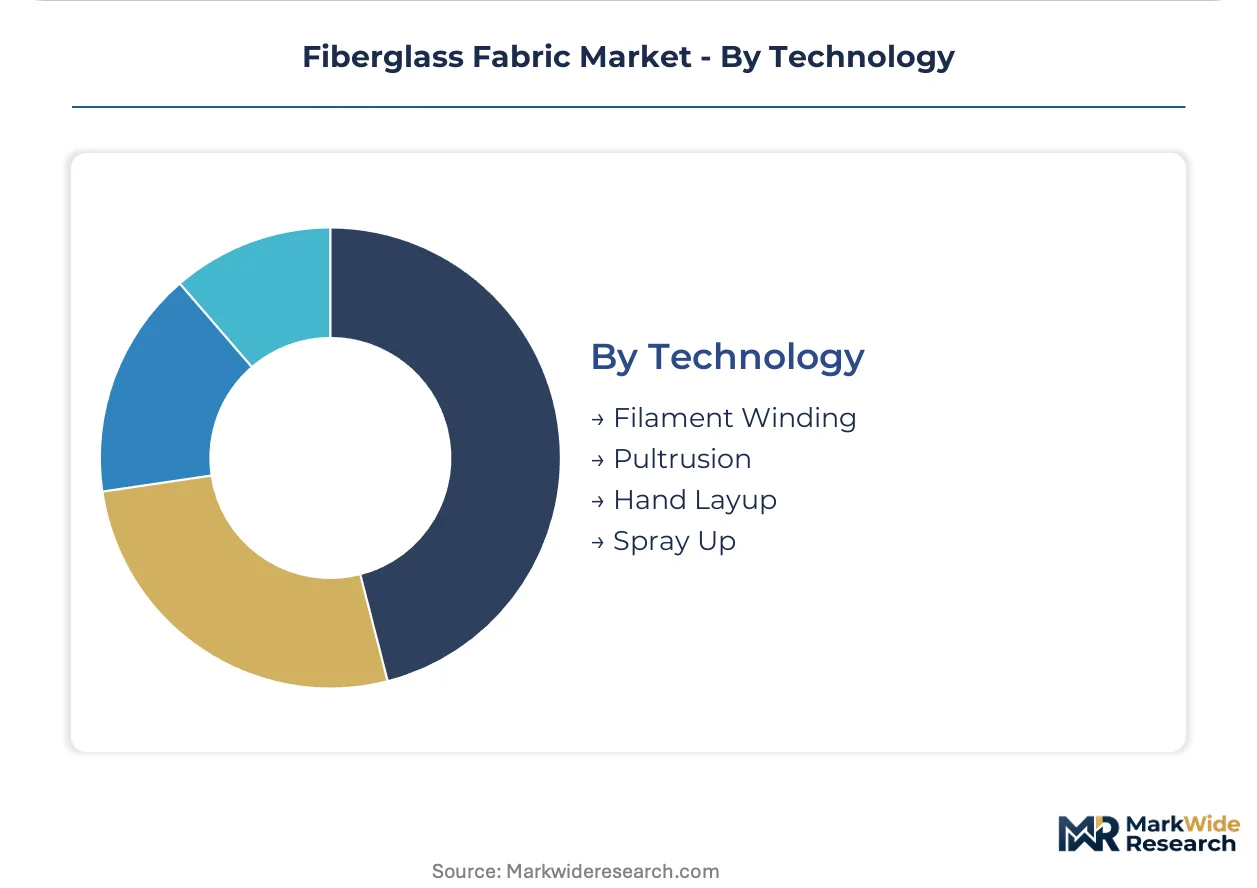
Technology:
Supply concentration favors integrated producers with captive glass-melting and in-house sizing formulation capabilities.
- Filament Winding:Automated fiber placement onto rotating mandrels produces pressure vessels and pipe with precise fiber angle control. CNG tank manufacturers in Germany and South Korea specify S-glass roving for burst strength requirements.
- Pultrusion:Continuous pulling of resin-impregnated roving through heated dies yields structural profiles with consistent cross-sections. Bridge deck and grating producers in Ohio and Ontario favor pultruded glass shapes for corrosion resistance.
- Hand Layup:Manual placement of woven or chopped fabric into open molds persists in custom marine and architectural applications.
- Spray Up:Chopped roving and resin simultaneous deposition suits large marine moldings and tub/shower enclosures.
Filament winding leads on growth momentum from hydrogen storage vessel demand. Hand layup retains volume in legacy boat building clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese weavers extract 15-20% pricing premiums over Turkish exporters into European wind supply chains, while U.S. domestic producers command equivalent spreads over Asian imports under EPA and OSHA compliance cost differentials.
China
Jiangsu and Guangdong provincial wind park targets absorb record E-glass roving and multiaxial fabric volumes from integrated domestic suppliers. MIIT dual carbon goals and GB standards on composite recycling are tightening material traceability requirements for blade exports. Yangtze River Delta weaving clusters around Shanghai are expanding vacuum infusion-grade capacity to serve both local turbine builders and export-oriented laminate producers.
United States
Texas and Iowa wind corridor expansions are pulling heavy-weight woven reinforcements through mill-direct channels bypassing legacy distributors. EPA workplace exposure limits on respirable glass fiber dust are shaping PPE mandates and ventilation investments for domestic weavers. Ohio and Indiana composite conversion clusters report 18-month technician training cycles for vacuum infusion operators managing permeability in heavy-tow stacks.
Germany
DNV GL and TÜV Rheinland dual certification timelines are compressing product launch windows for blade material suppliers into North Sea offshore projects. REACH registration requirements and EU Green Deal carbon-border adjustments favor domestic weavers with verified lifecycle assessments over Turkish imports. Bavarian automotive panel producers are qualifying thermoplastic-compatible glass mat from regional suppliers for battery enclosure applications.
Denmark
Vestas turbine divisions are negotiating long-term offtake agreements with integrated glass-melting operations, eroding margin pools for independent fabric distributors. ECHA hazard reclassifications for silane coupling agents are extending compliance timelines for imported fabric into European composite shops. Copenhagen-area blade engineering centers are qualifying polyamide and polypropylene matrix systems for root-insert and shear-web applications.
India
PLI scheme incentives for advanced materials are attracting technical textile investors into underdeveloped domestic weaving capacity for wind and electric vehicle battery enclosure fabric. CEA renewable purchase obligations are driving provincial solar-wind hybrid park announcements in Gujarat and Tamil Nadu. Maharashtra laminate producers report sourcing friction as imported fabric faces DGFT documentation requirements and BIS standard alignment delays.
Fiberglass Fabric Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in raw material and intermediate processing layers. The vendor base stratifies across three tiers: integrated glass-melting and weaving operations with captive sizing chemistry, regional composite converters dependent on external fabric supply, and specialized distributors facing margin compression from mill-direct procurement shifts. Two dominant competitive moves are reshaping positioning: backward integration into glass-melting assets by downstream turbine builders, and geographic expansion through joint ventures to bypass carbon-border tariff exposure.
Among integrated global suppliers, Owens Corning exemplifies the North American platform archetype with captive glass-melting and weaving assets securing long-term wind blade agreements. SAERTEX GmbH & Co. KG anchors European demand through specialized heavy-tow multiaxial fabric capabilities. China Jushi Co., Ltd. occupies the cost-competitive volume position, extending reach through captive logistics networks serving Asian laminate producers.
| Leading Market Players |
|---|
| Hexcel Corporation |
| SAERTEX GmbH & Co. KG |
| Owens Corning |
| BGF Industries |
| Chomarat Textile Industries |
| China Jushi Co., Ltd. |
| Johns Manville |
| Chongqing Polycomp International (CPIC) |
| Saint-Gobain Vetrotex |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta weaving clusters around Shanghai anchor global heavy-tow multiaxial capacity, concentrating pricing leverage among integrated glass-melting operations that negotiate mill-direct offtake agreements with Vestas and Siemens Gamesa turbine divisions.
Pricing Analysis
Configured-to-order pricing for custom-width vacuum infusion-grade fabrics commands substantial premiums over standard-width commodity weaves. Three-tier pricing structure across aerospace qualification, wind blade structural, and construction commodity levels reflects certification intensity and lot traceability requirements. Cost compression in standard E-glass roving intensifies because Turkish and Egyptian weavers face EU Green Deal carbon-border exposure. Construction insulation contractors exhibit the highest price sensitivity, while aerospace pressure vessel manufacturers absorb premium spreads for S-glass flame-smoke-toxicity compliance.
Supply Chain Analysis
Extended payment terms from turbine original equipment manufacturers are reshaping working capital structures for regional composite converters. Supply concentrates in China, Turkey, and Germany, with boron and fluorine feedstock for S-glass formulations drawing from concentrated mineral deposits in Turkey and the United States. Single-source vulnerability runs through silane coupling agent supply chains facing ECHA hazard reclassification timelines. Distribution runs through mill-direct procurement channels that bypass legacy fabric distributors across North American and European wind supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified vacuum infusion technicians capable of managing permeability variation in heavy-tow multiaxial stacks represent the critical capability gap compressing product launch windows for blade material suppliers.
For Market Incumbents: Entrench market position through captive sizing chemistry R&D and DNV GL certification pre-positioning before TÜV Rheinland dual protocols extend compliance timelines. Carbon fiber substitution above 80°C service thresholds in aerospace pressure vessels demands defensive S-glass cost reduction through backward integration into boron mineral sourcing. For New Entrants and Emerging Players: Underdeveloped domestic weaving capacity for wind and electric vehicle battery enclosure fabric in India represents the most penetrable entry point for technical textile investors. Gujarat and Tamil Nadu provincial solar-wind hybrid park announcements create immediate demand anchors. A joint venture with established glass-melting operations accelerates BIS standard alignment and DGFT documentation compliance. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underutilized heavy-tow multiaxial loom capacity and stranded silane formulation expertise. Long-term viability hinges on thermoplastic-compatible glass sizing chemistry positioning for recyclable blade decommissioning protocols. Watch ECHA hazard reclassification timelines for silane coupling agents as the inflection signal for downstream liability exposure shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glass-Melting Assets | Owens Corning and China Jushi secure captive borosilicate supply against Turkish mineral quota volatility. |
| Long-term Supply Agreement with Turbine OEMs | SAERTEX anchors North Sea offshore demand through Vestas mill-direct volume commitments. |
| Joint Venture for Regional Capacity | European weavers bypass EU Green Deal carbon-border exposure through Turkish-Egyptian manufacturing partnerships. |
| Thermoplastic Sizing Chemistry R&D | Danish blade engineering centers qualify polyamide matrix systems for welded joint repair protocols. |
| Dual Certification Pre-positioning | Material suppliers compress DNV GL and TÜV Rheinland parallel testing timelines for offshore blade contracts. |
Methodological Framework
A spread of perspectives from composite shop technicians, wind blade procurement directors, glass-melting plant managers, and ECHA regulatory affairs specialists converged on the working assumptions. Primary interviews with vacuum infusion operators and turbine OEM supply chain leads combined with secondary validation from customs trade data, SEC 10-K filings from integrated suppliers, ACC composite industry reports, and REACH registration databases. Bottom-up volume estimates from loom capacity utilization triangulated against top-down wind installation forecasts.
Demand-supply balance modeling across the analysis window segmented by fabric format, resin compatibility tier, end-use qualification level, and regional production hub concentration. CAGRs derived from weighted average of historical capacity expansion rates and announced turbine blade scaling programs. Boron mineral extraction quotas and ECHA silane reclassification timelines fed scenario-adjusted forecast ranges.
Macroeconomic conditions sit as an overlay; deviation in renewable energy subsidy regimes, carbon-border tariff implementation schedules, or S-glass feedstock extraction quotas would shift the trajectory. Forecasts reflect documented assumptions on technician training cycle completion and dual certification timeline compression. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Canvas Roll Market
Yarn and Fabric Manufacturing
Europe Textile Market
Yarn and Fabric Manufacturing
E-Glass Fiber Yarn and Roving Market
Yarn and Fabric Manufacturing
Knitting Cam Market
Yarn and Fabric Manufacturing
Italy Textile Manufacturing Market
Yarn and Fabric Manufacturing
Wool Worsted Yarn Market
Yarn and Fabric Manufacturing
South America Cotton Market
Yarn and Fabric Manufacturing
Mesh Fabric Market
Yarn and Fabric Manufacturing
Nylon 6 Filament Yarn Market
Yarn and Fabric Manufacturing
Felt Bobs Market
Yarn and Fabric Manufacturing
Asia Pacific Cotton Market
Yarn and Fabric Manufacturing
Wool Market
Yarn and Fabric Manufacturing
Global Textile Yarn Market
Yarn and Fabric Manufacturing
Mercerized Cotton Market
Yarn and Fabric Manufacturing
Silk Yarn Market
Yarn and Fabric Manufacturing
Polypropylene Yarn Market