
 Sewing Thread Market | 2026-2036
Sewing Thread Market Size, Share, and Industry Trends Forecast 2026-2036
Sewing Thread Market Insights
Aftermarket technical support revenue is narrowing as a margin pool as original thread suppliers consolidate repair-kit and color-matching services into direct digital platforms. Coats Group PLC leverages its industrial thread database to sustain aftermarket lock-in across automotive seating programs. AMANN & Söhne GmbH & Co KG anchors premium positioning through specialized high-tenacity threads for safety-critical applications. Vardhman Yarns & Threads Ltd. competes on polyester scale, dominating volume supply to South Asian apparel exporters.
Sewing thread comprises engineered continuous filaments or spun staple fibers, typically measured in ticket numbers or denier, twisted and finished with lubricants to achieve specified breaking strength and abrasion resistance for seam integrity in assembled goods. Polyester thread leads industrial end-use due to superior chemical resistance and dimensional stability under cyclic loading, while cotton retains share in heritage apparel and medical textile segments where breathability and sterilization compatibility matter. Thread size 40 occupies the highest volume position across apparel and upholstery applications, whereas reflective color types are gaining fastest in workwear and automotive safety applications where visibility standards tighten.
REACH chemical restrictions in Europe and OEKO-TEX Standard 100 certification requirements constrain dyestuff formulations and finishing chemistries, pushing suppliers to reformulate or forfeit market access in regulated jurisdictions. BIS quality mandates in India and GB standards in China add compliance layers for imported thread, fragmenting certification portfolios. Stakeholders must monitor how chemical disclosure rules and recycled-content mandates reshape raw-material sourcing decisions and supplier qualification timelines.
Market Dynamics
REACH chemical restrictions and OEKO-TEX certification mandates are forcing thread suppliers to reformulate dye chemistries and rebuild supplier qualification pipelines, compressing margins for non-compliant producers while locking in certified market access for early movers.
Growth Catalysts
- Electric vehicle upholstery programs:Automotive manufacturers in Germany and Italy are expanding thread procurement for EV interior seating and trim applications, creating dedicated supply contracts for high-tenacity polyester lines.
- REACH compliance redirection:European chemical disclosure rules are redirecting sourcing toward certified polyester and recycled nylon thread lines that meet restricted substance thresholds.
- Apparel manufacturing relocation:Bangladesh and Vietnam are absorbing sewing thread volume previously routed through China-based suppliers, concentrating demand in South Asian logistics corridors.
Market Restraints
- Petrochemical feedstock volatility:Polyester thread production faces margin compression from fluctuating PTA and MEG input costs tied to crude oil price cycles.
- Supply concentration in staple fiber:Spun cotton thread sourcing clusters in specific ginning and spinning regions, creating geographic vulnerability to climate and trade disruptions.
- Technical limitation in recycled nylon:Post-industrial recycled nylon 6,6 exhibits inconsistent tenacity and dye uptake compared to virgin polymer, restricting adoption in safety-critical automotive and medical applications.
Strategic Opportunities
- Reflective thread penetration in workwear:High-visibility safety standards in European industrial apparel are opening demand for retroreflective sewing threads in flame-resistant garments.
- Digital color-matching platforms:Thread suppliers can capture aftermarket repair-kit revenue by deploying spectrophotometer-linked direct-to-manufacturer color libraries, bypassing distributor color card delays.
- EU Green Deal recycled content mandates:Proposed textile sector circularity requirements will create preferential market access for thread lines with verified post-consumer recycled content certification.
Industry Challenges
- Dyestuff chemist talent scarcity:Formulating REACH-compliant reactive dyes with equivalent fastness properties requires specialized color chemistry expertise that suppliers struggle to recruit.
- Multi-standard certification timelines:Simultaneous pursuit of OEKO-TEX Standard 100, GOTS, and ZDHC MRSL compliance extends product qualification cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sewing Thread Market |
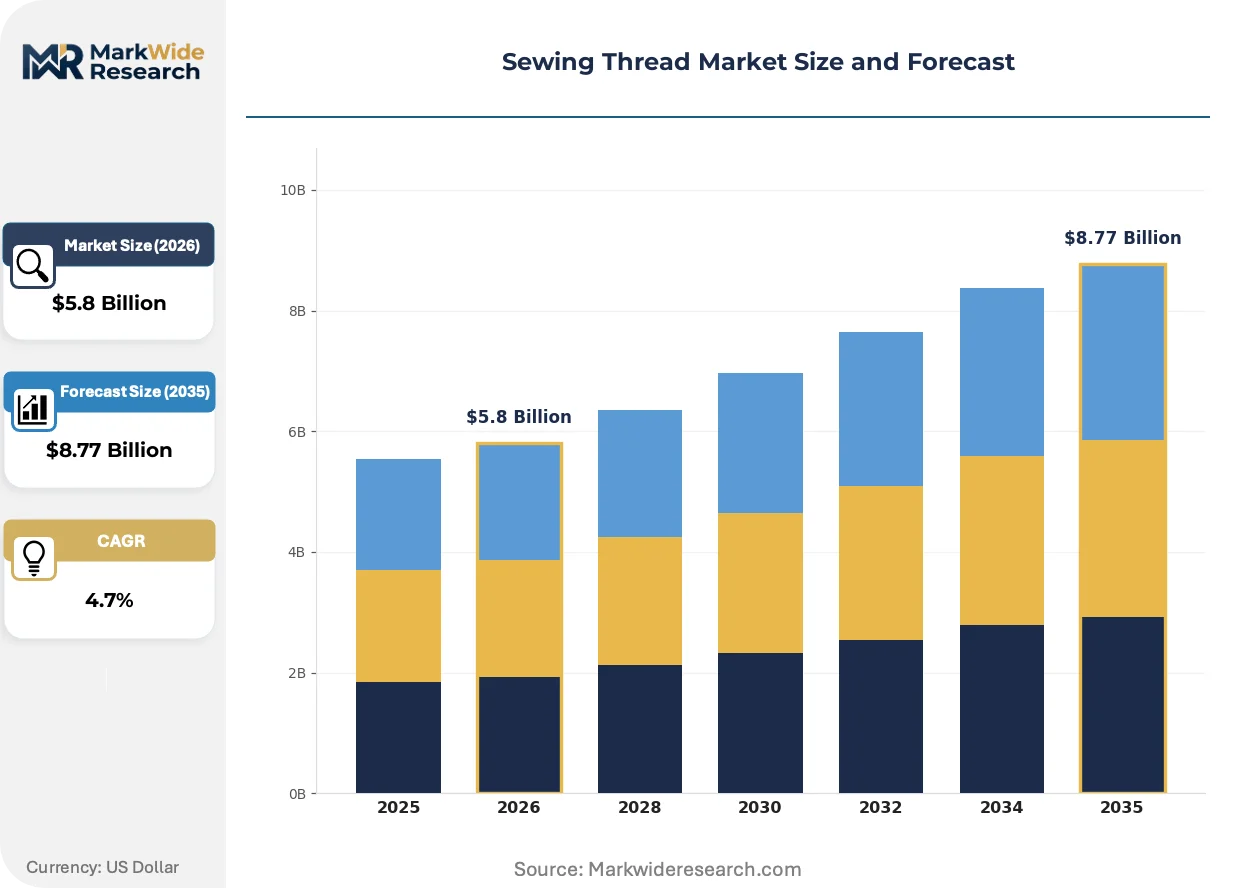
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.77 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cotton, Polyester, Nylon, Silk Thread Size: 30, 40, 60, 80 End Use: Apparel, Upholstery, Automotive, Industrial Color Type: Solid, Variegated, Fluorescent, Reflective |
| Companies Covered | FUJIX Ltd., AURIFIL Srl, Coats Group PLC, Durak Tekstil San. Ve Tic. A.Ş., Vardhman Yarns & Threads Ltd., American & Efird LLC, Gunze Limited, Ningbo MH Industry Co., Ltd., AMANN & Söhne GmbH & Co KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sewing Thread Market Trends and Innovations
Thread engineering is pivoting from commodity spun staples toward functional continuous filaments with embedded performance properties, while regulatory chemistry disclosure and digital procurement infrastructure reshape how specifications travel from brand to mill.
High-tenacity continuous filament polyester is migrating from conventional apparel seams into automotive safety applications where seam integrity under cyclic loading determines airbag deployment reliability. Tier-1 seating suppliers in Stuttgart and Turin are qualifying these threads for 15-year durability specifications. The shift is compressing demand for lower-tenacity spun polyester in premium upholstery segments.
REACH Annex XVII restrictions on azo dyes and heavy metal formulations are forcing European thread finishers to reformulate lubricant packages and pigment dispersions. Dyers in Portugal and Romania are investing in effluent-free supercritical CO2 dyeing systems to eliminate water-treatment compliance risks. The regulatory pressure is accelerating consolidation among small Italian thread finishers unable to absorb reformulation R&D costs.
Automotive OEMs are unbundling thread specification authority from tiered seating suppliers, issuing direct material approvals to thread manufacturers based on proprietary durability databases. This disintermediation concentrates volume with industrial thread specialists capable of maintaining lot-traceable technical files. The pattern is most visible in German premium vehicle programs where seating suppliers now procure against OEM-mandated thread tickets rather than self-specifying.
Sewing Thread Market Segmentation
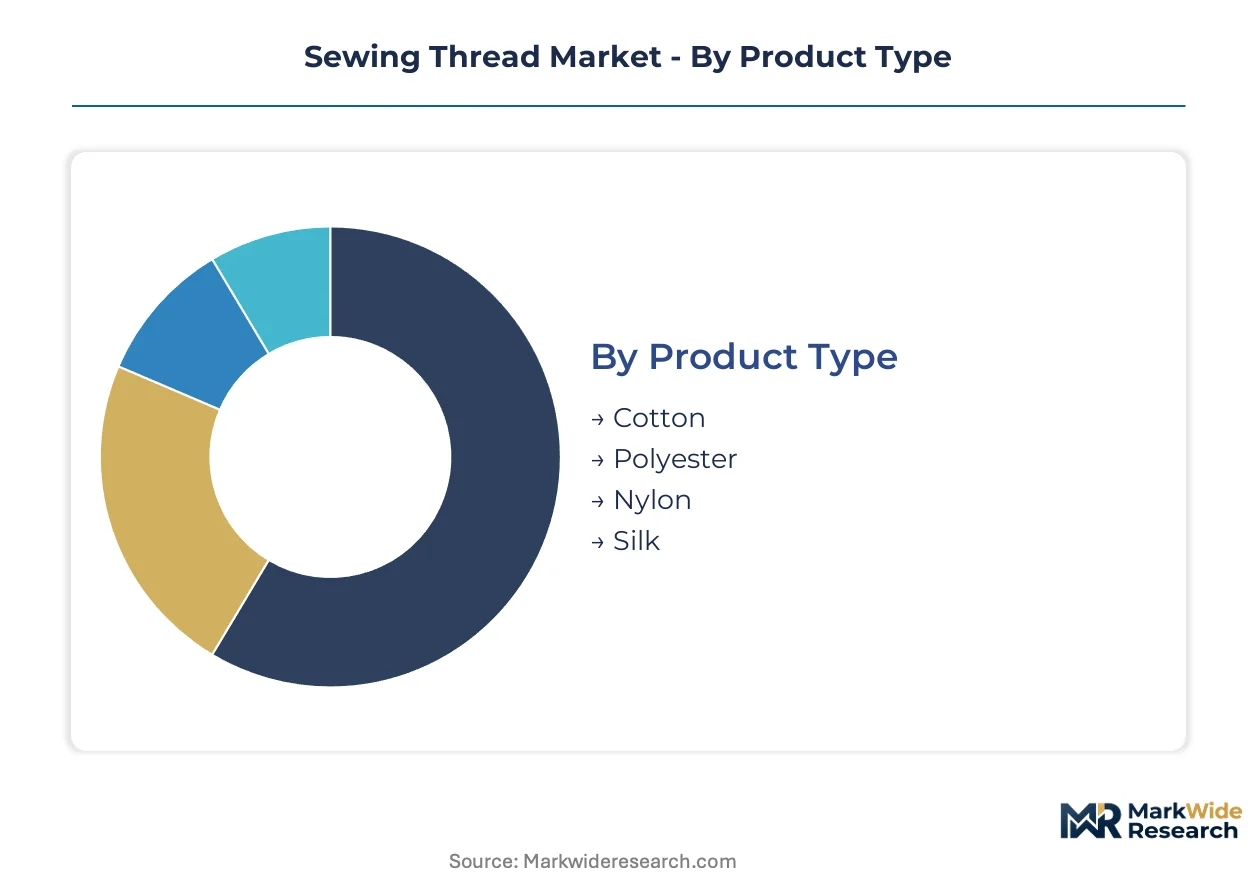
Segmentation in the sewing thread market reveals how technical specifications, regulatory compliance, and end-use durability requirements fragment procurement patterns. Thread selection directly determines seam integrity in safety-critical applications while color chemistry choices lock suppliers into specific certification portfolios.
Product Type:
Polyester thread turns inventory fastest in high-volume apparel supply chains, while cotton and silk rotate more slowly through heritage and luxury channels. Nylon occupies the middle ground with specialized industrial offtake.
- Polyester:Continuous filament construction delivers superior chemical resistance and dimensional stability under cyclic loading. Demand concentrates in Bangladesh and Vietnam apparel export corridors where OEKO-TEX certification requirements redirect sourcing toward certified polyester lines from European finishers.
- Nylon:High-tenacity continuous filaments achieve breaking strengths essential for automotive safety applications. German and Italian electric vehicle upholstery programs are expanding procurement of recycled nylon thread lines, though post-industrial recycled grades exhibit inconsistent tenacity compared to virgin polymer.
- Cotton:Spun staple construction from specific ginning regions retains share in heritage apparel and medical textiles where breathability and sterilization compatibility matter. Geographic concentration in cotton belt regions creates climate vulnerability.
- Silk:Luxury apparel and high-end embroidery applications in European fashion houses sustain niche demand with extended production cycles and premium pricing tiers.
Polyester anchors the volume base while nylon gains share at the steepest rate.
Thread Size:
Cost tiers separate commodity apparel specifications from premium automotive and industrial grades, with finer counts commanding specialized finishing chemistries.
- Size 40:The highest volume position across apparel and upholstery applications balances seam strength with needle penetration efficiency. Bangladesh garment exporters specify size 40 as the default standard for woven and knit assembly.
- Size 30:Heavy-duty construction for denim, canvas, and industrial webbing requires thicker filaments and specialized lubricant packages. REACH-compliant finishing chemistries add cost premiums for European-sourced size 30 lines.
- Size 60:Fine-count precision for lightweight fabrics and detailed embroidery work in Italian and Portuguese textile finishing houses.
- Size 80:Micro-filament specifications for sheer fabrics and technical medical textiles where minimal seam visibility matters.
Size 40 dominates procurement volumes while size 30 commands the widest margin spread.
End Use:
Application-specific durability standards create distinct qualification timelines, with automotive programs requiring 15-year traceable technical files against apparel's seasonal turnover.
- Apparel:Seasonal fashion cycles drive rapid thread specification changes with OEKO-TEX Standard 100 certification as baseline entry requirement. Vietnam and Bangladesh absorption of volume previously routed through China-based suppliers is concentrating demand in South Asian logistics corridors.
- Automotive:Airbag deployment reliability and 15-year durability specifications in German premium vehicle programs require high-tenacity continuous filament polyester with lot-traceable technical files. OEMs are unbundling specification authority from tiered seating suppliers.
- Upholstery:Residential and contract furniture applications balance abrasion resistance with color fastness requirements under REACH Annex XVII dye restrictions.
- Industrial:Safety harnesses, lifting slings, and filtration media demand engineered tenacity grades with specialized finishing for UV and chemical exposure.
Apparel anchors the volume base while automotive gains share at the steepest rate.
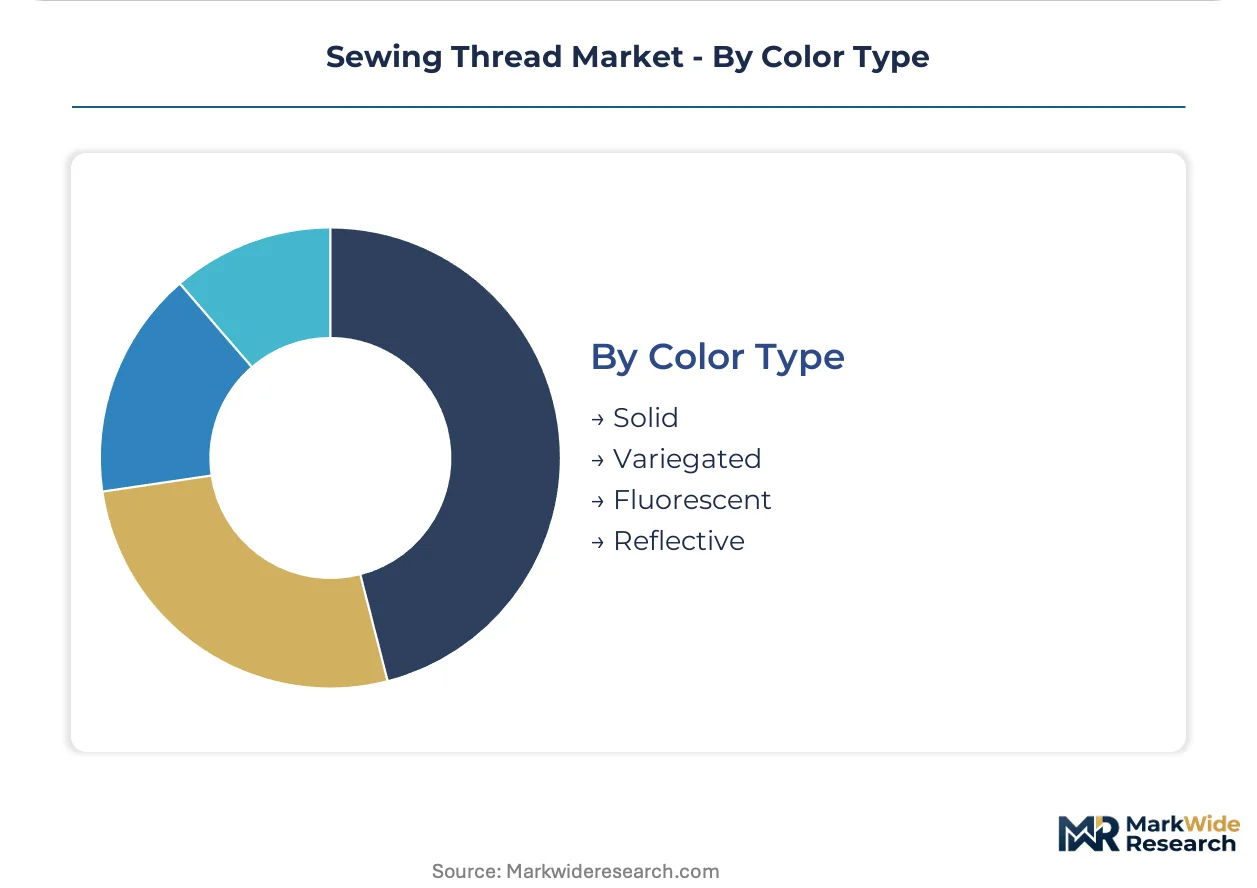
Color Type:
Margin structures diverge sharply between commodity solid dyeing and functional reflective or fluorescent finishes requiring specialized pigment dispersions.
- Solid:Conventional reactive dyeing dominates volume production with REACH-compliant formulations now mandatory for European market access. Portuguese and Romanian finishers are investing in effluent-free supercritical CO2 dyeing systems.
- Reflective:Retroreflective glass bead or prismatic film integration meets tightening high-visibility safety standards in European industrial apparel and automotive safety applications. Fastest-expanding segment as visibility regulations tighten.
- Fluorescent:Daylight-visible pigments for safety workwear and emergency services textiles with restricted substance thresholds under EU chemical regulations.
- Variegated:Multi-tone effects for decorative and craft applications with slower inventory turnover and artisan production scales.
Solid color anchors the volume base while reflective gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies, with European automotive programs demanding 15-year durability specifications while South Asian apparel corridors prioritize OEKO-TEX certified volume turnover.
Germany
Stuttgart and Munich automotive clusters drive procurement of high-tenacity continuous filament polyester for electric vehicle upholstery programs. ECHA REACH Annex XVII restrictions on azo dyes force thread finishers to reformulate lubricant packages and pigment dispersions. Bavarian and Baden-Württemberg seating suppliers now procure against OEM-mandated thread tickets rather than self-specifying.
China
GB standards compliance and dual carbon goals redirect domestic thread sourcing toward certified recycled content lines. Ningbo and Guangdong textile finishing houses face margin pressure from MEE environmental enforcement on dye house effluent. Yangtze River Delta apparel manufacturers are losing volume share to Bangladesh and Vietnam as brands diversify supply chains.
Vietnam
Ho Chi Minh City and Hanoi garment export corridors absorb sewing thread volume previously routed through China-based suppliers. OEKO-TEX Standard 100 certification serves as baseline entry requirement for European brand contracts. Da Nang and Binh Duong industrial zones concentrate new thread warehousing capacity to serve just-in-time apparel assembly.
United States
EPA chemical disclosure rules and state-level PFAS restrictions constrain finishing chemistry imports from non-compliant overseas suppliers. North Carolina and Georgia textile clusters sustain heritage cotton thread demand for medical textiles where sterilization compatibility matters. OSHA high-visibility safety standards open reflective thread penetration in industrial workwear segments.
India
BIS quality mandates add compliance layers for imported thread, fragmenting certification portfolios for domestic finishers. Ludhiana and Tiruppur apparel manufacturing belts drive polyester thread volume for export-oriented garment assembly. Maharashtra and Gujarat spinning mills expand capacity to capture thread demand relocating from China-based suppliers.
Sewing Thread Market Competitive Landscape
Capability concentration sits with industrial thread specialists maintaining lot-traceable technical files for automotive safety applications; scale advantage sits with volume polyester suppliers serving South Asian apparel corridors. The vendor base organizes around three archetypes: European premium specialists with REACH-compliant finishing infrastructure, Asian scale players dominating certified polyester volume, and regional mid-tier operators serving heritage cotton niches. Consolidation pressure concentrates among small Italian finishers unable to absorb reformulation R&D costs, while tier-1 seating suppliers unbundle specification authority to deal directly with thread manufacturers.
Within the premium industrial tier, AMANN & Söhne GmbH & Co KG and Coats Group PLC exemplify European specialists anchoring high-tenacity safety-critical applications. Vardhman Yarns & Threads Ltd. occupies a scale-driven position serving South Asian apparel export corridors with certified polyester volume. These three represent the capability-scale spectrum: German GmbH-structured precision engineering, UK PLC industrial database lock-in, and Indian Ltd. volume dominance in Bangladesh and Vietnam logistics corridors.
| Leading Market Players |
|---|
| FUJIX Ltd. |
| AURIFIL Srl |
| Coats Group PLC |
| Durak Tekstil San. Ve Tic. A.Ş. |
| Vardhman Yarns & Threads Ltd. |
| American & Efird LLC |
| Gunze Limited |
| Ningbo MH Industry Co., Ltd. |
| AMANN & Söhne GmbH & Co KG |
| Others |
Pricing and Supply Chain Analysis
Petrochemical feedstock volatility between PTA and MEG pricing cycles determines both margin compression across polyester thread tiers and the geographic relocation of finishing capacity toward integrated spinning corridors in Vietnam and Bangladesh.
Pricing Analysis
Long-term offtake contracts dominate automotive upholstery programs where German OEMs lock in 15-year supply agreements for high-tenacity continuous filament polyester. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified European finishers from OEKO-TEX baseline suppliers and uncertified commodity spinners. Cost compression in standard-grade polyester intensifies because Bangladesh garment exporters consolidate procurement volume and squeeze distributor margins. Apparel assemblers exhibit highest price sensitivity while automotive seating engineers prioritize lot-traceable technical files over unit cost.
Supply Chain Analysis
Tariff exposure between China and destination markets in North America and Europe dominates supply chain restructuring decisions across the thread industry. Raw material sourcing concentrates in China for purified terephthalic acid and monoethylene glycol, Vietnam for garment assembly integration, and India for cotton staple fiber ginning. Finished thread distribution runs through Ho Chi Minh City and Hanoi logistics corridors for European brand contracts, with Da Nang warehousing capacity expanding to serve just-in-time apparel production. Single-source vulnerability in cotton belt regions creates climate disruption exposure for spun staple thread lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric vehicle upholstery programs are accelerating penetration of high-tenacity continuous filament polyester into safety-critical seating applications, creating early-cycle expansion conditions for certified thread suppliers.
For Market Incumbents: Build regulatory certification moats by accelerating OEKO-TEX Standard 100 and ZDHC MRSL compliance ahead of EU Green Deal recycled content mandates. Coats Group PLC and AMANN & Söhne GmbH & Co KG should deepen backward integration into supercritical CO2 dyeing systems to eliminate water-treatment compliance risks. Consolidate position among small Italian finishers unable to absorb REACH reformulation R&D costs. For New Entrants and Emerging Players: Establish a beachhead in reflective thread segments where European high-visibility safety standards tighten fastest. Vietnamese industrial zones offer penetrable geography for OEKO-TEX certified polyester volume given Bangladesh and Vietnam absorption of China-routed demand. Pursue direct digital color-matching platform partnerships with automotive OEMs disintermediating tiered seating suppliers. For Investors and Strategic Acquirers: EU Green Deal textile sector circularity requirements reshape the acquisition landscape toward thread lines with verified post-consumer recycled content certification. Target mid-tier European finishers with REACH-compliant infrastructure but lacking scale to serve South Asian apparel corridors. Watch for recycled nylon 6,6 tenacity consistency breakthroughs as the signal indicating safety-critical automotive application viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Supercritical CO2 Dyeing | Eliminates water-treatment compliance risks for Portuguese and Romanian finishers under ECHA REACH Annex XVII. |
| Direct Digital Color-Matching Platform Deployment | Captures aftermarket repair-kit revenue from Coats Group PLC industrial thread database lock-in. |
| Recycled Content Certification Investment | Secures preferential market access under EU Green Deal textile sector circularity requirements. |
| Capacity Expansion in Vietnamese Industrial Zones | Serves Ho Chi Minh City and Hanoi garment export corridors absorbing China-routed volume. |
| Automotive OEM Direct Material Approval | Bypasses tiered seating supplier disintermediation in Stuttgart and Turin EV upholstery programs. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with thread industry stakeholders and systematic secondary validation across trade and regulatory databases. Primary fieldwork engaged procurement directors at German automotive seating suppliers, technical R&D leads at Portuguese dye houses, Bangladesh garment exporter supply chain managers, and OEKO-TEX certification auditors. Secondary sources included ECHA REACH substance restriction databases, GB standards compliance filings, customs trade data for PTA and MEG feedstock flows, and SEC 10-K disclosures from listed thread manufacturers. Bottom-up volume modeling triangulated against top-down market sizing across product type, thread size, end use, and color type segmentation.
Forecast inputs considered electric vehicle production ramp schedules, apparel manufacturing relocation patterns, and regulatory compliance timeline accelerations. Segmentation dimensions modeled include continuous filament versus spun staple construction, REACH certification tier, automotive versus apparel end-use durability specifications, and regional production hub concentration. CAGRs were derived from elasticity-adjusted demand projections across the analysis window. Industry-specific forecast inputs incorporated ECHA dye restriction enforcement intensity and recycled nylon 6,6 technical performance improvement trajectories.
Stress conditions across petrochemical feedstock price bands, tariff regime changes, and climate disruption frequency in cotton belt regions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and EV upholstery program adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Printed Textiles Market
Yarn and Fabric Manufacturing
Canvas Roll Market
Yarn and Fabric Manufacturing
Spun Yarn Paper Cone Market
Yarn and Fabric Manufacturing
Italy Textile Manufacturing Market
Yarn and Fabric Manufacturing
Fancy Yarn Market
Yarn and Fabric Manufacturing
Knitted Fabric Market
Yarn and Fabric Manufacturing
Wool Market
Yarn and Fabric Manufacturing
Wool Worsted Yarn Market
Yarn and Fabric Manufacturing
Polypropylene Yarn Market
Yarn and Fabric Manufacturing
Malaysia Textile Manufacturing Market
Yarn and Fabric Manufacturing
Textile Fabrics Market
Yarn and Fabric Manufacturing
Denim Fabric Market
Yarn and Fabric Manufacturing
South America Cotton Market
Yarn and Fabric Manufacturing
Tire Yarn Market
Yarn and Fabric Manufacturing
Global Cashmere Yarn Market
Yarn and Fabric Manufacturing
Silica Yarn Market