
 Wool Worsted Yarn Market | 2026-2036
Wool Worsted Yarn Market Size, Share, and Industry Trends Forecast 2026-2036
Wool Worsted Yarn Market Analytics
Direct-to-mill procurement channels for worsted wool tops is fragmenting as regional spinners bypass traditional commission houses. Sudwolle Group leverages captive wool-top operations in Germany and China to secure fiber traceability. Tollegno 1900 anchors its competitive stance through vertical control from scouring to finished yarn in Biella. Zegna Baruffa Lane Borgosesia differentiates via heritage branding and superfine micron specialization for luxury weavers.
Wool worsted yarn consists of long-staple fibers aligned through combing, then drawn and twisted into smooth, dense constructions typically ranging from 24 to 80 metric count; this structure delivers dimensional stability and clean surface finish required for precision tailoring and technical textiles. Combed yarn commands the dominant value share due to its performance in formalwear, while specialty yarn incorporating cashmere or silk captures expanding margin pools in accessory knitting. Fine wool grades sustain premium positioning among Italian and Japanese suit manufacturers, though blended yarn with technical fibers is gaining traction in performance outerwear applications.
REACH restricts azo dyes and formaldehyde-based finishing agents in European worsted processing, compelling mills to reformulate wet-chemical protocols or source certified inputs. China's GB standards and MEE discharge permits tighten effluent controls around wool scouring plants in Jiangsu and Zhejiang provinces. Stakeholders must monitor evolving fiber certification schemes and regional chemical compliance timelines to secure uninterrupted mill access across multiple supply jurisdictions.
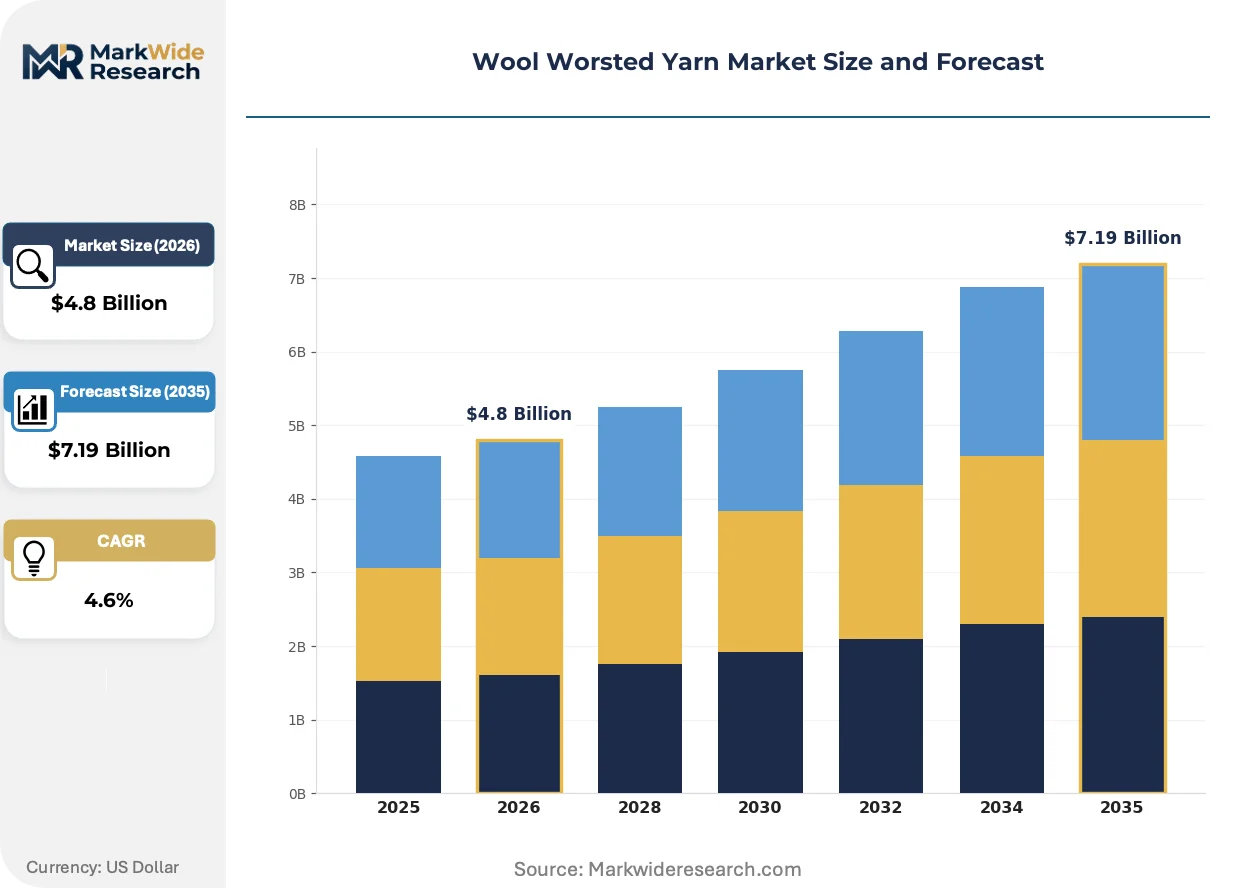
Market Dynamics
Direct-to-mill procurement is fragmenting traditional commission-house channels as regional spinners in China and Italy establish captive sourcing relationships with Australian and South African wool growers, compressing margins for legacy trading intermediaries.
Growth Catalysts
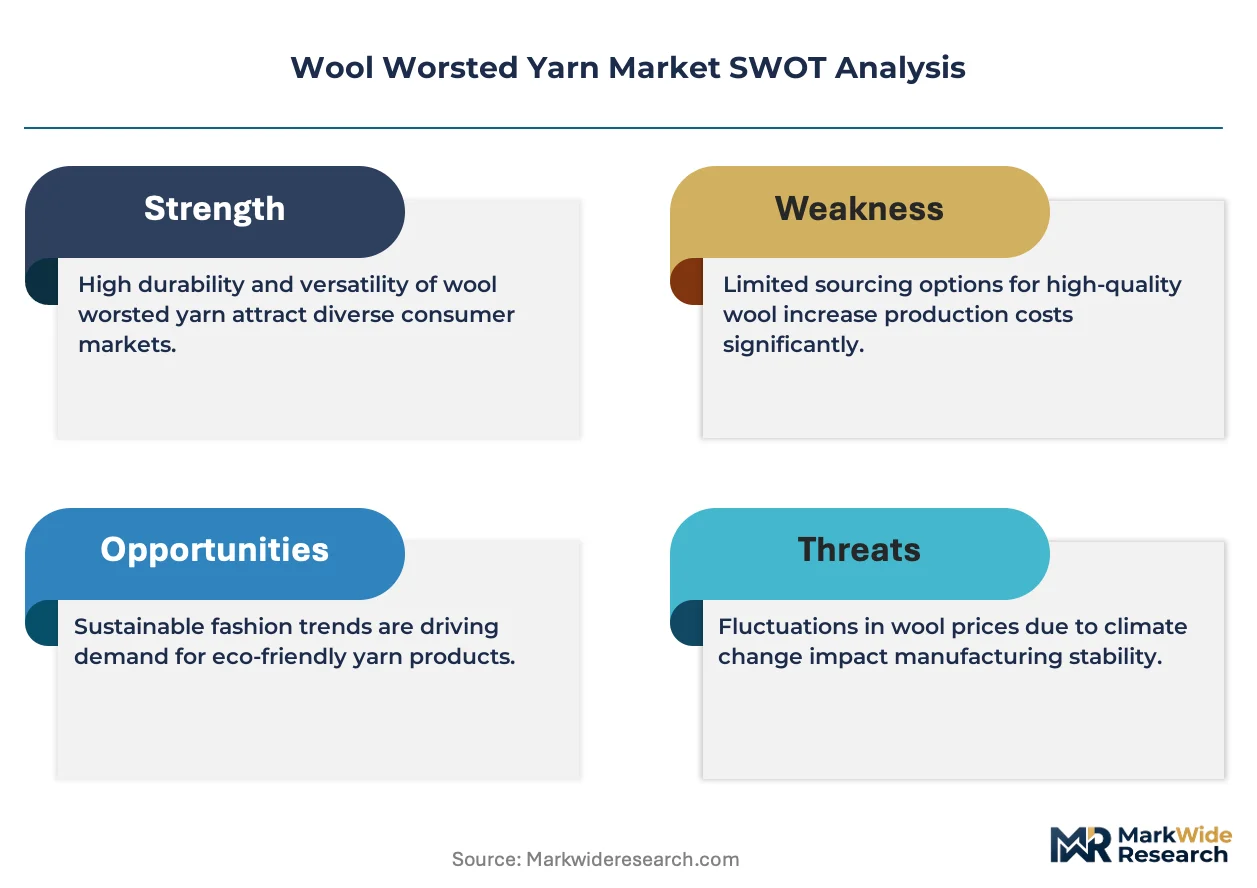
- REACH chemical reformulation:European mills are accelerating adoption of bio-based dye auxiliaries and formaldehyde-free finishing agents to maintain export access, creating premium positioning for compliant yarn batches.
- Luxury menswear expansion:Italian tailoring houses are expanding worsted wool programs for made-to-measure suiting, pulling superfine micron counts through Biella spinning corridors.
- Technical fiber blending:Worsted constructions incorporating flame-retardant modacrylic or conductive filaments are penetrating protective workwear and smart textile applications.
Market Restraints
- Merino price volatility:Australian wool auction volatility and currency swings compress spinning margins for mills without forward-contract hedging.
- Jiangsu-Zhejiang supply concentration:China's eastern manufacturing corridor dominates global spinning capacity, exposing buyers to regional power rationing and effluent enforcement disruptions.
- Synthetic substitution:Recycled polyester and bio-based polyamide yarns compete for outerwear and accessory knitting volumes on cost and washability metrics.
Strategic Opportunities
- India technical textile push:The country's PLI scheme for man-made fiber technical textiles creates pull-through demand for wool-polyester blended worsted inputs in defense and industrial applications.
- Blockchain traceability:Farm-to-finished-garment digital verification systems enable premium pricing for certified ethical wool in Japanese and South Korean apparel markets.
- Carbon-neutral scouring:Renewable thermal energy integration at wool-top processing plants aligns with EU Green Deal procurement criteria for public sector uniform contracts.
Industry Challenges
- Combing technician scarcity:Specialized skills for gilling and drawing operations are aging out in European and Japanese mill towns without adequate apprenticeship pipelines.
- MEE discharge compliance:China's Ministry of Ecology and Environment is tightening COD and suspended solids limits for wool scouring effluent, requiring capex-heavy biological treatment upgrades at legacy plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wool Worsted Yarn Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carded Yarn, Combed Yarn, Blended Yarn, Specialty Yarn Grade: Fine Wool, Medium Wool, Coarse Wool, Premium Wool Form: Skein, Cone, Ball, Hank End User: Knitters, Weavers, Manufacturers, Hobbyists |
| Companies Covered | Sudwolle Group, Shandong Hengtai Textile Co. Ltd., Indorama Ventures Public Company Limited, Henan First Textile & Apparel (Group) Co. Ltd., Yunsa, Tollegno 1900, Zegna Baruffa Lane Borgosesia, Suedwolle Group, JayaShree Textiles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wool Worsted Yarn Market Evolving Landscape
Digital process control and sustainable chemistry are converging to reshape worsted manufacturing economics, with mills investing in closed-loop water systems and AI-driven quality inspection to defend premium positioning against lower-cost regional competitors.
Automated roving transport and real-time tension monitoring systems are migrating from pilot installations at German equipment suppliers to mainstream adoption at Chinese spinning complexes serving export markets. European luxury weavers are specifying these systems for batch consistency in superfine counts. The technology is migrating from high-end niche applications toward volume-tier price competition, compressing differentiation windows for manual-process competitors.
REACH authorization requirements for chromium-based mordants and certain azo dye precursors are forcing reformulation of wet-chemical protocols across European finishing houses. Mills serving Italian and French luxury brands are qualifying bio-based alternatives through extended laboratory trials. The superfine segment faces the steepest compliance timeline, with certification deadlines clustering in the 2025-2027 window.
Brand-direct yarn sourcing is displacing traditional commission-agent relationships as vertically integrated apparel groups build captive spinning capacity or establish preferred-supplier frameworks with nominated mills. Japanese trading houses are consolidating their worsted procurement desks into fewer, deeper mill partnerships. This pattern is most visible in the China-Japan-Korea corridor, where lead times and minimum order quantities are compressing in parallel.
Wool Worsted Yarn Market Segmentation
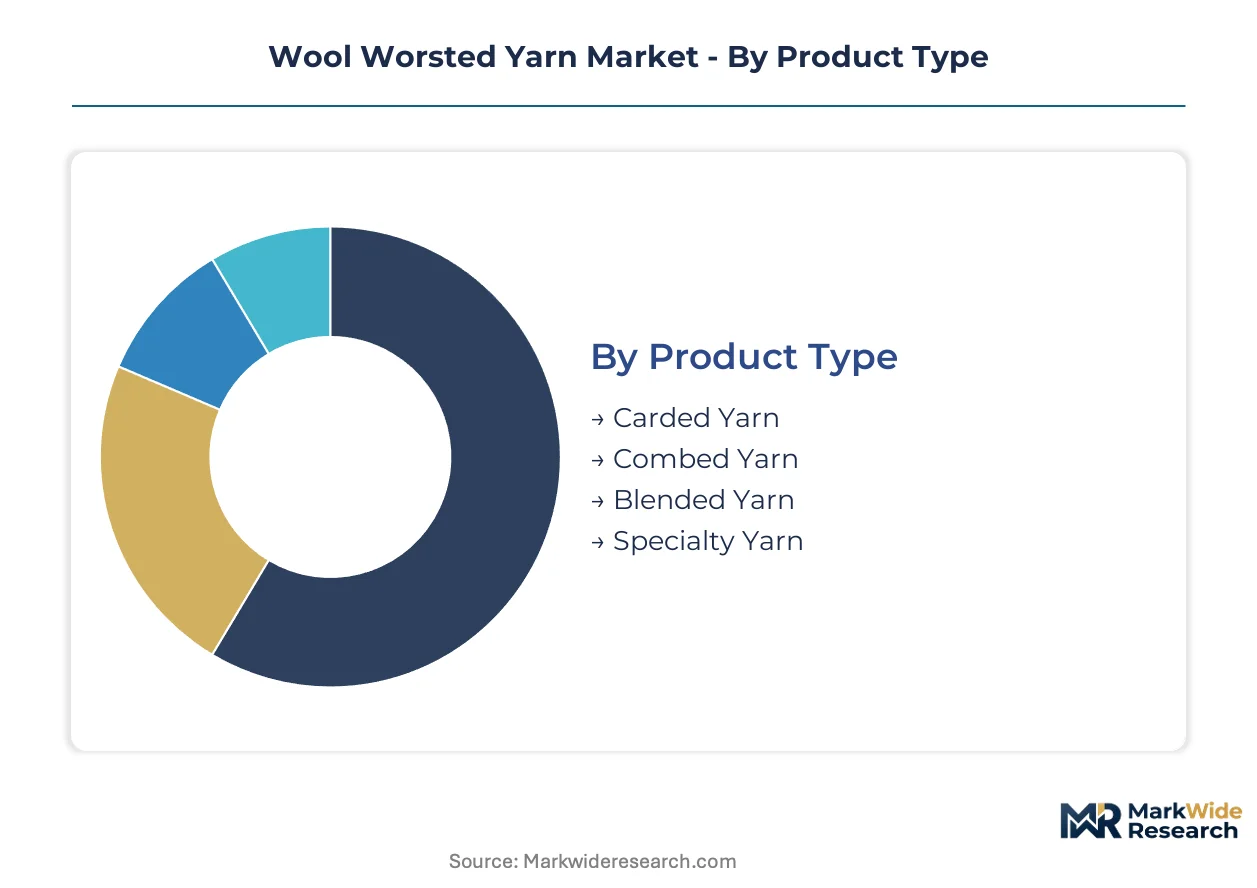
Wool worsted yarn segmentation reflects divergent technical requirements across formalwear, technical textiles, and craft applications. Distinct product types, wool grades, and delivery forms command specialized after-sales support ranging from dye-lot matching to tension calibration services.
Product Type:
After-sales-service intensity varies sharply across product types, with combed and specialty yarns requiring technical troubleshooting for downstream processing failures while carded alternatives need minimal post-sale intervention.
- Combed Yarn:Long-staple fibers aligned through gilling and drawing deliver smooth, dense constructions with superior dimensional stability. Italian luxury weavers in Biella and Japanese suit manufacturers concentrate demand for superfine counts, though REACH-mandated chemical reformulation is compressing margin structures for European finishers.
- Specialty Yarn:Incorporates cashmere, silk, or technical filaments to serve accessory knitting and protective workwear. South Korean and Japanese apparel markets pull expanding volumes for certified ethical blends, with blockchain traceability systems enabling premium positioning.
- Carded Yarn:Shorter staple fibers retain natural crimp for loftier, more elastic hand-knitting applications.
- Blended Yarn:Wool-polyester and wool-modacrylic constructions serve India's PLI-backed technical textile push in defense and industrial segments.
By volume, combed yarn leads. By growth pace, specialty yarn is expanding most quickly.
Grade:
Cost tier stratification separates micron-specific positioning, with premium and fine grades capturing margin pools in tailored suiting while coarse wool serves price-sensitive industrial applications.
- Fine Wool:Sub-19 micron fibers deliver the clean surface finish required for precision tailoring. Australian merino auction volatility and currency swings compress spinning margins for mills lacking forward-contract hedging.
- Premium Wool:Superfine micron specialization with heritage branding anchors Italian luxury positioning. Zegna Baruffa Lane Borgosesia and Tollegno 1900 concentrate output here, though synthetic substitution pressures from recycled polyester intensify competitive tension.
- Medium Wool:Balances performance and cost for mid-tier outerwear and corporate uniform programs.
- Coarse Wool:Rugged durability serves carpet backing, insulation, and heritage craft markets with minimal processing overhead.
By volume, medium wool leads. By growth pace, premium wool is gaining share fastest.
Form:
Delivery configuration determines handling automation compatibility and inventory velocity, with cone-wound formats dominating industrial throughput while skein and hank formats serve craft-channel flexibility requirements.
- Cone:Precision-wound packages enable automated feeding into circular knitting and high-speed weaving equipment. China's eastern manufacturing corridor in Jiangsu and Zhejiang provinces concentrates cone-wound output for export contracts, though MEE discharge permit tightening threatens legacy plant economics.
- Skein:Looped presentation supports hand-dyeing operations and small-batch artisan production. Independent dyers in Japan and South Korea favor this format for gradient and variegated color development.
- Ball:Consumer-ready winding serves retail craft channels and hobbyist convenience.
- Hank:Traditional presentation persists in heritage wool regions and specialty hand-knitting boutiques.
By volume, cone leads. By growth pace, skein is climbing the fastest.
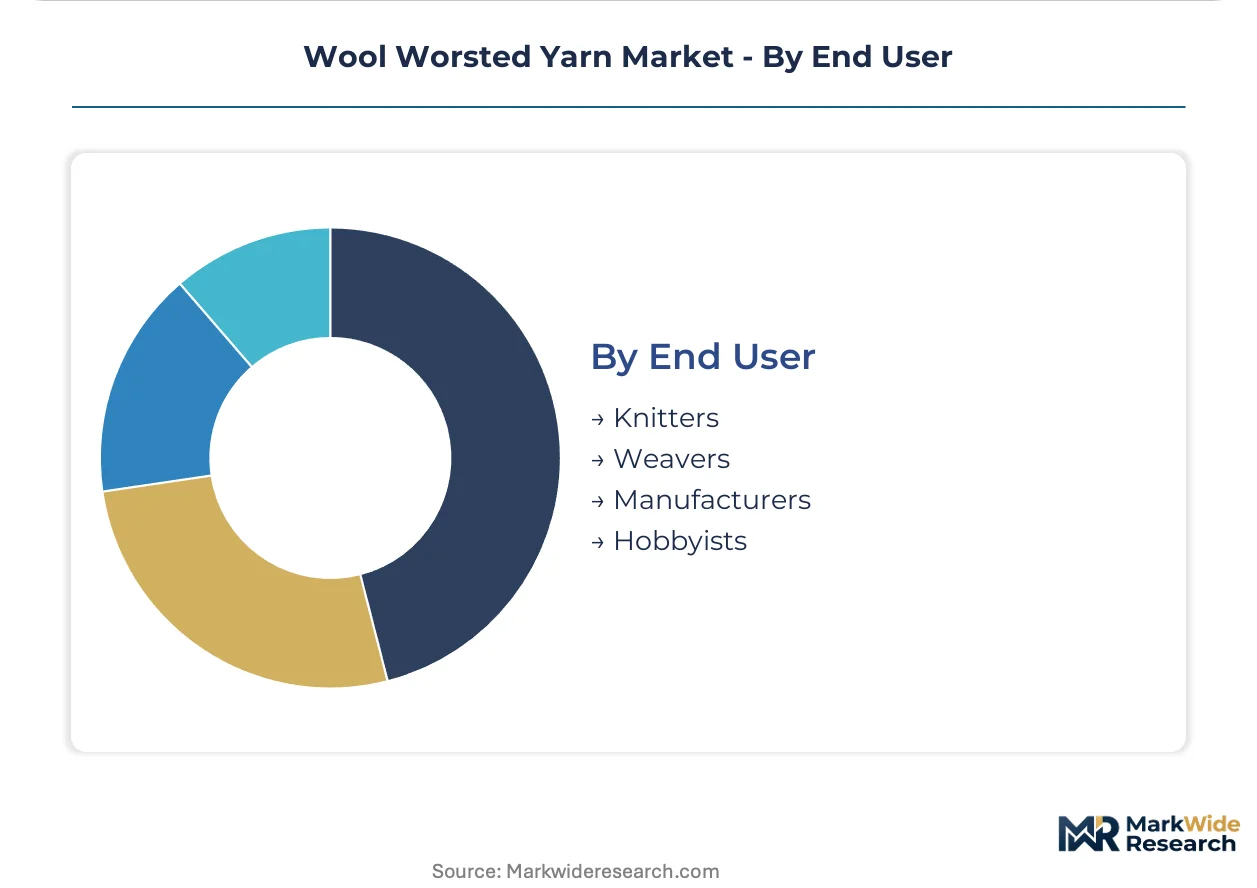
End User:
Customer type fragmentation separates specification intensity, with manufacturers and weavers demanding certified batch consistency while hobbyists prioritize color availability and tactile sampling.
- Weavers:Precision tension requirements and loom-specific yarn engineering drive technical collaboration with spinning mills. Italian tailoring houses expanding made-to-measure suiting programs pull superfine worsted through nominated supplier frameworks.
- Manufacturers:Volume procurement with traceability mandates dominates apparel and technical textile production. Brand-direct yarn sourcing is displacing traditional commission-agent relationships as vertically integrated groups build captive spinning capacity.
- Knitters:Hand and machine knitting applications span fashion accessories through industrial hosiery.
- Hobbyists:Craft-channel consumers drive seasonal color trend adoption with minimal technical specification burden.
By volume, manufacturers lead. By growth pace, weavers are pulling ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's container throughput underwrites China's dominance in worsted yarn export logistics, while the Brenner rail corridor feeds Italian Biella mills with Australian wool tops. These infrastructure assets shape regional competitive positioning across the trade lanes that matter most for long-staple fiber processing.
China
Jiangsu and Zhejiang provinces concentrate spinning capacity serving both domestic apparel brands and Japanese export contracts. MEE discharge permits are tightening COD limits for wool scouring plants, forcing biological treatment upgrades at legacy facilities. Nantong and Shaoxing mill clusters are absorbing automated roving transport systems to defend batch consistency against European competitors.
Italy
Luxury menswear houses in Milan and Florence are expanding made-to-measure suiting programs, pulling superfine micron counts through Biella spinning corridors. REACH compliance deadlines for chromium-based mordants are compressing margin structures for finishers serving French and domestic luxury brands. The Biella district maintains vertical control from scouring to finished yarn through Tollegno 1900 and Zegna Baruffa Lane Borgosesia operations.
India
The PLI scheme for man-made fiber technical textiles is creating pull-through demand for wool-polyester blended worsted inputs in defense and industrial applications. BIS certification requirements are tightening quality standards for yarn imports used in government uniform contracts. Ludhiana and Tiruppur clusters are developing specialty yarn capabilities to serve South Korean and Japanese apparel markets.
Japan
Japanese suit manufacturers concentrate demand for sub-19 micron fine wool grades requiring precision tension calibration. METI standards for textile chemical residues are aligning with REACH protocols, compelling mills to reformulate wet-chemical protocols. Osaka-based trading houses are consolidating worsted procurement desks into fewer, deeper mill partnerships with nominated Chinese suppliers.
South Korea
Seoul and Busan apparel markets are pulling expanding volumes for certified ethical wool blends with blockchain traceability verification. MFDS textile safety standards are tightening formaldehyde limits for finished garments, upstream pressure on yarn sourcing criteria. Daegu-Gyeongbuk textile complexes are investing in dye-lot matching services to serve domestic luxury accessory knitters.
Wool Worsted Yarn Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated specialists with captive wool-top operations and heritage branding capabilities. Three strategic archetypes dominate: German-Chinese scale players with traceable fiber pipelines, Italian luxury houses with superfine micron specialization, and Indian-Chinese volume spinners serving technical textile programs. Competitive moves center on backward integration into scouring operations and blockchain-enabled farm-to-garment verification systems.
Within the heritage-anchored tier, Tollegno 1900 and Zegna Baruffa Lane Borgosesia exemplify vertical control from fiber processing through finished yarn, occupying positions that command premium positioning among Biella luxury weavers. Sudwolle Group represents the scale-driven archetype with captive wool-top operations spanning Germany and China, securing fiber traceability for mills serving export markets. These three anchors illustrate how competitive positioning stratifies across branding intensity, geographic reach, and upstream supply control.
| Leading Market Players |
|---|
| Sudwolle Group |
| Shandong Hengtai Textile Co. Ltd. |
| Indorama Ventures Public Company Limited |
| Henan First Textile & Apparel (Group) Co. Ltd. |
| Yunsa |
| Tollegno 1900 |
| Zegna Baruffa Lane Borgosesia |
| Suedwolle Group |
| JayaShree Textiles |
| Others |
Value Network & Pricing Analysis
The Brenner rail corridor's freight cost dynamics compress margin structures for Australian wool tops moving into Italian Biella mills while amplifying price differentiation between superfine heritage batches and commodity-grade alternatives. This logistics chokepoint concentrates supply-side leverage among spinners with captive scouring operations, forcing price-sensitive buyers toward blended yarn substitutes.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates superfine micron heritage batches certified for REACH compliance from medium-grade contract spinning and coarse industrial inputs. Price differentiation hinges on fiber certification grade and geographic delivery cost, with Italian luxury weavers absorbing premiums for traceable Australian merino while Asian uniform contractors squeeze margins on volume orders. Pricing pressure stems from synthetic substitution in outerwear applications, compressing mid-tier wool-polyester blends. Brand-direct apparel manufacturers exhibit lowest price sensitivity; commodity traders and industrial knitters show highest elasticity.
Supply Chain Analysis
Tariff exposure between Australia and China dominates supply chain risk calculus for wool-top processors dependent on auction floor sourcing. Raw material flows concentrate through Australian merino auctions, South African Cape wool sales, and Chinese scouring clusters in Jiangsu and Zhejiang provinces. The supply chain draws from long-staple fiber gilling, bio-based dye auxiliaries, and automated roving transport systems. Single-source vulnerability persists at the combing technician skill layer. Distribution runs through direct-to-mill procurement channels displacing traditional commission houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wool worsted yarn market functions as a defensive-moat industry where regulatory entrenchment around REACH chemical compliance creates sticky supplier relationships that resist rapid switching.
For Market Incumbents: Pre-empt synthetic substitution threats by accelerating bio-based finishing agent certification before REACH deadline clustering. Secure backward integration into scouring operations to isolate margin structures from Australian auction volatility. Anchor capacity in China's eastern corridor with MEE-compliant biological treatment upgrades to defend access against effluent enforcement disruptions.
For New Entrants and Emerging Players: India's technical textile corridors offer the most penetrable white-space for wool-polyester blended worsted inputs serving defense and industrial applications under PLI scheme incentives. Target blockchain-enabled traceability verification as the go-to-market angle for South Korean and Japanese apparel markets demanding certified ethical wool. Qualify bio-based dye alternatives through extended laboratory trials to bypass REACH-mandated reformulation barriers.
For Investors and Strategic Acquirers: Captive wool-top operations with heritage branding capabilities represent the priority acquisition archetype for long-term viability across the five-to-ten year horizon. Monitor carbon-neutral scouring certification adoption rates as the inflection signal for EU Green Deal procurement alignment. Mills with automated quality inspection and closed-loop water systems command defensive positioning against lower-cost regional competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scouring | Captive wool-top operations isolate margins from Australian auction volatility and currency swings. |
| REACH Chemical Reformulation | Bio-based dye auxiliaries and formaldehyde-free finishing agents secure European luxury brand access. |
| Blockchain Traceability Deployment | Farm-to-garment verification enables premium positioning in Japanese and South Korean apparel markets. |
| Carbon-Neutral Scouring Certification | Renewable thermal energy integration aligns with EU Green Deal public sector uniform procurement criteria. |
| Technical Fiber Blending Capacity | Wool-modacrylic constructions penetrate India's PLI-backed defense and industrial textile segments. |
Research Methodology
Desk research of customs trade data, wool auction records, and regulatory filing databases preceded structured interviews with spinning mill operations directors, luxury apparel procurement leads, technical textile R&D heads, and chemical compliance officers at finishing houses. Primary fieldwork across Biella, Jiangsu, and Ludhiana clusters was cross-validated against Australian Wool Innovation reports, ECHA REACH authorization timelines, and China's MEE discharge permit records. Bottom-up volume modeling triangulated with top-down value estimates from trade flow analysis.
Assumptions held fixed include REACH compliance deadline adherence, Australian merino auction volume stability, and Chinese environmental enforcement intensity at observed levels; variables tested included synthetic substitution rates and technical textile blend adoption curves. The analytical framework segmented by product type, wool grade, delivery form, and end-user category across the projection horizon. CAGRs derived from historical trade flow trajectories adjusted for fiber certification scheme penetration and automation capital deployment cycles.
The forecast holds incumbent behavior within observed patterns; aggressive moves by bio-based chemical suppliers or recycled polyester fiber producers would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Textile Fabrics Market
Yarn and Fabric Manufacturing
Canvas and Muslin Bags Market
Yarn and Fabric Manufacturing
Tire Yarn Market
Yarn and Fabric Manufacturing
Nylon 6 Filament Yarn Market
Yarn and Fabric Manufacturing
Printed Textiles Market
Yarn and Fabric Manufacturing
Europe Textile Fabrics Market
Yarn and Fabric Manufacturing
Sailcloth Market
Yarn and Fabric Manufacturing
Cotton Bags Market
Yarn and Fabric Manufacturing
Indonesia Textile Manufacturing Market
Yarn and Fabric Manufacturing
Mercerized Cotton Market
Yarn and Fabric Manufacturing
Denim Fabric Market
Yarn and Fabric Manufacturing
Flat Knitting Machine Market
Yarn and Fabric Manufacturing
Global Textile Yarn Market
Yarn and Fabric Manufacturing
South America Cotton Market
Yarn and Fabric Manufacturing
Global Tire Cord Fabrics Market
Yarn and Fabric Manufacturing
Silica Yarn Market