
 Europe Hydrogen Generation Market | 2026-2036
Europe Hydrogen Generation Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hydrogen Generation Market Foresight
Buyer concentration among European refiners is rebalancing toward a broader set of ammonia producers and steelmakers seeking decarbonization feedstock. Linde plc sustains its integrated position across production and distribution infrastructure. Air Liquide leverages its pipeline network in the Benelux region to anchor long-term offtake contracts. Nel ASA specializes in PEM electrolyzer manufacturing, competing on modular deployment speed for gigawatt-scale projects.
Hydrogen generation encompasses the industrial production of molecular hydrogen through thermochemical, electrochemical, or biological processes, typically yielding purities from 99.9% to 99.999% depending on end-use requirements. Steam methane reforming currently dominates European output, though electrolysis is displacing fossil-based routes as renewable electricity costs decline and carbon border adjustments tighten. Electrolysis capacity is expanding fastest among production technologies, driven by dedicated offshore wind-to-hydrogen corridors. Ammonia synthesis and refining absorb the largest application volumes, while metal processing represents an emerging margin pool as direct reduced iron projects scale.
The EU Green Deal, REPowerEU, and the F-Gas Regulation collectively mandate renewable hydrogen quotas in transport and industry while restricting fluorinated gases used in cooling hydrogen liquefaction equipment. ECHA oversees chemical safety classifications that affect hydrogen handling standards across member states. Stakeholders must monitor national hydrogen backbone auction schedules and carbon contract-for-difference allocations to secure pipeline access and offtake certainty.
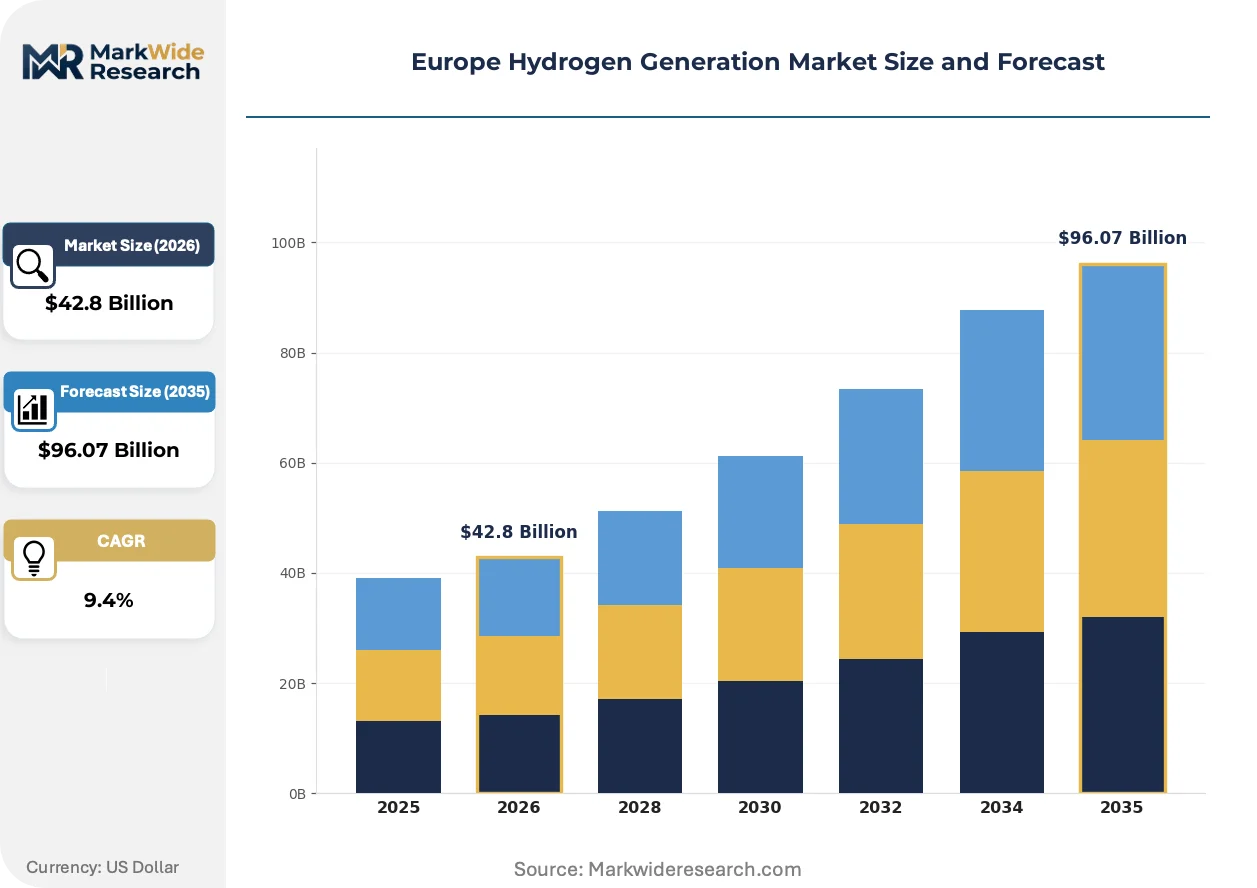
Market Dynamics
Electrolyzer capacity deployment is compressing project timelines across the European hydrogen generation landscape, as developers race to secure offtake contracts before national auction windows close.
Growth Catalysts
- REPowerEU framework:The hydrogen accelerator mechanism mandates renewable hydrogen quotas in transport and industry, redirecting capital toward electrolyzer manufacturing clusters in Germany and Spain.
- Carbon border adjustments:Steelmakers in the Benelux region are contracting for low-carbon hydrogen feedstock to maintain export competitiveness against imports from carbon-intensive production regions.
- Offshore wind-to-hydrogen corridors:North Sea lease rounds are dedicating seabed areas to integrated production facilities, collapsing the distance between generation and offtake points.
Market Restraints
- Grid connection queuing:Renewable electricity interconnection delays in the Netherlands and Germany are stretching project commissioning schedules beyond initial commercial operation date targets.
- Fluorinated gas supply constraints:The F-Gas Regulation restricts gases essential for hydrogen liquefaction cooling systems, compressing equipment availability for export-oriented projects.
- Steam methane reforming lock-in:Existing refinery hydrogen assets in Poland and Romania carry sunk capital costs that slow the economics of electrolyzer replacement.
Strategic Opportunities
- Spanish industrial zones:The Iberian peninsula's surplus solar generation and deepwater port access position it as a hydrogen export hub serving North African and Atlantic shipping routes.
- Pipeline network repurposing:Former natural gas transmission infrastructure in the Netherlands offers ready-made distribution channels for blended hydrogen injection.
- Carbon contract-for-difference schemes:National allocation rounds in Germany and Denmark provide price stability mechanisms that de-risk green hydrogen production investments.
Industry Challenges
- Electrolyzer stack manufacturing capacity:PEM and alkaline system producers face order backlogs stretching 18-24 months, constraining gigawatt-scale project execution timelines.
- Certification harmonization delays:Divergent national implementations of the EU's renewable hydrogen delegated acts are creating compliance fragmentation for cross-border offtake contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hydrogen Generation Market |
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $96.07 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Production Technology: Electrolysis, Steam Methane Reforming, Partial Oxidation, Coal Gasification, Biomass Gasification Application: Refining, Ammonia Synthesis, Methanol Production, Power Generation, Metal Processing End User Industry: Oil & Gas, Chemical Manufacturing, Energy Utilities, Metal Fabrication, Electronics Manufacturing Distribution Channel: Direct Sales, Distributors, Online Platforms, Third-Party Vendors, Government Supply Contracts |
| Companies Covered | Linde plc, Air Liquide, Air Products, Nel ASA, thyssenkrupp nucera, ITM Power, Engie SA, Plug Power, Messer Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hydrogen Generation Market Shifts & Advancements
Electrolyzer technology maturation is compressing capital costs per installed megawatt, while regulatory pressure on industrial emissions intensifies the pace of fossil-based hydrogen displacement across European manufacturing corridors.
Solid oxide electrolyzer technology is integrating high-temperature steam inputs from industrial waste heat streams, boosting system efficiency beyond alkaline or PEM alternatives. Steel producers in northern Germany are piloting this configuration at direct reduced iron facilities. The technology is integrating thermal management systems that collapse parasitic energy losses, enabling round-trip efficiency gains that reshape project economics at scale.
The EU Green Deal's delegated acts on renewable hydrogen are tightening eligibility criteria for electrolyzer electricity sourcing, mandating temporal and geographic correlation between generation and consumption. Industrial offtakers must now contract for firm renewable power or face exclusion from subsidy schemes. Refinery operators in the Netherlands are responding by co-locating electrolyzers directly behind offshore wind substations.
Long-term offtake contracting is displacing spot-market purchasing as the dominant procurement model for industrial hydrogen buyers. Ammonia producers and aviation fuel synthesizers are locking in 10-15 year supply agreements to secure project finance for their own capital-intensive facilities. This pattern concentrates most visibly in the German chemical corridor, where BASF and other majors are underwriting electrolyzer buildouts through guaranteed volume commitments.
Europe Hydrogen Generation Market Segmentation
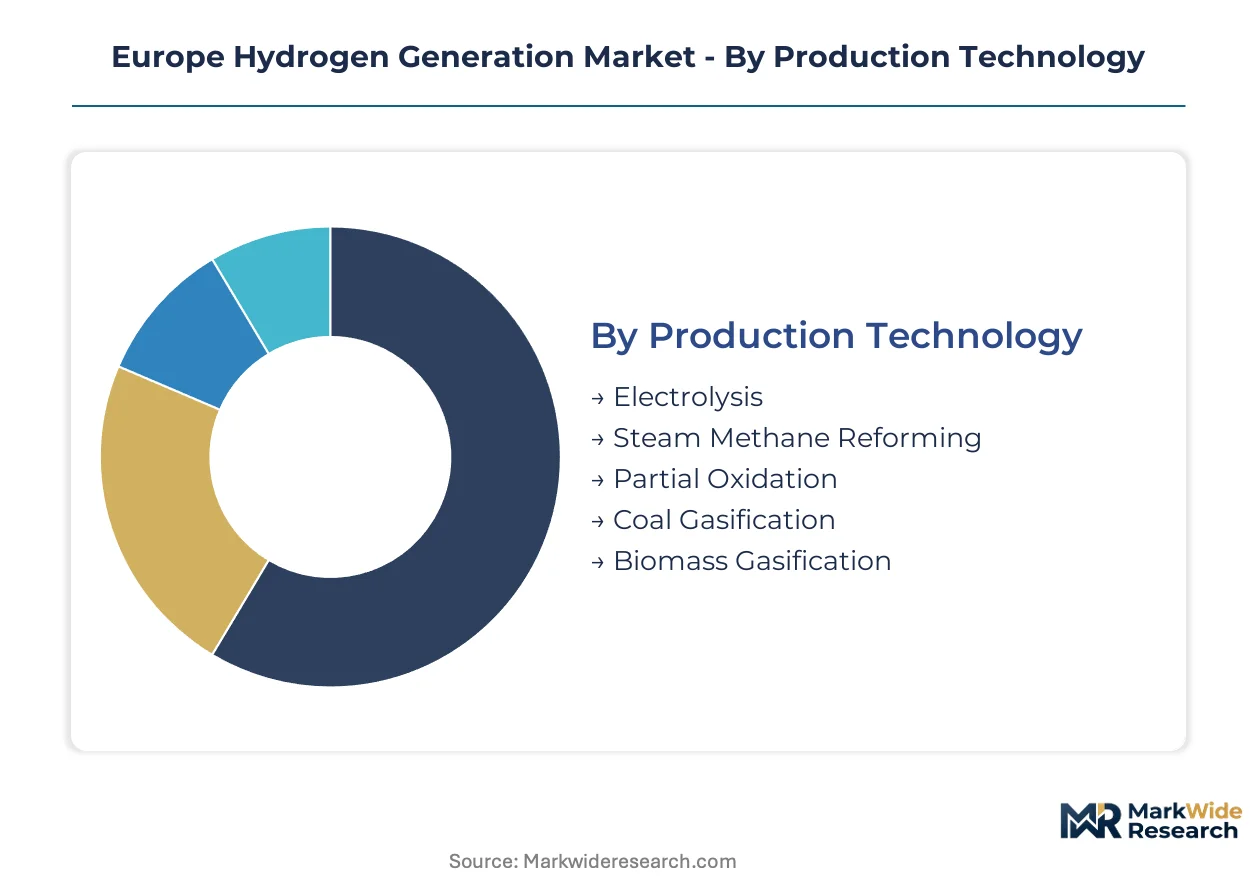
Production technology and application dynamics in European hydrogen generation diverge sharply between incumbent fossil routes and emerging electrolytic pathways. End-user procurement patterns cluster around carbon intensity thresholds that determine subsidy eligibility and export market access.
Production Technology:
Cost tiers separate mature thermal processes from capital-intensive electrochemical systems competing on carbon credentials.
- Electrolysis:Electrochemical water splitting yields high-purity hydrogen through alkaline, PEM, or solid oxide cell stacks. German offshore wind corridors and Spanish solar parks anchor the fastest capacity additions as developers chase REPowerEU renewable hydrogen quotas.
- Steam Methane Reforming:Catalytic reaction of natural gas with steam dominates current European output volumes. Polish and Romanian refineries maintain sunk investments in SMR assets that slow electrolyzer replacement timelines despite tightening carbon border adjustments.
- Partial Oxidation:Heavy hydrocarbon feedstock conversion generates hydrogen alongside synthesis gas for chemical manufacturing.
- Coal Gasification:Thermal coal conversion to hydrogen persists in limited Central European industrial clusters.
- Biomass Gasification:Organic feedstock thermochemical processing produces hydrogen with biogenic carbon credentials.
Volume sits with Steam Methane Reforming; growth tilts toward Electrolysis.
Application:
Margin profiles vary by carbon intensity requirements and offtake contract duration across industrial hydrogen consumers.
- Refining:Hydrocracking and desulfurization operations consume hydrogen at scale. Dutch and German refiners are contracting electrolytic supply to meet tightening EU fuel quality standards and maintain product export eligibility.
- Ammonia Synthesis:Haber-Bosch process feedstock demand concentrates in the German chemical corridor where BASF and Yara are underwriting long-term green hydrogen offtake agreements to decarbonize fertilizer production.
- Methanol Production:Catalytic synthesis of methanol from hydrogen and carbon dioxide serves chemical and fuel blending markets.
- Power Generation:Hydrogen firing in gas turbines and fuel cells provides grid balancing and seasonal storage.
- Metal Processing:Direct reduced iron and steelmaking feedstock represents an emerging volume pool as Swedish and German producers pilot hydrogen-based metallurgy.
Revenue concentrates in Refining; steepest expansion trajectory belongs to Metal Processing.
End User Industry:
Procurement sophistication separates integrated energy majors from fragmented manufacturing consumers.
- Oil & Gas:Vertically integrated majors leverage existing infrastructure and trading capabilities to source hydrogen across production routes. Shell and TotalEnergies are repurposing North Sea pipeline networks for hydrogen distribution while contracting electrolyzer capacity.
- Chemical Manufacturing:Ammonia and methanol producers anchor the largest industrial offtake volumes with 10-15 year supply agreements. BASF's Ludwigshafen complex exemplifies the shift toward captive electrolyzer installations behind renewable generation assets.
- Energy Utilities:Power sector hydrogen demand centers on grid storage and blending applications.
- Metal Fabrication:Steelmakers and specialty metals processors are emerging as price-takers for low-carbon hydrogen feedstock.
- Electronics Manufacturing:Semiconductor and display panel production requires ultra-high purity hydrogen for reduction processes.
Contract scale favors Oil & Gas; volume growth shifts toward Chemical Manufacturing.
Distribution Channel:
Supply chain configuration determines access to pipeline backbone versus captive production economics.
- Direct Sales:Producer-to-consumer contracts dominate large industrial offtake with dedicated pipeline or trailer delivery. Air Liquide's Benelux pipeline network anchors long-term agreements with Antwerp-Rotterdam chemical cluster consumers.
- Distributors:Regional gas merchants aggregate small and mid-scale demand across fragmented manufacturing bases.
- Online Platforms:Digital procurement channels are emerging for spot hydrogen trading and certificate exchange.
- Third-Party Vendors:Independent logistics providers manage compressed and liquid hydrogen transport for non-pipeline customers.
- Government Supply Contracts:Public procurement frameworks support strategic reserve and defense applications.
Transaction value concentrates in Direct Sales; platform adoption expands fastest through Online Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European hydrogen demand concentrates in industrial corridors spanning the North Sea rim and Iberian Atlantic coast, with project pipelines diverging between export-oriented electrolyzer clusters and captive refinery supply.
Germany
Chemical manufacturers in the Rhine-Ruhr corridor anchor continental hydrogen offtake, with BASF's Ludwigshafen complex underwriting electrolyzer buildouts through volume commitments. The national hydrogen strategy allocates carbon contract-for-difference funding to de-risk green production investments. Offshore wind-to-hydrogen pilot projects in Lower Saxony and Schleswig-Holstein are compressing commissioning timelines ahead of 2026 auction windows.
Netherlands
Rotterdam-Antwerp refining and chemical clusters drive demand for low-carbon hydrogen feedstock as EU fuel quality standards tighten. The F-Gas Regulation restricts cooling gases essential for liquefaction equipment, compressing availability for export-oriented terminals. Pipeline network repurposing from natural gas infrastructure offers ready-made distribution channels for blended hydrogen injection across the Benelux region.
Spain
Surplus solar generation in Andalusia and Extremadura positions the Iberian peninsula as an Atlantic export hub. REPowerEU renewable hydrogen quotas redirect capital toward electrolyzer manufacturing clusters in Zaragoza and Tarragona industrial zones. Deepwater port access at Huelva and Algeciras supports ammonia and shipping fuel synthesis projects targeting North African markets.
Sweden
Steel producers in the Boden-Luleå corridor pilot hydrogen-based direct reduced iron metallurgy, creating an emerging volume pool for electrolytic supply. The national industrial decarbonization program channels public capital toward fossil-free steel demonstration plants. SSAB's HYBRIT initiative in Norrbotten exemplifies long-term offtake contracting patterns spreading across Scandinavian metal processing.
Poland
Refinery hydrogen assets in Płock and Gdańsk carry sunk capital costs that slow electrolyzer replacement despite tightening carbon border adjustments. The EU Green Deal's delegated acts on renewable hydrogen eligibility create compliance pressure for export-oriented fuel producers. Silesian industrial clusters face stranded asset risk as neighboring German offtakers contract for certified low-carbon supply.
Europe Hydrogen Generation Market Competitive Landscape
German industrial gas producers anchor one tier; Nordic electrolyzer specialists and French energy utilities hold differentiated positions on technology and infrastructure vectors. Market structure tilts toward consolidated integrated players with pipeline backbone access, while modular equipment vendors compete on deployment velocity for gigawatt-scale projects. Strategic archetypes separate incumbent gas majors with distribution networks from pure-play electrolyzer manufacturers and project developers. Dominant competitive moves center on long-term offtake contracting and pipeline network repurposing rather than capacity expansion alone.
Within the integrated industrial gas tier, Linde plc and Air Liquide occupy positions defined by existing hydrogen infrastructure and long-term supply relationships. Nel ASA exemplifies the specialized electrolyzer manufacturing archetype competing on modular system deployment. Thyssenkrupp nucera represents the industrial engineering conglomerate model leveraging process technology heritage into electrochemical systems.
| Leading Market Players |
|---|
| Linde plc |
| Air Liquide |
| Air Products |
| Nel ASA |
| thyssenkrupp nucera |
| ITM Power |
| Engie SA |
| Plug Power |
| Messer Group |
| Others |
Supply & Pricing Matrix
The EU Green Deal's renewable hydrogen delegated acts gate qualified supply and premium-tier pricing access by mandating temporal and geographic correlation between electrolyzer electricity sourcing and consumption. Industrial offtakers lacking firm renewable power contracts face exclusion from subsidy schemes, compressing margins for uncertified production while rewarding compliant suppliers with carbon contract-for-difference allocations.
Pricing Analysis
Volume concentrates in long-term offtake contracts for ammonia and refining feedstock, while margins accrue to certified low-carbon supply serving export-oriented steelmakers. Price differentiation hinges on carbon intensity certification tier and geographic delivery cost to pipeline backbone versus captive production. Cost compression in uncertified hydrogen is intensifying because carbon border adjustments tighten, eroding Polish and Romanian refinery economics. Ammonia producers in the German chemical corridor exhibit least price sensitivity due to locked-in decade-long supply agreements, while fragmented metal fabricators show highest sensitivity to spot market fluctuations.
Supply Chain Analysis
Electrolyzer stack manufacturing workforce availability constrains expansion in Germany and Spain, where gigawatt-scale project backlogs stretch eighteen to twenty-four months. Supply concentrates in German offshore wind corridors and Spanish solar parks, drawing from iridium and platinum group metal catalyst inputs as well as fluorinated gas cooling systems for liquefaction equipment. Single-source vulnerability in PEM membrane supply creates chokepoint exposure for export-oriented terminals. Distribution runs through repurposed natural gas pipeline networks in the Netherlands and new dedicated hydrogen backbone infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe hydrogen generation market sits in a technology-transition phase as solid oxide electrolyzer systems displace alkaline and PEM alternatives in high-temperature industrial waste heat integration. This shift reconfigures competitive positioning around thermal management capabilities rather than modular deployment speed alone.
For Market Incumbents: Deepen backward integration into electrolyzer stack manufacturing to secure supply against eighteen-month order backlogs threatening project timelines. Anchor long-term offtake contracts with steelmakers in the Benelux region before carbon border adjustments fully phase in, locking in premium-tier pricing access.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in certified versus uncertified hydrogen offers white-space entry for modular PEM suppliers targeting mid-scale metal processors. Spanish industrial zones with surplus solar generation present the most penetrable geography, with direct reduced iron pilot projects offering a go-to-market angle through guaranteed volume pilot agreements.
For Investors and Strategic Acquirers: German carbon contract-for-difference allocation rounds are the leading indicator that national subsidy frameworks are stabilizing green hydrogen production economics. Target electrolyzer manufacturers with proven offshore wind co-location capabilities over the next decade. Watch for electrolyzer stack manufacturing capacity utilization rates as the inflection signal for supply-constraint easing.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyzer Manufacturing Scale-Up | German and Spanish clusters anchor gigawatt-scale deployment timelines against order backlogs. |
| Pipeline Network Repurposing | Dutch natural gas infrastructure offers ready-made distribution channels for blended hydrogen injection. |
| Long-Term Offtake Contracting | BASF and Yara volume commitments de-risk green hydrogen investments in the Rhine-Ruhr corridor. |
| Offshore Wind Co-Location | North Sea lease rounds collapse distance between generation and offtake points for Rotterdam-Antwerp clusters. |
| Carbon Certification Program | EU delegated acts on renewable hydrogen eligibility determine subsidy access and export market participation. |
Research Methodology
Document review covered EIA data, IEA hydrogen reports, FERC filings, and project development databases, complemented by interviews with electrolyzer manufacturing executives, utility planning officers, EPC contractors, and downstream chemical procurement leads. Primary fieldwork with hydrogen offtake specialists in German and Dutch industrial clusters was validated against secondary trade flow and customs data. Bottom-up electrolyzer capacity buildouts were triangulated with top-down policy target analysis.
Historical deployment trajectories were cross-referenced against expert panel input on technology cost curves and regulatory implementation timelines. The analytical framework modeled segmentation across production technology, application end-use, and regional regulatory framework throughout the forecast period. CAGRs were derived from capacity addition pipelines and offtake contract velocity, incorporating carbon border adjustment phase-in schedules and national hydrogen backbone auction timing as key inputs.
Inputs from electrolyzer OEM order books and national auction registries were available through the study window; gaps in fluorinated gas supply chain visibility introduce uncertainty bands around liquefaction equipment delivery timelines. Forecasts reflect documented assumptions on REPowerEU quota enforcement and temporal correlation mandate implementation. Material deviation in German carbon contract-for-difference allocation rounds or Dutch grid connection queuing resolution warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Hydrogen Purification Market
Hydrogen Energy
Hydrogen Powered Engine Market
Hydrogen Energy
Hydrogen Liquefaction Unit Market
Hydrogen Energy
On-Site Hydrogen Generator Market
Hydrogen Energy
Asia Pacific Liquid Hydrogen Market
Hydrogen Energy
Hydrogen Tanks Market
Hydrogen Energy
North America Liquid Hydrogen Market
Hydrogen Energy
Liquid Organic Hydrogen Carrier (LOHC) Market
Hydrogen Energy
Global Hydrogen Electrolyzers Market
Hydrogen Energy
Hydrogen Purification Units Market
Hydrogen Energy
Hydrogen Market
Hydrogen Energy
Gray Hydrogen Market
Hydrogen Energy
Hydrogen Station Market
Hydrogen Energy
70MPa High Pressure Hydrogen Storage Cylinders Market
Hydrogen Energy
Hydrogen Purifiers Market
Hydrogen Energy
Europe Clean Hydrogen Market