
 Viral Vector Purification Market | 2026-2036
Viral Vector Purification Market Size, Share, and Industry Trends Forecast 2026-2036
Viral Vector Purification Market Analysis
North American contract manufacturers is decoupling from legacy plasma-protein purification footprints to build dedicated viral vector suites. Cytiva leverages its chromatography resin portfolio to anchor multi-modal purification workflows for AAV and lentivirus programs. Sartorius competes through integrated single-use filtration and ultrafiltration skids that reduce cross-contamination risk in multi-product facilities. Danaher extends its position across analytical and purification instrumentation, giving end-to-end process control to gene therapy developers.
Viral vector purification encompasses the downstream bioprocessing steps that remove host-cell proteins, DNA, empty capsids, and adventitious agents from gene therapy intermediates, typically achieving final purity through chromatographic separation with 0.1–1.0 micron membrane filtration and resin-based affinity capture. The process serves as the critical quality gate between upstream vector production and final drug substance release for clinical or commercial gene therapy supply. Chromatography systems dominate capital expenditure budgets because resin lifetime and dynamic binding capacity directly determine cost per dose at commercial scale. Membrane filtration is displacing older depth filtration trains in gene therapy workflows, driven by single-use format adoption and reduced hold-up volumes that protect yield-sensitive AAV processes. Contract manufacturing organizations represent the fastest-growing end-user segment as biopharmaceutical sponsors outsource purification scale-up rather than building in-house downstream expertise.
FDA guidance on chemistry, manufacturing, and controls for gene therapy products shapes viral vector purity specifications, while EMA's ATMP framework imposes comparable viral safety and potency testing requirements for European market access. ISO 14644 cleanroom classifications and WHO TRS 941 viral safety standards further constrain facility design and operational qualification for multi-product purification suites. Stakeholders must monitor how evolving regulatory divergence between FDA potency assay expectations and EMA comparability requirements reshapes validation protocols for internationally supplied vector programs.
Market Dynamics
Biopharmaceutical sponsors are outsourcing purification scale-up to contract manufacturing organizations rather than building captive downstream expertise, concentrating demand among specialized CDMOs with multi-modal chromatography capabilities and segregated viral vector suites.
Growth Catalysts
- EMA ATMP Framework:The European Medicines Agency's advanced therapy medicinal products regulation mandates stringent viral safety testing, compelling sponsors to invest in validated purification workflows for European market access.
- Gene therapy pipelines:Biopharmaceutical developers are advancing AAV and lentivirus programs through clinical stages, creating sustained demand for high-purity downstream processing at manufacturing scale.
- Boston-San Diego clusters:Concentrated biotech ecosystems in these metropolitan areas anchor North American demand for viral vector purification services and equipment procurement.
Market Restraints
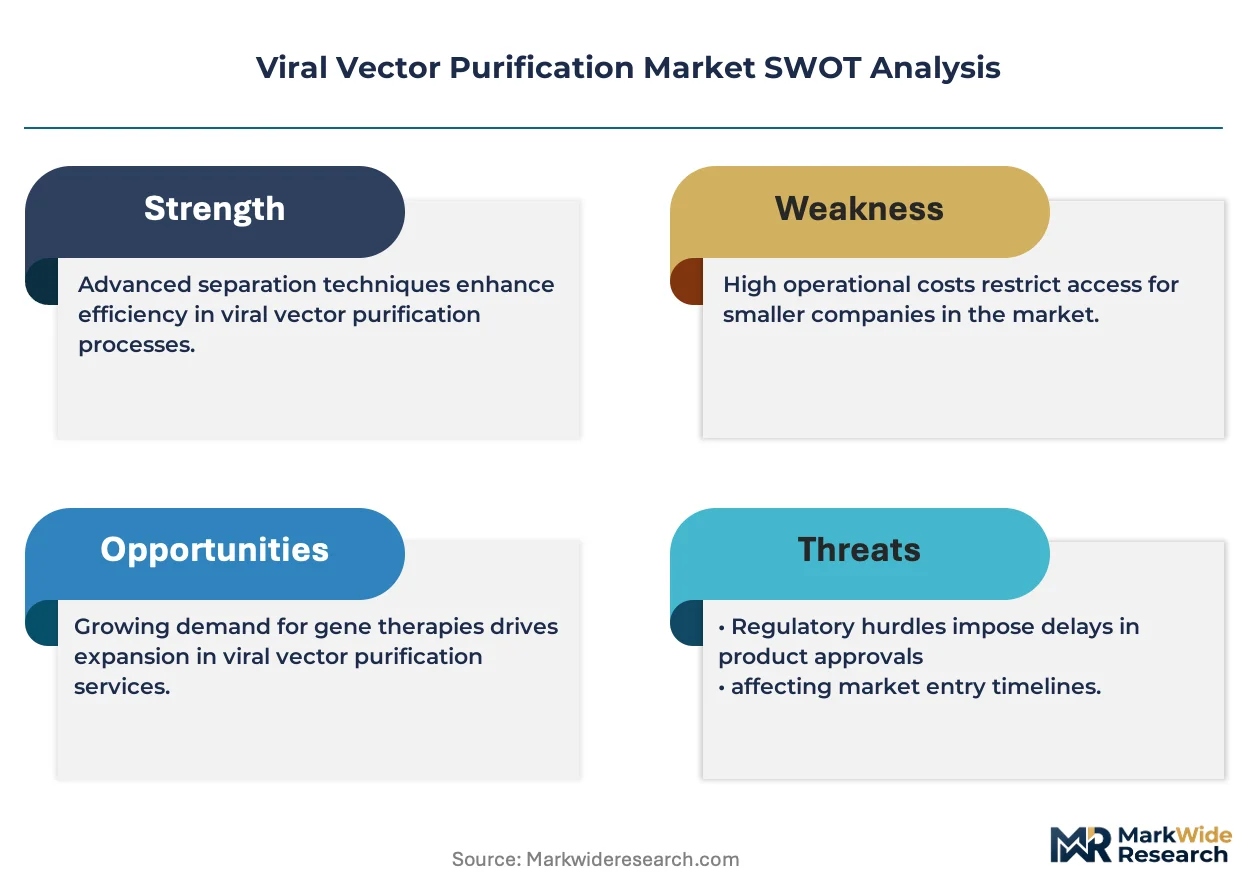
- Resin cost volatility:Protein A and synthetic affinity resins for AAV capture command premium pricing, with supply concentrated among specialized chemical manufacturers, squeezing gross margins at commercial scale.
- Single-use supply concentration:Bioprocessing film and connector supply chains cluster in East Asian manufacturing hubs, exposing purification operations to geopolitical freight disruptions.
- Empty capsid removal:Analytical ultracentrifugation and ion-exchange chromatography struggle to separate genome-containing from empty AAV particles efficiently, constraining yield optimization.
Strategic Opportunities
- India CDMO expansion:Contract manufacturers in Indian pharmaceutical hubs are building viral vector capabilities to capture outsourced gene therapy production from Western sponsors seeking cost arbitrage.
- Continuous processing convergence:Integrated perfusion bioreactor and continuous chromatography systems are reducing facility footprint and buffer consumption for viral vector manufacturing.
- FDA gene therapy guidance:Evolving chemistry, manufacturing, and controls recommendations create first-mover advantage for purification technology providers who validate platforms against emerging potency assay expectations.
Industry Challenges
- Downstream talent scarcity:Purification scientists with viral vector-specific expertise in resin screening, viral clearance validation, and DOE-based process development command premium compensation and limited availability.
- Multi-product facility qualification:ISO 14644 cleanroom segregation and campaign changeover protocols for AAV versus lentivirus programs extend validation timelines and occupancy costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Viral Vector Purification Market |
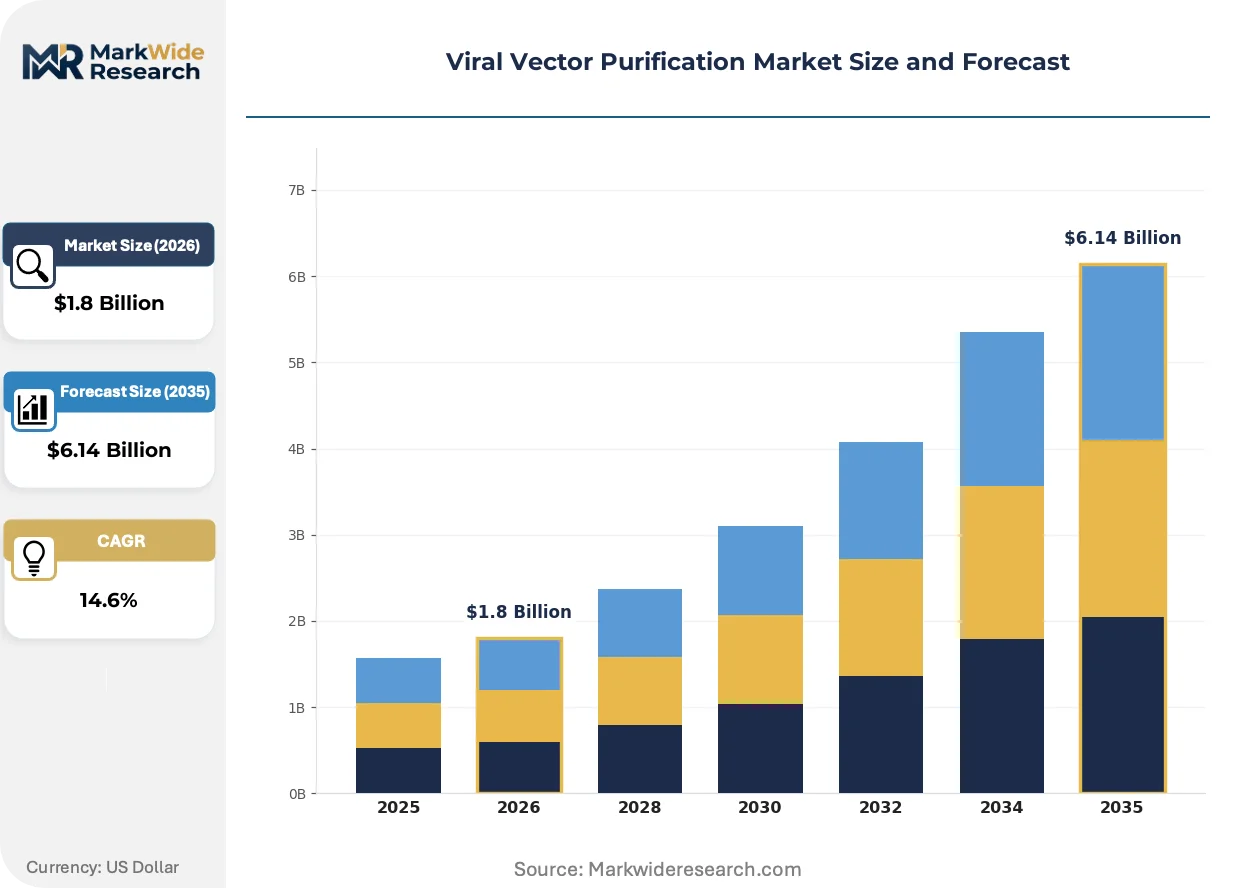
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chromatography Systems, Ultrafiltration Systems, Precipitation Kits, Filtration Devices Technology: Affinity Chromatography, Ion Exchange Chromatography, Size Exclusion, Membrane Filtration End User: Biopharmaceutical Companies, Research Laboratories, Academic Institutions, Contract Manufacturing Organizations Application: Gene Therapy, Vaccine Development, Cell Therapy, Diagnostics |
| Companies Covered | Agilent Technologies, BIA Separations, Bio-Rad Laboratories, Cytiva, Merck KGaA, Sartorius, Thermo Fisher Scientific, Repligen Corporation, Danaher, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Viral Vector Purification Market Emerging Trajectories
Membrane-based separation technologies are displacing legacy depth filtration trains, while regulatory agencies on both sides of the Atlantic tighten purity benchmarks that reshape validation protocols and equipment procurement criteria.
Multimodal chromatography resins combining ion-exchange and hydrophobic interaction chemistries are expanding into AAV purification workflows. Gene therapy developers at clinical and commercial scale are adopting these media to reduce step count and buffer volumes. This convergence is expanding into platform standardization strategies that compress process development timelines for new serotypes.
EMA's ATMP framework and FDA's evolving gene therapy CMC guidance are imposing divergent potency assay and comparability requirements. Sponsors supplying both markets must maintain dual validation dossiers, increasing regulatory affairs overhead. European contract manufacturers are responding by building dedicated analytical capabilities that satisfy both agencies without redundant testing.
Biopharmaceutical procurement teams are consolidating vendor relationships for end-to-end purification platforms rather than sourcing chromatography, filtration, and analytics separately. CDMOs and large pharma sponsors now favor single-source accountability for downstream performance. This concentration is most visible in United States coastal clusters where gene therapy developers negotiate integrated supply agreements spanning resin, hardware, and validation support.
Viral Vector Purification Market Segmentation
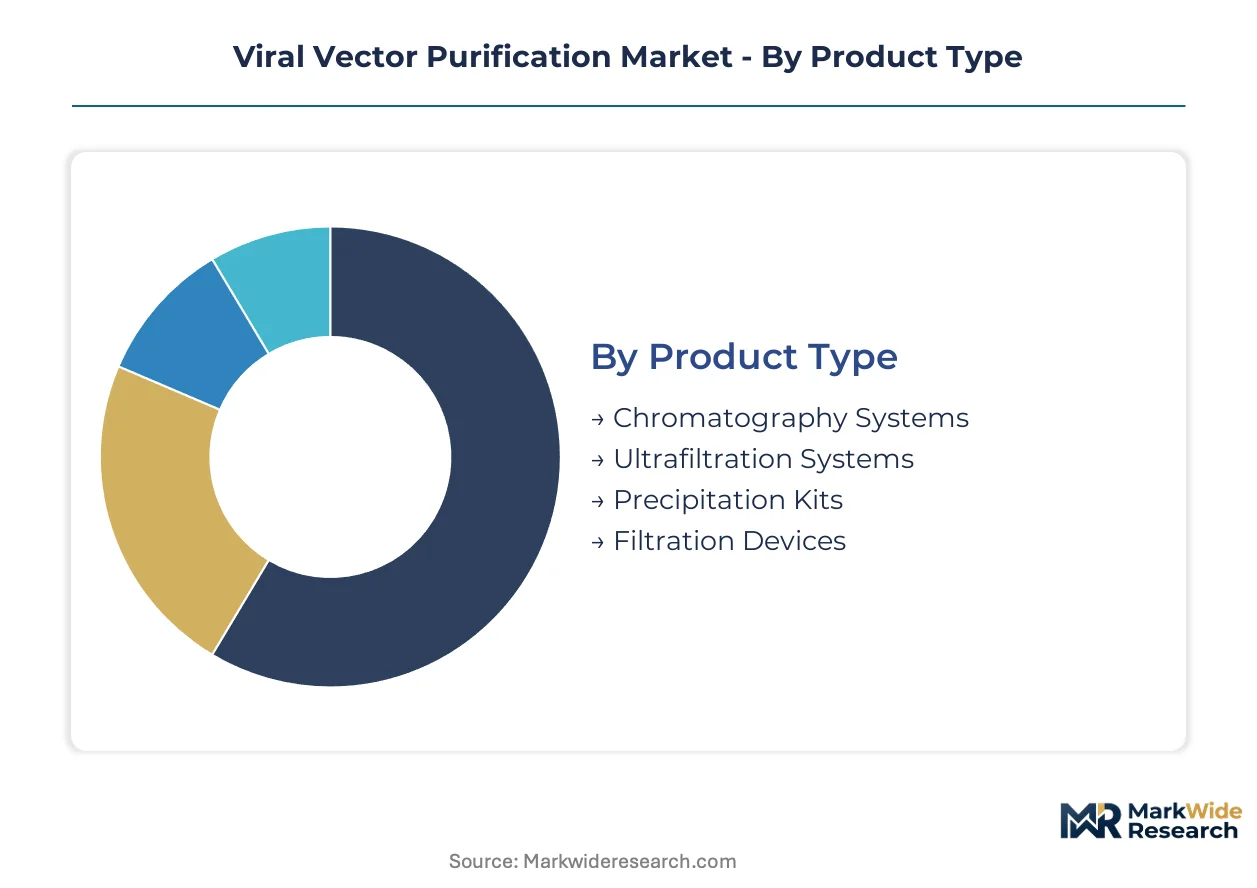
Viral vector purification equipment and consumables segment along technical, operational, and customer dimensions that directly determine procurement patterns and vendor selection criteria. Equipment specifications, regulatory validation requirements, and scale of operation create distinct purchasing behaviors across each category.
Product Type:
Capital equipment commands premium pricing and multi-year replacement cycles, while consumables generate recurring revenue streams that dominate lifetime account value.
- Chromatography Systems:Multi-column and single-column configurations with resin-packed beds achieve selective capture of full AAV capsids from host-cell contaminants. Demand concentrates among commercial-stage gene therapy sponsors in Massachusetts and California who require GMP-validated platforms for FDA-submitted manufacturing campaigns.
- Ultrafiltration Systems:Tangential flow filtration skids with single-use cassettes perform final concentration and buffer exchange steps. CDMOs in the Boston-San Diego corridor are standardizing on integrated ultrafiltration-chromatography trains to reduce facility changeover times between AAV and lentivirus programs.
- Precipitation Kits:PEG-based and salt-induced precipitation reagents offer low-cost alternatives for early-stage process development.
- Filtration Devices:0.1–1.0 micron membrane filters remove aggregates and adventitious agents prior to final fill-finish operations.
Today's leader: Chromatography Systems. Tomorrow's challenger: Ultrafiltration Systems.
Technology:
Capture chemistry selection determines yield, purity, and regulatory acceptance for specific vector serotypes and genome payloads.
- Affinity Chromatography:Protein A, nanobody, and synthetic peptide ligands enable selective binding of capsid surface epitopes. Ion-exchange polishing steps downstream of affinity capture are expanding most quickly among platform processes seeking to reduce empty capsid contamination.
- Membrane Filtration:Single-use hollow fiber and flat-sheet cassettes replace stainless-steel tangential flow systems in multi-product facilities. Gene therapy developers in San Diego are driving adoption of membrane-based separations to minimize cross-contamination risk during campaign transitions.
- Ion Exchange Chromatography:Anion and cation exchange resins separate particles by surface charge distribution.
- Size Exclusion:Gel filtration media fractionate by hydrodynamic radius for aggregate removal and buffer exchange.
Affinity Chromatography retains installed base dominance. Membrane Filtration is gaining share fastest through single-use format penetration.
End User:
Customer scale and in-house manufacturing strategy determine equipment configuration, validation depth, and service contract terms.
- Contract Manufacturing Organizations:Multi-product facilities with segregated viral vector suites purchase integrated purification platforms with dedicated analytical validation packages. CDMOs are climbing the fastest as biopharmaceutical sponsors outsource downstream scale-up rather than building captive expertise.
- Biopharmaceutical Companies:Integrated pharma sponsors with internal gene therapy pipelines invest in platform-standardized purification trains. Large-cap developers in Cambridge, Massachusetts anchor North American demand for high-throughput chromatography systems with automated buffer preparation.
- Research Laboratories:Discovery-stage groups prioritize flexibility and lower capital commitment over GMP compliance.
- Academic Institutions:University-based gene therapy programs purchase bench-scale systems for proof-of-concept studies.
Contract Manufacturing Organizations lead current procurement volume. Biopharmaceutical Companies represent the emerging captive manufacturing alternative.
Application:
Clinical indication and regulatory pathway shape purity specifications, viral clearance validation requirements, and analytical testing burdens.
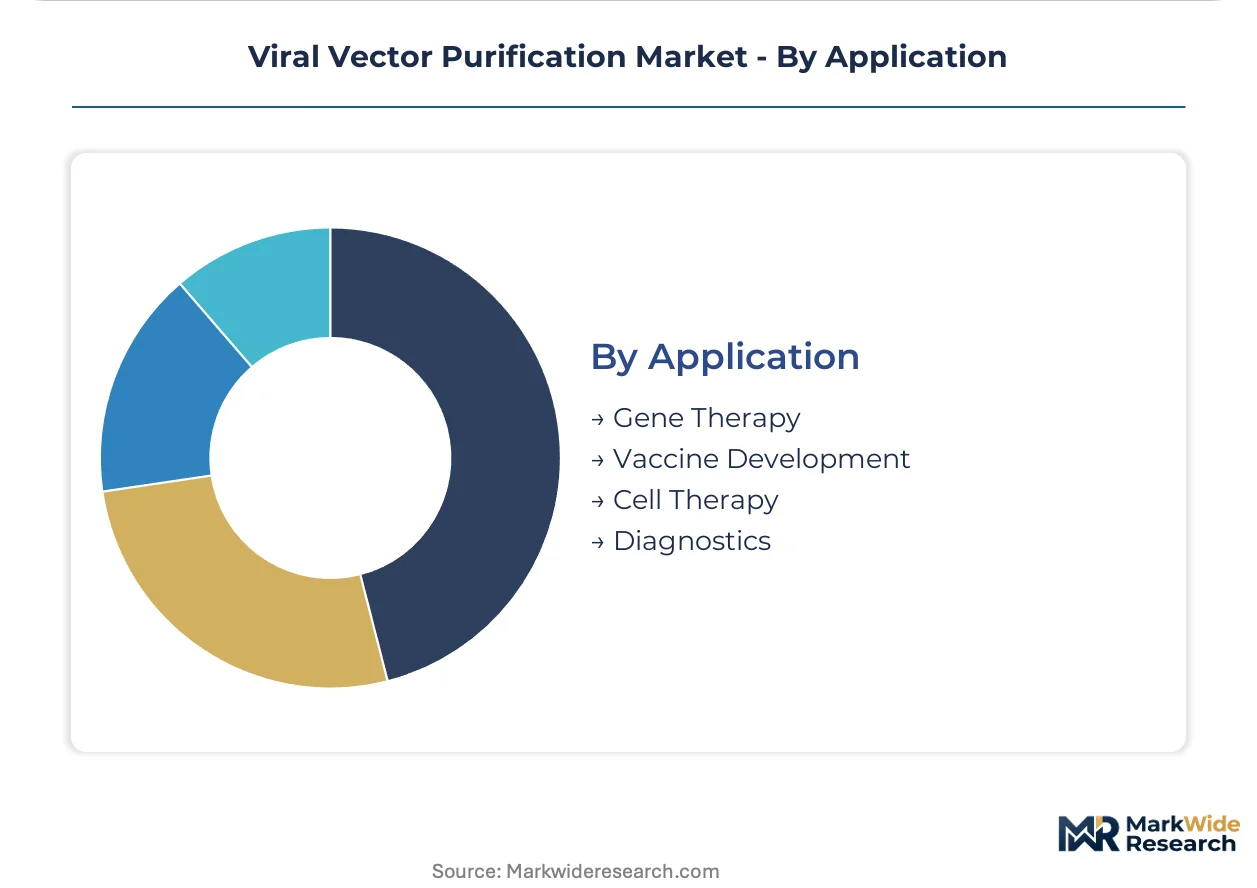
- Gene Therapy:AAV and lentivirus manufacturing for inherited and acquired diseases demands the highest purity grades with demonstrated clearance of replication-competent virus. FDA gene therapy CMC guidance and EMA ATMP requirements are tightening potency assay and viral safety standards for programs targeting both markets.
- Vaccine Development:Viral vector-based prophylactic and therapeutic vaccines require scalable purification with established platform processes. Developers are adapting AAV purification workflows originally optimized for gene therapy to meet vaccine manufacturing cost targets.
- Cell Therapy:Lentivirus production for CAR-T and other engineered cell therapies requires specialized containment and segregation protocols.
- Diagnostics:Reference standards and controls for viral load assays need purified vector material with defined genome titer.
Gene Therapy commands premium pricing and validation depth. Vaccine Development is expanding most quickly through platform adaptation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping viral vector manufacturing geography as sponsors relocate purification operations to jurisdictions with streamlined ATMP approval pathways and lower facility qualification costs. Production gravity is shifting toward specialized clusters that combine FDA-aligned GMP infrastructure with emerging EMA-compliant analytical capabilities.
United States
FDA gene therapy CMC guidance and IRA manufacturing incentives are accelerating domestic purification capacity buildout. The 21st Century Cures Act provisions expedite breakthrough therapy designations for vector-based treatments. Boston and San Diego biotech clusters anchor North American demand, with Cambridge-based CDMOs commissioning multi-modal chromatography suites for commercial AAV manufacturing.
Germany
EMA centralized ATMP marketing authorization procedures and BfArM early-access programs are concentrating European viral vector investment. The German Medical Devices Act implementation aligns with MDR quality system requirements. Heidelberg and Munich pharmaceutical hubs are expanding dedicated lentivirus purification facilities to serve EMA-submitted gene therapy programs.
Switzerland
Swissmedic streamlined licensing for advanced therapies and cantonal R&D tax incentives attract vector manufacturing investment. The country's bilateral mutual recognition agreements with the EU preserve EMA-aligned regulatory access. Basel-region biopharma campuses are integrating continuous chromatography platforms for high-purity AAV downstream processing.
India
CDSCO ATMP regulatory pathways and PLI scheme biopharma incentives are catalyzing CDMO viral vector capability investment. The National Biopharma Mission funds indigenous downstream technology development. Hyderabad and Bangalore pharmaceutical corridors are constructing segregated viral vector suites for Western sponsor outsourcing contracts.
United Kingdom
MHRA post-Brexit ATMP framework and Cell and Gene Therapy Catapult manufacturing support programs sustain purification infrastructure growth. The Innovative Licensing and Access Pathway accelerates commercial vector supply qualification. London-Oxford-Cambridge golden triangle research parks are deploying single-use filtration trains for clinical-stage gene therapy production.
Viral Vector Purification Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue continuous processing and analytical integration to differentiate positioning. Market structure concentrates among diversified life science conglomerates with chromatography resin portfolios and specialized filtration equipment fabricators. Three archetypes dominate: platform-integrated system providers, consumables-focused resin specialists, and analytical instrumentation bundlers. Capacity expansion and strategic technology licensing represent the primary competitive vectors as sponsors consolidate vendor relationships.
Among diversified platform providers, Cytiva and Danaher exemplify the integrated-system archetype through chromatography and analytical instrumentation bundling. Sartorius occupies a position within the single-use filtration specialist tier. These three entities anchor the competitive landscape by representing distinct strategic approaches to downstream bioprocessing capture.
| Leading Market Players |
|---|
| Agilent Technologies |
| BIA Separations |
| Bio-Rad Laboratories |
| Cytiva |
| Merck KGaA |
| Sartorius |
| Thermo Fisher Scientific |
| Repligen Corporation |
| Danaher |
| Others |
Supply Flow & Price Mechanics
GMP certification tier bifurcation separates FDA-validated chromatography suites from research-grade filtration skids, concentrating pricing power with resin manufacturers serving commercial-stage gene therapy sponsors while squeezing margins for early-stage precipitation kit suppliers.
Pricing Analysis
Distributor margins on consumables compress as biopharmaceutical sponsors consolidate vendor relationships into direct platform agreements with Cytiva, Danaher, and Sartorius. Three-tier pricing structure across premium, standard, and economy levels aligns with GMP validation depth, with CDMOs in Massachusetts and California absorbing premium tier costs for FDA-submitted campaigns while academic buyers negotiate economy-tier precipitation kits. Cost compression in standard-tier membrane filtration cassettes intensifies because East Asian manufacturers are expanding single-use bioprocessing film capacity. CDMOs represent the most price-sensitive segment due to multi-product facility occupancy costs, whereas integrated biopharmaceutical sponsors with captive manufacturing show least sensitivity.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme and the United States' IRA manufacturing incentives are reshaping sourcing patterns for chromatography resins and single-use assemblies. Protein A and synthetic affinity ligands concentrate in Germany, Japan, and the United States, while bioprocessing films and connectors cluster in China, South Korea, and Singapore. Raw material dependencies span agarose bead matrices, PEG precipitation reagents, and fluoropolymer films. Single-source vulnerability around nanobody ligand suppliers exposes AAV capture resin availability. Distribution runs through authorized distributor networks for capital equipment and direct OEM contracts for high-volume consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in viral vector purification hinges on continuous processing adoption reducing buffer consumption and facility footprint, while premium-tier sponsors absorb resin cost volatility for validated platform access.
For Market Incumbents: Anticipate displacement risk from continuous chromatography entrants by locking in multi-year resin supply agreements with Boston and San Diego CDMOs. Defensive consolidation moves center on backward integration into ligand manufacturing to capture margin from Protein A and nanobody suppliers, plus capacity addition in Switzerland to serve EMA-aligned sponsors seeking dual FDA-EMA validation. Regulatory divergence between FDA potency assay expectations and EMA comparability requirements threatens platform standardization strategies. For New Entrants and Emerging Players: Mid-sized biopharmaceutical sponsors with internal gene therapy pipelines represent an underserved buyer archetype seeking platform-standardized purification trains without captive downstream expertise. White-space targets include continuous ultrafiltration-chromatography integration for AAV manufacturing and analytical ultracentrifugation alternatives for empty capsid removal. The most penetrable segment spans Indian CDMOs building viral vector capabilities for Western sponsor outsourcing. Go-to-market positioning emphasizes cost-per-dose reduction through buffer volume compression and campaign changeover acceleration. For Investors and Strategic Acquirers: Consolidation pressure builds where CDMO procurement teams demand single-source accountability spanning resin, hardware, and validation support. Long-term viability favors platform-integrated system providers with chromatography resin portfolios over point-solution filtration specialists. Acquisition target archetypes include continuous processing technology developers and analytical instrumentation bundlers serving gene therapy CMC requirements. The signal to watch is FDA gene therapy guidance evolution reshaping potency assay validation protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Chromatography Platform Development | Reduces facility footprint and buffer consumption for AAV manufacturing campaigns. |
| Multi-modal Resin Portfolio Expansion | Captures demand from CDMOs standardizing on ion-exchange and hydrophobic interaction chemistries. |
| Regulatory Validation Bundling | Accelerates FDA and EMA dual-submission timelines for gene therapy sponsors. |
| India CDMO Partnership Structure | Captures cost-arbitrage outsourcing from Western biopharmaceutical sponsors. |
| Analytical Instrumentation Integration | Enables end-to-end process control from upstream production to final drug substance release. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with downstream process development scientists, CDMO operations directors, regulatory affairs leads at gene therapy sponsors, and chromatography resin procurement managers with secondary validation against FDA gene therapy CMC guidance documents, EMA ATMP framework submissions, ClinicalTrials.gov vector program listings, and SEC 10-K filings from listed life science conglomerates. Bottom-up triangulation across equipment procurement volumes and top-down validation against biopharmaceutical manufacturing capacity announcements anchored market sizing.
Segment-weighting approaches modeled viral vector purification demand across product type, technology, end user, and application dimensions, with regional regulatory cluster differentiation applied throughout the projection horizon. CAGRs derived from installed base expansion curves for chromatography systems and consumables replenishment cycles. Industry-specific forecast inputs incorporated gene therapy pipeline progression rates and CDMO facility commissioning timelines.
Underlying measurement precision varies by segment; commercial-stage gene therapy applications carry tighter precision than research laboratory procurement. Forecasts reflect documented assumptions regarding regulatory guidance stability and resin supply continuity. Viral clearance validation protocol changes or affinity ligand supply disruptions could revise projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Gene Therapy in CNS Disorder Market
Cell & Gene Therapy
Gene Vector Market
Cell & Gene Therapy
GMP Cell Banking Services Market
Cell & Gene Therapy
Global Neoantigen Cancer Vaccine Market
Cell & Gene Therapy
Nucleic Acid Based Therapeutics Market
Cell & Gene Therapy
Regenerative Medicine Market
Cell & Gene Therapy
Mrna Vaccines and Therapeutics Market
Cell & Gene Therapy
Asia-Pacific Gene Therapy Market
Cell & Gene Therapy
Global Oncolytic Virotherapy Market
Cell & Gene Therapy
Nucleic Acid Therapeutics CDMO Market
Cell & Gene Therapy
Global Gene Delivery Systems Market
Cell & Gene Therapy
Leukapheresis Products Market
Cell & Gene Therapy
Global T-Cell Acute Lymphoblastic Leukemia Treatment Market
Cell & Gene Therapy
Global Cancer Vaccine Market
Cell & Gene Therapy
Mrna Therapeutics Contract Development & Manufacturing Market
Cell & Gene Therapy
Rare Disease Gene Therapy Market