
 High-Silica Zeolite Market | 2026-2036
High-Silica Zeolite Market Size, Share, and Industry Trends Forecast 2026-2036
High-Silica Zeolite Market Outlook
Multi-source procurement among petrochemical catalyst buyers is consolidating around a smaller set of qualified suppliers with captive molecular sieve production. BASF SE leverages its Ludwigshafen integrated site to control zeolite Y and beta synthesis from raw alumina through finished catalyst. Albemarle Corporation anchors North American supply through its Kings Mountain processing chain, while Tosoh Corporation dominates Asian ion-exchange grade zeolite A output from its Nanyo complex.
High-silica zeolites are crystalline aluminosilicates with SiO₂/Al₂O₃ molar ratios exceeding 5.0, synthesized via hydrothermal crystallization of sodium silicate and alumina sources to yield frameworks with defined pore apertures between 0.3 and 0.74 nanometers; their primary commercial function is shape-selective catalysis and molecular separation in hydrocarbon processing streams. Zeolite Y captures the dominant margin pool in fluid catalytic cracking catalyst formulations, while Zeolite Beta extends into fine chemical and pharmaceutical intermediate synthesis where hydrophobicity requirements are stringent. Adsorbent applications sustain volume leadership in natural gas dehydration and air separation units, though catalyst-grade material commands premium pricing due to tighter lot-to-lot consistency specifications.
EPA fuel sulfur standards and the EU F-Gas Regulation constrain conventional acid catalyst alternatives, redirecting investment toward high-silica zeolite systems that operate at lower regeneration temperatures. China's MEE enforces dual carbon emission intensity targets that favor domestic zeolite catalyst manufacturing over imported alternatives, while REACH registration requirements in Europe filter out smaller non-integrated suppliers lacking toxicology dossier capabilities. Stakeholders must monitor how carbon border adjustment mechanisms reshape the cost structure of zeolite catalyst exports from energy-intensive production bases.
Market Dynamics
Petrochemical refiners are consolidating procurement around suppliers with captive molecular sieve synthesis capabilities as sulfur-content mandates from EPA and EU Green Deal tighten. This supply-side concentration is reshaping competitive positioning among catalyst formulators who lack backward integration into zeolite production.
Growth Catalysts
- EPA Tier 3 Sulfur Standards:Refiners in the United States are replacing conventional acid catalysts with high-silica zeolite systems to meet 10 ppm gasoline sulfur limits without capital-intensive hydrotreater expansion.
- China's Dual Carbon Goals:Domestic zeolite catalyst manufacturing is accelerating under MEE emission intensity targets, displacing imported supplies in fluid catalytic cracking units across Sinopec and PetroChina facilities.
- Zeolite Beta Hydrophobicity:Fine chemical manufacturers are expanding high-silica zeolite procurement for pharmaceutical intermediate synthesis where moisture tolerance determines catalyst cycle life.
Market Restraints
- Sodium Silicate Price Volatility:Energy-intensive production of sodium silicate precursors concentrates in coal-dependent regions, exposing zeolite manufacturers to input cost spikes during carbon border adjustment phases.
- REACH Registration Barriers:European chemical regulation filters out smaller non-integrated suppliers lacking toxicology dossier capabilities, consolidating formulation access among integrated majors.
- Metal-Organic Framework Substitution:Emerging MOF adsorbents threaten zeolite dominance in natural gas dehydration applications where ultra-high surface area requirements exceed traditional aluminosilicate performance limits.
Strategic Opportunities
- India Petrochemical Expansion:Reliance Industries and Indian Oil Corporation are building world-scale FCC complexes that favor long-term catalyst supply contracts with technology transfer provisions.
- EU F-Gas Regulation Tailwind:Refrigeration-grade zeolite adsorbents are capturing market share from fluorinated gases in commercial cooling systems under phasedown mandates.
- Biomass Pyrolysis Convergence:Zeolite catalysts are integrating with fast pyrolysis reactors to upgrade bio-oil into drop-in hydrocarbon fuels, creating new demand from renewable fuel producers.
Industry Challenges
- Crystallization Expertise Gap:Hydrothermal synthesis of high-silica frameworks requires precise control of gel chemistry and seeding protocols that few process engineers outside established suppliers have mastered.
- Lot-to-Lot Certification Timelines:Catalyst-grade zeolite production demands six-month validation cycles for petrochemical customers, compressing working capital efficiency for smaller manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Silica Zeolite Market |
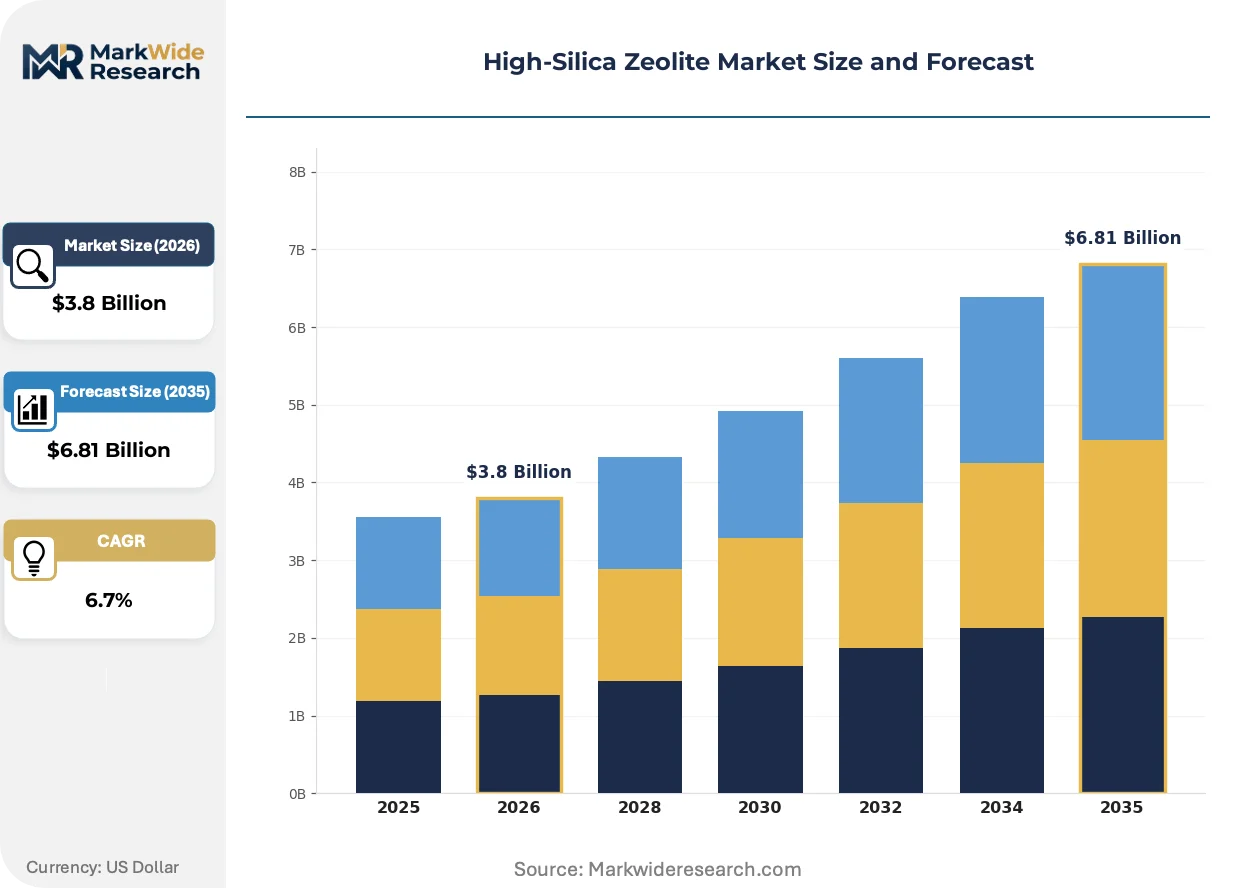
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Zeolite A, Zeolite X, Zeolite Y, Zeolite Beta Application: Catalysts, Adsorbents, Ion Exchangers, Drying Agents End User: Petrochemical, Water Treatment, Agriculture, Pharmaceuticals Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | BASF SE, Honeywell International Inc., Clariant, Zeochem, W. R. Grace & Co., Tosoh Corporation, Arkema Inc., Zeolyst International, Inc., Albemarle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Silica Zeolite Market Strategic Shifts
Zeolite framework engineering is advancing through hierarchical pore architectures that overcome diffusion limitations in bulky hydrocarbon processing. These structural innovations are reshaping catalyst performance benchmarks across refining and chemical synthesis applications.
Post-synthetic dealumination is absorbing research investment from catalyst manufacturers seeking to push SiO₂/Al₂O₃ ratios beyond 30 without framework collapse. BASF and Albemarle are deploying steaming and acid-leaching protocols at commercial scale to generate mesoporous zeolite Y with enhanced accessibility for heavy resid feedstocks. This technology is absorbing margin pressure from rare earth price volatility by reducing lanthanum exchange requirements in FCC formulations.
EU F-Gas Regulation is forcing refrigerant manufacturers to abandon hydrofluorocarbon blowing agents in favor of hydrocarbon and CO₂ alternatives that require zeolite-based drying systems. The industrial consequence is expanded ion-exchange grade zeolite A capacity across European molecular sieve producers. Air separation and natural gas processing units are most affected, with project developers specifying dual-tower zeolite drier configurations to meet leak-tightness standards.
Refiner procurement patterns are compressing catalyst evaluation cycles from multi-year trials to eighteen-month qualification windows as margin pressure accelerates technology adoption. Integrated suppliers with in-house zeolite synthesis are displacing merchant catalyst vendors in long-term supply agreements. This behavioral shift is most visible in China's coastal refining clusters, where Sinopec subsidiaries favor domestic zeolite-catalyst pairings over imported formulations.
High-Silica Zeolite Market Segmentation
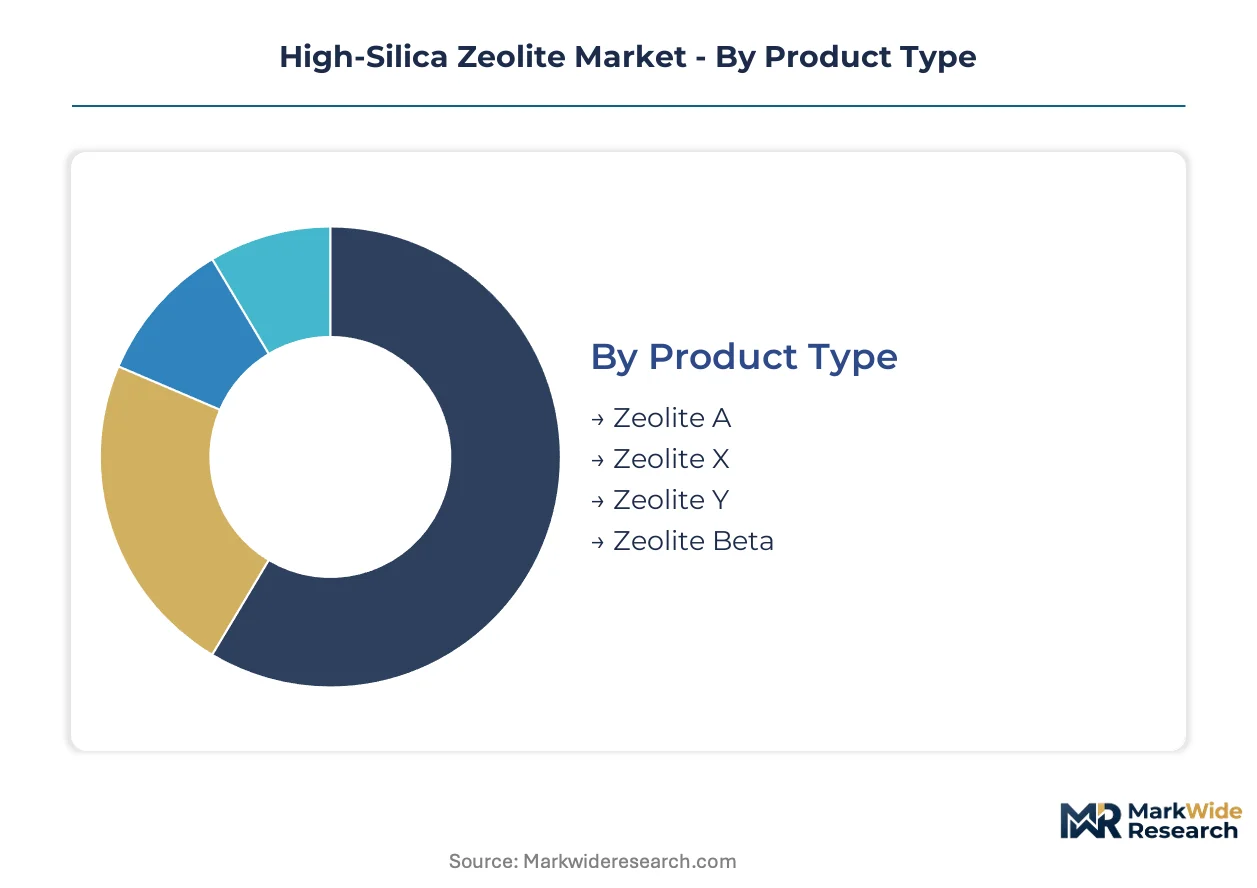
High-silica zeolite procurement patterns diverge sharply across framework types and functional roles. Specification requirements from petrochemical catalyst formulators versus adsorbent system builders create distinct margin tiers and supply qualification barriers.
Product Type:
SiO₂/Al₂O₃ molar ratios and framework topology determine catalytic selectivity and thermal stability thresholds.
- Zeolite Y:Faujasite framework with 0.74 nm supercage apertures dominates fluid catalytic cracking catalyst formulations. Refiners at Sinopec and PetroChina facilities specify rare-earth exchanged variants to meet gasoline sulfur limits under MEE dual carbon mandates without hydrotreater capital expansion.
- Zeolite Beta:Three-dimensional 12-ring channel system delivers hydrophobic surfaces critical for pharmaceutical intermediate synthesis. Fine chemical manufacturers in Germany and Switzerland expand procurement as moisture tolerance requirements tighten cycle life specifications for high-value batch processes.
- Zeolite X:Lower silica variant finds concentrated demand in air separation and natural gas dehydration where ion-exchange capacity outweighs acid site density requirements.
- Zeolite A:Small-pore LTA framework serves refrigeration drying systems under EU F-Gas Regulation phasedown mandates for hydrocarbon and CO₂ alternative refrigerants.
Mature deployment sits with Zeolite Y in refinery FCC units. Newer deployment is concentrated in Zeolite Beta for fine chemical hydrophobicity applications.
Application:
Functional role determines pricing architecture and customer validation protocols.
- Catalysts:Shape-selective acid sites enable hydrocarbon transformation with defined transition state constraints. Petrochemical formulators demand six-month lot-to-lot certification cycles that compress working capital efficiency for non-integrated suppliers lacking captive molecular sieve synthesis.
- Adsorbents:Surface area and pore volume specifications govern natural gas dehydration and air separation unit performance. Project developers specify dual-tower zeolite drier configurations to meet leak-tightness standards under refrigeration-grade deployment.
- Ion Exchangers:Cation exchange capacity drives water softening and radioactive waste treatment applications.
- Drying Agents:Static dehydration in pharmaceutical packaging and electronics manufacturing requires controlled moisture adsorption kinetics.
Catalyst-grade material commands premium pricing due to tighter consistency specifications. Adsorbent volumes lead absolute tonnage consumption.
End User:
Industry-specific purity and performance standards fragment procurement channels.
- Petrochemical:Refinery FCC and hydrocracking units absorb the dominant share of high-silica zeolite catalyst output. EPA Tier 3 sulfur standards and EU Green Deal mandates redirect investment toward zeolite systems operating at lower regeneration temperatures.
- Water Treatment:Municipal and industrial softening applications sustain ion-exchange grade zeolite A demand.
- Agriculture:Slow-release fertilizer carriers and soil amendment applications favor lower-cost natural zeolite alternatives.
- Pharmaceuticals:cGMP compliance requirements for excipient and active ingredient drying create qualification barriers for non-specialized suppliers.
Petrochemical buyers consolidate procurement around backward-integrated suppliers. Pharmaceutical end users impose the most extended validation timelines.
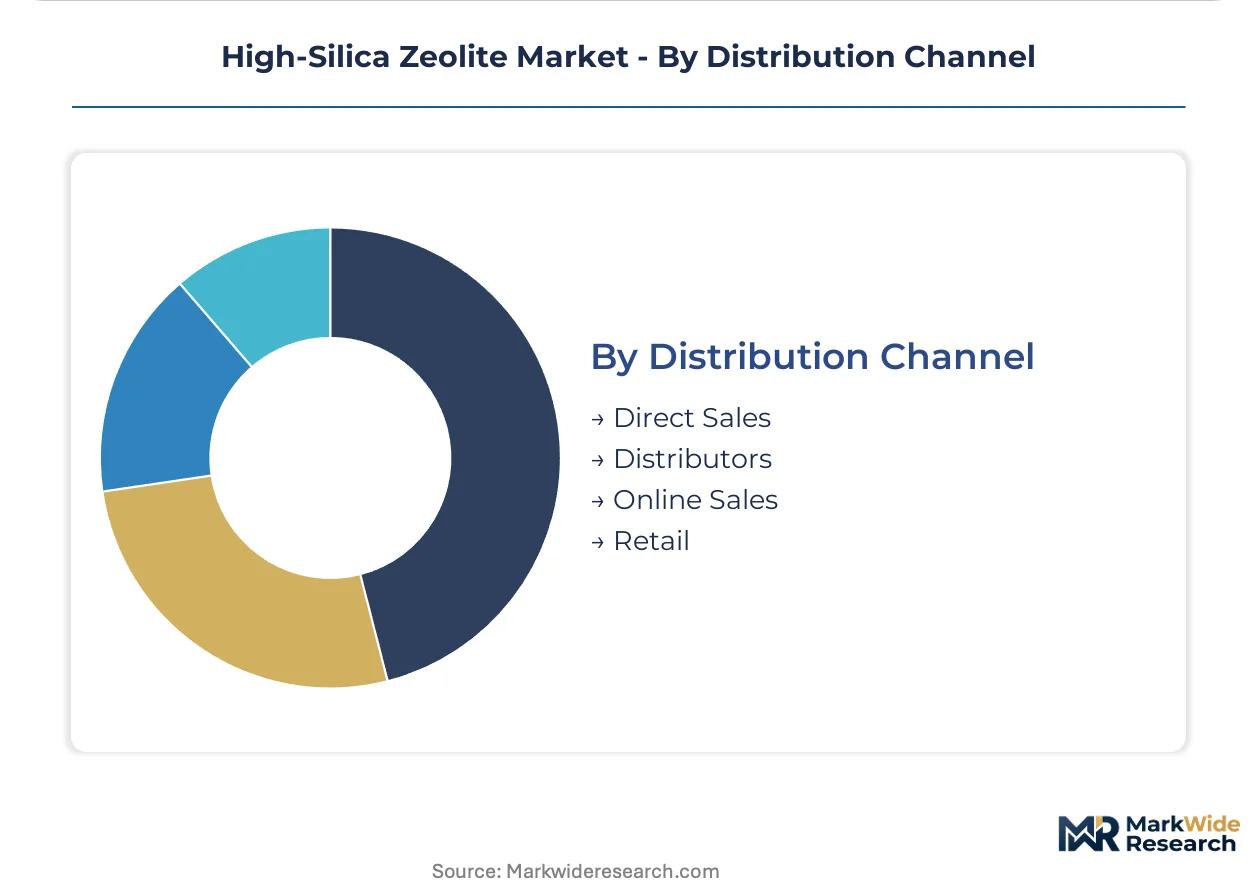
Distribution Channel:
Channel selection correlates with order scale and technical service intensity.
- Direct Sales:Long-term supply agreements with technology transfer provisions dominate refinery catalyst procurement. Reliance Industries and Indian Oil Corporation FCC complexes favor direct relationships with integrated molecular sieve producers.
- Distributors:Regional stocking points serve adsorbent replacement cycles in natural gas processing and air separation.
- Online Sales:Standardized desiccant grades for industrial drying move through digital procurement platforms.
- Retail:Consumer-grade zeolite products for household odor control and pet litter represent marginal volume.
Direct sales channels capture catalyst-grade premium flows. Distributor networks sustain adsorbent replacement volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sodium silicate production clusters in coal-dependent regions of China and the United States anchor upstream supply for high-silica zeolite manufacturing. Refinery catalyst demand concentrates in coastal petrochemical corridors where sulfur regulations are tightening fastest.
United States
EPA Tier 3 gasoline sulfur limits drive refinery catalyst replacement cycles across Gulf Coast FCC complexes. The Environmental Protection Agency enforces 10 ppm sulfur ceilings without hydrotreater capital expansion waivers. Houston and Port Arthur refining clusters favor direct supply agreements with molecular sieve producers possessing captive synthesis capabilities.
China
Dual carbon emission intensity targets accelerate domestic zeolite catalyst substitution in Sinopec and PetroChina fluid catalytic cracking units. The Ministry of Ecology and Environment mandates MEE compliance timelines that disadvantage imported catalyst formulations. Ningbo and Dalian coastal refining hubs consolidate procurement around state-backed molecular sieve suppliers with integrated alumina-to-catalyst production chains.
Germany
REACH registration dossier requirements filter catalyst-grade zeolite suppliers lacking toxicology documentation capabilities. The European Chemicals Agency enforces substance registration deadlines that consolidate formulation access among integrated majors. Ludwigshafen and Leverkusen chemical corridors anchor backward-integrated production of zeolite Y and beta frameworks for European refinery export markets.
Japan
Fine chemical manufacturers expand high-silica zeolite beta procurement for pharmaceutical intermediate synthesis requiring moisture-tolerant catalyst cycle life. The Ministry of Economy, Trade and Industry oversees industrial chemical standards that favor precision-controlled hydrothermal synthesis protocols. Nanyo and Yokkaichi production complexes dominate ion-exchange grade zeolite A output for regional air separation and natural gas dehydration demand.
India
Reliance Industries and Indian Oil Corporation world-scale FCC construction projects favor long-term catalyst supply contracts with technology transfer provisions. The Bureau of Indian Standards implements petrochemical catalyst quality specifications that accelerate supplier qualification timelines. Gujarat and Maharashtra refining clusters attract integrated molecular sieve producers seeking captive supply arrangements for greenfield complex startups.
High-Silica Zeolite Market Competitive Environment
Capacity expansion dominates the current landscape as integrated suppliers extend molecular sieve synthesis lines to capture refinery catalyst procurement consolidation. The vendor base separates into three distinct tiers: backward-integrated chemical majors with captive zeolite production, specialized catalyst formulators dependent on merchant molecular sieve supply, and regional adsorbent producers serving replacement cycles. Strategic archetypes include the integrated synthesis-catalyst pairing model, the technology licensing partnership approach, and the regional adsorbent volume play. M&A activity and capacity expansion represent the two dominant competitive vectors reshaping supply-side positioning.
Among Germany-based integrated chemical majors, BASF SE exemplifies the synthesis-to-catalyst vertical control archetype through its Ludwigshafen complex operations. Albemarle Corporation anchors North American supply positioning through processing chain investments. Tosoh Corporation occupies a specialist role in Asian ion-exchange grade output. These three entities represent distinct geographic and functional positioning strategies without implying equivalent scale or market presence across all zeolite framework categories.
| Leading Market Players |
|---|
| BASF SE |
| Honeywell International Inc. |
| Clariant |
| Zeochem |
| W. R. Grace & Co. |
| Tosoh Corporation |
| Arkema Inc. |
| Zeolyst International, Inc. |
| Albemarle Corporation |
| Others |
Value Chain & Pricing Dynamics
Captive molecular sieve synthesis at integrated chemical complexes anchors supply positioning and pricing power for catalyst-grade material. BASF SE controls zeolite Y production from raw alumina through finished formulation at Ludwigshafen, while Albemarle Corporation's Kings Mountain chain and Tosoh Corporation's Nanyo complex replicate this upstream control in North America and Asia. This integration pattern insulates qualified suppliers from sodium silicate volatility and compresses qualification timelines for refinery buyers under EPA Tier 3 and MEE dual carbon mandates.
Pricing Analysis
After-sales service bundling separates catalyst-grade pricing from adsorbent commodity tiers, with six-month lot-to-lot certification and technical support included in long-term supply agreements. Three-tier pricing structure across premium, standard, and economy levels stratifies by SiO₂/Al₂O₃ ratio consistency and rare-earth exchange levels. Cost compression in standard-grade zeolite A for refrigeration drying stems from EU F-Gas Regulation capacity buildouts. Merchant catalyst formulators lacking captive synthesis face the steepest price sensitivity as integrated suppliers capture direct refinery relationships.
Supply Chain Analysis
Dual-sourcing requirements from Sinopec and PetroChina facilities mandate qualified backup suppliers for fluid catalytic cracking catalyst, compressing vendor lists to state-backed molecular sieve producers with integrated alumina-to-catalyst chains. Sodium silicate production concentrates in coal-dependent regions of China and the United States, while finished catalyst formulation clusters in Germany, Japan, and coastal Chinese refining corridors. Feedstock dependency on energy-intensive sodium silicate and rare-earth elements for ion-exchange creates exposure to carbon border adjustment phases. Distribution runs through direct sales channels for catalyst-grade material and regional distributors for adsorbent replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH registration dossier requirements and MEE dual carbon mandates erect barrier-to-entry moats favoring integrated majors with toxicology documentation and captive synthesis capabilities.
For Market Incumbents: Hedge against metal-organic framework substitution in natural gas dehydration by accelerating hierarchical pore architecture R&D for zeolite Y resid processing. Lock in long-term sodium silicate offtake agreements with coal-independent production sources before carbon border adjustments phase in. Capacity expansion at Ningbo and Dalian coastal hubs captures Sinopec procurement consolidation.
For New Entrants and Emerging Players: The premium-economy price-point gap in ion-exchange grade zeolite A for EU F-Gas Regulation refrigeration systems offers white-space entry without catalyst-grade certification barriers. Target Indian Oil Corporation and Reliance Industries greenfield FCC complexes with technology transfer partnerships as the most penetrable demand pocket. Lead with biomass pyrolysis bio-oil upgrading catalyst formulations where qualification timelines remain undefined.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated chemical majors seeking regional catalyst supply positioning. Five-to-ten year viability favors molecular sieve producers with captive zeolite synthesis and existing REACH registration dossiers. Watch for carbon border adjustment mechanism implementation in European zeolite catalyst imports as the inflection signal for production relocation decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zeolite Synthesis | BASF SE and Albemarle Corporation lock in margin capture from raw alumina through finished FCC catalyst formulation. |
| Long-term Supply Agreement with Technology Transfer | Reliance Industries and Indian Oil Corporation greenfield complexes favor captive supply arrangements with molecular sieve producers. |
| Capacity Expansion for F-Gas Regulation Compliance | European molecular sieve producers add ion-exchange grade zeolite A output for hydrocarbon refrigerant drying systems. |
| Joint Venture for Domestic China Production | State-backed suppliers in Ningbo and Dalian displace imported catalyst formulations under MEE dual carbon mandates. |
| Green Manufacturing Transition for Carbon Border Adjustment | Coal-independent sodium silicate sourcing insulates zeolite manufacturers from input cost spikes during EU CBAM phases. |
Study Parameters
Document review covered customs and trade data from China and the United States, SEC 10-K filings from integrated chemical majors, and ECHA REACH registration databases, complemented by interviews with petrochemical refinery procurement directors, catalyst formulator technical leads, molecular sieve plant managers, and sodium silicate supplier sales executives. Bottom-up triangulation across framework type demand and top-down validation against end-use industry consumption produced convergent estimates.
Segment-level projections across zeolite Y, beta, X, and A frameworks by catalyst, adsorbent, ion-exchanger, and drying agent applications over the projection horizon fed into analytical models. CAGRs were derived from regression analysis against EPA Tier 3 implementation timelines, MEE dual carbon compliance schedules, and EU F-Gas Regulation phasedown mandates. Rare-earth price volatility and sodium silicate energy intensity served as key forecast sensitivity inputs.
Inputs from ECHA registration databases and MEE enforcement bulletins were available through the study window; gaps in real-time refinery catalyst procurement contract terms introduce uncertainty bands around direct sales channel estimates. Deviation in carbon border adjustment mechanism implementation timing or rare-earth export restriction severity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
High-Purity Hydrogen Fluoride Market
High-Value Chemicals
Hydroquinone Market
High-Value Chemicals
Hydrogen Cyanide Market
High-Value Chemicals
High Molecular Ammonium Polyphosphate Market
High-Value Chemicals
High Purity Magnesium Citrate Market
High-Value Chemicals
High Purity Lignin Market
High-Value Chemicals
Global High Temperature Grease Market
High-Value Chemicals
Phenanthroline Monohydrate Market
High-Value Chemicals
Hexafluoropropylene Market
High-Value Chemicals
High-Heat Melamine Foam Market
High-Value Chemicals
Asia-Pacific Hydrogen Bromide Market
High-Value Chemicals
Hydroxocobalamin Chloride Market
High-Value Chemicals
High Performance Fluoropolymers Market
High-Value Chemicals
Alpha Hydroxy Acid Market
High-Value Chemicals
Ultra-High Purity Hydrofluoric Acid Market
High-Value Chemicals
Global High Heat Foam Market